Small Cap Value Report (Weds 5 Jan 2022) - CNC, ADF

Good morning! It's Paul here with the SCVR for Weds.
Agenda -
Concurrent Technologies (LON:CNC) - "slightly ahead" trading update for FY 12/2021. I like the numbers - a reasonable PER, good reliable divis, and a superb balance sheet. That provides a decent base for further research by readers on the company's products, markets, and prospects. Outlook mentions an exciting pipeline of new products. Potentially interesting, and worthy of further research, I reckon.
Facilities By Adf (LON:ADF) - a new float on AIM today from Cenkos. I rummage through the Admission Document, and much to my surprise, think this looks quite good. Most of the money being raised at 50p, is to fund expansion, due to strong demand. Founders retain nearly 50% of the business. It has a fleet of specialist outside broadcasting vehicles for the TV/film industry, with 35% market share in the UK. It plans to expand into Europe through acquisitions. Current trading looks good. Just an initial view, but I like
Industry data - Propel newsletter (which I find interesting & useful) provided sector data yesterday from the hospitality sector - based on widely used software. December trade was obviously well down on 2019, but not as bad as I had feared, especially outside of hardest-hit London. It's a useful reminder that there is price-sensitive industry & macro data out there, which we can often access freely to improve our investing. Hence relying solely on the RNS for company specific data could mean we miss a trick. An excerpt -
Hospitality sales last month were down 12% compared to December 2019, according to the latest data from S4labour, the online labour-scheduling management system from Catton Hospitality. London sites’ sales were hit the hardest as like-for-likes fell by 23% on 2019 levels. Non-London sites also saw downfalls, however by a lesser figure of 10%.
[Source: Morning briefing email (4 Jan 2022) from Propel Info]
Hospitality sector experts Langton Capital also provide a wonderful (and often hilarious) free daily email - there's a signup box here (scroll down, on the left).
I mystery shopped the Bournemouth branch of TGI Fridays (owned by Hostmore (LON:MORE) - I hold) last night, and was surprised at how busy it was. If anyone's interested, I can post some pictures & comments.
This reminds me that a friend told me, before the profit warning, that he monitored website data for Boohoo (LON:BOO) (I hold) and reckoned it was down 20% at one point in the autumn, for the legacy brands (Boohoo and PrettyLittleThing). I don't know how accurate that is, but it correctly predicted the direction of travel anyway, so maybe I should pay more attention to this? Although in the past, when I have checked website data, for various companies, it didn't seem to correlate with subsequent trading updates, hence why I stopped.
Maybe the community here could pool our resources, and start a new thread on industry/macro data, and share any useful industry/macro data with each other?
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Concurrent Technologies (LON:CNC)
80p (pre market open) - mkt cap £57m
Concurrent Technologies Plc (AIM: CNC), a world leading specialist in high-end embedded computer products for critical applications, announces a trading update for the year ending 31 December 2021.
This sounds fairly good -
Based on its unaudited management accounts for 2021, the Company expects to report revenues and profitability slightly ahead of market expectations despite the ongoing challenges that the worldwide component supply chain is experiencing. Whilst the component issues are ongoing, the Company enters 2022 with a robust order book and an exciting pipeline of innovative product releases to grow our customer base and revenues in 2022 and beyond.
The Company also expects to pay a final dividend to shareholders and to pay this after the final results for 2021 are announced.
There’s no footnote provided unfortunately, to inform us what market expectations are. This wastes our time, having to look up forecasts, and we can’t always access them.
An old forecast from Cenkos on Research Tree indicates adj EPS of 4.68p for FY 12/2021.
Stockopedia has the same 4.68p EPS figure on the StockReport, so it looks safe to rely on that number.
“Slightly ahead” today could mean perhaps 4.75p EPS for 2021? That gives a PER of 16.8 - which looks about right, or maybe even slightly warm, given that the company looks ex-growth (no increase in EPS over the last 6 years) -

.
As you can see from the graphs above, the company has a decent profit margin, making £3-4m profit annually, on revenues ranging between £16-21m p.a.
Also note the regular divis, providing a reasonable yield of about 3.3% currently.
Balance sheet - nothing is said today, but I’ve checked the last balance sheet, as at 30 June 2021, and it’s fabulous - very strong, with net cash of £12.4m. Hence there’s clear scope to fund acquisitions, or a special divi or buybacks. This looks a safe, conservatively financed company.
Cashflow statement - again from the interim results, the only thing to note is that CNC capitalises a lot of development spending by the looks of it - £0.9m in H1, and £1.9m in FY 12/2020. The amortisation charge is in that ballpark too, so there’s no artificial boosting of profits. Also, the company doesn’t quote EBITDA (which of course is a meaningless number when companies capitalise their development costs).
My opinion - this company looks quite interesting.
The numbers stack up, it’s almost a value share - reasonable PER, decent & reliable divis, and a bulletproof balance sheet.
The question is, where’s the growth going to come from, and are existing profits sustainable? The trouble with small caps, is that profitability can sometimes be based on one, or a handful, of decent contracts. If they expire, then profits can collapse. Whereas with large caps there’s usually more business spread over a large number of contracts & subsidiaries.
Hence I think a key point to research for CNC, is client/contract concentration - there’s usually information about this in the Annual Report.
Today’s update mentions an exciting pipeline of new products. That could be a potential catalyst for the shares to re-rate, if new products drive growth in revenues & profit, perhaps?
The current share price seems well underpinned by existing profits & assets, assuming they’re sustainable. So any growth could be the icing on top in future, if it happens.
Overall, this share could be worth readers having a closer look at, it gets a thumbs up from me on the basics.
As always, remember I’m only giving a quick review of the numbers here, so more detailed research is needed by you, to assess the company’s products, competition, and outlook - which is what ultimately drives the share price up or down in future.
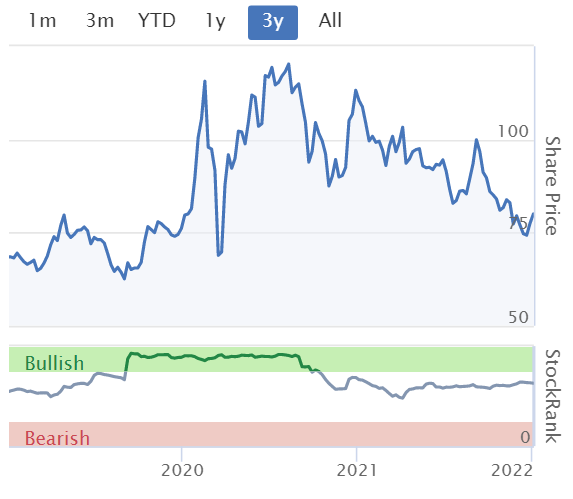
Share price performance in the last 3 years has been lacklustre, reflecting the lack of earnings growth -
.
Facilities By Adf (LON:ADF)
Admission to AIM and First Day of Dealings
It’s quiet for other news, so my attention was diverted to this new listing on AIM, floating today. I’ve had a skim through the Admission Document, and think it looks potentially interesting, and worth following.
In the last couple of years, too many new floats have proven to be over-priced, over-hyped, and opportunistic (e.g. short term pandemic beneficiaries), with management and/or private equity owners using the float as a way to bank a profit. All too often brokers & other promoters don’t seem to care about their own firm’s reputation, it’s just all about greed, in trousering ludicrously high fees.
Against that backdrop, it’s quite refreshing to see this new float, ADF, looking reasonably priced. Also, it’s what I see as a good float - i.e. most of the placing money is being raised for expansion of the business, with only a relatively small amount withdrawn by founder shareholders trimming their holdings, but retaining a large amount of skin in the game. So far so good.
The £2m fees unfortunately do not pass the reasonableness test, and seem very high for a £38m market cap float. One of the post-Brexit aims is to make the London market more competitive. Surely this could best be achieved by slashing the red tape, and therefore adviser fees?! Although there is a counter-argument that a really thorough scrutiny at time of listing is a one-off, and provides a wealth of information in the admission document. Not that many people read them. Although when companies fail, there were often warning signs lurking in the admission document, usually near the back, so it’s worth a read, which takes me about an hour typically as there are lots of parts you can skim over.
Incidentally, I carefully read the “risk factors” sections now, for all accounts, as there are often important warnings in there.
Numbers -
Placing of 30m new shares at 50p each, raising £15m (£13m after fees!) fresh cash for the company, to be used for expansion, due to strong demand.
Selling shareholders (Directors) are reducing from 40m to 35.3m shares, but holding a substantial 46.8% of the enlarged equity.
Total share count on listing will be 75.5m, so at 50p placing price, the market cap is £38m
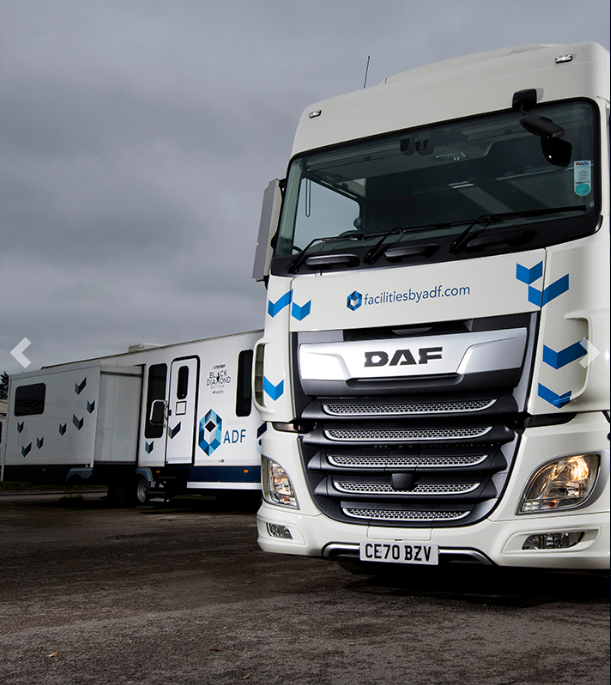
What does it do? ADF hires out specialist trailers (towed by articulated trucks) for the TV/film industry. Here’s the fleet, from page 18 of the AIM AD (Admission Document) -
.

.
The fleet seems to be mostly leased, so the balance sheet shows large entries for lease right of use assets, and lease liabilities.
The company is experiencing strong demand, and is booked up for 2022, so it’s raising more money to expand the fleet. That sounds ideal, I like that a lot as an investment proposition.
Historic numbers - are not bad, with the pre-pandemic year of FY 12/2019 showing £15.9m revenues, and £2.1m profit before tax (see page 41). However, I would caution that, as a listed company, this would be a good bit lower. Why?
Listing & adviser fees, non-execs, audit fee (of £11k in 2020!) etc, all could add maybe £250-500k p.a. in additional costs, and
Director remuneration - is typical for a private company, with salaries c.£100k (above which the marginal income tax rate goes to something ridiculous like 60%, due to tapering of personal allowances), then the rest is paid via dividends. That’s likely to change, so we could see Director remuneration as a listed company moving to £200k+ salaries, and share options. Thus I reckon that could add £500k+ p.a. to the overheads.
Put that together, and I reckon we could be looking at profits roughly halving, on the FY 12/2019 figures, as a listed company. Hence caution is needed when valuing this share on the historic numbers.
Interim figures for 2021 - this is where it gets interesting! See Section C of the AD - unaudited results for the six months ended 30 June 2021.
The restarting of TV/film production meant revenues soared to £11.5m (up 385% on lockdown 1 hit prior year comps) Profit before tax rose to £2.8m, in just 6 months remember. Whether profits are sustainable at that level, is another question though. Still, it’s not bad for a float priced at £38m market cap, and with £13m in new cash within that valuation.
Balance sheet at 30 June 2021 (unaudited) looks OK, with NTAV positive at £4.8m. It was nicely cash generative over this 6 month period, with cash rising from £1.25m to £3.1m.
Client concentration - see page 51 - is very high. The top 2 customers (which includes Netflix, I believe) make up 65% of total revenues in FY 12/2020, although that year was heavily impacted by the pandemic, with revenue roughly halving. Losses were minimised due to Govt support of about £1.8m.
Clearly the big companies (Netflix, BBC, Sky, and others) are absolutely critical relationships for ADF to nurture, and that is a risk. Although it’s also an opportunity, as if ADF gives top notch service, then that could lock out competitors, and maintain high margins.
Market size & expansion - I originally dismissed ADF as a potential investment, because it says on page 15 that ADF already has 35% market share (it’s UK only at the moment). So what’s the point in investing here, given that it’s probably not far from saturation in its niche? Although good organic growth is expected, as so much more original content is being made, due to newer creators like Netflix, focusing on original content (which they seem to be very good at, I have to say).
Page 22 of the AD explains that European expansion, through acquisitions, initially targeting Spain, France, and E.Europe is the plan. That makes sense to me, because I’ve heard that post-Brexit it can currently be difficult for musicians & other creatives to get visas for tours. Although that may not be so difficult for the TV/film sector, I don’t know. So buying (potentially distressed) European companies in this niche, looks a good way to instantly bolt on the people & equipment needed.
Acquisition risk is therefore a big potential issue here. I’d want to know more about the Directors and their experience. Even if they haven’t done acquisitions themselves before, some solid NEDs with plentiful acquisition experience would be very necessary, in my view. So many companies come unstuck with bad acquisitions. Plus of course there could be dilution from any future fundraisings, although mgt have too much skin in the game to do anything reckless or highly dilutive.
My opinion - I think this looks quite good, and reasonably priced, based on an initial skim of the AD.
I’ll keep an eye out for its future trading updates and accounts, which should gradually build my knowledge of the company.
On a first view though, unusually for a new listing, I’ve formed a positive early impression.
.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

78 comments
Significant breakout from Somero Enterprises Inc (LON:SOM) this afternoon. Is there any news or is this simply the market realising the value in this company?
Perhaps just no-one wants to sell their shares any more? It's had increasing good PR from PIs, who (agreeing with Paul) set the actual day-to-day pricing.
Bought by John Rosier of John's Investment Chronicle fame. The rise came after he'd emailed his subscribers.
Interesting, thanks. That seems to be quite late to the game for John. But he does have quite a few followers.
A quick glance at Concurrent Technologies (LON:CNC) following Paul's comments brought up one aspect key to whether there can be a breakout in earnings growth , namely the board.
Looking at the 2019 a/cs I would not invest in a company where the board consisted of:
Chairman - a solicitor who had been a director of the company for over 30 years
NED - former stockbroker running his own Conferences, Exhibitions & Corporate Event Management company, on board since 2004
MD age 66, with company since 1985, Director since 1989, who had stepped up during the year following sudden death of previous MD, who had himself been a director since 1985.
Engineering Director age 64, appointed a Director of the Company in 1995
These have now all gone and the board now has new Chair, NED, CEO from outside plus two internal promotions to board level so the key question is whether these can transform the company into one that grows profits. Judge fo yourselves here:
https://investor.cct.co.uk/boa...
The new guys sound pretty good to me with very relevant experience:
Miles Adcock – CEO
Re Concurrent Technologies (LON:CNC) -- I agree, and the Chair & NED also have highly relevant experience from Wolfson. Looking forward to meeting them at future AGMs and also to hear more from Lord Lee about his impressions. (Yes, I hold)
Read your article on "industry agenda " and your video review of your trading with interest . One of the shares I overlap with you is SCS and your comment regarding a potential profit warning based on supply chain issues prompted me into action -I decided to visit my local SCS store yesterday to get a feel on the shop floor as to what was happening .
1. I was particularly interested in supply chain issues and the sales person I dealt with was armed with the latest delivery dates for everything I said I was interested in . Very efficient in that respect and very helpful although I was only asking about sofas. The store appeared to be very busy with lots of footfall -in fact I was quite surprised at the number of "punters" who were in the store . The impression I had was that anything in leather (aprox 50% of sales ) was all made in China and lead times had increased over the last few months up to 16/20 weeks . The other 50% of sales were mainly sourced in the UK and if anything lead times had remained the same or if anything some improvement . I came out thinking that on balance the supply chain issues are still there but probably about the same as they were a few months ago.
2. in addition to the above I noted the following announcement the wife of CEO has made which I would suggest is quite a significant purchase - on my reckoning that's aprox £156000
ScS Group plc (the "Company") announces that on 16 December 2021, it was
informed that the spouse of Steve Carson, CEO of the Company, purchased 75,000
ordinary shares in the Company at a price of 208.5 pence per share.
Since your video I have agonized over whether to take any action but if Mr Carson is willing to spend that kind of cash i have decided to ride along with him . The fundamentals of the company are fantastic but only time will tell if my continued support is justified .
.
Just an anecdotal comment re £ADF. I live in an area that is very popular for filming, TV in particular. My car was once walked past in Motherland! Anyway I have noticed a definite uptick in activity in the last few months with lots of filming locally and regular leaflets through the door suggesting that our house might be suitable for a set.
Previous experience when allowing filming in restaurants is that the hassle is in most cases far greater than the reward.
Hi Paul
Just to revert to your portfolio review video
Just a couple of points:
Anyway thanks again and I look forward to the outlook for 2022 video.
Regards
Michael
I agree with Michael, when this share was discussed at Mello on 21 June 2021 the price was 361. The audience vote was interesting.
Buy 68%
hold 22%
avoid 5%
I did trust the audience based on "Who wants to be milioner" when the audience vote is the best answer. and it has been disaster.
I still hold!
I agree with Michael, when this share was discussed at Mello on 21 June 2021 the price was 361. The audience vote was interesting.
Buy 68%
hold 22%
avoid 5%
Yes, that's because at that point in time, the fundamentals looked attractive, on both the long-term track record of the company, and the growth, and broker forecasts - which had for years been repeatedly beaten. That's why the audience vote was positive.
All we have to go on, are the facts & figures at any specific point in time, which have since deteriorated. Hence why the share price has fallen. It happens.
Mello audiences are not clairvoyant, and are generally smart investors, so I think if you looked at all Mello audience votes they would look sensible. Rather than just plucking out one share that has gone wrong and implying that we're muppets from that sample of one. With hindsight.
I do think people need reminding, that it's completely normal for a third, to a half of our investments to not work out as we hoped. It's fundamentally all about trying to minimise the losses, and make sure the winners make more money than the losers, over the long term. Easier said than done!
Regards, Paul.
don't you mean who wants to be a milliner?
CNC
I would add that significant management changes over the last two years could be the catalyst for more dynamism from a company which, whilst high quality, appears either unable or unwilling to grow. Cf REC.
CNC - had a look based on the Tangible Surplus (TS) - i.e. the average annual growth in tangible equity over the past 4 years added to the yield, the sum of these two is then expressed as a % of MCap.
The TS cuts through the nonsense and shows what a business is really creating for its shareholders relative to what they are paying.
A bit rough and ready as I have just used my phone - sifting Morningstar data is a little awkward on the phone, but I am in bed recovering from Covid so I am not moving.
I get a TS of about 5%. This suggests a fair price, but not a bargain. CNC does not issue shares of any significance, which is always good to see. Not over priced, unlikely to lose your shirt here, but to buy in you would need to be very confident that genuine retained earnings are set to accelerate from here.
To be a bargain at the current sum of the equity growth and the yield, you would be looking for the share price to be a good 50% lower.
Thought that I would have a look at Bohoo as it is often talked about here.
No yield, regular share issuing and the accompanying dilution. The share issuing averages around 2.5%pa, so not huge, but it happens pretty well every year.
Net tangible equity does grow, typically around 4% pa over the past 4 years. But once you deduct the average 2.5% share issuing and there is no dividend, the Tangible Surplus falls to around 1.5%.
Hideous even after the recent price falls, prior to the price falls, a buy recommendation for Bohoo would be a highly irrational investment, with no underpinning whatsoever, I still see no underpinning now, even after the price falls.
What about any investment opportunities on other shares?
Regards
Current holdings in order of size: LGEN, BWY, Fort, ScS, Boot, CAML, Plus500 and a small £25k Tesla short position.
I did not ask that but anyway
Thanks
Oh good, Legal & General (LON:LGEN) is my biggest non-speculative position, which has done well, and I'm wondering how much further it can go over my 320p target, when that hits...
Boohoo (LON:BOO)
No yield, regular share issuing and the accompanying dilution. The share issuing averages around 2.5%pa, so not huge, but it happens pretty well every year.
No yield - yep they are growing buisness having grown sales from 195 mill to expected £2.3 bill in 7 years . They have deployed resources exactly where they should do growing sales 10 fold in 7 years.
Most years the increase in share count has ben materially below 1%. Share count has increased no doubt ref specific items for example the recent 5% increase would have been down to the buyout of minority sharholder interests so that issue was in theory going to be earnings enhancing .
I summary i think the actual increase in shares not for specific investment in buisness i nothing like the 2.5% increase you quote - probably closer to 0.5% which is fine and dandy to me (albeit i would rather it was nil!) for a company that has grown sales 10 fold + in 7 years - the share count increase has been very manageable in that time!
Net tangible equity does grow, typically around 4% pa over the past 4 years. But once you deduct the average 2.5% share issuing and there is no dividend, the Tangible Surplus falls to around 1.5%.
Well the investment in brands and expansion isnt really going to flow through to the bottom line in this regard . Basically if you build a warehouse or improve warehousing systems or buy new brands you spend money with payback probably only starting 1-2 years later - its easy to see where their cash has been invested thats not going to show up as nice fancy ROI type stats though due to the nature of the spend. It could be their global domination plans will be a spectacular failure - the jury os out there if for sure in that regard at present. sometimes you jsut need to expense expannsion costs to the bottom line too.
Doug2b
Hideous even after the recent price falls, prior to the price falls, a buy recommendation for Bohoo would be a highly irrational investment, with no underpinning whatsoever, I still see no underpinning now, even after the price falls.
Thats your right to have your viewpoint mine is completely different thats what makes a market. To me pile it high and sell it cheap buisness model on simple principles as they have provne to work is about as simple a business model as you can get - if you fail to see or understand reasons for share count increase and where they have been investing money and trot out its a crap business based on your 2 or 3 personally selected quoted stats then sadly you have probably not done enough research to see that the opposite viewpoint may have some valid arguments - your reasons for dismissing the company seem simplistic and lacking any detailed work - thats fair enough no one is really on this board to convince anyone else to buy anything they think is crapola.
Over the past 4 years, the average share issuing is c2.5% pa, over the past 6 years it is c1.95%.
Growth! This is not a growth business relative to its MCap. There is little net tangible surplus growth, Boohoo does not create sahreholder wealth. The apparent earnings growth is misleading, these earnings are not creating wealth for shareholders, it creates little.
This is an extreme example of investors complusively following an alleged earnings growth story without ever checking to see if the retained profits ever drop into the tangible equity line of the balance sheet to a level which justifies the MCap.
I am not opposed to intangibles either, this is how you account for acquisitions when you pay above the tangible asset value which you will of course in this sector. But intangible assets must ultimately create tangible wealth, this is not happening, clearly it is not, the cupboard is bear!
Take ScS and Plus500. These businesses do not need a high tangible asset base either. But they have one because their earnings are real they are rapidly piling up tangible cash for shareholders.
The problems with Boohoo are two fold. Firstly it is a weaker business than you think, not a basket case but weaker than assumed. Secondly, you are paying far too much for what is actually there, way way too much.
And this is after the price falls, who on earth was recommending this before the price crash, that was true investing insanity.
Boohoo (LON:BOO)
Doug2b
This is an extreme example of investors complusively following an alleged earnings growth story without ever checking to see if the retained profits ever drop into the tangible equity line of the balance sheet to a level which justifies the MCap.
What a load of cobblers - boohoo hasnt until recently done too bad a job in that regard book value had gone from 73 mill to 481 mill - the point is i am not expecting them to be accruing excess funds into tangible equity at a rapid lick right now i am expecting them to drive the sales of the business forward at a rapid rate reinvesting as much as is sensible in that regard so sales growth is maximised whilst keeping some semblance of decent margins. If you spend £200+ mil in new warhousing and the like for future gain it obviously aint gonna be pretty short term.
There are many ways to skin a cat - look at Amazon over the years i am guesing this would have not presented from the mere numbers as being a quality buisiness as they reinvested within the business to ramp up turnover - not all good businsses pass all the basic quality metrics tests that you are defaulting too - thats a given. Are you saying amazon was a baasket case and have you though you could be wrong along thos similar lines here - presumably you think you cannot be wrong ? .
Take ScS and Plus500Ref SCS you are comparing a business that has had declining turnover in 5 years to 2021 to a business that has increased sales nearly tenfold and increased profits 5 fold in the same period that really is an apples and pears comparison. Plus 500 is lucky enough to not need the capital type investment that boohoo needs to do well - you could probably argue Pus 500's buisness model is therefore much less risky and you woluld be right but not a reasonable comaprison here due to the different busines types.
The problems with Boohoo are two fold. Firstly it is a weaker business than you think, not a basket case but weaker than assumed. Secondly, you are paying far too much for what is actually there, way way too much.
Firstly it is a weaker business than you think, not a basket case but weaker than assumed.
Well i will agree with you here the jury is out now they have certainly hit a poor patch (note they have previously temporarily hit the rocks too and come back strongly) - facts are we won't really know who is right and who is wrong here until the mop flops in a couple of years time and we see whether their plans come to fruition or not.
Secondly, you are paying far too much for what is actually there, way way too much.
Not necessarily if they end up where they want to be - if they can get up to £4 billion of sales and get close to 7% operating magin and apply 20 times multiple to that the market cap would be 3.7 * what it is now. Thats the kind of path they would be hoping to hit and if they do IMHO thats some decent upside potential from where we are right now.
I guessing you will say thats all fantasy numbers in which case we will leave it there and see how the mop does flop. Note it is clear the wheels have somewhat fallen of the truck this year and that is aligned of a period where they are doing a huge amount of investemnt for the future anyway i can sort of see why you may think the worst - hey ho two opinions make a market.
The problem with Boohoo is that over the past 4 years the gain in tangible equity relative to the MCap is c1.5% pa. Clearly Bohoo is dramatically over priced. This assessment does not factor in any particular recent bad news so the valuation before the price falls would certainly be into the realms of madness.
Fort is opening a new brick plant this year. Investment in such an expensive and lengthy develpopment has held back their tangible surplus for a few years. But its TS is still over 7% currently, likely rising to the mid teens over the next 2 to 3 years. So for Fort I am factoring in the future, but at least I have a valuation starting poin that is half decent. Bohooo will hav to work miracles from here to justify a valuation.
Amazon you mention - as for now, Amazon is not creating shareholder wealth, the share price may be going up but it is not creating sahreholder wealth. Shares are issed every year, without the share issuing, the tangible equity is shrinking. In terms of economies of scale and a favourable tailwind, Covid, it could not have been better of late for Amazon. But the balance sheet reality is there to see, the business is grossly over priced, perhaps their scale of operation is not now helping them.
ScS created a tangible surplus of around 30% of MCap or more last year, Bohoo would take around 25 years to achieve the same. Amazxon may struggle to achieve a net tangible surplus ever again.
I can't believe that I am giving out such basic tuition for free, I hope that you are all very grateful, you certainly should be as it seems like a number of people have been merrily lead down the garden path with Boohoo!
Over the last 20 years I have been a pure growth investor.
I have achieved success in a number of investments, including 50x returns in the likes of Amazon, Google & Tesla.
However I have today seen the light & will be liquidating my growth portfolio to invest the proceeds in cigarette butt stocks like Scs (LON:SCS) and LGEN .
Thanks again for the insight Doug2b.
You misunderstand the term cigar butt investing. The businesses that I reference are rapidly growing their tangible equity year after year, they are no cigar butts.
Take the SMT fund. Comfortably behind my 12+ year SIPP performance, but I am well behind during the past 5 years.
The tangible surplus - equity growth and dividend, expressed as a % of MCap - for my holdings averages over 10% now, but for SMT it averages between 1% and 2%. SMT (and Fundsmith) are riding a price bubble and so are many of you. This will not end well for you.
Whatever Doug2b- i admire your disciplined approach to investing - thats something to be applauded - and clearly on fundamentals at present Boohoo isnt exactly winning any favours with its poor run - what i do disagree with is your cock suredness that you are right and that its a given therefore that Boohoo is wildly overpriced simply due to the fact it doesnt sit right with your selected criteria - you might be right you might be wrong. Feel free to come back in 24 months and gloat that you were right with this company - i certainly get it wrong plenty so i could easily be wrong here.
Yes we are.
ScS is a better company than Amazon.
God help us all!!
Thanks
Yes, because of the way that it is priced. ScS is now generating huge returns relative to MCap. This makes ScS a significantly better investment than Amazon at current prices.
You actually think that ScS generates huge returns ??
Wait and see.
As I said :
God help us all!!!
You may or may not be right in what you say but your arrogance is most objectionable.
In terms of your final through sentences. I have been a SIPP investor since July 2009. My SIPP performance was verified by the DT in an article under the pseudenym Bogdan Branislov last April. 17 times times up ar the time, after 12 years, I recall, 19 times up now. These are my unlveraged returns, my moderately leveraged funds have done a lot better.
I will let you decide whether you think that qulaifies me to comment on Boohoo's valuation. Let me put it another way, name someone who you think is better qualified to comment on this and give your justification.
Thanks for the insight Doug2b, I ditched Boo again today.
Many years ago Lord Lee was interested in Concurrent Technologies (LON:CNC) and I have followed it ever since . It has never really gone anywhere. I do not see any catalyst for growth in the latest figures. being part of a larger company could give it the springboard that it needs
RE CNC:L 'a good 50% lower' still better than stockreport analysis :
Analyst Forecasts 1p, (98% lower)
Think someone is having a laugh. Whilst I agree growth is sluggish they reported record order books last year and have consistently met or beaten targets over the last 3 years. A lot of their work is in the defence sector which should be quite reliable I would have thought given the state of this world at the moment. What has been a little disappointing is the lack of news on Ai developments for which they specifically designed an integrated board over a year ago. Sadly one of the founders died a couple of years ago, the CFO retired and they have had quite a change of top management recently, replaced by some promising staff with impressive management credentials in this field. Then of course there is Lord Lee as an investor with connections to security advisory committees.To me this is a very exciting prospect 'with lots in the pipeline.' Highly recommend their website for news on products and innovations. It pays a decent dividend. Maybe a bit of a steady Eddie, but has come up from around 20p in the last ten years, so beats most ftse 100 companies by a mile, and plenty of opportunities with 5g and Ai involvement. Like many small caps liquidity can be an issue when the big players come in for a quick buck and don't get one. Coffee beans may not be flavour of the month but I consider this is to be one of mine.
How do you define tangible equity out of interest? Tangible assets only minus all liabilities minus preferred stock? Do you also factor in share options? Genuinely interested.
I think you would get your messages across better by having a slightly more moderate tone - there is much sense in what you say and some good reminders here (whilst not being the only view of the world...) and I would think the community could benefit from hearing more of it, albeit in a more sociable manner that would facilitate discussion and learning rather than one-upmanship.
AdvancedAdvT Limited
(the "Company")
Acquisition of shareholding in M&C SAATCHI PLC
The Board of AdvancedAdvT Limited (LSE:ADVT) confirms that the Company has acquired 12,000,000 ordinary shares of M&C SAATCHI PLC for a price of £2.00 per share, representing c.9.82 per cent. of the current issued share capital of M&C SAATCHI PLC, viewing this as a good investment opportunity.
A bit off topic.... but I'm struggling to find an ETF to give me exposure to a basket of China-based tech companies. Eg the usual big names... Alibaba, Tencent, JD, etc...
One that is listed on the LSE, that I can buy into my ISA, in GBP.
Anyone have an ETF that they know of to recommend?
Try £KWBP
£EMQQ (USD) or £EMQP (GBP)
KWEB
Listed on NYSE with $6B assets and 0.7% fee, tracks the CSI Overseas China Internet Index
has Tencent, Alibaba, Baidu, JD etc...
Chart looks interesting for bottom fishers, price peaked at $105 now $34 back to where it was in 2016 !
I am surprised that there have not been more trading statements out covering the Christmas period.
Because trading has gone well to expectations, neither too poorly or outperforming?
I think we could create a "TGI Indicator" The Speke Branch also seems to do good business and has maintained that over the last months. The Restaurants are open and airy, at least the ones I have patronised, and that may well help !
Morning all,
In terms of useful data, I've previously used SimilarWeb to get a rough indication of website traffic.
Using Best Of The Best (LON:BOTB) as an example, Similarweb suggests that traffic to botb.com has declined in recent months - https://www.similarweb.com/web...
Does anyone use a similar resource? Because the data is estimated, it's difficult to know how accurate it is and it would be great to find a robust solution.
Cheers,
I would use similar Web data with a pinch of salt, especially for a specific website. IMO it is most useful when looking at an industry overall (several sites), or comparing relative performance amongst a peer set.
Hi Boon
On the topic of Best Of The Best (LON:BOTB) , and knowing your experience in this sector, I wondered whether you had seen declining CPMs recently?
There seems to have been quite a dramatic fall in the last few months (according to the below) and I'm not quite sure what might have driven it. Has Facebook been forced to decrease its CPMs as firms have found it harder to target users?
The current rates now look lower than pre the IDFA changes last year.
Any thoughts as always appreciated,
Cheers
A
Interesting graph! If I remember correctly, is this based off USA campaign data?
In the UK, my personal experience (and this is a subset of FB audiences, very telco specific) that CPMs have not come down, they are still elevated. Been steady since early autumn. I have had convos with two other digital marketers in the last two weeks, both agency side, and both have grumbled about the continuing high CPMs. Their clients are in different industries, albeit I don't think they have gambling clients.
I wonder if BOTB high CPMs will remain. They compete for gambling audiences with the likes of sports betting. During covid when sports were stopped, they of course saw lower CPMs as the likes of Ladbrokes, William Hill pulled back campaigns. But now sports is fully back.
Best Of The Best (LON:BOTB)
Hi Boon
Thanks for that, most appreciated!
You are correct, the graph is US-based. BOTB told me that the UK follows a similar, albeit delayed, trend.
Good point on the gambling firms - it's interesting that you mention them as I follow a few (and own one) and I don't recall any mention of IDFA impacts, but there must have been an affect on marketing budgets at some point.
Hopefully there will be a BOTB update soon.
Cheers again
A
Hmm knowing what I know about FB CPMs, it is a real time auction based on competition and supply for that impression/user. And the auctions for US ad inventory is completely separate to UK. (eg if I wanted to advertise on FB, I'd have to specifically set to target and bid for US and UK geos). So I question the assumption that UK CPMs follow USA CPMs, as there is very little overlap in the advertiser set. Especially for gambling audiences.
Best Of The Best (LON:BOTB)
Hi Kieran
BOTB themselves told me that similarweb does not reflect reality for their own website and wasn't worth using.
I did try following similarweb trends for BOTB, but after a while realised that this didn't really show me much either.
I no longer use similarweb for any sort of tracking.
A
I am amazed at the promotional work Omaze is doing and cannot help but wonder if they are eating into BoTB earnings.
Omaze are advertising heavily on TV.
Am I alone in finding the presenter (Jo Pickard I think she is called) very irritating? She has such a sickly smile and every advert feels very false and over hyped. Annoying.
Rather belatedly, many thanks Paul for your portfolio review. It was good to hear about your portfolio performance and the strategies behind it.
One important questions you raised was: “Why am I chasing money I don’t need and risking money I do need for my retirement?” I think it is always vital to review why you are investing and the connected question: Will my strategy achieve that objective?
An IFA friend rather presumptuously told me a couple of years ago I was too old at 73 to be investing in AIM listed shares. As my two largest SIPP holdings are and probably were Somero Enterprises and BegbiesTraynor (each is currently just short of 5% of my total shareholdings spread across about 65 different stocks) I gave some thought as to why I felt comfortable having held these for over 5 years and holding many other AIM and small cap stocks.
My answer was that I was not simply investing for my own probably limited lifetime but for that of my 15 year younger wife and my two sons. In other words I could take a long term view. As I don’t draw down the whole income generated by the SIPP even a substantial market fall would not drastically affect my living standard. The fact that my SIPP fell less than the market as a whole in March 2020 was subsequently reassuring evidence that choosing AIM and small cap shares was not automatically to experience excessive volatility. It helped that I had a significant amount of cash in the account at the time.
One thing that struck me was your reference to retirement. I can’t imagine that on reaching 67 you will simply pass your portfolio over to a pension fund to manage. You will I suppose continue to manage your money until perhaps senility sets in. In that sense you will not retire. You just need to ensure you don’t blow all your money through gearing and think about what will happen to your money when you are no more. I was a co-trustee on a trust for a friend of my father’s and she frequently became worried about the market and I told her that the important thing was to invest in a manner that doesn’t give you stress and enables you to sleep at night even if it doesn’t give optimal results. I try to follow that advice myself.
My SIPP has returned 18.15% this year and 34:75% over the last 3 years, despite holding some Boohoo - my largest drawdown.. My ISA returned 24.38% this last year and 24.78% annualised over the last 5 years - according to my SIP and ISA providers - although there is no guarantee they are right. I can provide a bit more details of my holdings if anyone is interested, but given I lagged the SMXX as highlighted by you previously and Patrick L today I don’t see my fairly broad stock picks will hold great interest.
I hope, incidentally, you will find some time to be interviewed by my youngest son for his Finance degree course this coming year as I mentioned to Jack. He now has a small portfolio of his own to manage. All the best for the New Year.
Interesting comments Homosap re IFA. I am one too and sometimes our hands are a bit tied by compliance officers and FCA re levels of risk for "older" investors. Personally I appreciate that many clients much older than you are still comfortable investing in "high risk" AIM shares due to the investment time horizon being longer than one's life expectancy. Of course AIM portfolios can also be a great home for any investor with a potential IHT liability, due to Business Relief that might save 40% IHT if held for 2 years. BR doesn't apply to SIPP holdings of course so can be worth considering having the AIM holdings in ISA instead if that's an issue.
Yes, I did understand were my friend was coming from even though I was irritated by the bluntness of his comment.
Although I don’t use an IFA myself I understand their value which is often primarily as a sort of financial life coach. I recommended “The Laws of Wealth” by Daniel Crosby to my youngest son. You have to approach someone else’s money in a different way to your own.
I am a trustee on a number of trusts where the settlor wanted me to suggest investments because she knew of my interest in investing but I always declined to do so. The trusts are currently invested on a discretionary basis by J M Finn and provide another benchmark for my own investments.
Apart from having gone through a very fraught time as a result of being a Lloyd’s name in the late 1980s, which rather put me off relying on others to guide my investments, I also find the current IFA business model rather frustrating. I want from time to time technical advice on an hourly basis regarding some of the more complicated pension rules, but when I have approached IFAs they have not wanted to provide such advice but rather take over the management of my investments on the basis of taking a regular percentage regardless of whether they do better than I would have done.
Although I do have a significant portion of my ISA in AIM listed investments I am loath to rely on an IHT rule that might be withdrawn at any time - although I suppose the same may be said of the ability to pass on my SIPP investments without more taxation than is currently in place.
Homosap - BR, originally BPR, has been around since 1976 so I suspect it isn't going away any time soon. Wouldn't be surprised if AIM shares ceased to qualify at some point, but in that instance I would be tempted to roll the investment over into one or other of the "low risk" BR strategies offered by companies like TIME and Triple Point. Also worth looking at rolling assets that already would benefit from BR into Discretionary Trusts, up to the IHT allowances. Need to be sure of what you are doing but IHT savings can make high fees look rather small. None of this should be taken as advice of course!
Many thanks for that suggestion.
What a lovely and useful post Homosap .... thx for sharing. I recognise all the issues you raise!
Paul I was interested to hear in your very insightful 2021 wash-up that the SMXX (FTSE SmallCap ex Inv Co Index) was up 28% last year and looking at the chart it was at all-time highs last August. I've tended to focus on the FTSE all-share and FTSE 100 for benchmarks but looking at the 250 that also did very well last year going beyond previous all-time highs. It's a bit of a reality check for me at least as maybe I simply rode the wave (up 28.8% last year) rather than being a good stock-picker especially as quite a few of my stocks are in the SMXX (although also AIM which didn't do so well). Perhaps it might have been easier, if less interesting, just to have bunged my savings in a SMXX tracker at the start of 2021, as it probably was always going to be a good shout at the start of the year that small caps would recover quite a lot.
Does anyone think any particular indices, sectors, or trackers are historically lower priced going into 2022 and have a good chance of recovery this year? I upped my exposure to the travel sector at the end of 2021 as it had a bit of a sell-off in November and December and I think there is a reasonable chance we will see some normality return to holidays by the summer - or at least the hope of it which will drive share travel sector prices.
Morning Paul,
A hands up for TGIF pics and comments please.
Richard
I was slightly expecting an RNS from M&C Saatchi M&c Saatchi (LON:SAA) (I hold) this morning given the huge transactions at the close last night, about 20 percent above the day's trading price.
The shares have reacted positively this morning. I hold.
No idea whats going on but one of my largest holdings, can it hold it ?
The options highlighted by Paul previously made me limit my exposure, although I do have a 1.6% or so exposure in my SIPP. You are bold to have this as one of your largest holdings. But it has been performing well recently. Did you sell any into the spike that seems to be subsiding?
Advancedadvt (LON:ADVT) have just announced they have bought 9.82% of M&c Saatchi (LON:SAA) at £2.00 a share, in addition to the c.13% Vin Murria already owns...
Seems to be just shy of the % were they need to make an offer.
Vin Murria would likely be deemed a concert party member with £ADVT (as she is director of the above
I wonder if this signals down the line that Vin Murria sees acquisition value in M&c Saatchi (LON:SAA)
and I wonder if there is a predator out there who may be ultimately be interested?
Seems to be just shy of the % were they need to make an offer.
Vin Murria would likely be deemed a concert party member with Advancedadvt (LON:ADVT) (as she is director of the above)
I wonder if this signals down the line that Vin Murria sees acquisition value in M&c Saatchi (LON:SAA)
and I wonder if there is a predator out there who may be ultimately be interested?
Paul
Any chance you could take a look at Georgia Capital (CGEO} who announced the sale of one of their portfolio last week .
Looks a bit of a special situation that must rerrate as it has a NAV of circa £16 pounds a share , a market cap of circa 320 million , a share price currently around £7.25
What is significant is that the entire market cap is supported by just two of its holdings boyh of which seem bulletproof
- they own around 20% of bank of Georgia with a value around 160 million
- the sale last week was around 160 million too
So that’s the market cap covered and the rest of the portfolio seems to be in there for free .
I think this share flies under the radar and it’s very much a special situation now given the big crystallisation deal announced last week .
Sorry don’t have the exact numbers to hand but this looks set to rerate this year as it looks rock solid now .
Hiplanetx,
Thanks for your summary of Georgia Capital (LON:CGEO) - sounds a potentially interesting special situation.
It's (at least) a whole day's work to investigate special situations like that, so doubt I'll look at it. Also I'm not really interested in owning shares in Bank of Georgia - I have to want to invest in the underlying assets, to want to buy a cheaper, backdoor way into those assets (which is why Electra Private Equity (LON:ELTA) (I hold) appeals to me, even though the assets haven't yet re-rated to a more realistic valuation - give it time though).
I've flagged the share to a mate who is an expert on special situations, so will see what he thinks of it.
Thank you for the idea.
Regards, Paul.
Paul
Thanks for the reply .
I am with you not really wanting to own bank of Georgia however that should be considered only as a rock solid asset foundation that underpins Georgia Capital - to the tune of 160 million of its market cap .
Add on then the cash that is coming from the utility sale another 160 million then that is the market cap covered with cash and quite literally a “banker” .
The rest of the investments which are the ones harder to value but potentially more upside are in for free , looks to have virtually zero downside and plenty of upside ,.
I ran all the fag packet numbers last week but then lost the fag packet so apologies if a few of these numbers are a bit broad brush .
Dave
The broad thesis around Georgia Capital (LON:CGEO) was that the market didn't necessarily believe the valuations making up NAV given its Georgia developing market theme. I've often counter argued that actually the assets it does own are relatively easy to price on a private equity sale basis because of their utility nature - eg Water, healthcare (pharmacy network & hospitals) etc. Then add Bank Of Georgia (LON:BGEO) publicly listed on LSE.
In other words this is not some unicorn tech focused PE fund out of Georgia having a go! It is highly asset backed by key infrastructure to the Georgian economy.
The Water deal should be seen as a landmark or catalyst then : it sold to outside investors at a premium to the booked NAV and was one of their large assets. Therefore it is reasonable to infer that the rest of the assets are conservatively priced and that they are capable of both buying, extracting value and selling assets.
I appreciate that Georgia will come with a discount but by my calcs NAV stands at somewhere around £13 and probably a bit higher. I look at Bank Of Georgia (LON:BGEO) and think that is undervalued too and it makes up half the share price so more scope there. In my view the discount to NAV shouldn't be 50%.
As a result I hold and hope that this will re-rate to perhaps £10+ over the next 12 months but whether the market will give it that credit who knows.
Perhaps a discount due to geo political risks. Georgia's neighbour is Russia which invaded in 2008 & continues to occupy around 20% of the country.
hence why I highlighted that it will come with a discount, just not 50%. The political situation is actually pretty stable.
In the statement, £CGEO stated that the sale had led to an uplift of 2.2% in the last reported NAV. At current exchange rates, that takes the NAV up to 1464p per share. I hold both Georgia Capital and Bank of Georgia.
Yep 3% favourable currency change and 2.2% on Water utility sale gives around 1464p NAV
so sitting at a massive 52% discount. Pre-covid the discount ranged between 10 & 30% which also took into account the specific country risk, so should look to trade between £11 & £12 you'd imagine compared to the £7 as of today. That would still be a discount against peer group but accounts for the perceived geo-political element. Not quite sure what catalyst is going to narrow that gap in the short term mind. I would have thought the Water sale would have had more of an impact but it has been a bit muted.