Small Cap Value Report (Weds 6 Dec 2023) - SYS1

Good morning from Paul & Graham!
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. OR it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
.
Summaries
System1 (LON:SYS1) - up 25% 218p (£27m) - Interim Results - Graham - AMBER
Some strong earnings upgrades at this marketing platform with higher margins, operating efficiencies, and a positive outlook statement all contributing to a brighter picture here. A robust cash balance also strengthens confidence. Might be worth looking at again.
Graham’s Section
System1 (LON:SYS1)
Share price: 218p (+25%)
Market cap: £27m
System1 Group the marketing decision-making platform www.system1group.com announces its unaudited interim results for the six months ended 30 September 2023 ("H1", "H1 FY24").
We last covered this one in September, when it announced that it would beat expectations for the current financial year (FY March 2024).
Today’s adjusted numbers are a significant improvement on last year, with the company crossing over from a loss into profitability, and with a 27% improvement in revenues:
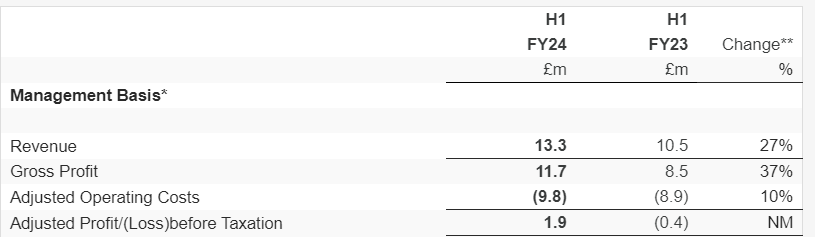
The company was previously forecast to generate adjusted PBT of less than £1m for the entire year - but in fact we have £1.9m in H1 alone.
However, before we go any further, let’s make sure we are comfortable with the definition of “adjusted” PBT. Here are the costs that get adjusted out:
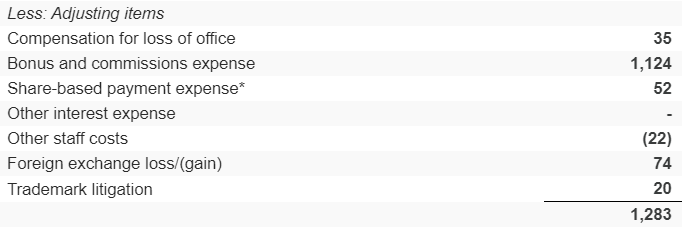
“Bonus and commissions” are not something I would be inclined to adjust out, and so personally I can’t sign off on the idea that the adjusted numbers are more meaningful than the actual numbers.
Here are the actual H1 numbers (this year highlighted in yellow). They are still a significant improvement on last year:
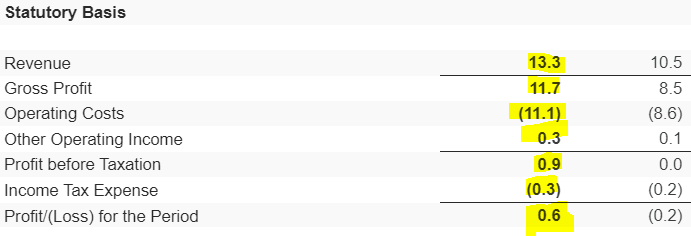
SYS1 reached a settlement with another company using the name “System1”, and is going to receive payments over time from this other company. The total value of the payments is confidential but they are included within “Other Operating Income” (£0.3m in the above table).
Cash balance rises to £6.3m.
H1 Highlights
136 new clients (H1 last year: 69) and improved retention of existing clients.
Gross margin 87.8% (H1 LY: 81.5%), and cost of sales down, “due to platform and supply chain efficiencies”.
Current trading/outlook: mostly positive.
Second half of the year has started well, and at this stage we expect H2 revenue to exceed H1.
Gross profit margin to date remains close to that achieved in H1, and well above recent historic levels.
Despite a difficult economic environment in some key markets, and challenging conditions for media owners and advertisers, we believe System1 can continue to grow profitably by gaining market share from large incumbents that we believe have less predictive products.
CEO comment proudly mentions the large number of new clients, which include “a global top three advertiser, a leading global breakfast foods company, a leading European car manufacturer, a leading budget airline, a 'big four' UK supermarket, and a multinational consumer goods company.”
Estimates: Canaccord Genuity have upgraded their adj. PBT forecast for the current year from £1m to £1.6m, thanks to higher expected margins and operational gearing. The revenue estimate is nudged only slightly higher to £26.9m.
Graham’s view
I’ve been amber on this one for some time, and I’m inclined to maintain this stance for now.
However, the share price reaction this morning suggests a great deal of interest in developments here:
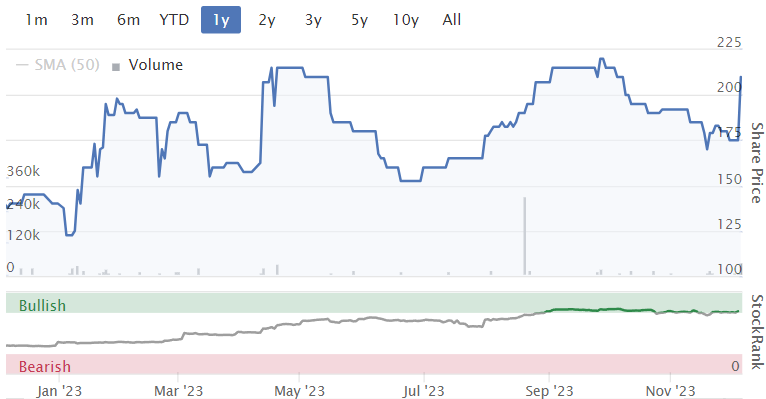
The most generous way to value this would be on adj. PBT and to treat it as a growth stock, with a growth multiple. With 27% revenue growth in H1, it might be possible to justify that.
The strong balance sheet is another factor here; cash of £6m means the “enterprise value” is only £21m, even after this morning’s gains.
Bear points: the company’s overall revenue profile has been uneven, as its business model has evolved:
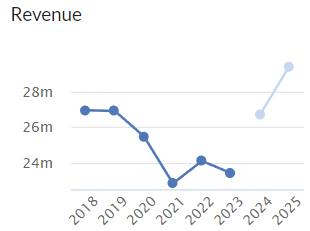
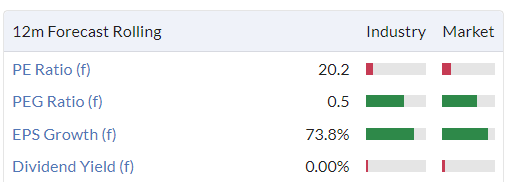
Also, there is “only” revenue growth of 10% expected for FY April 2025; not a bad result but I’m not sure that it would help to justify an above-average earnings multiple for the stock.
So for now, I’m inclined to think that this stock remains around fair value. But this morning’s H1 results were very good: hopefully this is a sign of more good things to come.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

101 comments
Agree. US in basket-case economic mess with unfeasibly large debt burden. Stock market holding up only because retail shareholding is very common and most people don't know much about the intrinsic value of any share they hold.
Think MS International (LON:MSI) report tomorrow which I hope will be interesting in a good way. Will be good to get more colour (well as much as the directors ever give) around the ‘Step change’ they mentioned in some of the recent defense contract win announcements and whether this is also accompanied with a bunch of other non disclosable smaller contracts.
MS International (LON:MSI)
Hi David, can I ask why you think they report tomorrow ?
I have been looking forward to the H1 2024 numbers with interest but couldn't find any publicised date. It is normally first or second week in December and on no particular day . Obviously there is nothing on their Investor Relations site.
MS International (LON:MSI) reported 8th last year 7th 2021. So could be Friday, even Monday
UK 10Y below 4% !! Dropping like a stone. Even US looks like it is heading below.
Should start to result in a bit of multiple re-rates.
Price of oil is at its lowest for sometime as well-recession looming?
Or already here maybe………. Market seems to be alluding to the need for significant rate cuts across the board, starting with Europe. UBS think the US will cut 275bps next year which definitely suggests recession as I can’t see FED doing that unless there is one.
My personal opinion is that everything will unravel…….. after the US presidential elections and the UK parliamentary elections.
Without hopefully sounding thick yiannos unraveling as in in recession finally arriving followed by interest rate cuts ?
Yes that’s my personal opinion. US cannot manage this enormous debt on the current interest rates.
Thanks Yiannos I went to a JP Morgan seminar a few weeks back and they anticipate that the US entire tax take won't be enough to pay the interest on the debt by 2035 and that's modelled at lower rates than now.
I agree with you theres only three ways out default (unlikely), some kind of global debt reset where loads of debt is netted off against different countries, or most likely its rates back down to near zero as soon as possible and QE to infinity.
It is worrying to see Trump is ahead of Biden in the pols in my opinion the fella is the greatest danger to the free world on the planet, but the general US population see Biden as too old.
Here's an interesting/terrifying stat the US deficit is increasing at $200 million dollars per hour I suppose when you owe $33 trillion that's par for the course lord knows where it all eventually end's up but the Fed do seem to have the best left foot in the business when it comes to can kicking.
I agree with you theres only three ways out default (unlikely), some kind of global debt reset where loads of debt is netted off against different countries, or most likely its rates back down to near zero as soon as possible and QE to infinity.
what about the possibility of facing the facts that once debt gets to a certain level - action will be taken to live within ones means or limit future rises in real terms. Is this not what happened when truss took over - a plan that clearly was a step to far - markets reacted and plans were scaled back. I wont disagree debt is scary high but does it really the case that it will never be at least managed to not get worse?
It is a possibility but I think the problem western governments face is since all the free money handed out during covid the populations mindset has changed to more like the french.
Where if you try to mess/cut benefits there's either civil unrest or mass strikes no easy answers, but I do think they will aim to have rates back down as soon as it looks like inflation is licked as the most palatable option.
Look at Hunt's budget tax cuts despite our dire debt situation.
The Tories know they are beaten so I wouldn't be surprised if Hunt engineers more cuts in the next budget and then leaves labour to pick up the resulting mess. To be fair though no different to what labour have done to the Tories in the past when they knew writing was on the wall.
To be fair though no different to what labour have done to the Tories in the past when they knew writing was on the wall.
Yeppers I seem to remember some snarky note having left saying u r f or summit similar.
I don’t have any answers here but the reality is in the real world it’s highly likely we will cut our cloth to make ends meet as is needed - one can default to it being the end of the world but as anyone 50+ knows life was all hard work back then the reality nowadays I suspect is that when needs must most peeps will buckle down and get on with rhetoric everyday life of grafting
Maybe their preferred solution (problem, reaction, solution) to the massive government debt will be the digital currencies that they keep talking about, which will be a disaster for the personal freedom/ privacy etc of their citizens.
CME FedWatch Tool is currently showing 1.25% which may be more realstic but I do hope its 2.75% which would enable the UK to more easily cut rates too.
Well it would be nice to see some Investment Trusts (REITs, alternatives, infrastructure) start to move back up as all the 'qualified' commentators say rising gilt yields a large part of the problem in them moving to massive discounts vs. NAV. As ever they appear to be wrong as there isn't any significant upward trend as yet!
ACounsell.
Surely a lot of REITS and Infrastructure Trusts have started to move up and some so much so that the great buy opportunity (covered either here or on Investment Trust threads here almost at the bottom) could well have gone.
e.g these Commercial Property Trusts:-
Tritax EuroBox (LON:EBOX) up nearly 40% from 44p to 61p and dividend now 7% instead of even better 9% at the low. Described in a previous post at 45p as ludicrously oversold when on discount over 40%.
Supermarket Income REIT (LON:SUPR) up 15% from 70p to 81p. Dividend now down to 7.4%.
Tritax Big Box REIT (LON:BBOX) up about 30% from 124p to 162p.
Alternative Income REIT (LON:AIRE) up 20% from 56p to 68p. They recently increased the dividend and it’s still 9% even after that rise.
I hold those, except the lower dividend paying BBOX.
I don’t hold any Infrastructure Trusts but see that Ecofin Global Utilities and Infrastructure Trust (LON:EGL) is up 20% from 145p to 175p. Ian Cowie (Sunday Times) frequently seems to plug this one.
HICL Infrastructure (LON:HICL) is up from 117p to 134p and
3i Infrastructure (LON:3IN) is up from 280p to 321p.
Bit there are still plenty of Invrstment Trusts that are still at extreme bargain prices that surely won’t last for ever, including the 5 in my post this morning, and others mentioned in replies. Those replies include further info on both Pershing Square Holdings (LON:PSH) and Caledonia Investments (LON:CLDN)
It’s good to see increasing interest in Investment Trusts and at opportune time to be checking them out. There are threads on Investment Trusts here, including one with a superb post from Charles Mitchell on Private Equity Trusts. That’s another sector with very successful Trusts on unusually big discounts, I have held Harbourvest Global Private Equity (LON:HVPE) now on 44% discount and Oakley Capital Investments on 35% discount for a few years. Oakley Capital Investments (LON:OCI) has doubled…yet is on 35% discount. Both are covered in Charles Mitchell’s detailed Private Equity post.
Hi Ken Mitchell
Appreciate your posting of information/ideas on Investment Trusts and I do partly agree that there are signs of life in the REITs/Alternatives/Infrastructure sector. I hold a number you mention Supermarket Income REIT (LON:SUPR), HICL Infrastructure (LON:HICL), Harbourvest Global Private Equity (LON:HVPE. In addition I also hold Renewables Infrastructure (LON:TRIG), Warehouse Reit (LON:WHR), Gore Street Energy Storage Fund (LON:GSF), Impact Healthcare REIT (LON:IHR), Bluefield Solar Income Fund (LON:BSIF). All are sitting at significant discounts with share prices well down from my purchase cost - a factor partly alleviated by the decent dividend yields on offer even at my original buy price. Even worse are the ITs I hold which may not survive the de-rating of the sector, namely abrdn European Logistics Income (LON:ASLI) (which surely is in the same area as Tritax EuroBox (LON:EBOX) , Digital 9 Infrastructure (LON:DGI9) (should have chosen Cordiant Digital Infrastructure (LON:CORD) instead!) and Asian Energy Impact Trust (LON:AEIT) (a true catastrophe!). There are some special circumstances with these three but all were bought in sectors with apparently solid growth opportunities and decent yield potential. I also hold some growth focused ITs but they are still suffering (e.g Baillie Gifford Us Growth Trust (LON:USA) and Biotech Growth Trust (LON:BIOG)) from the impact of 'higher for longer' interest rates. If this really isn't the likely scenario going forward then I would hope to see them re-rate pretty quickly. We shall see!
ACounsell
Doesn’t the disappointing performance of your Investment Trusts reflect the same thing as why so many holding small cap shares have had a bad year? I.e a lot of those shares have fallen heavily and got way oversold. Unlucky if they were bought ahead of those falls. That’s a key reason. I.e Another unfortunate timing. Anyone who bought Investment Trusts ahead of the big falls and ever widening discounts this year is likely to be under water still. It’s not a reflection on the quality of the Trusts you hold. Ditto very often with good quality small companies bought ahead of the recent big falls. E.g look at On Beach group (LON:OTB) . Just 90p a month or so ago. Good update this week and share is up 60% to 150p.
My preferred tactic for buying shares and Trusts is to buy the big dips and look to hold long term unless news justifies selling. So most of my Investment Trusts were bought either in the previous big dip in 2020 covid year, or more recently in the current dip. Hence most of mine are doing well and with some very big dividends providing copious income too.
Of yours and this is only fwiw and not a strongly held opinion, I’m now wary of some of the green type Trusts partly because it’s sometimes hard to see what they are investing in, along with uncertainty about things like battery storage. Are there big profits to be made from that. So apart from Foresight Solar Fund (LON:FSFL) I don’t now hold any others.
Also I cut a loss on DG19 at 47p after their first awful update. I’m ruthless with any share or Investment Trust I hold that issues a profits warning or disappointing update. My portfolio performance improved big time once doing that and running the winners, and only holding losers if newsflow justifies it.
Some 'STOCKing filler' Xmas reading material for 'crack' investors.
Love Market Wizards, great book
Is that a photo from your library Paul.
Where's Zulu and Beyond Zulu by Jim Slater, thought that would be essential reading.
The Psychology of Money by Morgan Housel is another classic.
Supreme (LON:SUP) down 10% on read across from British American Tobacco (LON:BATS). Taken the opportunity to open position
Supreme (LON:SUP)
I don't think that the drop is so much a read-across from BATS as the pronouncement today by the shadow Health Secretary. He thinks the Australian action (making vapes prescription only) is wonderful. Has nobody told him that as a result Australia is one of the few countries where smoking is increasing?
That shows adult smoking rate but youth rate is also increasing there.
https://www.dailymail.co.uk/he...
Has nobody told him that as a result Australia is one of the few countries where smoking is increasing?
facts are smoking was decreasing before vaping came along if vaping was limited/banned i would see no reason long term that smoking wouldnt continue to decline "long term". I would would expect a short term spike in smoking if vaping was banned/limited as one addictive item is pretty obviously temporarily going to replace another but tat doesnt mean that there wont be a later decline. The graph posted may suggest otherwise but i personally dont think vaping is the solution that many make it out to be - its just another easy form of addition that very obviously isnt good for ones health - how bad it is for ones health may be unknown but certainly aint zero imho.
Not really - smoking has a very high healthcare and benefits cost. High %age of vapers apparently say they would likely return to smoking if vaping were banned. So there is a very real cost and given current strain on NHS that’s unpalatable.
What happens in these scenarios where you ban or restrict is that black markets spring up. As we already know these black market products are often contaminated and dangerous. So vaping wouldn’t go away - it would just be criminally led and far more hazardous to health. You think the Police force is equipped to enforce any of this? Dealers would sit outside schools selling it at inflated prices making it even more cool to teenagers. The people that would lose out most are those that use it to avoid smoking.
Far better is to make it regulated but readily available and relatively cheap but unappealing….not cool. Someone like Supreme (LON:SUP) has already taken big steps with removal of flavours, plain packaging, managing where in the stores it can be displayed, age check policies on all their products. They also have super high quality control and test literally every batch, so at least you know what you are getting. I think that proactive approach (well ahead of any regulation) is actually to be applauded. Whilst the villagers cry ‘burn the witch’ and get their pitchforks ready and politicians pander to the crowd preparing the dunking stool Supreme (LON:SUP) are actually tackling the problem - which is not vaping itself but making it less cool.
This is far from a simple good versus bad argument despite the rhetoric. Politicians say things they think are popular with the demographic they are trying to appeal to at the time and not because it makes any sense. If the bandwagon and media are heading in a certain direction you can bet the opposition party will be hurling themselves at it irrespective of whether they would apply any of it if actually elected.
i think the decline in smoking destroys this argument there has been a real lonmg term decline in smoking whether vaping exists or not. The facts are that smoking % is well below what it used to be and its always going to be genrational thing.
allowing free for all in vaping has simply started another smoking issue that will affect peoples health potentially loing term - unfortunately that genie is out of the bottle but the least wort thing to do is try and put it back in the bottle to make clear like smoking its bad for your health - hopefully if its made harder over time the non smoking related evaping epedemic will decline over time even though the addicts will deffo go black market to some degree.
Thats just my view - i do see where the counter argument is coming from i just feel the "vaping epedimic as cure for smoking " was totaly unecessary. I can guarantee at some stage whether legal or not there will be many peoples health who is damaged by someone "in the chain" taking shortcuts (at least if its not legally condoned its their own fault if peeps partake) - similar to issues that happened in us. I think thats unavoidable unfortunately - i pity the fools who dont see the obvious damage they are doing to themselves.
rmilaree you’re talking total tosh and obviously haven’t researched the subject - vaping has everything to do with the declining smoking rates. And just so you know vapers no longer emit smoke as there is no smoke.
vaping has everything to do with the declining smoking rates.
you can believe whatever you want but the downtrend in smoking has been clear for many many years t well before vaping was anything like popular. I wont deny that vaping may have helped some quit but imho its clear the smoking downtrend existed before and would have continued to exist had vaping not become so popolar.
Are you denying there was a clear downtrend in smoking before vaping became popular?
if you are agreeing there was already a downtrend in smoking before vaping really became popular do you think that downtrend would have stopped had vaping not come along?
the fact its popular to switch and thats not a bad thing doesnt mean that smoking downtrend would not have continued anyway without that help.
Xaar (LON:XAR) - I really should take notice of Graham Neary (see SCVR report on 29th November) and Stockopedia views on profit warnings. Thought I would give it a week to let the dust settle and perhaps see bit of recovery from bottom but no - down another 45% in a week! Now probably too far gone to sell and it joins my 80% down club. Now only an 'option' (as Graham described it) on any recovery at some far distant point in the future.
Sorry to hear that, ACounsell. I hope your overall portfolio is doing ok despite this! G
Lawrence Hulse / Onward
Had a listen to the podcast thing yesterday someone put link to in comments .
He used to work under Richard Staveley at Gresham strategic which became Rockwood .
He has set up Onward fund under Dowgate .
Some holdings in sone pretty small recovery plays
React
Angling Direct
RBG
Transense (Harwood own too)
Comptoir
Restore (Harwood own too)
Not sure if any of those float my boat .
RBG has fallen off a cliff and I was a huge critic of the management for awarding themselves ludicrous amounts of zero value shares with no performance r criteria other than driving to work . Hopefully those muppets are long gone .
Comptoir seems to be an upmarket kebab shop albeit one with almost as much cash in the bank than market cap ?
Restore I’m buying so agreed on that
Angling direct looks ok but share price has already corrected so too late I think
Transense I’ve no idea on looks a bit hard for a simpleton like me to understand what they are making .
Just waffling he’s a young guy might be worth seeing how he gets on .
Just in case of interest to anyone, the following five Investment Trusts all look well worth checking out.
Henderson Far East Income (LON:HFEL) 203p.
Awful performance for a good while now, but at last the share price has stopped falling. Recent update was frank about the failings and the Manager has gone. Dividend yield is 11.5% and it’s been increased for multiple years and they are determined to keep to that annual (albeit tiny now) increase policy. Good one to lock away.
International Biotechnology Trust (LON:IBT) 596p.
Biotech sector has boom and bust spells. The bust spell has now lasted around 3 years and signs of the worst bring over with share well up from 546p low. IBT with 5.3% dividend yield and at 10% discount is a good way to play the sector.
BlackRock World Mining Trust (LON:BRWM) 540p.
I posted on Sunday why 2024 could be a very good year for Mining sector on a separate thread. BRWM with the bulk of their portfolio in major Miners like Glencore (LON:GLEN) (9.7% of their portfolio) BHP (LON:BHP) (8.5%) Rio Tinto (LON:RIO) 8% etc is a good way to play it. Discount is modest at 4.5% but useful 7% dividend yield even in weak year like this one and much higher in good years like 2021 and 2022. Share is near the year low of 530p.
Pershing Square Holdings (LON:PSH) £31.50.
This Trust has a superb record and even this very bad year for the Investment Trust sector where discounts are at near record levels, PSH is up 12%. Over 5 years it’s up 194%. Yet it’s trading at an extraordinary 34% discount to NAV. If PSH was an open ended fund investors would have to pay that full £59.65 NAV. So it’s a Stunning bargain price at £31.50 though off the even more stunning year low of just £27.
Caledonia Investments (LON:CLDN) £35.50
Another excellent performer at a bonkers too wide discount of 32%. Share price is still down 6% this year but up 43% 3 years and 143% 5 years.
Best site for checking out all Investment Trusts is in my opinion the official trade body site for Investment Trusts AIC. This link gets traders to Pershing Square Holdings (LON:PSH) .
https://www.theaic.co.uk/aic/f...
Just click on the red PSH heading to bring up a wealth of info and headings.
Also very good is Trustnet:-
https://www.trustnet.com/fund/...
Interesting ideas. I hold Caledonia and Pershing Square- the latter is excellent value given it's long term growth. Just boughtBlackRock Frontiers Investment Trust (LON:BRFI) , been following a while and just watched a presentation by the lead manager- interesting person. Recording should be available on Research Tree later I guess- not there yet https://www.research-tree.com/...
Long term holder of #CLDN. Very well managed and have continuous delivered value and yes the discount is crazy.
Pershing Square Holdings (LON:PSH) is one of the biggest conundrums out there. A fantastic performer from the time Bill Ackman decided to stop shorting and become a long term investor who makes occasional assymetric bets. The notionally very high fees put a lot of people off, but they are performance fees, and only get paid if he does well. The fund only holds about 10 investments and some are true global giants - Alphabet (NSQ:GOOGL) and Universal Music NV (AMS:UMG) being the standouts. There is always talk that he might find a way of becoming a US trading company like Berkshire Hathaway (NYQ:BRK.A) and eradicating the discount overnight. In the meantime you can be pretty confident that he will outperform the US indices over most timeframes and that will do me.
Agree a lot of the discounts make no sense at all. I've invested in ITs for years, and I think what tends to happen is that certain trusts (often for no particular reason) get stuck on a certain discount and this then becomes entrenched - this can last for years and it will usually need some sort of trigger to remove the discount. In the case of Pershing Square Holdings (LON:PSH) this could be some sort of corporate activity or a move to a US listing.
Restore
Bizarre anomaly just happened
I always check buy and sell and stock available
Could sell at 213.5
Could buy at 211
Scratched head then thought oh well what the hell
Sold 10k at 213.50 , then bought 20k at 2.11
probably worth 100 quid or so but nevertheless feels a bit of a naughty little win .
And they say there’s no such thing as a free lunch
Used to be called a "Backwardation" when the stock market floor existed. You had to advise the Jobbers.
Non digital arbitrage
Speaking to a Land Rover salesman yesterday. He said 2nd Hand prices are normalising, and says they are very busy with back- to-back appointments for sales. He is quite surprised compared to the market gloomy headlines.
Still a hugely popular product/brand. There are not top of the stolen league for no reason.
Land Rover are an utterly unreliable brand though. We got rid of our Range Rovers and replaced them with Toyota land cruisers .... never had a problem. This was in the Saudi desert. Now on the farm in the Highlands I would never look at buying land rover and I don't know anyone around here who would either. Mud or sand .... sadly LR is a poor substitute for a proper reliable working vehicle.
Maybe for Land Rovers... but overall, second hand prices of cars in the nearly new segment (1-5 years) and where its outside the cheap no-frills segment, have been plummeting.
I'm avoiding Motorpoint (LON:MOTR) who probably is being clobbered at the moment on margins. They are wafer thin already, and when the decline MoM is in the single digit percentages, they must be losing money on some cars!
In the medium term, this extra stock of cars coming into the nearly new segment, plus the resetting of prices to a more affordable level, will drive increasing demand for this segment again. So we should see a whipsaw with Motorpoint in about 12 months!
Jorge Cosmen Non-Independent Deputy Chairman of Mobico (LON:MCG) (national Express) just reported buying another 1% of the company, he has 13% now, not too shabby.
There are now reports that TUI want to delist from the London Stock Exchange and move to Germany - honestly there won't be any companies left at this rate!
Is there a benefit for them to list on an EU market as apposed to a non EU.
You do wonder at some point if there's going to be some mega merger of the Stock exchanges at some point as clearly there's little incentive to be on the smaller ones these days
You can't blame TUI AG (LON:TUI) for wanting to take their ball back home, especially since the UK is no longer in the EU plus there is the so-high corporation tax to be considered.
I don't hold TUI but do hold Smurfit Kappa (LON:SKG) which did exactly the same thing a couple of months ago.
I agree, Brexit means our stock market will becomes less "international". I won't be surprised if we see a slow drip of foreign, primary listings leaving the UK, like CRH (LON:CRH) leaving earlier this year and Flutter Entertainment (LON:FLTR) is also rumoured to delist.
Hopefully the Edinburgh reforms will ignite more listings in the UK: https://www.gov.uk/government/...
I've stopped adding any new money to the UK Markets due to the lack of choice in the market. I wouldn't take anything out at this stage as I feel there are a lot of companies at very attractive ratios but you have to worry about the long term viability of the market given what we are seeing.
What tools are you using to find markets outside the UK to invest in? Do you recommend the stocko app with bolt on options for US and other countries or are you using an alternative? Ta
I am mainly doing ETFs outside of the UK as I don't have the same knowledge or capacity to monitor them. I am quite heavy into India and the Russel 2000 as that's got whacked as much as the FTSE 250 has. I do a few smaller Tech companies that I get tips from an ex broker friend on the US market.
The Russel 2000 can be a poor index to use an ETF on. You might find this research interesting:
https://verdadcap.com/archive/...
I still invest in the UK because, as per my post yesterday in the SCVR, UK Small Cap momentum produces extraordinary alpha so there is plenty of money to be made in our domestic markets. It also means a portion of my portfolio isn't subject to FX risks.
However, I completely understand why investors are ditching the UK, post Brexit. The U.S and EU are getting inflation under control much faster than the UK and we now have structural economic problems in almost every industry. We will see stronger economic growth elsewhere, particularly in the U.S and so I think we shall see stock prices do very well across the pond!
Fx works both ways. The £ has fallen since Brexit against the US$ and many other currencies. So actually investing in £s you have lost money. There is risk if you only hold £ shares, I see the £ as more risky than the $ or Euro. By investing in foreign stocks you are spreading the risk. The advantage of UK shares is dividend tax.
Hopefully the Edinburgh reforms will ignite more listings in the UK: https://www.gov.uk/government/...
I hope so as anecdotally access to capital is a perpetual complaint of SMEs
However suspect not as capital markets tend to follow business (to europe) Rather than the other way round.
No chance of getting a sun bed by the pool now!
TUI AG (LON:TUI) shouldn’t have been allowed to be listed anywhere.
Filtronic (LON:FTC) rising. Another where Harwood have a stake.
I note a number of interviews with respected investors recently start "UK equities are really cheap and we like these shares". In no way do I malign respected investors their input is always most useful. My concern is the shares they mention seem to step up almost immediately. This is great for their performance but I urge other investors DYOR. Incidentally I saw Chris Harwood at Mello, his views on the broader market were fascinating.
Ten Entertainment (LON:TEG) Now it's beginning to feel a lot like Christmas :) This was a core holding for me and in a way sorry to see it go because it has been a painless exercise being a shareholder but kudos to Christopher Mills again, how well connected he must be! Well done fellow holders, i'm a happy UK small cap investor today.
Ten Entertainment (LON:TEG) - damn!! Another undervalued business taken out for a modest valuation by PE. Real shame as even a re-rating to peers would have achieved north of that price. I had hoped for 500p or more from this share. Oh well.
Still, I bought a couple of years back at around 150p so shouldn’t complain too much and there is plenty to recycle cash into I guess.
Ten Entertainment (LON:TEG)
Ditto here - nopt particualrly in a hurry to sell this one as fundamentally the business is sojn d- preumium is probably enough for it to be adone deal unless someone offers more which i think is slightly unlikely
As you say nice time to get some cash proceeds to reinvest elsewhere.
Must be a reasonable chance of another bid for Ten Entertainment (LON:TEG) (here's hoping) as at 412 only on a forward pe 12x.
Mixed emotions for me!
£TEN
The answer is we dont know - i would have thought its less likely than likely as consumer facing bowling is pretty niche - i would agree its not impossible though. The main candidate would probably be holywood bowl but the uplift in shareprice may be such that they would be paying more to add sites than their own sites are value at by the market - they would have some obvious efficiency savings and it might be deemed worthwile defensively if they thought new owners were going to start a price war or aggresively expand onto their turf - the two have co existed quite nicely up till now. Yes possible but to me chances probably less than 25% - thats pure guesswork on my part though. Would be nice if sale price was upped to 450p that does have a nice round ring to it.
Well done! Saw BOWL got a bit of a lift on a read across. No doubt these takeovers will keep coming whilst UK stocks remain on the floor.
Why the offer for Ten Entertainment (LON:TEG)? Part of the reason must be that it's a Harwood holding and it seems to me they are traders, not long-term holders. But here's a possible reason why they have been able to persuade Lazards to recommend the offer and get 39% acceptance. From the RNS: In addition, the TEG Directors realise that TEG shares have consistently traded at a discounted valuation multiple to its core peers in the public markets. Further, the TEG Directors recognise that the market for TEG shares is relatively illiquid, making it challenging for TEG Shareholders to monetise their holdings in the Company should they so wish.
And TUI AG (LON:TUI) are citing liquidity as a big reason for moving to Frankfurt.
This is serious. If things don't imporve we might not have a decent sized stock market in 10 years time.
Meanwhile it makes increasing sense to put a decent chunk of any portfolio into takeover prospects.
Hostmore (LON:MORE) announcement re the FD would appear to be another small step forward in the path to redemption. Would seem to me to be a huge hospital pass to give him stock with a bonus consuming tax bill only to wipe him out in a discounted fund raise. Time will tell obviously and the whole thing hinges on the £10m FCF forecast … fingers crossed. (I own).
Hostmore (LON:MORE) is interesting. Risky but CEO seems to be doing the right things and stock could happily be 4 or 5* the price if they can hit the cash flow the Chairman has been talking about. Debt coming down and banks supportive suggest equity dilution could be avoided/limited. Tempted to take a small position for possibility of outsized return but can’t decide if I should wait for trading update post Xmas first.
Hostmore (LON:MORE)
I would say hostmore is deffo a red flag binary type outcome share - anyone buying here should be happy losing their shirt if things dont work out - facts are they expect buisness to be loss making and there is debt - so the fact they are not investing and trying to pay down debt as priority doesnt mean the fundamentals are anything other than woeful at present - heyho at present thye expect to make money next year. I would agree the flipside of possible 1005 losses is that this could easily multi bag if the turnaround works so i am not saying this is a bad investment - just face facts here that although it may look cheap there is imho zero downside protection.
If one is wanting to invest here please do read the customer reviews on trustpilot-** i would like to think that ata minimum this company would get the basics right and provide decent customer experience
https://uk.trustpilot.com/revi...
** i know trustpilot reviews probably dont reflect the real customer experience - but facts are peeps will look at trustpilot and avoid eating there.
Definitely risky - it’s another Harwood stake build. Rockwood put 2% of NAV into Hostmore (LON:MORE) so meaningful but clearly not betting the ranch either. They know the new Chairman very well and he has a very good track record.
Fundamentally this is a brand play but if they get it wrong then clearly there is little downside protection so any position I take will be sized accordingly.
Trustpilot is a waste of time imo. If you pay/subscribe they will help ensure you get lots of reviews but if you don’t then you just get the usual 1* complaints and 5* disciples. Most people don’t bother with it and TGI Fridays is such a well known brand in the UK market no one is going on trustpilot to decide whether to go there.
Hostmore (LON:MORE)
no one is going on trustpilot to decide whether to go there.
i would disagree and say that trustpilot wil put some people off - i dont want to over egg it though would agree it would perhapsa not be material %. One thing it is though is bad impression of buisness that is out there in the public domain. No biggie though dont think wetherspoons reviews are any better and i would say that genrally service in JDW isnt terrible for what you pay.
Hostmore (LON:MORE)
I wouldn't use Trustpilot as I find its not always the best indicator. If it was, I would never hire a car from anyone! They all get slated. I would use Tripadvisor for a restaurant though. You can look at each restaurant or scan down the list to get an idea of where they score overall. Some restaurants score better than others
I would not use Tripadvisor for restaurants, so many fake reviews. You read about the fake restaurant in London that got to number 1. The guy who did it, used to write fake reviews. Abroad they also have many good ones missing. I tend to avoid TA restaurants in Asia, as they tend to cater to tourists, prices are much higher and the taste is dumbed down.Too many reviews are based on about burgers. TA reviews don't seem so popular now. Google I think is better, as used more by locals.
You have it wrong here as McBride (LON:MCB)
You have to distinguish the debt that cannot be paid and the debt that CAN be paid (steps taken here by some very clever people that control the management of the company).
Hostmore (LON:MORE)
You have it wrong here
You have to distinguish the debt that cannot be paid and the debt that CAN be paid
Nope you have it wrong - i never said debt couldnt be repaid - i would agree they possibly can repay debt even whilst making losses. Its easy if you cut all essential spend to the bone to enhance cashflow short term - normally under investing is to the detriment of the buisness loing term.
The management here are that clever that they cant even turn a profit not a great advert for their capabilities - albeit they are where they are ref tough outlook for teh sector.
Note even if debt can be repaid now they dont have much margin of safety if outlook worsens starting from point of being lossmaking now ! Hopefuly ref inflation and cost pressures the worst is over though.
Hostmore (LON:MORE)
It’s very rare in the stock match to across to a company that its EBITDA and market cap match and this is always an investment opportunity of a lifetime.
Here to match the price has to go to 30p!
Good luck with your investments.
Thanks
I couldn’t wait so I have bought the last three weeks.
Redde Northgate (LON:REDD) Results look OK to me, I hold. Struggling to buy right hand drive vans; supply is clearly stronger in Europe. Yet another negative impact of Brexit. There is a lot to digest and depreciation rates are part of the puzzle. I get the impression that the core business is diversifying while van resale prices are high. This makes sense. Hopefully interest rates will fall when van prices fall, thus counterbalancing each other. I'm convinced that Central Banks have overtightened in response to external inflation. I continue to hold, but I'm not a big fan of a Halfords merger.
Redde Northgate (LON:REDD) Seems way undervalued. An annual underlying eps exceeding 65p with a strong dividend and a lot of tangible asset value (far exceeding debt) shouldn’t be trading on a PER of just over 5 in my view.
Agreed, this one will get taken out at these levels at some point. Very stable and strong cash flows. Continues to be a long term holding of mine
Redde Northgate (LON:REDD)
Seems way undervalued
Yep strongly agree this is possibly my personal favourite share at present (not a company i would like to go massively overweight in though i msut say). Main attraction here that they seem to keep delivering operatioanlly wise and seem to have a clear simple plan. Its easy to focus on the fact they have massively benefited ref residual van availablity issues and ignore thn eprogress they have ben making ref commercial deals. supply constraints are a two way issue two in that they need new vans to keep customers happy and its not great that supply is short in that regard.
Evidence of their good progress ref long term commercial contracts is confirmed here - so deffo morphing into a b2b business where customers have a need for their products.
Over 75% of Redde revenues were generated from multi-year contracts with more than 12 months to run
On then flipside soem may say they could struggle if there was excess supply out there - i still think its logical for larger comapnies to outsource fleet supply and maintenance for obvious reasons.
Some main moan about the net debt here its up from 694 mill to 755 mill - they have £250 mil of investment in new fleet this year and net asset value per share has continued to climb now 452p per share compared to 413p 12 months ago. Although debt is up debt compared to fleet size is unchanged.
They are still expanding and thats also consuming cash - at some stage though as investment slows i would expect free cashflow would mirror profits (and some hopefully)
My morning smallcap tweet: Reverting to hype
Ilika (LON:IKA) Ten Entertainment (LON:TEG) Various Eateries (LON:VARE) Quadrise (LON:QED) Mirriad Advertising (LON:MIRI) Kakuzi (LON:KAKU) System1 (LON:SYS1) Redde Northgate (LON:REDD), Likewise (LON:LIKE)
◄Ilika (IKA)► Goliath battery prototype achieves lithium-ion energy density parity of 250 Wh/kg. CEO coughs up cliches: "This key achievement in our cutting-edge Goliath battery re-emphasizes [sic] the strength of our solution and further demonstrates Ilika's differentiation as we strive for a more sustainable future". Shame he can't spell. [SP=42.8 Cap=68m]
◄Ten Entertainment (TEG)► 412.5p rec offer, a 33% premium. [SP=310 Cap=212m]
◄Various Eateries (VARE)► £10m placing at 25p, a 4% discount (but 9% on SP before co proposed it yesterday), for working cap and expansion. Also d4e at 25p. [SP=25.77 Cap=23m]
◄Quadrise (QED)► yet another update on test results. [SP=2.49 Cap=39m]
◄Mirriad Advertising (MIRI)► two new master service agreements including a prominent US TV network. "In-content sales proactively generated by Mirriad's partners in the ten months to October 2023 have grown by 53%." [SP=2.11 Cap=10m]
◄Kakuzi (KAKU)► the Kenyan agrico refreshingly offers a "Profit Warning Announcement". FY23 net earnings may be at least 25% down YoY. Blames weak Macadamia demand. [SP=0 Cap=NA]
◄System1 (SYS1)► H1-Sep in line. Outlook - "H1 has started well, and at this stage we expect H2 revenue to exceed H1. Gross profit margin to date remains close to that achieved in H1, and well above recent historic levels". [SP=175 Cap=22m]
◄Redde Northgate (REDD)► H1-Oct. Guides FY modestly ahead of market consensus. [SP=358 Cap=821m]. I hold.
In line: LIKE
´Reverting to hype´.. LOL.
Ilika .. ´Goliath battery re-emphasizes [sic] the strength of our solution´. Clearly the CEO´s already thinking about the US market.
I remain completely unable to work out where Ilika (LON:IKA) (I don’t hold) stands in the non-lithium solid state battery market. If Ilika, as it insists, actually has a significant technological card to play then the Uk has one of the critical future tech players and we should be backing it with everything we can throw at it from private and public funds. IF…..
But every time I try to find non-Ilika based commentary on the market they are almost never mentioned, even in the non-lithium category. Does anyone on this board have enough knowledge to help us understand where to place the company, to help judge its prospects, especially in the face of some huge companies that are already in this field?
Nice result for Ten Entertainment (LON:TEG) holders this morning!
Well done holders - could never understand the big discount to Hollywood Bowl (LON:BOWL) Another good company leaves the market.
Another Harwood share taken over…
https://www.voxmarkets.co.uk/r...
Redde Northgate (LON:REDD) interims out this morning. Quite a lot to take in but the board” are confident of delivering earnings modestly ahead of market expectations “ . Interim dividend raised 10%.
Moonpig (LON:MOON) 6 month results appeared to come out in the afternoon yesterday. Seemed underwhelming to me, but would appreciate your thoughts especially with the read accross to Card Factory (LON:CARD)
Personally, i think they operate in different parts of the same sector (pricing, store approach etc), but i can see CARD being dragged down until they issue a TU or results.
Moon also had a very interesting comment
"Greetz revenue decreased by 9.8% year-on-year during H1 FY24 with a continued trajectory of improvement in trading across the period.". Not sure how that works !
Cockney Rebel wrote an interesting comparison between Moonpig (LON:MOON) and Card Factory (LON:CARD) (I hold) - it's a long piece, search for "95p" https://cockneyrebel.substack....
I hadn't seen that before. A great piece by CR and thanks for flagging it.
The yield on the US 10 year Treasury seems to be dropping like a stone.
Now down to 4.2% as investors predict that the Federal Reserve will cut interest rates faster than previously expected - ie in response to (hopefully) inflation falling below 3% in Q1'24.
For me what is interesting about this is it has occurred during a time the market was supposed to be worried about how the US would finance its deficit… now there is clearly scope to cut rates … but this is sort of what you would expect during higher for longer. The move has given a reprieve to the obvious victims in areas like REITs and housebuilders et al However Nov and Dec CPI data may fail to catalyse further moves since the numbers falling out of the data are already negative. It is most likely February when we get January data that the falling inflation trend resumes … so how the market takes todays data will be v important short term. The Dollar will be the tell.
Also, take not of Bond vol..at 127 it is ticking up...suggesting we are not out of the woods just yet....
RD without hopefully coming across as blowing smoke up your butt you seem pretty mustard on macro and asset classes any chance of expanding on where you see bond yields going from here (2 and 10 year) and could you expand on when some more large inflation figures should drop out of the rolling 12 months figures.
Regards Andrew
Will have a go but probably Friday now … Apol for some reason I thought it was coi today but actually next Tuesday.
Thanks RD
Yip, turns out high inflation was transitory after all.