Small Cap Value Report (Weds 6 July 2022) - AO., ZOO, CER, AGFX, RWA, NUM, PROC, TEG

Good morning from Paul & Graham.
Sorry we didn't get round to looking at Equals (LON:EQLS) or Quiz (LON:QUIZ) (I hold) yesterday, as both look interesting. We'll try to cover those later this week.
Agenda -
Paul's Section:
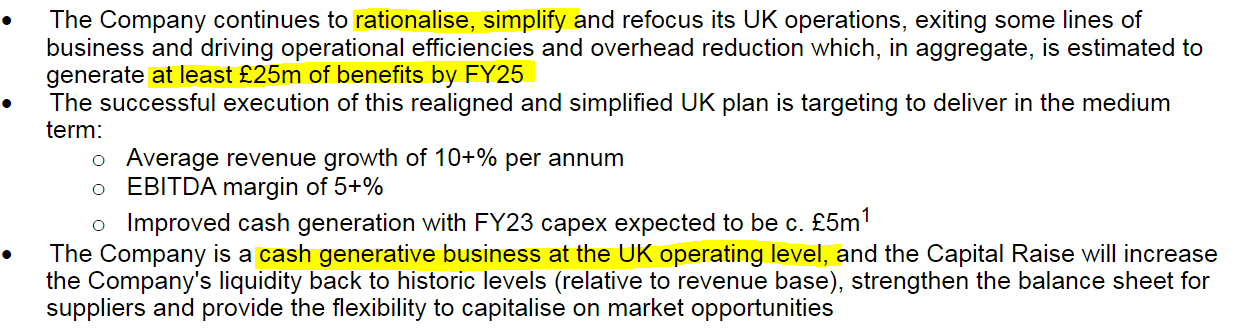
AO World (LON:AO.) (£225m) - Fundraise - a £40m placing is announced, at 43p. This should shore up the finances, and I like the simplified strategy, intending to strip out £25m of excess costs. Looks investable again, now that solvency risk has been addressed. Although I still don't think it's a good business.
Zoo Digital (LON:ZOO) (£92m) - [No section below] Results for FY 3/2022 were scheduled for release today, but instead there's an RNS saying the "auditors have been unable to meet the pre-agreed timetable...", and that "the company has been informed by its auditors that it should be in a position to sign its results for the year ended 31 March 2022 shortly". A webinar scheduled for today is being rescheduled for next week. This doesn't sound serious to me, based on what the company says, but it does introduce a little doubt.
Cerillion (LON:CER) (£289m) - [No section below] - "Major contract win worth £15m" - more good news from this excellent little company, which offers billing software for the telecoms sector. It's the increased size, and stickiness of contracts that really impresses. This one is for 10 years and "... helps to underpin existing market forecasts...", so not earth-shattering in itself, but still good news. This share looks expensive, but I think the superb track record, high margins, growth, and quality of contract wins, do justify the high price. Well done to holders, I think you're onto a winner here.
Robert Walters (LON:RWA) (£401m) - a positive Q2 update. Staffing companies are doing well, due to skills shortages. RWA is mainly international. Looks modestly priced, but it depends on your view of the economic outlook. If there's a deep & prolonged recession on the way, then staffing companies' profits could wilt.
Ten Entertainment (LON:TEG) - a fantastic trading update. Ahead of market expectations. Shares look cheap. Although I question whether this outstanding level of performance is sustainable, or benefiting from pent-up demand? Consumers still seem happy to spend on discretionary, leisure activities.
Graham's Section:
Argentex (LON:AGFX) (£90m) - Excellent revenue and profits growth at this forex broker. The company is growing internationally and developing its online platform, and these efforts are showing in improved financial results. The stock is beaten down but offers a dividend and a single-digit forward PE multiple to those who are willing to take the plunge. It is rare to have the opportunity to buy growth this cheaply - until the recent sell-off, that is!
Numis (LON:NUM) (£290m) [No section below] – Q3 update from this investment bank. The outlook for the full year remains in line with market expectations. These expectations are for full-year revenues of £145.8m and pre-tax profits of £25.1m. It’s a cyclical industry: these estimates are enormous reductions from the bumper year 2021, and are also worse than 2020. The decline in UK small-caps and mid-caps had, as you would expect, a big impact on trading revenues.
The good news is that the company sees a strong M&A pipeline and continues to focus its efforts on growing its M&A business. It will expand in the EU through a new Dublin office.
My view – I would get very interested in this if the stock price dipped closer to book value. For now, it retains a 55% premium over book, reflecting the company’s strong franchise and diversified product offering. I suspect that fair value is around current levels.
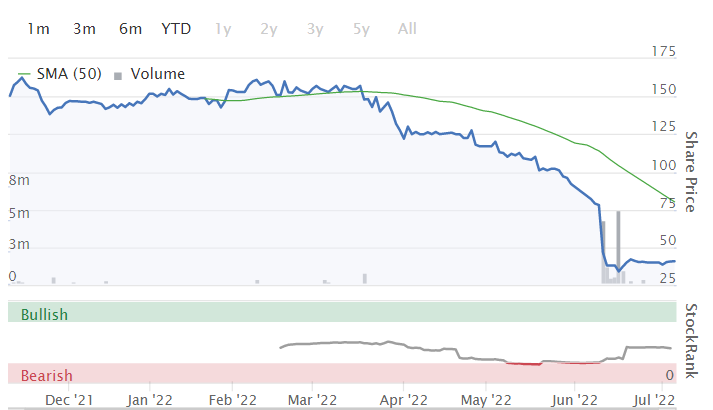
PROCOOK (LON:PROC) (£44m) - This recent listing (with a tiny free float) is down by 70% in less than a year. It’s a kitchenware brand with 55 stores and excellent reviews on Trustpilot. Unfortunately, shareholders have to put up with huge IPO-related employee bonuses, and profits for the new financial year are forecast to fall by up to 50% or even more (before the cost of employee bonuses). The company is reliant on borrowing facilities. I will certainly be giving this one a wide berth.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Paul’s Section:
AO World (LON:AO.)
47p (at close yesterday)
Market cap £225m
Proposed Placing & PrimaryBid Offer
As we suspected, AO needed to do a fundraise, we’ve been discussing this earlier this week, but I didn’t expect any announcement this quickly.
It takes a few weeks to organise a placing, and have all the meetings with the big investors who are invited to participate.
It seems crazy to me that the shares continue trading, in what is essentially a false market. The system needs to be reformed, so that shares are immediately suspended when a placing is decided upon, then a fast, electronic method, open to all, should be developed.
The current system is awful - cloak & dagger, with many people (probably hundreds) made insiders, so of course the news leaks out a bit, and insider trading goes on.
The Sunday Times article will have probably caused the placing price to be lowered, so there won't be many fans of them at AO HQ!
Key details-
Price 43p.
£40m (before fees) is being targeted.
Jefferies & Numis are the joint bookrunners.
Strategy - I like this bit, which sounds obvious, and common sense -
.
Medium-term targets -
o Average revenue growth of 10+% per annum
o EBITDA margin of 5+%
o Improved cash generation with FY23 capex expected to be c. £5m
Current trading - this largely reiterates what the company said in Monday’s response to market speculation -
Current trading and financial performance through the first quarter is materially in-line with the Board's expectations as set out in the trading statement of 29 April 2022.
The Board remains mindful of the ongoing volatile and challenging macroeconomic environment and continuing supply chain disruption.
The MDA [Paul: major domestic appliances] market is stabilising around levels seen in April and May 2022, underpinned by the distressed purchase model for white goods.
Consumer behaviour is evolving as the step change in online consumer buying trends varies by category and the Board will continue to monitor this closely and react as necessary.
Dilution - I can’t see any workings on dilution (possible it’s buried somewhere in the extensive text, which I’ve only skimmed through, due to time constraints), but we can work it out ourselves:
£40m (gross) at 43p per share is 93.0m new shares.
There are 479.5m existing shares, so that is enlargement of 19.4%, at a low price. I would describe that as unwelcome for existing holders, but not a disaster.
It’s better to hold a smaller percentage of £225m (market cap pre-placing), than a bigger percentage of nothing! (if it went into administration).
My opinion - I expect we’ll get a further announcement later today, because when placings are announced, they’re usually a done deal. Management are participating, apparently.
Overall, this is clearly a positive development, as it addresses concerns about liquidity and solvency.
I like the sound of the more focused strategy, to strip out costs. That’s the way companies in this sector need to be run - as efficiently as possible, and on a shoestring wherever possible. That’s what smaller rival Marks Electrical (LON:MRK) seems to do. Whereas in the past, I think mgt at AO World (LON:AO.) (especially the founder) got carried away with tech market mania, and chased revenues instead of profits. That era looks over now, and investors want profits & divis again, not growth and fancy talk. To be fair, it sounds like AO has realised that, and is restructuring accordingly.
Current forecast is for only c. breakeven for FY 3/2023, so unless it can beat that meaningfully, then it doesn’t interest me, especially in a consumer downturn.
For a more upbeat assessment, subscriber Bully15 posted this excellent comment yesterday, thanks for that.
I imagine shares are likely to bounce today on the placing news. There’s also likely to be some buying from short-covering.
Overall then, disaster averted, and hence my view on this share is now less negative, with the finances now a lot healthier once the placing completes. This might stop the rot, in terms of plunging share price. What a pity they didn't fix the roof when the sun was shining - which I suspect will be a sentiment felt in many boardrooms in the coming months.
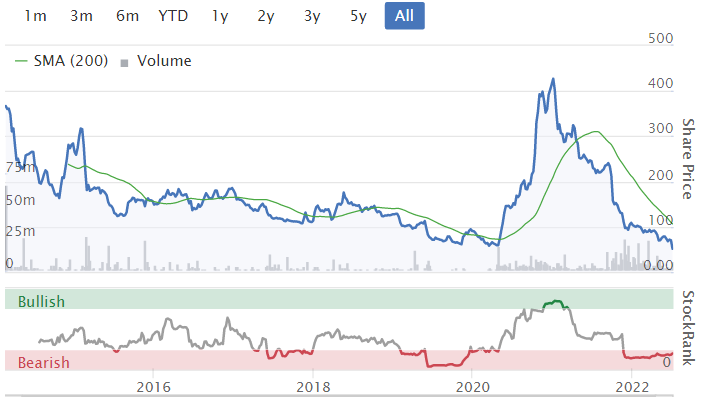
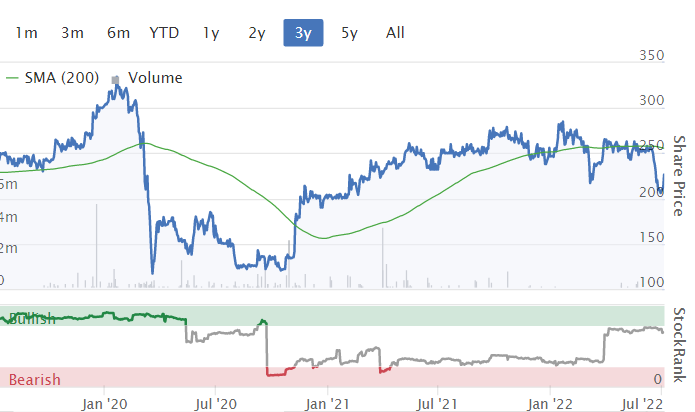
Here's the chart below for AO since it listed in 2014. Thanks to my friend Mark, who messaged me to say he'd dug out the original prospectus, and the founders cashed out £348m in the original float. Smart cookies!
.
Robert Walters (LON:RWA)
528p (up 4% at 08:30
Market cap £406m
We like this decent quality staffing business here at the SCVR, along with SThree (LON:STEM) - both of which look attractively cheap at the moment. No doubt that’s because investors are anticipating a recession. For the time being though, we have a very buoyant employment market, with shortages of good people in many sectors, and with wages going up. Ideal conditions for staffing companies, hence the sector generally posting good trading updates.
Q2 Trading Update - RECORD QUARTER
No subtlety here, with an RNS title that shouts from the rooftop about strong performance! Why not though, it certainly drew my attention to this update.
Main points -
Q2 net fee income up 26% (25% at constant currency) - impressive.
Slowest growth is +13% in the UK, which is only 18% of total revenues, so this is a mainly international group - could be useful, if you’re bearish on the UK economy/currency.
Net cash of £81.6m at end June 2022, down a fair bit from £112.8m a year earlier, but still very good.
Balance sheet - last reported at 31 Dec 2021 - it looks strong to me, with a healthy working capital position, and ample net cash. This group should be fine re solvency, even in a recession, so nothing to worry about here, and no need to dilute with a placing.
Profit guidance -
"This continued strong performance means that profit for the full year is now expected to be slightly ahead of current market expectations."
My opinion - note that RWA has increased its own headcount by 7%. No doubt it’s also having to pay higher salaries/bonuses to its own staff. Although I like the fact that in this sector, pay is variable, due to bonuses in the good times, and lower payouts when it’s quiet.
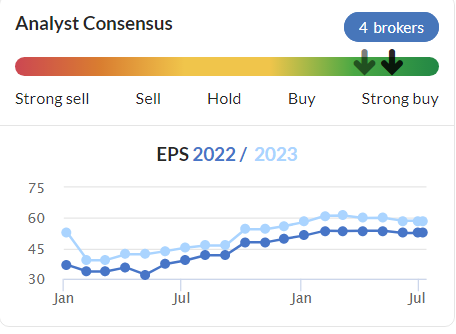
Broker forecasts have been raised a lot, as you can see below, yet it’s still trading “slightly ahead”.
.
Could we be at or around peak earnings though? The market seems to think so, with a low PER of only 9.2.
If you think we’re heading for a deep, prolonged recession, then clearly this sector won’t appeal. Although as things stand now, there is full employment, and skills shortages, so decent quality staffing companies look attractive to me. They've also got built in inflation protection, because when wages go up, they can lift their fees maybe even automatically, if it's on a % basis of the workers' wages?
STEM & RWA look the best ones in my opinion, in the smaller caps staffing companies.
It’s tempting to have a nibble, but they could get cheaper still, who knows?
Attractive valuation scores below -

.
Ten Entertainment (LON:TEG)
226p (up 7% at 12:09)
Market cap £155m
This is a smaller rival to Hollywood Bowl (LON:BOWL) - both of which sold off heavily in recent market turmoil, but now look to be bouncing, on strong trading.
Ten Entertainment Group plc ("TEG" or "the Group"), a leading UK based operator of 47 bowling and family entertainment centres, today announces a trading update for the 26 weeks to 26 June 2022.
PR headline -
Strong demand continues, driving record growth
Here are my notes -
H1 update, for FY 12/2022
Net cash.
New site openings underway.
Repaying Govt CLBILS loan, so it can resume divis.
Guidance - trading ahead of expectations for this year.
LFL sales growth in H1 is remarkable, at +46% vs pre-pandemic figures from 2019.
Value for money pricing has led to a +43% increase in footfall - I particularly like this, as consumers will spend, if they perceive things to be value for money.
Profits ahead of last sequential half year, H2 2021, but no figures given (fair enough as it’s only a week after H1 period end).
Strong cashflows - self-funding roll-out of new sites & refurbs.
Proven track record of offsetting inflationary pressures.
Outlook for H2 - expected to “temper slightly”, but continued record growth expected.
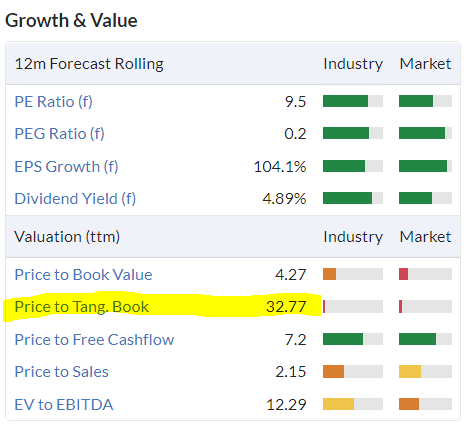
Valuation - attractively priced on PER and dividend yield too (based on yesterday's forecast earnings, which is likely to rise now).
Note there’s not much asset backing though (a high Price to Tang. Book) - this ratio is better when it’s smaller.
.
My opinion - an absolutely cracking performance from TEG.
What’s confusing me at the moment is that the media is full of stories about impending recession, households incomes squeezed, etc. Yet here we have a bowling alley operator, which is totally discretionary spending, trading its socks off!
So it seems that there are plenty of households who can still afford leisure activities, and want to do them. Maybe spending is shifting more towards experiences, and less from buying objects? If that’s right, and it’s sustainable, then perhaps leisure, travel & hospitality could contain some oversold bargains?
I do wonder though, how much of the stellar growth at TEG is sustainable? People are probably still feeling pent-up desires to do the things that we were prevented from doing in the pandemic from March 2020 onwards.
For that reason, I’d prefer to value this share on say 12 times 20p EPS, which looks a sustainable level of profits. Even though this year it’s likely to smash that earnings figure on the upside.
Hence I’m coming up with a reasonable price target of 240p, which is not much above the current price of 226p. However, I think my sums here are pretty cautious, and build in some downside protection.
Overall then, this looks an attractive share, but possibly benefiting from pent-up demand, which might not be sustainable. For that reason, I’m not interested in chasing this up in price, given how wobbly markets are right now. One for the watchlist though.
.
.
Graham’s Section:
Argentex (LON:AGFX)
- Share price: 79.6p (pre-market)
- Market cap: £90m
Good morning, everyone. I’m starting with a look at this forex broker to institutions and wealthy individuals.
It listed on AIM in June 2019, so it is still a relative newcomer to the public markets.
The share price currently offers a nice discount to the issue price (106p) and the pre-Covid high (over 200p!).
After falling so far, it is now on a single-digit PE ratio, with a trailing dividend yield of 2.5%.
Let’s see its headline results for FY March 2022:
· Revenue +23% to £34.5m.
· Operating profit +33% to £10.4m (I prefer using this, rather than the adjusted measure).
· Unchanged total dividend payments for the year.
It’s surprising to see such growth momentum and profitability from a stock which has suffered such an enormous share price decline.
Analysis
The details as to how Argentex achieved these results are equally encouraging.
The number of active corporate clients is up 17%, to 1,624. Customer diversification is improving, though is still something to watch out for: the revenue from the top twenty customers falls from 41% of total to 36% of total.
Interestingly, there’s an unchanged business mix in terms of the currencies being traded and the types of trades. This means that Argentex has not needed to change what it does, in order to continue growing.
Finally, the company headcount has only just broken over one hundred. It’s a labour-intensive and sales-driven business, and it’s impressive that the company has reached this scale without needing even 100 employees until now. New international offices are opening, with the first of these in Amsterdam and the second in Australia.
Technology offering
Argentex says that its online platform helped the company to have its best ever month in March 2022, and is accelerating the investment in this side of the business:
Following strong initial feedback from existing clients, there will be an acceleration of investment in new products to seek to capture new customers, gain further international reach and enable improved efficiency and improved share of client wallet
I don’t think it’s right to think of Argentex as a tech-driven company today, but it does sound as if it has had a lot of success with the online platform so far. This could be a differentiating factor in the company’s success over time.
It aspires to be “a multi-product, global business” - a strong online platform will be a key asset if it is going to achieve this.
Outlook
The outlook statement is very confident – any why not, after the results they’ve just posted?
Q1 revenue is up 22%, and we have the following statements of intent:
Continued investment into people and technology expected, underpinning momentum in client base growth and accumulation of market share from incumbent banks which account for 85% of the cross-border market.
The combination of the above initiatives is expected to generate a strong return on investment in the medium term through growth in revenues, boost in profitability and improvement in quality and visibility of earnings
It’s very helpful to quantify the market share still held by mainstream banks. Unless the banks react – if they are able to – then more and more business is going to end up in the hands of Argentex and other specialist brokers.
Maybe banks aren’t interested in the FX business, if they can’t charge a horrendous spread while providing very little service?
Change of accounting date
Unfortunately, Argentex also announces the intention to change its financial year-end, from March to December.
I say unfortunate, because I often find little benefit when companies do this, and it messes up the numbers.
Argentex is doing it to “address the imbalance” caused by results being weighted to the second half, since Q4 (January to March) is its busiest quarter.
But won’t this mean that future results are weighted to the first half, since January to March will now be Q1? Is a H1 weighting better than a H2 weighting?
See what I mean about little benefit from changing the accounting date?
Balance sheet
The company has net assets of £33m, very few intangible assets, and a nice surplus of current assets over current liabilities.
My view
I’m inclined to think that this is one of those stocks which has sold off too far during the small-cap sell-off.

I can’t say with any certainty that Argentex is going to outperform its competitors in the very competitive FX broker space, but the risks are arguably priced in now, at a sub-£100m market cap.
If the company was struggling to grow, that valuation would make more sense to me. With the company showing very healthy growth and lots of ambition, I don’t see why shareholders can’t do well here.
PROCOOK (LON:PROC)
· Share price: 41.2p (+1%)
· Market cap: £44m
Only a third of this stock’s market cap is held by small shareholders, i.e. the free float is only worth about £15m. So I’ll try to keep this brief.
Procook is a recent float (November 2021) and has previously been covered by Paul. The company sells kitchenware online and through 55 stores nationwide.
The stock is down over 70% since IPO, which is quite terrible even in the context of a weak environment for small-caps.
Let’s summarise the full-year results for FY April 2022:
· Revenue +29.5% to £69.2m
· “Underlying profit before tax” +14.5% to £9.5m
· Actual result: small loss for the year.
Unfortunately, the IPO cost the company an amazing £9.4m, and these costs are excluded from underlying profits.
Included within the IPO costs are £2.47m of direct costs, and £6.7m of “IPO Share based compensation”. Bonuses to employees, in other words.
And these costs aren’t finished yet:
Expenses in relation to these IPO awards are expected to continue through relevant vesting periods to FY25, albeit these costs reduce over time.
Already, I’m not sure that I can stomach reading any more of this. The company’s entire profit for FY 2022 was lost, mostly to employee bonuses, and you have to read the footnotes and the CFO’s review to discover it.
Personally, I wouldn’t want to get involved with any company which did this. But for completeness here are some excerpts from the outlook statement. I’ve added the bold:
The rapid deterioration in the consumer and macro environment means that we have now had to adjust and re-prioritise our focus…
In line with our recent trading update on 10 June 2022, the Board expects that revenue for FY23, will be broadly in line with the last year, with underlying profit before tax of between £4-6m, reflecting ongoing investment in future growth, cost inflation and a return to a more typical seasonal second half weighting.
Remember that underlying profits exclude the cost of employee bonuses.
Balance sheet – there are £13m of net assets, but the leases are material relative to the size and profitability of the company (£2.8m in short-term lease liabilities, and £19.6m in long-term lease liabilities).
There are also borrowings of £5.5m, so the company has a net debt position of £1.8m. After year-end, the company opened a new £10m borrowing facility.
My view
Procook has excellent reviews on Trustpilot, and I like investing in direct-to-consumer brands. I also like investing in bargains. Unfortunately, the IPO bonuses have turned me off this stock and it also looks like the balance sheet carries some risk – not ideal for a kitchenware company in recessionary conditions.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

64 comments
Regarding PROC. Interesting to see Fackelmann of Germany take a 4.633% stake . An acquisitive company that does exactly what ProCook does in the UK.https://www.fackelmann.co.in/
Just been to Crestchic factory tour / new building opening .
Crestchic sell manufacture and rent loadbanks .
- very good sector
- very established clients such as US navy , they were just finishing two loadbanks for US submarines destined for San Diego
- Uk mod a big customer for a long time with ongoing support and maintenance
- massive sales to data centres
- importantly going forward I noted the previous facility / offices were borderline not fit fit purpose and had clearly been a big factor in both limiting sales and inefficient
- very good most and hard to see a competitor entering this category easy
- very strong rental side that is unique to them
- the new 40,000 sq ft facility build on time and for a remarkable 2 million budget (seemed very good price )
- a major online retailer buying loadbanks from them for cooling their data centres (Amazon for sure )
- their rental loadbanks are typically written off after 10 years but have a 20-30 year life so big understatement on asset value .
Anyway to sum up production and sales bound to improve as the company can now make stuff without falling over each other , in a great category , with a unique understated rental fleet .
And finally management and employees all grounded and hard working .
Crestchic (LON:LOAD)
Hi Paul
Regarding your comment:
"It seems crazy to me that the shares continue trading, in what is essentially a false market. The system needs to be reformed, so that shares are immediately suspended when a placing is decided upon"...
Whilst I appreciate the sentiment, how would this work in practice? If you have listed shares constantly being suspended for days or weeks I'm afraid you "break" the equity market. Open ended funds such as OEICS would be unable to deal in the shares, and would struggle to manage inflows & outflows. Tracker funds would be unable to match the market. Fund managers would be forced to create umpteen "sidepockets" which would be a logistical nightmare, and what price do you put on a share while it is suspended?
What it would do in practice is make open-ended funds run a mile from any share where a suspension was likely, because they simply can't afford to take the liquidity risk. I suspect the consequences for small/mid caps would be very unpleasant indeed.
We already "pretend" that company management are not in possession of price sensitive inside information most of the time (otherwise they could never deal), and I suspect this is another of those areas where we may need to tolerate the lesser of two evils? I'm sure things could be improved, but markets can never be made entirely "fair".
Monte Carlo, you make some very good points. I think the UK market works quite well with very limited suspensions (apart from reverse takeovers). A possible half-way house would be to require companies to make an RNS announcement that the company is thinking of doing a placing, when say 10 people have been taken "over the wall." To be fair to AO.com this is similar to what AO.com did yesterday - they said that they were thinking of "strengthening the balance sheet", which obviously caused the price to decline. But I come from the old school, that thinks management's job is not to massage the share price.
Hello Paul,
I totally agree with you about insider dealing and leaks when a fundraise is imminent, and that the shares should be suspended. Some years ago I was on a 94 bus on Oxford Street and some very loud Aussie who was clearly an insider in a company was yakking away on his mobile about what was happening at that company and that an RNS would come out the next morning, which indeed it did. We could all hear him. I've been an insider a few times and just keep my mouth shut and not even tell anybody.
Paul I finally got round to listening to your Saturday Podcast which I found contained some very useful nuggets of information and opinion in these depressing times for private investors.
Your comment " do not sell good Companies now" struck home and the key for me was "patience". I am down 24% on my Portfolio this year and hold 20% in cash.
I should have listened to a Golfing friend who told me he was 100% cash 6 months ago!
Please continue your Saturday Podcasts which seem to have justifiably found wide support and approval from the Stocko community.
Supreme (LON:SUP) Zoom presentation -
The CEO acknowledged that the latest RNS had been a profit warning and there was a concentrated focus on the cause, their Lighting category. They emphasised that they had not seen this coming and neither had their customers. Their main buyer in lighting didn't see it coming and bought shares recently. It suddenly became apparent that there has been not only overstocking in their retailer customers which they hope will resolve in 6-9 months, but also a sharp decline about 20% in retailer sales to consumers. They got this from real EPOS data which their biggest customers have let them see. They think people are not keeping spare LED bulbs, are turning lights off to save electricity, not doing DIY or buying new lighting fixtures. The Lighting category is all licensed sales in bulk, containers going straight from factories in China to retailers' warehouses in the UK, so the orders are large and when they suddenly pause the impact is huge. But it's a pause, not a full stop.
Batteries also down in sales at the consumer level but they don't expect the same overstocking problem.
At the moment vaping clearly dominates the business with no sign of growth slowing - they are growing their share of a growing market.
Wellness is also growing and is direct to consumer sales for Sealions (vitamins). They make the products. Other categories not seeing massive inflation but for protein powders it's a problem - whey is in all the products, was £4 now £11; they increased raw material stocks because they saw the latest increases coming and expect prices to start declining in a few months.
Supreme is set up to handle any kind of FMCG trade, and they can either manufacture or sell under license. They pride themselves on being very lean. They are slowing down their plans to acquire new premises, 'This is not the time to be moving to a fancy new building'.
Dividends - the biggest loser from the coming dividend "cut" (as a percentage of profits) is the CEO who has [60%?] of the shares - he wants the cash to be left in the business because they are seeing a pipeline of acquisitions which can be bought at good prices ad the long-term return to shareholders will be greater if they have the cash now to take advantage of opportunities.
They have £25m existing debt facility with another £10m "attached" and neither the CEO or the CFO want to borrow any more than that. They are very risk averse.
Share buy-back? Can't say, not allowed to.
I was very impressed by the CEO and CFO. Straight talking, open, intelligent, young, energetic, entrepreneurial. It seemed to me they know their business inside out. They handled the stress of a presentation straight after a final results profit warning very well. A lot of the the time investment is about backing people. I bought today for the first time, at 80.6p
Michael C,
That's a fantastic write-up of the Supreme (LON:SUP) webinar, thank you!
Very much appreciated, as I'm really pressed for time this week, so you just saved me a time-consuming job! :-)
My main problem with SUP is that I previously (wrongly as it turns out) thought it was selling consumable products, with predictable, repeating revenues.
It now turns out that significant part of the business (lighting) is lumpy & higher risk than I realised.
For that reason, I think SUP deserves the drop in share price from 200p last autumn, to 80p now.
Note that the spike up to c.240p in Jan 2022 was caused by a tip sheet recommending it.
I agree mgt come over very well, esp the founder/CEO.
Regards, Paul.
Paul, thanks for the compliment. I wondered about the spike. I certainly wasn't interested in Supreme (LON:SUP) at £2+
There is no such thing as predictable repeating FMCG revenues in the long run. In the brief part of my life when I had "proper" jobs I worked for FMCG companies, Victoria Wine, Forbuoys/NSS newsagents, then the largest privately owned CTN (Confectionery/Tobacco/News) retailer in the country, where I was on the board. Consumer behaviour can turn on a sixpence. You can have a product which has sold steadily for years and suddenly you find demand has dropped by 20% in the space of a single quarter, you have excess stock in the warehouse, and everyone is sitting round the boardroom table wondering what on earth just happened. This is what happened to the Supreme (LON:SUP) lighting business. They now think that (a) the sales in 2020/21 were exceptional because of COVID-induced behaviour, and (b) they think current sales are reduced below normal because people are literally turning lights off and not always replacing burned-out bulbs. They think that as soon as the excess stock (which is LED bulbs with no sell-by date) has gone through the system they will be back to predictability, albeit at a slightly lower sales volume.
Meanwhile the Vaping side of the business is "growing its share of a growing market", batteries are OK, there's a good future for the vitamins and protein powders, and they have excellent prospects for adding on new business. If the shares go much lower I will average down for the first time in my life. These guys are not going to go bust.
Supreme (LON:SUP)
These guys are not going to go bust
I seem to recall when I did a bit of research (when the shares were being ramped) that the CEO went bust with a previous venture.
Just saying.......
I wanted to write something similar but I was worried it was going to be deleted ( yet again ) , just because I offer a different but honest opinion based on figures and facts.
I would not go that far saying that this company will go bust , but the current CEO has a previous bad record.
Also , I was very sceptical about this stock from the early days of its listing , as I counted 7 ( yes , Seven ) different newspapers or monthly tip sheets promoting this.
I’m going to have to guess that you are referring to Supreme (LON:SUP) since you didn’t mention the ticker?
The Supreme (LON:SUP) presentation was very good in that they knew shareholders wanted to know about lighting so concentrated on that in detail as ably summarised by Michael C
I have just received the follow-up questionnaire which included:
3. Are you confident that the customer overstocking issues in Lighting are an isolated one-off issue?
!
£D4T4
Mcap 95m (yesterday)
SP 245p
(I hold)
Surprised that no one has commented on the D4T4 prelims this morning. But then there is plenty else going on at the moment, On the face of it uninspiring results from this customer data and fraud data platform software company seemingly always poised for signicant growth.
Revenue increased by 7.3% to £24.5m but profits falling with profit before tax of £1.8m (£3.0m). Oops. Not such a growth company?
Part of the reason for the fall in profits is the switch to ARR up 32% at £14m, also apparently the product mix with 3rd party supplied product at lower margin increasing during the year – with gross margin falling from 62% to 52% - which is expected to reverse in the current year.
Lest I get too caught up in the negatives – the company is in a major transition, not just from one-off sales to recurring revenues. They launched a major new Fraud Data Platform product in the last year complementing their customer data plaform and acquired a small marketing/sales company to provide a direct channel to market alongside its traditional partner route. As well as launching API’s to allow customers to plug in the software products which will further extend the size of the market. The longtime CEO has just completed the handover to new CEO Bill Bruno and CFO Ash Mehta who have experience in growing significant businesses and are busy investing in the systems and people needed to provide rapid scaling up of the business. Will it work? That’s always the big question.
For me D4T4 is in the sweet-spot - a niche software developer that is already profitable, dividend paying, with cash on the balance sheet as well as fully investing in its ongoing product development and with a potentially huge global opportunity.
The dividend is lifted by 3.9% to 2.92p with the cashpile of £11.4m (£14.2m) – but that’s a little misleading as payment from significant sales partners after the year end helped boost the cashpile to to £26.5m at 30th June 2022 and a special dividend of 12.5p is recommended to return excess cash over and above that needed within the business to shareholders.
Outlook statement is positively enthusiastic. I am embarrassed to say I have no idea whether this company will continue to plod along growing modestly with the sunny uplands just around the next corner – or whether the new products and management team will lead to sales and profits increasingly at well over 20% a year? Obviously I hope that consistent growth will arrive this year. But then isn’t that always the case with these software stories? In this case as its already profitable with healthy margins – it won’t take much increase in sales for profits to rise substantially.
FY23 forecasts are for 27m revenue up 10% and earnings of 9.8p up 45%
That’s the magic of ARR. Sticky customers and almost zero costs in added sales. The new Fraud product has already won its first customer, an upsell to a major US financial institution and was recently recognised at the Infosec 2022 awards – giving some credibility to both the product and the sales opportunity in the current year.
With the share price down 42% from its 400p peak – at 235p this morning and presumably the market unimpressed by the promise of more jam tomorrow – it’s still not cheap at 24x current year forecast earnings – but that looks modest to me in view of the increasing quality of earnings and size of the medium term opportunity. With the floor set by a profitable business more than capable of funding its growth opportunity with no need for fresh funds. Quite the reverse - it seems to be a cash generating monster already.
I’ll be adding a few more now and then in the coming months – funded largely by the special dividend - but I'm not in a hurry it will most likely take a while for contract wins to come through and in the meantime I may be offered shares more cheaply by the market,
cheers
Mark
Yes, re £D4t4 it would be great if Paul could have a look - if too late for today, perhaps later in the week? Please note that there is a webinar on IMC at 3pm today!
Forecasts for FY24 from finnCap are worth a look. In that note they also break out the SaaS license element (from the recent results) which had more than doubled; this bodes well for the future - hopefully layer upon layer of recurring, high margin revenues will make the company an even better cash producer than it already is. Rock solid balance sheet.
Customer data - in real time, without tags and cookie problems - should be in demand going forward, and the new fraud detection product has found some customers. The hope for rapid growth remains, and we are getting jam today as well. (I hold)
Ten Entertainment (LON:TEG)
I sadly no longer hold this one. Amazing results today and it's hard to see much not to like.
If there was one thing holding me back from buying again, it was the possibility that 2022 is a year of pent up demand that is masking more normal trading behaviour.
Customers/site in 2019 was 128k.
Customers/site in 2021 was 165k (an annualised value that I calculated given site closures.)
And so far in 2022 "footfall....is 43% higher than experienced in 2019," which would be c.183k customers/site.
That's a very big boost since 2019 and I wonder if, like many "pandemic" stocks, footfall will eventually recede back to historical norms.
If trading did revert back to 128k per site per year, then I still think the current share price looks good value.
But I'm not convinced that the market would take kindly to a drop in revenue, even if the reasons were rationale.
Then again, I have a feeling that this is another one that I'm overthinking.
GL to all holders.
Cheers
A
Ten Entertainment (LON:TEG). This might well be a good recovery play but I am put off by the 198m of debt that dwarfs the Market Cap of this share and will probably take years to pay off.
They say today that "the Group had a net cash position at the end of the first half."
Ten Entertainment (LON:TEG)
Watchdog
I am put off by the 198m of debt
There is debt and there is "fake"accounting debt :) - this is most fake acounting debt.
Per the finals
net bank debt was £2.5 mill - hopefully all gone now
and £195 mill of "lease debt" - practicably speaking that aint debt its nearly all future "rent" due (to end of lease) with a little bit of future lease payments for their machines (future hire). Note as their trading sites are fundamental to them earning their buck they want to have as long a lease as possible. Until reasonably recently these lease liabilities would have not showed up as "debt" .
If Paul does a writeup hopefuly he will explain better than i can that this aint real debt practicably speaking.
Hi rmillaree,
Yes you're right, unfortunately the data provider includes IFRS 16 leases as debt. So multi-site businesses like Ten Entertainment (LON:TEG) and retailers, etc, all seem to have huge debt, but as you correctly point out, this is "fake" debt relating to future rent payments.
So I've nothing to add to your excellent explanation!
Regards, Paul. (I'm being super-polite today, please note! ;-D
In Stockpedia, the 'net debt' bit now includes lease liabilities. But my understanding is this should be offset by the 'right of use assets' in the assets part of the balance sheet, as this is the property/machines being leased which gets amortised every year...for example, for Ten Entertainment (LON:TEG), 'lease liabilities' comes to £195,662, but the 'right of use assets' come to £167,324, leaving net lease liabilities (if there is such a term) at £28,338.
Stockopedia doesn't take this into account so I do not use Stockopedia's net debt figure, I go work it out myself...
I'm not an accountant though !
Hi truegent,
Yes, that's correct.
I've asked Stockopedia to remove the lease liabilities from debt, or give us both numbers (net debt with and without leases), but apparently the data provider takes the view that IFRS 16 is an accounting standard, which they have to follow.
Hence as things stand, we have to manually adjust net debt, or just refer to the most recent results statement and do CTRL+F for "net debt", which quickly highlights the relevant figures.
Annoying. I loath & despise IFRS 16. As a canny reader commented here recently, if everyone adjusts the accounting standard out, then it's not fit for purpose. I couldn't agree more.
Still I suppose you could argue it gives us an advantage, since other investors might overlook good, cheap companies, mistakenly thinking they are swamped in debt!
Regards, Paul.
Regards, Paul. (I'm being super-polite today, please note! ;-D
No worries in that regard - i 100% appreciate all your opinions/comments even if disagree 100% with what is being said.
rmillaree,
Jolly good, thank you!
We really value your contributions here, which are excellent. So I didn't want to upset you.
Regards, Paul.
Ten Entertainment (LON:TEG)
At Dec 2021 the company had £192m of "Capital Lease Obligations" due in more than 1 year - ie rent on its locations stretching off into the future.
Stocko could do us all a favour by segregating this figure out from debt.
But perhaps more to the point the accounting profession could do us all a favour by killing IFRS16 - if everyone adjusts for it, it's not fit for purpose.
Phil
Ten Entertainment (LON:TEG)
If trading did revert back to 128k per site per year, then I still think the current share price looks good value.
But I'm not convinced that the market would take kindly to a drop in revenue, even if the reasons were rationale.Then again, I have a feeling that this is another one that I'm overthinking.
Your thinking is 100% logical Abtan - no need to take the risk in that regard and there has to be a % chance your concerns may pan out. I bought corsair at back end lockdown on the basis that end of lockdown would be a blip as they are a growing company it wasnt - so it is a very decent question as to whether peeps will get bored of the novelty. From my persepctive the more i bowled the more i wanted to go back to try and beat my top score - most people probably arent that competitive but there is certainly is for me "enough of a hook" that they have enough to make want peeps want to return. So long term no issues and hopefully any tail off will simply put them back where they were pre pandemic roughly speaking which was a pretty tidy place anyway - as with any business though with large mostly fixed overheads when it does go wrong .......
Ugly day yesterday but the S&P 500 has held the 3666 level so far and the bounce theory still holds. To be honest it isn't really broken if it goes lower... history suggests we remain in a zone where we can bounce.
Yesterday oil was very weak but defensives in the UK market got hammered...and are bouncing hard this morning. I think this suggests - get me out - means defensives weaken now.... and very few places to hide. For me this is another sign we could get a more prolonged bounce... perhaps with a fed hike and pause...may be 50bp hike would be taken quite well, for now.
Violent moves don't tell you too much about where to be invested IMO....but the 2001 - 2003 period scarred me forever. It took a long time for the cyclicals to motor and staying in cheap, defensive and (my view at the time) boring steady stocks worked for a long time. It definitely helps on the really bad days if you have confidence your companies will survive.
The advent of ETFs and passive investing does change the landscape... and so the market has moved fairly quickly to discount a recession. Classic victim sector's like house building may be overdone.... they look cheap but they looked cheap for the whole of the 90s too. Personally I still favour a pretty cautious classically defensive portfolio ....until the Fed does more than pause. Also worth noting that the QT comments will be just as important as the rate moves. Ironically the oil move is GDP positive and a positive catalyst for the consumer.... the retail sector is inversely correlated to fuel prices.... and so further weakness in oil actually reduces the need to pause not the reverse.
All in all a pretty random and scary day but the scope to bounce holds.... and for me this is a chance to shore up defensives for a likely tough winter before 2023, when hopefully the market starts to anticipate a recovery. Back in 2003 It took many rate cuts before the market bottomed... rising about 15% from memory on the eve or going to war with Iraq in March. But it had fallen much more than current levels.... if we followed the path of that market cycle the S&P will ultimately bottom around 2200-2400. All bear markets are different so I don't expect this again but I wouldn't be getting aggressive on the recovery side yet.
2001 to 2003 was terrible. I had some bad losses during this period. When I sold those and bought the growth stocks after the start of the 2003 war I made all that money back and more. I had some astounding wins with some huge gains achieved in just 4 weeks. My lesson was to not be long on a bear market. if all the indices are below their 200 day average, how can one make money? You are swimming against the tide It could be a long wait, but I think cash is a better place to be in at the moment. Now is about looking for what might be the next big winners, but without getting in until the market has definitely bottomed.
Regarding the last minute delay for Zoo Digital (LON:ZOO) results, although the RNS does not name the auditors I see from the company's IR website that it is Grant Thornton again.
They were responsible for successive delays to Venture Life (LON:VLG) results and here is the CEO responding to my question about that.
£RLE
This comment: "The Board recognises the need for market consolidation within the real estate and REIT market and remain alert to options that align with the interests of our shareholders"
I think that welcomes bidders!
My initial reading of Redde Northgate (LON:REDD) is that the results and outlook statement are generally positive, but need to sift the details. Any help from Paul or Graham as always appreciated. I hold.
Difficult year to date for my small cap portfolio, 27 holdings, one disaster to date, hoping to keep it to that.
I concur, a look at Redde Northgate (LON:REDD) would be appreciated, thanks.
I agree - a look at Redde Northgate would be much appreciated.
Graham spotted your comments, and is taking a look at Redde Northgate (LON:REDD) as we speak, for Thursday's SCVR. I also think it's an interesting value share, and have held before.
Regards, Paul.
Does anyone have a screen for investments which might survive a sudden interest rate shock? I had been thinking this was possible but I now think it is probable.
Yesterday Guido (order-order.com) reported Boris as saying to a group of Conservative MPs “‘I know you’re all avidly in favour of tax cuts and tonight’s events might make that a bit easier to deliver.”
In February the Bank of England MPC said: ' ...the Committee agrees at this meeting that the Bank of England should cease to reinvest any future maturities falling due from its stock of UK government bond purchases.' If this means that the magic money tree really has been felled, and if the government borrowing requirement increases because of tax cuts, and if the current account deficit of 7.1% of GDP in Q1-2022 doesn't reduce, I really don't see how the BoE can avoid a disruptive hike in interest rates.
Does anyone have a screen for finding companies which might survive? I'm a bit rubbish at setting up screens and my screens never seem to produce investment success!
Looks like I am right about interest rates - I hadn't read this before I posted: https://www.telegraph.co.uk/bu...
If you are looking for something "which might survive" then why are you screening for individual companies anyway? If you want an investment in companies that is guaranteed to survive then invest in a stock market ETF, not individual stocks.
But more importantly, if your key criterion is survival, then do what has worked down the ages: invest in a balanced, all weather type portfolio. That would include cash, bonds, commodities and other hard assets as well as some collective investments in stocks.
If by "survival" you mean something you can be confident wont fall in nominal value as a result of globally higher interest rates, then your only option is cash.
But, despite this, if you're going to screen for companies anyway, you should screen for something that is (1) non cyclical (2) net cash or lowish gearing (3) free cash flow positive (4) a P/E ratio not much higher than median, implying it is not priced on future growth which will now get discounted (5) a stocko risk rating of Conservative or Balanced.
I already have collective investments/funds/real estate/precious metals at Bullionvault.... no bonds though, not a single one at present. I have in the past bought short duration Gilts if I needed a temporary home for largish sums.
But I like buying individual company shares as well & I have a 6 figure sum looking for a home. As I said I think there is an interest rate shock coming and I wanted a screen which identifies companies which will survive that. Your suggestions are good and I'll try to set up a screen like that.
Appreciate (LON:APP) benefits from interest rate rises. Look at the recent results' notes section and search for interest rates
I've read your note on Appreciate - it's very good. Definitely tempted.
I watched the Appreciate (LON:APP) recent webinar, and have mixed feelings on it.
Negatives -
Management sound awkward & wooden, but does their poor presentational style really matter? Maybe not.
I don't like the business model, having tried out the product (ONS gave me a £10 Love2Shop card for participating in a survey) - to redeem it, you have to give intrusive personal details, such as date of birth, address, etc. I'm not keen on that at all. Also, I forgot about the voucher, and when I came to redeem it, it had expired, so was worthless! I think that's dreadful, and it has permanently tarnished the brand name in my mind.
Adjustments to the accounts mean that underlying EBITDA (slide 8) was actually down.
Management said business was seriously under-invested, with manual or old IT systems, so a lot of changes were needed. That worries me, given that it's handling millions of transactions, as top notch IT is surely vital?
There are competitors - e.g. ONS came to see me again this week, and my £10 reward this time will not be Love2Shop, they have switched to a competitor. So margins are likely to be thin.
Positives -
Good growth initiatives explained well in the webinar.
Interest income on big (>£100m) cash balances in trust could be a nice driver for profit growth.
Strong current trading & good new business.
Financially sound, and not used RCF. Although NTAV is quite small.
Improving divis.
Sticky clients, with over 90% retention.
Cost of living crisis is an opportunity - e.g. employers giving vouchers to buy food, would be appreciated more by struggling employees.
Overall - I'm neutral on APP currently, but have it on my watch list. I can see the bull case, and am tempted, so probably leaning more towards a positive view, but with reservations.
Regards, Paul.
Redde Northgate (LON:REDD) results put this share on 50p adjusted EPS and 21p dividend. It trades at c.335p and looks too cheap to me. But minimal commentary about outlook which is annoying although they expect to continue to benefit from higher disposal profits in FY23 (the notes section has more detail on that). When I get time I need to look at whether the adjustments look reasonable to rely on the adjusted EPS figure which is quite different to statutory (which is still putting this share on a single digit p/e.
There is a bit of confusing commentary about contract hire competitiveness that I don't really understand and would welcome more educated views.
After a bit of head scratching I’ve worked it out …they’re saying they’ve ‘borrowed’ £155m on contract hire …even though it’s less attractive on interest rates now that they’ve reduced their cost of funds
..big difference is they don’t get residual value exposure on contract hire
Redde Northgate (LON:REDD)
When I get time I need to look at whether the adjustments look reasonable to rely on the adjusted EPS figure which is quite different to statutory (which is still putting this share on a single digit p/e.
Well they have managed to incur negative £3 mill of restructuring costs which is bit of a pleasant change from the usual "hidden real costs" - looks like there has been prior kitchen sinking for whatever reason.
I hold here and am a fan of management - i will forgive them ref sketchiness ref outlook - the final results isnt the place for that - but to me its clear the wording has no negatives so to me they are clearly saying its as good as previously expected which is fine for me. At least no radio silence. Note we did have pre close trading update 6 weeks ago too with outlook comments then so no point rehashing what they previously said.
The new financial year has started well and the business is well positioned in its addressable markets. Further revenue benefits are expected from new long term contract wins already secured but yet to commence. While the Board is mindful of the economic uncertainty it remains confident that it has the right strategy to deliver long term sustainable value.
The elephant in the room is how much the are/have "temporarily" benefiting from tight supply of vehicles and exceptional secodn hand values. I think for me thats too hard a question to answer - i would guess 25-33% of the profits may be fluff so despite holding i dont think its deffo as cheap as it appears at face value but i like management here and they seem confident at present so perhaps profits may not drop off a cliff. Note the elephant is the reason for the large adjustments between underlying profits and formal profits adjustments to depreciation - good luck making sense of that. I am still content holder - i will keep an eye out on where future earnings expectations are trending - i dont expect that trend to be positive if the easy money departs the building but i am comfrotable with that .
As an aside i noticed there may be oversupply of components ref iphones and similar (Micron warned of slowdown) - and i was watching youtube video ref vehicle repossessions in US - it appears at present there may be something approching a tidal wave of peeps there handing vehicles back - so the second hand market can be expected to tank - with knock on issues ref selling new vehicles at decent margins (if peps can pick up nearly new baragin again) . Not massively expecting the same to deffo happen here but i do expect there to be oversupply arriving sometime soon that may not be great for the likes of Redd.
Ten Entertainment (LON:TEG)
Some numbers
LfL sales vs 2019 +46%
Footfall 43% higher( 2 extra sites)
Shares on about 9x pe pre upgrades.
Pipeline for growth. Labour costs relatively low at 19% of total costs. Electricity hedged till 2024. Have kept prices at 2019 levels.
Net cash now.
Its not the only consumer discretionary name I own but its probably the best one in terms of risk adjusted outcomes. Some of the others I'm clearly a bit "early"!
I hope I haven't got my numbers wrong as I get a PE of c6 for Ten Entertainment (LON:TEG)
In H2 21 they made a net profit of 12.8m and they have just stated they did more than this in the first half, so hopefully they should exceed 25m for 22.
Ten Entertainment (LON:TEG) ( I hold)
A good set of numbers( again!). They've sold off recently having held up well prior. Business being run well, opportunity to grow, economies of scale , energy costs hedged from memory to 2024. A low cost family entertainment option. There's a lot to like. Looking to resume divis as they pay off CBils.
Any thoughts welcome! This is a market that tests patience... Hollywood Bowl (LON:BOWL) I would also expect to report strong numbers( I no longer hold).
Consumer discretionary clearly the worst part of the market. So its a rubbish backdrop but there are clearly some businesses that will thrive.
Ten Entertainment (LON:TEG)
This share is a very easy hold for me at present , cant think of any real major negatives at present other than they have hit a purple patch with stonking numbers the last 12 months - I wouldn’t say we should be expecting much growth long term above inflation other than from increase in outlet numbers - that’s good enough for me here.
yep Ten Entertainment (LON:TEG) looks good value at least 12.8m next profit for h1 from reading what h221 profit was looks on a p/e 6/7
Ten Entertainment (LON:TEG)
Liberum have increased forecast for PBT by 17% ( EPS 25.4p and DPS 11.7p ) for 2022.
Looks good value to me.
Phil (I hold )
Morning ! Another great 'ahead of' update by Robert Walters (LON:RWA) this morning, happy to have topped up last week, plus some fantastic results by Argentex (LON:AGFX), highly cash generative, but with net cash now nearly £40m, why have they kept the dividend flat ?
Re Argentex (LON:AGFX) this looks like a good update with Q1 trading well but the commentary about technology investment suggests this might not translate into higher statutory profits until the medium term? That might be why they have kept the dividend flat.
I'd be interested to hear the thoughts of Paul or Graham on todays Argentex (LON:AGFX) results (I hold) which although showing good progress appear to be a miss against consensus broker forecasts. Any info on updated forecasts will be useful especially given PatrickL's comments on reinvesting the cashflow in the short/medium term.
Argentex (LON:AGFX)
.
Argentex (LON:AGFX)
There is a very sparse note from Singer this morning.
It shows the EPS falling to 4.9p for the Y/E Dec 2022 (annualised to allow for the change of accounting date) rising to 6.4p in 2023 and then 10.1p in 2024.
They give no explanation for the fall - presumably Argentex are investing for the future.
Phil
Argentex (LON:AGFX)
It certainly looks like investment in growth (technology, headcount, overseas offices etc) will lead to reduced EPS in the short term. Can't see that they have spelt this out in today's RNS, a mistake in my view.
Today's results are an EPS miss (adjusted EPS 7.0p v 7.4p) which is probably the main reason for a 3% fall in SP today.
There is a presentation on Investor Meet today at 4.00pm.
Looks like more patience will be required for existing holders and Mr Market is likely to maintain a depressed view on the share price for a while more.
A very frustrating share (I hold).
Cerillion (LON:CER) continues to be a rare bright spot in my portfolio, announcing a £15m contract (over 10 years, mind). It's very hard to know what the secret sauce of companies is from the outside, but whatever they're doing it seems to be very attractive to their network operator clients. But the breadth of what they now do is presumably a factor:
Under the terms of the contract, Cerillion's flagship BSS/OSS* suite will replace existing product management, customer relationship management ("CRM"), charging, billing, service orchestration and network inventory systems in a significant digital transformation project. Cerillion will supply and implement the solution, providing it within a private Cloud deployment. The Company will also provide managed services as well as maintenance and support following implementation.
https://www.investegate.co.uk/...
In other positive news both Robert Walters (LON:RWA) and Ten Entertainment (LON:TEG) have provided good updates today. I hold neither but both look very interesting at their current levels. It's hard to know how economic contraction will effect recruitment, even with a company as good as RWA, but TEG's offering looks ideal for difficult times.
timarr
Good morning, Epsilon. Re your very useful response to my query on the 'unexpected' cumulative SP movements for Sylvania Platinum (LON:SLP) on Mon and yesterday, I left an additional couple of comments and your thoughts would be helpful. Thank you in advance.
I was in touch with the company's NOMAD and PR agency yesterday to express my surprise that there had been no RNS to say that Sylvania Platinum (LON:SLP) had terminated their share buy back programme, a feature I had noticed previously with other companies. They just said effectively anyone would have noticed the buy backs had stopped and acted accordingly, which I found rather unsatisfactory behaviour on their part, but there you go. Clearly, other investors had noticed what I had not, and that was likely to have been the trigger for the SP fall,.
Sylvania Platinum (LON:SLP) announced on the 9/5/22 that the share buyback would finish on the 30/06/22
Sylvania Platinum (LON:SLP) RNS of 9th May 2022 was crystal clear: "The Share Buyback will be effective from the date of this announcement and will expire on 30 June 2022."
Re Sylvania Platinum (LON:SLP) and its RNS on the 9th May, thanks to you both. My fault entirely. Funny that neither of the people I contacted mentioned thst RNS, but that doesn't change the fact that it was there and I missed it.
Morning ridavies
You can create a chart of any financial instrument you wish in google sheets. If you are familiar with Microsoft Excel, you will find google sheets easy to use.
Additionally, you can use google sheets to model real-time portfolios - I have included a dummy portfolio at the top by way of illustration:
https://docs.google.com/spread...
PS I took the weekly platinum price data from investing.com :
https://www.investing.com/comm...
I hope this helps.