Small Cap Value Report (Weds 6 Sept 2023) - DOTD, RTN, HFD, BKS

Good morning from Paul & Graham!
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £1bn. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk.

Summaries
dotDigital (LON:DOTD) - up 2% to 86.6p (£259m) - Acquisition - Graham - GREEN
Dotdigital makes a £25m acquisition (mostly paid in cash) for a business with which it already works in partnership. The logic behind the combination makes perfect sense in my view and so even if Dotdigital is paying a full price for it, I think it’s good news for the stock.
Restaurant (LON:RTN) - up 1% to 44.2p (£337m) - Interim Results - Paul - AMBER/RED
Trading has improved, with quite good revenue growth in the circumstances. However, the profit margin is wafer thin. The dreadful balance sheet, with onerous leases, and far too much debt, completely puts me off. Why get involved in a highly indebted restaurant/pubs group that's struggling to eke out anything in profit (and it largely comes from questionable adjustments)? Poor risk:reward in my view.
Halfords (LON:HFD) - up 2% to 190.6p (£417m) - Trading Update (in line) - Graham - AMBER
Things are going to plan at Halfords as Services/B2B revenues grow strongly, offsetting weaker performance in retailing (especially cycling, not helped by poor weather this year). It’s an interesting stock but with low margins and perhaps fairly valued at this level.
Beeks Financial Cloud (LON:BKS) (Paul holds) - down 2% to 95p (£62m) - Trading Update - Paul - AMBER/GREEN
A cunningly concealed revenue & profit miss for FY 6/2023, which is annoying, and undermines trust. Good current trading though, and high visibility due to big and growing recurring revenues. I'm not quite ready to add to my existing (small) position, and I remain of the view that this is a good growth company, and reasonably priced.
Paul’s Section:
Restaurant (LON:RTN)
Up 1% to 44.2p (£337m) - Interim Results - Paul - AMBER/RED
The Restaurant Group plc ("TRG" or "The Group") Interim results for the 26 weeks ended 2 July 2023 ("H1")
Increase in management expectations for FY23 EBITDA and excellent progress in executing medium-term plan
That’s a strong-sounding headline from this chain of 380 restaurants/pubs (Wagamama, and others).
I see the word “moderate” didn’t make it through from the section below, to the headline above!
Outlook -
· FY23 costs in line with previous expectations and medium-term cost outlook continues to improve
· The trading performance supports a moderate increase in management's FY23 Adjusted EBITDA1 expectations
o FY23 Net debt1 expected to be between £180m and £190m
I’ve searched the announcement using CTRL+F for the word “expectations”, as I was hoping there would be a footnote telling us what profit expectations are, but there’s nothing. Also no up-to-date broker notes are available, so this is all rather unsatisfactory and vague.
Key H1 figures -
- Revenue £467m (up 10%)
- Statutory profit (PBT) is only £2.3m! (£28.5m loss last time)
- Adjusted PBT is also small, at £7.2m pre- IFRS16, or £17.5m post-IFRS16.
- Exceptional costs of £15.2m, some of which is rationalising the store estate, which I would say is a normal cost of doing business, not really exceptional, groups like this will always be pruning out loss-making sites.
Balance sheet - as in the past, this is a the deal-breaker for me, it’s a desperately weak balance sheet with onerous leases, and too much debt.
Working capital is very thin, with payables looking too high to me - indicating it might be stretching its creditors to keep interest-bearing debt under control?
Lease entries indicate that there must be some loss-making individual sites, and quite a lot of them too, I reckon. RoA assets of £240m is an estimate of the value of trading from the leasehold sites. The related lease liabilities are much larger at £391m. So it definitely has some problem sites, which are costing it heavily.
NAV is £380m, which includes a massive £597m of goodwill. Take that off, and NTAV simplistically is negative £(217)m.
Debt is too high, with £214m in long-term borrowings. With debt costing more now, and lenders more cautious about wanting to lend to troubled sectors, I’m very wary of this balance sheet. Therefore I see dilution risk as high.
Paul’s opinion - I’m not going to go through all the rest of the detail, as checking the balance sheet has ruled it out as a potential investment for me.
The upbeat-sounding commentary seems out of step with the numbers, which show it barely above breakeven.
LFL sales growth looks pretty good, so revenues are growing more than enough to cover cost increases I think. But it’s still a pretty marginal business, like everything in this sector - a combination of rampant food price inflation, higher wages and energy, means it’s incredibly difficult to make any money at all from restaurants. That might change in future, if we're being optimistic. There's way too much capacity in the industry, although RTN might benefit from smaller competitors falling by the wayside perhaps? Wagamama seems a popular brand - which has always surprised me, as I can buy a packet of noodles for 60p, and stick a bit of chicken & spring onions in it myself, at a fraction of the cost charged by Wagamama. I'll have to mystery shop it again to see if anything has changed. Last time it reminded me of my old university refectory.
So as investors, why would we want to get involved? I think it could take years for restaurants to rebuild margins, and in this case RTN needs to seriously repair its balance sheet as a priority. So the prospect of shareholder returns looks weak - no divis for now, and I think the dividend paying capacity is close to nil unless trading dramatically improves.
For me, risk:reward doesn’t work here at all, so I’m steering clear. Hence a moderate thumbs down, AMBER/RED.
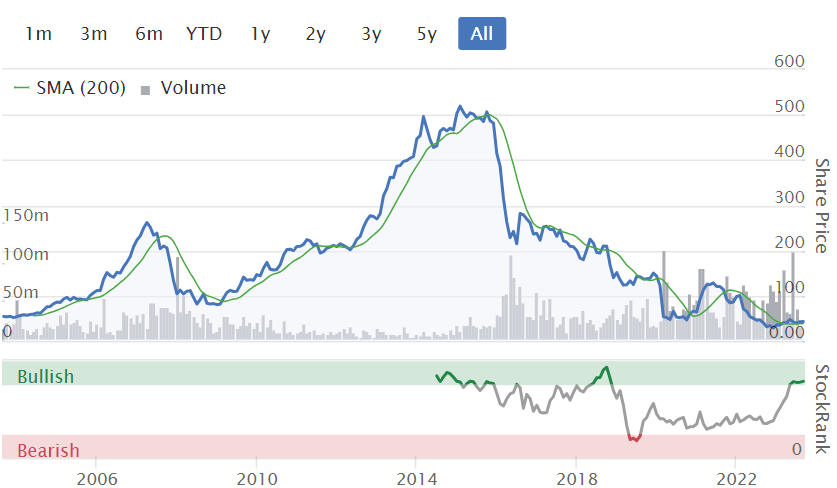
Note that the share count has increased 2.7x compared with pre-covid, so this share is not likely to regain anywhere near to its previous highs.
Massive shareholder value destruction in the last 10 years -
Beeks Financial Cloud (LON:BKS) (Paul holds)
Down 2% to 95p (£62m) - Trading Update - Paul - AMBER/GREEN
6 September 2023 - Beeks Financial Cloud Group plc (AIM: BKS), a cloud computing and connectivity provider for financial markets, provides an update on trading for the year ended 30 June 2023 (FY23).
FY 6/2023 revenues up over 20% on LY (last year) - this looks to me below expectations, as broker consensus implies 33% revenue growth. Canaccord’s note confirms that this is a 10% (£2.5m) revenue miss against its £25m target.
Recurring annualised monthly revenues hit £23.8m at 6/2023, and has risen further to £25m by Aug 2023 - this is encouraging, meaning the £30m FY forecast revenue for FY 6/2024 might be achievable, as most is already in the bag. I like recurring revenue businesses.
Underlying EBITDA up 35%
Underlying PBT up 10% - Canaccord says this implies £2.3m, well short of its estimate of £3.1m.
Positive free cashflow in H2.
Net cash £4.4m (up from £3.35m in last 6 months)
Strong start to FY 6/2024, with “significant visibility” due to recurring revs.
Current trading in line with expectations for FY 6/2024
Pipeline - significant and growing. Large contracts take time to convert (as mentioned before)
Further potential upside from new contract wins.
Paul’s opinion - I don’t like the way this revenue & profit miss against forecast has been concealed, and only properly revealed in broker notes.
However, strong current trading and reiterating FY 6/2024 guidance (of £30m revenues, and increased profits) is encouraging.
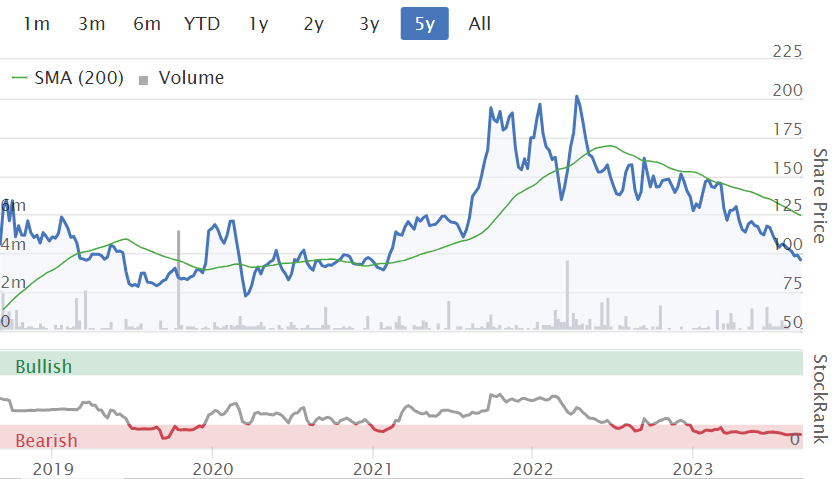
The share price has drifted steadily down in the last year, partly due to the general bear market in small caps, but also I think as some investors (including me!) have felt the newsflow wasn’t strong enough to make me want to buy more. So I’ve top sliced a few times, when I’ve needed money to buy other more compelling opportunities.
Does today’s update make me want to start hitting the buy button? Not really, I have to say, although the good visibility for FY 6/2024 is encouraging.
If it continues to drift down further to say 75-80p, then I think that would be the sort of level where I’d be a buyer again.
What do readers think? I know we’ve got quite a few sceptics in the house for this share, so I’d be happy to hear your take on things.
I'm surprised the StockRank is so low, given that Beeks is now profitable.
Graham’s Section:
dotDigital (LON:DOTD)
Share price: 86.6p (+2%)
Market cap: £259m
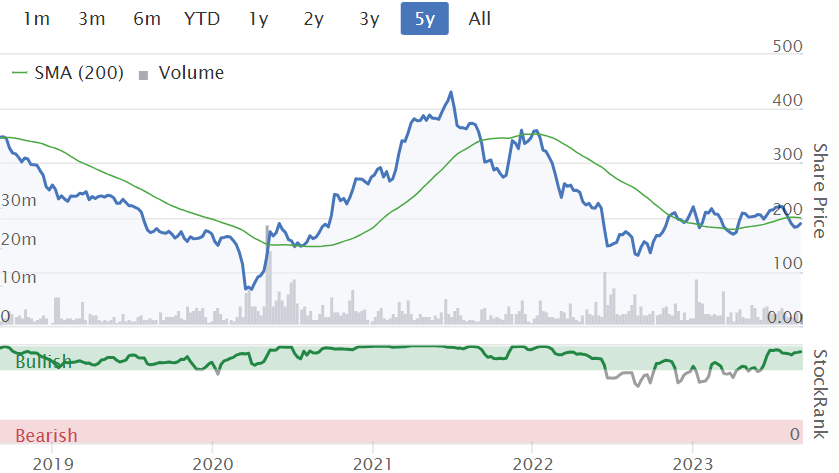
These shares have retreated a very long way from the heights they reached during the Covid rally:

Let’s see if we can untangle some word salad:
Dotdigital Group plc (AIM: DOTD), the leading SaaS provider of an all-in-one customer experience and data platform (CXDP), is pleased to announce the acquisition of Fresh Relevance Limited ("Fresh Relevance"), a vendor of cross-channel personalisation technology ("the Acquisition").
In simpler English, Dotdigital provides a marketing platform.
The company it’s buying, Fresh Relevance, helps companies to target individual customers with personalised product recommendations, personalised emails, etc.
The acquisition “accelerates Dotdigital's CXDP roadmap, bringing highly complementary cross-channel personalisation and website technology together with technical expertise”.
The two companies are said to have “a strong existing relationship and a proven track record of joint success”. They already have joint customers and their respective products already enjoy a level of integration with each other.
The goal is that with them being fully integrated, customers will enjoy a more seamless experience and the improved joint offering will “open up substantial new, higher value customer acquisition opportunities”.
The Fresh Relevance brand will be maintained.
Price - it’s a £25m deal, £19m in cash and £6m in DOTD shares. Dotdigital will still have a cash balance of £38m after the deal, “giving the flexibility to look at further strategic acquisition opportunities”.
Valuation - not particularly cheap. Dotdigital is paying a price to sales multiple of 4x (expected revenues are £6m) and it sounds as if there will be no contribution to profits in the current financial year (FY June 2024)
CEO comment:
"The acquisition of Fresh Relevance and its expertise in the realm of web significantly enhances our personalisation capabilities and provides opportunity for average revenue per user expansion. Its addition marks a leap forward in our CXDP growth journey, bringing together customer insights, cross-channel engagement, and on-site personalisation capabilities to provide marketers with the tools to exert greater influence across the customer journey.
Graham’s view
Despite the full-looking price paid, I’m going to give this deal two thumbs up.
There are times when I have to do a lot of work to figure out the point of an acquisition. This is not one of those times: the companies already serve the same companies with products that are so complementary to each other that they have already been partly integrated.
In a situation like this, it’s harder to find a reason not to combine the two enterprises. They can now work together more efficiently for their existing customers and improve their service to target new ones.
On the financial side of things, Dotdigital can afford it and still has a significant cash balance.
As for the merits of DOTD shares, I see that Paul covered them in March (at 93p) and in November (at 85p) and was positive on each occasion.
Dotdigital itself trades on a P/S multiple of about 4x but it is profitable:
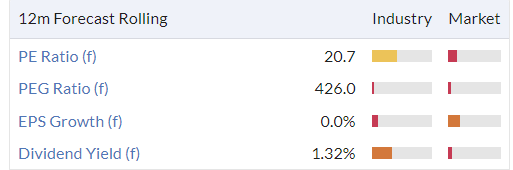
Although the SCVR doesn’t have a “House View”, I think I’ll maintain the positive view on these shares as the valuation doesn’t seem too excessive when you consider that it has net cash, a fine track record of profitability, and good quality metrics. So it’s worth studying in greater detail.
Today’s acquisition will boost revenues by around 10% and should eventually help to boost profitability, too. That might take a few years but then patience is a virtue!
Halfords (LON:HFD)
Share price: 190.6p (+2%)
Market cap: £417m
Halfords Group plc (“Halfords” or the “Group”), the UK’s leading provider of Motoring and Cycling services and products, today announces its trading update for the 20 weeks to 18 August 2023 (the “Period”).
Here are the highlights from this trading update, which reports that trading is in line with expectations despite unfavourable weather:
Like-for-like revenue +7.8% (i.e. keeping up with inflation).
Services/B2B is now 48% of total revenues, up 6 percentage points.
“Market share gains across all categories and in line with expectations.”
Cycling-related revenues reduced slightly, and this is attributed to bad weather and low consumer confidence.
CEO comment:
"It’s been a good start to the year for Halfords, and our ongoing focus on essential maintenance and servicing is driving a strong performance in our Autocentre and Retail Motoring business. Group Motoring, which now accounts for over 75% of our total sales, is a resilient sector and we’re progressing with our long-term plans to become a one-stop-shop for motoring ownership.
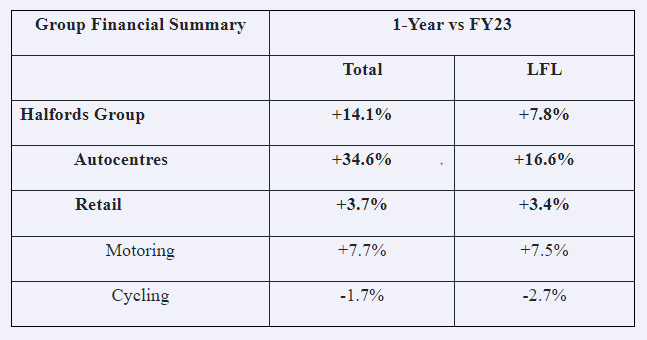
Here is a handy table showing how the Autocentres are growing faster than Retailing, even if you strip out acquisitions and focus only on the like-for-like column:
Strategy: on track for £30m of cost savings. Large commercial fleet servicing contract with Yodel. Motoring Loyalty Club has 2.5 million members.
Outlook: there’s a wide range of possibilities with full-year PBT for FY March 2024 expected between £48 - 58m. Total revenues are in the region of £1.7 billion so profit is the difference between two large numbers!
The cost savings are expected to improve profits in H2, while H1 will be held back by the accounting of some FX hedging contracts.
Graham’s view
On the face of it this stock is cheap:

They’ve done a lot to move away from their traditional cycling and retailing image, with a move into essential services. The intention is to be “a more resilient business with higher customer retention, lower risk profile and stronger and more sustainable returns on capital”.
It would therefore be incorrect to write this off as a low-quality retailer: with the help of acquisitions and strategic focus, it’s a different animal now.
But is it “quality”? It has a well-known brand but it’s operating in a very competitive sector. And despite its strategic changes it’s still a fundamentally low-margin business, although it’s hopefully less risky than it was before.
Paul did a great analysis of this one in June and I would echo what he said about the company’s balance sheet - not super strong (equity of £563m but that comes with a huge pile of intangibles, and large leases). Therefore I would also think that the dividend here could potentially be vulnerable in future.
I have little choice but to take a neutral stance. It’s an interesting stock but I wouldn’t be in a rush to buy it despite its superficial cheapness.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

88 comments
Beeks Financial Cloud (LON:BKS) This highly rated software company updates the market with a statement that is actually a profit warning, but attempts to gloss over it in the hope that virgin investors will be deceived. Unless there is a dramatic improvement in the company's prospects, then the price will be significantly lower in a couple of months than it is right now.
Hi Gimmers, thanks for the comment. I don't see any news on SDI apart from the appointment of a new COO. Unless something changes I probably will take a positive stance below £100m market cap . We are already at an unusually low earnings multiple. Big director sales in recent years were at 165p-195p. A c. 50% discount to that level would provide some comfort. G
Thanks Graham! Appreciate your comments and personal thanks to you and Paul for doing such a great job! :)
You're very welcome Gimmers! G
Beeks Financial Cloud (LON:BKS)
However, strong current trading and reiterating FY 6/2024 guidance (of £30m revenues, and increased profits) is encouraging.
Is this not a potentially a con though ??- if £2.5 mill of sales has been delayed into q1 next year - should they not be £2.5 mill ahead of where they previously expected - if they had previously expected those same sales to be in this year just finished. I am presuming its simply contract delays here - not sure if that was confrimed or not ?
Seems kinda "sketchy behaviour" pimping up material sales increases during the year then taking them away after year has finished (timely update to market please) - then double counting them by boasting about the same sales in the next year !
how would outlook have been had they booked the shortfall this year as they expected to till the very last minute ?
2023 sales say 24.5 mill
2024 sales 27.5 mill (i have used broker note on their website 29.1 mill less £2.5)
expected 12% increase
almost makes me wander if it suited them to have the sales slip so the future narrative remained good.
I always worry if companies might need near term funding that they are either consciously or subconsciously biased towards putting "best possible narative forward" - thats probably looking after those already invested - but screwing over those that hadnt earlier but did so on basis os promises likely being met.
Fair play for putting up targets and missing - but imho they should have updated earlier - or not ben over optimistic and they should have been more workmanlike in how it was comunciated too.
As a non holder if they are on track for 2024 those are genuine numbers (ie not pimped up) and the shareprice is depressed due to lack of "investor faith" then perhaps the price now looks attractive (is it pe off11?) - then again perhaps stocky "sucker stock" clarification is right.
Hey ho no doubt if future news aint good price will continue to drop in advance (coincidence?) and if futuire news is good no doubt shareprice will have risen back up before we get reeasonable clarification they arent going to screw us over this year.
Not sure what companies history is but they should be ensuring there is no repeat this year due to excess enthusiasm.
Think for now i am happy sitting on the fence.
Any company that is using any form of XYZaaS model for it's revenue is going to go through the same thing Beeks Financial Cloud (LON:BKS) is going through. Revenue takes much longer to build up than it would with the traditional approach of selling hardware and charging support & CRs. And of course their upfront commmitments are significant.
I have a small holding. Not tempted to increase it or to sell at the moment. I lost out on Sage (LON:SGE) by selling out too early (albeit at a profit) when they went through the pain of adopting a SaaS charging model. So planning to be more patient this time. Disappointed through that the RNS wasn't as open and clear as it should've been.
Sage (LON:SGE) - it can be frustrating holding and shares not delivering sage for me has been a proper example of playing long game - I bought when price had previously spiked over 900p thought it must be worth a punt when it dropped to 360p (I knew it was a good business fundamentally) - after purchase it went below 100p.
The secret to success was simply waiting the 23 years needed for sage to get back to its 1999 highs - we are there now thankfully so acceptable result I guess factoring in divis, shame I didn’t do a Paul and load the boat at the bottom hey ho.
Can anyone beat 23 years for share to beat prior peaks without going bust in the meantime ?
As an aside sage was the first share I ever bought - hmmmm now where is my paper certificate ?
£bks
I understand fully about the long game - what the saas model - agreed it takes time to build that’s known and factored in - in some respects because it takes time to build recurring revenues missing on revenue late in year is extra surprising - they might have been unlucky with something lumpy but it should be reasonably easy to plan conservatively and deliver with perhaps a beat on top - it’s poor form imho for them to do what they have done - so late in the day albeit as one of one might be tempted to give them a pass. To me there is more to like here than not like but the reality is it’s not as good as they have led us to believe previously particularly if they have boosted new year by stealing from one just finished .
Grateful for the Halfords (LON:HFD) update. I did hold for a period of time as I think managements focus on a move to the more profitable service side of the business and larger one-stop shop sites made a lot of sense. My worry with Halfords, however, was its significant shortfall in service technicians and the plan for correcting this didn’t seem achievable (focus mainly on attracting under-represented groups into apprenticeships). If anyone has any recent updates on how Halfords are progressing with their recruitment plans I’d be happy to hear them as I do feel the rebalancing of the company makes it a good medium term bet, but only if there is definite progress on closing the recruitment gap.
Halfords (LON:HFD)
My worry with Halfords, however, was its significant shortfall in service technicians and the plan for correcting this didn’t seem achievable (focus mainly on attracting under-represented groups into apprenticeships).
Seems like thats a great long term plan to me - if it ups the numbers (rather than simply keepong numbers the same and replacing with less able applicants)
I would agree short to medium term - its probably going to involve going backwards before you go forwards if its trying to replace qualified with unqualified.
I guess its also likely to fail if there is zero plans to keep the peeps who are fully trained up and will need market rate wage thereafter.
I was at one of their National Tyres centres the other day and it was noticeable that there were female technicians as well as someone with a disability, so maybe the strategy of getting under represented groups in is working. Obviously I've got no idea how long they've been there or if they're even in apprenticeships, but thought I'd mention it in the context of this discussion.
For what it's worth, their MOT price was good value (compared to the competition) and carried out efficiently with no hard selling.
I don't hold Halfords (LON:HFD) .
Here's the Headlam (LON:HEAD) management presentation and Q&A from yesterday video & podcast.
Highlights were:
Forthcoming management webinars with Q&A, register for both here:
This afternoon, 3pm Somero Enterprises (LON:SOM) H1 2023 webinar, following results last week.
Friday 8th September, 12.30 Pebble (LON:PEBB) H1 2023 following results yesterday.
Recent profit warning rns was
Headlam (LON:HEAD) "Flags weaker-than-expected trading volumes in residential segment, expects recovery in sales volumes to take longer. "
Highlight 4p interim dividend was cut from 6.2p!
Hi Paul,
Really nice prestigious contract win for Restore (LON:RST) up to £140m over 5 to 7 years. Looking forward to the revised broker forecast. Shares currently up nearly 16%. Hopefully you're still holding some for the gain.
Hi Paul and Graham,
Please can I have your thoughts on Headlam (LON:HEAD) from yesterday? Did you catch up with Tony Brewer from Likewise Group?
Hi Mark,
Yes, i'll circle back to Headlam (LON:HEAD) either tomorrow or Friday, it's near the top of the list!
Regards, Paul.
Sometimes luck is a huge part of it isn't it. I bought LungLife AI (LON:LLAI) a while ago at about 80p, it dropped to 20p so I averaged down to 60p average, seems like it could be very useful for early cancer diagnosis. It's now up over 500% to 108p over the last 2 months, no idea why.
I don't have much in and sold a few just in case.
Anyone else got a view on this one?
"AI" is the new ".com"? etc.
M Winkworth (LON:WINK) Solid interims ,despite profit down 24%. Dividend increased. Expect to be able to weather current difficult market and make improvements eg change some underperforming franchise holders. Increased cash holding. Lettings very busy, but expected to tail off due to post Covid normalisation.
I much prefer these over Belvoir (LON:BLV) ....but I am biased.
Hi Deegee,
I like all of the franchised property guys.
Curious what you see as the key differences between Winkworth, Belvoir (and maybe TPFG), and how you came to your preference?
Good morning Paul & Graham,
Can I request you take a look at Gateley (Holdings) (LON:GTLY) today?
They seem to be succeeding where the other listed law firms are failing- a decent track record of revenue and earnings growth with a progressive dividend policy (yield now approx 6%) and (perhaps most importantly when cf listed peers) relatively low indebtedness- maybe because they're attempting to grow at a more reasonable pace?
Also, the SCVR has previously commented on Tpximpact Holdings (LON:TPX) - there was an update on trading yesterday which might have been missed
Thanks!
Graham would appreciate your thoughts on SDI (LON:SDI) following your comments on 8th August - "I’m not ready to go green on SDI yet but I think it’s starting to look interesting at a sub-£130m market cap. I think I’d be very interested at a £100m market cap". I am having another look at SDI (LON:SDI) - one of my best returning shares for some years - and see market cap down to £107m this morning. Apart from market sentiment following recent updates, I cant see any other reason for the continuing drop. Any thoughts/comments would be welcome. I can easily see SDI (LON:SDI) becoming a potential target for Judges Scientific (LON:JDG) ?
Not sure about SDI (LON:SDI) becoming a potential target for Judges Scientific (LON:JDG. Judges tends to buy smaller privately held businesses at significantly lower multiples. Other than that SDI is a very interesting business. I have been wondering, though, about the recent appointment of a new CFO. Given the small size of the central function, the previous CFO must have been a key part in the evaluation and the negotiation of acquisitions. Let's see how well the new guy does.
Completely correct Wol,
There is no chance of Judges Scientific (LON:JDG) buying SDI (LON:SDI) due to the strict acquisition criteria.
Thanks Cocker - I don't follow JDG these days so not aware of their criteria (sadly sold out at £15 - my bad!)
David Cicurel did mention a few years ago that he had held SDI (LON:SDI) shares before in his personal account before selling them on valuation grounds . So he has given it a small seal of approval ….
The problem with SDI (LON:SDI) is the debt. While they claim to make their new acquisitions from retained profits, net debt has risen from £m1.81 in 2021 to £m6.33 in 2022 to £m20 in 2023. This is a very steep rise, and occurs at a time when debt is becoming increasingly expensive.
Yes I agree about SDI's debt john2 and I would also note that at least one of their recent acquisitions have gone wrong. I would recommend viewing their results presentations on Investormeet. Some of the remarks made by their CEO, Mike Creedon, are a bit unorthodox (such as his limited interest in financial markets) and although a personal thing, I wonder if his "cheeky chappie" style might irritate some company owners, although he hasn't done badly up to now.
Severfield (LON:SFR) - Severfield have updated trading this morning - not exactly bleak, rather holding up well in the current circumstances - but Paul - you were right back in June when you said - ' not for me' and today the shares have tumbled 5% though seem to be recovering a bit already. I hold and will continue to do so, though with that proverbial hindsight should have sold long ago.
meant to mention - there is at least a decent divi!
I think the key question is have they resolved the issues with the Labour force and the work to rule/strike that was ongoing?
The other key is understanding the contracts, how and when do inflationary clauses kick in and where are the gremlins of jobs that were bid 1 or 2 years ago at a steel cost a lot lot lower than the current environment?
And obviously there is always the job that goes wrong! This is Construction after all.
Sorry my industry so don't invest in it...
Good luck!
Tommy
Hi,
I just wanted to post a quick comment to personally thank Paul and Graham for their research.
Directly due to Paul's recommendation on POS I am now above break-even for the last two years.
I personally hope Paul, Graham and Roland will continue their high quality company reviews here for many years to come.
Hi c038644,
Thank you for your kind message! That's great you've achieved breakeven over the last 2 years, no mean feat given how the small caps market is down 43% in that timeframe! I'm pleased you've done well on Plexus Holdings (LON:POS) (I hold).
Although just to clarify one point, we never make "recommendation"s - we're just flagging up ideas for you to research yourself in more depth.
As we're flitting from one thing to another here, these are just brief reviews, and it's entirely possible that we might miss something important. Hence why it's so vital you do your own more detailed research (and let us know if there's anything important we've missed).
Best wishes,
Paul.
Filtronic
I hold
Had a very interesting conversation with a well regarded manager who has done a lot of deep digging on Filtronic and holds a decent position (can’t mention names)
Technology they have is seemingly now being bought by Elon Musks crowd as well as the recently announced 3.2m contract with European space agency .- headline grabbing names but “talk is cheap cash buys houses” so hot air really .
Admittedly Filtronic appears to have failed to deliver much on the past but looks to be well placed with good technology in a pretty amazing sector .
I’m still trying to understand the business and at the moment it’s definitely outside my circle of confidence as I am no rocket scientist .
At the moment it’s more of a “follow the smart money” move whilst building a position and trying to understand it .
I’m going to ask them if I can go for a look round so if anyone else would like a company visit who is holding maybe come along
Two benchmark comparator stocks are Texas Instruments (NSQ:TXN) and Analog Devices (NSQ:ADI), who are amongst the biggest in mixed signal semiconductors.
Of course Filtronic is a minnow in comparison and the financials are in different worlds, but if you want to understand the business you'll need some familiarity with them.
Filtronic (LON:FTC) has been immensely frustrating from an investor perspective over multiple decades. I think part of the problem has been that Filtronic are just so much smaller than many of the companies they supply, and seem to have the weaker hand when it comes to negotiating commercial terms.
the Boohoo (LON:BOO) comment. i suspect the motivation might be the rise Plexus Holdings (LON:POS) and perhaps a little jealousy that Paul's largest position is doing so well!! i'm delighted to see so many subscribers write at length in defence of Paul. I DYOR and find Pauls + team contribution invaluable - thks!
I Cant believe the rise! I am definitely gutted i didn't have a look myself and take the risk, after Paul covered it. Reward seems to have out weighed the risk in this occasion! I also find Paul + teams contributions invaluable and educational.
If Paul is anything like correct in his assessment of Plexus's future Mrk Cap value , its not too late to take starter position now.
I'm really pleased to see the rise in Plexus - I know Paul had difficult year in 2022 so very good to see this year going so well.
I suppose it's inevitable that when a very well regarded and trusted expert puts a meaningful percentage of their portfolio in an absolute minnow - and publicises that very well - that it will rise very quickly. I find it a very good and important test of character. I at times can feel overwhelming amounts of FOMO (and I expect I will continue to do so given it'll be mentioned quite a number of times going forward - over years perhaps) but it's a real moment to take a breath out, appreciate all the excellent knowledge/wisdom shared by almost all of us on this platform, and trust that your strategy is right for you and, by sticking to it, you should also reap the rewards one day.
It's not easy. A real test of character. Unfortunately some don't pass the test (I expect we've all been there at one point in time) but it's yet another important chance to learn and get better.
Does seem a very sour grapes comment
I've lost so much money on Boohoo (LON:BOO), but can only blame myself for that. It did look like a fantastic opportunity at the time for a company that had a fantastic track record, and Paul rightly pointed that out. I can only blame myself for not selling out when things went south for the company as well as the whole sector. I'm still holding so hoping it will turn around at some point, although it's not something I expect to happen anymore...
Hagon - you are not alone!
Good half year report from Bakkavor (LON:BAKK): “Strong first half performance, with momentum continuing into H2”. Maybe the world is eating out again?! Stocko momentum rank has been going down, so hoping this turns it upwards (I hold).
On a positive note...
I would just like to highlight to subscribers here the superb catch up yesterday between Paul Hill and Paul Scott on Vox Markets (I watched on You Tube).
The conversation covered the macro position and stocks insights, but for me the best parts were the frank exchanges around winners and losers - with a bit of psychology of investing thrown in.
Great stuff - Thanks' to both Pauls, I look forward to the next catch you guys do .
Andy.
Well worth a watch, those two bounce of each other really well!
Thanks Andy! Yes I really enjoy my quarterly catch ups with Paul Hill, we always seem to bounce ideas around, and could go on for hours! I listened back to it last night, and have to say I enjoyed listening back to it myself!!
Paul - Yes a great listen as always - Perhaps you need a can of that special "Chilled" drink before every future catch up with Paul Hill, you did seem very calm and focused this time! (Sorry people an in joke for those who have listened to it already, we do all seem to be getting a bit off topic in this heat today)
A super trading update from Beeks Financial Cloud (LON:BKS) "Revenue for FY23 is expected to be over 20% higher than FY22, delivering underlying EBITDA(1) growth of over 35% and underlying profit before tax(2) growth of approximately 10% versus FY22.". Quite a relief, as one of my larger holdings. Would love to hear your thoughts Paul, thanks.
Beeks Financial Cloud (LON:BKS) update is a mild profit warning....
Agreed this is a mix bag update in my opinion. There was a revenue miss which the update seemed to try and gloss over by saying by august the run rate was 25m. There was no mention of any profit either which I am okay with it they are investing for growth.
On the positive side they were cash flow positive in the 2nd half of the year but again with Capex being a big cash driver we have no idea whether they just paused that side. Still a question whether more fundraising is needed.
It remains a great opportunity but the challenges of getting new customer signed up is stalling the growth story. I still hold but am not as enthusiastic on this as I was a year or two ago and am not willing to invest more.
Yes it is.
I assume you are referring to the requirement of a fundraise rather than it remaining a great opportunity Yiannos?
I am referring to the well hidden mild profit warning.
Expected revenues were £26m for FY23 and EBITDA at £9m. But they chose to fool investors by just talking nonsense.
Beeks Financial Cloud (LON:BKS)
Gordon McArthur has form for over-promising. I understand he is excited but it spoils things from an investment perspective. Beeks do seem to potentially have something special but over-promising tempers this.
I want to invest in companies which under-promise and over-deliver, and management who do what they say. Managing expectations is an important skill for directors to master.
I think it is actually a statement worded cleverly to focus on the fact it hasn't had as many big contracts as expected. Personally I think it might drop a bit at the open!
its up a little at the moment but agree this could go either direction. Don't forget its already come down such a lot in the last year that a lot of this might be priced in
I hold a small position, but am sitting tight, I agree with you that the recent drop has been so significant that a hit to growth must be heavily baked into the price. I am a bit disappointed that management have chosen to write the RNS in the manner they have, it is a bit of a smokescreen.
If I was being harsh I'd say it's up on deliberately obscure wording that fails to acknowledge a miss of expectations. Would have thought the market will see through this as day progresses.
Cash is ahead of expectations
EBITDA about £0.5 shy of analyst forecasts
But nonetheless a 20% growth rate is good and 80% 2024 revenue visibility is excellent.
The market it is in contracts can take time but they are very sticky
Investors need to stop being so fixated on a balance sheet date at a point in time
Cash ahead presumably because Sales are short.
EBITDA perhaps not the best metric considering constant cap-ex, & still shy.
Would have thought Beeks Financial Cloud (LON:BKS) investors have already proved a decent level of patience.
Spot on Darktrade. EBITDA is not a good measure for a company that has to lay out so much capital expenditure:
1. to provide hardware for new contracts
2. to keep hardware up to date and functioning
'Underlying' EBITDA is definitely not a good measure for Beeks Financial Cloud (LON:BKS. We will need to see good free cashflows and good cash returns on investment before we can be confident that the business model is really working. As an ex holder who would like to jump back on board I hope this happens soon
Looking through my logging of my notes on Beeks Financial Cloud (LON:BKS) - this is the trail of conclusions I'd come to since tracking at the start of 2022:
I need to dig into my detailed notes later today, but somehow in my mind it seemed clear back in July that the H2 results would be disappointing...
I do have a silly 46p buy price target on this :)
Boon - Very bold of you to publish today (of all days), your opinion and time line on a share
I hope in 2 years time someone doesn't dig it out and hold it against you