Small Cap Value Report (Weds 7 July 2021) - TLY, KINO, ACSO, SOM, WIN, QTX, REDD

Good morning, it's Paul & Jack here with the SCVR for Wednesday.
Timing - today's report is now finished
Disclaimer -
A friendly reminder that we don’t recommend any stocks. We aim to cover notable trading updates & results of the day and offer our opinions on them as possible candidates for further research if they pique your interest. We tend to stick to companies that have news out on the day, and market caps up to about £700m. We avoid the smallest, blue sky type companies, and a few specialist sectors (e.g. resources, pharma/biotech).
A central assumption is that readers then DYOR (do your own research) and discuss in the comments below. The comments, incidentally, sometimes add just as much value as the articles. We welcome all rational views, whether bull or bear!
It's helpful if you include the company name or ticker within reader comments, otherwise some readers may not be aware of what company you are commenting on.
Agenda -
Paul's Section:
Totally (LON:TLY) - results from yesterday. Only trading around breakeven at PBT (I see EBITDA as a red herring, due to high depreciation & amortisation charges). Growth potential, but for me the £77m market cap looks high enough, or too high for where things currently are.
Somero Enterprises Inc (LON:SOM) (I hold) - what a lovely company! High quality, cash generative, and we're treated to another strong trading update today. Broker forecasts go up c.14%. Still looks good value to me.
Quartix Technologies (LON:QTX) - an in line with expectations update for H1, and confirms full year guidance. Impressive growth in fleet numbers, and overseas expansion going well. Valuation is too rich for me personally, but I like the business and management.
Redde Northgate (LON:REDD) - as it's not a small cap any more, I've commented on its results today in the comments section below this article, so please see that area if you're interested in this company.
Jack's Section:
Kinovo (LON:KINO) - notes from a follow up Q&A session with company management following yesterday's results, which saw the share price fall c7%.
Accesso Technology (LON:ACSO) - revenue expectations for FY21 have been upgraded again, this time to more than $100m. Trading sounds encouraging but not much to go on yet in terms of concrete figures.
Wincanton (LON:WIN) - strong momentum also in evidence across the logistics sector. Wincanton looks well placed to benefit but the share price is already comfortably above pre-Covid highs.
Paul's Section
Totally (LON:TLY)
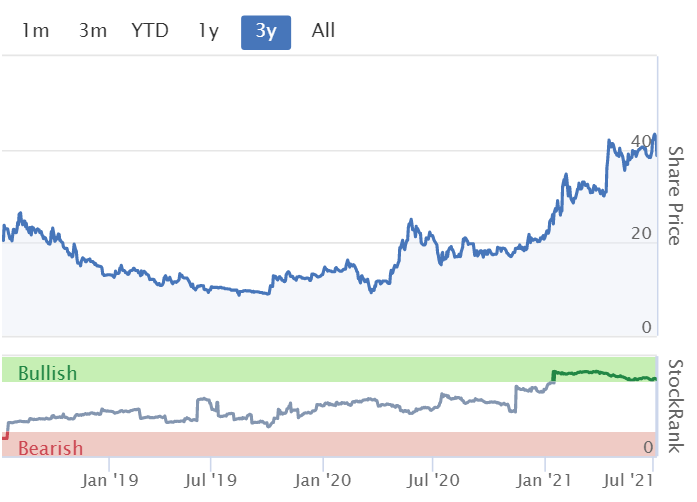
38.7p (down 9% yesterday) - mkt cap £77m
Totally plc (AIM: TLY), a leading provider of a range of healthcare services across the UK and Ireland, is pleased to announce its preliminary results for the 12-month period ended 31 March 2021.
Title -
Record Revenue and EBITDA
Key points -
Impacted in various ways by the pandemic
Revenues up 7% to £113.7m, 93% of which is called “Urgent care”, which I think is mainly operating the NHS 111 phone line.
Low margin - gross margin of 18.3%
EBITDA of £5.0m, up 25% on LY (H1: £2.3m, H2: £2.7m)
Profit before tax only £0.1m (LY: £(3.4)m loss) - why such a big shortfall between £5.0m EBITDA and almost breakeven at PBT? (large depreciation £2.0m, & amortisation £2.8m charges)
Dividends of 0.25p interim, 0.25p final = 0.5p for the year (yield of 1.3% - low, but in a pandemic year when many companies suspended divis)
Presentation due on InvestorMeetCompany platform at 14:00 on 14 July 2021. There are 2 previous webinar recordings available to watch, I’m listening to the interim results presentation in the background whilst typing this (who says men can’t multi-task!)
No exceptional charges this year (LY: £2.0m)
NHS is a “reliable payer”, so cashflow is good - confirmed in the figures, as receivables look low relative to revenues, and cash of £14.8m is healthy..
Balance sheet - fixed assets are only £1.1m, so how come depreciation charge is £2.0m, seems too high? I suspect this may be due to IFRS 16, where some rent payments end up in depreciation & finance charges (ridiculous).
NAV is £34.0m
Intangible assets are £37.5m, deduct that, and we get £(3.5)m negative NTAV - not great, but given that it’s a capital-light business model, and receivables are low, the balance sheet seems perfectly adequate.
Cashflow statement - cash rose by £5.87m, but this is mostly due to £2.71m +£2.04m = £4.75m favourable working capital movements (receivables, and trade payables).
In my view, the business itself is not generating much free cashflow, once you strip out favourable working capital movements (since they can easily reverse in future years). Payments to HMRC were de
My opinion - I can’t get excited about this. Providing these services to the NHS involves a lot of work, and the margins are low. It’s only trading at around breakeven at the PBT level (EBITDA of £5.0m is a red herring in my view, as it ignores a lot of real world costs).
Therefore the £77m market cap looks too high, based on where the business actually is right now. Investors must be applying a premium valuation in the hope & expectation that profitability can rise significantly in future. Maybe that's justified, as management do talk about expansion.
There’s also the question of how much additional profits could be made as covid hopefully recedes?
I think this share is all about backing management to grow & develop the business. Subjectively, I imagine that management talk the right sort of language to reassure & connect with health professionals - their background is steeped in the NHS, a good thing. That’s probably why contracts tend to renew, and there’s an opportunity to gradually win more business from weaker competitors, perhaps.
I can see why investors might want to back this management team, but the numbers just don’t stack up for me personally, at £77m market cap. As always, I've no idea what the share price is likely to do, because that's driven by sentiment, we just look at the fundamentals in these reports.
.
.
Somero Enterprises Inc (LON:SOM)
(I hold)
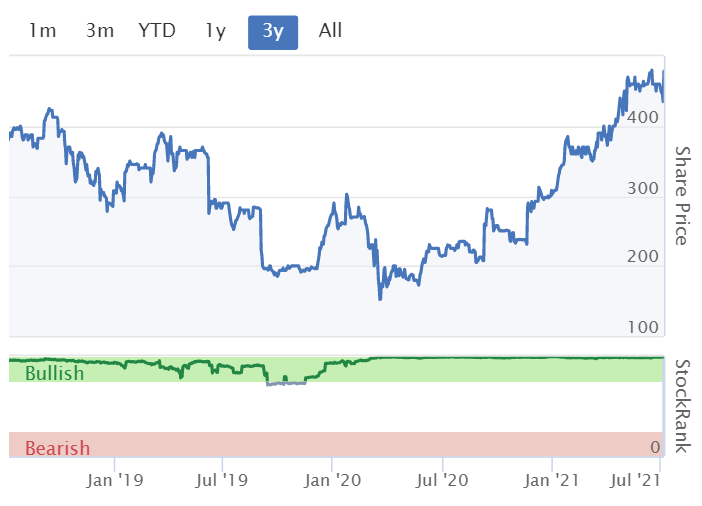
435p - £250m mkt cap
Somero® is pleased to provide an update on trading for the current financial year, ending 31 December 2021 ("FY 2021") following the end of its first half ended 30 June 2021 ("H1 2021").
Raising guidance due to stronger than anticipated trading in the US to end H1… and with this momentum carrying over to begin H2 2021, it now expects to exceed previous guidance for FY 2021 established in the 6 May 2021
Old guidance -
The Company's previous FY 2021 guidance indicated revenues were expected to approximate US$ 100.0m, adjusted EBITDA would approximate US$ 31.0m and net cash would improve consequentially from the original US$ 27.4m target established in our 10 March 2021 final FY 2020 results statement.
New guidance -
The Board now expects FY 2021 annual revenues will approximate US$ 110.0m, adjusted EBITDA will approximate US$ 35.0m, and year end net cash is expected to exceed US$ 33.0m.
That’s a 10% upgrade to full year revenues, and 13% increase in EBITDA guidance.
Or, $10m additional revenues, and $4.0m additional EBITDA. That makes sense, given that the gross margin was 55% last year, so today’s upward guidance allows for $1.5m higher overheads (i.e. $5.5m additional gross profit, resulting in $4.0m additional EBITDA).
Other points -
- Strong trading in May & June 2021 in its main market of the US.
- Higher momentum is carrying over into the start of H2
- Customer workloads at high levels, extending into 2022 (backlogs from covid) & healthy construction market (non-residential sector)
- eCommerce requirement for new warehousing is mentioned as a driver for growth
- Other regions trading in line with expectations
- New products contributing meaningfully to growth as expected
- Pipeline of new products to expand addressable market
- Dairy date 8 Sept 2021 for interim results to 30 June
Valuation - Finncap has issued an update. Price target going up to 590p.
Profit forecasts go up 13.6% this year and next year:
FY 12/2021: 45.4c = 32.9p (at £1 = $1.38), a PER of 14.3 (based on 470p current share price)
FY 12/2022: 48.7c = 35.3p, a PER of 13.3
My opinion - Somero looks good value to me, for such a high quality, cash generative business. It pays out cash in divis, and retains a strong balance sheet. This share seems woefully under-appreciated by the market, and always has been. I think it could sensibly re-rate to a PER of 20+ in the current market, so there’s good upside if I’m right about that.
Obviously we have to take into account that it’s a cyclical business, so how you view it depends on where you think we are in the economic cycle? My view FWIW is that it’s looking increasingly as if we’re in the early stages of an economic boom - which tend to last several years before things overheat & crash.
Personally I’m sitting tight with no plans to sell, or trim my existing holding in SOM. Obviously it’s up to you what you decide to do with your own money, e.g. some people like to bank profits when things rise a lot, or top slice some of them. For me though, the compelling value means I’m sitting tight for the foreseeable future. A takeover bid wouldn’t surprise me, as a bidder could pay the customary c.30% bid premium, and still buy it at a reasonable price, load it up with debt, and pay off the debt from the cashflows. Looks an obvious candidate for private equity in my view.
.
.
Quartix Technologies (LON:QTX)
489p (flat today, at 11:27) - mkt cap £237m
Quartix Technologies plc, a leading supplier of subscription-based vehicle tracking systems, software and services in the UK, announces that it will publish interim results for the six-month period ending 30 June 2021 (the "Period") on Wednesday 28 July 2021. They will be posted on the Company's website that morning, together with accompanying presentations.
Quartix has traded well in H1
Strong growth in new fleet telematics installations
FY 12/2021 guidance -
In line to achieve consensus market expectations for the year
1 The Board believes that consensus market expectations for 2021 prior to this announcement, were as follows: Revenue: £25.6m; Adjusted EBITDA £5.1m; Underlying Free Cash Flow2: £4.0m.
H1 guidance -
The Board expects to report revenue of £12.5m, adjusted EBITDA of approximately £2.7m and underlying free cash flow2 of approximately £1.3m for the Period. The Company's cash balance was £4.2m at 30 June 2021.
Supply chain issues - this is self explanatory, and doesn’t sound concerning to me -
Although the sourcing of electronic components has been challenging during the first half, the Group has been able to secure its production supplies and remains confident of doing so through the rest of 2021. This has, however, been at the expense of higher costs in some cases and of needing to purchase larger quantities where components are available. This has had an impact on free cashflow in the Period and could have a moderate impact on free cashflow for the year as a whole if contingency stock levels need to be increased, but the additional costs are not expected to have a material impact on the Company's expected financial performance for the year.
Other points -
- Strong growth in new installations - 31% ahead of H1 2020, and 13% ahead of H1 2019 - good to see both comparatives
- Fleet subscription base is up 8% in the last 6 months, to 188,155 vehicles
- Insurance telematics - forget about this, it’s been winding down and is not significant
Current trading -
All major territories are now operating at above pre-pandemic levels with the exception of the UK, where record orders in H1 2019 were driven by a significant number of larger contract wins and distribution orders. This will be an area of focus for the Company's sales teams as contact restrictions are lifted.
New installations in international markets exceeded those in the UK for the first time, and performance in the Group's new territories and France were particularly encouraging.
Further investment initiatives are already underway which are expected to contribute to continued growth in the second half.
My opinion - every time I report on Quartix, I bellyache about the valuation being high, which it is. Based on current forecasts, the PER is now in the 50s, for this year and next year.
Is it a speculative frenzy then? No, I don’t think so. High valuations are often just a sign that the market believes in strong growth to come, and that forecasts are likely to be beaten.
The international growth is going well, and again that could be a reason why the valuation is so high.
Quality metrics are excellent, and often it can make sense to pay up for quality in the long run -
.

.
The founder + family trust sold 7.2m shares at 401p in Jan 2021 (grossing £28.8m), but retain a very substantial remaining 10.66m shares.
Overall, for me, I like the business and management, but can’t get my head around the valuation.
.
Jack’s section
Kinovo (LON:KINO)
Kinovo management discussion
I spoke with Kinovo management about their results yesterday, which caused the share price to fall c7%. First CEO David Bullen rattled off some points and then there was a more unstructured Q&A chat.
Notes are a little rushed - it’s hard to listen to, ask questions, and type up notes on a one-on-one video call to C-suite!
Key takeaways:
- This is a resilient performance given Covid disruption; £60m revenue is a good result
- H1 everyone was in the same boat; lockdown
- H2 was more complex with variable government tiering and new Covid variants; didn't re-furlough beyond initial wave; access rates to sites were an issue in H2
- In March 2020 the share price dropped down to 8p, so the company has proven its ability to navigate these tough conditions
- Net debt reduction and strong cash generation. Less than 1x leverage. Focus on WC efficiencies & investments during the year. However the cash conversion of 156% is likely unsustainable (see below)
- Divi subject to AGM - 1) nod to historic investors, 2) put a flag in the sand re. historic issues
- Rebranding & repositioning is important as it closes the legacy off & provides clarity on direction
- Underpinning that is recurring rev. £170m over three years, which doesn't include any frameworks like fusion 21, electrical, SSE for new build
- Will continue to focus on local auth housing associations, compliance and sustainability, long term contracts, recurring revenue, strong cash generation
Questions:
What is your competitive strengths that keep others at bay? Closest competitors?
End-to-end services help to strengthen the market position. The three Rs of recycling, renewables, and regeneration leave it well placed for organic growth (it’s a huge market).
Regarding its divisions of Mechanical, Electrical, Building Services, and Construction: there’s often a dividing line between mechanical + electrical and construction. Construction will be small scale but important as new builds will have to comply with sustainability initiatives, eg. no new gas boilers from 2025.
Kinovo’s businesses complement each other in terms of crossover work.
Huge market opportunity from existing and prospective clients.
Market shake up / disruption?
There was no supplier support or client support and limited government support for Kinovo.
Shake up has yet to come as there has been a lot of government support for others. That should unwind as support withdraws and some of it must be repaid. Also some inflationary elements (as companies in other industries have reported) so more to come.
Covid has become a positive and it’s possible that struggling competitors could be a tailwind down the line.
What is your target margin on a long term view? Gross and operating.
Run rates - gross margin dipped down during the year (covid related) down from 25% to 21%. Around half of this was down to volume and half down to less productivity and efficiency due to H2 site access issues.
They would hope for a sustainable gross margin of around 25% and an operating margin mid-single digits (north of 5%) on an adjusted basis depending on the exact nature of the contracts they ultimately win. Still low margin, so the company must be well managed at all times.
Where are you investing capital?
Historically Bilby had a buy and build focus with less attention on organic growth. This focus has been reversed under the new management, who believes there is great opportunity to grow organically.
It is building an end to end type service delivery in terms of what it offers. Build on core strengths: mechanical, building services, electrical and construction, but increase the breadth and depth across these areas. For example, Kinovo can become more involved in fire and security elements in electrical.
Compliance is non-discretionary spend. They can bring more of this house
Have ‘broken the back’ in terms of fixing the core of the business - the rebrand and repositioning, streamlining, reduction in net debt. Now it’s about depth & bredth of front end specialisation
They are not averse to acquisitions; will be very strategic to accelerate the above areas.
Why dividend over buybacks & strengthening balance sheet? Do you want any debt?
Positive progressive divi policy - older investors want income but the group will be conservative as it wants to reinvest into the business; have now got the backbone of the group, any further investment will be self-financing
Bullen doesn’t mind debt - but he wants good debt not bad debt, ie. debt taken on from a position of strength to finance growth and fund selective acquisitions, rather than an historic debt burden weighing on profitability.
By end of year the group, Kinovo should be near enough net debt free.
How much of an impact did Covid have? Why was electrical services down so much?
Struggled to access properties in H2 due to changing restrictions. This impacted electrical. Legal and regulatory work has been deferred and moved right.
Pent up demand is concrete, as a lot of the business is regulatory and compliance, which buildings will still have to do. It’s non-discretionary.
Closure of Purdy office etc. Quantify annualised cost savings
Fundraise in November, Covid in March, down to 8p and since recovered. Placing was well timed in retrospect.
Savings this year of c£1m+ but it won't all be to profit. The group is restructuring its cost base so that it can invest internally for growth.
Kinovo has moved very rapidly from survival to stability to growth in a time frame of just two years.
£4.6m cash inflow - is this a sustainable level of cash inflows? Or Covid benefits and expect moderation?
Not sustainable as a cash conversion percentage (156% this year). Internally they want high 80s; will continue to invest in the business; there is a positive one off element here.
They have invested in HR, IT, payrolls, and are offering opportunities for internal progression and personal development; improved clarity of strategic outlook. 90% of business is ensconced in ESG.
Standalone sustainability report will come out later in the year.
Accesso Technology (LON:ACSO)
Share price: 590p (pre-open)
Shares in issue: 41,245,456
Market cap: £243.4m
Accesso generates revenue from ticketing, mobile and eCommerce technologies and virtual queuing solutions for the leisure, entertainment and cultural markets. As with other leisure companies, the shares have rerated strongly amid the successful vaccine roll out and, in this instance, are now above pre-Covid levels.

It’s worth noting that the company appeared to run into problems before the outbreak though. Accesso also has a net debt position, whereas most other high quality software companies tend to be net cash, in order to bolster their often light balance sheets.

Year-to-date revenues in 2021 significantly ahead of expectations… As a result, in the absence of major new impacts from the pandemic, the Board now expects full year revenue for 2021 to be in excess of $100m.
The current consensus appears to be for around $90.5m of revenue. In the group’s AGM statement, it said that stated guidance was $83.5m so its trajectory is now well ahead of that.
Since its AGM trading statement on 18 May 2021, Accesso has continued to benefit from pent-up customer demand and the accelerating trend towards online commerce. Its virtual queueing solutions have seen demand ‘well beyond historic levels’.
Accesso has also seen a significant uptick in demand from potential customers who are looking to introduce technology upgrades as part of their pandemic recovery initiatives.
To capture this long-term revenue opportunity, the Group is currently deploying additional resources across technology implementation, product development and customer support. While these investments will have a limited impact on Cash EBITDA in 2021, their full annualised effect will be felt in the 2022 financial year.
That’s interesting. It sounds like this is more than just pent up demand, but more of an entrenched shift in the positions of its customers. It’s good to hear the company talk about investing for the long term opportunity rather than a temporary boost that will revert.
Steve Brown, accesso CEO, said:
We are pleased by the robust results we are seeing as the leisure sector reopens. We're working hard to capture strong pent-up demand alongside ensuring significantly higher utilisation across our solution set. As our end markets emerge from the pandemic, we will continue to respond with adjustments to our business in order to capture the long-term value associated with this uptick in demand for our technology.
Conclusion
This company has not always been profitable, so understanding more about what went wrong in FY19 would be the next port of call. Presumably 2020 was largely down to lockdowns.
There have been some reasonably significant director buys recently.
I’ve never encountered Accesso’s services myself, but making physical queue lines a thing of the past sounds good to me.
Apart from that, there isn’t much detail here to go on. Yes revenue is up, but what about profits and cash generation? Presumably both are good.
I’m neutral for now until the next set of more detailed results but clearly there’s good trading momentum here and the fact that customers are looking to introduce technology upgrades does suggest that there could be further good news ahead.
Wincanton (LON:WIN)
Share price: 440p (-6.4%)
Shares in issue: 124,543,670
Market cap: £548m
It’s a great time to be in logistics right now when you consider the amount of companies currently reporting issues, and Wincanton is well placed as a leading supply chain partner for UK business.
This is a very brief update today, so won’t spend too long on it.
The Board confirms that the strong revenue performance recorded in the second half of the prior year has continued into the first quarter of this financial year, with sustained growth and an attractive pipeline of opportunities in each of the Group's four sectors. Wincanton continues to make operational and strategic progress and it is trading in line with expectations. Profits are up significantly on the same period last year.
Ikea has awarded two contract extensions to operate its customer distribution centres in Kent and Essex.
The group does note ‘sector-wide pressures related to the availability of drivers’ however.
Broker forecasts have been consistently nudged up but remain below pre-Covid forecasts. Meanwhile, the share price is comfortably ahead of pre-Covid levels.

Conclusion
It’s a very short update, but one that helps to confirm the positive tailwinds in this part of the market. Wincanton looks to have done some good work in its efulfilment capabilities, which have helped it to win those Ikea contract extensions.
Wage inflation would have to be fairly significant in order to outstrip the current buoyant trading. The net debt figure looks a concern at first, but around two thirds of it are capital lease obligations.
There’s a pension fund here to be aware of, with a recovery plan that sees Wincanton pay £18.2m pa from 2021 through to 2024 moving up with inflation, then £21.3m pa from 2024 through to 2027. It’s a big drain on cash flows, but if things go the right way then a recovering pension scheme can actually be great news for equity. That's very risky though, and not something management or shareholders have control over.
That aside, the question is whether or not the current environment is a transient logjam that will shake itself out or is symptomatic of a more sustainable increase in logistical demand going forward. The strides made in efulfilment look like a solid way to take more share in future.
The company also appears to have rerated from a multiple signalling distress to one that has broadly recovered and has growth prospects. On balance, it does sound like good news is to come but the valuation appears to have some of this priced in for now.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

33 comments
Redde Northgate (LON:REDD) (no position)
I've been trying to articulate some thoughts on Redde Northgate (LON:REDD) but I find myself confused by all the moving parts.
For example, I don't follow the movements in # of UK vehicle numbers:
#FY20 Closing vehicles (51.4k)
- vehicle disposals (15.8k)
+ new vehicle purchases (12.5k + 1.6k)
= 49.7k
But FY21 UK closing vehicles = 54k...why is there such a material difference?
It's also worth noting that 11,500 vehicles were de-fleeted in the UK, but 15,800 were sold. How can a company sell more vehicles than it removes from its rental fleet?
I'm also a bit flummoxed by the cash flow statement, but I'll leave that to one side for now as it's the query below that I'm hoping someone here might be able to assist me with.
Fleet Age
How has the average age of the UK fleet gone up by 3 months, when 15,800 vans were sold and12,500 (or +1,600 = 14,100) new vans were purchased?
"The average age of the fleet at the end of the year was three months higher than at the same time last year"
Is the company selling it's newer vans rather than it's oldest ones first (which might explain why revenue/sale has gone up by £800, but profit per sale has gone up by £1.4k, i.e. less depreciation has been booked on the newer vans, so profit is relatively higher, perhaps? - see table below.)
Does this mean that the company is actually booking "future" profits now.
Why is not selling it's oldest vans first?
Also will this stymie future rental profits, as presumably an older fleet will attract lower rental income?
How to Value
If there is some merit to my thoughts/concerns above and profits can be moved around, doesn't it make it quite hard to value this business?
Any thoughts would be appreciated!
A
On the average age of the fleet going up:
The quote says "The average age of the fleet at the end of the year was three months higher than at the same time last year".
If no vehicles are added or removed from the fleet each year (e.g. through buying and selling) then the average age of vehicles in the fleet would go up by one year.
If the average age has only gone up 3 months then it looks like they have sold old vehicles and bought new ones.
Redde Northgate (LON:REDD)
Hi RBStock
Thanks for continuing the discussion.
The company is adding and removing vehicles each year from its fleet.
In fact it removed far more vehicles than it bought last year. The exact numbers are in my earlier post.
I find things hard to explain without visualising them, so please see my table below.
---
I have assumed the company has 10 vehicles, bought 1 year apart from each.
After Year 1, the company sells 3 of its oldest vehicles and buys 1 new one.
The average age of the fleet goes from 5.5. years to 4.5 years i.e. a decrease.
This makes sense to me.
So why has the average age of the Redde Northgate (LON:REDD) fleet increased - it's 3 months older - even though they sold more vehicles than they bought? It doesn't make sense to me. It implies to me that they have simply sold younger vehicles, not the older ones i.e. they've pushed forward future profits.
I could of course be misunderstanding something somewhere, but I'm not sure where.
Hope my thinking is clearer.
Cheers
A
Redde Northgate (LON:REDD)
Sorry, I should probably have added the below, whereby middle-aged vehicles have been sold off before the older vehicles.
Note the average age of the fleet has now increased from 5.5 to 6.0 years old.
Hi Abtan
I think the answer to your question lies in inventory. It is my reading that the cars are de-fleeted (for Northgate UK&I: c. 11,500 in 2021) and then moved to inventory for re-sale. Inventory for the Group has moved from £49m to £22m, which at £7.8k per vehicle and assuming the parts element is unchanged, is about 3,400 vehicles reduction in inventory, which have been sold. This doesn't explain all the movement, but could be most. I haven't taken account of movements in Spain and Redde.
Like you, my conclusion is that the average age (at the start of the year) of the disposed vehicles must be less than the average age (at start of the year) of the retained vehicles. That isn't what I would have expected either.
Headlam (LON:HEAD) Capital Markets Day was impressive as is their new Ipswich distribution centre. Here is the complete event, with presentations and the tour. Paul wrote about them last week on the day of the CMD & TU here. The day was introduced by Steve Wilson, CEO, and features presentations from the managers responsible for projects under the Company's Operational Improvement Programme. (They are Europe's leading floorcoverings distributor.) An excellent event. Video & podcast.
Panoply Holdings (LON:TPX) full-year 2021 investor presentation, given on Monday. An excellent year. 19% organic revenue growth, +62% including acquisitions. The momentum has accelerated into the current year, leading FY22 to be significantly ahead of current market expectations, expecting to deliver analysts' expectations for FY23 a full year early. Video & podcast.
Forthcoming PIWORLD events:
Vertu Motors (LON:VTU) Investor Presentation. We're delighted Robert Forrester, CEO and Karen Anderson, CFO will present to investors followed by a Q&A. Tuesday 13th July, 4.30pm. Register here. This has taken a long time to come to fruition, so I hope there will be lots of interest. Paul discussed VTU on his recent PIWORLD interview, 9m50s and the share price hasn't moved much since. They look to be motoring on all cylinders - pun, pun! So I'm really interested to hear this one. (BTW this interview with Paul has now had 6,000 views - which makes the time spent by Paul and ourselves producing these really worthwhile. Many thanks to Paul and to everyone who's viewed.)
Exploring the listed private capital opportunity - Part 2. Listed private capital gives all investors access to high-performing private equity and credit instruments. Presenting will be BMO Global Asset Management, CVC Credit Partners & £OCI. We had Part 1 yesterday, and the funds are impressive, all achieved an annual IRR of over 15%, sometimes much more (video/podcast to follow). Not a class I was familiar with and it was rather interesting. Monday 12th July, 2pm. Register here.
Accrol Group (LON:ACRL) full-year results webinar. Thursday 15th July, 1.15pm. We'll catch up with management following the recent acquisition of a state-of-the-art tissue converter. Register here.
Sosandar (LON:SOS) full-year results webinar. Wednesday 21st July, 11.30am. Another company Paul knows very well. They seem to have navigated CV19 very well. It will be interesting to get an update on trading once lockdown is relieved, and the advertising world returns to normal pricing. Register here.
Tekmar (LON:TGP) (virtual) Capital Markets Day. Thursday 22nd July, 4.30pm. Tekmar a leading provider of technology and services for the global offshore energy markets, is hosting a virtual Capital Markets Day events for investors. The events will provide further information on the Company’s strategic plan, and how, by building on the strong foundations of the business today combined with a robust growth strategy and attractive market fundamentals, the Company intends to deliver on its ambition to double organic revenue within 5 years and improve the financial characteristics of the business more broadly. Register here.
For those who registered for the Creightons (LON:CRL) results today, sorry for the disappointment. When a new date has been announced you'll be able to register on the PIWORLD events page.
Ages away in September, we have the next highly popular Stockopedia / PIWORLD StockSlam with Damian Cannon. Wednesday 8th September, 6pm. Register here.
Beyond that, after popular demand, we have a new PIWORLD interview with Richard Leonard to be recorded later this week, published on Friday 9th July.
Probably more for a Friday conversation but thought I'd put it out there. Are we getting to the top of the bull run now there's literally dozens of companies planning on floating out there?
I'm not a big fan of buying newly floated companies but acknowledge there's sometimes a gem or two, is there anything that's caught anyone's eye in the current /future floatation's?
Bought I3E today through downloading the Primary Bid app on iphone. Oil Gas bad boys in Canada, so no need to follow that but the app was very good - quick set up and off you go. Should notify of new listings via email. Did it just to test the app on a co I was looking at but High Risk DYOR etc in capital letters, bold and underlined with emoji ref flags flying.
Don't know about the company but the app worked very well. Fake links and good password would be sensible methinks.
On the new float theme, took a position in Trustpilot (LON:TRST) - if you can't trust this share then maybe 'killer' sharks have just entered the pool.
Morning Paul, RWA :- see you covered june 11th, Significant Q2 trading statement out this morning. One of those LOVELY'ahead of expectation' statements,with some expectation figs. thrown in,and continued growth expected,and increase of staff nos. to cover expectations. Wondered if you'd seen ? Tony
Mornjing tony,
Yes I've got Robert Walters (LON:RWA) down on my pad, as something to look at, given a positive update. Always good to flag up out-perform updates which we might have missed, so thanks for that. We try to prioritise positive updates, as they're so much more useful to investors than in line updates.
Regards, Paul.
£ACSO
It’s worth noting that the company appeared to run into problems before the outbreak though. Accesso also has a net debt position, whereas most other high quality software companies tend to be net cash, in order to bolster their often light balance sheets.
They are in a net cash position. The full year results from 31 December 2020 showed a net cash position of £29.7m. They also repaid all of their outstanding facilities with Lloyds in March 2021 so are debt free.
Busy morning with regard top companies i hold.
Somero Enterprises Inc (LON:SOM) - excellent news here , i do slightly worry whether for a company like Somero any quick spike as we are seeing in sales due to economic conditionals can be maintained long term. I guess long term they need further product expansion - in that regard it will be fun to see what their new product is later this year. I accidentally sold day of last update (news then was also ahead and my sell order was not fully cnacelled) - i did manage to buy back in and see no reason to sell now.
Redde Northgate (LON:REDD) again nothing not to like ref the update here - they seem to have a cunning plan they are execucting well - similar to Somero i bought edd as a bit of a bottom fishing exercise - must admit i have been mightily impressed by the newsflow and the plans in the short time i have held - again no plans to sell up here.
Ten Entertainment (LON:TEG) - again a very positive update sincve reopening lfl sales upo 22% compared to 2019 - i was initialy worried post fisrt lockdown wearing facemasks and other restrictions would stop bods going bowling - seems my worries were completely unfounded - £23 million of spare headroom. Hopefully presuming no more full lockdowns they are now back in buisness again - yay.
J D Wetherspoon (LON:JDW) - they have put the press to te sword ref their continual lies - apologies from all and sundry in the press for creating ficticious news about whetherspoons that always creates a jackanory story about something that isn't reality. Trading update hard to tell if good or bad - didn't exactly seem positive or negative in tone - it is what it is for now. They have some covenant negotiation work to do - i doubt they will need to raise any more emergency finance having already had the begging bowl out. Impressive noises about investing £750 mill for growth so in all likelyhood there will be a new wheterspoons coming to your local area sometime in the next 5 years i guess.
Ref net debt - there have been aspersions cast here that whetherspoons debt has balloned over covid period - they have blown funds raised to a certain degree but net debt at 26/1/2020 was £804 mill and is expected to be £833 mill at this financial year end - so there has been no material change as far as i can see. Note JDW have been buying up freeholds at a lick last few years so the debt compared historical levels is not being compared on a LFL basis as they have the extra freehold backing now that didn't previously exist at such a high level. They had £175 mil spend on freehold purchasases in 2020 and 2019 financial years. So other than the extra shares in issue JDW is in a strong position IMHO particularly if there may be town centre properties coming up for sale due to the new world realities. Anything but a cheap share at present but certainly a coffee can type holding for me even if it may have the whiff of stale beer (and worse?) from time to time.
Thanks Paul for commenting on Redde Northgate (LON:REDD) - I found the results statement today measured, coherent and indicative of lots of work aimed at really improving the businesses and developing opportunities. You have rightly commented on how the whole market has been rising, but I do think that a lot of this has been underscored by so many companies, such as Redde Northgate (LON:REDD) , accepting the challenges of Covid and fully utilising the opportunities to reorganise, refocus, and speed reform and development of their businesses. Most impressive.
I do hope you can continue to comment on this company in future.
I like the aquisition from K3 Capital (LON:K3C) but I'm not sure I understand why they've gone to the expence of a raise to pay for it? Any ideas?
Pat on the back for Somero Enterprises Inc (LON:SOM)
Hi Doug,
£K3C I suspect additional shares were needed to partly fund the acquisitions and also to issue to the selling directors as part of their buy-ins and there was a lack of shares held in treasury. As it is a small dilution and at above last nights closing price as a holder I am fine with this - hopefully some additional strong acquisitions and with the owners tied in for a number of years it looks like a good deal.
hi Paul and Jack
End of financial year report came out for Enteq Upstream (LON:NTQ) this morning and was wondering if you had time to review? In light of the news coming out of Mexico wondering if this could affect people’s sentiment to the oil industry?
Redde Northgate (LON:REDD) (I hold) headline figures for FY 04/2021 look good - ahead of expectations at 31.0p u/l EPS - PER is 12.9 (at 401p/share).
Strong momentum continuing.
15.4p divis in total = 3.8% yield
Balance sheet strong - NTAV of £623m
Too big to cover in the main report, but just thought I'd mention it.
I'm really grateful to the readers who nagged me to look at REDD shares last autumn, as I was bowled over by how cheap it was, and bought some myself after doing a positive write-up here. Am sitting on a lovely profit now, it's more than doubled from my purchase at 183p, so many thanks!
I can't see any reason to sell, it still looks cheap. Earnings should continue to rise, given that the accident management business is bound to see higher volumes as the economy recovers, and demand for white vans is bound to be strong, given how often delivery drivers visit us these days, I'm on first name terms with some of the Amazon drivers around here LOL!
Regards, Paul.
£(LON:REDD) results really encouraging and like you Paul I intend to keep for the long term. This is actually the best performing share in my portfolio in the last year .
Hi Paul, many thanks for your coverage of Redde Northgate (LON:REDD) over recent months. Having seen Richard Leonard talk about this company on Tamzin's PI World show and your subsequent coverage, I bought in at around 180 p.
It has done extremely well and benefits from a very experienced management team, who are experts in business transformations and based on their track record, are building a larger business with a view to selling on in the future.
I intend to keep my shares and potentially add on dips. It would be a shame for you to drop coverage of this now, so perhaps you could reconsider or post elsewhere - if you are doing a more detailed review personally??
Regards, James
I think quite a few of us bought in around the same time (I got in at 180p.) Just shows the value of this board both Paul and Jack but all the readers and people who comment on here. I don't agree quite a bit on here but that's the beauty of stock picking and the ability to see other people's perspectives.
I see no reason to sell this one, having bought in at a good price this will become a real nice dividend yield on the original price.
Re Redde Northgate (LON:REDD) (please remember to put in the ticker everyone, it just makes things clearer for everyone) an update note has just come through from Zeus, via Research Tree (which is worth its weight in gold), as follows:
Current year forecast FY 04/2022: 34.6p
Next year forecast FY 04/2023: 43.4p
Note the substantial 25% rise year-on-year. I think the FY 04/22 forecast looks beatable.
At 400p per share, with a strong balance sheet (remember net debt is comfortably covered by the assets of vehicles owned), and that debt should move off balance sheet as they are planning on leasing a lot of vehicles on bulk leases, rather than owning, in future.
I like Zeus forecasts, as they tend to be more realistic, rather than the ultra-cautious (ridiculous, in a booming economy) approach taken by many analysts at other firms.
All of which means that REDD probably should be priced at about 500-700p at some point in the future. Maybe the shares need to digest recent rises, and consolidate, which I'm fine with, given my longer term investing approach. As long as the fundamentals justify a much higher price, then I'm happy to buy more on the dips.
For balance the main risks with REDD? Loss of a major insurance contract at the Redde side of the business has happened before, and there is client concentration. Also on the Northgate side of the business, it could be getting a one-off benefit from rise in value of secondhand vans maybe?
Regards, Paul.
Very helpful comments on Redde Northgate (LON:REDD) which I bought at 201p and will continue to hold given the excellent upside potential. Good to see the downside risks explored.
I second the comments about continuing the coverage despite it being outside the normal market size.
My morning smallcap tweet: 17 companies today
£K3C Woodbois (LON:WBI) Somero Enterprises Inc (LON:SOM) Robert Walters (LON:RWA) Sabien Technology (LON:SNT) £7DIG Cohort (LON:CHRT) Myhealthchecked (LON:MHC) accesso Technology (LON:ACSO) Brave Bison (LON:BBSN) £GRFD Tribal (LON:TRB) Ten Entertainment (LON:TEG) KKV Secured Loan Fund (LON:KKVL) Seeing Machines (LON:SEE) Steppe Cement (LON:STCM), Wincanton (LON:WIN)
K3 Capital (K3C) £10m placing at 340p, a 1% premium, to fund acquisitions. [SP=336.3 Cap=232m]
Woodbois (WBI) guides H1 rev up 22%, constrained by freight constraints as warned. "Once the freight industry normalises, which experts have forecast for later this year / early 2022, the Company expects a step change in pace of revenue growth as well as further margin improvement." [SP=4.6 Cap=85m]
Somero (SOM) guides FY(June) rev c.£110m and adj EBITDA c.$35m up from guided $100m and $31m."This higher than anticipated momentum is carrying over to begin H2 2021, with customer workloads at high levels and project backlogs extending into 2022." [SP=434 Cap=243m]. I hold.
Robert Walters (RWA) guides FY(Dec) profit significantly ahead of June guidance. Q2 net fee income up 31%. [SP=714 Cap=545m]
Sabien Technology (SNT) FY(June) rev up 116% at £0.97m. "Executing an expansion strategy via acquisition can be challenging and expensive due to necessary market regulation. The Board will not be deterred by these challenges, and we are actively considering innovative structures within which to maximise the returns to shareholders as soon as possible while minimising execution expenses." [SP=21 Cap=3m]
7digital (7DIG) wins 2 year contracts with fitness companies Barry's and Volava. Np £££. [SP=0.99 Cap=27m]
Cohort (CHRT) wins order worth over €49m from Italian Navy. ""This is a major achievement for ELAC SONAR and its first major contract win since becoming part of Cohort in December." [SP=575 Cap=236m]
MyHealthChecked (MHC) guides H1(June) rev £3.27m (de minimis). "Whilst customer discussions are ongoing and there is still no certainty over ongoing volumes of sales, it is likely that these increased revenue levels will continue into the summer." [SP=3.51 Cap=26m]
Accesso Technology (ACSO) guides FY rev over $100m, significantly ahead of expectations. "Group's confidence in its future growth trajectory is also bolstered by a significant uptick in demand from potential customers who are looking to introduce technology upgrades as part of their pandemic recovery initiatives. To capture this long-term revenue opportunity, the Group is currently deploying additional resources across technology implementation, product development and customer support. While these investments will have a limited impact on Cash EBITDA in 2021, their full annualised effect will be felt in the 2022 financial year." [SP=590 Cap=243m]
Brave Bison (BBSN) guides FY(Dec) above market expectations after H1 rev rose 33%. [SP=1.64 Cap=10m]
Galliford Try (GRFD) gets into Scottish Water £350m 6 year framework. [SP=NA Cap=NA]
Tribal (TRB) signs first two customers for its newly launched cloud-based Tribal Admissions module. Trading in line. [SP=100.43 Cap=210m]
Ten Entertainment (TEG) LFL rev up 23% in the first six weeks of opening cf 2019. [SP=246 Cap=168m]
KKV Secured Loan Fund (KKVL) will return 3p/sh to Ords and 7p to C Shareholders. [SP=16.98 Cap=108m]
Seeing Machines (SEE) agreement with Airservices Australia to integrate SEE's technology into the Air Traffic Control environment. Initial work worth A$250K. "This collaboration will launch Seeing Machines' capability into the highly regulated and safety critical console-based environment " [SP=10 Cap=380m]
Steppe Cement (STCM) guides H1 rev up 22% (in Tenge) on vol up 10%. [SP=50.5 Cap=110m]
In line: Wincanton (LON:WIN)
K3 deals?
Hi Paul/Jack, any views on the Circle Property (LON:CRC) update today? Thanks
Totally (LON:TLY) According to MarketScreener https://www.marketscreener.com... the CFO Lisa Barter-Ng also sits on the board of 17 other companies. Seems a lot to me! Given that Totally has a good relationship with the NHS and plenty of work, one must wonder about the financial control within the company, when they only make 100k a year.
deleted - duplicate
It looks to me that many and perhaps all of the other directorships for Lisa Barter-Ng are TLY subsidiaries. She is Group FD.
Steppe Cement (LON:STCM) looking strong still. A lot of construction projects seem to be moving forward and demand is high in this market it seems
Another superb update from £SOM.
I'm looking at Somero Enterprises Inc (LON:SOM) (I hold) next! Section should be up shortly.
Seeing Machines (LON:SEE) new contract win in a new market after 5 years of feaability studies so great barrier to entry. Looking good for the future here with more cars coming online all the time and the aviation division starting to monetise as well.
Another strong update from Somero Enterprises Inc (LON:SOM) this morning.