Small Cap Value Report (Weds 8 Feb 2023) - RNO, SOS, CNKS, SDG, SMRT, PZC, PEN, SDY, ASHM

Good morning from Paul & Graham!
Today's report is now finished.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Agenda / Summaries -
Paul’s Section:
Renold (LON:RNO)
24.5p (pre market)
Market cap £55m
Good news for shareholders of this industrial chains manufacturer/distributor today -
The Group has traded strongly since announcing its interim results in November 2022, with order intake running ahead of sales. Supported by the positive market outlook, the Board now anticipates that underlying operating profit for the full year will be above current market forecasts.
Other points -
Revenues up an impressive 25% for the 10 months to end Jan 2023 (helped by forex)
Order intake up 19%
N.America “particularly strong”
Order book at record high, of £104m, so good visibility.
YUK acquisition going well.
Net debt “comfortably below” 1.5x EBITDA
Revised forecasts - thanks to Finncap for an update note this morning. It raises forecast profit by about 6%, to 4.8p EPS (LY actual was 4.0p, so healthy profit growth).
This gives us a PER of just 5.1x at 24.5p per share.
Although the reason the PER is so low, is because you need to adjust for the now increased level of net debt (after a recent big acquisition), and of course the hefty pension deficit, which is a consistent drain on cashflow every year. Which also explains why there are no divis.
Forecast free cashflow for this year is negligible, as capex is quite hefty too, and a lot has been absorbed into increased working capital - an inevitable consequence of higher inflation, that we’re seeing affect lots of companies, as the value of their inventories and receivables go up. I’m not too worried about that though, as the money hasn’t disappeared, it’s just temporarily tied up in assets which turn into cash later.
My opinion - Renold is a much better business now, than it was a few years ago. There’s been a slow, but effective turnaround, improving margins. Also it has demonstrated that demand remained robust through both the pandemic, and through the recent spike in inflation, where RNO also showed it can raise prices effectively.
As the business, and its profits grow, that helps dilute the negative aspect of its pension deficit. Higher interest rates also seems to be taking the edge off pension deficits, so maybe the market is now being too gloomy with the valuation of RNO shares?
It’s only had a modest bounce since the everything rally began in Oct 2022, so it strikes me that RNO shares seem a bargain hiding in plain sight. Hence a thumbs up from me.
Note that it comes up on a negative Z-score screen, so you need to be sure you're comfortable with the financial position.
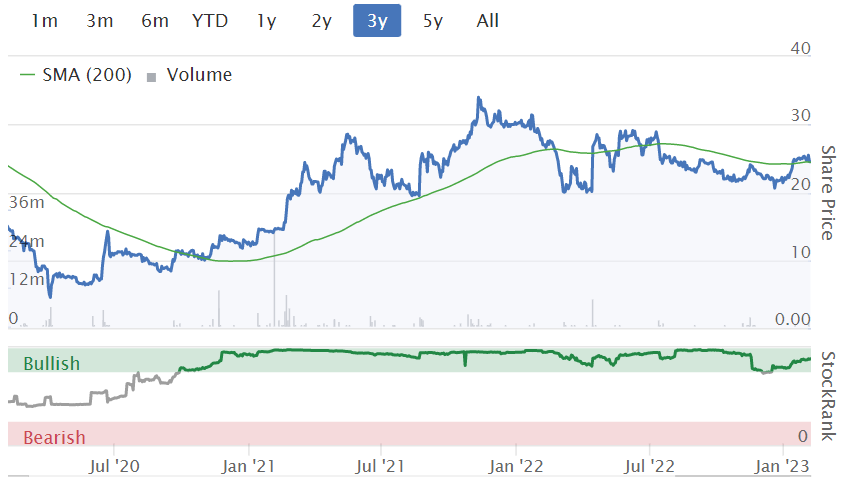
Good StockRank, I see below -
Sosandar (LON:SOS)
26.4p (pre market open)
Market cap £58m
I’m probably not the only person surprised that SOS has yet again passed around the hat to raise more cash from investors. Now it’s reached profitability, I had assumed that the direction of cash would reverse, and investors might start to get something back in divis, rather than pouring more cash into the company.
Details as follows -
Raising £4m (before fees) in a placing, plus up to £0.5m in a retail offer.
Priced at 22p (a c.17% discount)
About 20.4m new shares, if retail offer taken up fully.
New shares represent 9.2% of the existing 221.4m shares in issue, so dilution isn’t excessive.
Reasons given for this latest fundraise are to accelerate growth.
Trading update - continues to trade in line with market expectations for FY 3/2023.
My opinion - it’s must be getting a bit tiresome for shareholders to be asked yet again to pump more money into Sosandar. There again, it’s now profitable, so this cash is not being burned, it’s going into the larger working capital needed to drive sales & profits further.
I think growth companies can get addicted to raising money from the market, and there needs to come a point where they become self-supporting, and start paying divis to shareholders.
That said, Sosandar is delivering stunning growth, and clearly has established itself as a credible mid-market brand, and is shrugging off the consumer downturn. So I can see the argument for maximising that growth with more funding. I'm expecting today's announcement to take maybe 10% off the price of SOS shares, but we'll see. Update at 09:12: down about 13% to 23.0p, snuffing out the recent rally, this latest fundraising has not gone down well with investors. I'm remaining green on this share, due to the excellent growth, and move into profit this year FY 3/2023, but the latest fundraise is stretching my patience, so it's borderline between amber & green now.
Sanderson Design (LON:SDG)
121p
Market cap £87m
Sanderson Design Group PLC (AIM: SDG), the luxury interior design and furnishings group, is pleased to announce its trading update for the financial year ended 31 January 2023.
This looks OK to me -
Underlying profit in line with Board’s expectations.
Revenue £112m for FY 1/2023 (flat vs LY)
Good bits - Morris & Co, N.America, licensing.
Bad bits - withdrawal from Russia, manufacturing revs down slightly.
Net cash remains very healthy at £15.2m- this is a sleep soundly at night share for investors, with a lovely strong balance sheet. Note that SDG didn't dilute shareholders during the pandemic, as it was adequately funded already.
Outlook - nothing said, we have to wait until April 2023 for the full accounts.
Inflation - raised its selling prices twice, in Feb & Aug 2022 (as opposed to more usual once per year price rise). So given that revenue is static, this must mean volumes are down.
Forecasts - thanks to Singers for updating us. It’s forecasting 13.9p EPS for FY 1/2023, and a fall to 12.7p in FY 1/2024. At this stage, with macro uncertainty, I’m happy with soft targets for future years. As rival Colefax (LON:CFX) recently warned, high end furnishings tends to lag a slowdown in the high end property market by 6-12 months, so it’s possible that SDG could see a downturn in demand in 2023/4.
The PER is only 8.7x based on 121p share price, and 13.9p EPS for FY 1/2023.
That’s an attractively modest valuation.
Plus of course, as with everything, we’re not just buying this year’s earnings, we’re buying all future earnings, which should rise in the next economic cycle.
My opinion - no change. I’m positive about this share, which looks attractively cheap. There could of course be bumps in the road in 2023/4, that’s unknown at this stage. However, as it’s well-financed, and well-managed (I think), then this would be a share to just hold regardless of short term performance. OR, one to keep on the watchlist, to grab a bargain on any future trading disappointments. Anyway, it's another thumbs up from me.
Graham’s Section:
Cenkos Securities (LON:CNKS)
Share price: 51p
Market cap: £29m
Following on from the larger investment bank Numis yesterday, today we get a full-year update from smaller rival Cenkos:
Revenue for the full year is expected to be approximately £20m and the Board expects to break even at underlying profit level. This has been achieved against a backdrop of significantly depressed market conditions for 2022, with the overall level of money raised on AIM at its lowest since 2003 and new money at its lowest level since launch in 1995.
Among the brokers, Cenkos stands out to me as a company that has always managed to make a small profit, even in vicious bear markets (it has been listed since 2006).
This is because, over the years, they have always radically reduced variable pay (i.e. bonuses) when market conditions have deteriorated.
Mark Simpson’s excellent recent article notes that over the past two years, revenues and staff costs have moved hand in hand.
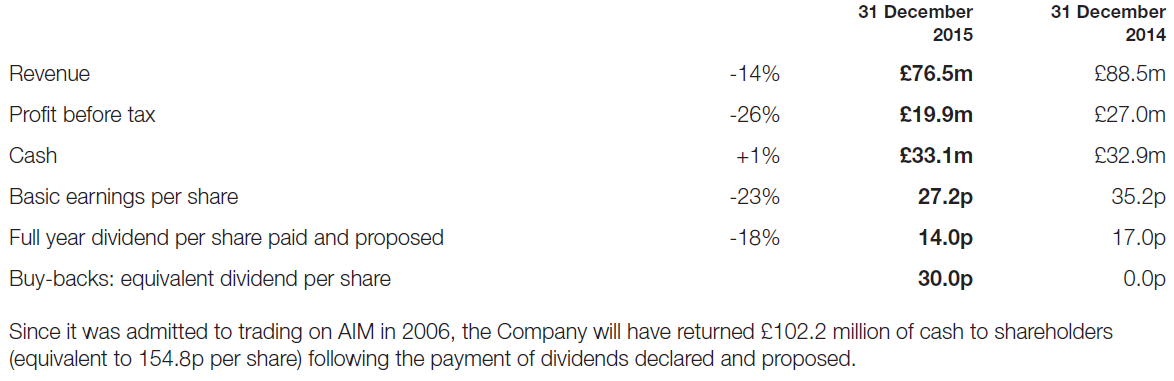
However, during bull markets of the past, there have been some occasions when revenues have far exceeded costs and significant wealth has been returned to shareholders. For example, here’s an excerpt from the 2015 annual report, showing fabulous results and shareholder returns:
But Neil Woodford, their most important investor client, has no more large business to offer them. The small-cap market has been ruptured by a collapse in investor sentiment, and very few companies are willing to IPO into this environment. Annual revenues for Cenkos of just £20m are the lowest they have achieved since around the time of their founding and IPO.
So where do they go from here - surely the only way is up? Here’s the outlook:
Conditions remain challenging and the outlook uncertain but markets have made a more encouraging start to 2023. We have made a solid start to the year with revenue for January ahead of the average run rate for H2 2022. We have already completed four placings and one M&A transaction this year, with a growing pipeline of future transactions and clients continuing to engage on both capital raising and M&A opportunities.
My view
I think the variable pay structure at Cenkos is brilliant - up until now they have never made a loss, and I’ll forgive them if net income is slightly negative in 2022.
As of June 2022, they had net assets of £24m (equivalent to 42p per share). This included cash of £16m (equivalent to 28p per share), financial assets related to their market-making activities, and options taken from companies in lieu of fees.
Would I pay a small premium over net assets for Cenkos? Yes, I think this represents decent value. Of course a discount would be even better. Stockopedia currently gives a ValueRank of 87.
However, a word of caution.
While I do expect Cenkos to do well in the next bull market, I don’t think anyone could view it as a stock that can compound higher for investors over the long-term. It is fundamentally cyclical.
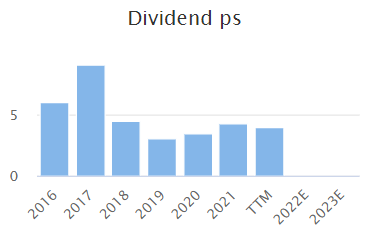
However, there is a cheat code for investors that could help the compounding process: diligently reinvesting Cenkos dividends back into the company every year.
Reinvesting 3p-4p per share every year, assuming that Cenkos remains capable of this payout in future years, could seriously help to boost returns:
PZ Cussons (LON:PZC)
Share price: 203p (-5%)
Market cap: £871m
We don’t usually cover this one but on a lighter news day it’s worth a look. This one is a member of the FTSE-250 (i.e. outside the FTSE-100 but within the top 350 UK-listed stocks). It owns a variety of brands including Carex, Imperial Leather, Original Source and St. Tropez.
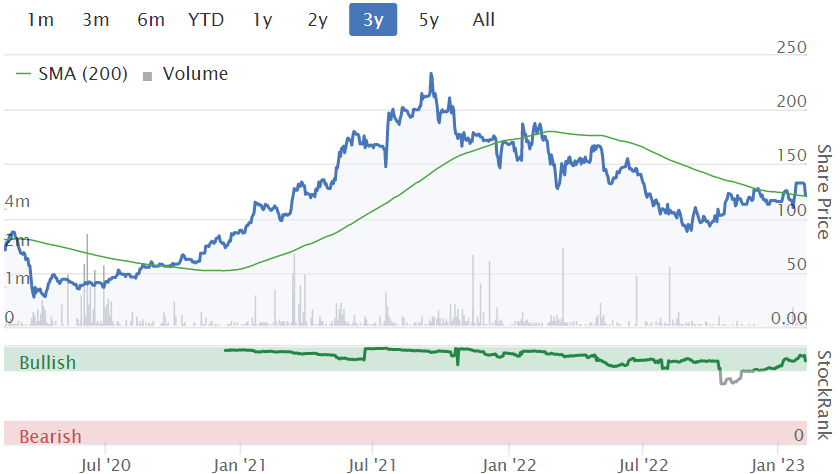
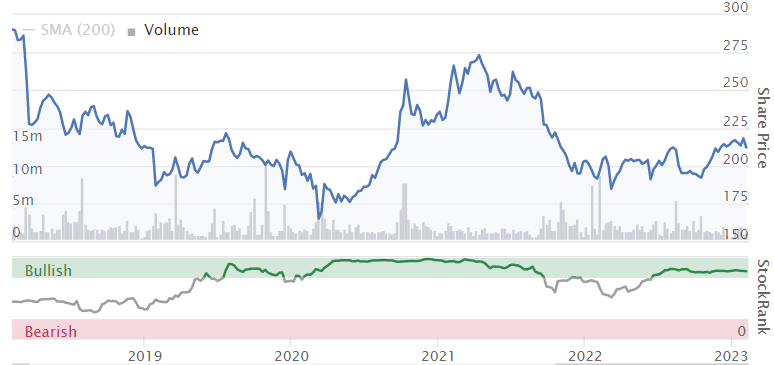
The shares have been range-bound for several years now:
Today brings H1 results for the period from June to November (inclusive). Technically, H1 ended on 3rd December 2022.
Key points:
H1 performance in line with expectations and full-year outlook unchanged
LfL revenue growth 6.1% driven by price/mix (i.e. selling more valuable items at higher prices, passing inflation onto consumers).
Volumes declined 5.4%. Demand for Carex products is lower post-Covid, and one of their Nigerian businesses is deliberately choosing price and margin over volume.
Reduction in adjusted operating profit margin from 11.6% to 9.9%.
Unchanged interim dividend of 2.67p.
Inflation is being managed, as you can see from the above, although not quite enough to keep the adjusted profit margin where it was. Carex and St. Tropez are high-margin brands, and their sales are now lower than they were during Covid.
There was also a reduction in adjusted EPS by 8.5% due to a higher tax charge on pre-tax profits, and minority interests - the other shareholders in PZC’s subsidiaries - taking a larger bite out of results.
CEO comments - the commentary in this report is very cautious, pointing to the “challenging macro environment, with ongoing high cost inflation and reduced consumer confidence”. The reference to “near-term headwinds” may partially help to explain this morning’s share price weakness, despite the full-year outlook having been reiterated.
Simplification - the company made a profit of nearly £12m by selling residential properties in Nigeria (!), as part of a simplification strategy. This helps to explain why PZC’s statutory results (which include those profits) are far more flattering than the adjusted numbers they voluntarily present.
Outlook
They are looking for an improvement in H2:
…we expect a stronger operating margin performance in the second half of the year driven by improved trends in our Europe and Americas business, more benign cost inflation and the full impact of price increases implemented part way through the first half. We remain mindful of significant macro-economic uncertainty, including the continued depreciation of the Nigerian naira, but expect to report FY23 adjusted profit before tax in line with current market estimates.
Despite no change to the PBT target, they do now expect a higher tax charge of 26-27% (22-24% previously), due to geographic mix.
Adjusted net debt is modest at £35.7m. Lease liabilities are low. There is an additional c. £100m headroom on their primary credit facility.
My view
This is a “buy and forget” type of stock. Even if management were incompetent, they should still be able to make some money out of these brands.
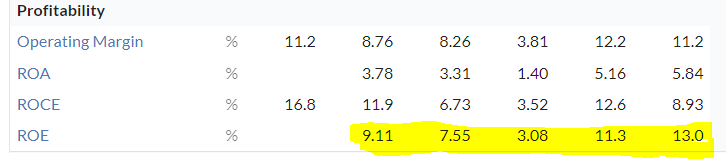
I’m a long-term fan of this business but I do acknowledge that they have failed to grow in recent years and that ROE has been less than stellar.
Therefore, while I want to be bullish on this one, I can’t until there is stronger evidence of improving performance, that will help to get the stock out of its current holding pattern.
Ashmore (LON:ASHM)
Share price: 277p (+1%)
Market cap: £1.9bn
Let’s briefly review the interim results from this emerging markets asset manager. Mark Coombs, founder and 31% shareholder, remains CEO here.
The fall in average AUM compared to H1 last year is something to behold, down by over a third:
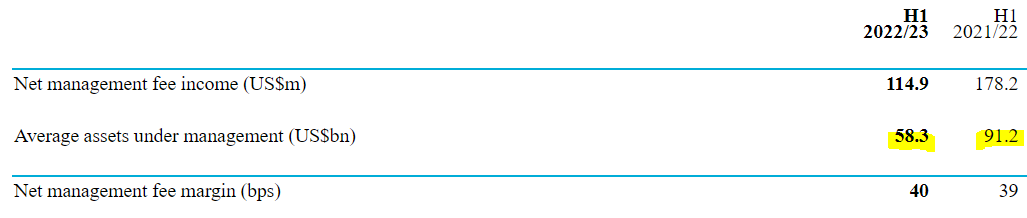
During H1, Ashmore experienced net outflows of $7.6 billion, far outweighing the positive investment performance of $0.8 billion.
Emerging markets, like micro-caps, see little interest from nervous investors in times like these.
Ashmore is primarily a debt investor, rather than an equities investor (only about 10% of its AUM is invested in equities). However, I imagine that the long-term underperformance of emerging market equities relative to the S&P must be a factor that weighs on sentiment for prospective investors.
Ever since about 2010, the S&P 500 has trounced emerging market indices. The strength of the US dollar has been remarkable, too. People have been saying for years that the performance discrepancy will be corrected. But it never has.
That is the context in which Ashmore makes the following observations:
Emerging Markets valuations remain at attractive levels, significant discounts to Developed Markets assets
Light investor positioning in Emerging Markets after a period of global risk aversion
Continuing market recovery supports Emerging Markets outperforming in coming periods
My own instincts, for what it’s worth, are to agree with Ashmore that emerging markets are due and deserve to have a substantial period of outperformance. But I have been thinking that for a long time, so I’m probably wrong!
I did a poll on my Twitter recently, asking people which type of ETF they might invest in. Less than 30% chose an ETF that included emerging markets. That might be partly due to the higher fees that go with investing in these markets, but I think it also reflects the knowledge that developed markets have performed better, and a belief that this is likely to continue.
And when you look at the outflows experienced by Ashmore, I think you can start to piece together an argument that emerging markets are “under-owned”. At least, that is the bullish argument for emerging markets - that they are neglected by investors, because they have performed so poorly for so long.
Ashmore’s outlook statement includes a reference to the IMF’s forecast that EM GDP growth will return to a premium of 3% over developed markets in 2023 and 2024. While this growth will be bumpy, it’s easy to forget about the very rapid development of GDP in so many non-Western and developing countries, especially China.
My view
Ashmore’s income statement (for the six month period) shows net revenue of £103m (excluding FX gains), and personnel and other expenses of £47m. There are other moving parts but these are the most important ones, in my mind. So there’s about £55m in “underlying” pre-tax profits.
According to the forecasts in the market, Ashmore is trending towards c. £100m in annual after-tax profits at its current AUM:
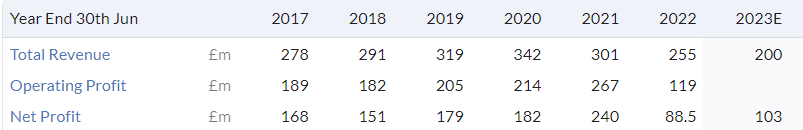
The high PER reflects the likelihood that profits will bounce back:

When the EM bull market returns, which I acknowledge could take a few years, these shares will look great value. I consider Ashmore to be another very good share to buy and hold for the long-term.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

57 comments
Been looking at Renold (LON:RNO) assuming there’ll soon be a year end update. The update in February made no mention of the impact on sales growth from the Spanish acquisition - I assume that would have had a meaningful impact, or am I being thick?
Seems strange to say what sales are in constant currency but not adjusted for acquisitions.
Sosandar (LON:SOS) As I suspected, last weeks Placing was to allow a new institutional holder in
Today’s RNS confirms that William Currie are now a 3.5% share holder. What’s particularly interesting about William Currie is that Sir Terry Leahy is part of the company
Sosander
I am a long term holder and remain so, BUT.
This placing was at a significant discount to the closing share price, why? I would suggest as the directors clearly knew they didn’t have the backing of their major shareholders.
Yes it was over subscribed, but only just and the bar was set low.
The reason given for the placing
Growth, but also funding of additional stock levels, really? What! the company has such poor relationships with its debt funders that with such a clearly cyclical business with clear working capital needs, it can’t raise finance to support stock holdings?
The financial forecasts of stock levels and cash generated from those stock sales must be clear, do their banks/ debt providers not believe them?
If you are doing a placing to raise funds for stock holdings that also suggests that this will go on and on and on, as the business grows, that has to be wrong.
I think the board has Seriously misjudged the market and their position in it.
I worry that as shareholders we are invested in a “ growth stock” that is failing to provide any value for that growth to shareholders.
I will hold for now, but a lot needs to happen over the next 12 months to convince me that this is a company that can provide value for shareholders.
Adept Technology (LON:ADT) cash offer of 201p, 78% increase. Worth holding for the offer as can only sell at 186p
Jadestone Energy (LON:JSE), released news that full production at its Montara site will resume in late Feb, production was halved due to technical issues.
Chart pattern is a flag, and today's move has broken out of the it intraday, best to wait though for it to close above the breakout price for confirmation . Plenty of upside to come as flags often appear in the mid point of a move, so price target is around 110p+, 30 percent upside from current price.
Fundamentals on Stocko are excellant. Buy for me.
tinyBuild (LON:TBLD) - huge fall without news - ask is 60p
WOW! good news.
Those on the SCVR on 31/1 who moaned about the Stocko format for RNS will be pleased to know that they were heard and the link is now clickable.
If you appreciate that give DanJSmith a thumbs up here -
https://www.stockopedia.com/co...
Thanks for covering the PZC and Ashmore . I hold both and did not know what to make of the results. Most likely I sell PZC and keep Ahmore.
What does the TR-1 RNS for Trustpilot (LON:TRST) that was just released actually refer to/mean (in laymans terms please)?
http://newsfile.refinitiv.com/...
Isn't it just Molten Ventures reducing their stake in Trustpilot to 2.9%. they went from 6.1% to 5.5% 18th January also.
Had 12 million shares left on 7th Feb. 8m block went through yesterday and another 4 millon today. Id say theyre probably sold out completely now, or 1-2 million left.
I dont hold so may be other info ive missed.
LON:MTW thanks to Graham for initial comments on Mattioli Woods interims y'day, and for anyone keen to have any complexities unravelled there is a thorough (18 pages) note out today from Equity Dev, with a maintained fair value of 950p. Freely accessible here: https://www.equitydevelopment....
Interesting, is that Cinch with an opening stake in Vertu Motors (LON:VTU) ?
The order book on level2 is looking v positive as is the chart. If they're building a stake this could have some way to go yet.
Yep I saw that. Cinch are part of the Constellation Group, who also have Marshall Holdings and others as part of its group. I reckon this could be a pre-cursor to a bid for VTU? That would be nice as I am a holder! Any thoughts Paul, as I know you hold VTU in high regard.?
Atb DH2
fyi, Vertu Motors (LON:VTU) Constellation Group also took a 20% stake in Lookers (LON:LOOK) at 102p Jan 2022 last year too. interesting to see how this all plays out but consolidation does look likely but who knows when. (I hold both)
There's some background info here - https://cardealermagazine.co.u...
Thanks for the link Wolf of Small Street, Vertu is our biggest holding by number of shares, this has the potential to reward our patience.
But the interesting thing is who owns Cinch and believe me ; they are massive.
There will be a takeover here very soon and it will not be even close to the current price.
Seeing Machines (LON:SEE)
Following on from other day CFO has bought another 450,000 shares. I need to check but I think he's bought around 4m shares over the last couple of months so circa £300k worth. Must be pretty confident in prospects from here given his knowledge of the business. Interesting.
The director purchases in Seeing Machines (LON:SEE) are strange. Why would M J Brown sell 73,000,000 at 5.5p on Nov 11 and then 3 days later start buying at a higher price?
I agree looks pretty odd. Possibly tax reasons? He bought 18m at 11p before, so maybe to cancel out some gains? He sold 73m and has bought back a small amount. He still has around 15%.
No - not odd at all. MJ Brown is a non exec director by virtue of being involved in Lombardier Asset management who own a lot of Seeing Machines (LON:SEE)
In November Lombardier completed a restructuring of a number of their funds which resulted in some transfers and sales. The fund that now holds shares in Seeing Machines (LON:SEE) was also buying.
This was not MJ Brown buying or selling : this was the institution Lombardier Asset Mgmt : Brown is closely associated hence it is declared as director transaction even though it actually isn't.
The new CFO came in at the end of last year and he has been consistently buying - now well over 4m shares which looks to be a decent indictment of prospects given he is (a) new and (b) has access to all the financial expectations and trading.
Hopefully an indication rather than an indictment?
I wish we had a 'live chatroom area' on the left to chat with you all in real time. So many questions to ask and opinions to share lol.. but mainly questions!
Ask away!
Hello Paul, I don't think the tags are working again, yesterday is only showing one, same as today.
Thanks Rusty2, I'll check out the tags & replace where necessary.
I'm old with a slow brain. Shouldn't really be investing but wth. I hold SOS and was as as surprised as anyone by the placing. Mr Market might not be impressed by it but there have been a fair number of smallish buys-I made one of them-and very few sells this morning. There were a couple of very big sales recorded at the beginning of the morning but they might have been after hours sales last night, possibly by insiders. Hence the remark in the RNS, that seems to have been rushed out in response to insiders selling before the price drop.
I'm sure there are many more knowledgeable than me who might have a different view.
Hi Paul, may I ask if your SCVR - summary tables link has changed? I bookmarked it but my link shows it last being updated on the 3rd Feb? Is this correct or do I have a defective link? Just asking for clarity please.
I tend to update it in batches when I get a free minute, so currently only done up to 3 Feb, sorry about that. So your link should work, it doesn't change.
I don't have a dog in the fight with Sosandar (LON:SOS) but the only potential problem I see is the discount...but is that a management competence or market conditions issue? Its better that they grab the big growth opportunity before them rather than sit around waiting for more ideal times. If you own the company I assume you like business...and are in a position to assess the competence v conditions trade off. Whatever, its not massive dilution.
Little companies on AIM are there to fund growth...
PS its my long held (and stale as not updated in years) opinion that the joint CEOs should direct their talents at product and operations and appoint a dedicated single CEO with some relevant experience. Its hard to prove but I think their growth execution could have been neater doing this. I guess (total guess tbc) that they've had lots of "helpful advice" over time and that has created a bit of a corporate execution clusterf at times
I tend to agree Mojo and I think whilst they didn't appoint a dedicated CEO they did change the CFO who appears to be pretty good, and from what I can make out probably bridges any gaps.
What I would say about the placing price is that it was clearly set around the mark of the share price back 2 weeks ago (22-23p). As we all know placings don't happen overnight so these discussions were most likely done around the time the price started moving up.
This seems to be classic on AIM - it strikes me that the pattern appears to be.....companies have discussions about a placing, share price rises over the window, placing gets done at a 15-20% discount to new share price and hey presto any insti's taking some of the placing can sell on to retail with a nice margin for error.......or maybe I'm just being cynical but this sort of rise into a placing is far from an isolated phenomenon.
I don't overly mind the raise for growth - they might as well establish themselves now and expand for growth. The prize for Sosandar (LON:SOS) isn't a £50m company it is a £500m company and for that they do need to grow
I think Bayes Theorum comes into play. Think of two alternative universes. In both universes, SOS was two weeks ago discussing a placing at around the then current market price with institutions. institutions (like everyone else) love to buy at a discount.
In universe 1, the share price moves up as the discussions progress to 26p. When all are on board, some of the institutions insist on the initial price indication of 22p and the placing gets done at 22p.
In universe 2, the share price sags down to 18p during the discussions. Some of the instiutions refuse to pay a premium to market (or even insist on a further discount). The board reevaluates and decides to not do the placing - either moderating its growth plans, or taking out bank debt or crossing its fingers and hoping for better luck in two months time. No placing is done.
The point is that most placings are done at a discount and it is easier to get a placing away when the share price is moving up. Therefore, I think your observation that placing are normally after a rising trend is what is to be expected - not necessarily a sign of nefarious practices.
On the inverse, when the share price has been falling before a placing, there are often complaints that the placing must have leaked out beforehand - I think accusations in such cases of something dodgy going on are more likely to be credible.
Maybe I am being too cynical but there was no real reason for the price to move gently upwards over that 2 week window. My suspicion is that more effort goes into telling the story when a placing is going on, particularly if it is a good story when a company wants funds to expand rather than needs funds to survive. That helps the share price and a placing at the original price looks like a discount.
Nonetheless I'm not particularly concerned about the raise itself. The company isn't burning money so this isn't really dilutive - if that money is invested to achieve a strong return on capital and accelerates expansion then it can be a positive. I have no reason to believe that isn't the case with Sosandar (LON:SOS) so I'm marginally positive.
Well, no reason at all, apart from the small matter announcing a deal with Sainsburys which is big enough for them need £4m to buy stock.
Sosandar (LON:SOS) appears to be a subscription paying fan club.
Yes getting fed up with Sos (NYQ:SOS) shares are down 14% today.
M&C Saatchi (LON:SAA) small profit upgrade in today's announcement, easily missed (pbt forecast £31.8m v 31m preciously)
Paul the very promising news from Oxford Biodynamics (one of your holdings) has been picked up by the national press.
https://www.dailymail.co.uk/he...
Unfortunately, tests take time to get approval and commercialize (COVID excepting), so this prostate cancer treatment test will likely take at least a year to "hit the shelves", either in the US and UK. And then adoption by the medical community is usually slow.
Look at the CiRT test that got USA approval and launched last year Feb22. Barely 150 tests in total sold as of Jan this year.
Oxford Biodynamics (LON:OBD) has approximately 12-15 months cash runway from Nov22, is my estimate. So IMO, management have a difficult choice now. Focus solely on CiRT commercial sales, and freeze further commercialisation of the prostrate cancer test until H2 or 2024.
Or invest in that commercialisation process, but definitely need to raise some funds in H2 this year, while still unprofitable, and praying that CiRT sales run-rate is healthily growing by that point.
However, it does seem that there are investors who really highly value this company. They got away a placing in Oct22 at 20% premium to the share price. Rare to see for a company that had almost zero revenues, heavily cash burning. So maybe there is really something in this tech, and that they will be able to get another placing off at nil discount or even a premium again.
(I hold in the Boon Fund)
Thanks D99,
It's just a fun money punt, so I'm not bothering with that.
Regards, Paul.
Clearly nobody trusts Sosandar (LON:SOS) enough to lend them money at a sensible interest rate. Surely a far preferable approach for the company had it been achievable.
Exactly. There should have been enough of a trading record, as well as all those signed 3rd party distribution contracts, for Sosandar (LON:SOS) to negotiate some sort of RCF facility or similar from a bank?
Unless, of course, management believe that 22p share price is overvaluing the company. In which case an equity fundraising makes sense.
or maybe they just don't want debt. It's another party to keep happy, comes with restrictions etc. I don't overly like debt in smaller companies as the banks demand all sorts of onerous protections, irrespective of your current track record.
A lot of people think we're about to enter an enormous recession. The AEP article in the Daily Telegraph points out some monetary indicators that are looking ominous (yes AEP is a doom monger, but similar signals foreshadowed to 2008 problems).
In that context balance sheet strength could be the difference between the company surviving or not. Get the placing done when you can, there might not another chance.
Trident Royalties (LON:TRR) For those of us who follow lithium mining, today's announcement about the court approval is positive news.
The announcement states the win could eventually result in royalties of £55m to Trident Royalties (LON:TRR) when the mine is up and going. 5 years time? Very significant, given turnover to June 22 was only £3.1m.
Simon Thomspon of IC likes Trident Royalties (LON:TRR) - whilst Thacker looks like it will be significant it is a long way off going into production and I seem to think there is also a court case going on but I may be wrong.
I looked at them but couldn't get excited at the current price. It seems too much is already factored in for Thacker that I just can't see where the growth over the next 3 years might come from to justify the price.
Very limited knowledge though for me so happy to hear from someone who has done proper analysis on it.
hi Paul, sorry for the silly question. Can shareholders object the fund-raising by any chance?
I was really surprised of the news. First thing I said when I saw it was WTF. The already profitable, so why do you need more fundraising.
Hi DrMeShaker It's important not to conflate profit and cash. A growing business is likely to absorb cash as it grows, thus cash can shrink (for example as stocks and receivables increase) even as revenues and profits rise. SOS are growing fast and that absorbs cash.
thanks
Nice trading update from Renold (LON:RNO) with the magical words "the Board now anticipates that underlying operating profit for the full year will be above current market forecasts"
Record high order book up circa 20%.
Not sure there is much more to add form the short update, but a company that has been highlighted in these pages positively over the last few months, even a Paul interview with CEO lurking somewhere
My morning smallcap tweet: Frogmarching failures to the sin bin
Cellular Goods (LON:CBX) Sosandar (LON:SOS) Speedy Hire (LON:SDY) Pennant International (LON:PEN) Renalytix (LON:RENX) Renold (LON:RNO) Cenkos Securities (LON:CNKS) M&C Saatchi (LON:SAA), Civitas Social Housing (LON:CSH)
◄Cellular Goods (CBX)► car crash co terminates proposed acquisition of Cannaray Brands and Love CBD Health from Cannaray as a result of changes in the deal itself.Co "proactively reviewing its product range, proposition, financials, strategy and opportunities". [SP=0.61 Cap=3m]
◄Sosandar (SOS)► £4.5m placing and retail offer at 22p, a 17% discount (not mentioned), to accelerate the execution of its omni-channel strategy and customer acquisition. [SP=26.5 Cap=59m]
◄Speedy Hire (SDY)► finds c.£20m of hire assets gone missing, a huge 41% of non-itemised items like scaffolding. Launches external investigation. Trading in line. [SP=41.57 Cap=195m]
◄Pennant (PEN)► guides FY-Dec rev down 14%, EBITA c. £0.5m (-£0.8m) thanks to margin improvement. 3 year order book £25m (£22m). In line? [SP=28.99 Cap=11m]
◄Renalytix (RENX)► $20.3m placing at $2.17 per ADR = 90p/ord, a 27% discount (not mentioned), mainly for clinical product development and marketing. [SP=124.75 Cap=116m]
◄Renold (RNO)► guides FY23 rev and U/L op profit above market forecasts. Cites "continued sales growth, a strong orderbook, benefits of the cost reduction and efficiency programmes, and the successful recovery of cost inflation on raw material and energy". [SP=24.57 Cap=55m]
◄Cenkos Securities (CNKS)► guides FY-Dec rev c.£20m and breakeven U/L profit. In line? Outlook - more encouraging start to 2023. [SP=51 Cap=29m]
◄M & C Saatchi (SAA)► guides FY22 rev in line and adj pretax £31.8m, slightly ahead. Current trading in line. Capital markets day with new strategy with cost savings and new capabilities, with a focus on data, technology and digital transformation. Targets headline earnings growth of 22% CAGR. [SP=169.92 Cap=208m]
In line: CSH
Good morning Paul,
Sosandar (LON:SOS) have announced a placing this morning of approx. £4 million to help them develop their strategy of expansion through various sales channels.
You mentioned, after the last trading update, that you weren’t expecting another placing now that they are profitable.
Do you see this as a positive step ? Or rather one taken out of necessity?
(I hold)
Thanks for your great output, by the way.
Why would Sosander need to tap the markets again when they have forecast PBT for next 3 years of £2m>£3.3m>£5.7m
Haven't they heard of banks?
I'm not a shareholder but I'd be mightily pissed off if I was, and it does call into question how accurate they believe forecasts to be. The ballooning share count over the last few years would put me off investing here.
I would have preferred one of their large partners to do a cash injection and validate the project than a fundraising.
Joules would've preferred their large partner Next to do a cash injection. They bought the company for buttons instead. Placing has to be better than that outcome.
Morning :)