Small Cap Value Report (Weds 8 June 2022) - FUL, NEXS, MRK, IGP, CPC

Good morning! Paul & Jack here.
Agenda -
Paul's Section:
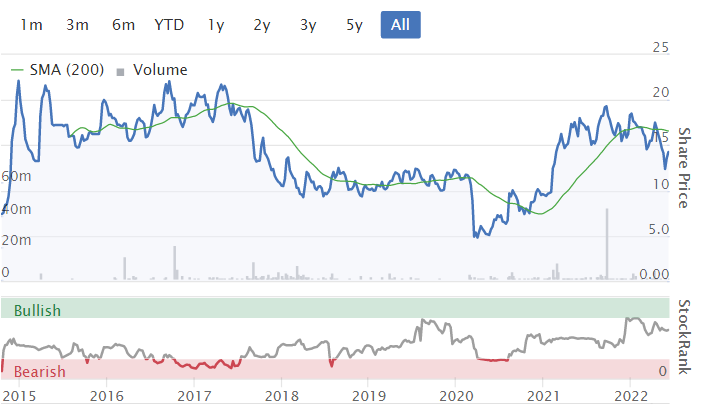
Fulham Shore (LON:FUL) - a decent, in line trading update for Apr & May. Acceleration of expansion into new sites, in prime locations, on attractive rents - so this is a good quality restaurant roll-out. Long-term, I think this share is likely to do well. Shorter term though, the valuation isn't a bargain. Since listing, the share price has basically gone sideways over 8 years.
Marks Electrical (LON:MRK) - as I expected, profit margins are falling from unrealistically high levels. Hence profit is flat, despite a 44% rise in revenues, for FY 3/2022 results. This seems a shrewdly managed business, lean on overheads, which is what's needed in a low margin, highly competitive sector. Too expensive for what it is.
Intercede (LON:IGP) (I hold) - a profit warning in April reset expectations downwards, so no surprises in today's results. Growth has stalled this year, but it's still profitable and has a sound balance sheet, with cash. We need to see growth resume, which could happen if contracts that were not signed by year end are signed in the new year. I've cooled a bit on this share, due to no growth. However, that's been reflected in a much lower share price already.
Jack's section:
Nexus Infrastructure (LON:NEXS) - a solid update, with a small hiccup in the energy transition business, but the company is confident of recovering gross margin in H2. Nexus is clearly working in some high growth areas and compares favourably to some more speculative alternatives, but the valuation is not particularly cheap and I wonder if near term pressures and investments might lead to a more attractive entry point some time in the future.
City Pub (LON:CPC) - an encouraging recovery in trading with good like-for-like progress, new site openings, and the prospect of the first uninterrupted summer’s trading in two years. Valuation has always been a concern for me though and I still struggle to see the upside, particularly after accounting for the recent increase in share count.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Paul’s Section:
Fulham Shore (LON:FUL)
14.25p (pre market open)
Market cap £90m
Fulham Shore owns and operates "The Real Greek" ( www.therealgreek.com ) and "Franco Manca" ( www.francomanca.co.uk ) restaurants.
The Board of The Fulham Shore PLC is pleased to provide an update on trading for the first two months of its financial year ending 26 March 2023.
April & May - trading in line with management expectations.
Tourists returning to London & many other cities.
Office areas - improving, but still behind pre-pandemic.
Cost inflation - mitigated by -
- Increased menu prices
- Negotiations on rent reviews (i.e. lower rents)
- Strong trading in suburban areas & shopping centres.
New sites - 10 opened in FY 3/2022, 3 more this YTD. 11 more set to open just in H1 this year - an accelerated pace of expansion (18 expected in total for FY 3/2023).
New openings: “continue to trade very well”
Key point - getting “historically low rental levels” on “prime new locations”, “not been seen for many years”.
Net cash of £3.6m (ignoring lease liabilities) at 6 June 2022 - looks fine.
Plenty of liquidity, with undrawn bank facilities of £16m
Outlook - “We continue to be very optimistic about the significant growth opportunities”
Diary date - 21 July for FY 3/2022 results.
My opinion - this looks a strong update in tough conditions.
I see FUL’s restaurant formats as likely to continue doing well, because Franco Manca in particular offers good value for money, plus an interesting & tasty product, very fast service too. It also has grown delivery & takeaway offerings well during the pandemic, so is a better business now than it was pre-pandemic.
At the moment, stock markets seem obsessed with the cost of living issues, but at some point sentiment is likely to turn more positive towards companies which are trading well despite headwinds, and have lucrative expansion underway (prime new sites on great deals from landlords).
The trouble is, investors can see that FUL has good formats being rolled out, and that attracts a premium valuation. Even now, after a recent c.30% fall in share price, FUL still looks expensive, on c.33 times forecast earnings.
The share price has gone nowhere since it moved to AIM in late 2014, despite the business growing considerably, and not many new shares having been issued.
So it’s a tricky one. I can see that this business is likely to be maybe double the current size in 3-5 years’ time, which is appealing. It’s a roll-out of proven, differentiated brands. The product is good. Conditions are perfect for expanding into prime new sites at cheap rents. Although as the economy improves, then rent reviews could hike those rents 5 years down the line.
Overall then, I’m neutral, leaning towards being slightly positive. In a future bull market, this share could be double the current price, I reckon. But it might take several years of waiting, and tolerating a reduced price in the meantime, if markets take another plunge at some stage.
If I already held, then today's update would reassure me to continue holding.
.
Marks Electrical (LON:MRK)
93.5p (up 2% at 08:25)
Market cap £98m
Marks Electrical Group plc ("Marks Electrical" or "the Group"), a fast growing online electrical retailer, today announces its audited results for the year ended 31 March 2022 ("the year" or "FY22").
Strong revenue growth of 44% to £80.5m
Low gross margin of 19.8% (down from 21.3% LY) - as I would expect for an online business selling other companies’ products, in a highly competitive sector.
Advertising & marketing spend has risen a lot, to 5.0% of revenues, LY 2.9%
Adj EBITDA margin has fallen from 13.7% to 9.0%
Adj EBIT (operating profit) margin down from 12.2% to 7.9%
Adjustments look reasonable, being £2.7m of IPO costs (it floated on AIM in Nov 2021)
Adj EPS is 5.0p, down 1% on LY
PER of 18.7 looks too high to me.
Cashflow looks good, mainly due to adverse working capital movements last year partially reversing this year.
Small maiden divi of 0.67p. Given the lack of capex, and a sound balance sheet, better divis should be possible in future.
Outlook - strikes me as uninspiring -
Competitor pressure has increased in FY23, coupled with a challenging market backdrop, but despite this, the business has continued its momentum, gaining market share and focusing on leveraging its cost base to maintain a strong Adjusted EBITDA margin.
Our disciplined approach to margin management, capital allocation and cash conversion demonstrated in FY22, provides us with solid foundations to deliver our strategic objectives in FY23.
Continued positive trading momentum in the first months of FY23, with revenue growth exceeding 20% year on year
Disciplined approach to margin management, capital allocation and cash conversion demonstrated in FY22, provides the Group with solid foundations to deliver our financial targets and strategic objectives in the year ahead
Balance sheet - it’s a capital-light model, with hardly any fixed assets.
£3.9m cash, with no interest-bearing debt.
NAV & NTAV are both £9.4m
Looks fine to me, no issues here.
My opinion - as mentioned before here, I didn’t believe that MRK’s high operating margin relative to the sector made any sense, and probably wasn’t sustainable. Today’s results confirm that, with the operating margin down from 12.2% to 7.9%. I would expect that to fall further. Larger competitors can’t achieve that margin level, so how does MRK manage it, with less buying power?
It seems to me that MRK operates a lean cost model, which might work well whilst the company is relatively small. However, as it expands, I reckon it could become less efficient, as overheads mount, warehouses get bigger, product ranges expand, etc.
There are well-known headwinds too, including staff who are probably expecting a 9% pay rise, plus distribution costs rising (fuel costs especially), and continuing supply chain problems (particularly for electrical appliances, reliant on limited supply of chips).
Combine that with little to no pricing power, as customers just compare prices online and go for the cheapest option. There’s no customer loyalty to the retailers. AO.com has proven that focusing on superior customer service doesn’t work commercially. People want the lowest price, once they’ve decided on which product they like. In 5 years’ time you won’t remember if the delivery driver was pleasant or not, you just want the product to still be working, and the price the lowest!
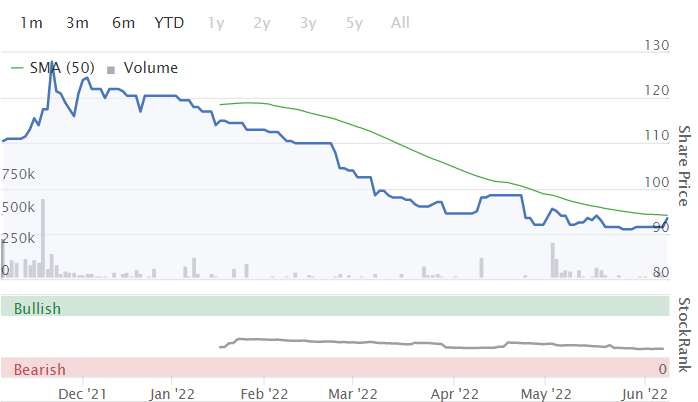
I’d say MRK is a much better option than AO World (LON:AO.) , if you absolutely have to own an electrical retailer. But I’d want it on a PER of 10 or less - hence for me, I wouldn’t even consider buying above 50p per share (currently 92p).
MRK seems a shrewdly managed business though, run on a shoestring. So MRK is much more appealing to me, than the delusional management at AO, thinking they could take on the world with a high cost, high service model, which is inappropriate in this sector. But the price of MRK still includes an IPO premium I think, which is likely to wear off. I can buy great businesses like Dunelm (LON:DNLM) or B&M European Value Retail SA (LON:BME) on a PER of 10. So why pay more for this?
.
.
Intercede (LON:IGP) (I hold)
51p (up 10% at 09:47)
Market cap £29m
Intercede, a leading cybersecurity company specialising in digital identities, derived credentials and access control to enable digital trust in a mobile world, today announces its preliminary results for the year ended 31 March 2022.
Intercede warned on profits in April, which I covered here. Contract signing delays resulted in anticipated profits for FY 3/2022 being largely wiped out. Or hopefully deferred into the current year, possibly? It did highlight though the dependence IGP has on some big, long-term customers (especially the US Govt), and that profits are unpredictable.
On a more positive level, overheads are now largely covered by recurring, high margin revenues.
I’m frustrated that the turnaround has not yet moved on to meaningful growth.
So there’s nothing exciting in the numbers, all as expected.
Balance sheet is strong now, with plenty of cash.
Profit after tax (fine for companies with tax credits each year) was £0.7m, half the prior year's level.
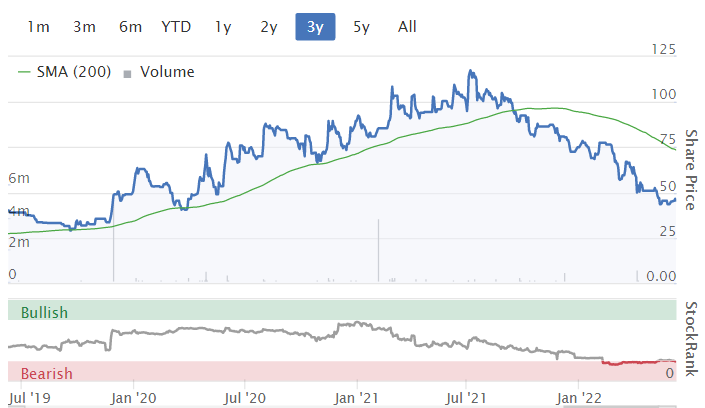
A rather disappointing year has already been reflected in a share price down almost two thirds from the peak, and £29m is hardly a demanding valuation.
Today’s commentary talks a lot more about acquisitions, which has been flagged in the past. I’ve got mixed feelings about that, in particular I don’t want to be diluted when the share price is low.
Outlook -
Moving forward, the Group has a great opportunity for growth with Intercede having established a strong market position in a rapidly expanding sector. Our differentiated offering sets us apart from competitors, in addition to a quality team and a strong financial position. We look forward to the future with confidence.
My opinion - I’ve cooled somewhat on Intercede shares, because the growth needed to re-rate this share hasn’t as yet been forthcoming. Hence I’ve trimmed my position size from large to medium, and recycled some money into Beeks Financial Cloud (LON:BKS) (I hold) where rapid organic growth is happening, but it’s much more expensive. But I'm happy to continue holding a reduced position for the long-term.
I remain of the view that IGP could re-rate significantly, once the growth starts to motor, but we don’t seem to be there yet.
Costs are mainly staff at IGP, who will need bigger pay rises this year, so a headwind there, as for all IT companies. Hence growth is needed, just to stand still.
The StockRank has fallen to a low 23 now, mainly reflecting poor momentum.
The share price is almost back to where it was 3 years ago, which I think seems harsh, given a lot of operational progress, and de-risking the balance sheet. The share count has risen from 48m to c.58m, reflecting conversion of loans into shares at c.68p from memory.
.
.
Jack's section
Nexus Infrastructure (LON:NEXS)
Share price: 185p (unchanged)
Shares in issue: 45,481,904
Market cap: £84.1m
Interim results for the six months ended 31 March 2022
Nexus focuses on multi-utility solutions for residential developers, civil engineering, and has a fast-growing energy transition division focused on things like electric vehicle charging.
- Revenue +26.1% to £80.3m,
- Operating profit -26.7% to £1.1m,
- Group order book remains strong with a 6.6% increase since the year end to £306.7m (H1 2021: £301.6m)
The interim dividend is up 66% to 1.0 pence per share ‘reflecting confidence in the second half of the year’.
TriConnex continues to grow by attracting new customers with its multi-utility networks. This division designs, installs and connects energy, water, fibre networks and electric vehicle charging infrastructure on new residential properties. Customers are a mix of large, small and mid-sized residential developers.
Revenues have risen by 2.5% to £25.0m, with operating profit also up 2.5% to £2.4m and the order book up 3.4% to £197.4m.
eSmart Networks, the energy transition business (including electric vehicle charging, industrial electrification, and renewable infrastructure), is scaling up and is seeing ‘significant growth’ in its order book. Revenues are up 208% to £8.6m, although the operating loss has grown from £0.4m to £1.1m, with the order book up 72.1% to £21m.
The loss reflects £1.4m of growth investment as this business further establishes its position in the UK's energy transition markets. Total group operating profit was lower than anticipated though, due to a low margin contract which is now complete. Gross margin was 15.9% in the period and is expected to recover to c25% in H2.
Nexus continues to look for ways to crystallise shareholder value in this part of the business, which has so far resulted in a minority investment from a third party. I wonder if management had been hoping for more interest by now?
The civil engineering business Tamdown has grown its order book but the focus now moves to protecting margins. Revenues up 26.8% to £46.7m (H1 2021: £36.8m), operating profit of £1.1m (H1 2021: £0.3m), and order book of £88.4m (H1 2021: £98.5m).
Balance sheet
Net assets have increased by 8.5% to £32.7m and cash levels are stable if down slightly (cash down from £25.6m to £23.1m and net cash down from £13.7m to £12.5m). Since the period end, Nexus has eliminated group borrowings with the sale and leaseback of its head office, which has brought in another £2.9m and increasing net cash to £13.9m. The balance sheet looks fine.
Outlook
During the first half of the financial year the Group's performance reflected strong underlying trading across all businesses. Looking ahead, although there are currently signs of significant levels of input cost inflation across the industry, the Group is committed to taking the necessary mitigating actions to protect and maintain margins.
Nexus continues to be well positioned to support established and new customers with their Net Zero plans, which is in line with our strategy of enabling the UK's energy transition by delivering sustainable infrastructure including electric vehicle charging, industrial electrification and low carbon heating sources. TriConnex continues its strong performance, eSmart Networks continues to scale up and is expected to deliver significant revenue growth and deliver profits during the second half of the year in line with management expectations. Tamdown is on track to enhance profitability over the medium term.
Conclusion
Unlike some other more speculative energy transition companies, Nexus does have a track record of profitability - although it has been struggling to make progress on this front.

That is reflected in a share price that has not done too much since listing.

Still, Nexus is positioned in some promising growth markets and appears to be more established than other more speculative energy transition plays so as a thematic pick, it has some merit. eSmart is the most interesting opportunity, but I get the feeling that its strategic review has not really taken off in the manner management had hoped.
The group's order book is ahead year-on-year and has grown over the past six months. It is confident of meeting full year expectations. A reassuring, if unexciting update then. The one negative surprise is in eSmart, with the low margin contract.
Nexus is forecast to make 9.73p of earnings this financial year, increasing moderately to 10.7p the following year, so it’s still not cheap by any stretch in my view. It does strike me as more attractive than others in what is a hyped up and speculative part of the market, but I wonder if there is still significant investment to come. That could weigh on near term profits.
It has spent a lot on capex in the past.

It’s still too early for me. There are short to medium term inflationary pressures to navigate before realising the longer term opportunity, which makes me wonder if we might see a more attractive entry point in future.
City Pub (LON:CPC)
Share price: 95.35p (+1.98%)
Shares in issue: 103,868,430
Market cap: £99m
This is an owner and operator of 42 premium pubs across Southern England and Wales.
Trading is recovering. Like-for-like sales have continued to strengthen faster than predicted, with May 2022 5% ahead of May 2019.
Two new sites opened: The Oyster House in Mumbles and The Tivoli in Cambridge, with initial trading encouraging at both sites. A new all-day concept in Bury St Edmunds, Damson and Wilde, is expected to open next week. One other site, The Nest in Bath, is anticipated to open in August. Beyond that, some existing sites have been refurbished or had their capacity increased.
Cost inflation:
We continue to seek ways of mitigating the increased cost inflation facing the wider sector and have reviewed our cost base with renewed vigour, with particular focus on labour scheduling to maximise sales and efficiency. Control of energy usage and procurement remains a key focus from both environmental and cost perspectives and we continue to evaluate our menu offering to provide best value and experience for our customers, whilst delivering great food in a cost-effective way for the Group.
So recovering trade, but increasing costs.
The Jubilee Bank Holiday weekend was particularly strong, with LFL sales up in excess of 20% versus 2019. That’s a one-off event, but it could be the foundation for a strong summer.
Executive chairman Clive Watson comments:
We continue to see our sales growth reflecting the quality of our pubs and customer offering. With a strong foundation to build on, and momentum that has been created through investment in - and opening of - our development sites, we look forward to an uninterrupted Summer's trading for the first time in two years. Despite the macro economic headwinds, recent openings, tight cost control and a low net debt position leave us well positioned to continue to develop our business both organically and through selective high-quality acquisitions during the rest of the year as opportunities arise.
Conclusion
It’s great to hear operators looking forward to their first uninterrupted summer in two years. Watson himself is an experienced hand and City is a competent outfit, but I’ve never seen particularly good value in the share price.
It remains some way below its c170p IPO level established nearly five years ago now. Back then it had 34 pubs and a market cap touching £100m. Today it has 42 sites and approximately the same market cap.

And lockdowns led to a significant amount of equity dilution (which is why the market cap is broadly the same even though the share price is down).

Pubs are a great cultural institution, but they can struggle to generate durable earnings growth. The ones that do grow tend to have a ceiling in terms of how large they can become, plus the ever present prospect of hungry and ambitious competition to contend with.
City does have a good freehold estate, which provides security and could even see a valuation uplift, but it’s not enough to tempt me as I suspect there are companies with more upside potential out there.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

44 comments
I hold my hands up and admit my understanding re: Intercede (LON:IGP) is limited, but it was a very positive update on investor meeting company tonight I thought.
Whilst updating the models on some of my holdings I noticed that the CAGR shown in Stocko's financial summary seems to be incorrect. Does anyone have an explanation for this?
I've just realised that I'd been using the wrong time period by treating the first year's value as the PV - Doh!!
I know Paul is a holder of Revolution Bars (LON:RBG) and I notice, as I live in Devon, that Revolution Bars (LON:RBG) are opening in Exeter on 1st July in a site which was a Las Iguanas Restaurant.
The new Bar will create 70 new jobs and £2m has been expended on the site.
Open from 12 noon until 2am on four days and Midnight on the 3 less busy days the Bar should do well in a City which is growing fast and has a big student population. I do not hold.
Hi portugull,
You've reminded me, I happened to be passing Revolution Bars (I hold) in Bournemouth earlier this week, whilst taking my afternoon walk, despite inclement weather.
I was strangley drawn inside, by a placard outside offering lunch for £6.95 - this seemed a very good offer, and indeed here it is -
.
Let me walk you through this - it's a chicken caeser salad, and 2 upgrades: chips for £1, and a pint of Amstel instead of a pesky soft drink for an extra £2. Total £9.95 - what a bargain! This was the £6.95 lunch offer you can see on the menu that I positioned in the picture.
Moreover, service was fantastic, charming staff, food arrived quickly, and it was delicious.
Even better than that, the Bmth site manager, Scott, who I chatted to months ago, recognised me, and said, "Hello Paul, great to see you again!". I invited him to join me, and we chatted for a bit, then when my food arrived, Scott said, I'll let you eat, give me a shout if you need anything. Then he looked back, and said, "Do you need any salt for your chips?", Yes please, and some vinegar if you don't mind. Sure - here you are. I like that - detail. The manager doesn't see himself above providing the basics, he's checking to see if it's done.
Lovely food! I went to pay, and a different voice called out, "Hello Paul!" - it was the Southern area manager who I'd also chatted to once before. I thought it was you! How's it going? All good thanks. Don't tell me anything confidential, but are you seeing people reducing their spending due to cost of living crisis? Well, a bit of that, yes. But our customers are young, they're not worrying about electric bills, they want to party!
Your wooden floor looks stunning still! Oh the refurbs are great. Have a chat to another of my managers - come over xxxxx (I forget his name). Hello! I'm Paul, a small shareholder in the company, and I mystery shop it and put it in my blog occasionally. Oh! (didn't really understand, and looked quizzical). Our refurb is great too, pulling in punters from across the road, as the competitor (in Brighton) is old & tatty. Are you that funny building near the Odeon? Yes, looks like a big haunted house LOL! We're really busy. Oh my niece has just moved there, I'll have to get her to mystery shop you! Yeah, get her to bring her friends in too!
Anyway, I got the impression everyone seemed happy, and that the refurbs are going well.
As I left, the managers & area manager all noticed, and acknowledged me, take care Paul, see you next time. What a nice experience. I think this share is going to do well. 15p looks so cheap. The refurbs should deliver good LFLs, and it has cash to roll out the new formats too (competitive gaming). Patience should pay off here, I reckon - I see RBG (I hold) as a 100% gain from 15p to 30p. Or, it might not.
As always, I would never base an investment decision on just visiting one site out of about 70 in total. But I like the feel of my local Revs in Bmth. The area manager said to me, Paul you've got to get the right managers in - that's what it's all about. I couldn't agree more.
Regards, Paul.
Anyone know what is up at RM (LON:RM.) ? Share price just fell circa 25% in 2 days on no news that I am aware of....
RM (LON:RM.)
Can't see anything on the other place (advfn) - it does seem odd move - albeit with illiquid shares it doesnt take much to move the dial and the recent newsflow aint exactly been great. So mystery to me - in situations like this would be nice if company did say "no reason for drop" to fut ones mind at rest. Could there be big seller with relevant newsflow confirming that sale still pending - hopefully thats the most "innocent" explanation. Not good if its leaky bad news in advance of news being made official move.
It is due to be kicked out of the FTSE All-Share due to falling below the minimum liquidity threshold.
That doesn’t sound good. Where did you find this info?
Marks Electrical (LON:MRK) are going to present on Friday at 10.30 am https://www.equitydevelopment.... if you want to ask them directly about those operating margins...
Spaceandpeople (LON:SAL) requested their shares be temporarily suspended from trading! Interesting. "Pending an announcement". M&A? Administration?
What happened yesterday at the AGM??
I noticed there were some strong blocks of votes against some of the resolutions, even though all of them passed.
(I hold in the Boon Fund)
I used to hold Spaceandpeople (LON:SAL) some years ago and from memory it did reasonably well for me. How odd it should be asking for a share suspension during market hours. I also noticed that some of the AGM votes were hardly a ringing endorsement. I wonder what is afoot.
Bizarrely it looks like Spaceandpeople (LON:SAL) need to suspend the shares to do a 10 for 1 share consolidation that was approved yesterday. Weird. Never seen a share consolidation requiring a suspension.
Integrated Diagnostics Holdings (LON:IDHC) posts 1st quarter results. Conventional sales increase as Covid sales decrease. Record-breaking dividend.
£IDHC
Forgot to say... I hold
Integrated Diagnostics Holdings (LON:IDHC)posts 1st quarter results. Conventional sales increase as Covid sales decrease. Record-breaking dividend
Strong dollar has been holding back EM shares. If/when that reverses, shares should run. Meanwhile enjoy the huge coupon. I have been adding aggressively - but this is no guarantee of results if recent performance is a guide.
Good morning Paul, it's rare right now for one of our shares to be going in the right direction but as Mr Contrarian has covered earlier Ramsdens appears to tick a lot of boxes, a comment would be much appreciated if you have time.
Hi JASVFS,
I'm really sorry we didn't get round to looking at Ramsdens Holdings (LON:RFX)
The reason being that I was on a really short timeframe today - I started at 7am as usual, but had to leave home for a long drive from Bmth to Reading, for an investor lunch that started at noon. So I had to down tools at just after 10am.
Jack did his best, but is still recuperating after a bout of illness. Sorry if I wasn't meant to mention that.
This was our agenda today, which we use to prioritise what we cover - I think we should try to cover Ramsdens tomorrow or Friday in a catch up? If there's a good reason for us to cover something, then shout! If we've missed a little gem, then we want to know!!
Also, when I know I've only got 3 hours, then I get more & more stressed, and often just grind to a halt & can't turn reading & thinking into writing. Whereas other days, it just flows out with great vigour.
Anyway, I love going through the reader comments, and the top % movers of the day, at my first morning tea break. Full of useful stuff, so please flag stuff to us that is exceptional & we should cover it! I'll happily drop some drudge of a company, to dig into something more interesting you people flag up to us! :-)
Best wishes, Paul.
VP (LON:VP.) is up for sale, has just come out with year end results in line with expectations, and as yet the SP has not moved. It seems a little underpriced?
£VP. says "The Company has launched a formal sale process and further communication with shareholders will be made if and when appropriate to do so." It does not sound like it is inundated with offers. I hold.
Richard
Journeo (LON:JNEO) (I hold) latest contract announcement was already included in management forecasts for this FY. Still a bird in the hand …….
I’m excited about this tech. Transport management systems are going to be the way to make the most of Limited resources and drive efficiency.
Intercede (LON:IGP), Final Results "It has been a promising year of financial and operational progress and Intercede is now very well positioned for further growth. We enter FY23 with
positive momentum and lots of opportunities. When I look at the various elements of this business; particularly the experienced management team, the high growth cybersecurity market, the blue-chip customer base, the pipeline and the resilient response to market conditions in the last two years, I remain confident of the Group's future prospects. Significant progress was made in FY22 and I am excited for the year ahead."
Hope this Falling star moves into a Turnaround .
For those interested, finnCap have a research note out on Research Tree.
I find Intercede (LON:IGP) a frustrating company - they don't capitalise their R&D so earnings are suppressed relative to some peers (or perhaps we should say peers overstate their earnings...).
Regardless, the lack of top line growth remains problematic. £10.4m in March 2020 vs forecast £10.9m for 2023. COVID 19 is cited as delaying project decisions, but the rest of the cyber security/cloud market seems to have ploughed onwards & upwards regardless, which makes one wonder about whether the product set addresses a niche market and is struggling to gain traction elsewhere.
The concentrated US Federal/Military customer base remains a two-edged sword - validates the product but puts revenues at the mercy of the budget cycle.
The operational gearing will be phenomenal if they achieve wider commercial deployment, but I am mindful of previous comments on Stocko where people more informed than myself observe that the product is high-end and overkill for many applications - IT managers aren't looking at this as an alternative to Okta. If most organisations decide that third party authorisation via a code texted to the user's mobile phone is "good enough" (and the online banking/broker platforms seem to think so) then what is the true addressable market?
Regulation may ride to their rescue, but waiting for your customers to be forced into buying your product can be a very long wait indeed.
I think I need to go back and look at the product again - anyone here have direct experience?
Thanks for your post a new angle on Intercede (LON:IGP) Monty Carlo. I hold but am wondering whether to cut the loss. Hopefully Paul will be able to comment?
I haven't yet done my detailed analysis of Intercede (LON:IGP) results today, but did a quick skim and on the fence still at the moment as a disappointed holder.
There are lots of positives going for it; recession-proof government client base, growing macro environment, high gross margins and operational gearing, and a solid (if not excessive) balance sheet strength.
The negatives are, of course, hashed out already by others. Disappointing lack of growth, despite management having trumpeting growth plans for the last two years. Very woolly management commentary in the results; they should just fess up and admit that they haven't delivered the growth they have dangled in front of the market. Does one really want to invest in management that waffles and deflects from their inability to deliver? So far, I haven't been able to find a single tangible sign of a strong outlook (ie order book numbers, etc) in the results.
Clearly trading at a high multiple - at 1.3p EPS, the shares could half if the expectation is of static profits at this level for years to come. However, my back of the envelope modelling is that if revenues can increase 15%, then 2p EPS is easily achievable, but even that would put the current share price at a 20+ PE ratio, which isn't a bargain to pay for future growth that shows no tangible signs.
However, if you then factor in most of the net cash as surplus to requirements, then the valuation looks more sensible at around 17x for a 2p EPS forecast.
The other consideration is FX. Most of their revenues are in USD, while costs are in £. With the exchange rate looking like it will be approximately 6-8% more favourable for FY23, this naturally will drive EPS upwards, probably to the 1.7p range I believe, all else being equal between FY22 and FY23. So there is already some EPS "growth" we can take for granted, and only needs another extra contract or two this year to get to 2p+ EPS.
(I hold in the Boon Fund)
You failed to mention the biggest negative, its main product doesn't add much in a cloud first world.
There are numerous identity providers including Microsoft, Google and Facebook. Good luck competing against them.
There are numerous identity providers including Microsoft, Google and Facebook. Good luck competing against them.
RE: Intercede (LON:IGP)
Not to mention Okta. Or RSA. Or Ping. Etc.
But the question investors need to ask themselves is: would the US government really put its security in the hands of a tiny UK company? And if we think they wouldn't, what does that mean?
timarr
I doubt it means anything as the product the US govt has bought is most likely the non-cloud connected one, where most of the identity providers don't have an offering. So, the US Govt hasn't put its security in the hands of a tiny UK company, it's bought an authentication product that provides an authentication token as a small part of the overall security picture.
Has IGP done anything to prepare for the secure remote desktops that are starting to become the industry standard for sensitive operations as the world moves to zero trust?
Dear Various, above -
It's pretty obvious that you don't understand what Intercede (LON:IGP) (I hold) actually does. I don't really either.
It's niche software for managing very large numbers of security identities online.
It's used extensively by lots of large organisations, including the US Govt. So if you are questioning why the US Govt would use a tiny AIM co to manage cyber security. Err, it has done for about 20 years. IGP provide a bit of it.
Paul.
Paul.
I work for a large multinational IT services provider, one of the things I help customers with is identity management. I've been somewhere that has looked at Intercede's offering in the non cloud connected space and it seems pretty good. It's the online part of the business that is struggling as far as I can tell as there are many ways of doing multi-factor authentication built into the cloud provider's services that don't require extra licensing or set up. Trust me, I get it and I get why it's not growing revenue - there's only so many non cloud connected environments out there, and their numbers are diminishing.
It's pretty obvious that you don't understand what Intercede (LON:IGP) (I hold) actually does. I don't really either.
Paul
I also work in the industry, I've worked with IGP and a range of its competitors in the past and on US and other government identity projects. I think I get what they do ...
timarr
Some of us do have a reasonable technical understanding (there is plenty online to explain PKI and FIDO, there are Gartner reports), but the commercial case is a different matter.
Assessing complex software platforms as an external observer can be very difficult indeed, especially if you are talking about individual components in a wider system environment that is provided by integrators/resellers (e.g. Thales for example) so the end user of the system may not appreciate what is going on under the bonnet.
The devil is in the detail - what the company says in their sales material (and to investors!) is not what the project manager who ran the RFPs discovers to be accurate when choosing which solution to buy, and they don't always go for the "best" technical option either if an inferior product is sufficiently cheaper and good enough.
Anyone here with a City background who has had to choose between risk system providers (e.g. Aladdin, Bloomberg, Delta, Statpro, Barra etc) will get the problem.
Given Intercede (LON:IGP) talk about >£20k new deployments as a major KPI they are really a tiny piece of the jigsaw....
There are a wide range of case studies on the IGP website, but those customers probably didnt choose MyID, they chose a broader solution which happens to incorporate MyID. Some integrators will then discount to get a foot in the door, making the picture very muddy indeed.
Someone at Thales or Accenture will have a good idea of the value proposition, not easy for the rest of us.
Intercede (LON:IGP)
"I find Intercede (LON:IGP) a frustrating company - they don't capitalise their R&D so earnings are suppressed relative to some peers (or perhaps we should say peers overstate their earnings...)."
Over the long term though not capitalising r&d spend should end up with the same end result - you are only delaying things by capitilising and later amortising.
As IGP has gone nowhere in last 7 years ref annual sales i would expect that any r&d capitalising issues should be neutral (as you have less amortisation charges than you would have done if you had capitalised stuff previously) unless they and spending much more in that area now than they were way back when - if they are spending more now to "stand still" than they used to have to spend to "stand still" then that also aint a great sign - if they are spending more to stand still i would expect they would somewhat "amber" the situation by pretending they are investing for the future "sales increases" -on a positive note the company is less of a basket case than it was back in 2016 and 2017 and 2018 looking at the numbers.
In my view, and as someone who works in the software industry, the capitalisation of software development costs is a bit of a racket. Over time a continuous spend is needed just to keep software current (in line with latest versions and technologies) and as software matures it tends to become increasingly complex meaning that even small changes mean exponentially more work.
Far safer to expense development costs and have a clear picture going forward of what the revenue to ongoing overheads ratio (mainly people) is.
I should have made the sarcasm in my comments a little clearer...P/E ratios not always being the best approach to software companies....
Nevertheless, Intercede (LON:IGP) is different to the mainstream identity providers, providing multi-factor protection that involves hardware such as smartcards or USB sticks within a PKI solution (anyone else here remember Baltimore Technologies reaching the FTSE?). Nor am I claiming they are unique - RSA SecureID being another public-key encryption provider I've come across.
My presumption is that Intercede (LON:IGP) 's solutions are more appropriate to controlling access to secure networks with national security implications.
I don't worry about the US using a UK company too much in this space as they can be replaced- BAE Systems was permitted to acquire US companies that were involved in key US Army supply chains. There is an ongoing spat over Ultra Electronics that may change that, but we've seen similar before. HID Global does a lot of US business in this space, but is owned by Assa Abloy.
Where I do struggle is assessing the commercial merits of IGP's solutions relative to competitors in the same space, and trying to assess whether demand will spread beyond the current customer base as cyber security concerns rise up the priority list for blue chip companies.
Hi Quilleron,
Thank you so much for this. It's such common sense, and is what I've always said re software businesses, bravo! :-)
"In my view, and as someone who works in the software industry, the capitalisation of software development costs is a bit of a racket. Over time a continuous spend is needed just to keep software current (in line with latest versions and technologies) and as software matures it tends to become increasingly complex meaning that even small changes mean exponentially more work."
Best wishes, Paul.
I'll be tuning in to the IMC presentation tomorrow at 16:30 and it'll give those who are interested a chance to pose their questions.
Another great update from Coral Products (LON:CRU) this morning. Still well ahead of (admittedly unadjusted) expectations and still generating huge amounts of cash, in spite of spending on acquisitions and share buybacks.
https://www.investegate.co.uk/...
On top of that, top line growth of over 100% is already baked in for 2022/23 due to the recent acquisitions of Film & Foil and Alma Products, with material bottom line and cash flow improvements likely to come through too.
I just wish that they would sort their dividend policy out. They should be identified as a very secure, high-yielding (6.6%, including today's dividend and at yesterday's closing price) opportunity by stock screens. However, my concern is that, by paying the dividend as a 0.5p interim, 0.4p additional and 0.2p final, the additional will get "lost" in the databases and the screening algorithms will consider this latest announcement a 60% reduction in the final dividend, rather than the 20% increase that it is in practice.
Further to Coral Products (LON:CRU), here's a rough estimate of 2022/23 revenue based on the most up to date data available for the various parts.
£14.4m - existing businesses 2021/22 revenue
£8.7m - Alma Products 2021 revenue, but only for 11 months for Coral in 2022/23
£10.1m - Film & Foil 2020 revenue
Sub-total £32.5m.
Add on, say, 5% for growth and/or inflation:-
Total £34.1m
So massive top-line growth this year, with obvious potential benefits to operational gearing.
Good to see that Stocko now rates Coral Products (LON:CRU) a Superstock.
Sherborne Investors (Guernsey) C (LON:SIGC) statement re the appointment of E Bramson to the board of Navient, US listed student loan administrator. There are details of the cooperation agreement in the proxy statements on Navient website. All would appear friendly.... In Navient`s last quarterly update they already hinted at costs reducing in future quarters...and so next news I expect is an improvement in this with possible review to identify more savings. Traditionally Sherborne go for a strategic review but it may not be necessary this time. The CEO and board are well paid in stock and have significant options.
The Sherborne model is to find businesses where they can improve operating margins and reposition for growth - driving a higher rating. They identify opportunities with 100% upside....which would be mid 40s Navient .... this translates to > 150p £SIGC. Current price 47.
I held Sherborne Investors (Guernsey) C (LON:SIGC) a while ago when it was invested in Barclays but didn't want to continue to hold until I found out more about the new target Navient. Unfortunately Sherborne provide zero information on the rationale so not easy to research this. Investor relations definitely not their strong point. That said they have a good track record so wouldn't be surprised if they unlock some nice returns.
Great update on financing from Phoenix Copper (LON:PXC) today! This will be a game changer in getting the Empire Copper Mine into production again, which will produce a steady and hefty revenue stream to explore and develop its other impressive assets. Definitely an exciting and promising junior miner, without the usual risks/uncertainties and in a great jurisdiction.
"The Bonds will pay a semi-annual coupon linked to the copper price with a minimum of 7.5% per annum (at a $3.60 / lb or lower copper price) and a maximum of 20% per annum (at a $11.95 / lb or higher copper price)"
20% coupon ?!
We really have entered into a period of high inflation+ high interest rates.