Small Cap Value Report (Weds 8 Nov 2023) - JDW, RCH, EAAS, STB, WINE

Good morning from Paul & Graham!
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
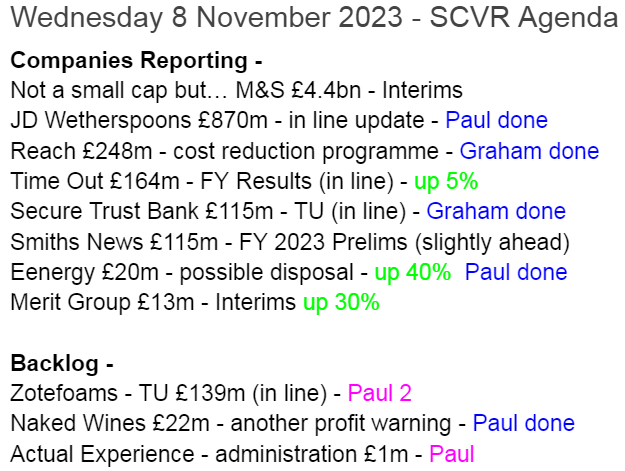
Agenda
Summaries
J D Wetherspoon (LON:JDW) - 676p (pre-market) £870m - Trading Update - Paul - AMBER
Reassures with a decent Q1 (Aug-Oct) update, LFL sales again exceeding industry average. Cost pressures abating, apart from energy, which is high still. Overall trading in line with expectations for FY 7/2024, which implies the PER coming down from high to middling. Looks priced about right to me, and I admire the company's long-term track record. Could hotels be a new growth area?
Reach (LON:RCH) - up 0.6% at 78.4p (£249m) - Cost reduction programme - Graham - GREEN
This large news publisher announces 450 job cuts as part of plans to reduce operating costs by another 5%-6%. It’s tough news for staff but I expect that it will help to maximise cash generation as the company continues on the road towards paying off its pension deficits.
Eenergy (LON:EAAS) - up 43% to 5.7p (£20m) - Luceco investment & potential disposal - Paul - AMBER/RED
Luceco makes an investment into EAAS, but seems to be doing it so that EAAS can pay invoices for goods supplied by EAAS. EAAS also tells us it has received indicative bids for its larger division at more than double last night's group market cap. That could transform the finances of this financially stretched group - I remind readers below of the nasty balance sheet.
Secure Trust Bank (LON:STB) - down 1% to 592p (£112m) - Q3 Trading Update - Graham - GREEN
This specialist lender publishes its Q3 trading update. There is nice growth year-on-year although new business lending has cooled down a little quarter-on-quarter. At a PER around 3x, and no sign of imminent collapse, I can’t avoid a positive stance on this stock.
Naked Wines (LON:WINE) - down 36% to 29p y’day (£21m) - Trading Update & Board Change (profit warning) - Paul - RED
Another quite bad profit warning. I've covered all the negatives here 3 times previously in 2023, being RED each time. Although with the market cap now only £20m, I'm wondering if this could be viewed as a special situation, a risky recovery trade, by people prepared to have a punt, knowing that it could end up at zero.
Paul’s Section:
J D Wetherspoon (LON:JDW)
676p (pre-market) £870m - Trading Update - Paul - AMBER
J D Wetherspoon plc (the "company") today publishes its scheduled trading update announcement for the 14 weeks to 5 November 2023, comprising quarter one (Q1) and a further week.
Summary - it’s trading in line for FY 7/2024, from 816 pubs -
"The company currently expects an outcome for the financial year in line with market expectations, and will provide further updates as the year progresses."
Anecdotally I’ve heard that trading has been tough for some bars, but serving the value for money end of the market, Wetherspoons looks resilient -
Like-for-like (LFL) sales in the first 14 weeks of the financial year were 9.5% higher than the same period last year.
It says this is higher than the industry average of +5.9%, a continuing trend of out-performance over the last 13 months.
Hotels - interestingly, it also mentions its hotels today, which I’ve never focused on before. Google says it has 57 hotels (which look like rooms over larger pubs, judging from the photos on Wetherspoons website booking area for hotels). They look quite nice, and cheap, although in locations that I generally wouldn’t particularly want to visit.
Budget hotels are a lucrative area at the moment - I recall being amazed at the tremendous profitability of Premier Inn, within Whitbread (LON:WTB) - and it pointing out that the UK only has a few budget hotel brands, whilst lots of independents have left the market.
Could this be a longer-term opportunity for Wetherspoons to further expand into larger sites, with a hotel above, or even standalone hotels? Maybe a different brand name for the hotels might be a good idea? Wetherspoons has both good, and bad brand aspects in my view. I’d need reassurance that its hotels use industry-leading sound deadening in the building, before wanting to book a room!
Inflation - pressures are easing, except for energy which “remain at far higher levels than pre-pandemic…”.
Capex is being increased to £70m this year (LY: £47m), to improve existing pubs - a good indication of a company that’s now on the front foot, after all the pandemic disruption. That sounds a lot, but it’s only £86k per site.
Financing - it looks as if some new interest rate fixes were agreed in Aug & Sept.
This is the key area to research, as finance costs consumed 64% of its (much improved) operating profit in FY 7/2023.
Note that free cashflow was hugely boosted in FY 7/2023 from a highly lucrative deal to close out interest rate swaps (set up very cannily in the zero interest rate era), which was a one-off. So free cashflow is much less than it seems, if normalised.
Paul’s opinion - it’s difficult not to admire the achievements of management here, with an excellent long-term track record. The main differentiating factor being low prices, which has obvious appeal to customers, especially when disposable incomes are under pressure.
Are the shares good value though? On the historic numbers, no not really. It did 26.4p adj EPS in FY 7/2023, so at 676p we’re being asked to pay 25.6x earnings. That implies the market thinks earnings should improve further in the future.
The StockReport is showing big forecast increases in earnings to 40.4p FY 7/2024, and 50.4p FY 7/2025. If those numbers are achieved, then the PER drops to a much more palatable 16.7x and 13.4x respectively. So you need to be comfortable that forecasts are achievable, to hold this share. Note that broker forecasts have been steadily increasing this year, which is usually a good sign -
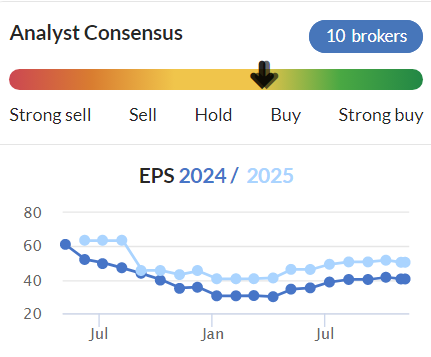
Assuming it achieves forecast, and we’re told Q1 is in line, then the share price looks about right to me.
JDW has said in the past that there’s upside in the valuations of its freehold properties.
Lots of competitors continue to go under, so JDW could end up with greater market share in the long-run.
Taking everything into account, this share looks priced about right to me, so I’ll stick with AMBER.
JDW once again reiterates its defence document against a strikingly large number of inaccurate, misleading press articles, and politicians’ inaccurate comments, where JDW has obtained retractions/apologies. There does very much seem to be an anti-Wetherspoons agenda - I wonder if that’s because Tim Martin was such a vocal supporter of Brexit, and is generally outspoken? The press seem to be out to get him, a bit like their determination to destroy Boohoo (LON:BOO) whilst ignoring far worse abuses by the Chinese operators that are now dominating the fast fashion sector. The internet may be full of nonsense, but half the time so is the conventional media! That’s why I never believe anything I read in the media, and instead always check source documents myself, where possible, and listen to the opposing point of view too.
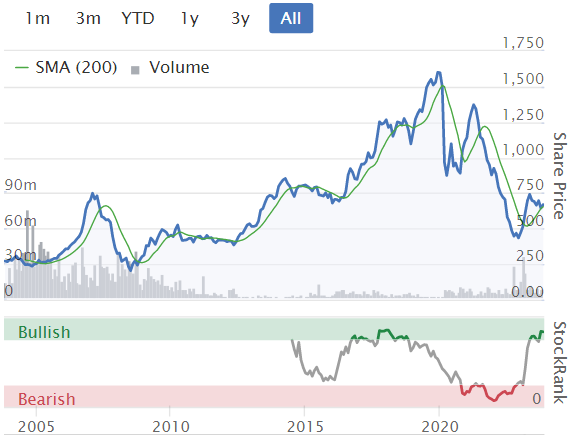
Stockopedia likes JDW, ranking it as a "Super Stock", and with a high 82 StockRank.
See from the long-term chart below, the share price is still a long way below pre-pandemic levels. Although note that there were c.106m shares in issue pre-pandemic, which has since risen to c.129m. So the equivalent peak market cap would be a share price about 18% lower now.
Eenergy (LON:EAAS)
Up 43% to 5.7p (£20m) - Luceco investment & potential disposal - Paul - AMBER/RED
Many thanks to one of our regulars, eParo, who flagged in the comments below interesting developments at eEnergy. There are 2 elements to this announcement -
Luceco (LON:LUCE) is subscribing for 35.078m new shares in eEnergy, at 5p per share = £1.75m.
What makes me sceptical about the reasons for doing this, is that Luceco is a supplier to eEnergy, and is owed money! We’re not told how much is owed by eEnergy to Luceco (Luceco supplied electrical parts to eEnergy).
As I mentioned here on 29 Sept, it’s clear from the 30 June accounts that EAAS is having financial trouble. The receivables book was far too large at £22.9m (compared with £33.2m annual revenues!), net bank debt of c.£6.5m, and negative NTAV of £(4.75)m. It also has debt maturities of Feb & May 2024 which need refinancing, although the company said in its last going concern statement that it expects to be able to refinance, including more equity “if required”, which sounds a pretty loose set of assumptions to me! Accordingly, I previously marked it RED, due to the need to refinance, which is currently unclear.
Possible disposal - this bit is much more important, and is the reason buyers have moved in today, taking shares up 40% in early trades -
Board considering unlocking value via a disposal of the Energy Management division
EAAS says it received
“a number of unsolicited approaches expressing interest in acquiring the Energy Management division”,
and received,
“a number of indicative cash offers which valued the Division in excess of £30 million. The Board has now entered into a period of exclusivity with one of the interested parties”.
Discussions are at an advanced stage, but there’s no guarantee the deal will complete, or as to its terms. Also, we’ve only got the word of EAAS on all of this, I can’t see any supporting third-party announcements, or named suitors.
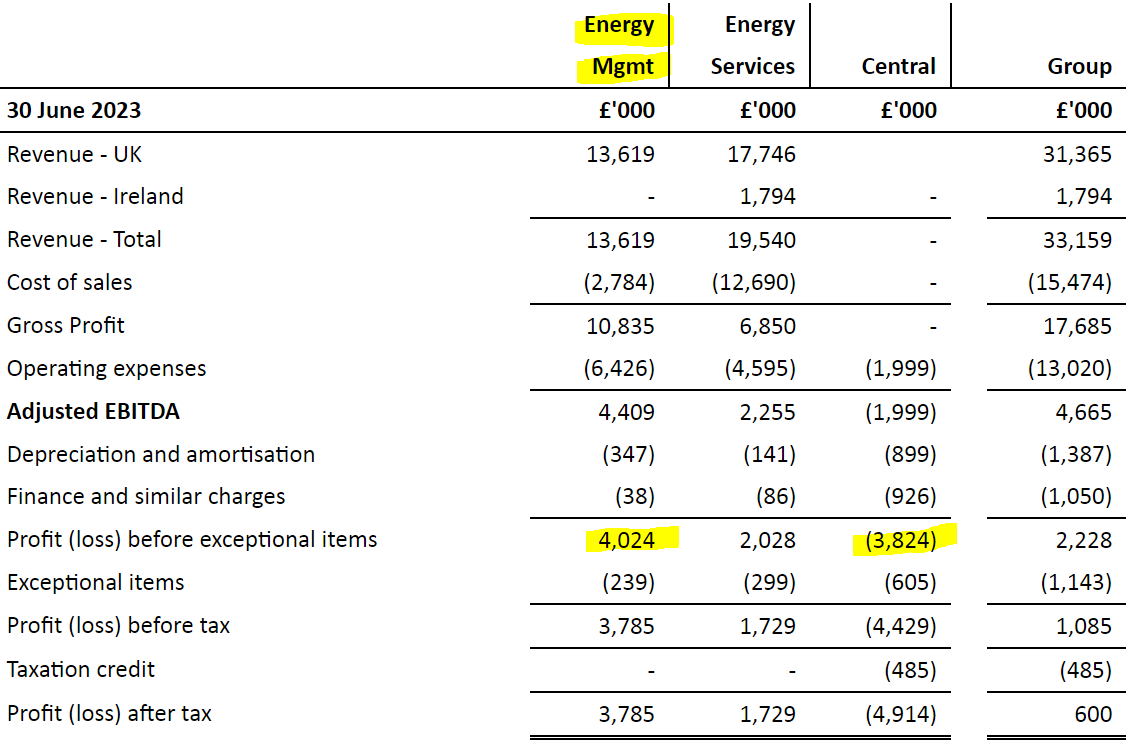
Looking back at its 12 month results to June 2023, there is a divisional split, showing that the Energy Management division looks decently profitable at £4.0m. However note the very large central costs of £3.8m, which seems very high considering there are only 2 divisions. Although central costs are actually £2.0m, with the £1.8m above that being depreciation/amortisation and finance charges.
Paul’s opinion - this is clearly a financially stressed group, and it has been clear for some time that it needs to refinance. If a disposal goes through, and raises >£30m, then I’d be more than happy to take a more positive view of EAAS shares. Although that would depend on how viable the remaining, smaller division is? Is it trying to sell the family silver, to get out of a hole?
However, that’s not something I would want to gamble on, because this deal may not happen. In which case all the question marks over balance sheet, cashflow, and refinancing, would take centre stage again.
The deal with Luceco doesn’t particularly impress me either, as it looks a roundabout way for Luceco to get paid from a customer that’s in financial trouble.
As planetx points out in the comments below, how is the Luceco subscription not insider dealing, given that the market had not been informed that a possible disposal is at an advanced stage for (at last night’s value) double the group market cap?
Overall, the news about a possible disposal does sound very significant (if it completes). However, I still have considerable concerns about EAAS if this deal were to fall through. Therefore I’ve got to continue reflecting the negative financial position as things stand currently, but also the upside from a potential deal, so have decided to improve from RED to AMBER/RED.
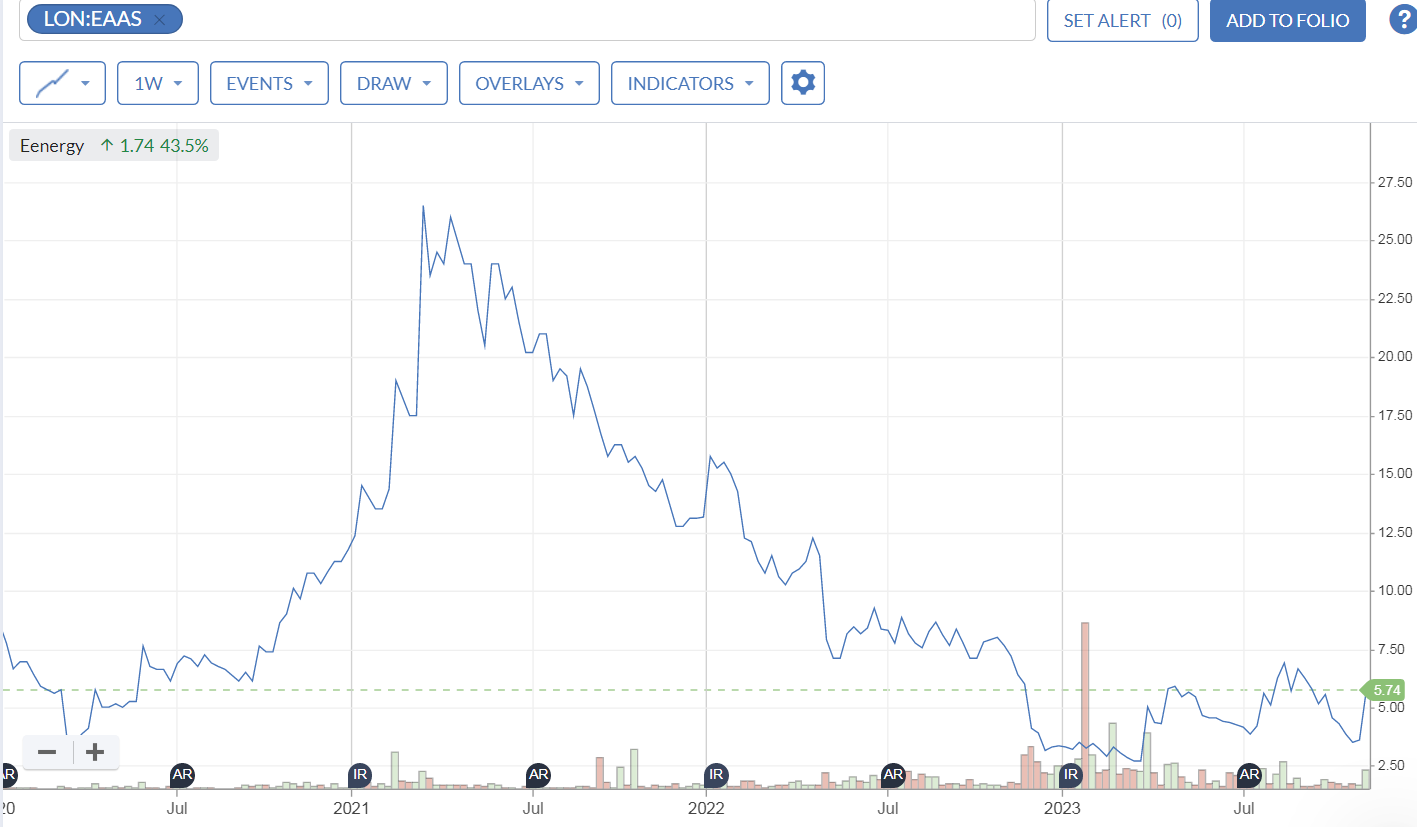
EAAS seems to have been formed in a reverse takeover, on 9 Jan 2020, of Alexander Mining. Failed junior resource stocks don't die, they just morph into something new! The Doctor Whos of the shares world! The first day of dealings announcement on 9/1/2020 says EAAS had 130.9m issued shares on admission, at 7.5p. Note that EAAS has been a prolific issuer of new shares in the last 4 years, with the total having since risen to 352.1m shares.
I've set a custom date range below, from 9/1/2020 to today, so we can see the performance of EAAS as a standalone entity post. As you can see, a lot of excitement in 2021 has fizzled out, and it's now back below the original listing price, despite today's 40% surge -
Naked Wines (LON:WINE)
Down 36% to 29p y’day (£21m) - Trading Update & Board Change (profit warning) - Paul - RED
This is the well-known wine subscription service that's trying to expand in the USA as well as its home market of the UK.
Checking our previous notes here, I was unconvinced by the turnaround strategy in Dec 2022, so amber. But we then went RED on 27 April, 4 July, and 20 Sept 2023, because there was no evidence of the turnaround plan working. Problems we reported on included late FY 3/2023 accounts, material uncertainty in going concern, weak current trading, and massively overstocked on its balance sheet with its own wine lake - where I suspect more write-offs might be necessary. The founder returned as Chairman, and has today taken over as acting CEO.
I don’t believe WINE has ever really demonstrated it has a viable business model. With the market cap now only £21m though, is there a chance it might survive and prosper?
Astonishingly, WINE shares peaked at almost 900p at the market peak in summer 2021. I remember happening to be watching CNBC at the time, when some crazy Yank was ramping WINE shares, saying it was an expanding “platform”, or maybe even “eco-system”, I can’t remember the specifics, but do remember he was talking total nonsense!
The share count hasn’t been diluted (yet), and remains around 74m shares in issue.
This is the latest detail from yesterday’s profit warning -

That’s clearly a large reduction in adj EBIT (operating profit), now only expected to be £2-6m (previous forecast £8-12m, and LY actual was £17.4m).
There were very large adjustments of £31.6m last year, so it was a statutory loss of £(15.0)m. £14.0m adjustments LY was stock impairment, which to my mind is not justified to be adjusted out. It’s a bona fide cost of business - from bad buying decisions. I suspect it might be the tip of the iceberg of unsold inventories, time will tell.
NTAV was £83m at 3 April 2023, 4-times the market cap. So the share price is implying what I also think - that inventories of £166m could contain a lot of problem products that need writing off.
Liquidity - this actually sounds OK -
The Group ended H1 with £3m net cash and £45m of additional liquidity available through its credit facility. The Group is currently at its lowest point of forecast liquidity and continues to anticipate converting excess inventory to cash over the next 12-18 months given its materially reduced inventory commitments. As a result of the reduced revenue expectations in the US, the previous destocking timeline has extended slightly.
The Group has met all borrowing covenants to date and is projected to continue to meet all covenants under the revised guidance set out above.
Paul’s opinion - the CEO has left, being replaced in the interim by the founder, who says this rather scathing comment -
My view is that this [US trading] shortfall is largely to do with execution, which in turn is largely due to Nick Devlin splitting his time across both the role of CEO and US President.
Overall, I’ve got to maintain my RED opinion here, as there’s still no sign of a turnaround, and with another profit warning under its belt, the question remains whether they have a viable business here or not?
On the upside, liquidity and covenants sound OK. Although I’ve just re-read the extensive going concern statement published on 19 Sept 2023, and it still contains a “material uncertainty” warning.
I don’t know what will happen in the future, but I think it looks like a coin flip now as to whether the founder can improve performance enough, and turn inventories into cash, to ensure survival.
With the market cap now down to only £20m, it’s almost being priced to go bust.
Could it be worth a punt, as a trade for a rebound? Maybe, for risk-takers who are happy to accept the risk of either massive dilution from an equity raise, or even losing all your money in an insolvency.
Someone might come along and bid for it, you never know - there must be some value in the brand, and the customer lists.
So definitely not for widows and orphans, as a regular investment, it’s a definite avoid for me though, with my sensible hat on.
The more excitable part of me is starting to get interested though, purely as a small, speculative, risky trade, that may or may not work - the valuation of £20m leaves plenty of room for recovery, if the founder does manage to turn it around. What's the time difference between here and the US? Is it worth a phone call to CNBC I wonder?!
Naked Wines was meant to be the saviour of the old Majestic Wines, so that hasn't really worked. Although to be fair, shareholders did have a lovely selling opportunity in 2021 to cash out at a premium.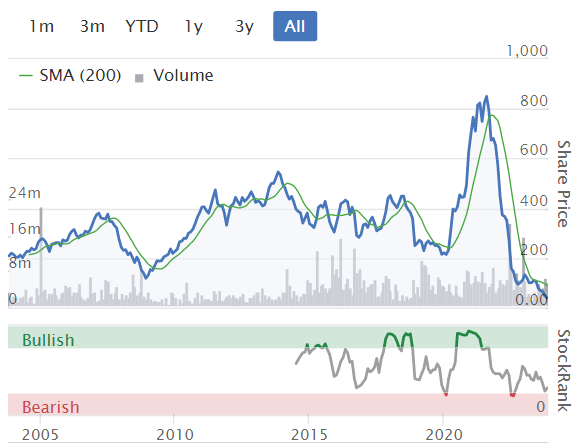
Graham’s Section:
Reach (LON:RCH)
Share price: 78.4p (+0.6%)
Market cap: £249m
A brief announcement from Reach plc this morning, with bad news for the workforce.
First, the company reiterates that it will deliver the 5-6% reduction in operating costs that was planned for 2023.
Then:
Furthermore, Reach will deliver a 5-6% in-year reduction in the operating costs for 2024 as part of its ongoing planning process. This cost reduction programme is part of the Company's drive to strengthen its position as a leading digital publisher, and mitigate against the backdrop of continuing inflationary pressures that we expect to impact 2024.
As part of this programme Reach proposes to reduce its total workforce by an estimated 450 full time roles. The savings will allow the business to deliver on its long term plans, while continuing to invest to drive better customer value, develop online products and grow new audiences.
Checking the 2022 annual report, I find the following description of average staff numbers:
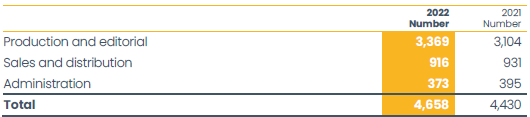
So 450 full-time roles should be somewhere in the region of 10% of the total.
Given that 72% of staff (as of the end of 2022) were in production and editorial, it’s inevitable that the cuts will hit this group. I’d be curious to know where Reach thinks the greatest efficiencies might be achieved - in production/editorial, in sales or even in admin?
CEO comment is unapologetic:
Our industry has a history of change and the future will undoubtedly involve yet more. That's why it's essential we set ourselves up to win, by making our operations suited to an increasingly fast-paced, competitive and customer-focused digital world."
Graham’s view
I remain very interested to see how this share will pan out. Much depends on how the pension funds are resolved - see my comments in October trying to guess at future contributions.
Sadly, I doubt that very many at all of the staff losing their jobs in 2024 will enjoy anything like the pension benefits of the previous generation.
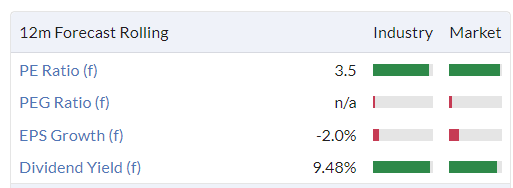
From an investor point of view, I think these jobs cuts are a good sign that the company is being run for cash flow and for profit: let me remind you that there are some very nice profit forecasts for the next two years, even after downgrades:

As the enormous contributions into the old pension schemes get paid (probably around £60m p.a. until 2028), I think this stock could gradually see its earnings multiple recover towards something normal.
The other possibility is that the pension contributions sink the company. But the nicer outcome looks more likely to me at the present time, so I’m keeping my positive outlook on Reach. Today’s announcement underlines management’s ruthlessness in ensuring that the company continues to generate as much cash as possible.
Secure Trust Bank (LON:STB)
Share price: 592p (-1%)
Market cap: £112m
It seems topical to look at banks, given their very “cheap” valuations. STB has a ValueRank of 98! Price to book is only 0.35x, according to Stocko, and how about this for a P/E ratio?
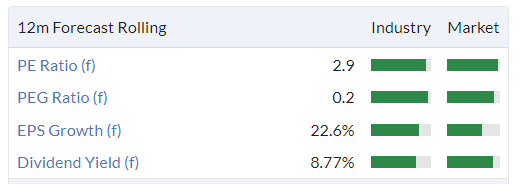
Let’s check out the company’s Q3 trading update to see if there are any signs that investor concerns are justified.
Highlights table:
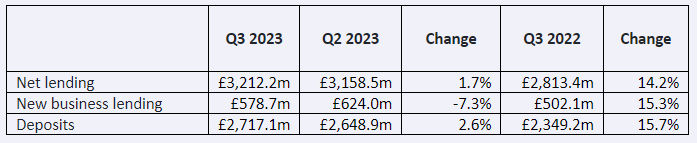
Net lending: steady growth of 1.7% quarter-on-quarter in the loan book, helped by 16% growth in commercial finance. STB is a specialist in asset-based lending: invoice finance, stock/inventory finance, etc.
New business lending: this falls 7.3% in the quarter but is up 15.3% year-on-year.
I think the new business figures are clouded by the fact that Q3 2022 was a time of particularly high uncertainty - there was the mini-budget in September, along with rising interest rates and inflation. So I’m not sure I would read too much into the growth figures in Q3 2023 vs. Q3 2022. The company was very cautious in Q3 2022, for good reasons.
Deposits: growth here is commensurate with the growth of loans. The company offers a range of savings accounts, fixed rate bonds and fixed rate ISAs, and the rates offered look competitive to me (e.g. 5.5% on a 1 year cash ISA).
CEO comment:
The Group has continued to grow in the third quarter and demonstrated the diversity of its business model with Business Finance contributing its highest quarterly new business volumes in over a year…
The continuing fall in inflation is welcome. We may have seen the high point of interest rates as a result, although the current rate environment has resulted in demand softening more recently. The impacts of the recent high inflationary environment may not have materialised fully yet and so we continue to monitor our markets and customer portfolios closely.
Graham’s view
STB is not acting as if the sky is about to fall, and I don’t see any sign of economic calamity striking it just yet.
Interim results to June showed a pre-tax profit of £16.5m which included the cost of a big impairment in commercial finance. The company guided for a “significant improvement in profitability during the second half of the year through loan book growth and cost leverage”.
Shore Capital are forecasting adjusted PBT of £45.6m for the current year.
Balance sheet equity was last seen at £314m, supporting £3.1 billion of total assets.
This is another high-risk, high-reward situation but again I have to point out that investors don’t get offered valuations like this every day.
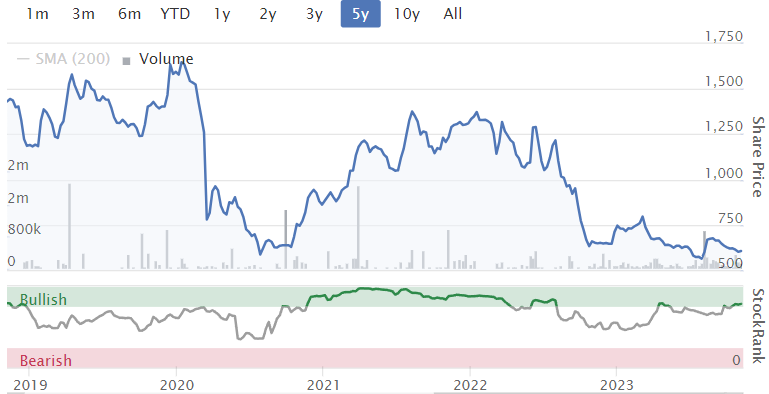
Sentiment is on the floor and the chart looks terrible but I don’t see how I can avoid taking a positive stance on the stock at this valuation. I was neutral at 735p earlier this year, when uncertainty seemed higher. But below 600p today, I can’t deny that this looks like a bargain.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

85 comments
Just as an addition to MetalMaid's excellent post. In my experience online bookmakers don't like punters who only use them when they have the longest odds. They only want mug punters who use them regardless of the value that they are actually getting. I too have had many accounts closed, or restricted, one after placing just 4 bets, all of which lost.
I also used to back a horse with the bookmaker, and lay it off on Betfair if the odds were such that I could make a profit regardless of if the horse won or not (arbing). On one occasion, I backed a horse with Betfred and Tote Bookmakers (owned by Betfred) and simultaneously laid it off on Betfair. When the horse won, Betfred imposed a rule 4 deduction, but the others did not! Another great way to increase profits, and screw the punter.
Today we have sen the inadequacies of three financial regulators (SFA, SFO - see also many past issues Private Eye - and the Gambling Commission) described on this site, as well as frequent references to the inadequate regulation of AIM by the LSE. Does the private investor have any realistic protection?
Eenergy (LON:EAAS) - Strategic developments highlight valuation anomaly *** new research report with audio summary ***
Link here: https://www.equitydevelopment.co.uk/research/strategic-developments-highlight-valuation-anomaly
eEnergy has announced a strategic investment from Luceco plc, whereby Luceco will invest £1.75m via a subscription for new ordinary shares at 5p per share, a 25% premium to yesterday’s closing price. Luceco is a significant supply partner to eEnergy’s eLight business (part of its Energy Services division). The investment looks strategically sensible, strengthening this longstanding relationship, as well as eEnergy’s balance sheet. Additionally, the Board is exploring the potential disposal of the Energy Management division.
After receiving a number of indicative cash offers, which valued the division at >£30m, the Board has entered into a period of exclusivity with one of the interested parties. Irrespective of the outcome of this process, we feel that these developments shine a light on the underlying value of the Group, which, in our view, is not reflected in a current market cap of just £15m.
I see that Zotefoams in on the 'to-do' list. If you have time, it would be interesting to read your comments. Not so very long ago, you did an interesting interview with the CEO.
Zotefoams has a capitalisation of £130 million, and what appear to be some moated products, therefore it seems to be a candidate for this forum.
Hi nettle,
Yes indeed, I like Zotefoams (LON:ZTF) and hold a few personally.
I've earmarked it for Friday's report, catch up day.
Best wishes, Paul.
Entain (LON:ENT)
Not a small cap but spent some time going through the presented strategy and it’s actually pretty compelling over a 4-5year horizon.
To summarise - Average 7% NGR growth across purely regulated markets. plus a bunch of cost savings £100m annualised and moving ebitda margin up towards 30%. this all excludes the US JV which should be material additionally.
Should push them towards an ebitda of £1.8bn plus the US the high I estimate could be half again.
Strip out interest costs and tax and they would be generating north of £1bn cash flow p/a plus US. On an average rating they could get to £30-40 p/share.
So assuming the plan is sound and it doesn’t look overly optimistic to me then could see a nice 30% annual compounder over next 5 years plus dividends.
I noticed the directors all bought a decent amount yesterday and that an institution has taken a considerable holding. Interesting.
I think the apparent £2.5billion debt might put lots of potential investors off? (£1.5bn when taking their cash pile into consideration)...
They can generate around £700m + a year mjfgs so debt isn’t really a problem. It is 2* ebitda and easily serviceable. But you’ll find that drops dramatically as well given the 5 year strategy is now focused on organic growth rather than acquisition. Not sure that’s particularly well understood.
Sigmaroc (LON:SRC)
I see that M&G (LON:MNG) has reduced its holding from 9.95% to 4.8% . I wonder who the buyer is? Sigmaroc (LON:SRC) is up today in a tepid market, but like most UK small cap/AIM shares remains cheap.
I hold.
Blackrock? Chelverton? Both have added this year.
Great work as ever, especially Paul. Podcasts are great too, something i look forwaqrd to each week. Worth noting the large buys on J D Wetherspoon (LON:JDW) by Tim this year. If anyone knows the business its him and having bought many more millions in shares I think its likely a safe bet.
In favour of the Spoons customer experience. J D Wetherspoon (LON:JDW)
In favour of the company:
I'm not sure about hotel expansion Paul, I think it's mainly a crafty use of excess space in some of their huge premises, and of course hotel guests will be pub users. I've not stayed in one of their rooms but think they've won awards before now - would it stack up standalone?
I don't hold J D Wetherspoon (LON:JDW) but have been know to hold a pint ....
They do pay a fair bit of tax, but I think describing contributing a bit less than 0.1% of total taxation (their claim) as "almost singlehandedly" is perhaps stretching it a bit?
I know this is a forum for serious debate but I think perhaps that you might have missed the light hearted tone of my commentary.
Blimey the description can only apply to Mrs Coates of BET365.Great knowing that tax has to be paid on my losing bets in contrast with the off shore merchants and boy does she contribute.True Brit and massive employer as well
I have spent much of my adult life being a 'professional' gambler. I was making very good money from poker for about 10 years and this allowed me the opportunity to save enough that I can now live fairly comfortably. I started around 2003 and was playing full time until about 2015. Over the years the poker games got gradually tougher, as the dumb money mainly fell away or got smarter. My personal income levels were dropping significantly and it all became a bit of a grind.
After poker, (as well as investing) I started taking sports betting quite seriously. I was using a lot of statistical models and I was focusing on specific types of betting (mainly smaller track horse races with 7 or less runners). Well as you can imagine, this is not an easy market to beat. The bookies have a spread on the prices, which makes it hard to find mispriced opportunities. Anyway, I had been betting on many online sites. Many of which I had a historical losing account with. After about a year (probably around break even) I finally worked out a profitable strategy, it was still at best a marginally winning system!
Unfortunately my system required me to place bets either the night before or very early in the morning (6am) - so Betfair exchange wouldn't be useable as there was either no market or no liquidity at these times. So I was using online betting sites.
Within one year of me betting, using only a marginally winning system - I had managed to get myself either barred or restricted at every online operator. Most of them took action within only a few winning bets. Some sites barred me when I had even lost money! I think it was Betfred that I placed 4 losing bets, then got an email saying they have closed my account. The reason they did this? Because they can see that a customer placing a bet at 6am at 8/1 must know something if the horse goes off at 5/1 at 3pm. So you don't need to even win, all they need to see is you're backing a shortening price. If they don't see any dumb bets on the account - they assume you're a 'sharp' bettor and take action immediately.
I have always been around gambling. Its something of a culture in its own right if you're in that world. I have known countless problem gamblers, many of which have been some of my closest friends. I know better than most the dangers of gambling addiction (I was myself an addict for many years before poker saved me). I also know how these gambling companies operate. And I wanted to share this with this community so people are under no illusions as to how the majority of the industry currently operates.
The old way was knowledge and skill - (Mr William Hill will be rolling in his grave if he saw how they operate today!). The old way use to be that a skilful knowledgeable bookmaker, who understands the sport and how to price outcomes, would produce a correctly balanced book. They may be happy to have additional exposure to certain outcomes - but basically they trust their own knowledge and pricing models. This means anyone can bet at the offered price, and prices can be adjusted accordingly - they wouldn't care if you were the worlds stupidest punter or the worlds best gambler. The book balances at certain odds and they understand their exposure levels at different price points.
The new way is far more profitable and requires no knowledge and no skill. It is a marketing based model with the objective being to get as many new sign-ups as possible. You then ban anyone with half a brain cell, and hard-sell to anyone who has an addiction (i.e. free bets etc). This model has proved much more profitable. Its an exploitative model aimed at problem gamblers. They have shown time and time again that they have no morals and couldn't care less about the wider impact on society.
Two of my closest friends have lost basically everything to Bet365 over the years. We are talking tens of thousands at the least. While they need to take responsibility for their addiction and behavioural tendencies, it is clear the predatory nature of some of these companies. When they were not betting, they were being harassed with emails and phone calls. Constantly being offered a free £50 bet on tonight's game. One of my friends returned from rehab to a £500 bonus on one of his accounts - its a mute point that he was at rehab (however ironic), but the fact that they would do this just because he hadn't bet for a few weeks says it all.
Also just to note. I have been outright banned from about 30% of online sites, the other 70% only restricted my account. So if I go on Bet365 the maximum I can bet on a horse race is about 5p! So why don't they bar me outright? Because they are hoping that one day, maybe after a few whisky's, I'll chose to use the casino offering - which is not restricted, and I'm more than welcome to lose my shirt.
The gambling industry claims only 1% of customers are problem gamblers. What they never tell you - is how much of the profit is made from this 1%. They count all sign ups as customers, regardless of the activity level on the account. So 1 problem gambler could easily generate more revenue than tens of thousands of other accounts combined. A customer who loses £1 million in a year is still only 1 customer, the same as someone who loses just £1 a year on the grand national. I think we can all agree that these customers are not the same. I have no data to support this thinking, but it is my belief that we would be shocked if we knew how much of the profit actually comes from this small but extremely active pool of accounts. Obviously the industry doesn't want to share this type of data.
So to sum up - It is my opinion that these companies are acting in a predatory way. The banning of, or the overly heavy restriction on winning players, seems not only unfair but contradicts their right to own a gaming licence, where they are suppose to be offering a fair and transparent product to all, without prejudice or discrimination - this behaviour is hidden from the unknowing public. By banning winning players, they go against everything that the smart and skilful bookmaker used to stand for. Now they just target problem gamblers or those that are intellectually vulnerable.
I have written to the gambling commission many times about this. At best I have only received a generic response about how regulations are always being reviewed. There is an argument that the gambling board is not fit for purpose. And that the gambling companies have all the power due to the size of these companies - and such things like political donations etc. So when I see Denise Coats annual earnings are now over £400 million - it does leave a bitter taste that she bans people like me for winning a very small amount of money. Yes she pays her taxes, and good on her for that. But she operates a pure greed model, that is unfair and also has no regard for the negative impacts she has on the wider society. Just my opinion of what I believe is a broken system that has done a lot more hurt within society that many other sectors that seem to get a worse wrap. So much so that most people are unaware that this is how the industry is operating.
There is a youtuber trying to shed light on these dark antics within the betting industry. Below is a link to one of his short videos explaining some of what I have discussed.
Apologies if this post was a little long.
BET365 EXPOSED - YouTube
What a great and insightful post ....fantastic !!
What a great and insightful post ....fantastic !!
Seconded. And that’s why gambling stocks are off-limits for me
Absolutely!
hi MetalMaid
I can confirm the accuracy of your excellent detailed post, written in clear detail and hence easily understood by those who are not familiar with the industry.
Following a lifetime of being a recreational losing punter on horseracing whilst being in full time employment and after taking voluntary redundancy over 20 years ago I became a successful and more disciplined punter earning a tidy supplement to my pension income.
In the early years I could get easily get my bets on (by phone or online) with plenty of established bookmakers. My annual turnover was around £250k (total bets). All my bets were placed either the night before racing or first thing next morning. I was able to cherry pick the best odds enabling me to have a margin in my favour by consistently beating the starting prices. Of course I had to put in many hours of studying races and replays to be able to form my own views to help me identify clearly mispriced horses.
In the past 10 years or so it became progressively harder to get bets on with bookmakers operating with increasingly tighter algorithms which enabled them to more easily identify people like me (and MetalMaid) from profiting from our strategy. This triggered account restrictions and closures.
I have had over 50 accounts closed or (more usually) heavily restricted. This includes accounts I subsequently began opening and operating in the name of friends and relatives (with their help and permission of course).
I have had 6 or 7 accounts closed by all of the major bookmakers and many other accounts with minor online firms. Nowadays I can only get a (modest) bet on with 2 bookmakers (but on their terms, not mine) so my turnover is now only around 5% what it was. I'm effectively a Persona Non Grata with UK bookmakers. I'd classify that as a restraint of trade.
Bet365 were the first to come down heavily with restrictions, probably because they always had the superior IT systems having been the first UK bookmaker to go 100% online.
As MetalMaid makes clear, bookmakers now only want to accomodate recreational punters, mugs and known heavy losers (whether addicted or not). They are leaches.
I have written to my MP about this but only received a bland response. At least I got it off my chest but I wouldn't expect there to be any political will to help winning punters get their bets on!
Finally, The Gambling Commission are currently proposing to introduce intrusive financial checks on punters which will likely have a major negative impact on the horseracing industry revenue. The Gambling Commission have just added some new appointments to their board (3 I think) but interestingly none of those 3 nor any of the existing members have any experience of the betting industry. God help the industry.
Rant over but thanks to MetalMaid for raising the awareness.
Snazzy
An all too familiar story unfortunately. Many thanks for sharing.
'I wouldn't expect there to be any political will to help winning punters get their bets on!'
Very well put, couldn't agree more!
This so resonates with me one fella I used to work with lost 400k through gambling, wife and kids knew nothing about it until the house was repossed he went from one of the nicest chaps you could meet to someone who would rob you for a fiver at the end.
My best friend lost over 100k contacted all the online gambling companies to say close my accounts and weeks later he was getting emails saying we have put 5k in your account come back.
The amount of lives ruined by this industry is huge it does get my goat that some sports personalities promote these sites when many of the fellas they used to play with have lost millions in some cases.
The difference with gambling with other addictions is generally it takes time to kill yourself from drink or drugs but with gambling you can ruin your life in weeks.
You could argue gambling addicts would always find ways to destroy themselves and thats probably true but having seen the tricks used to snare my best friend I have no doubt the industry is geared to milking the 1% of addicts for every single penny possible, awful industry.
It's really a sad state of affairs when we have an industry causing so much harm. I do think all the constant advertising, the very large amounts of markets / exotic bets being offered, along with constant free bonuses / promotions etc is not helping those that might have an addictive personality. And I am sure the industry understands this and targets these personality types.
Sorry to hear about your friend...many thanks for sharing.
That's a really interesting insight. I used to work with a person who made money betting on horses - he only used to bet on course, for tax reasons as I recall. Would that still be a viable means of making money from betting?
If you are able to gain further insights about the horses from being at the track via monitoring their behaviour then you can possibly gain an edge. However, for the average person this wouldn't be possible. It's really just those people that have spent their lives around race horses that can gain this type of edge.
The main problem with betting at the course is the odds you get are generally not as good as the odds on the betting exchanges. Many of the punters at the track will be using their phones and betting on Betfair exchange.
My strategy (and Snazzy also by the looks of it) relied on getting ones bets on early (often the night before). The track betting only starts later in the morning when most of the prices have already moved.
As I am not qualified I won't comment on the tax reasoning, but its possible that there could be beneficial reasons for dealing in cash and expensing costs.
Have just gone through the JDW hotel list and I stayed at nine JDW hotels. The rooms are generally good, but the rooms are variable in terms of size as each building is very different (often historic and listed) whereas a WTB Premier Inn is much more modern design and standard size. Have never heard any noise from the pub area, but as many are old buildings noise insulation and creaking floors can be an issue (Leighton Buzzard and Bewdley). I personally reckon the best hotel in Barrow in Furness is the Spoons. One selling point over WTB Premier Inn is I have found have similar lowest rate, but JDW can be cancelled FOC until day before, and you can pay on day as opposed to upfront (allowing better cash flow for me to trade). My gut feel is JDW won't become a significant hotel player, but as their average pub size has increased in size over the years, it's likely it will be a greater share of revenue for JDW in future. Not been a shareholder for years, but was in past, and JDW used to offer hotel perks for shareholders, think stay one night, get next night for free.
Not a shareholder in spoons but an enthusiastic regular frequenter with my pal where we discuss the market and use their WiFi to do so.
Only foray to their hotels is the one in Tewkesbury where the garden backs down to the river, not a good place to be in the flooding. Good experience, just upstairs from the pub and eatery. Old staircase and uneven floors and doors but a wonderful view over the Severn. Would certainly return
I stayed at the Spoons in Worcester a few weeks ago, the room was excellent, quite grand for the money, personally I couldn’t fault the customer experience. TBH I would look to stay at a Spoons before looking at Travel Lodge or Premier Inn.
I've stayed in one . it was pretty good - no complaints.
I just had to mystery shop one of my local 'spoons here in Bournemouth, after writing about it today, the "Moon in the Square".
Quick version - perfectly acceptable. Amazing fish n chips - probably the crispiest, best cooked fish I've had in ages, good sized portion too. Overcooked, tasteless peas though. And it only cost about £10.50, which included a pint of Stella. Free Wifi worked well.
Bad points? Totally indifferent staff, who didn't even pretend to give a s#it about anything or anybody. Still, at these prices, who really cares? Is it worth paying an extra fiver for a fake smile? No.
I could see myself even holding business meetings here in the afternoons, as the booths were plentiful and private.
An influx of children (well, more like toddlers) with their parents at about 16:00 spoiled the ambience a bit (I can't stand kids in pubs).
I popped into Revolution Bars (LON:RBG) on the way home - a howling wilderness as usual, despite doing permanently discounted Amstel for £2.99/pint. The staff are lovely there, but I can't help feeling the format doesn't have any appeal any more, other than for Saturday nights. Too much competition.
Regards, Paul.
I'm currently away with work and staying at the Dunfermline Wetherspoons - The Guildhall & Linen Exchange.
Can't fault it really and £3.32 for a large glass of plonk is helping me get over my portfolio performance of the last couple of years!
Eenergy (LON:EAAS)
As planetx points out in the comments below, how is the Luceco subscription not insider dealing, given that the market had not been informed that a possible disposal is at an advanced stage for (at last night’s value) double the group market cap?
Thanks for comments Paul, I think by definition a company and its officers are always inside and therefore a primary transaction can not be .... by making the announcement they free Luceco to acquire stock in the open market should they wish to, subject to panel rules. I may be wrong but whilst it looks odd it's obviously not insider dealing. A company can raise fresh equity at any level it wants subject to pre-emption rules if they apply.
Sure, the Directors of EAAS will always be insiders.
But I think the question about insider dealing is more that they must have disclosed to Luceco (LON:LUCE) about the possible £30m disposal. That's the inside information, and I agree with others here that the question should be asked why LUCE is allowed to buy new shares when presumably in possession of material inside information that had not been disclosed until today, alongside the deal with Luceco. It's not an accusation, just a question.
Re: EAAS and Luceco. Often there are placing with (positive or negative) trading updates or with regular results. The trading update will have been disclosed to the cornerstone investors in the placing (who will have been "wall-crossed") before the placing is publicly announced.
I can't see how this is inside information as Luceco has not bought shares on the open market but effectively from EAAS - who also has the same inside information. Now this information is out in the public domain, so the market has context about why Luceco agreed to pay a 25% premium to the last traded price. As the NOMAD (Strand Hanson) and the two joint-brokers (Canaccord and Turner Pope) have got their names on the bottom of the RNS - they will also be presumably content that all is above board.
Luceco paid a 25% premium for the shares. Presumably they were told about the approaches. Maybe Luceco (LON:LUCE) are confident of the disposal which will transform Eenergy (LON:EAAS)
Ok ... because it's not a market transaction and both the buyer and seller has the same info and agreed a price. The transaction was then disclosed with the information...and the market can decide the right level. It's possible Luceco (LON:LUCE) remain inside and can't buy or sell in the market... these transactions fall outside the domain of the rules. When pre-emption applies (full list) then the same terms have to be offered to all shareholders.
Secure Trust Bank (LON:STB) this really is one of the chepeast shares on the market. 65% discount to book value or 3x PE. It's not exactly junk either as share price would seem to imply - they are well capitalised and have been quite prudent in their lending, recently shifting more towards prime borrowers.
They are also quite strong in their particular niche of retail finance - I think they have a share of around 12% but think they can grow this to high teens as one of their biggest competitors pulls back from this market. Might be worth seeing today's capital market day for more details.
Re Reach (LON:RCH) The pension triennial review takes some of the unknown away (good) and the cost cutting is of course good too. The huge opportunity for Reach (and Future (LON:FUTR) ) however comes when Google Chrome removes third party cookie (tracking) in 8 months from now (to create a more private web). This makes profiling customers very difficult and will drive advertisers directly to publishers like Reach. A massive opportunity
Kromek Group (LON:KMK) there has been a lot of news lately (contract wins, a collaboration, refinancing completed) all assessed in update note out today. No change to outlook or FV, as you can read here: https://www.equitydevelopment....
Yes, a positive read - only thing I would flag is their FY2025 FV is 5 times the current share price so looks like plenty of upside. Balance sheet now looking OK - i.e. have enough cash. I am pondering topping up.
Equity Development - the thing with Kromek (LON:KMK) Is that they need to be self cash generating. Once this occurs then I agree they are likely to be worth multiples of the existing share price but the drag has been because they spend more on R&D than the cash flow coming from sales which means runway is still a consideration despite profitability.
When do they hit that inflection point?
I can see they become cash flow profitable this year which is a big step forward but does this include Capex as most of that will be capitalised rather than expensed. (Not unreasonably given the type of r&d but nonetheless means overall cash goes out of the business rather than in).
Paul, I can't help but totally agree on your comment on how the media gang up on Wetherspoon and Boohoo led it often seems by the BBC. It makes me wonder whether they see themselves as leading public opinion instead of reporting it. I don't trust what I see or hear either, it's sometimes a small step away from propaganda telling us what we should think or worry about. Sorry I'm almost stepping into political territory, hope you'll forgive me.
Twas ever thus? Consider
The bayeux tapestry (written by the french - arrow in the eye)
Roman histories (written by romans - wiser and better armies than the greeks or egyptians)
Cave paintings (look we got a bison! Outperfrom!)
The difference is that now it has become a lot less expensive to publish to an audience and regulation is lighter.
Flaviius josephus, the chronicler of the Judea-Roman wars, was the first propogandist we know of.
Another two and a half years before the crooks who defrauded investors in Patisserie Valerie are put on trial. What have the SFO been doing for the last 5 years! No doubt in the mean time these criminals will be spending the millions they made from selling share options at prices based on a fraudulent set of accounts. Just what is the SFO for?
Serving Fraudsters Only? for the benefit of the rich at the expense of the poor. Why else do we have these regulatory bodies in place?
yes, yes the coat on the way out
I seem to recall that the SFO has a poor record on bringing cases to court and securing convictions. They may still be found not guilty at the end of a very long process .For some reason the SEC in the US has more potency than the SFO and FCA in the UK.
The deck is stacked against the investors in the UK. It's surprising that the private investor makes any return at all on small companies.
Its also worth considering that they have only been charged and might be innocent (until proved guilty).
If the SFA have spent all this time persuing somone who can prove innocence - then a major overhaul of the SFO should be undertaken.
"That’s why I never believe anything I read in the media, and instead always check source documents myself, where possible, and listen to the opposing point of view too."
I completely agree. From an investment point of view I'd highly recommend anyone just starting to watch as little news as possible, and completely ignore things like CNBC. When you stop listening to worthless noise and focus only on what's important everything becomes so much easier and simplifies the whole process of decision making.
I don't totally agree with that Wolf. I used to spend a lot of time trying to work out the macro environment. It became clear that the time reward ratio was extremely poor. So I started watching Bloomberg. The idea being you get lots of senior investment professionals giving their view. Individual views are irrelevant but where there is concensus it can be extremely useful. But broadly I think we are in the same court.
I'd say consensus views are only useful if they're correct. Consensus view last Sept/Oct was US was heading for a recession. Didn't happen, market had a great rally. Hedge fund consensus was large short positions on S&P couple of weeks ago, S&P up 6% last week. UK media reached peak panic on pound v dollar on the day it bottomed.
This from last year just as the US market bottomed. If everyone thought a recession was coming and they acted on it whos left to sell. I'm more concerned now they're moving to a soft landing consensus.
CEO confidence was sky high as the market started to roll over in 2021.
I'm more concerned now they're moving to a soft landing consensus.
This has been the investor consensus for some time. More than 6 months stateside and in the case of my bank, since forever. The economic pre-conditions for a US recession are not in place with the employment market so tight. Only a shock (war, credit crunch, oil?) or more tightening by the Fed could bring it about. That’s why the Fed was jaw-boning yesterday to try to tighten conditions without acting on rates.
Sure but having tried to do macro for 35 years i know it is very difficult to get right. If you break the long term into lots of short terms the concensus doesn't have to be right but it does mean you are with the money, which after all is what a market IS. Right.
Indeed you are wise young Wolf.
Successful trader Jason Shapiro (featured in Market Wizards) says he's made a lot of money from watching CNBC by taking a contrarian view to what they are saying.
....which is presumably what Wazza The Great meant by his "close the doors" speech.
Hunting (LON:HTG)
Coverage initiated with current Fair Value seen at 421p/share
https://www.equitydevelopment.co.uk/research/connecting-market-position-and-clear-ambition-1
Marks and Spencer (LON:MKS) Not a small cap but got to like Shore Capital's headline on this morning's Interim's.
"H1 FY24 - 'Blown the bloody doors off!' More upgrades!'"
Have noticed what generally good value and decent design the men's clothing side is in the last season. Some good products also for winter wear, at decent prices.
I thought exactly the same thing when I was in last week. Then I felt the colour drain from me when I realised I am that old!
I think M&S clothing range has got a lot better and is probably looking better to younger shoppers as well guessing at 30+ would consider buying there now.
Have to admit I am back shopping at M&S - jeans are excellent! Also many other places now organise by brand rather than item - drives me nuts! Quality often better than other brands too. I'm old (ish)... but my youngest son seems to have the same opinion.
'Blown the bloody doors off!'
I am becoming increasingly annoyed by the way in which this phrase in misused. In the film The Italian Job a van and its contents are completely destroyed by an explosion, and Michael Caine says, "You're only supposed to blow the bloody doors off".
Thus, blowing the doors off would have been meeting expectations, not completely (and destructively) exceeding them. Yet people seem to think that the phrase means exceeding expectations.
John2 - The phrase "blow someone's doors off" originated in the 1950s in the United States, primarily in the context of car racing. In car racing, to "blow someone's doors off" means to pass another car with such speed and force that the other car's doors appear to have been blown off. (Langeek)
But the phrase 'blow the bloody doors off' originates in The Italian Job.
Strange then, John2 that you wrote "Thus, blowing the doors off would have been meeting expectations, not completely (and destructively) exceeding them. Yet people seem to think that the phrase means exceeding expectations."
Certainly not something to get annoyed about anyway John.
Hi john2,
Isn't it just that referring to the Italian Job phrase means something has been far more dramatic and impactful than instructed or planned?!
Given your becoming "increasingly annoyed" by this reference, I might switch to referencing the exploding sperm whale from Oregon in 1970. This fascinating article (with a video of the actual explosion) details what went wrong, when some miscalculations caused the authorities to use half a ton of dynamite, intended to destroy the whale carcass into small pieces that seagulls would clean up.
Instead, bystanders found large pieces of whale meat raining down on them, and a car was badly damaged a quarter of a mile away.
This gave rise to the spectacular alliterative headline -
"Blasted blubber beyond all believable bounds"!
We could maybe adapt this into something like -
You were only meant to blow the bloody blubber into bits on the beach?
Right, back to work, Naked Wines (LON:WINE) profit warning next I think.
Yes, but look at Marks and Spencer (LON:MKS) as reported in the media this morning. The starting headline in The Telegraph was nothing to do positive results and all to do with the increased Ocado (LON:OCDO) joint venture loss. They've moderated the reporting since to make it more reflective of the half year update.
Headlines headlines...
[I hold MKS]
Markets set to open weaker this morning on the back of renewed concerns from Minneapolis Fed President Neel Kashkari yesterday that the US might still raise interest rates - "Fed's job is NOT yet done."
That guy is a contrarian indicator - see this article from 2021 - he predicted zero rate increases through to end of 2023.
https://www.cnbc.com/2021/06/1...
That guy is a contrarian indicator - see this article from 2021 - he predicted zero rate increases through to end of 2023.
The Fed doesn’t want to raise rates any higher for fear of tipping the economy into recession. But they’re concerned that the very expectation that they will not, accompanied by falling bond yields that had tightened financial conditions by at least 50 bps, will loosen those constraints and re-heat the economy. Hence yesterday’s reprimand to investors from a Fed mouthpiece. Who uttered the reprimand is irrelevant - they simply pass the mic around to give everyone a moment in the sun.
What trumps (surely not!) everything is elections - surely with us and uk elections around the corner interest rates will be cut in time to please the masses. The only tricky thing is how the powers that be in the uk "make it so" if the boe are "meant to be independent" make it so they will.
surely with us and uk elections around the corner interest rates will be cut in time to please the masses
While that is my basic assumption also, the chances of the Fed bending to the will of the incumbent party are apparently not high and I understand there is little precedent, although no doubt statistics can be dragged up to support any argument. Intriguingly, the Fed stands to gain favour with an opposition who will gain electorally if rates are held high for longer and with the incumbents who gain if they cut sooner. In this way, the Fed collectively strengthen their hold on the levers of financial power whichever way they bend. The question that springs to mind is to what extent their individual political leanings sway monetary policy and how much is driven by their desire to stay in post. Powell is a Trump appointee it should be recalled.
For what it’s worth I’m not sure that rates should be cut before it is too late for Biden, ie Q3.
Luceco (LON:LUCE) invests £1.75m in Eenergy (LON:EAAS) at 25% premium.
Furthermore, potential disposal of Energy Management Division for approx £30m+ leaving Eenergy (LON:EAAS) to focus on Energy Services.
https://www.investegate.co.uk/...
E energy and Luceco
That stinks a bit .
First part of announcement
Luceco effectively acquires 9% of the company for circa 5p a share
Second part
Luceco in advanced talks to divest part of its business for 30 million , twice its market cap .
Seems to be a staggering bit of insider trading with Luceco in possession of information not on the market .
At least dick Turpin used to wear a mask .
Nuts
Typo Eenergy in advanced talks to sell its division for twice market cap
Re E energy and Luceco planetx, we hold Luceco and I wondered if it not only cemented the relationship, it ensured payment for goods already supplied, no figures given but it is mentioned as coming out of the investment figure.
I’m sure it’s the correct move for both Luceco and e energy
But I think the correct way to do it is
- release an RNS to the market letting it know they are in due diligence to sell the non core division for 30 milllion
- let the market absorb this
- only after this can Luceco take its chance to buy 10% of the company
Just out of interest why aren't Eenergy (LON:EAAS) up more ?
Stocko states that Eenergy has 3 employees. What does that mean to this layman?
My morning smallcap tweet: May the farce be with you
Versarien (LON:VRS) Seeing Machines (LON:SEE) Reach (LON:RCH) Smiths News (LON:SNWS), Secure Trust Bank (LON:STB), First Property (LON:FPO), Time Out (LON:TMO)
◄Versarien (VRS)► slippery supercrock makes £455k placing at 0.275p, a 47% discount, to keep the lights on. [SP=0.55 Cap=2m]
◄Seeing Machines (SEE)► $15m contract to deliver an additional automotive program for an "existing European automotive manufacturer". Glad to know the customer is real. Those made-up ones just don't pay up. Starts 2026. [SP=5.74 Cap=239m]
◄Reach (RCH)► plans 5-6% cost cuts in 2024, cutting 450 jobs. [SP=77.88 Cap=248m]. I hold.
◄Smiths News (SNWS)► FY-Aug 'ahead of expectations', but only slightly. Adj op profit £38.8m vs £38.3m guided. Adj EPS 10.8p vs f/c 10.3p (Stockopedia). Outlook in line. [SP=48.17 Cap=119m]. I hold.
In line: STB, FPO, TMO
Wonderful, Mr C. "May the farce be with you" and "slippery supercrock" are award winning.
I'm looking forward to Mr C using the phrase "May the farce be with you" next year on Star Wars day... 4th May 2024!!!
As a personal challenge, I never reuse titles!