Small Cap Value Report (Weds 9 Nov 2022) - PURP, VLX, GYM, NMRP, SNWS

Good morning from Paul & Graham!
Today's report is now finished. I got halfway through Norcros (LON:NXR) so will finish that off this afternoon & put it in tomorrow's report first thing.
Agenda
Paul's Section:
MADE.com - As a post script, ThisIsMoney reports that, as expected, Next (LON:NXT) has bought the brand & intellectual property of this failed online furniture retailer - which went from a well-financed IPO in June 2021, to insolvency in Nov 2022 - astonishing. The price paid is a paltry £3.5m. The article says that inventories are likely to be disposed of via TK Maxx, the dicount branded retailer, so it might be worth a visit to see if there are any bargains on offer.
Volex (LON:VLX) - Interim results look good to me, given tough macro conditions. I have a good dig into the numbers, including balance sheet and cashflows, and overall it looks pretty good to me. Shares seem reasonably-priced, and overall I give this a thumbs up.
Smiths News (LON:SNWS) - encouraging results, ahead of expectations, for FY 8/2022. Legacy problems are now resolved, and what remains is now a reliable cash generative, largely de-geared business. The remarkable divi yield of c.11% looks sustainable in the medium term too, as finance charges should fall sharply. Long-term, who knows? As a high yielding value share, I can't help but give this a thumbs up! Whilst being a bit wary about the longer term uncertainty.
Graham's Section:
Purplebricks (LON:PURP) (£35m) - shareholder anger over the long-term Chairman’s position has bubbled over and resulted in a requisition for a General Meeting. I agree with the shareholder that the Chairman has failed and needs to go, to take responsibility for many unwise ventures and the incineration of vast amounts of shareholder cash. Unfortunately, it looks like the shareholder might struggle to get the necessary votes needed to get this done. Purplebricks is an interesting special situation where net cash and speculatively some brand value might help to support the valuation. However, its efforts to stop losing cash are probably about to run into lower property prices and reluctant home buyers, which I expect will make the job much more difficult.
GYM (LON:GYM) (£196m) - a disappointing update from this gym operator as the WFH trend has prevented it from reaching pre-Covid levels of performance at some of its mature sites, as it originally hoped to do. Other sites, not dependent on workers, are at 93% of pre-Covid levels. Unfortunately, the recovery has been slower than I hoped to see play out. Additionally, rising energy costs are set to increase costs by up to £10m next year. I’m starting to wonder if the company’s existing expansion plans might be too aggressive, given the changed circumstances.
National Milk Records (OFEX:NMRP) (£25m) (unchanged) [no section below] - this “agri-tech information services provider” issues a Q1 update (for the three months to September). Note as always that this stock is listed on Aquis, not on AIM or the Main Market. Q1 revenues are up 4.4%, with Johne’s disease tests doing slightly better than the other primary revenue streams. Q2 will see “a major engagement with milk processors and vets to underpin the detrimental role that this wasting disease has on animal health, milk production and sustainability.” Elsewhere, genomics testing revenue is still in its infancy but could prove to be an important new source of profitability. I retain my positive view on this share.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Paul's Section:
Volex (LON:VLX)
273p (yesterday’s close)
Market cap £434m
Volex plc ("Volex", the "Company", or the "Group"), the global supplier of integrated manufacturing services and power products, today announces its half year results for the 26 weeks ended 2 October 2022 ("H1 FY2023").
So this is H1, in FY 3/2023.
The headline numbers look good to me (it reports in US dollars) -
Revenue $357.5m (up 22.1% - of which 14.3% is organic, the balance from acquisitions)
Underlying profit before tax (PBT) $29.1m (up 14.1%) - that’s an 8.1% profit margin, which strikes me as fairly decent, in tough economic conditions (down from 8.7% H1 LY).
Statutory PBT $21.5m is 26% lower than underlying PBT. Given that gap, I’ll need to check out the adjustments, and make sure I’m happy with them (see below)
Underlying EPS is 14.4c (up 4.3%)
Acquisitions are progressing well - remember that VLX has a strategy to grow through acquisitions of complementary businesses in various geographies & niches, that enhance its overall offering.
Target is $1.2bn revenues by FY 3/2027 (currently running at almost $700m annualised).
Net bank debt has risen a lot, due to acquisitions, it’s now $98.8m (LY: $22.3m)
“Robust customer demand”
Interim dividend of 1.3p (H1 LY: 1.2p). Note that, in the last 3 years, the final divi has been exactly double the interim divi, which implies 3.9p this year for total divis, a low yield of 1.5%, so it’s a growth share, rather than an income share.
Demonstrated ability to pass on cost increases to customers - very important.
Gross margin is low, at 20.6%, so keeping overheads lean is of paramount importance, which Volex seems to manage, with an underlying operating profit margin of 9.0%.
Adjustments to profit - underlying PBT is $29.1m, whereas statutory PBT is $21.5m, quite a big difference of $7.6m costs. These are -
$4.3m Amortisation of acquired intangibles (i.e. goodwill amortisation) - that's fine, it customary to strip out this bookkeeping entry.
$0.7m Acquisition costs - again, this is a fairly normal deduction, as it's not an underlying trading cost, more one-offs on acquiring other companies.
$2.6m Share-based payments charge - same as H1 LY. This is more questionable, as it's part of management remuneration, so there's an argument for adjusting this back in again as a regular cost.
Webinar - is today at 14:00, on InvestorMeetCompany, with Q&A. Well done to the company for doing these, all companies should do results webinars for private investors, no excuses!
Markets - as mentioned before here, Volex seems to operate in generally attractive, growing markets, which is reinforced today with these comments -

Outlook - trading in line -

As you can see below, broker consensus earnings expectations have been trimmed a bit over the summer, but have been edging up a little in recent months, which I like to see - it’s good to have this graph moving about a bit, as it suggests to me that the company is probably communicating with brokers, and steering them in the right direction, which reduces the likelihood of an obligatory 30% plunge on a profit warning -

.
In unpredictable times, we need to pay much more attention to how market expectations are being managed, and that’s a good question to ask management on webinars - e.g. how closely does the FD work with brokers, to keep market expectations accurate? Do you leave a margin of safety in forecasts, to mop up anything unexpected?
Balance sheet - NAV is $200.9m, but of that $75.3m is goodwill from acquisitions, and $41.2m is “other intangible assets”. I always write these off, which brings NTAV down to $84.4m, which still looks reasonable for the size of business. There’s always a risk with acquisitive groups that they end up hollowing out the balance sheet, and taking on too much debt, but that doesn’t seem to be the case here. Note that the balance sheet has taken a forex hit (which by-passes the P&L) of $19.4m - shown in the "unaudited consolidated statement of comprehensive income" - this is a statement that most investors & analysts ignore, but it's there to enable us to reconcile the movements on the balance sheet, with net profit (which should be the same once these non P&L items are taken into account).
Working capital looks healthy, with current assets (incl. $23m cash) of $307m - note that inventories & receivables are both rising, as I would expect in inflationary times. Plus these will also reflect acquisitions made. Current liabilities are much smaller, at $172.4m, giving a current ratio of 1.78 which looks good to me. For this type of business, I like to see a current ratio upwards of about 1.3, so 1.78 passes my test by a generous amount.
Non-current liabilities is where the bank debt sits, at $115.9m, which is getting towards the upper level of what I’m comfortable with.
Net bank debt is $94.4m (cash of $23m, less gross bank debt of $117.4m) - a little high, but well within the bank facility limit.
Acquisitions - 10 have been done in 4 years, totaling $200m, and the section on this in the commentary I think rightly claims to have a proven, methodical approach.
We have an interesting acquisition pipeline containing highly attractive targets that we are pursuing, all of which fit within the core competency of our senior operations team. We qualify every acquisition extensively using our deep industry knowledge to find the best opportunities. We firmly believe that our strength in this area will be a significant value driver.
There is a potential issue of dilution - given that bank debt is looking a bit high now, then I would prefer future acquisitions to be funded at least partly from fresh equity. Although with the share price low, this is not a good time to be issuing new shares. The boos, Nat Rothschild, will be more aware of this than anyone else, as he owns 25% of the company. So shareholders can rest assured that interests are aligned.
Cashflow Statement - cash generation was good, but a fair bit $22.2m was sucked into additional working capital - as I would expect in a time of higher inflation. Both inventories and receivables go up, but trade payables also rising only offset just under half. Nothing to worry about, that’s just what happens when businesses grow, and in times of higher inflation.
After capex, payments for acquisitions, and divis (small), there was a cash outflow, financed from increased bank borrowings.
Going concern statement - is short, and fine. Points out that there is $82.3m headroom available under the existing bank facility.
Broker updates - nothing has come through yet, but Singers usually update us.
EDIT: an update has just come through from Singers, many thanks for that. It looks to have slightly decreased FY 3/2023 adj EPS from 26.4c below, to 26.2c, not significant. End of edit.
Its last forecast will do, as we’re told today that expectations are in line for the full year.
That indicated $690m revenues, and adj EPS of 26.4c, or c.23p in sterling, for FY 3/2023.
The share price is currently 268p, so that’s a FY 3/2023 PER of 11.7 - that strikes me as an attractive price. Although net bank debt is about 19% of the current market cap, so if you adjust for that, then the PER on a cash/debt free basis would be something nearer to 14 (roughly), which is still a fairly reasonable valuation I believe. Not amazingly cheap, but fairly decent.
My opinion - I’ve admired the big turnaround at Volex executed by Nat Rothschild, and the thoughtful acquisition strategy seems to be working well. Today’s results look solid to me, given the challenging macro environment. In particular, the proven ability to pass on cost increases, is a key point in favour of these shares.
Why has the share price dipped 2% this morning? Who knows, it did rise strongly yesterday, and I don’t tend to read much, if anything, into short term share price movements when a company reports trading in line with expectations.
Is this a good long-term investment, is really the key focus we have here at the SCVR? Based on the good track record in recent years, the solid H1 figures today, and a robust outlook statement, and a reasonable valuation, my view is that yes, it looks good. So a thumbs up from me, for a decent company, on a reasonable valuation at 267p per share.
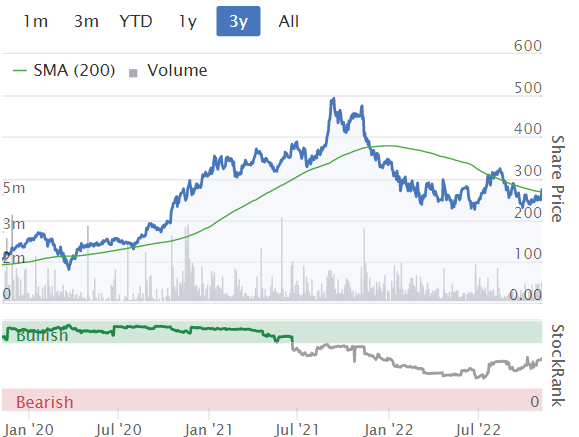
As you can see from the chart below, it's been a wild ride in the last year, reaching an overvaluation (as with so many other shares) a year ago, but now having de-rated to something a lot more palatable.
Smiths News (LON:SNWS)
38.3p (down 1% at 11:20)
Market cap £92m
Audited Financial Results for the 52 weeks ended 27 August 2022
Performance ahead of expectations with material debt reduction and increased dividend
We’ve covered this value share extensively here in the SCVRs in recent years, with a very convincing turnaround having been executed.
Figures today look good, with EPS flat vs LY at 10.8p, putting this share on a tiny PER of only 3.5
Bank net debt has been almost wiped out now, from some expected one-off cash receipts, and the reliable cashflows of the core business, down to only £14.2m (down 73% in a year). Hence bank net debt should now be seen as almost insignificant.
Pension schemes have now been sorted, with SNWS even receiving a cash surplus, as planned. So I think that issue is now permanently resolved.
As a result, finance costs on the P&L should reduce in future years, meaning profit could go up.
Outlook comments reassure -
The new financial year has started well. Trading to date is in line with expectations, and in October 2022, contracts representing 35% of newspaper and magazine sales revenues, were renewed until 2029. Despite recent economic volatility, inflationary pressures continue to be consistent with planning assumptions and the combination of sustained margin mix and close cost control give us confidence in maintaining performance in FY2023.
Balance sheet - is still in a net liabilities position, so NAV is £(32.0)m, but I don’t think that matters, because the business is decently cash generative.
Dividends - this is the most interesting bit. Total divis for the year are 4.15p, giving a yield of 10.8%! That yield could conceivably rise further, because the problems have now been sorted (debt, and pension scheme).
My opinion - the turnaround here has panned out exactly as management guided, when I started focusing on this share a few years ago. It’s not often that happens!
Given that it’s trading well, has fixed the main problems, and is paying out huge divis, why are the shares still so cheap? It’s because the market sees this as a dying business, given that it’s distributing newspapers & magazines, through a rapid overnight system, with mainly outsourced logistics. However, cover price rises have offset a lot of the volume decline, and SNWS revenues are based on volume x price, thus making its revenue declines much slower than people might have imagined.
The wild card, is that some bright spark might dream up some additional use for this high speed delivery network, to transform it into a growth business, instead of a dying legacy business. Imagine what the re-rating could be like, were that to happen? Previous management tried this, with the Tuffnells acquisition, but it was a disaster. So new management are understandably reluctant to try out any new ideas. Maybe an acquirer might bid for it, if they come up with a new strategy?
Overall, and despite the sharp recovery in share price recently, I think this share remains a very attractive value share. Especially for income seekers, with that c.11% yield, which looks sustainable in the medium term anyway. Longer-term, who knows, that could be tricky.
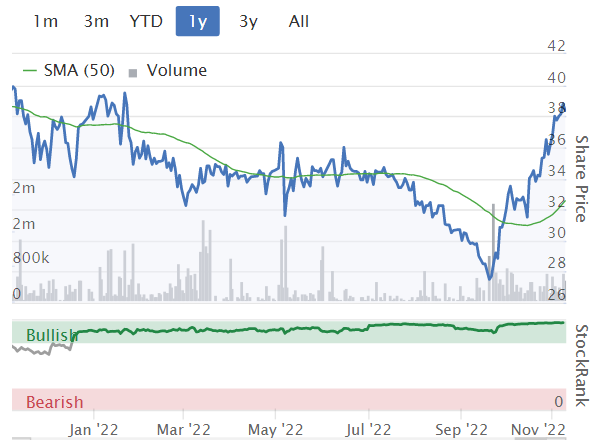
The StockRank has been consistently very positive about this share (as have I!) over the last 3 years -
Graham’s Section:
Purplebricks (LON:PURP)
Share price: 11.55p (pre-market)
Market cap: £35m
It’s not every day that you get a requisition of general meeting: a disgruntled Purplebricks shareholder is looking for change at the top of the company.
The shareholder is Lecram Holdings, controlled by Adam C Smith:

The first RNS relating to Lecram Holdings and Purplebricks was published on 11 July 2022, notifying that Lecram had a 4.18% stake in the company. By October, this was revealed to have increased to 5.0%.
Over on Lecram’s website, there is a letter to the Purplebricks Chairman dated 4th July 2022, stating that they owned 2.98% at that time. I wonder when they bought their shares - hopefully not anywhere near the peak!

In their July letter, Lecram’s investment banker states the following to Purplebricks Chairman Paul Pindar:
Following the destruction of shareholder value evidenced by decline in the share price from 489p in 2017 to around 15p today, we believe that urgent action is now essential to stabilise the Company and restore its credibility within the investment community.
As Chairman you have presided over this highly unsatisfactory performance and you should now stand aside in favour of a replacement with necessary experience and skills to address urgently the Company’s continuing cash burn and operating performance within the residential estate agency sector.
In August, Lecram went public with their criticism.
Yesterday, they sent a new letter, this time to all Purplebricks shareholders. It's less than three pages long and is a very quick read.
The argument in simple terms is that Purplebricks has wasted most of the cash it has raised on multiple bad decisions, has seen its share price fall by 89% since its 2015 IPO, and yet is still overseen by the same Chairman, despite having had four CEOs and five CFOs during this time.
Excerpt:
Paul Pindar has thus far chosen to dismiss these concerns by remaining in post and has, therefore, prompted me to call a general meeting… I regret the short-term disruption this may cause and, rest assured, have engaged extensively with Mr Pindar in order to avoid this course of action. We have also been encouraged by other frustrated shareholders over this period.
In the place of Paul Pindar, they would like to see the appointment of Harry Hill (former CEO of Countrywide and former Chairman of Rightmove, in which I have a long position).
Response by Purplebricks: Purplebricks are “reviewing the legal validity of the Requisition”, which is standard. If there has been any procedural mistake on behalf of Lecram, they will certainly deny the request.
As for the position of their Chairman, they say:
The Board reaffirms its support for Paul Pindar as a director of the Company and Chairman of the Board and believes that Paul has the continued support of a number of major shareholders. This includes Axel Springer SE, a 26.5% shareholder in the Company, which has confirmed it remains supportive of Paul and intends to vote against the proposed resolution for his removal as a director of the Company.
As regards to Purplebricks turning itself around, they say that their FY 2022 results included a clear plan “to improve business performance, return to positive cash flow and profitability, and build a scalable business model”, and they point to the recent addition of new NEDs and a CFO as having bolstered the Board’s capabilities.
My view
Firstly, I of course agree with Lecram that Paul Pindar’s position is untenable. If you have been running a listed business for seven years and the share price is down by 90% over that time, then you have failed. Simple as that.
Secondly, I agree with Lecram that there are likely to be more qualified candidates for the job, including their preferred candidate. Mr. Pindar has had an incredible career but it’s not a real estate or estate agency career. It looks like it’s time to bring in a specialist.
Unfortunately, being right does not mean that you get your way. Lecram’s ownership stake is big enough to call a general meeting, but it’s much smaller than Axel Springer’s stake and is not even as large as Mr. Pindar’s (who has recently been buying Purplebricks shares, perhaps because he doesn’t want to own fewer shares than Lecram?).
At the end of the day, Lecram/Adam C Smith can have all of the facts and the logic in the world on their side, but it won’t count for anything unless they convince fellow shareholders.
In normal circumstances, I would expect a Chairman who presided over failure for seven years to voluntarily step down. One of the major reasons to do this is precisely to avoid confrontations with angry shareholders. But Mr. Pindar must somehow have convinced major shareholders that the company’s disastrous expansion efforts were not his fault.
Axel Springer were joint venture partners with Purplebricks in Germany, so they clearly bought into the expansionary vision.
With Axel Springer’s support, my best guess is that Mr. Pindar will get to keep the role of Chairman. I could be wrong about that, but it’s difficult to beat a 26% shareholder in a vote!
As for the merits of Purplebricks shares at this level, the £43m cash pile (as of April 2022), plus some brand value, suggest that there is a level at which it is “cheap”.
However, the company did burn through £20m of cash in its operating and investing activities last year (before movements in working capital, which were an additional £15m outflow).
It said that it was looking to cut £13m of annual costs, and that would certainly help, but it also now faces the challenge of higher interest rates and a weaker housing market. It’s entering this difficult economic period from a position of severe weakness, not of strength. And this is a company that has never demonstrated consistent profitability.
Therefore, from my perspective, these shares should be trading at a very big discount to net cash. Anything more than that relies either on a turnaround or on another company finding value in the brand and taking it over. Recent reviews on Trustpilot are hit-and-miss and their competitor’s reviews are better. So I’m not sure if the brand is ultimately going to be worth much. As a consequence, while I accept that a turnaround is possible, my personal view is that Purplebricks shares are to be avoided.
GYM (LON:GYM)
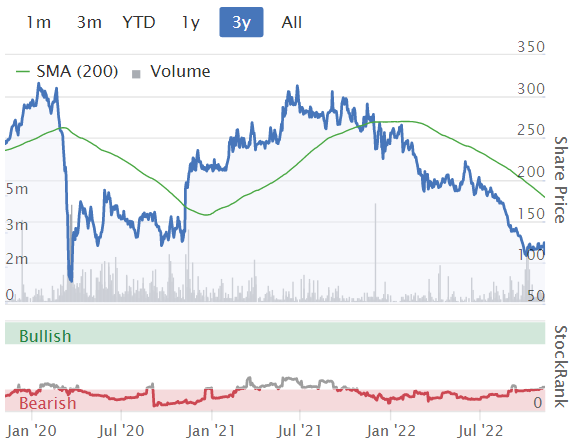
110p (down 11% at 09:59)
Market cap £196m
This low-cost gym operator issues an update for the first four months of H2. Unfortunately, the company’s hopes to reach 2019 like-for-like performance has not yet materialised, and it may not be able to do so at some of its sites. Revenues at the “majority” of its sites are now at 93% of pre-Covid levels. However, there are 16 sites (out of a total of 224) where “changes in working practices”, i.e. more people working from home, have impacted performance. They still plan to open 25-30 new sites next year. Non-property net debt stands at £68.5m, up by over £10m since the end of June, although the company says that it had “tight cost control, leading to strong margins and cash flow in the period”.
Looking ahead, utility costs are expected to rise £8m-10m in 2023. New sites are performing in line with expectations and total membership numbers are up 16.7% year-to-date. This company was very badly hurt by Covid and I think we do have to make an allowance that a full recovery will take some more time. Unfortunately, the rising energy costs are an additional headwind although it could be argued that a low-cost gym operator should find it easier to keep winning market share in this environment. And the balance sheet could be stronger, even though Gym has already raised over £70m in fresh equity in the last two years. Would it make sense perhaps to put the brakes on the expansion, to enable some internally generated cash flow to pay the bills for the next year or two?
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

70 comments
I do wonder where all these Bitcoin gurus are now.
In the beginning it was the new currency , then when they realised this couldn’t sell anymore , they went for the story that Bitcoin was better than gold ( yeah keep on dreaming ) and finally they went for the inflation hedge , then as inflation was rising and bond yields flying and Bitcoin falling they lost the game completely and couldn’t think of anything else.
You do have to feel for the people that believed all these stories as all these cryptocurrencies will end up worthless at some point in the near future.
Can anyone explain how Stockopedia calculates the %gain column in Folios? I have set valuation to use Bid prices "for realistic vakuations" because "last price, for consistent valuations" seems absurd when the last proce may be at Bid, Offer or somewhere within or outside the spread.
Even so, the % change on the day looks more like the difference between the closing Mid Price and either the Bid or Mid price currently.
Anyone worked it out or found an explanation?
FWIW I too use ‘bid’ price for valuation and have asked more than once for it to be used throughout the folio figures for consistency. No response from Stocko to date.
Just got an email from Fulham Shore (LON:FUL) re the expected launch of Franco Manca cook at home pizzas. They're in Tesco, so who's going to be the first SCVR reader to mystery cook them?!
Here it is in Tesco. £4.50, with a Clubcard, sounds a bit steep. £5.75 without a clubcard!!
It's not clear what diameter the pizzas are, but 480g suggests it's a reasonable size. I just compared with a Co-Op frozen pizza in my freezer that's 300g, and costs £1.15.
There's only one customer review so far, which is 5 star, saying "Great quality pizza!"
There's one thing for sure Paul, if it' a cook at home pizza it will resemble nothing like that picture!
I like what Fulham Shore (LON:FUL) are doing. Great management and a good company to come out of the recession doing well. Waiting to jump in at some point.
Re GYM (LON:GYM) - I respectfully disagree with Graham. I hold and I think now is exactly the moment for an aggressive expansion strategy. This is despite LFL on mature sites being index 93 vs 2019 (so closer to 85 after inflation!) AND 13 inner city sites which have not recovered even well due to WFH/changing work habits (which will no doubt lead to big write downs/provisions at year end) and utility prices forecast to go up £5-10Mn next year.
That's because
i) their GM is so big that even a 5% price increase (achieved this year) will recover the utility on cost
ii) personally, I think they will find to control it to the lower £5Mn - energy efficiency, on site solar
iii) they still have space to price up as lowest cost provider in the low cost segment (they claim 10% cheaper vs PureGym in comparable locations) and can afford through Tech and Marketing budget to keep promoting
iv) the non-low cost segment will hurt really badly. Premium gym users will trade down as posh gyms close their expensive pools or have to price up big time,; many local authority gyms are going to have to close
v) A low cost gym membership is actually a cheap form of entertainment. Go 4 times/month and you have an OOH activity for £5/time. Cinema/pub/meal out will cost much more and no sense of self improvement.
vi) Most crucially of all, over the next 12-124 months will be a great time to do deals on property. Growing at 20-25/yr is what they have done before and can be tweaked if needed if recovery a bit slow)
The Gym Group are going to emerge, with Pure Gym in a very profitable duopoly in a big market where they have all the best sites in town - like the Supermarkets in the old days. High St regeneration is going to put them in High Streets as well as top retail parks. Their investment in tech means theirs Apps and value adds create a big moat vs smaller players.
If they wait 2- 3 years for better times, the development pipeline will mean it is will be too late for the best deals.
My only gripe is the re-branding which was required, has some good parts (the g logo, optimised for searching) but remains too generic and corporate - who will ever say they are to The Gym Group
But hey raised more money via a placings at 150p (£41Mn, Apr '20 Covid scre) and 275p ( £31M, July '21, recover). I can now buy at 108p (post Truss, cost of living crisis.
We all focus on stories we believe in. I believe in a future for low cost Gyms, see The Gym Group a long term winner and will wait patiently for 3-5 years for it to come good.
Sureserve
Has dropped down significantly despite rising market .
Has a similar shareholder base to Crestchic and looks like one of the funds is selling down causing downward pressure .
I think these small cap funds are being forced to raise cash to meet liquidity requirements , this means the “larger” small caps where they actually have the ability to sell are de-facto choices .
Zero to do with company fundamentals and to do with liquidity and regulatory requirements I think is throwing up sone decent buys .
Keep an eye on the size of the trades,.
Interestingly another Harwood share .
If this dips into the 60s looks a great entry point .
Thanks Planet that's a great shout.
Level 2 has the big boys sat at 70,69,68 with buy orders. It seems very good value at that level IMHO, so I'm buying an opener.
Margins are a slight worry and of course Stocko has it expensive on P/E I assume because its linked in with Construction, which is perhaps a tad unfair. No Divi's, but again decent growth projections for the next two years, so SP upside from here I would suspect.
A sort of mini Minsky moment?
Paul following up on your Report on Smiths News (LON:SNWS) today I just listened to the Investor Meet Podcast with the CEO and CFO which was excellent. I hold and the Dividend of 10% is very welcome and looks sustainable. The part I found most interesting was the new initiatives to enhance revenue which the Company has launched in the last year or two.
For Subscribers with access to Investor Meet the Podcast, just 40 minutes, is well worth a listen.
Thanks portugull! I'll check it out later.
Is there a running joke here, which I'm unaware of, where people deliberately re-name the website Investor Meet Company?! ;-)
Best wishes, Paul.
Podcast Meets Investor is good, tho do prefer World of Pi
Yes totally agree - a very useful presentation by a mgt team who are very focussed and aware of past pitfalls and the need to steward the cash cow core business whilst looking for complimentary new profit streams. My second largest holding.
LON:JDW. Just noticed an update from Spoons. Sales pretty flat and is closing 10 sites. Shares down 7%. Love it or hate it (I'm a bit of a fan having paid £6:39 for 3 decent pints in Nottingham this weekend) this is a well run business that should do well in a down turn. Debt is an issue but I view the above news as sensible in the environment.
For me this has parallels with Greggs several years back where they closed some underperforming outlets and had flat sales. I've since multi-bagged on Greggs and am beginning to wonder if Spoons isn't worth an investment. The downside seems to be written in. Disclosure - I don't hold.
Hi Berksbee,
I've been meaning to look at J D Wetherspoon (LON:JDW) for a while. I saw today it has cashed in some interest rate swaps for a large profit, but it looks getting close to desperate, in terms of the debt, and rather thin NTAV on the balance sheet, at a time when the freeholds are probably dropping in value.
I'll come back to it in more detail when time permits.
I'm busy currently, fixing up hopefully 2 new CEO interviews for this Friday.
Regards, Paul.
Gym's not looking good, what's the chances of a placing? unless they raise their pricing suspect 2023 profits wiped out? big loss this year as well potentially
Someone on here will have a much better in-depth view on the wholesale energy market than me so I'd welcome any corrections but slightly off topic I have been looking at prices and think there should be a significant deflationary effect coming down the pipe quite soon. Plus the infamous £50-£100bn borrowing by the government to cap energy prices looks to actually be zero (possibly positive to the chancellor).
Wholesale electricity in the UK is now back around 9p (8-13p during the day) at spot pricing. That's almost the historic norm of the last decade. Spot gas is still much higher but at $285 p/m/t is almost half the expected rates back in the summer. The Govt guarantee assumed prices of $600 with a b/e of $300 vs spot pricing so it shouldn't be spending anything on the guarantee.
So a few things jump out to me intuitively.
1) The energy cap should start rapidly coming down and fixed rate deals back on the market anytime in the next 3-6 months helping consumer finances/certainty considerably
2) The plugging of £50-60bn on govt finances is likely going to prove to be over austere - I wonder if that is deliberate to allow the Chancellor to cut taxes in a sweeping popularity contest 12 months before the next election (time to take effect)
3) Interest rates will not rise much further - 2Y is saying 3.27% and 10Y 3.54% which means although the housing market is a bit dislocated right now mortgages will get freed up quite quickly again at reasonable rates.
Also looking at freight costs, copper, steel, lumber, cotton are all down circa 25-30% YoY so that must be feeding through to input prices soon. Main detractors are foods - oats, rice, mil, cheese all 20% up with wheat flat YoY.
Yet all we hear in the media is doom, gloom, woe and fear, which may be the case right now but the forward pricing picture doesn't look quite so bleak to me.
Hi David,
You sound like me. I quite often surprise friends with a rosier picture that that which is painted - I like to think that some of these opinions are backed by at least some facts! I am not saying we are without our challenges but news of the UKs death is exaggerated.
I agree on your basic premise that next year will be better than people think (optimism bias?).
There are several major deflationary forces in operation now, led by energy/commodities/ shipping. Some settlement/stalemate in the war in Ukraine is also possible as both sides run short of ammo and energy. (Only the big geo-political risk of say China invading Taiwan or a nuclear bomb in Ukraine obviously goes the other way ).
On energy in particular, it looks as if Europe is ready to cope with this winter (the UK, as ever, has done less to prepare) with gas stocks high, energy saving policies in place and a dash to alternatives underway (extending nuclear plants, accelerating renewables, etc). If they get to spring, they have another summer to make another leap in capability. If Europe do this well, then the price of energy in the common european energy market will stay lower than feared.
In the UK, I suspect the new Govt will be more economically rationale than the last 2 administrations and put an energy efficiency / demand mgt strategy in place eg the National Grid/energy suppliers ready to support differential pricing by day part, tax payer giveaways on 'green home' and green business' investments.
High energy prices this winter will focus minds on basics like loft insulation and rooftop solar (Indicatively, in companies I follow, £MSHL capital day presentation said 70% of Scottish new build had solar built into new builds vs only 10% in England!, Headlam (LON:HEAD) like many companies is investing in solar arrays on warehouse roofs). Only where political calculation intrudes on common sense (like cancelling plans to stop inhibiting cheap, rapid, onshore wind generation and being beastly to Europe) will this not apply. So much could be done quite quickly leaving a much smaller core of homes/businesses requiring targetted not expensive, broadscale help).
Net, whilst things may get worse before they get better (Nov statement, tough Christmas retail sales, hospitality closures in Q1), the bottom should be in sight. Here's hoping !
Cornwall Insight are still projecting high energy cap prices (note Q123 is Q1 2023) before Govt subsidy:
Also fixed rate deals are currently effectively blocked by Ofgem's Market Stabilisation Charge (a mechanism that the fixed rate provider has to compensate the existing provider - I think the compensation is set at 85% of the saving) which is due to expire by 31 March 2023, but I expect it will be extended. There is a Consultative Document and I expect the energy suppliers will argue we need stability and lobby a continuation of Market Stabilisation Charge that reduces competition.
40% uk windpower production!
Volex (LON:VLX) talk a good game but don't generate cash. Revenues grow faster than EBITDA, that grows faster than PBT, which grows faster than EPS
The reason they don't generate cash is contingent consideration which they don't include in the net debt.
Never been a CFO myself but to exclude lease repayments from free cash flow (and operating cash flow) is in my view incompetence but holding such views might be why people won't ever let me be a CFO.
Its pretty well liked (with good reason), delivering>20% top line and high teens Op Profit growth. Even in bear markets it should not be on a sub 12 multiple but is.
Makes you think no?
Hi Vsihv,
An acquisitive group will spend money on acquisitions. That isn't a problem to me, it's as expected. So the operating business is generating cash, but is using that to (amongst other things) buy other businesses. They've issued equity as well to part-fund some acquisitions. Revenues & profits are rising faster than share issuance, hence why EPS is on an upward trend (apart from a spike in 2020, due to a big tax credit - so this looks pretty healthy to me -
As regards the treatment of leases on the cashflow statement, that is the required format under IFRS 16. So you can't call the FD incompetent for doing what he is required to do.
Your point on contingent consideration is a valid one though. Looking again at the balance sheet, I see "other payables" of $58.5m is in current liabilities (with no explanatory note). This was $61.9m in the last full year accounts, so I've done some digging. There is an explanatory note in the 2022 Annual Report (note 20), which describes the $61.9m as comprising $11.2m relating to deferred & contingent consideration. The rest is mainly accruals & deferred income., which is mostly when customers pay up-front, and trade payables that haven't yet been invoiced.
You make a good point that the $11.2m should be considered as debt, so added to the net debt figure. It's not particularly material though, so doesn't alter my overall view of valuation, which I think is reasonable.
Thanks for flagging this point though, and making me dig a bit deeper! :-)
Regards, Paul.
Hi Paul,
I can see the argument for acquisitions. I probably even apply it for my own holdings! Guess time will tell I guess whether the upfront cash was worth it.
As for lease repayments, I was not referring to IFRS 16 presentation on the cashflow statement but its exclusion when from underlying free cash flow, which was not an IFRS measure from what I could tell.
I think we can agree that as a management team, they are more than happy to use underlying and adjusted figures that non IFRS figures to help shareholders better understand the operating performance.
Ex holding and FWIW, if I had to pick, I'd be a buyer but fortunately I don't and I am not.
I've never been a fan of Volex (LON:VLX) ...partly I didn't see it as an attractive biz (the share price and opinions of others tells me I'm wrong!)....and I wouldn't trust Nathaniel Rothschild as far as I could throw him! (Not a random prejudiced remark but based on seeing and being around some of his investment dabblings...when trying to be or impress daddy)
Volex (LON:VLX) (no position)
Management stated today that they expect to achieve market consensus revenue = $692m for FY23.
If this is correct then year-on-year H2 growth is currently forecast to be c+4%.
This seems quite weak given the positive commentary and in the context of 4 acquisitions made since October 2021 (H2 is October-March.)
Here are my notes from the Volex Annual Report for 3 of them for any interested:
"In FY2022, TC contributed $2.4m to Group revenue.
If TC had been acquired at the beginning of the year, it would have contributed revenues of $11.6m."
"In FY2022, Prodamex contributed $3.3m to Group revenue.
If Prodamex had been acquired at the beginning of the year, it would have contributed revenues of $14.9m."
"In FY2022, Irvine contributed $6.8m to Group revenue
If Irvine had been acquired at the beginning of the year, it would have contributed revenues of $21.7m"
Vertu Motors (LON:VTU) as much rumoured, they announce another potential acquisition. Unless I missed it, they don't mention the size of the deal so not clear how significant this could be. Will try and do a bit of digging.
It's big, some nice brands in there & based on its latest accounts showed turnover of £626m & EBITDA profit of £33.9m
The potential Vertu Motors (LON:VTU) deal is material. Helston Garage Group had over £600m revenue in its last published accounts.
What the hell is this utter wibble from Hostmore (LON:MORE)
Rhiannon Scarlett, Hostmore plc's Chief Marketing Officer, commented:
"Show Your Stripes" brings new meaning to the Fridays iconic stripes that we all know and love, and it has been incredible to work with our team to create something that we really believe speaks to both our current and next generation of guests. We want everyone at Fridays to feel like they can show up as their true selves, and know that Fridays is a place where they can show their stripes - whatever they may be."
Just so the CEO isn't left out of the stupidity-
Robert B. Cook, Hostmore plc's Chief Executive Officer, added:
"In an environment where consumers are putting more thought into where they spend their money, we recognise the importance of elevating our positioning as an aspirational destination and are investing in enhancing our marketing efforts to achieve this."
Overpriced food and flat Coke is now "aspirational" ?
The website gets to the nitty gritty.
As long as you keep buying expensive cocktails you can be as drunk and obnoxious as you like.
Is this a successful long term business plan? I doubt the aging board of Hostmore would set foot in the place.
I'd turn up to see stripes added to the CEO's back.
I used purplebricks to sell a property just after lockdown and the service I got was excellent, I think a massive factor is the local agent they have on the ground and the service they personally are willing to provide. However I haven't seen a purplebricks for sale sign in my area in a long time. Most of the signs are Strike or a local guy that seems to be doing really well at the minute. Even though I was happy with the service I got and would have used them again it doesn't appear they have any presence or brand value around here.
Revolution Bars (LON:RBG) For long-suffering holders (myself included) Finncap has just published updated note available free on ResearchTree. Still targeting 36p, one can dream of happier times
Ive had a look at Conduit Holdings (LON:CRE) I hold ... its a Bermuda based re insurance co... everyones specialist subject I know! Its a recent IPO 2020 I think. So is building up its book, this year has been tough with hurricane Ian and Ukraine. The shares have been weak and picked up a bit recently. Its a hard mkt and the co are making lots of very strong noises (pricing up - best mkt in decades etc etc ) ...and naturally they have grown their premiums nicely into this. They don't have legacy issues ....so claims inflation not a huge issue. Looks cheap, at a 20% ish discount to book and yielding 9%.
Investment losses aren't good but they do expect to recover these in the run to redemption of a relatively short dated book. 6% YTD... so the book value has fallen. If rates are peaking this good news.
If anyone is an insurance buff and wants to pour cold water on the idea please do. Def not buy and hold forever but could do ok H12023... Insurance is traditionally quite defensive.
I've had a quick look, I used to hold quite a few insurers, now I have none. What I couldn't see in the trading statement was a this year projected combined ratio, which is the crucial statistic. Only a medium term mid 80's, which is fine.
Not good this year but its difficult in the early years of building the book 105.1 ....at interims....no further losses....
hardening mkt helpful but it's essential to know the key underwriters' track record and cycle management. For that reason I rate LRE, HSX and previously AML for cat reinsurance.
Hostmore (LON:MORE) (I hold) Wishywashy marketing statement on the face of it but....they re getting on with it, and not the action of a business about to go under. Arguably priced as though it is. I have my eyes open, it might need some extra capital but the upside is plenty to absorb the dilution. A soft way to add is just double your share count for a fraction of the cost...it still sits in the bottom draw but with less heavy lifting to get back to breakeven. Clearly high risk.
RDHOWARTH - As an ex FMCG Mkting Dir, the promo video linked to in the RNS (e: https://bit.ly/3MFQfUK encapsulates everything i feel about Hostmore (LON:MORE) (which I hold).
Great potential - Absolutely solid, pushing bar heritage and strategic/distinctive selling line "show your stripes" final line; the brilliantly distinctive red&white stripes visual, trendy ping pong-playing, racially-mixed, roller-skating cast with men drinking cocktails and women pints. And yet.....
Weak execution. It feels like an old person living on past glories, trying to be trendy but with a 'suit writing the creative'. The stuttered frame start is old fashioned and cheap, they bottled the young-and-trendy adult theme to reassure you can bring kids, is the heroine on skates a staff member or a customer carrying the drinks; only 1 brief shot of staff in the new thick red&white striped shirts - the iconic element, the same actress is used to first be trendy part-goer and then as Mum but not as part of a story; it was cheaply shot in the day in a near empty bar and it feels it. These details matter. I'll bet the Creative Director who shot it does not put in his show reel for his next client
It certainly does not feel like a happening-but-accessible premium brand re-inventing itself. Its heritage and established footprint of stores will I think see it through but this approach is not going to put a rocket under sales.
They are 'getting on with it' because to not market a branded F&B chain like this is to die. But this is not going to do much more than keep it ticking over. Not everything is by the numbers. This sort of business needs flair.
So the next Marketing Director / CEO (!!) may do well - but with F&B going to be so competitive through a cost-of-living crisis, this share will sit in the drawer for at least 2 years on the basis of this effort. I'll keep holding at the current price but wont be able to afford going to Friday's on the basis of my return.
Yes, I cringed at today's announcement from MORE. Especially how they've latched on to the current fad for inclusivity, and being your true self, etc. That would have been very refreshing 30 years ago, when nobody gave a monkey's about inclusion, but these days it's just what every company is saying, because they feel they have to, and it's what the competition is doing. Ooh put up a rainbow flag, make sure the adverts are diverse, exaggerate an insignificant example about recycling, to make us look green. I think most people completely see through all of this nonsense. And do we want companies projecting social or political values at all? I don't! I would prefer them just to serve nice food & good cocktails, at reasonable prices.
I regularly mystery shop TGI Fridays, about twice per week, since their £10 meal deal was great - a starter, plus fries, and a flat diet coke, for £10. Not bad. I would combine that with the £12 for 2 cocktails offer. The cocktails are very good actually, I've tried most of them, and been pleased.
This is the £10 meal deal, chicken sesame strips, with fries (and flat coke). I saw a woman on the next table send all her kids' lemonades back, probably because they were flat. So it's not just me that doesn't like flat soft drinks! Such a basic thing, and it's been like that for about a year now, in the Bournemouth site. Why has nothing been done? Why haven't the staff told the Manager (and him told the Area Manager) that customers keep complaining about drinks with no fizz in them. Thousands of people will have gone away disappointed, and many of them won't come back. Basic failings like this make me very concerned.
Anyway, the £10 deal has now stopped. So I had just a main course (and 4 cocktails) earlier this week. Chicken fajitas, was very nice, and sensibly priced at £14 -
Ah no, those were the 2 for £12 strawberry daquheries, delicious, but gave me brain freeze, as it's all ice.
This was the chicken fajitas, a good portion size (the tortillas are in a bowl under the plate of garnishes), and two empty cocktail glasses :-)
I also find the staff absolutely lovely at the Bou'mth TGIs. Service is usually quick too, although they often look stressed & understaffed.
A nice incident happened recently. I saw something on the floor, by the till, and was amazed to find it was a £50 note folded up! I looked around, and nobody saw me bend down, and I fleetingly wondered about keeping it. But then my conscience kicked in, and when the waiter appeared, I handed it over, saying somebody must have dropped it. She looked stunned.
Anyway, a couple of weeks later, the same staff member served me, and I asked if anyone had claimed the £50 note? She gave me a wonderfully honest answer, saying "Oh my God, I got home and found it in my pocket, and thought I must hand it in. The next day, I asked my manager if the till was £50 down, or if anyone had come in and asked for it, they said no. So I spent it on buying drinks for the whole team after work that night".
I just roared with laughter, and thanked her for being so honest, and said that they deserved it more than me, so well done! :-)
Regards, Paul.
Investment Karma - well done
Paul, perhaps it 'fell out of your pocket'... a subconscious tip after all those 2 for cocktails? ;-)
£50 notes. The new £20 notes.
Hi RDHOWARTH,
I do agree , but this will need a big fundraise to bring down the debt and probably the current shareholders will end up with almost nothing. After the fundraise and better market conditions this will be a good investment. The current CEO has to go as well and hopefully replaced by someone that can do deliver on his promises ( the recent new shrewd shareholders will make sure of that ).
PS. Today’s announcement was embarrassing.
Any views on Georgia Capital PLC - they release the trading update today? NAV is being boosted by their bank of georgia stake. NAV grew to £18.55 ... https://uk.advfn.com/stock-mar...
That's quite some gap to the share price!#?
There has always been a Russia/ Putin factor for this share / country. Potentially an outcome of the war is that the threat of further military interventions into satellite states has diminished hugely and the flood of educated young men into Georgia to avoid conscription will be an asset to the country.
In my mind country risk for Bank of Georgia (LON:BGEO) and £CGEO has diminished .
I hold both.
Or alternatively, the diminished strength of Russia will create a power vacuum in the region increasing instability. So personally, I still think Bank of Georgia (LON:BGEO) would be a bit of a gamble.
Georgia Capital is actually benefitting from Ukraine situation as Georgian economy is booming .
It’s simply an unloved share because everyone trots out the geopolitical risk .
I look at on two counter points
- I would rather have sone money invested in a country with a booming economy that the Uk and others that are in recession ,
- the NAV discount is silly , and the Georgia Capital NAV is actually underpinned by bank of Georgia which is also at discount to NAV . Sort of like a DFS double discount sale .
Interstingly I was speaking fo someone last night who was taking a lot a “China blocksde” next year which would mean an export ban ? He’s a high up finance guy and that’s the first I had heard of it but that would obliterate a lot of UK importers .
yes the UK situation is a bit miserable at the moment. The budget will only make life harder in the new year.
Yes, the Georgian economy is doing well, the country is well liked by World Bank and EU, and the recent flood of educated Russian immigrants will no doubt add to the mix. Yes the discount for £CGEO seems overly generous, especially after it’s successful asset sale of its water business last year and the rise in value of its Bank of Georgia (LON:BGEO) shares recently, but I’m happy to wait for a future re-rating, perhaps when the Ukrainian war ends.
Georgia Capital (LON:CGEO) - Georgian economy doing well +10% GDP with inflation under better control. NAV at £18.55 end of Sep but will be north of £20 by now given Bank of Georgia (LON:BGEO) has risen 20%. The latter though has very good CET capital well above minimum thresholds. Trades on a PE of just 4 even at these levels with a dividend closing in on 10%. In the current inflationary environment I'm a holder of both. They are well managed in my view in a resilient and growing economy. Wouldn't surprise me to see Georgian currency appreciate further against $ & £ as well which will further boost NAV and earnings.
Georgia Capital (LON:CGEO) does have some debt that will need refinancing in 2024 I think. Not high leverage though with plenty of liquidity and I'd be surprised, given mgmt's experience in capital markets, if that doesn't get done easily enough when the time comes.
There have always been 2 arguments against Georgia Capital (LON:CGEO) the first being that NAV is illiquid and could they realise value through the cycle. They demonstrated that with the Water utility sale but now still trade at a significant discount to the value of just their listed holding, which appears absurd in my view. The second reason was always the "anywhere near Russia" which is valid to a degree so investors have to take a call on that. My own view is that the problems the Russians have suffered in invading Ukraine makes an invasion of Georgia far less likely for a long time to come so I am happy enough here.
Sitting at a 65% discount to NAV though does just look like the wrong price given the weighting of that NAV to listed Bank of Georgia (LON:BGEO) but in this market no-one really cares. Going to have to be patient.
thanks for this write up on LON:CGEO - i had some discussion here two days ago when it came on my radar and expected a positive NAV update given the currency situation and LON:BGEO holding.... didn't take much research to identify the same undervaluation , at 65% discount to NAV as of the update today and probably slightly more given LON:BGEO has moved up a tad since then. What's a fair NAV discount is the question here - they have proved they can realise it on the water deal on some of their investments at least. Maybe a discount around 40%????? (just guessing and being pessimistic) would imply £11/share. (50% is £9.30/share) so still looks incredibly good value but not without any risk but what is here!
I think that's the point. There is a perception that somehow geo-political risk outweighs all other risks. I mean why buy Bank of Georgia (LON:BGEO) say when you can buy Lloyds Banking (LON:LLOY)
But the reality is look at the two businesses and I'd far rather have been the owner of the former for the last 15 years than the latter. One has lost shareholders a ton of money whilst sitting in a perceived safe geo political environment whilst the other has delivered super shareholder returns and still has a CET way ahead of minimum, a cost to income of just 30%, a dividend circling the 9% mark and is growing nicely whilst run in a conservative and well managed manner.
Now I'm not saying investors should ignore geo-political risk - merely that it is often used lazily for avoiding an investment; instead plumping for something that has an equal overall risk say but offers far lower returns.
As for Georgia Capital (LON:CGEO) my own view is that most private equity type businesses will trade at a discount to NAV but because of Georgia Capital (LON:CGEO) weighting to listed stocks that liquidity risk is somewhat lowered. So for me a 25-35% discount to NAV is probably fair which would make a share price of £13-15. Whether we ever get there without liquidating holdings and returning capital who knows though!
Zotefoams (LON:ZTF) confirmation of acquisition and been marked up this am. My fav of Pauls interviews so far ....on the watchlist at the moment.
Volex (LON:VLX) half year to Oct. Revenue and profit up from 2021. EPS 14.4c (13.8c 2021). Net debt has climbed $117 ($40). Acquisition of Review Display Systems for $6m. Presentation today.
An underwater hold in the coffee can.
Busy morning for my 25 company portfolio. Three companies reporting ITV (LON:ITV) Volex (LON:VLX) and £SNWS. On initial reading I am more than happy with the updates,
ITV (LON:ITV) is not a small cap, although looking at the share price you would be forgiven for thinking otherwise. A solid performance from Volex (LON:VLX) and I remain happy to stay with Nat Rothschild as the company evolves. Standout results from Smiths News (LON:SNWS), final dividend of 2.75p with debt falling dramatically. It will soon be debt free and continues to throw off £s. I hope that it uses the money wisely.
Thoughts from Paul/Graham on Volex (LON:VLX) and Smiths News (LON:SNWS) would be welcome, time permitting.
All the best
Good set of numbers from Smiths News (LON:SNWS):
Performance ahead of expectations with material debt reduction and increased dividend
Headlines
· Performance ahead of full year market expectations
· Core sales remaining resilient and benefiting from a favourable margin mix
· Successful mitigation of inflation in line with expectations
· Free cash flow of £48.2m benefitting from £22m of expected one-off inflows
· Significant reduction in bank net debt to £14.2m, representing 0.3x EBITDA (ex. IFRS16 leases)
· Final dividend of 2.75p proposed, making a full year dividend of 4.15p, a total payment of £10m
· Contracts for 35% of our newspaper and magazine revenues re-secured until 2029
Paul/Graham, are you covering this today?
Also Volex (LON:VLX) has good (IMO) have good results out (I have only skimmed as out running) but divi increased and this caught my eye:
“Electric Vehicles - strong momentum continues with 53% organic revenue growth delivered through a diverse product set.”
I hold.
Regards
Michael
I mentioned Ashtead Technology Holdings (LON:AT.) yesterday.
Just for transparency, an accelerated book build was announced last night and the agreed price this morning was 260p. So I would expect the price to perhaps come down a bit today (but who knows in these market conditions?).
Could be a good entry point, or if you have a buy order in perhaps suspend and watch and see.
Just didn't want anyone paying to much on my account!
Cheers
Paul
(I Hold)
I mentioned Ashtead Technology Holdings(LON:AT.) yesterday.
Just for transparency, an accelerated book build was announced last night
Very helpful thanks. I was frustrated to have missed the RNS upgrading expectations but this morning was able to grab a third of a position near the discounted price
Paul and Graham I would welcome your comments on Sourcebio International (LON:SBI) possible delisting and tender offer this morning. I am wondering if we are going to see more of this given the current mark downs on small and micro caps.
I am very disappointed by the management. They have done little to promote the company, and rather than use the cash balance to grow the company they presumably want to take it private to run it for the cashflow or sell it to private equity. The main hope for shareholders must be a white knight, but that feels unlikely.
Yes, any comments on the go private proposal for SourceBio would be welcome as this company is not a blue sky biotech, so more amenable to financial analysis. Assuming the company is right in saying annual savings of about £600,000 would result from the de-listing, this move would seem reasonable bearing in mind its low rating and decent growth prospects in multiple areas. This company (or its predecessor) has already been taken private before and relisted with an increase in value so perhaps they can do the trick again. The association with Christopher Mills ensures that there is plenty of private equity expertise available. I have made a small top-up at below the suggested tender price as I have a long time horizon.
re Sourcebio International (LON:SBI)
If they are taken private, assuming they don't re-list, what's your exit strategy? Presumably there will be no market to sell into, unless I'm missing something?
Snazzytime you are correct that there will be no market to sell into if they don't re-list or make a trade sale. I judge that management will be able to continue growing the company over the next 5 to 10 years and will have the incentive to realise this value at some stage in the future, but you definitely need patience if holding a stake in a private company. Look out for another post in 10 years time.
Tracsis #TRCS Full Year 2022 overview by Chris Barnes, CEO and Andrew Kelly, CFO.
Join us this Friday 11th November, 1pm for a webinar with Chris and Andy presenting the results.
Register here: https://bit.ly/TRCS_FY22_results
Volvere (LON:VLE) confirmed last night what we already assumed from statements in the interims that Indulgence has been closed. Its a shame to lose the money but timing of covid clearly scuppered their chances a bit. Property sales may limit their overall impact. The company has bought back a lot of stock since the interims to the benefit of NAV.
Just glanced at Marks and Spencer (LON:MKS) which look ok and continue to watch an interesting Bond - 3% Dec 2023....might be a tasty yield on this for a year....you can pick it up now at 7% but you are paying a huge accrued interest so im waiting until 9 Dec.