Small Cap Value Report (Weds 9 Oct 2024) - CMCX, HERC, MARS, NET

Good morning from Paul & Graham!
All done for today!
Explanatory notes -
A quick reminder that we don’t recommend any shares. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech, investment cos). Although if something is newsworthy and interesting, we'll try to comment on it. Please bear in mind the "list of companies reporting" is precisely that - it's not a to do list. We typically cover c.5 companies per day, with a particular emphasis on under/over expectations updates, and we follow the "most viewed" list of readers, so if you're collectively interested in a company, we'll try to cover it. Obviously with the resources available, we can't cover everything! Add you own comments if you see something interesting, and feel free to discuss anything shares-related in the comments.
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to, if they are using unthreaded viewing of comments.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. And/or it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Others: PINK = takeover approach, BLACK = profit warning, GREY = possible de-listing.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom), Video update of results so far, June 2024.
** New SCVR summary spreadsheet for calendar 2024 ** This is the live one! (updated 6/9/2024)
Archive - SCVR summary spreadsheet for calendar 2023.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
Phil Hanson's data analysis measuring performance of our colour-coding system in the SCVRs, from July 2023- Mar 2024 (with live prices). My video explaining/reviewing it.
My other video (June 2024) - How to screen for broker upgrades on Stockopedia. More stock screening strategies here (possible bargains?) - 21/9/2024.
Companies Reporting
Summaries
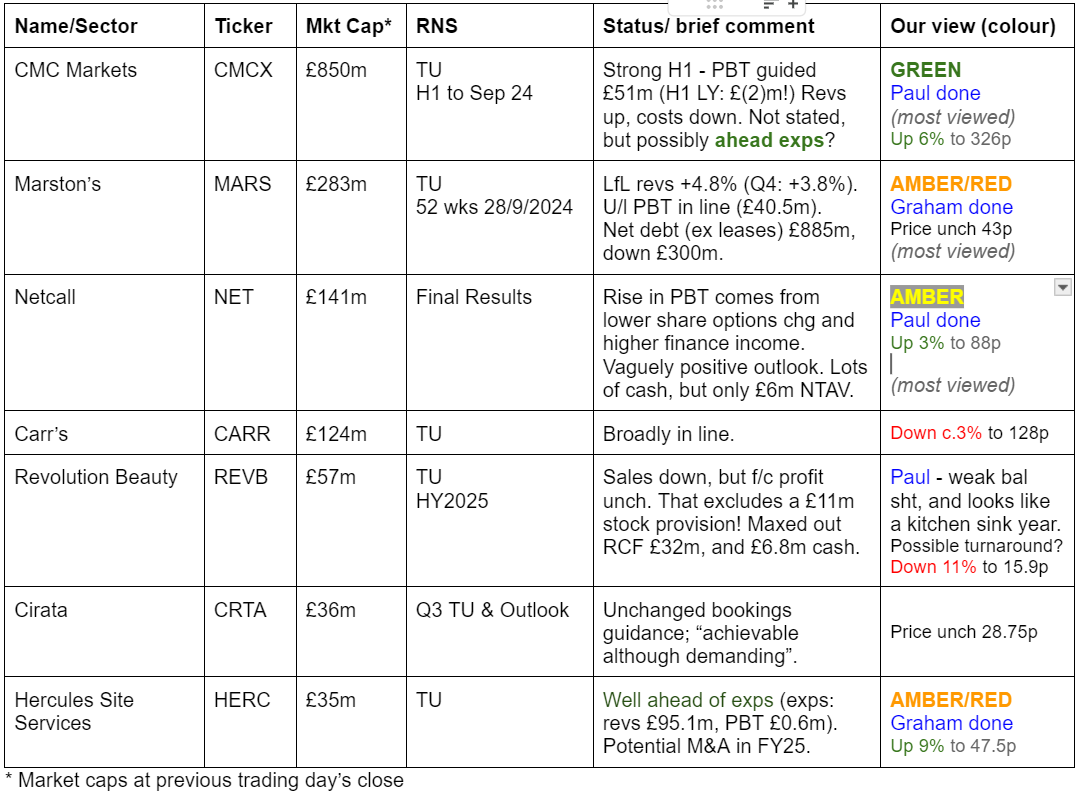
CMC Markets (LON:CMCX) - up 6% to 322p (£900m) - Trading Update - Paul - GREEN
This looks a strong update for H1, with guidance for £51m PBT, massively improved from a small loss in H1 LY. This is a combination of much stronger revenues, and a lower cost base. I reckon this share could still be decent value, if H2 delivers a likely seasonal uplift. Broker forecasts look too low for FY 3/2025 I think. Hence I'm happy to remain at our 6th GREEN this year for this high-performing share.
Hercules Site Services (LON:HERC) - up 11% to 48.3p (£38m) - Trading Statement - Graham - AMBER/RED
An excellent update from this supplier of labour to the construction/infrastructure industry. Forecasts are raised accordingly, with revenues trending c. 10% higher than prior expectations. The company is profitable and is owner-managed but I’m picky in this sector and the valuation worries me.
Marston's (LON:MARS) - up 1% to 43.3p (£275m) - Trading Update - Graham - AMBER/RED
A decent update with this pub group outperforming the broader market thanks to LfL sales growth of 4.8%. I’m leaving AMBER/RED unchanged as recent financial results from MARS have struggled under the weight of the company’s net debt (£885m) and I’d like to see confirmation that this has improved.
Netcall (LON:NET) - up 2% to 87p (£144m) - Final Results (FY 6/2024) - Paul - AMBER
OK results, with EBITDA up 5%. Big cash pile mainly comes from favourable timing of customer payments up-front. Valuation on c.23x PER looks about right to me, for a decent quality business that has established a good multi-year track record.
Paul’s Section:
Netcall (LON:NET)
Up 2% to 87p (£144m) - Final Results (FY 6/2024) - Paul - AMBER
Netcall plc (AIM: NET), a leading provider of intelligent automation and customer engagement software, today announces its audited results for the year ended 30 June 2024.
Strong performance driven by cloud demand and enhanced product proposition
To date this year we’ve not had a proper look at NET. Although we did note it announced in line trading on 23/1/2024 and 6/3/2024, with no further comments.
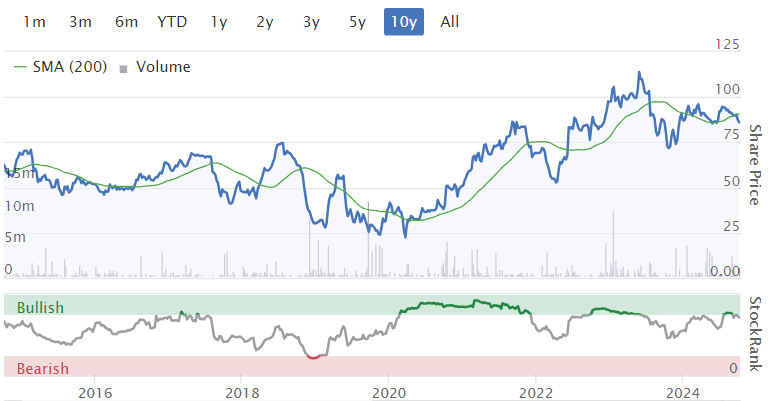
The long-term track record is mixed, but something seems to have started going well in 2020, with the shares having more than 3-bagged since those lows -
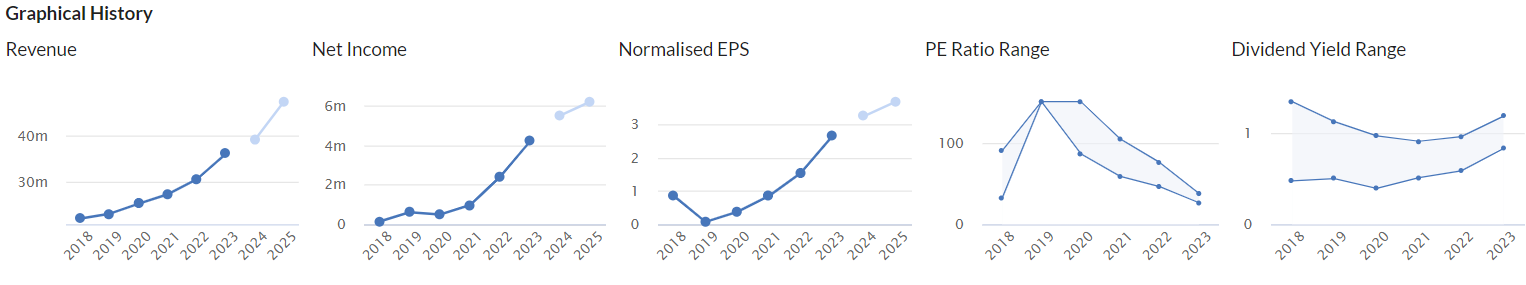
This looks to have been driven by the improving fundamentals, with much better profit growth kicking in from FY 6/2022 -
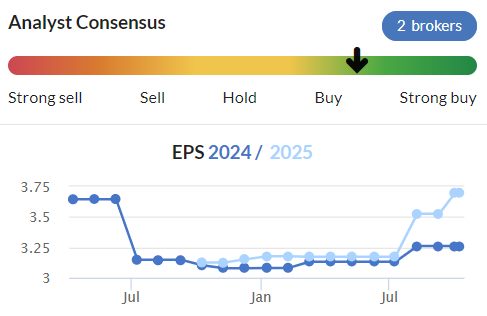
Broker consensus data also tells a positive story -
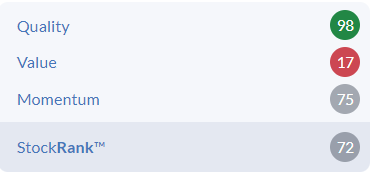
The StockRank nicely sums things up - very high quality, with good momentum, but not cheap -
The growth & value section tells the same story - good quality, but expensive on a PEG of 1.9, and PER of 23.1x, plus almost no asset backing, with P/TBV of 19.9x -
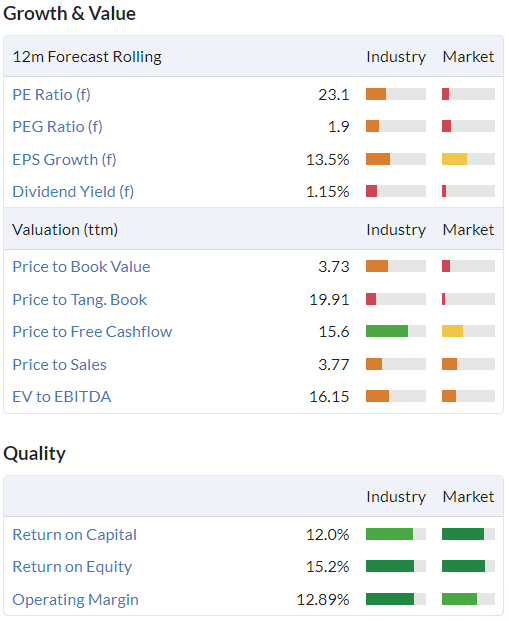
It takes about 30 seconds to review all the above items for any company, which gives me an almost instant rough idea of whether I want to pursue the stock idea any further. I can already tell you that I’m probably not interested in NET because it’s fully priced. So I’d want to see some catalyst (eg. big new contract wins, accelerating growth, blockbuster new products, etc), to get me excited about any further possible upside.
Performance in FY 6/2024 -
It splits out the faster growth rate in “Cloud services revenue” below, but I note they’re not showing the nil growth from the other part of the business, that row is missing below!
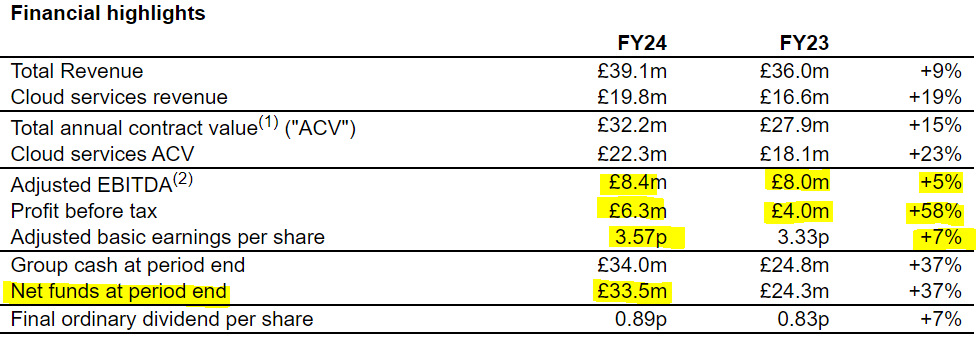
As mentioned in our snapshot posted first thing, I was struck by the large difference between Adj EBITDA +5%, but PBT +58%. The difference is explained below, where I’ve highlighted the 2 large items which boost PBT vs LY (last year), neither of which are related to the performance of the business. Hence I would say the +58% PBT is a bit of a red herring. Underlying performance is only slightly up on LY.
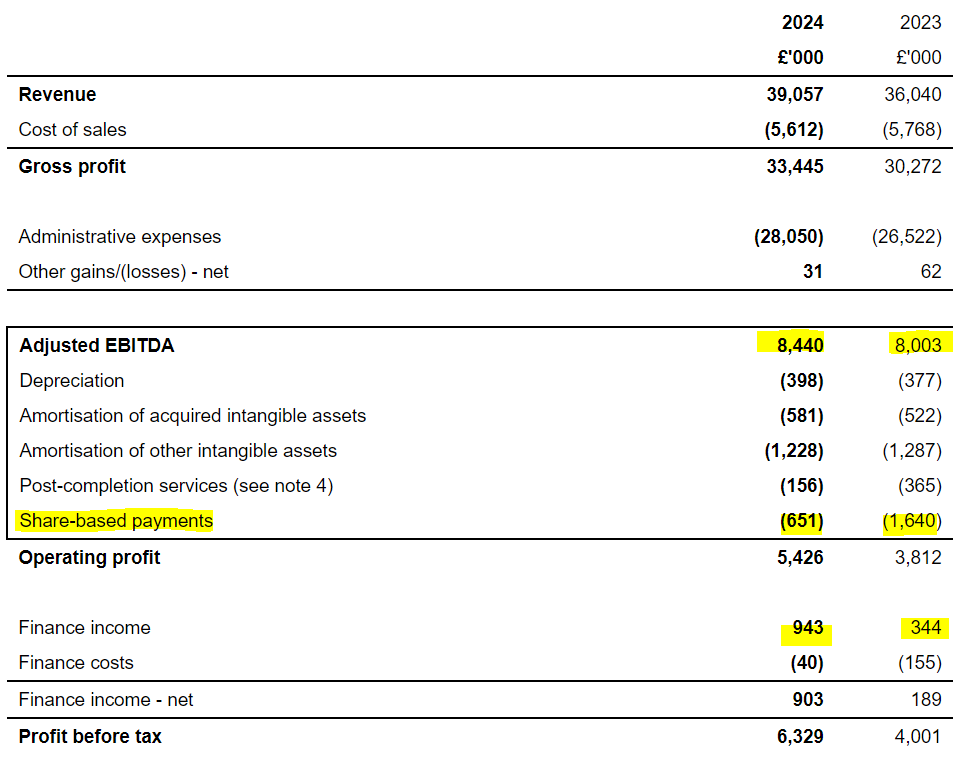
Still, those are good numbers, and this is a decently profitable business, making nice margins, whichever measure you prefer. It’s earning a lot of interest on the cash pile too, that’s material to overall profits.
Recurring revenues are 76% of the total, which investors like, and tend to pay highly for that visibility.
Acquisitions -
“Post-period end acquisitions of Govtech and Parble, both of which are expected to be immediately earnings enhancing with substantial potential for cross-selling”
The only acquisition I can find in FY 6/2024 was Skore Labs (£2m initial cash, plus £4.2m potential earn-out).
Dividends are negligible, yielding only just over 1%.
Outlook -
“Positive sales momentum continuing into the start of the new financial year which, together with the contracted revenue expected to be recognised in FY25, provides good revenue visibility.”
“Our robust pipeline and product roadmap, together with a growing base of recurring revenue and a healthy cash position, leaves us well-positioned to capitalise on the market opportunities ahead."
Balance sheet - the stand-out feature is a whopping £34m net cash pile. However, NTAV is only £6.9m, so this big cash pile has mostly come from customers paying up-front. So I would caution about imagining this is surplus cash, because it’s not. There is a £26m “contract liabilities” line in current liabilities, which shows that a lot of the cash will actually be used to provide the services that customers have paid up-front for. However, if NET can be sure that they can always get paid substantially up-front, then they could possibly use some of the cash pile eg for acquisitions. Canaccord forecasts that cash will drop about £8m in 2025, reinforcing my point that it's favourable timing this year, so don't get carried away re cash!
Cashflow statement - operating cashflow of £14.7m looks great, but benefits from a £5.2m favourable “Increase in contract liabilities” working capital movement. Personally I would adjust that out, as it could just be a one-off, and might even reverse in future.
Further down the statement, it spent £1.6m on payments for acquisitions, and £2.6m on capex, most of which £2.3m is capitalised development spend - almost double the amortisation charge, so profit is flattered by about £1m from this factor.
A further £1.3m was spent on divis.
Overall, the cash pile grew by £9.3m, with £5.2m of that coming from increased customer receipts, paid up-front. So underlying cash generation is less than half the total, but still looks reasonably good. So I don’t think there’s anything untoward in these numbers.
Broker forecasts - take your pick from Canaccord and Singers, both of whom kindly make their notes available on Research Tree, very helpful indeed.
Both have 3.7p adj EPS pencilled in for FY 6/2025, giving a PER of 23.5x
Paul’s opinion - NET has certainly established a good track record of growing profits. It’s not clear how much is organic, and how much has been bought in from acquisitions?
There are some interesting parts in the commentary, and I think this looks a fairly decent business. Cloud computing is obviously a growth area, and it also throws in a garnish - something about AI, almost obligatory these days.
Put it like this, I can’t see anything wrong with these numbers, but equally I don’t see anything exciting enough to make me want to buy any shares at this valuation.
My main software investments are BKS and IGP, which I think have more exciting growth than NET, hence why I’m prepared to pay a higher multiple for their current earnings.
Overall I think NET should be on AMBER - ie nothing wrong with it, and probably priced about right for now.
CMC Markets (LON:CMCX)
Up 6% to 322p (£900m) - Trading Update - Paul - GREEN
CMC Markets Plc, a leading provider of online financial trading and B2B institutional solutions, today issues a trading update for the six months to 30 September 2024 ("H1 2025" or "the period").
Both Graham and I picked this share at c.100p as one of our top share ideas for 2024. The appeal then was turnaround potential, with an operationally geared recovery in profits possible, plus full cash & near-cash asset backing, so you basically got the business for free. Talk about favourable risk:reward! For some bizarre reason, I omitted to buy any personally, which is so annoying. Although I think it’s fair to say that we didn’t expect the profit recovery to be quite so spectacular, and so fast. Lesson learned for the future - when an excellent risk:reward situation arises, grab it fast, rather than dithering & waiting to see what happens.
In a brief update today, it gives us some guidance on H1 trading -
Net operating income up 45% to £180m
Costs down 7% to £113m (this exclude staff bonuses) - note that CMCX slashed its overheads earlier in 2024.
PBT c.£51m (implying £16m additional costs over the £113m mentioned above) - this is remarkable, as the LY H1 comparative is a £(2)m loss! A big turnaround was expected and in the forecasts, but I think this looks like a beat. I don’t have access to any broker notes, annoyingly, so can’t 100% confirm that it is an earnings beat, but the share price is up 6.2% at 08:40, so it’s been well received by the market - implying it probably is a beat.
Given that the summer period tends to be quietish for trading, then I imagine H2 might be a seasonally stronger half perhaps? So could we be looking at >£100m PBT for the full year? That seems likely to me. Looking back at previous years’ H1:H2 split, it’s so disrupted by the pandemic and market volatility, that I can’t draw any firm conclusions. Although it clearly makes sense to me that Oct-Mar would be busier in the markets than Apr-Sept most years, so it’s probably sensible to assume CMCX could report higher H2 than H1 profits.
Cost savings are kicking in now, as expected - we covered this here on 5/2/2024, when £21m of cost savings (200 staff cut) were announced.
Product range is broadening, although it’s not yet clear which (if any) of these are likely to be significant in the group’s future performance -
“From an operational standpoint, the Group has continued to enhance its service offering across platforms with the expansion of cash equities and options products, as well as the upcoming launch of cash ISAs in the UK underpinned by our treasury management division and proprietary technology.
The onboarding of Revolut clients has commenced following a soft launch, with the number of clients live and actively trading increasing steadily. The Group will continue to keep the market updated on the progress of this partnership.”
Valuation - I’ll have to wait to see what moves there are in the broker consensus numbers, probably another upgrade, on top of an already pleasing trend -
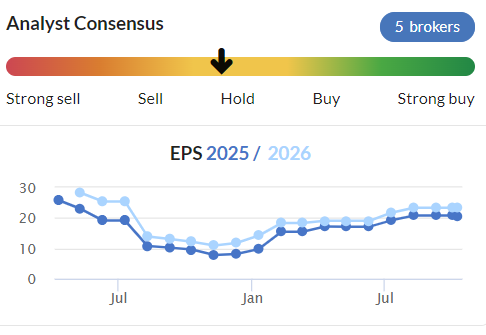
Making up my own numbers, if it achieves, say £120m PBT for FY 3/2025, take off 25% corporation tax, I get PAT of c.£90m. Divide by 280m shares in issue, that’s 32p EPS. The StockReport currently shows only 20.7p broker consensus for this year. So there could be good upside on forecasts, and a PER of about 10x on my guess for EPS. Not bad! Particularly as it has lovely liquid asset backing, and ample dividend-paying capacity.
Although we do have to bear in mind this sector is a bit feast or famine, with high fixed costs, and revenues that can suddenly be curtailed in bear markets.
Paul’s opinion - CMCX still looks decent value to me, despite the shares tripling this year. Performance has radically improved, so the company is worth a lot more. Valuation doesn’t look even remotely stretched to me, so I think there could be further upside here, maybe to 400-500p/share possibly (in the fullness of time [nice and vague!]).
So it’s a continuing GREEN from me. Both Graham and I have reviewed CMCX, this is now the 6th time in calendar 2024, and we’ve been unanimously GREEN on each occasion, as the facts justify the superb share price performance. So it’s not a case of us falling in love with a big winner for us, it still stacks up fully on fundamentals I think.
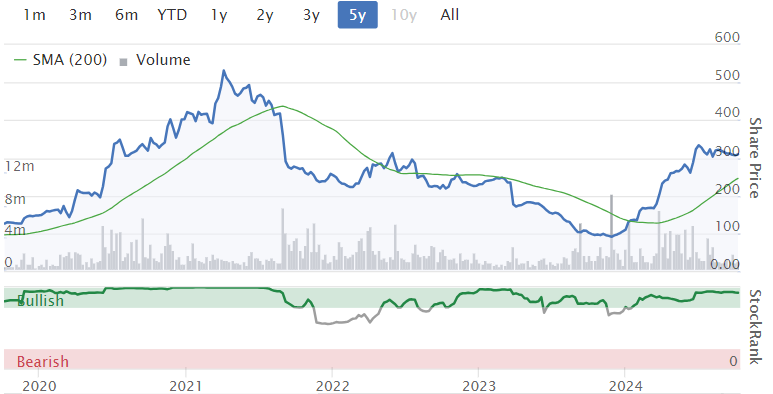
Note that the share count has actually dropped slightly over the 5-year period shown below. Note CMCX is controlled by founder Peter Cruddas, who controls c.60%, so he'll be zooming up in the rankings of the next Sunday Times rich list, given the share price performance here!
Graham’s Section:
Hercules Site Services (LON:HERC)
Up 11% to 48.3p (£38m) - Trading Statement - Graham - AMBER/RED
Hercules Site Services plc (AIM: HERC), a leading technology enabled labour supply company for the UK infrastructure and construction sectors, is pleased to provide a trading update for the year ended 30 September 2024 ("FY24").
Excellent news today: performance for FY24 is going to be well ahead of market expectations.
These prior expectations, helpfully provided in the RNS, are for revenues for £95.1, adj. EBITDA of £4.5m and PBT of £0.6m.
Revenues: the new revenue forecast is over £105m, up c. 24% on the prior year and 10% higher than the market consensus.
CEO comment:
"We are thrilled to have delivered growth well ahead of the market's expectations for the year, once again reaching new record highs and adding to our proven track record of achieving significant year on year growth…
"We have a lot to look forward to in FY25. With a successful £8 million fundraise under our belt, we have the funds available to potentially acquire selected labour supply companies in the infrastructure sector, which is well-supported by the new government.
Further Estimates: a useful note out from Cavendish this morning provides fresh estimates and further explanation of HERC’s outperformance this year.
The adj. EBITDA forecast moves from £4.5m to £4.9m, and the adj. PBT forecast moves from £0.8m to £1.1m.
Cavendish point to the challenges in the water industry that require increased levels of investment, higher numbers of staff working on HS2, and the new nuclear power station Sizewell C.
In addition to the forecast changes for the current year, they also increase their revenue estimates for FY25 and FY26 by 10-11%. However, the adj. PBT estimates for each of those years increase by only £0.1m.
Fundraising/shareholder changes: the company raised £8m in a placing in September, so I guess we can treat it as having an enterprise value of about £30m (market cap minus cash raised). It previously had a small net cash position.
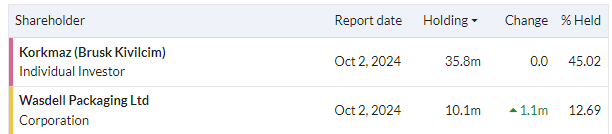
When that fundraising occurred, the founder-CEO of HERC sold 6 million shares, to a new “strategic” investor, Wasdell Packaging. Of course it can be disconcerting when a founder-CEO is selling, but he still has a very large stake and the corporate buyer should have some good reason for getting involved:
Graham’s view
I am very picky when it comes to staffing and recruitment firms and I’m afraid that I have my doubts about the merits of this one as an investment idea.
Additional revenues of over £10m this year (reality vs. prior expectations) are feeding through to perhaps a £0.3m increase in pre-tax profits.
At least there is some profit margin on the additional revenues, but it’s so thin that I would really struggle to get excited about owning this. This performance is probably perfectly normal for the sector - but this is a sector where I’m very picky.
I can only presume that the market is valuing this on the much larger EBITDA figure rather than on PBT.
Checking the interim results, EBITDA left out large depreciation and finance (presumably lease-related) costs. I would want to treat these as real costs, so I wouldn’t want to use EBITDA to value this stock.
Therefore I’m afraid this stock is not for me.
I’m nervous about taking an AMBER/RED stance on this because it is enjoying positive momentum in both its share price and its trading momentum, and it is profitable. However, the forward P/E multiple (using the latest adjusted EPS forecast) is nearly 50x. It’s risky to stand against momentum but I feel obliged to take a mildly negative view on this, at the current valuation.
Marston's (LON:MARS)
Up 1% to 43.3p (£275m) - Trading Update - Graham - AMBER/RED
Marston's, a leading UK operator of 1,339 pubs, today announces a trading update for the 52 weeks to 28 September 2024.
This is a brief full-year update. Key points:
Total retail sales +5.8% (including at franchised pubs).
Like-for-like sales of 4.8%, “outperforming the broader market”.
Like-for-like sales in Q4 (the 13 weeks to the end of September) were up 3.8%, “a strong result that comes despite the very wet weather towards the end of the period”.
Profits for FY24 are expected to be in line with an underlying PBT of £40.5m. This excludes any profits from its brewing business during the year, which has been sold to Carlsberg.
Net debt: the sale of the brewing company, along with other sources of cash, has enabled a reduction in net debt of c. £300m year-on-year. Net debt is still a staggering £885 million.
CEO comment:
'The strong revenue performance is very pleasing. This reflects the quality of the experiences we are providing for our guests as well as the continued focus and passion of our team. This performance, combined with our recent disposal of CMBC puts Marston's in a strong position to drive value for our shareholders as a focused pub business…
Graham’s view
As noted by Paul in January, this is a special situation where the company’s equity is a fraction of the value of the debt pile.
Interim results to March 2024 showed underlying pub operating profit of £53m only matching the company’s net finance costs of £53m, leaving zero profits for shareholders. The statutory (unadjusted) results were worse than this.
The company will confidently argue that it has a freehold estate with an asset value of £2.1 billion, and that it has borrowed against its assets at attractive rates. The most recent interim balance sheet helps the argument that the company has strong asset backing, as it showed a net asset value of £600m, almost entirely tangible.
Even if that’s true, however, the company still needs to generate enough cash profits to pay its interest bill and other obligations. Last year’s annual results contained a “going concern” warning as the company seemed to be in an uncomfortable situation. The subsequent interim results also included analysis along these lines but my interpretation is that there was more confidence in the company’s solvency by that point.
Overall, I am happy to leave Paul’s previous AMBER/RED stance unchanged on this, although I’d be open to upgrading when we get full-year results that show an improved income statement (in terms of both underlying and statutory numbers) and improved solvency. At this stage, there are too many unknowns for me to take a neutral stance.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

43 comments
Thanks, Paul, for your analysis of Netcall (LON:NET) on a day when the subdued market response does not call for the name to sit high on the attention queue. It’s much appreciated and adds another name to the extraordinary breadth of coverage you provide.
Some very good points made although I wonder about your observation that most of the growth this year just completed is down to acquisitions. A NRR of 117% almost demands that the growth comes from land and expand strategies, although what may be happening here is that the cloud implementation is cannibalising the traditional license revenues. And that NRR figure they quote is, I believe, for cloud software only, lending weight to that possibility.
On balance, I think the small tick up is justified by the company’s operational progress. But it is no cheaper relative to its earnings than Adobe or Salesforce or Sage, giant, secure companies with far more powerful moats. And absent a big improvement in margins, which are low for the sector, any value derives from the possibility of interest from private equity. On the margin story, that could be something to keep an eye on because those should improve as revenues grow, provided there isn’t a concomitant increase in demands on developers.
Hi Bnb!
This confused me -
"Some very good points made although I wonder about your observation that most of the growth this year just completed is down to acquisitions."
Err, I didn't actually say that!
Regards, Paul.
Err, I didn't actually say that!
Then I’m mis-remembering and have made a fool of myself. Sorry about that, Paul.
Thanks Paul. A few points:
In the presentation, the CFO says underlying revenue growth was +11%. They do have some US$ revenues so that probably accounts for the difference. Skore was acquired in H2 and its contribution would have been < 200k.
The cash dropping 7mm in the Cannacord forecast is due to 13mm acquisition spend. The nature of their business is that they'll always have positive working capital while they're growing as they're paid upfront for the year. This year the working capital boost was larger than usual but even next year CC forecast FCF of 6.9mm (net of the actual intangible asset spend).
Personally I think Amber/Green would have been more fitting. They're 80% cheaper than Beeks Financial Cloud (LON:BKS) (I hold) on an EV/FCF basis, 45% cheaper on a fwd PE basis and grew their ACV organically by 15% vs Beeks Financial Cloud (LON:BKS) 18% last year. Their growth is also likely to be less lumpy than Beeks Financial Cloud (LON:BKS) .
Margins are suppressed for this past year and next by the increased investment in their cloud contact centre rollout with brokers forecasting a return to 30+% EBITDA drop through from next year.
That’s odd. From Cannacord I’m seeing fairly steady c.20% adjusted EBITDA margin persisting FY24 through FY26. What numbers are you looking at?
It's in the Canaccord note and Singers note. Singers expects a 110bps margin improvement from 2026 as the Liberty CX investment winds down while Canaccord see a return to 31% EBITDA margin on incremental revenue.
Thanks again for your thoughts. I can see where the 50% higher PT is coming from. Just takes execution.
Any thoughts on XP Factory (LON:XPF) Paul - a new revolving credit facility to keep growing....? I thought they were planning to grow organically by now
https://www.stockopedia.com/sh...
The bank facility at XPF was previously announced, I covered that in my last review of it. So I think today was just confirming it's formally now in place as expected.
Thanks Paul
NHS pension tax grab could see ‘return to strikes’, government warned
https://www.cityam.com/nhs-pen...
l oody hell why is it always only an issue when its the public sector being hit slightly annoying that they should never be inconvienced the reality is those not in then puiblic ssctror are continually invonvenienced regularly. Ok its possibly these article writers stoking the fire here for dramatic effect.
Hercules Site Services (LON:HERC) - "Trading well ahead of expectations" - new research note freely accessible here: https://www.equitydevelopment....
A strong year end update from Hercules this morning confirms another period of impressive organic revenue growth, well ahead of expectations. This prompts 11% upgrades to our revenue and adjusted EBITDA forecasts, sustaining recent momentum into the new financial year. Hercules is led by an entrepreneurial and ambitious management team with additional firepower - following last month’s £8m fundraise - to take advantage of opportunities as they arise.
Hercules expects to report another record year, with revenue, adjusted EBITDA and adjusted PBT for FY24 all well ahead of market expectations. Revenue is expected to be over £105m, an increase of 24% year on year. For us, this prompts 11% upgrades to revenue and adjusted EBITDA forecasts, and a 55% upgrade to adjusted PBT, albeit from a low base.
Each of Hercules’ core divisions has delivered organic revenue growth. The Group’s markets (infrastructure and construction sectors) have been supportive but not without challenges. The performance has been underpinned by Hercules’ own growth initiatives (e.g. the launch of the Hercules Construction Academy) and an ability to respond to opportunities as they arise.
We share the confidence shown by recent supporters of the fundraise and see scope for further operational outperformance as FY25 progresses, with M&A being an obvious potential earnings and share price catalyst. We increase our Fair Value / share estimate from 60p to 70p.
Is anyone else portfolio loss/gain for the today showing incorrectly. When I count the individual shares gain/losses I am up, but portfolio at top is showing as huge loss. Has the stocko calculator broken or can I not add up?
Maybe a different situation to yours but I bought Vistry yesterday a.m. after a 28% drop in share price and Stocko showed the Today's Gain as if I had held Vistry from the previous day i.e. large loss. I got this explanation from Oliver:
As alluded to in the Learn Guide, Today's gain is calculated as below:
We calculate the value of all share holdings by multiplying the current number of shares held by the current price on the stock.To calculate today's gain we use the calculation as follows:Todays Gain = (Last Price - Yesterday's Close Price) * HoldingThe total days' change for the whole portfolio is based on the sum of each individual position's change on the day .As such this means that if you have made a purchase on the day, it will not be reflected in the value shown at the top of the page. Your gain on the position (and sum of gains shown in gains breakdown section) will however take this into account. Your Valuation (and history) will correctly reflect all purchases
Have you checked to see if you have any holdings with a cost without value as of today - i had nasty surprise about a week ago when virgin stopped being listed. Must admit i dont fully update my portfolio as i should do (laziness in old age). Hey ho i like a bit of pessimism at times so at least stocky aint over reporting my gains
No comments at all on the very well timed RTC (LON:RTC) 6.92% share buy back @87.75p, announced yesterday. As these shares are being cancelled, its good for all shareholders.
RTC (LON:RTC)
Good value here , no debt , positive FCF.
All the best
RTC (LON:RTC) are you not concerned about the shareholding of Bill Douie who died ~ recently and represents 17% of the stock? Long term probably a red herring, but it could be an overhang.
RTC (LON:RTC) I'd be more concerned about the 9% spread with just 3 market markers. Had a quick look at this yesterday, actually looked OK but ......welcome to the Hotel California.
Wolfie that’s a very serious issue that makes me not wanting to be involved anymore.
This spread shouldn’t be allowed and the whole MM should be banned. Every order should be visible in the system at any stage.
I will not name the country but the same MM issue was sorted 20 years ago! Everyone sending an order through a regulated broker (like you and me) was allowed to be in the system and matched if available.
All the best
SETSqx are Market maker only, SETS we can add buy/sell orders onto the order book if you have an IG account. They have different auction times as well.
If anyone wants to know which is used on any company you can look on London stock exchange or level 2 obviously.
I quite like market maker only as I can sometimes read what will happen to the price by the way theyre moving, but SETS are generally more liquid and much better if you want to force your way out.
Wolfie
Different things we are suggesting.
I am saying that every order should be allowed to be there in the system. If I want to put an order to buy RTC (LON:RTC) tomorrow at 1.01 then I should be allowed to and the order to be sent and shown with no stages involved.
All the best
Wolfie,
Would there be any difference if ringing your broker as opposed to trading on-line?
I use ii for my trading on-line but I think you can ring the broker direct? I agree with Yiannos, these MM's abusing their position will damage the market, well at least where PI's are concerned. I'm sure the institutions etc' don't have to put up with what we have. At the end of the day PI's sometimes provide the liquidity in some shares.
Graham.
I tend to look at the numbers and not distracted by things irrelevant to the financials.
Synectics (LON:SNX) CEO sadly passed away recently and although he has about a 4% the price has risen about 50%.
RTC (LON:RTC) I can see value here and I will try to build a position although the spread is not fair.
All the best
CMC Markets (LON:CMCX)
Not sure if there’s any seasonality in the results but definitely look on course to beat FY expectations.
Having watched IG Index , cmc and plus500 over the years i would say there is a huge element of randomness in the results and almost zero visibility. Things will look fantastic with these companies when the good times are rolling in and look not so great when they are in a poor patch. Perhaps not impossible to forecast but i would always be wary of predicting that a good patch would continue indefinitely or even past the very very near future. Obviously over time they may have done things to minimise variability but we only have to look back to last years comparatives to see how quickly the froth can evaporate. To be fair to the company looks like at moment they are doing a great job if they are diversifying and bring in new profit streams - so well done to management here for delivering. Revolut must bring a tidy of of new customers there way so things to look pretty tidy here as things stand (must admit i have exited this share personally as i was lucky enough to make a quick buck on the way up and was slightly worried profit bounce may not last - my reservations look over cautious as things stand)
CMC should also benefit from the volatility we're likely to as we move closer to the US election.
The most interesting set of results (to me, a predominantly tech investor) comes from Netcall (LON:NET) . With their cloud transition well underway, will the promised acceleration in revenue recognition next year prove fleeting or sustainable? The company is really a hodgepodge of small software enterprises assembled together in the growing segments of communication/contact centre and low code/robotic process automation. They have, to my mind, been over-reliant on acquisitions to build their suite of services. And it is too soon to evaluate whether the 2024 integrations of Automagica and Skore will be successful. Nevertheless, outside the dominant players in this space, ServiceNow and Salesforce, they occupy a healthy position in the UK software ecosystem. I’d be interested in thoughts from contributors and very much in the analysis of Paul or Graham if they could lend the balance sheet expertise to the task of unpicking the compan’s health. My thanks to all in advance of their thoughts.
Netcall (LON:NET)
thanks for flagging this up BnB- earnings trend looks pretty nice albeit thast starting from a very low base - company doesnt excatly look cheap but recent upgrades perhaps show that the future may perhaps be brighter. Not sure how much visibility they have but trend looks ok and sometimes then trend is your friend if they are doing a good job.
Netcall (LON:NET)
Not sure how much visibility they have but trend looks ok and sometimes then trend is your friend if they are doing a good job.
A key metric is a NRR of 117%, confirmed today. If that is sustained then revenue grows by 17% without winning any new customers. Sounds good, but the chart indicates a sideways consolidation is in train, itself a bullish signal for the longer term as the company grows into its valuation, but not indicative of short term momentum. I see the little jump this morning has lost impetus. I see this as being for long term investors only who believe in the durability of the digital transformation theme. Hopefully Paul or Graham will pick up on it since it has been a little neglected of late in the SCVR. At some point it is a clear acquisition target being on 3x revenues vs, wait for it…, 17x for sector leader ServiceNow (NYQ:NOW), incidentally my single largest position as of today.
Thanks Paul for the Netcall (LON:NET) comments, and BnB and others. Here's the analyst presentation from this morning video & podcast.
Not sure if it's relevant and this should be treated purely as scuttlebutt but I know a little about their most recent acquisition (Govtech). It's a very nice little business which interfaces with the big local govt providers (Capita, Civica, Northgate) for revenues and benefits processing. However, while the actual technology is useful and clever it's not exactly sophisticated and essentially just follows some very complicated scripts which need to be defined painstakingly, miles away from AI/ML etc.. I'm also confident that they could have had the business a fair bit cheaper, which I suppose is a credit to the brokers on the deal and a sign that Netcall saw 'strategic' value in the deal.
I guess I'll give it a go.
I wouldn't call Netcall (LON:NET) a hodgepdge. It does consist of two parts - the old legacy on prem contact centre/call handling software and the cloud based Liberty platform which provides Intelligent Automation/RPA/AI and now CCAS (contact centre as a service). The legacy part is mature and will decline gradually as clients migrate to the cloud, and the cloud part is growing at 20% pa and now makes up 51% revenues with Cloud ACV growing at 23%.
Their focus is on highly regulated entities with large customer numbers to automate those interactions and they focus on EMEA with 90% UK. So NHS, Councils, Housing Associations, Banks, Insurers, Utilities and Transport. They don't really compete with the Servicenows of this world. e.g. Network Rail uses Microsoft RPA tools for its internal processes but Netcall Liberty for outward facing processes. The NRR of 117% shows the land and expand model where their largest transport customer (I'd guess Network Rail) started at 100k ACV in 2018 and recently increased to 1.7mm ACV.
Their target market have a lot of legacy systems which would be horribly expensive and disruptive to replace. Liberty sits over the top of them, using APIs to access the data and providing a low code interface to allow them to build their own apps and processes. So all your notifications from Nationwide, L&G come from Liberty apps and your council digital /NHS app interactions will as well if they're a Netcall client. Government has realised imposing a big bang top down system on the NHS/Councils is hopeless and that platforms such as Liberty are the way forward so funding should be available. They were the first to integrate their hospitals with the NHS app and they are now used for appointment confirmations/bookings/wait list validation for over 2mm patients.
For me the positives are:
1. They generate a large amount of cash which is unusual for a small growing tech company - 27mm over the last 3 years. Cash inflow is running at 135% of EBITDA. Now that the Liberty Platform is well established, they're deploying that cash in buying in cloud product that can be integrated into Liberty and which expands their client base. So the recent acquisition of Govtech increased their Council client base to 34% from 26% of the UK councils. Combine their steady 10% organic growth with recycling 10-20mm into incorporating new product into the Liberty platform and Singers reckon they could be at 100mm revenues and 25mm EBITDA in the next 5 years.
2. Long runway / large moat. Netcall (LON:NET) already have a relationship with 75% of the NHS hospitals, 34% councils etc due to their legacy call centre software. Only 26% of their Customer Engagement clients currently purchase Liberty which increased by 5% last year but leaves a lot to go for. Combine that with the 20-30 new clients they sign each year and low churn of <5% gives strong SaaS metrics. AI tools are being incorporated and copilot type assistance will move them from low code to almost no code.
3. App sharing between clients. The advantage of serving the public sector is that their clients don't compete and all talk to each other. This network effect does a lot of the marketing. e.g. TFL and Network Rail recently shared an app for equipment certification.
4. No over-reliance on one sector. 30% NHS, 38% Public Sector and 22% Fin Services means that they're less exposed to public sector funding issues.
5. They're cheap for a fast growing SaaS company. Forward PE is 23/20 and 19/16 if you strip out the cash. About 3.4xARR pre the recent acquisitions and FCF yield of 5%. Compare that with ServiceNow (NYQ:NOW) who's growing at a similar rate as Netcall (LON:NET) 's cloud business but is valued 6x higher according to BnB.
The negatives:
1. Earnings growth is pedestrian for last year and this year. Last year they got beaten up by their largest client - a Fortune 500 financial services firm who had to cut their IT budget. Netcall (LON:NET) agreed to renegotiate a $7mm pa 2 year contract for a $4mm pa 5 year contract which knocked over a 1mm off earnings growth. No client is now>10% of revenues and the cliff edge of that contract renewal has now gone. This year, their margins are suppressed by an increased 1.5mm investment in the CCAS product. However it does seem to be paying off with Liberty CX ACV up 51% to 5.5mm and it was only launched in April.
2. They're not well known to retail investors. Hopefully that will start to change as I see they've listened to shareholders and started doing investor presentations on piworld.
3. There seems to have been IHT Aim related selling over the last few weeks. Octopus are a 3% shareholder. Hopefully that should clear up one way of the other after the Budget.
Note: It's my second largest holding after Intercede (LON:IGP) so I'm biased.
I forgot to add the other positive is their hub concept. Moving to a low code platform can be daunting so Netcall (LON:NET) provide pre populated hubs for Hospitals, Councils and Housing Associations which allow a new client to make an early start in getting the economic benefit from their digital transformation. They have 80+ hubs in use so far. This is something their more generic American competition don't do AFAIK, particularly for UK public sector organisations as it's too niche for them.
This morning China has sold off 5.6%. Yesterday I said China was up 28% compared to HK up 20% since the fed rate cut. China was up 5% MTD Vs HK flat. So after todays move ... China +22% and HK 19%. Quite clearly the gap is closing. China was closed all week and so traders used HK as a proxy... obviously some technical unwinding of hedge/positioning has taken place this week. Most commentators seem to be ignoring this, and choosing the index that has moved the most to further their bullish/bearish stance. I have no positions, except a long running Silver stock, for my sins. Seems silly to me to make a call on this trend until the relative position of HK and China settle down and start to move together which they normally do. I focus a bit more on HK since it's most palpable to non Chinese investors. Personally I would see the policy statements from China as establishing a floor .. and so steer clear of the enough/not enough debate.
News of a new contract win for 1Spatial (LON:SPA) this morning. Q2 results due out on 14th October will be interesting as the share price has been drifting down for sometime now and it’s entered oversold territory. (I hold).
CMC Markets (LON:CMCX) strong trading statement with revenue up 45% for the period.
Yes indeed, CMCX statement looks good, although no mention of performance vs expectations. Looks like a beat, based on the StockReport's FY post tax number. If anyone gets any broker notes, pls let us know their conclusion. Infuriates me when we're kept in the dark like this, whilst the privileged get info that we can't see.
Paul,
CMC Markets (LON:CMCX) Consensus PBT for FY25 is £86.8m, so they’ve done £51m of that in first half. Not sure if there’s any seasonality in the results but definitely look on course to beat FY expectations.
Some useful stats on Revolut here including number of users (1 in 6 UK adults have an account!): https://www.finder.com/uk/digi...
ref Revolut there referral initiatives and overall simplicityn of using app has done a treat. I would guess you might struggle to find many under 30's who dont have either a revolut or a starling account so sharing costs (or paying of wagers lost) with friends is made super easy.
Thanks Simoan.
Last year, CMC Markets (LON:CMCX) did a loss before tax of £2m at H1, and then the full year PBT was £63.3m.
With the qualification that performance is dependent on market conditions, rather than any sort of predictable cycle, they need a slow H2 (or big variable costs) to miss or only hit expectations.
Cheers
Chris