Small Caps Value Report (Tue 12 July 2022) - SDG, SOS, SYS1, WIN, CRL

Good morning! Paul & Graham here again. Let's hope we don't have any profit warnings today (EDIT: I spoke too soon, unfortunately), although I think there are probably plenty more to come, where broker forecasts are still unrealistic in some places.
Agenda -
Paul's Section:
Sanderson Design (LON:SDG) (I hold) (£87m) - a surprisingly upbeat AGM trading update, with performance tracking full year expectations. Macro conditions don't seem to have dented performance, so maybe high end products is the place to be, to ride out tougher macro conditions that don't impact spending by the rich? Shares look cheap. Great balance sheet too.
Sosandar (LON:SOS) (£43m) - Fantastic growth, and it's now reached profitability. Given that, and a £6m cash pile, I think it shouldn't need any more placings. There's something special going on here, in my opinion. Fashion risk, so won't appeal to everyone.
Wincanton (LON:WIN) (£448m) - an in line trading update, so no great shakes. This share does look interesting, and I suspect a re-rating could be in the pipeline, if the pension deficit payments (currently massive) reduce as expected. Looks largely recession-proof too, and has pricing power from cost-plus contracts. Interesting. Overall, I like this share.
Graham's Section:
System1 (LON:SYS1) (£39m) - a disappointing and cautious Q1 update today, published with final results which appear to have slightly missed profit forecasts. The company has allowed costs to rise as it spends on a new strategy. While it used to behave more like a traditional ad agency, it has spent a few years attempting to automate as much of its work as possible and to build automated products that it can sell on a subscription basis to its customers. In tandem with this, it's also seeking to raise its industry profile. The strategy appears to be working, though is still at a very early stage. Shareholder patience is required to see if it can ultimately achieve its ambitions.
£CRL (£28m) - inflation has hit this manufacturing company quite hard, at the same time it integrates new companies it bought during the most recent financial year. Financial risk has increased with borrowings and other financial liabilities taken on at perhaps the wrong time. Revenues fell slightly in FY March 2022, but within that, its core business and its own labels performed well. This is another one where energy costs may need to reduce or at least stabilise long enough for profitability to normalise.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Paul’s Section:
Sanderson Design (LON:SDG)
122p (before market opens)
Market cap £87m
Sanderson Design Group PLC (AIM: SDG), the luxury interior design and furnishings group, will hold its Annual General Meeting ("AGM") at 10.00am today. At the AGM, Dianne Thompson, the chair of Sanderson Design Group, will make the following statement on current trading:
The current financial year is FY 1/2023.
Obviously the share price here has been marked down, as markets anticipate a slowdown in discretionary spending on redecoration. Also, as timarr pointed out yesterday in the comments, higher interest rates means lower PERs for shares. OR, another way of looking at it, is that speculative money has been leaving the stock market in its droves, and taking down almost everything with it. Things are not necessarily rational I find - prices move due to the flow of money in & out, which is sometimes rational, sometimes not.
I was fearing a profit warning at SDG, but the tone of the last webinar didn’t suggest any panic or serious deterioration. So I’ve also been holding out the hope that SDG might get through a downturn relatively unscathed, because there’s a good turnaround underway, with lots of sensible improvements having been made to the business. For that reason I decided to continue holding a reduced size position - for a recovery, and possible takeover bid.
In that context, today’s update is pleasing -
"Overall, trading at the Company in the financial year to date is broadly in line with the same period last year and profits remain on track to meet the Board's full year expectations.
Slightly below last year then. Although the broker consensus figure on the StockReport shows a rise in normalised EPS from 12.6p last year, to 14.1p this year, which doesn’t seem realistic to me, given the macro situation. It’s also not consistent with what the company says today, about being slightly below (“broadly in line”) last year.
There’s no footnote to explain what market, or the Board’s full year expectations are. That adds to the confusion. And no broker research. This is not going well. I like simple updates, with full information (which requires a footnote to explain what market expectations are).
The rest of the announcement sounds surprisingly upbeat, e.g.
The key growth trends outlined in our full year results on 28 April 2022 - including manufacturing, the Morris & Co. brand and the US - have continued strongly in the weeks following the results announcement. Licensing has also continued to perform well.
Recent product launches have “performed well”.
“Strong net cash position” but no numbers.
My opinion - looking back at last year’s results, its adj EPS was reported at 13.75p. So it sounds like we might be heading for something similar this year, hence at 122p per share, the PER looks below 10. That’s cheap, for a decent quality, niche business, with pricing power, and lots of heritage brands. Also a superb balance sheet, so no dilution or solvency risk.
I’m really pleased with this update, which is far better than I was expecting. So this gets a thumbs up from me. I suppose high end, luxury products, could be largely immune from macro problems, maybe?
Lisa Montague has worked wonders at SDG, an excellent, commonsense, turnaround in recent years.
.
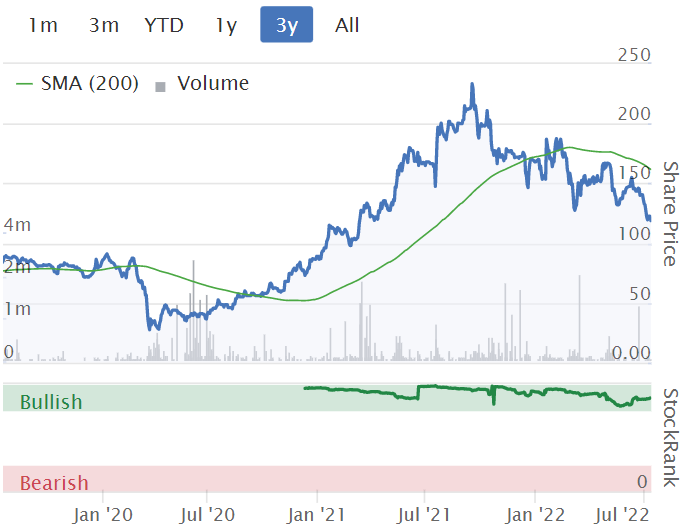
Sosandar (LON:SOS)
19.25p (up 4% at 08:19)
Market cap £43m
Sosandar PLC (AIM: SOS), one of the fastest growing fashion brands in the UK creating quality, trend-led products for women of all ages, is pleased to announce its financial results for the year ended 31 March 2022 and an update on trading for Q1 of the current financial year.
PR headline -
Continued strong momentum drives substantial revenue growth and a profitable second half
This is another strong statement, confirming the business is now profitable - something that many sceptics wrongly believed would never happen! -
FY22 was a milestone year for the Group as it delivered an exceptionally strong financial performance, exceeding market expectations that were upgraded in April 2022, with nine consecutive months of profitability now delivered (H2 FY22 & Q1 FY23).
Here are my notes & comments from skimming the results announcement -
Stunning revenue growth, all organic, +142% to £29.5m. Bear in mind the context for this - that many online retailers struggled to even match the prior year revenues, due to the pandemic boost reversing. Hence +142% being all the more remarkable - something special is happening here, if growth can be maintained of course.
Gross margin - is absolutely key, maybe even more important than revenue growth. It’s strong here, at 56% (LY: 48%). That indicates to me good products, which customers are mainly paying full price for.
Near-breakeven overall result, at £(0.2)m EBITDA - which is very close to real profits here, as there are negligible depreciation/amortisation/interest charges. Big improvement on last year’s £(2.9)m EBITDA loss.
Loss before tax is £(554)k for FY 3/2022.
Net cash of £7.0m, which dropped to £6.1m at end June 2022. I think that’s enough, and it should not need any more placings.
Returns rate in line with expectations. The notes suggest a rate of 45% is assumed. That’s high, but typical for the sector. It would be worth asking management about any plans to start charging for customer returns, which some now see as inevitable.
Going concern note says that the Ukraine war has had no impact on consumer spending - so remember that when other companies in this sector blame it for their underperformance (whilst accepting that it is having some impact in other sectors, e.g. agriculture).
Very ambitious management - note the aspiration to “become one of the largest womenswear brands globally”
Sosandar was only founded in 2016. I think what they have achieved in 6 years, is astonishing.
Affluent customers, don’t seem to be impacted by the current spending squeeze.
Balance sheet looks fine to me, with negligible fixed assets (logistics are outsourced to Clipper), and decent NTAV of £10.6m. That looks comfortable to me.
Current trading & outlook - very strong Q1 for FY 3/2023 - same as Quiz (LON:QUIZ) (I hold) recently reported. SOS is up 81% on Q1 LY, which is a flying start to a year where forecast revenue growth is a lot less, at +44%. Hence they’re already ahead of that, so it looks as if the risk of a profit warning looks low, because SOS already has some excess performance in the bag. That’s the way we like it here at the SCVR - broker forecasts that are set up to be beaten.
Trading in line with expectations for the full year, and a lovely footnote to save us time & hassle, thank you! Everyone should be doing this. If not, why not?! -
* Sosandar believes that market expectations for the year ending 31 March 2023 are currently revenue of £42.5 million, an EBITDA of £2.2 million and PBT of £1.9 million.
As indicated above, I think this looks a soft forecast, that should be beaten. However, best not count our chickens just yet, given the deteriorating macro situation.
My opinion - this looks fantastic, and the market cap of £43m strikes me as a potential bargain, assuming growth continues (albeit inevitably at a lower % rate).
That’s obviously dependent on Sosandar continuing to perform strongly, which cannot be guaranteed. You either believe in management or you don't, it's that type of growth share.
Downside risk is that growth could suddenly slow, or even halt/reverse, if mistakes happen on product design. Sometimes fashion brands hit a sweet spot, producing designs that customers love, and snap up at full price. At other times, the designers & buyers go off the boil, and product fails to resonate with customers, and has to be sold at half price (e.g. Joules (LON:JOUL) (I hold)). That’s sector risk in fashion/retail.
In my view, the team at Sosandar have clearly demonstrated that they know their target market (which is wide & under-served), and repeatedly produce products that customers love. Key person risk is high here, as the business is so dependent on the joint founders. Although as it grows, that risk should reduce somewhat, as it becomes more about recruiting/retaining a talented team, rather than doing everything yourself.
If things go well at Sosandar, this share could be a multibagger in the long term.
Risk is greatly reduced now too, given that it’s reached profitability, and probably won’t need another placing. So risk:reward is probably now better than it's ever been for this share. No longer hoping for profitability & positive cashflow, because it's now achieved it.
Overall then, this gets a major thumbs up from me, for people prepared to tolerate some sector risk, and run with it long term.
I don’t currently hold any, because it was in my leveraged account, which sadly is now a crumpled heap of former glories. Hence I didn’t have a lot of choice about cutting my position in Sosandar. Based on today’s results though, I’m itching to buy back in.
Obviously, it’s fashion, so that won’t appeal to a lot of more cautious investors.
.
.
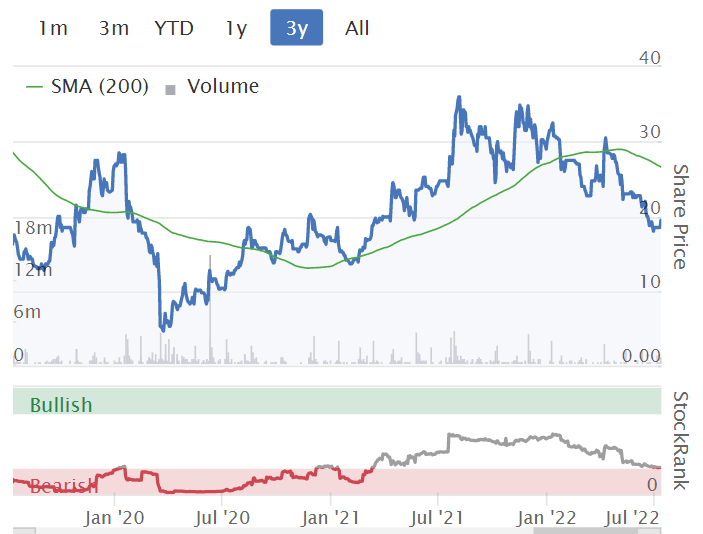
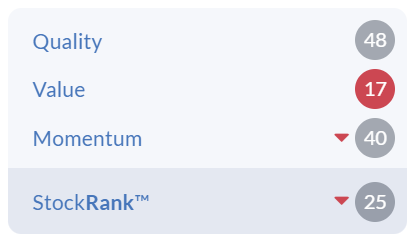
The StockRanks are still negative on SOS, but I reckon this is likely to improve considerably in a few days, as the latest numbers feed into the system -
.
Wincanton (LON:WIN)
358p (flat)
Market cap £448m
Wincanton plc, a leading supply chain partner for UK business, will hold its Annual General Meeting at 11:00 am today in person at the offices of Herbert Smith Freehills, Exchange House, Primrose Street, London EC2A 2EG. At the meeting, Dr Martin Read CBE, Chair, will make the following statement:
PR headline -
Continued growth and strategic progress, outlook unchanged
We’ve been impressed with WIN’s progress in recent years, and it strikes me as a decent business - experts in outsourced logistics.
Today’s update is in line -
Wincanton continues to make good operational and strategic progress and is trading in line with current market expectations despite the wider economic headwinds.
Management continue to wrongly believe that they have a strong balance sheet, which does worry me -
Backed by a strong balance sheet, the Group continues to focus investment into robotics and automation…
NTAV is actually negative, I went through all the detail here in its last full year results. It’s not necessarily a deal-breaker, but it’s useful to know if a company has a weak balance sheet, because it increases risk in a downturn.
Re-reading my notes from May, the pension scheme is still sucking in massive cash recovery payments, but there are signs that might be sorted in the next couple of years - actuarial deficit is rapidly reducing. If that’s correct, then I think this share could re-rate up onto a higher PER (which is currently low, due to the pension deficit & weak balance sheet).
WIN’s business model looks solid though, in that many customers are retailers & ecommerce, so business is likely to continue flowing pretty much regardless of the economy. It's winning new business, suggesting a competitive & good service. Also I like that it has mainly open-book contracts, so increased costs (such as fuel, wages, etc) just get passed through. That’s really important in a higher inflationary environment we’re currently seeing.
Outlook - sounds solid -
While it is mindful of the macroeconomic environment, the Board remains confident that the combination of a robust business model, new contract wins, disciplined pricing and a strong balance sheet, means the Group is on track to deliver full year results in line with current market expectations.
As set out in the full year results, a final dividend of 8.00p per share in respect of the year ended 31 March 2022 will be payable on 5 August 2022 to those shareholders on the register on 15 July 2022, subject to approval at today's AGM.
The yield is worth having, at 3.8%.
My opinion - this share strikes me as a decent place to be, in uncertain times. That’s despite its weak balance sheet, which doesn’t seem to hold back performance.
Today’s update confirms that trading is OK. There’s more detail in the announcement if you want it.
WIN has 3 key properties that I’m looking for right now -
- Ability to pass on cost increases to customers is built into most contracts.
- Recurring business with big clients, in FMCG - so recession risk is probably low.
- Repeated above, or in line trading updates.
I like the potential for this share to re-rate, as the pension deficit recedes in future, so it could be good for patient investors, and the risk of a profit warning strikes me as low.
Note also that Clipper was bought out on a much higher multiple than WIN not long ago, suggesting that it might look cheap to an acquirer maybe?
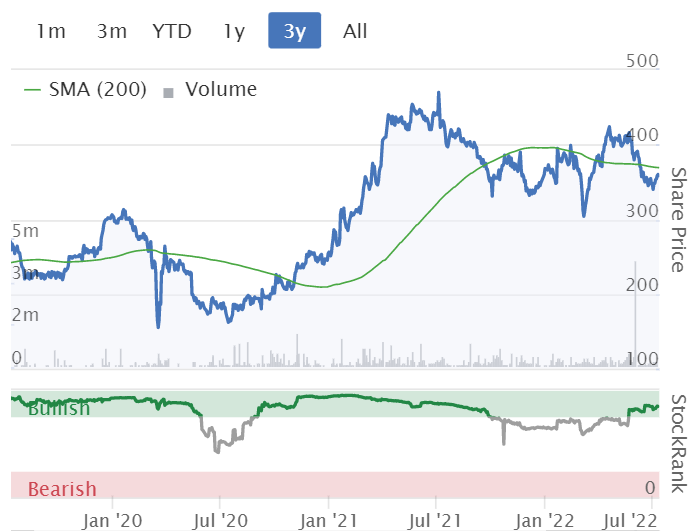
The defensive characteristics, and good trading updates, have see this share hold up better than most -
Graham Section:
System1 (LON:SYS1)
- Share price: 310p (pre-market)
- Market cap: £39m
Last month, I wrote favourably about this company's updated distribution policy. In essence, the company has decided that it prefers share buybacks over dividends, and will distribute 30%-40% of "through-the-cycle" net income to shareholders in this way.
What I couldn't say, at the time, was whether the company's strategy to improve the quality of its earnings would succeed.
In the past, it earned enormous profits from one-off projects which, by their nature, led to lumpy and unpredictable results.
But in recent years, it has been working hard to build its automated solutions designed to test and predict whether advertisements will succeed.
These automated products are less labour-intensive and produce (in my opinion) a higher quality of earnings.
Let's look at today's preliminary results (for FY March 2022) and Q1 trading update to see how it is getting on.
Key points from the full-year results:
- revenue +6% (£24.1m), gross profit +5%
- adjusted operating costs +18% (£19.2m) (actual operating costs +11%)
The "adjusted" numbers are the ones that management look at and use on a daily basis, while the numbers that I call "actual" are the ones that end up in the financial statements!
Unfortunately, the rise in costs means that profits get hit badly and are down by 65% (adjusted) or 54% (actual).
Prior to this morning, the company's broker was forecasting £24.1m of revenues and £1.1m of adjusted pre-tax profit. System1 has managed to hit the revenue forecast but the profit figure is a slight miss at £1.0m
What happened?
It's important to understand why operating costs were allowed to increase, and the company does have an explanation: it was "the planned investment in people, partnerships and platform".
Here is the complete explanation of operating costs:
The biggest area of increase was sales and marketing. Of the £3.0m cost increase year on year about a half was people costs and the other half external spend such as fame-building activity including Ad of the Week and the launch of Look out and Feeling Seen…
The next largest increase was in IT, primarily due to the growth in the number of in-house developers working on new platform features including Test Your Brand and Test Your Idea. We also expanded the number of categories on the TYA Premium database (previously called the AdRatings Database), which now 95% has coverage in the UK and nearly 60% in the US.
Strategy
To update my view on this stock, I've been checking out Sytem1's new initiatives - their Ad of the Week publication, the book launch by their Chief Innovation Officer, and the pricing on their new "Test Your Ad" products.
It's impossible to deny that there's a lot happening at the company. They've tested 80,000 ads and don't know of any larger database of "validated ad-effectiveness data".
From an investment point of view, it's attractive that their very first strategic goal is to Build Defensible Assets. They've built their database by automating tasks they used to have to painstakingly do by hand. This sounds like the type of work that could build a serious competitive advantage!
Their second strategic goal is to "Generate Fame", and I guess that can be expensive, too - but with significant payoff if it works out.
While it's true that profits in FY March 2022 are on the disappointing end of the spectrum, I think the company has made a strong argument to shareholders that the increased costs are justified, and could set them up for future success.
The outlook statement is on this theme:
There remains much to do, but we believe our marketing decision-making platform is far ahead of our competitors and combined with our ability to advise customers on how to improve the effectiveness of their marketing, leaves the company well-placed for accelerated growth and influence in the industry.
Trading update (separate RNS)
Q1 (April to June) revenue and profits are broadly in line with management expectations.
In this context, "broadly" can be understood as "less than, but not by much".
Issues faced by the company include "inflationary pressures, tighter marketing budgets for some customers and continued softness in bespoke consultancy revenues".
System1 also includes a warning that revenues and profits would be adversely affected by recession in major economies - it's obviously true, but what's noteworthy is that the company feels the need to mention it. Conditions must be tough!
My own view is that economic conditions are already recessionary in nature, regardless of whether or not we get a technical recession. I think many companies are feeling that way, too.
But let's get back to System1. Revenues fell 20% in Q1, compared to Q1 last year. Bespoke consultancy work has dried up, it seems, but the more automated "Data" revenues rose to their highest ever level, and accounted for 57% of revenues.
Conclusion
I've already shared many of my views on this stock, but it's time for a conclusion.
Here are the good points:
- Shareholder-oriented (the company announced today that £1.5m will be returned to shareholders in buybacks - and see my previous SCVR commentary on the company's distribution policy).
- Not just a labour-intensive ad agency. Working to build data assets that will allow them to sell subscription-based, automated services to customers. In this context the loss of consultancy services doesn't concern me too much.
- The company genuinely seems to be respected and admired in its field.
- The founder and CEO still owns 22% and should be well-aligned.
The bad points:
- Short-term profitability is lower now, partly because of the loss of bespoke consultancy work and partly because the company's ambitions require increased spending in the short-term.
- In a recession, marketing and advertising budgets get savaged. It would not be enjoyable to hold this through a recession (shares are already down c. 40% since the high in January).
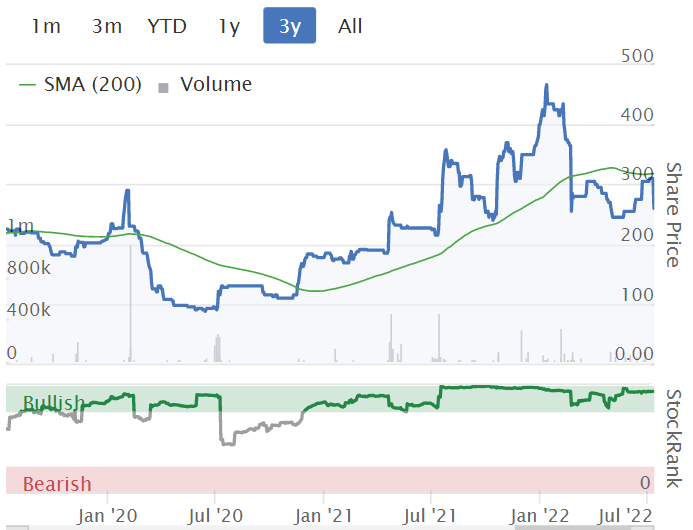
It's hard to predict the ultimate success or failure of System1's current strategy. The company does have an excellent track record of earning profits and paying dividends to shareholders over many years. Therefore, on balance, I would trust management to either succeed with the current strategy, or else to fail gracefully and then try something new!
.
Creightons (LON:CRL)
Share price: 15.4p (-28%)
Market cap: £20m
Commiserations to holders here, as I know this is a widely-held stock among private investors. Indeed, I used to hold it myself! But I don't currently have a position in CRL, and haven't had a position in it since 2020.
Things have changed quite a lot since then.
The company spent big (relative to its size) on some acquisitions:
- £4.86m for skincare brand Emma Hardie Ltd, and this came with £2m of debt.
- £4.85m for Brodie & Stone, which has a portfolio of personal care brands. This also came with an element of debt (£700k).
Let's see the new balance sheet at Creightons, as of March 2022:
- Net assets £25.7m
- Significant intangible assets arising from the acquisitions. Strip out intangibles and NTAV is £12m.
There's a surplus of current assets over current liabilities, but inventories and receivables have both risen materially and helped to suck up the company's cash balance, which has reduced to less than £1m as of the accounting date.
Net debt is £6.2m (cash minus borrowings).
There's a feature of the Emma Hardie acquisition that sticks out to me: Creightons paid £1.36m in the form of 1.6m shares, at a price of 84.8p per share.
But in addition to this, Creightons apparently made a bet on its own share price, with the sellers of Emma Hardie:
The company has guaranteed to the sellers of Emma Hardie Limited a share price for Creightons PLC at £1.25 per share as at 28th July 2022… The ultimate liability can only be assessed 12 months after the acquisition date on 28th July 2022.
Unfortunately, the lower the Creightons share price falls, the more they have to pay out to the sellers of Emma Hardie. It's easy to say in hindsight, after the share price has collapsed, but there has to be a better way to structure a deal than this.
The CRL share price has fallen by approximately another 20p since the accounting date, so I reckon that the contingent consideration is likely to have increased by another six-figure sum, compared to the number on the balance sheet published today. The final amount will depend on what the share price does between now and 28th July.
If we add CRL's deferred/contingent consideration, we get adjusted net debt of £7.7m.
This may help to explain why the company has today cancelled its dividend:
The Directors do not propose a final dividend for the year ended 31 March 2022, (2021: 0.50 pence per ordinary share) due to the challenging and volatile economic conditions facing the Group and the need to be prudent about utilisation of cash resources.
Let's read more about the challenging and volatile conditions facing the group:
- revenue down 0.7% to £61.2m
- "core business" (excluding hygiene and acquisitions) revenue +21.8% to £57.3m
- operating profit down 19.1% to £4.37m
- operating profit margin 7.7% (2021: 8.8%)
- EPS down 32% to 3.98p, and benefits from a reduced tax charge (though one-off costs could arguably be adjusted out of this).
All of this is quite discouraging, except for the growth in sales in "core business". That genuinely looks very positive, particularly the 37.7% growth in own-brand sales (excluding hygiene). Remember that two years ago (FY March 2020), total sales at Creightons were just £48m. I think that significant progress has been made.
The big problem, again, is inflation. While it has plenty of ambition in brand development, it is still essentially a manufacturer. And manufacturing is not easy, in inflationary times:
In common with most manufacturing businesses we have had to deal with unprecedented increases in our input and energy prices together with significant disruption in the global supply chain. We have developed a detailed cost indexing system which monitors all cost increases and have engaged proactively with our customers.
Gross margin is still doing well, but the company says that it is being hit when it comes to distribution costs, energy and insurance.
There is no outlook statement, but there are concluding paragraphs which tell us what the company is doing:
…we have embarked on a programme of overhead cost reduction and of improving manufacturing efficiencies which should significantly reduce operational costs by the end of the year ended 31 March 2023...
In summary the Board believes that good management, strong customer relationships and financial position will continue to enable the Group to manage the current crisis and that the Group is well placed to proactively manage new challenges and take advantage of any new opportunities that may arise.
We are still keen to expand but will only do so when the infrastructure is fully repositioned to deal with the volatile conditions we are facing.
My view
I still have a fondness for this company, while remaining wary of some of the risks associated with it:
- generous employee schemes leading to significant dilution for outside investors
- previously, Creightons bucked the trend of manufacturing businesses earning low ROCE. Unfortunately, its ROCE has fallen to a more average 12.9% in FY 2022.
- there is now an increased element of financial risk as it relies on borrowing facilities to fund acquisition costs along with rising inventories and receivables. The company reports headroom of £6.3m as of March 2022.
On the more positive side, the long-term track record is, I believe, much better than the average manufacturing business. The growth it has achieved with its own brands is something I find particularly encouraging, and there is still plenty of time for the company to prove that it did not overpay for this year's acquisitions.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

99 comments
M&C Saatchi (LON:SAA) does anyone understand what is happening?
Just had an email about a tender offer for my shares, need to respond by 14 July. Default is 2.043 ADV shares and 40p in cash.
Following
There must be something in it for someone, remember Rockrose Oil's tender offer? I gave up and got out of £SAA at considerable loss, learned a lesson at Rockrose.
Thanks, I don't recall what happened at Rockrose.
Im a bit confused by this tender. I understood that M&C Saatchi (LON:SAA) rejected this offer from ADV, why are they offering a tender with the default for ADV shares/cash? The Next Fifteen Communications (LON:NFC) was a better offer.
I hold shares and have had no emails
Who is your broker?
Im with IG group (LON:IGG)
Wondering if they have made a mistake. usually the default option is no action, ie don't take up the tender. Why such short notice?
Probably a waste of time phoning them up.
I will send an email tomorrow rejecting it.
ADV looks like a poor company imo, am not interested in two of that.
My broker is AJ BELL.
Yes, I have rejected this tender offer, think IGG may have got this wrong, never seen anything like it.
Further to my previous post on M&C Saatchi (LON:SAA), IG have now scrapped that offer and replaced it with a new one, with the default being no action, as I would expect.
Those of us wanting quality discussion boards on other sectors (e.g Mining) that are as good and popular as this one are maybe forgetting why the Small Caps Value Reports are so popular.
It’s mainly because Paul is an exceptional analyst and the best by far I’ve come across in over 30 years of investing. It would be nigh on impossible for Stockopedia to find another like him to comment on Miners or other sectors. Of course there are other excellent analysts too including the likes of Graham, Jack, Roland and others, but Paul is in a league of his own not just for the quality but also the time he puts in to it day after day and even weekends too. My fear for Paul for ages now, has been burn out as I can’t fathom how he absorbs so much information so fast and so accurately, and is then able to write in such detail and quality so fast too.
It seems a lot of Stockopedia subscribers subscribe just for the Small Cap Reports and don’t even seem to use the Stock pages which should imo be the key reason for subscribing. So I would much prefer Stockopedia to ensure that the standard of, and the figures in, the stock pages are as high quality and accurate as possible , and updated regularly and fast after results, ahead of increasing focus on bulletin boards. There’s otherwise a risk of quite big loss of subscribers if Paul decided at some point to call it a day
A mistake some make, and is probably a reason posts and posters are much fewer at present is in seeing Paul, Graham etc as tipsters instead of analysts. Paul might be the first to agree that he is a far better analyst than he is investor! So those not realising that can come badly unstuck.
Also small Company shares have fared very badly and much worse than some others in this bear market. So those with unbalanced portfolios holding only UK small Company shares covered here have been hit very hard in this bear market.
Finally, it would be good if posts on other threads and themes including those covered by excellent Stockopedia writers, were more popular. It’s very hard to generate the same interest as there is in small companies. A couple of us tried it with Investment Trusts, a great way to invest all round the World; it went down like a damp squib!
Ken, I agree with you. I really like the daily column. But I subscribe to several platforms in several regions. I'm a keen investor in many of the companies that SCVR comments on. But I also use Stockopedia extensively for US, European and Australian stocks and I pay for these, but there is zero coverage ...
If it is the intention of Stockopedia to gain more subscribers, then that will have to be addressed...
I would welcome a daily Small Miners Value Report, there is much to be considered and it is the comments that one such would bring forth prove to be most useful. At present it's a desert.
There is maybe a dozen small miners and you could hold them all for £200 a pop and see where it goes. I like watchlists and alerts but it's time.
I think the problems with miners going forward is all governments are broke and will increase royalties (tax), become greedy and not understand the very high risks of mining, drilling etc where all the easy finds have been made. The big boys can hedge but it's harder and the minnows have no chance.
Seems investing has become political. Watching Serco (LON:SRP) breakout of 170p nicely established and tailwind behind the dinghy.
Thanks ken, cheque's in the post (it might bounce though!) ;-)
Sosandar (LON:SOS) (I hold) rises 4.5% on an update like that! The update was up at the top of my expectations (hopes, even) but the lack of response in the market was certainly not. It is a very strange place at the moment,
I watched the Sosandar (LON:SOS) webinar and was very impressed. The cost of customer acquisition has fallen sharply and will fall further. Each new customer is profitable on their second order and retention rates are high. Next and M&S are marketing for Sosandar (LON:SOS) at no cost to SOS and they don't pay their influencers and celebs - they ear SOS clothes because they like them. No plans to charge for returns (they don't need to) but will monitor competitors. Much more on the webinar - I expect a recording will be available. Overall I was impressed greatly. I hold and will add.
I've said it before and will again. It would be great to have some coverage of resource stocks (oil,gas,coal,mining). These feature heavily in the UK market and have done well over the past 6m, but Stocko has no analyst coverage! - instead it focusses heavily on retail, which has done nothing but slide for the past year...
I argue that these are relatively simple businesses compared to retail. There are also a lot of high quality businesses, paying good dividends with the companies themselves having strong balance sheets. It's a mystery why these companies are ignored...
Agreed. I see no reason why all but major Mkt Cap stocks are not covered. Appreciate that this will need more resources but the extra subscribers such coverage will produce, should make it worthwhile to Stockopedia
Exactly! It surprises me that shaky companies such as Ted Baker and Joules are covered, while Serica Energy is not!
Having worked in the oil industry for 30+ years on and off, but now retired, I too would be very interested if Stocko would consider hiring a resource specialist in the future.
How do you know there are any resource experts out there both capable and willing to provide such a service?
The answer would be in the comments generated, all that is required is a Conductor.
Exactly! It surprises me that shaky companies such as Ted Baker and Joules are covered, while Serica Energy is not!
Well, why not go and start your own thread as provided by the Stockopedia discussion facility? That way you can all go and discuss resource stocks until your hearts are content, instead of asking Paul and Graham to comment on companies completely outside their sphere of experience and knowledge. There's a very good reason why most experienced investors have no interest in small cap resource stocks! Maybe one day you'll find out...
All the best, Si
"There's a very good reason why most experienced investors have no interest in small cap resource stocks! Maybe one day you'll find out..."
I think this is an extremely arrogant and ignorant reply... it's the sought of reply that one would often see on anonymous stock boards.
Nobody is asking for Paul or Graham to do this. I invest across the spectrum of sectors and I've invested in many of the stocks that Paul has mentioned over the years. I highly value his work.
The company that I mentioned (Serica Energy) supplies 5% of the UKs natural gas. They have no debt. They have hundreds of millions of net cash sitting in the bank. You have no idea what you are talking about.
In addition to Stockopedia, I subscribe to several paid research platforms, including Zacks for the US stocks. They provide analysis across the full range of sectors. This proves that it is possible. If done properly, it might also bring in many more Stocko subscribers.
Anybody that invested in companies such as Boohoo, Ted Baker, Joules (yes, I was one of them) knows that retail stocks, like all stocks are not without risk.
BattleofBrit said -
Anybody that invested in companies such as Boohoo, Ted Baker, Joules (yes, I was one of them) knows that retail stocks, like all stocks are not without risk.
Tell me about it! It's been a nightmare in the last year.
That said, with valuations so bombed out, I reckon we could see some multibaggers in future, if we monitor things closely. Time will tell.
A terrible time though, and I'm very sorry for leading people up the garden path on shares that have done badly. I feel awful about it. As always though, it was just giving an opinion on the information that we had available at the time.
Regards, Paul.
It's called SCVR but should be called SCVR (but excluding oil, gas, miners & biotechnology).
I do have an agenda since most of my Folio is in those sectors. It's not rocket science to highlight red flags, profit warnings, or contract wins & to interpret income statements, balance sheets & cash flows for subscribers.
Maybe this is where you can add your expertise then Barry5, to give us the miners coverage in the comments, then it may get traction to eventually become a standalone blog
It's called SCVR but should be called SCVR (but excluding oil, gas, miners & biotechnology).
Yes, and that’s what it says on the tin. So which part of this daily disclaimer do you not understand?
…We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
I suspect the reason Stockopedia do not cover small cap resources specifically is that there is much less interest in these sectors within the subscriber base than many here presume. They also probably remember what happened the last time these types of companies were popular with PI’s.
IMO a SCVR should be exactly that and not exclude any sectors that are too difficult or not interesting enough for the analysts but I do understand the sentiment on here is to accept the status quo. I still enjoy the insights and banter
I agree it should cover all aspects of the market. How ever I believe stockopedia struggle to find the people specialised in other sectors to do this.
I am not sure I agree with you guys. I would rather have someone say "look I don't consider I can offer anything here" rather than someone who offers lots of bravado but actually has no competitive edge. I have come to know Paul and Graham and they have strengths and weaknesses, don't we all. For me its about quality not quantity. Just saying...
I didn't take BattleOfBrit's comments as any kind of criticism of Paul or Graham. And I don't think this is a matter of seeking to have the SCVR extended to embrace energy/resources small caps.
It's simply a matter of fact that Stockopedia does not give coverage, along similar lines to the commentary and analysis of news that Paul and Graham provide in the small caps arena, to stocks in the energy/resources sectors.
But maybe I've read this wrong.
Anyway, it's an issue that's been raised often before ... including by me. My impression, based on the discussion that has ensued, is that most of Stocko's current subscribers are happy with things the way they are. I'm not ... but I've come to the conclusion that this is unlikely to change and I shall just have to 'like it or lump it'.
BoB - I see where you are coming from. I have quite an exposure to resource stocks, but rely on wiser heads than I.
As an ex-retail analyst I would argue that retail is quite simple to analyse, otherwise I would have not managed it! Resource stocks require a degree of technical expertise. It is really up to Ed as to whether he wants to resource (ahem) a specialist analyst of this area.
I've said it before and will again. It would be great to have some coverage of resource stocks (oil,gas,coal,mining). These feature heavily in the UK market and have done well over the past 6m, but Stocko has no analyst coverage! - instead it focusses heavily on retail, which has done nothing but slide for the past year...
Well, when I first joined Stockopedia you couldn't move for the various threads about Soco International (now Pharos Energy). I think you should take a look at the long term chart for that one and many other O&G companies that were PI favourites last time Oil was > $100 a barrel. Many shirts were lost...
I argue that these are relatively simple business es compared to retail. There are also a lot of high quality businesses, paying good dividends with the companies themselves having strong balance sheets. It's a mystery why these companies are ignored.
I guess you are relatively new to investing in shares? If you believe these are simple companies to analyse, you are fooling yourself. Most retail shares do not have to deal with the corruption and political instability of the countries they operate in for a start. These are highly cyclical businesses whose profits, and hence, share prices are totally dependent on commodity pricing outside of their control. If we have a serious recession (especially if China joins in) then resource stock share prices will plummet.
All the best, Si
I agree. We don't need a mining specialist or someone who professes to know the energy business inside out. Most of the resources pundits I've come across don't really have a great track record of predictions, and most of them aren't very good at digging into reports. What I would like is someone with a long-term interest in their speciality and the ability to comment intelligently when results and news arrive. Someone like Paul, Graham, and Jack really. However I suspect the cost of someone like that would be quite high.
Hard to cover all sectors - I like pharma, defense and cyber. Miners are terribly dangerous (certainly the golds) but where the action is. But agree after Boohoo (LON:BOO) have no interest in fashion.
Started a position in Blackrock Smaller Companies Trust (LON:BRSC) which should be a bellweather for small caps when they eventually rise back into the sunlight. Blackrock World Mining Trust (LON:BRWM) also useful and pretty much tracks the big boys.
Cathay Innovation, a global venture capital group backed by TotalEnergies TTEF.PA , has launched a 1 billion euro ($1 billion) fund to invest in technology start-ups with an eye on sustainability.
When everyones piling in, time to chip out.
CQS Natural Resources Growth and Income (LON:CYN) is a pretty good option for commodity exposure - good track record, well diversified across energy and a wide range of metals (including some gold). Currently on an attractive discount too.
Previously invested in individual resource companies, but with small companies just too much individual risk which can never be accurately factored in (political, operational, explorational, etc). To spread this risk, my commodity exposure now comes only from collectives or large caps (where you effectively get a portfolio effect given they'll have exposure to dozens of mines).
Yes. I have no interest in retail, it will get hammered in a recession. Resource companies however are a better bet as well as an inflation hedge.
I think this is an extremely arrogant and ignorant reply... it's the sought of reply that one would often see on anonymous stock boards.
Nobody is asking for Paul or Graham to do this. I invest across the spectrum of sectors and I've invested in many of the stocks that Paul has mentioned over the years.
So why do you and others keep on and on pleading for coverage of small cap resource stocks in the SCVR comments section then? It's boring, and the very essence of ignorance is someone who keeps banging their head on the same wall over and over again as you and others continue to do. The Stockopedia team is, in my experience, very responsive. So why not contact Ed and the team directly if you want a resource specialist to do a new column? Its made perfectly clear in the SCVR header each day that resource stocks are not covered. End of. Anyone who continues to ignore that polite notice is completely ignorant and very arrogant IMHO.
The company that I mentioned (Serica Energy) supplies 5% of the UKs natural gas. They have no debt. They have hundreds of millions of net cash sitting in the bank. You have no idea what you are talking about.
With regard to Serica I agree, I have absolutely no interest, but you've now narrowed your argument from the original "It would be great to have some coverage of resource stocks (oil,gas,coal,mining)" to a specific company. Fine, move the goalposts as far as you want why don't you...
In addition to Stockopedia, I subscribe to several paid research platforms, including Zacks for the US stocks. They provide analysis across the full range of sectors. This proves that it is possible. If done properly, it might also bring in many more Stocko subscribers.
Sounds like a no brainer for Ed then. As mentioned above, why make comment here instead of contacting Stockopedia directly using the green button? FWLIW I have no problem with the idea and would welcome a separate place for resource companies to be discussed, which I could then totally ignore.
"Join our expert analysts every weekday for the best insights into small-cap shares"
No exclusions there!
I'll look at Zacks thanks. Have an IKBR $ account - cheap as chips trading and peanuts spreads - but need a degree in how to work the platform :(
Hi BattleOfBrit,
I understand your frustrations.
It's not possible for me to cover everything and I'd rather focus on things where I have some understanding of the sector. Resources is a completely different thing, and best left to sector experts I feel.
Appreciate that your point is more about overall Stockopedia coverage, not having a go at me.
I wish my sector specialism was NOT retail, right now! But things have a habit of reverting to the mean, longer term.
Regards, Paul.
I am sorry, but I have to disagree with the statement that mining companies are "relatively simple businesses to analyse". They require a unique mix of metallurgy, mining, geology, macro market, and financial expertise ... I am quite confident they are considerably more complex to analyse and considerably riskier than say retail, which is the example used.
Supreme (LON:SUP) Hats off to CEO for purchasing 500 k shares this morning....Shows he really believes in the company
Supreme (LON:SUP) But why do the CFO and chairman have so few shares. I have more than them put together.
Dunno but I pray they don't get some via nil cost options like £RBGP. I prefer to see cold, hard cash in these troubled times
In the recent Webinar the CFO was replying to a question about share buybacks (the answer was they aren't allowed to say anything) and she threw in a remark that she did not have deep pockets.
yes I heard that to and suspect that she's hankering after the nil cost ones
What are “nil cost shares” ?
When nil cost shares are issued we simply need to stand up and create an almighty fuss because it is simply theft .
No self respecting CFO or CEO would like to be called a thief , so if they have the brazen gall to issue nil cost options they deserve to be called out for what they are doing .
The RBG gift of 500k shares was blue collar crime by a set of thieves stealing from the company owners .
Creightons (LON:CRL) what struck me about the results, inter alia, was the revenue from Emma Hardie that came in at £2.3m for the 8 months since acquisition to end March 2022. if we extrapolate this figure it suggests annual revenue of around £2.9m.
Admittedly times are tough, but it does appear to be a very expensive acquisition. Creightons (LON:CRL) paid £6.36m for the brand, £5m in cash and 1.6m shares. Seems an awful lot of money for £3m or so of turnover.
It strikes me that the cash on the balance sheet may well have been 'burning a hole in the company's pocket' ? Still it may well yet deliver.
IIRC, they figured that they could strip out a lot of costs from EH and give them immediate access to markets and marketing that the original owners couldn't easily fund. I suspect/expect that they should blow that £3m revenue figure out the water this year given the narrative from CRL on the two acquisitions. Time will tell if it was a good investment :)
Emma Hardie is a business I know quite well. It has not been run particularly well and from memory lost quite a lot of money.
At the time of acquisition I remember been somewhat amazed they had paid £6m for it. It seemed they had cash burning a hole in their pocket.I appreciate they say they can rationalise costs and provide working capital but they left the same management team running it.
There also seemed to be a positioning problem. Their plan is to manufacture this high end offering in amongst the low end stuff they offer. They want to make the luxury brand more available in the mass market. I am not sure that is a plausible strategy.
I also remember watching their presentation post acquisition. I think the MD or deputy MD used to be the marketing director. She spouted a lot but nothing of substance.I had been keen on Creightons (LON:CRL) up until the acquisition. Knowing what I did about Emma Hardie I decided it was not for me.
Synectics (LON:SNX) - interim results.
Synectics (LON:SNX) is a very small cap security group with just a £18m mcap. Deals in a variety of security from casinos to cities like London and Berlin. Worth reading some of the older broker notes as it is quite interesting.
No debt and cash increased to £4.2m, ahead of expectations. Strong order book and second half is seen as the stronger part of the year.
Still has parts of the business no fully opened from covid.
Technically it is trading near the bottom of its trading range and I can see returning to 160p level this year giving a 50% uplift.
gmtrader
Synectics (LON:SNX) looks interesting. Do you know anything about their 29.9% shareholder, Whitehall Associated S.A. registered in Panama?
Hi, no I don’t know about them except the obvious that they last increased their holding about a year ago at a similar price to todays sp. Synectics (LON:SNX) is in better shape a year on.
I note a broker report has come out today now giving a value between 230p -285p. Covid restrictions I’m Asia have restricted the casino side of the business which should obviously improve. Security is an area that imo should be a good sector to be in these days.
The recent drop in sp is mainly due to higher costs I think from energy but the company is able to pass on these costs. Plenty of R&D going on and the company has spent the last two years getting their costs under control.
The broker note suggests they have a capacity to do $100m in revenues.
I like the fact that they are quite diversified in offering security to casinos, oil and gas, bus services and city infrastructure as well as midlands police service.
Paul Scott reviewed the company a year or two ago and high lighted that the company would have a large cash burn but the company has seemed to controlled this very well. They are still looking at improving their margins.
£SNX Investor Meet presentation 14 July
Just to add to the collective complaint about the false market created in the shares of companies that we own that are receiving, making and rejecting takeover offers without any regulatory announcements whatsoever, today's merger proposal from Kistos (LON:KIST) of Serica Energy (LON:SQZ) makes for eye opening reading.
Turns out that Kistos approached Serica on On 16 May 2022 to propose a merger which was rejected 2 days later. Kistos returned on On 24 May 2022 with a more detailed proposal which Serica again rejected but this time Serica countered with a proposal to takeover Kistos.
Both sides entered into an NDA to start discussions and Serica then made a takeover proposal to Kistos on 1 July 2022. Kistos rejected this proposal a week later.
Finally today for the first time shareholders are told of Kistos's new takeover proposal for Serica.
This all feels highly unusual and it seems astonishing that over a 2 month period, the board of Serica Energy (LON:SQZ) have both received and rejected a takeover offer as well as making their own rejected takeover offer without at any point considering it appropriate to inform the owners of the business.
Re Kistos (LON:KIST) and Serica Energy (LON:SQZ) this seems to be turning into a battle of the Chairmen, both very respected operators in the business but Serica's offer to takeover Kistos at a 4% premium and fire all the Kistos execs seems laughable.
Smacks of the need to do something to keep their shareholders at bay. Not a serious offer at all. But I do see merits in a merger and a possible entry into the FTSE 250.
I think it was meant to be laughable .... insulting even!
Totally (LON:TLY) - looking very promising with finals released today.
Cash of over £15m, 8p per share, I’d expect more acquisitions this year.
Revenues and profits up as well as the dividend and cash.
With the NHS so far behind this year in appointments I only see Totally (LON:TLY) continue to have a strong few years ahead.
Technically it has fallen back to support of where it last broke upwards. Looks to be a cup and handle formed on the daily and weekly. Broker target of 75p looks very possible imo.
gmtrader
I noticed that Stonehage Fleming Investment are a major shareholder in both Totally (LON:TLY) and in Synectics (LON:SNX) (which you mentioned earlier). Is this just a coincidence?
yeah I think it is.
Maybe they think both companies are in a good position to benefit from coming out of lockdowns.
Had a look at Totally (LON:TLY) results and these seem to be way below forecasts according to Stocko figures. They had net profits forecast of £3.30m and EPS of 1.86. In April management forecast EPS of 2p, actual is only 0.59p.
I note from todays broker report : Adjusted PBT was 43% ahead at £3.7m and adjusted EPS was 28% ahead at 1.92p. £TLY
Totally (LON:TLY) Yes, the problem is that most analysts forecasts are for adjusted eps and some companies give these in the headlines at the top of the report and others bury them in notes to the a/cs. Totally does neither! Allenby says the results were "ahead of our revised expectations" - true except for eps where they forecast 1.99p and it came in 1.92p due to the tax effect. The previous year there was a £0.3m tax credit but last year a deduction of £0.2m. They estimate tax neutral this year and the next two.
There is a presentation on IMC tomorrow - a good chance to raise this.
The summary of the BRS-KPMG Retail Sales Monitor report for June makes for a depressing read: https://brc.org.uk/retail-insi...
Quite what this means for companies serving the retail sector is something I'm going to have to get to grips with. In particular, the effect on middle-income households and where they allocate their discretionary spending, if they have any left after energy and inflation are taken into account.
I think retail reports need to be read terribly carefully.
People mix up volumes, prices, and value.
With higher inflation, we should expect higher prices, lower volumes, and maybe mildly higher value. Let's see.
Sosandar (LON:SOS)
Havent really looked through the numbers but top marks again to this company ref reporting transparency - they have gone from somewhat sketchy at best to being model of simplicity and clarity for others to look at.
Update today
The current financial year has started strongly and we are trading in line with our expectations for full year growth. As we are well practiced at, we will continue to manage the business carefully, building our partnerships and growing our existing customer base whilst remaining cognisant of the external environment.
* Sosandar believes that market expectations for the year ending 31 March 2023 are currently revenue of GBP42.5 million, an EBITDA of GBP2.2 million and PBT of GBP1.9 million.
Thats how its done peeps not exactly complicated is it !!
Sosandar (LON:SOS) (I don’t hold but have in the past) Not top marks from me, the sales numbers are nothing without the returns info… they make this really hard info to find. Actual numbers are not given but buried near the bottom of the report you are given an assumed percentage of 45% Very quick to give you all the positive numbers and incredibly upbeat read, but the cold facts are what we need not a sales pitch.
Hi TStubbs,
the sales numbers are nothing without the returns info…
But sales numbers are net of customer returns, so what's the problem?
It all flows through to the bottom line, so if they're making a profit (which it is now, in the most recent 9 months or so), then the business model works, regardless of what the returns rate is.
45% customer returns is pretty normal for the sector.
SOS will have included this returns rate in their forecasting, so the c.£2m expected profit this year allows for customer returns, it won't be a surprise.
I discussed this with Quiz (LON:QUIZ) (I hold) recently, and they said the high returns rate isn't viable for lower cost companies, but is fine for higher priced companies. Also, it's reckoned that some sort of charges for customer returns is now the way the whole sector is likely to go, for online. Maybe not a postage charge, but an administration fee of some kind, deducted from the refund. It will be interesting to see how trading standards, and the courts regard this?
I spoke to Seraphine (LON:BUMP) (I hold) recently too, and interestingly they said they see free customer returns as a key customer service point. Given its high average transaction value, and very high gross margins, BUMP can afford free returns. Some other online fashion businesses may not.
Good point to raise though, as this is a key issue for the sector as a whole.
I wonder if a review of customer accounts might be a good way to tackle it - i.e. close the accounts of unprofitable customers, who over-order, then send back most of the items. Although that could set off a storm on social media & review websites, so it's a tricky one.
Regards, Paul.
Boohoo are now charging £1.99 deducted from the refund for returns.
The problem with online is people buy in lots of different sizes to get the best fit and look for themselves. This is understandable considering they can't try anything on before buying it.
So, I think it's imperative and sensible for online fashion companies to charge for returns deducted from the refund.
Well done Boohoo.
Hi Paul, thanks for your review of sos, it does indeed look like a terrific result. Some of this growth must be coming from new channels ? like next website or m&s site, I admit I don't know where exactly they're listing. In which case that'll be a one off ? However, I noticed since the fd changed a few years back that they suddenly became very canny about their on line advertising spend, and only spend in ways that get a decent return. since then we've had a pretty solid set of results. It's somewhat frustrating though that a share that touched 30 p in April trades below 20p a couple of days after this kind of update !! But then I suspect the smart money has cashed out in significant proportions, and will buy back in when things are clearer. I fear for the worst I must admit. Lets hope for the best. With high inflation, cash doesn't seem such a good option either.
Sosandar (LON:SOS) (no position)
Hi Kenobi
I made a rough estimate of Sosandar.com sales vs those from 3rd party platforms based on the sosandar.com-only KPI's provided.
Here are my results:
In the call management confirmed my 3rd party sales workings in yellow ("just under 30% for the full year & 1/3 of sales in H2.")
There's been impressive growth in 3rd party sales (since launch in August 2020 I believe), however, even the direct website sales growth is looks very good, and against strong comparatives too.
---
I couldn't find much to fault in the numbers, but I remain on the side lines as I still don't fully understand how they're doing it.
How can this tiny player in such a vast market be managing inflation, supply constraints, increased CPMs, etc... when all the bigger players say they are struggling?
The company said that one of their key strengths was that they now ship by sea, hardly a cheap logistical solution over the last couple of years, even when compared to air freight 2 years ago:
"During the year, a larger proportion of stock has arrived using rail, road and sea which are at reduced cost compared with air resulting in gains to the gross margin."
---
I also couldn't find much in the way of instagram/tiktok marketing, with the former bringing up fewer liked/tagged posts than I recall when I did research on this a few years ago.
A back link checker shows that their 2nd highest traffic driver was www.clippergroup.co.uk, something which doesn't really conform with their non-remunerated influencer traffic driving claims.
(I used https://ahrefs.com/backlink-ch... to research backlinks.)
---
One final observation. I was actually quite unimpressed with the founders during the call. They seemed to defer most numbers based questions to the CFO.
That's of course fine for something very specific, but some of the questions were quite simple and ones I expected a CEO to be able to answer themselves.
eg there was a question, which was passed onto the CFO, on whether the company will break even in the current financial year. This is simple stuff.
(it's around minute 9:00 in the call.)
---
It would be great if the company provided more information on marketing, logistics and 3rd party platform costs as they grow in importance.
Without this information I feel that it's quite hard to make a firm conclusion, irrespective of the numbers, which, as I mentioned before, do indeed look very good for last year.
A
I do like these updates but I take issue with constant comments like "the PE is 10 and this is cheap". In a falling market with inflation going crazy and serious economic and geopolitical issues ahead a PE of 10 is not cheap. PE 5 is cheap but I can see many many good companies rerating down and they will go way below PE 10.
Agree. Just because something is cheap, it doesn’t mean it can’t get cheaper. Market conditions are not good and lots of stocks are in the bargain basement. It’s a great time to be building an income portfolio if you have cash.
I think something's cheap, you don't. That's fine, different opinions are what makes a market.
In the case of Sanderson Design (LON:SDG) (I hold), I think it's cheap because -
Trading is resilient, as revealed today - profits not falling.
Balance sheet very strong, so no risk of dilution/insolvency.
High end customers are still spending, and don't care about the electric bill.
I look long-term, and accept that profits are likely to dip this year & next year, for many companies, but are then likely to recover, as always happens for decent companies. So a PER of 10, in a tough year, would likely become a PER of 5 in future - so it might already be at your target valuation, looking forwards.
SDG indicated in a previous webinar that it has pricing power, and passed through a (from memory) either 7% or 9% price rise in Feb 2022. It also said price rises are being implemented twice per year from now on.
Licensing revenues are pure profit, and tend to be more valuable than trading earnings, and SDG has a strong licensing stream, which it confirmed today is doing well.
The back catalogue is arguably very valuable, and is huge. That's what drives the licensing revenues, things like William Morris designs, which SDG owns.
Takeover potential.
In conclusion then, I think it's far too simplistic to just say oh it's cheap because it's on a PER of x or y. Surely we have to blend together lots of different factors, and come up with an overall view on valuation.
I only think SDG is cheap because there are so many positives, as listed above.
By contrast, I think the £CER is maybe not cheap, but justifiable value on a PER of nearly 30, because it's growing so well, and winning impressive, long-term recurring revenue contracts.
I'd be surprised if you're able to buy quality companies with net cash balance sheets, on a PER of 5! Maybe you're channeling 1974? But you could be right, if the world really does go t@ts up. Or it might not, as we discussed yesterday, the factors driving inflation higher are already turning down. So it could wash through, and end up back to normal conditions maybe in 2023 or 2024? Nobody knows.
All interesting to discuss though, so thanks for your thoughts!
Regards, Paul.
I'm curious - how long can a company "own" a design like Sanderson own William Morris designs? William Morris died over 120 years ago.
Copyright duration is 70 years from death of creator (as is Design protection for works deemed to have "Artistic Craftsmanship").
However, this is what the Sanderson Design (LON:SDG) website says about their Morris & Co. designs "Always guided by Morris’s creative intuition, designs are inspired by treasures in our Morris & Co. archive, which houses historical log books, samples of every wallpaper, printed and woven textiles and original wooden printing blocks. "
I haven't looked into this in detail, but this suggests to me that they are creating new designs, inspired by their owned collection of Morris & Co originals. This could include applying existing patterns to new products. They will have unregistered rights (incl Copyright), and will probably be filing registered designs for, their newly created designs.
The above is, of course, not legal advice!
Thanks Glorenfeld. I should explain I don't hold Sanderson Design (LON:SDG)
I tend to be mostly in cash at the moment as it is hard to predict with an in line trading statement whether the company is just behind the curve. With Sanderson Design (LON:SDG) if they have pricing power and have passed on 7-9% inflation then shouldn't revenues be up strongly and EPS stable?
A broadly inline statement should imply either they cannot pass on cost inflation or their sales have taken a hit. I read this as saying their sales are down but not to worry as they are making cost savings to keep the bottom line intact.
Hi grazza,
With Sanderson Design (LON:SDG) if they have pricing power and have passed on 7-9% inflation then shouldn't revenues be up strongly and EPS stable?
Good question.
I don't know, is the honest answer.
I'm working on the assumption that higher selling prices, will inevitably mean a reduction in volumes.
We're in a period of discovery right now, where we'll find out how elastic demand is, at many companies.
Some will be able to increase prices and see little reduction in demand. Others won't. It's a total mystery right now.
Regards, Paul.
Some will be able to increase prices and see little reduction in demand. Others won't. It's a total mystery right now.
We're about to find out very soon with the US July results season upon us. It's pretty much the first full quarter since inflation really took off including effects of the war in Ukraine. So far so good with PepsiCo reporting strong figures today and showing strong pricing power (it raised prices 12% last quarter).
We'll also be getting half year results for UK companies with December year ends over the next 6 weeks or so. Should be interesting...
All the best, Si
Paul,
My recollection is that the archive catalogue that Sanderson Design (LON:SDG) hold, Morris, Sanderson et al was valued at 92p per share. This was at the back end of its life as Walker Greenbank and just before Lisa Montague's appointment.
I have just added a few at 107p, cognisant of the fact that it may well go lower. We shall see.
All the best
Hi RCTurner,
Just to correct what you said in your comment. You said -
"the PE is 10 and this is cheap".
You put that in quotes. Yet it is NOT a quote. I did NOT say that at all. So it is a false quote. If you put something in quote marks, it has to be accurate.
This is what I actually said -
"My opinion - looking back at last year’s results, its adj EPS was reported at 13.75p. So it sounds like we might be heading for something similar this year, hence at 122p per share, the PER looks below 10. That’s cheap, for a decent quality, niche business, with pricing power, and lots of heritage brands. Also a superb balance sheet, so no dilution or solvency risk."
We all have to get things right.
Sanderson Design (LON:SDG)
"Overall, trading at the Company in the financial year to date is broadly in line with the same period last year and profits remain on track to meet the Board's full year expectations.
Paul
Slightly below last year then. Although the broker consensus figure on the StockReport shows a rise in normalised EPS from 12.6p last year, to 14.1p this year, which doesn’t seem realistic to me, given the macro situation. It’s also not consistent with what the company says today, about being slightly below (“broadly in line”) last year.
I guess technically its plausible that they could be slightly behind last year now but still be expecting to end the year ahead - ie sort of second half weighting or first half last year being harder to beat than second half this year. So not necessarily anything inconistent IMHO - but slightly annoying that they didnt clarify by confirming what year end market expectations are that the expect to meet them and that they are better than last year and as stocky state now.
Obviuoysly there is the knock of effect ref folowing year if they do fall short. So as you say all slightly annoyingly vague when there was no need to be IF they are still on target "for now".
Either way still an easy hold at current prices for me while now material worsening of expectations.
I’m with Paul on Sanderson design .
It only just “made the cut” in terms of shares fo hold.
Clearly looks vulnerable to a downturn but that William Morris archive and the licensing revenue generation and increase is a real potential gold mine .
Licensing revenue is clear profit and if it increases will really increase overall margin.
And once recurring licensing revenue reaches a certain level the company becomes a nailed on takeover target , owning such a strong brand and portfolio with enough recurring revenue that it justifies the buy and the manufacturing operation is almost for free .
I would personally then farm out / sell / get rid of the manufacturing / distribution operation and they would become a royalty payee .
Then you are left with the simple task of collecting revenue and building your brand .
What’s the tipping point ? I’d say if annual royalty revenue reaches 10 million then this becomes a formality .
Not sure where it it up to right now ?
Creightons (LON:CRL) - hmm, maybe I'm not keeping track of things well enough, especially as this company doesn't have any forecasts, but I was pretty surprised to see the dividend held back given how small a payout they do. However I can see the justification given how much cash they have laid out over the last 12 months on acquisitions. They've gone slightly net debt instead of net cash, hopefully this year's sales will put them in a net cash position again although the narrative talks of further acquisitions as they try to hit their arbitrary £100m sales target, so maybe not.
The recent fall off in share price makes more sense now, I guess someone is better than me with a calculator and worked out the fall in EPS from the interims as I'm sure it wouldn't be caused by some people having more access to privileged information.
Can we please pester Creightons to give some forecasts, whether they be via broker or their own via RNS. Maybe a question PIWorld can put to them?
With you on this JP. This as come as (another) unpleasant surprise.
My notes on Creightons (LON:CRL) this morning in case helpful to others:
No outlook given (as per normal – but often they provide more detail in the results presentation next week) but given the economic outlook people will assume a poorer revenue outlook.
I really like Creightons (LON:CRL) as a business but have sold out this morning as the combination of rising admin costs and economic outlook doesn't bode well for this company. I will look for an opportunity to buy back in when the share price better reflects current risk.
At the webinar next week it would be great to find out if they hedge their energy costs at all and whether they expect these to go up further towards the end of the year.
Good morning all,
Good set of finals from Totally (LON:TLY) this morning. Doubling of divi, increase in cash despite acquisitions and positive outlook.
I hold.
good news for Serica Energy (LON:SQZ) shareholders takeover rejected
$SQZ Kistos wanting merger with SQZ see KISTOS rns
and it now looks like Serica also made a counter offer for Kristos......the offers both ways have been rejected
Sosandar (LON:SOS) (I hold) - your comments on today's Final Results would be much appreciated.
Sosandar (LON:SOS) +1.
I thought the results were encouraging, 9 months of profitable trading according to the narrative and a full year of profitable trading is being predicted. I'm nervous about the economy having an impact on their sales in H2 but they sound confident at this stage of the year. Forecast P/E of 22 probably somewhere between about right and touching on a bit rich given the macro picture.
Held these for years, can't see any reason to bail out on them now.