Smith & Nephew remains hip

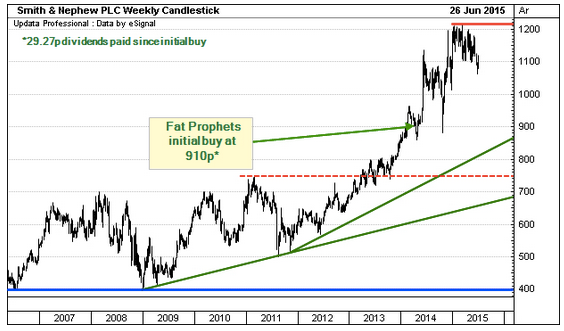
Smith & Nephew is the UK’s largest listed medical equipment company and is known for its hip and knee implants. The group has been moving into higher growth areas and undertaken a number of acquisitions. Smith & Nephew has long been viewed as a takeover candidate with Stryker recently showing interest.
In 2011 Smith & Nephew teamed up with Billie Jean King to highlight the impact of her double knee replacement. The former tennis world No. 1 stated in a press release that: “I feel like I’m 20 again, and I’m back on the courts playing tennis.”
Ms King benefited from Smith & Nephew’s Legion knee with VERILAST Technology. At the time this was the only technology tested for 30 years of wear performance and as such was expected to provide 30 years of active mobility.
With an ageing global demographic demand for hip and knee replacements is set to increase. Smith & Nephew is also benefiting from increased demand in emerging markets and a strategic shift towards higher growth areas.
Smith & Nephew’s growth drivers

Source: Smith & Nephew investor presentation
Healthcare can be an attractive area to invest, as it is defensive and healthcare spending increases over time. However, pharmaceutical & biotech firms have drug development uncertainty and are faced with ongoing patent expirations.
The healthcare equipment & services sector offers a lower risk way to obtain healthcare exposure. Smith & Nephew is the UK’s largest listed medical equipment group, with a £10bn market value, and was founded in Hull in 1856.
Smith & Nephew and Healthcare M&A
Smith & Nephew has been topical due to takeover interest from US rival Stryker in mid-2014. Stryker had been in the early stages of considering a takeover but was forced to abort its plans following a media leak.
Under UK Takeover Panel rules there followed a six-month period in which Stryker was unable to make an offer. This ended in December 2014 but a recent US$2bn share buy back from Stryker suggests that its interest may have waned.
The bid premium in Smith & Nephew’s shares has therefore fallen back but Stryker may return at some point. Other candidates to takeover Smith & Nephew include the US pharmaceutical giant Johnson & Johnson.
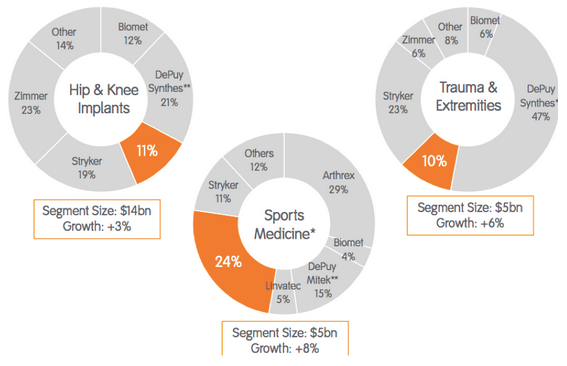
Combining with Smith & Nephew would increase Stryker’s market share in Hip & Knee Implants, Sports Medicine and Traumas & Externalities. With ongoing healthcare consolidation Smith & Nephew remains a potential target.
2014: Smith & Nephew would boost Stryker’s market positions
Source: Smith & Nephew investor presentation
Smith & Nephew 101: moving to higher growth areas
Smith & Nephew’s business two business areas are Advanced Surgical Devices (ADS) and Advanced Wound Care (AWC). ADS generated 71% of revenue in 2014 and 77% of trading profits while AWC generated the remainder.
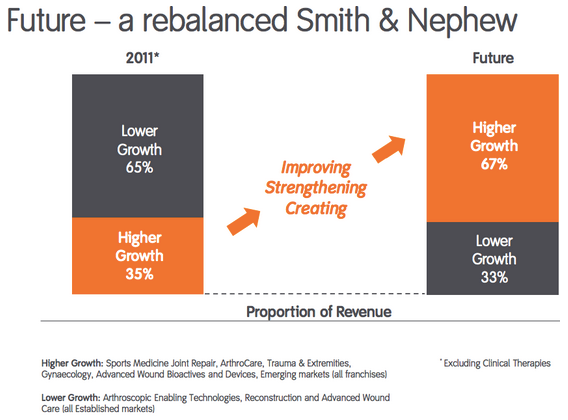
The group is looking to move to higher growth areas, which in 2011 were only 35% of revenue. The target is to lift this to 67% with growth areas including emerging markets, traumas & externalities and sports medicine joint repair.
In line with this goal the group bought Arthocare in May 2014 for an enterprise value of US$1.5bn. Arthocare is described as a higher growth medical device company with a complementary sports medicine portfolio.
Source: Smith & Nephew investor presentation
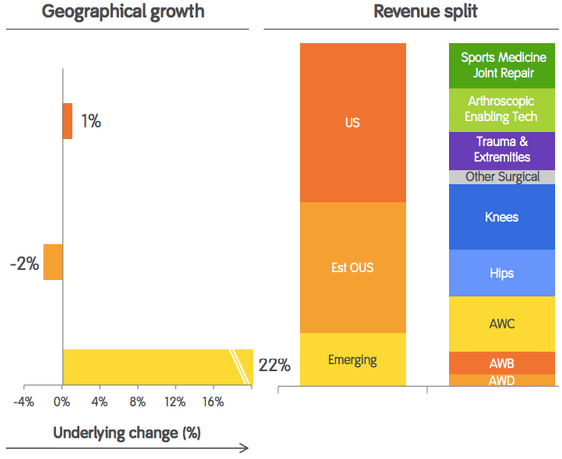
In terms of the geographic mix the US generated 43% of revenue in 2014 and established markets outside of the US (Est OUS) contributed 42%. The remaining 15% of revenue came from emerging markets & International markets.
Emerging markets & International markets have been the main driver of growth with 22% underlying revenue expansion in Q1 2015. The US only saw 1% growth and markets outside the US saw a 2% decline.
Smith & Nephew revenue mix in Q1 2015
Source: Smith & Nephew investor presentation
Financial performance: slow and steady
Smith & Nephew has seen underlying revenue increase by 16% from US$3.96bn in 2010 to US$4.6bn in 2014. Underlying adjusted earnings per share rose by 13% in the same period from US$0.736 to US$0.832 in 2014.
This represents slow but steady growth with underlying revenue in the whole of 2014 up by only 2%. The trading profit margin improved to 22.9% last year, which helped boost underlying adjusted earnings per share by 8%.
As Smith & Nephew shifts towards higher growth areas the underlying growth rate for revenue and profits should improve. The near-term momentum will be supported by the takeover of Arthocare and the shift towards emerging markets.
Summary and valuation
Smith & Nephew is aiming to improve its growth rate by focusing on higher growth product lines, emerging markets and acquisitions. Global healthcare demand is also underpinned by the ageing global demographic.
Turning to the valuation and Smith & Nephew trades on 20X forecast earnings for 2015 which falls to 18X for 2016. The steady underlying business growth sees the ratings fall to 16.5X in 2017 and then 14.2X in 2018.
Net debt increased to US$1.6bn at the end of 2014 from US$0.253bn at the start of the year due to the Arthocare takeover. This is a modest net debt to EBITDA ratio of 1.2X and with excess cash the group has been buying back its shares.
With the number of people in the world aged over 65 set to triple by 2050 to 1.4bn the long-term prospects are strong. As such the valuation is reasonable, in our view, and Smith & Nephew remains a potential takeover candidate.
This report was produced by Fat Prophets Senior Analyst, Andrew Latto
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
2 comments
Replying to a 5 year old post but still good info. S&N has long been on my radar but looking a bit cheaper now... got me thinking.
Price looks a bit high at 1680p with a p/e of 20.4. Anyone know what is going on to push the price up.