Stock Brief - BP (LON:BP.)
After the onset of the Covid-19 pandemic in 2020, global primary energy consumption witnessed its largest decline since 1945. Oil prices turned negative for the first time in history, reaching record lows of -$40 a barrel. The result was that BP ended the year with $20 billion worth of losses, a growing debt pile, and a precarious outlook.
However, a swift global economic recovery, fueled by record stimulus packages, has seen a remarkable restoration in oil and gas demand. OPEC has intervened to maintain tight control over supplies over the past year, and it now appears as though the oil market has stabilised at a much higher level today, with Brent oil currently trading at over $80 a barrel.
At these elevated prices, BP generates substantial amounts of free cash flow. The company is now paying down debts whilst simultaneously increasing dividend payments to shareholders and carrying out substantial share buybacks to the tune of $1 billion per quarter (as long as Brent remains above $60 a barrel).
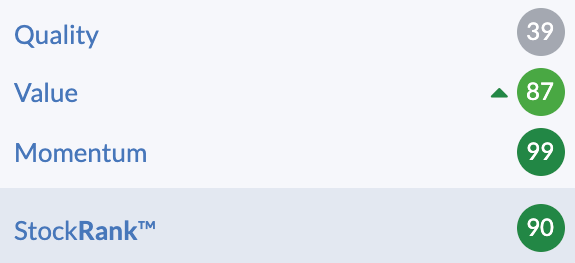
Despite the impressive financial performance this year, and the recovery of oil prices to beyond pre-pandemic levels, BP’s share price has lagged behind. The company now trades on a forward PE ratio of 6.6 and pays out a forward dividend of just under 5%.
Profile
What are the company's principal business activities, how does it generate its revenues?
BP is one of the largest integrated energy businesses in the world, with operations in over 70 countries, across 6 continents. The company’s primary source of revenue generation still comes from Oil & Gas production, with the company producing just under 3.5 million boepd (barrels of oil equivalent per day) in 2020.
BP is currently organised into four business groups: Production & operations, Customers & products, Gas & low carbon energy, and Innovation & engineering.
Production & operations - At the heart of BP lies its P&O division, where it seeks to discover and develop hydrocarbon resources, operate oil and gas production assets, as well as refineries, pipelines and terminals around the world.
Customers & products - Is focused on innovation in order to grow the company’s convenience and mobility offering to a wider range of customers. The division looks after Castrol lubricants, aviation fuelling, and mobility and convenience as well as fuels
Gas & low carbon energy - The company is seeking to further develop its existing natural gas capabilities with significant growth in low and zero-carbon businesses and markets. This includes: Biofuels, Onshore Wind, Offshore Wind, Solar Energy & Hydrogen.
Innovation & engineering - The smallest division, Innovation & engineering (I&E), is responsible for overseeing all central engineering and safety & operational standards. The technical expertise within these teams also plays a key role in part of the strategy to accelerate energy transition to net zero.

Source: BP Annual Report 2020
Size, Sector & Exchange
BP is one of the largest companies to trade on the FTSE 100. At the current share price of 344.5p, the company is valued at just over £67 billion. The company operates within the Oil & Gas industry, within the wider Energy sector.
Business strategy
BP’s business strategy now centres around ‘performing whilst transforming’. The company has recognised the need to develop a strategy that will see it ‘pivot from being an international oil company focused on producing resources to an integrated energy company focused on delivering solutions for customers’.
With this new sustainable approach in mind, the company is increasing the proportion of capital investment into its non-oil and gas businesses. It expects to spend 40% or more of CapEx on low carbon electricity and energy, and customer convenience and mobility by the end of the decade. This will see investments in these areas grow from $500 million today to over $5 billion from 2030.
The company’s strategic partnership with Equinor to invest $1.1 billion for a 50% share in two offshore wind projects in the US, that will be able to power over 2 million homes, is testament to this change in focus.

Source: BP Annual Report 2020
Overall, BP aims to have developed 50GW of renewable energy generating capacity, or enough to power the needs of 36 million people by 2030 vs. the 2.5GW available today. Investments into bioenergy, core hydrogen markets, electric vehicle charging points and building energy partnerships with big cities across the world also form part of this new business strategy.
BP will simultaneously reduce oil & gas production as more of its renewable energy projects start to come online. The company expects to reduce its oil and gas production by over 40% in the coming decade and carry out no further exploration in new countries. It has even committed to becoming a net zero company by 2050 or sooner.
History & Growth
BP’s history can be traced back to 1908 with the discovery of oil in Persia. The company, then called the Anglo-Persian Oil Company, has since developed over the years to become one of the largest oil and gas producers in the world. BP boasts significant onshore to offshore reserves, and has started its next transition towards a lower carbon future with investments into new renewable energy sources.

Source: bp.com - Our History
Recent News
Q3 Results 2021 - BP reported a strong set of results during Q3, as it continues to benefit from elevated oil & gas prices and higher refining availability. Financial highlights included:
- Underlying replacement cost profit of $3.3 billion, compared with $2.8 billion for the previous quarter.
- Reported loss for the quarter was $2.5 billion driven by significant adverse fair value accounting effects of $6.1 billion pre-tax charge. Under IFRS, reported earnings include the mark-to-market value of the hedges used to risk-manage LNG contracts, but not of the LNG contracts themselves. This mismatch at the end of the third quarter is expected to unwind if prices decline and as the cargoes are delivered. The underlying result is adjusted to remove this mismatch.
- Operating cash flow of $6 billion.
- Divestment proceeds of $5.4 billion in the first nine months, expected proceeds of $6-7 billion for 2021.
- Net debt fell to $32 billion at the end of the third quarter.
- Further $1.25 billion share buyback planned.

Source: BP Q3 report
Chief executive officer, Bernard Looney, commented: “This has been another good quarter for bp - our businesses are generating strong underlying earnings and cash flow while maintaining their focus on safe and reliable operations. Rising commodity prices certainly helped, but I am most pleased that quarter by quarter, we’re doing what we said we would - delivering significant cash to strengthen our finances, grow distributions to shareholders and invest in our strategic transformation. This is what we mean by performing while transforming.”
Catalysts
Trends & Events
The supply and demand dynamics of the oil and gas industry are ever evolving. Unforeseen shocks can make it difficult to accurately predict where prices will trade, but the current dynamics seem favourable for major oil and gas producers, such as BP.
Demand
Oil demand is expected to remain buoyant in the short/medium-term. Crude oil prices have continued to climb over the past year as a result of steady draws on global oil inventories.
The fundamental long-term demand drivers are expected to come from emerging and developing economies, underpinned by rising populations and incomes. Asian oil demand is forecast to continue its rise, albeit at a slower pace than in the recent past. By 2026, global oil consumption is projected to reach 104.1 mb/d, representing an increase of 4.4 mb/d from 2019 levels.
However, the Covid-19 pandemic combined with the rapid change in government attitudes towards a low-carbon future have shifted demand expectations for oil consumption over the next 6 years. Behavioural changes, such as work from home, and accelerated investments into renewable energy projects could mean oil demand has peaked sooner than we expected.
Supply
After the oil price plummeted in 2020, producers were forced to hold back spending on development projects. During the year, they spent one-third less than originally planned. In 2021, overall investment is only expected to rise marginally.
The spending cuts and project delays have ensured that supply growth remains tight across the globe. Oil production capacity is predicted to increase by 5 mb/d by 2026, but would need to rise 10.2 mb/d by 2026 to meet the expected rebound in demand.
However, in the shorter-term, oil prices are expected to subside as production growth from OPEC and US producers outpaces demand growth in 2022. The US Energy Information Administration sees Brent prices declining from current levels to an annual average of $72/b next year.
Risks
What risks does the business face?
Operational - There are few industries more operationally challenging than oil and gas producers. BP will always be prone to natural disasters and extreme weather, which heightens the risks of technical integrity failure. The Gulf of Mexico oil spill, in which the company still paid out $1.6 billion worth of damages last year, highlights this risk.
Macroeconomic - Despite being a major oil and gas producer, BP is still reliant on market forces that determine the prices. The oil price is notoriously volatile and affected by a multitude of factors such as global economic health, political developments, and OPEC. The fluctuations in oil prices make it difficult to accurately forecast stable and consistent earnings for BP.
Diversification - BP remains focused on its ‘transforming while performing’ strategy to accelerate its shift towards renewable energy production. This is a necessary move for the company and will appeal to ESG investors. However, with diversification and transition comes risk. Renewable energy still remains a less efficient and therefore less profitable form of energy generation than traditional hydrocarbons. As the company aims to reduce oil and gas production by 40% over the decade, its bottom line may be negatively impacted by this move.
Summary
Bull points
Generating huge amounts of free cash flows at current oil prices, ongoing global demand for oil despite growing ESG pressure, carrying out share buybacks to the tune of $1 billion per quarter and returning 5% in the form of dividends, diversifying asset base should lead to less oil price vulnerability in the future
Bear points
Vulnerable to oil and gas price fluctuations, large debt pile as a result of the pandemic ($32 billion as at end of Q3), potentially risky strategy to focus so much investment on renewable energies that may be less profitable for the company (especially at a time of elevated oil and gas prices)
Overall, it seems as though BP is currently unloved by the markets despite its rapid change in fortunes. Over the past year, the company has proven that it can deliver on its strategy: divesting legacy assets, investing in renewables, and returning substantial free cash flows to shareholders in the form of buybacks and dividends, all whilst strengthening the balance sheet.
With a promising fundamental supply and demand backdrop, it will be interesting to see where the BP share price goes if oil prices continue to hold up around the $70-$80 mark over the next year.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

27 comments
BP doing well , seems to have broken above resistance level...same with RDSB, and Bank shares
I bought more £BP shares (I was already holding it since 2017) when it went down to 182p during first wave, just on the basis that
I think it will much longer than 15 years, I can’t see countries such as India using mostly electric cars by then, yes US and Europe may have mostly switched over by 2036. Also what about aeroplanes, ships etc?
Also oil is used to produce many other products.
I thought there be more mention of gas, I don’t know how much gas Bp (LON:BP.) Produces but with the current prices, they must making considerable profits from gas. I read an article on Royal Dutch Shell (LON:RDSB) which said about 20% of their profit increase in 2021, was due from gas, these were pretty rough figures mind you.
I had been selling some of my Bp (LON:BP.) as l thought oil prices were near the peak but I may buy some back if they fall below 300p.
Interesting analysis. Would be even more so if a like exercise were done for Shell. These two names are similar in many ways and represent a contrast with their U.S. competitors.
With apolgies to Keelan for tearing off on the side-track.
Do I appreciate an attempt to look closely at and assess the business situation and investment attractiveness of bigger companies? You bet I do!
Do I think Stocko pays enough attention and puts in enough effort to analysing mid/large cap stocks? You bet I don't!
Stocko is hugely frustrating in its fixation on small stocks. I will not continue to pay for this very much longer. It's a platform that has an obsession with the small-caps in which I have only an interest.
Many of your subscribers have long been pressing for change. I will be gone soon. Stocko offers me not much value.
Thank you for the above analysis.To much liquidity in the markets have led to an increase in inflation .How do the central banks control inflation by increasing interest rate .However this can destabilise the property market, which is already vulnerable due to Brexit and major banks and financial institution moving their offices to the Euro zone.Covid hasn't helped either with leisure and travel industry worst affected area.The new variant found in South Africa and Hong Kong has triggered a market crash. The new variant is as deadly as before probably not.Why?the virus has mutated to survive therefore has to be weaker than the original strain.
The Govt has managed to control inflation target (2%)by keeping the oil prices low in recent years.The single most important factor in the economy ,where oil is needed for transportation ,travelling ,manufacturing,,extraction of raw materials etc, etc.If the govt can keep price of oil low then inflation can be reduced without needing to increase the interest rate.
BP needs to survive if their is deflationary pressure on oil prices and trend to move towards cleaner sources of energy.Bp needs to reinvent itself .
How?
Need to think.
That was an excellent summary of a complicated business. Bp (LON:BP.) is a stock I have held and I have every intention of getting back into it. But I believe that we are due for a major market correction (A crash) and, so, I think that I will be able to re-enter at a price lower than it stands today. That said, it might be worth recalling what Bernard Looney, CEO of BP said in August 2021.
“ On average at around $60 per barrel, we expect to be able to deliver buybacks of around $1.0 billion per quarter and to have capacity for an annual increase in the dividend per ordinary share of around 4%, through 2025.”
To some extent, that underpins the investment case. I still think that its stock price will be hit in a market sell-off. But providing there is not a complete and sustained collapse in oil prices, it strikes me as being in a very strong position as it morphs from big oil into big energy. My understanding is that the demand for oil looks set to wane over the very long-term ie 2040 onwards. But the opposite is true of energy demand, including natural gas. I can find no evidence to support a case for falling long-term energy demand. On the other hand, there is plenty of evidence to support a dramatic fall in the search for new oil resources. Oil reserves are being depleted and not replaced.
Incidentally, I get the impression that some investors seem to believe that big oil and gas is giving way to a patchwork of small operators in a cottage industry of energy providers. In my view, whether we like it or not, the energy sector will be dominated by a small number of major players. Much like the present oil and gas industry. The capital expenditure required to provide clean and firm (Reliable) energy will be huge. And it will be very very complex with many moving parts. So, I believe, the real issue is who those key players will be? In my opinion, BP will be among that group.
Bp (LON:BP.) Shares down 7% as oil prices crash.
I would have had one of the risks as political: even with a Conservative government, I can see pressure to put in place some sort of 'excess profits' tax if oil prices remain high. You would think the example of Shell and the European Courts would be sufficient to prevent this but modern government is increasingly blown around by the winds generated by social media pressure to 'do something'
Yes that is a potential risk, and partly explains their shift to renewables - it's a PR move as much as anything and may help keep policymakers off their back if they start making massive profits.
A contrarian bet among all the hype regarding ESG!
Excellent, thanks. Good to see a larger company analysis - the lack of which is a definite weakness of Stockopedia IMO. Sounds like you are a buyer? I hold, and am leaning towards topping up.
So true. This is a the biggest stocko weakness. Small caps are such a casino, I want quality mid and large cap analysis. Too much hyping small cap stocks here.
suggest there are many other sources for large cap stocks . Personally, I am very happy for Stockopedia to concentrate on its strength in providing unmatched invaluable info on small to medium caps
Large caps are over covered elsewhere but small caps are neglected. Many small caps are less volatile than £BP share prices over the last few years. Why invest in uk large caps when they have underperformed other indexes?
I agree with pinstripe - all stocks whether small, mid or large should have a place to be discussed on Stockopedia regardless if stocks are discussed on other platforms. On Stockopedia there is almost a cult like following for highly volatile small caps partly as position taken by the company to place emphasis on small caps by using specific contributors to report on a daily basis.
I don't have an issue with regards to small or large - as a trader would be nice though to see a variety of stocks discussed.
DYOR and good luck to all
Large caps are discussed, probably the most discussed stock on here is Boohoo (LON:BOO) which is not a small cap. Still over £2Bn even after the fall. Other large caps are discussed but there seems less interest.
There has been 3 large cap articles in the last 2 weeks, Itv (LON:ITV), Burberry (LON:BRBY) and now Bp (LON:BP.)
I am always interested in reading all the different caps even though I am a technical trader. Boohoo (LON:BOO) I think graduated from the small caps report as reason for being discussed so much (along with all the fashion type retailers).
Boohoo (LON:BOO) was a large cap until recently, so has no place on the Small Cap Value Report.
Other large caps don’t seem to attract much interest. Why should Stockopedia focus more on large caps, when there is more interest in mid and small caps.
There are a lot more small and mid caps than large caps as well. Proportionally large caps probably do get a similar coverage.
Looking at the discussion board, large caps hardly any posts, small caps generally a lot more posts. Burberry (LON:BRBY) only 6 comments, Itv (LON:ITV) 3, Phoenix Copper (LON:PXC) 72.
I get it you are not interested in mid / large caps that's fine. I am interested and happy when commentary is provided for all the different caps. I like reading about the overall picture of our stock market.
I’m interested in them, I hold quite a few, even Bp (LON:BP.), I hold less small caps, than mid/large caps. So you don’t get it. As I said there are far small and mid caps than large caps.
There is actually nothing to stop you posting about any stock on the daily thread provided by Paul and Jack. Obviously, you can't expect Paul and Jack to respond but there are posters who will respond to genuine news with regards to results, trading updates etc.
The likes of Royal Mail (LON:RMG) have appeared on those threads recently.
Hi letap73 - that is a thread dedicated primarily to small caps and I do enjoy reading the expert analysis. All that I said is that I enjoy reading about all cap sizes so not to discourage from experts to continue to write about BP etc in the future.
It might actually be worth suggesting that a large/mid cap daily thread be put up - the opening post could be in the style of a Mr C post? The analysis would then come from regular posters.
It also might be worth remembering that many large/mid-cap UK listed companies are small by international standards. A broad generalisation, I know, but I get the impression that most small quoted companies remain small and that's a global phenomenon. While large public companies are often simply getting larger.
In the UK, large companies don't often grow that much, that's why the FTSE100 in the last 20 years has hardly gone up at all. The growth in the UK is in small to mid caps not large caps.
In the US is a different picture.
I'm really looking for small companies that will grow into large companies, a few that have done that are: Fevertree Drinks (LON:FEVR), Burford Capital (LON:BUR), Boohoo (LON:BOO), Future (LON:FUTR), £AHT and £JD.
Hi Berksbee,
Thank you for your feedback!
We are always looking to provide more comprehensive coverage of the markets, so we're glad to hear that you are enjoying the mid/large-cap company analysis articles!
I personally don't hold a position in BP at this time, but if oil continues to hold above $60 in the coming months I think Oil & Gas majors such as BP would make a good addition to the portfolio.
Hope you have a nice weekend!
Kind regards,
Keelan