Stock Brief - Novacyt (LON:NCYT, EPA:ALNOV)
The Investment Case (or not)
After a rollercoaster 12 months, Novacyt shares are currently trading at £3.08, having peaked at a price of £12.76 towards the end of January 2021.
As an international specialist in clinical diagnostics solutions, Novacyt was one of the first companies globally to respond with an accurate and certified Covid-19 test in January 2020 . This first mover advantage has transformed the company’s fortunes and revenues and profits have exploded over the last year.
However, a dispute with the Department of Health and Social Care (DHSC) has overshadowed much of the progress the company has made over the past 18 months. The uncertainty around this dispute, which was announced in April 2021, relates to a second supply contract with the DHSC. This has had a notable impact on its Q4 2020 and Q1 2021 revenues and inevitably, the company’s share price.
Nonetheless, Novacyt has built a reputation for itself as one of the best in class in the diagnostics field. The company is now well-established, with a significant global base of over 400 distributors and is building a direct presence in the US and in key European markets. A £90+ million cash hoard has enabled the company to also further its research and development capabilities, and it now houses its own clinical trials team.
It’s been a whirlwind 18 months for Novacyt, but the company has built solid foundations on which it can transform itself into a diagnostics leader in a rapidly growing high-margin industry. However, with Covid revenues starting to subside and investor sentiment weighed against the company, do the risks outweigh the rewards?
Profile
What are the company's principal business activities, how does it generate its revenues?
Novacyt Group operates through 4 main subsidiaries: Primerdesign, Microgen Bioproducts, Lab 21 Healthcare and IT-IS International.
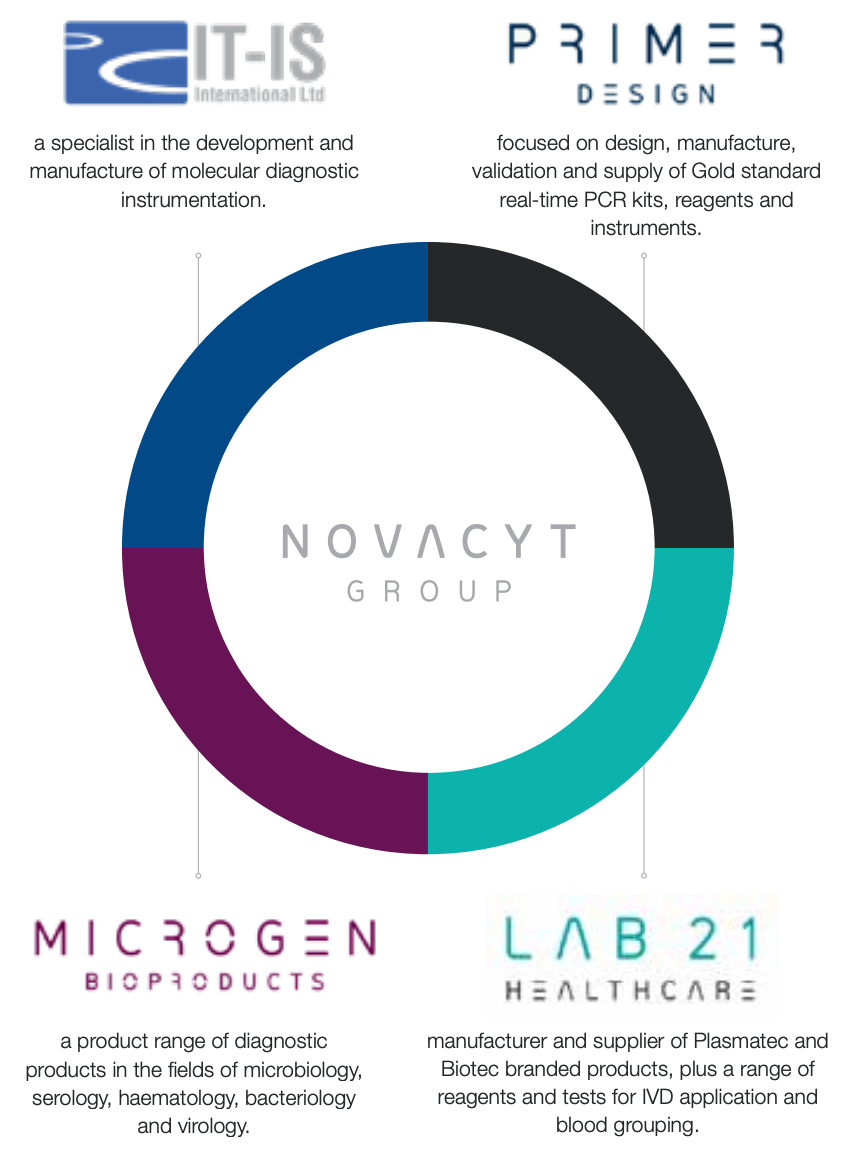
Primerdesign, which accounts for the vast majority of the group's revenues, is a world leader in qPCR assay development used for diagnostics. The company was one of the first in the world to produce a highly accurate Covid-19 test in January and quickly received CE certification and FDA approval. It has greatly expanded its portfolio of Covid-19 products over the past year, to streamline the extraction process for PCRs and make them more accessible in decentralised near-patient settings.
Microgen Bioproducts is primarily focused on the food diagnostic industry, which is essential in ensuring that food manufacturers provide consumer safe products. However, in recent years, Microgen Bioproducts has also expanded its portfolio of PathFlow Rapid Lateral Flow Tests to cater for detecting Influenza A&B, Mononucleosis, Adenovirus, Streptococcus and much more, within 5-15 minutes.
One of the smaller divisions, Lab 21 Healthcare, provides reagents and test kits for In Vitro Diagnostics and blood grouping applications, which include Infectious diseases, thyroid function and fertility products to name a few.
Acquired in October 2020, IT-IS International, is a specialist in the development of molecular diagnostics instrumentation, delivering high performing technology for real time PCR. The company is responsible for the manufacture of the agile, portable, high performing real-time PCR instruments genesig® q16 and q32 and MyGo PCR Systems.
Size, Sector & Exchange
Novacyt’s current market capitalisation sits at £219 million. The company operates in the Healthcare sector, more specifically the Biotechnology & Medical Research industry. The company is listed on both London’s AIM market and France’s Euronext exchange.
Business strategy
Novacyt has repeatedly stated its ambitions of becoming a leading mid-cap diagnostics player on the global stage. The company’s historic approach has been to focus on growing its capabilities organically, through innovation in its core areas of expertise in advanced molecular and protein detection technologies, but also inorganically, through strategic acquisitions that accelerate the company’s growth plans.

Testament to Novacyt’s ability to innovate are the 10 new products it launched in 2020, in order to support labratories and clinicians testing for Covid-19. This included developing products such as: Exsig®, PROmate®, genesig® COVID-19 HT 2.0 and Winterplex®, to improve workflow efficiency and address testing needs in both central and near-patient settings.
The company has continued to deliver on its impressive research and development stream, with the recent developments of: VersaLab™ for near-patient PCR testing in the private sector testing market, SNPsig® (including VariPLEX™) to diagnose Covid-19 variants, and the expansion of the PathFlow® lateral flow test portfolio, which now includes a rapid test for Covid-19.
Moving forward, Novacyt has earmarked 3 clear strategies for growth: Test menu expansion, Instrument expansion and Geographic expansion.
Test menu expansion will focus on developing the company’s existing Covid-19 portfolio to respond to ever changing market needs, but will also centre around Covid-19 Plus testing in adjacent areas such as the flu. Furthermore, post-Covid testing will try to address unmet testing needs beyond Covid, such as pathogens resistant to antimicrobials, sepsis and transplantation.
Novacyt has seamlessly integrated its acquisition of IT-IS International into its workflows and it plans on utilising IT-IS to provide the basis for further Instrument expansion. The company is now working on developing multiple tests (multiplexing) to run on the q16 and q32 platforms.
With the UK well covered with over 40 sales and marketing staff, Novacyt is now looking further afield as part of its Geographic expansion plans. Direct sales teams have now been established in the US, Germany and other key European markets and there have been several notable management additions in the US.
History & Growth
Established in 2006, Novacyt has seen its growth accelerate since 2014, primarily through a series of notable acquisitions. The timeline taken from the company’s website below highlights this strategy well.

Recent News
Most recent trading update
Proposed accounting treatment of DHSC dispute - On 16th September 2021, Novacyt announced that it would be making accounting adjustments for its upcoming H1 2021 results as a result of the unresolved Department of Health and Social Care dispute.
This dispute with the UK government has been going on for almost half a year now. Whilst the company still believes that it is in a strong legal position in relation to the dispute, it has decided to take a conservative approach to its reporting, which includes the following:
- Company will not recognise the H1 2021 revenue of £40.8 million from the DHSC
- Company will recognise manufacturing costs of £6.9 million relating to these disputed sales.
- Company is also taking an exceptional one-off cost of £28.9m to write down inventory that the Company had built in anticipation of further DHSC demand.
On the back of the announcement, the shares closed 5% lower and have dropped a further 5% today, so this announcement has clearly weighed on investor sentiment.
Half year update - The company recently published some strong H1 results, continuing on the momentum from the first half of 2020. Revenues jumped 50%, reaching £94.7 million in H1 2021 vs. £63.3 million in H1 2020.
Importantly, the company noted that £54 million of the revenues came from a mixture of overseas sales and increased uptake from the growing UK private testing market. This meant that the company’s non-DHSC revenues had grown 20% year on year.

In the update, Novacyt also announced a nine month supply contract of the PROmate® reagent to the DHSC. The contract could be valued at £4.7 million, although there were no minimum purchase levels specified.
Furthermore, the company announced that it had entered into a two-year Long-Term Agreement (LTA) with the World Health Organization (WHO) for the supply of its genesig® COVID-19 tests and received confirmation from UNICEF that its existing LTA with the organisation had been extended by 12 months.
The board commented the following on the results: ‘The Company expects continued strong growth in private testing as markets and travel reopen and, as the Northern Hemisphere heads into winter, the potential for higher infection rates will increase the need for COVID-19 testing. Since the start of 2020, the Company has launched 16 new CE-IVD products and expects to launch a further 10 by the end of 2022.
The Company therefore reiterates revenue guidance of £100 million for the full year, excluding DHSC revenues, as announced on 22 June 2021.’
Catalysts
Trends & Events
DHSC Dispute Resolvement - After announcing a contract initially worth a minimum £150 million in September 2020, it came as a shock when the company announced it was in dispute.
The update on the 16th September makes it appear as though the company is prudently preparing for the worst. However, should the company win its case against the DHSC, it will end up with well over half of its market capitalisation in cash.
Continued demand for Covid-19 testing - Whilst the company does expect revenues from Covid-19 testing to drop in the coming years, the emergence of new variants and drop off in vaccine efficacy will make monitoring via testing essential. Most scientists now agree that Covid-19 is likely to become endemic, in which case the revenues are likely to stay for some time.
Fundamental changes in testing and monitoring of diseases - The rhetoric from governments globally, as well as the scientific community, seems to reiterate the importance of more accurate and reliable testing across a range of infectious diseases and other key medical areas. Significant growth in the diagnostics market is predicted over the next decade, growing from $69.52 billion in 2020, to be worth $113.86 billion by 2030.

Risks
What risks does the business face?
Competitive - One of the principal risks that Novacyt faces is the rapid innovation within the diagnostics industry. Covid-19 has seen countless startups emerge, which are constantly striving to develop faster, more reliable and cheaper tests. This is not straightforward to do, but it means that there is a strong likelihood of profits being eroded over time, especially with regards to Covid-19 testing.
Operational - There have been several reports in the news about the government cutting out faulty test providers from its approved list and this is a risk that every company in the diagnostics market faces. Should the tests lose their accuracy (sensitivity and specificity) due to the emergence of new strains/variants of Covid-19, they run the risk of their tests being taken off the market.
Declining Covid revenues - Revenues are already expected to drop from £277 million in 2020 to £100 million this year, and will most likely continue to decline over the medium term.
Acquisitive - Novacyt’s management has reiterated how acquisitive growth will also form part of the company’s strategy. Whilst the company’s track record of acquisitions has been excellent, its cash pile might make it look at riskier, more ambitious options to accelerate growth, which may prove costly and counterproductive.
Summary
Bull points
Diagnostics tailwinds - The diagnostics industry is set to fundamentally change as a result of Covid-19. Testing for infectious diseases and in other areas of life such as oncology, diabetes and blood disorders will become much more prevalent.
Balance sheet strength - Novacyt has paid off all of its debts within the last year and now sits on £90 million in cash, which is the equivalent to over a third of its current market capitalisation. Acquisitions seem likely.
Unrivalled Research & Development - Novacyt’s success over the past year has enabled it to invest heavily into growing its operations, including its research and development department. The company has filed over 20 patents over the past six months and continues to innovate and expand its Covid and non-Covid testing portfolios.

Bear points
Continued uncertainty over DHSC dispute - Despite the accounting changes, the DHSC dispute remains to be resolved. This has been holding back the company and its share price for some time now, and there is no clarity or time frame on which investors can look to for guidance.
Covid-19 testing to subside over coming years - Novacyt’s management team expects Covid revenues to have a half-life every year, and this will inevitably lead to substantially lower revenues and profits.
Investor sentiment - After the DHSC dispute, and the profit warnings as a result, it seems that investor sentiment is really at an all time low. With a lack of visible near-term positive catalysts, the share price is in danger of drifting lower.
Chart technicals - From a technical perspective, the selling pressure on the back of the DHSC accounting update has caused the shares to fall back below the 50 day moving average. This is typically a bearish signal. Previous attempts to break the 50 day moving average have also failed, with most rallies being sold into. The shares continue to have significant overhead supply, with a majority of shareholders buying at higher prices. This technical overhang may continue to weigh on the shares for a considerable period and incur an opportunity cost for investors.

The Stockopedia Investment Club took a position in Novacyt in October last year, which performed exceptionally well before reversing sharply in January 2021 and triggering our stop loss. I wrote an in-depth Stock Pitch here, outlining the key findings and risks at the time. It’ll be interesting to hear the community’s thoughts this time around!
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

8 comments
An excellent, well-researched and most helpful article Keelan. Thank you very much.
Maybe a buy at some point in the distant future, when it has invested its cash pile into something revenue earning and not covid19 related. I think the bear points probably say it all
Has anybody any views on the outgoing CEO's departure and what the incoming CEO will bring to the table? It seems there is some restructuring going on at board and senior management level, but has not been mentioned in the otherwise excellent brief by @Keelan
The new boy has kitchen sinked the numbers, which has caused the latest drop, and the hope will be he can kick start the recovery from here. I have not looked into his background in any way, but I believe he has not held the top job before.
Nah, he didn't, I believe it's his first executive position at the top of the chain, but he has experience in the sector. IMO writing off the DHSC numbers it's a conservative approach which shows they are not promising anything they don't have control of. Even if they don't win the dispute, as long as the company stays on top of its R&D and focuses on the private sector it should do well, the only other big L is the opportunity cost if one has a large position in their portfolio.
It would help to have further details about the dispute &/or the prospects of compromise.
Novacyt Sa (LON:NCYT) was a small position in my portfolio at 2.3%. My timing was all wrong having made my first of 2 buys last November at 1044p.
I sold out yesterday and I did so for the very reasons Keelan has listed under bear points.
I should have sold much sooner.
This is a clear case of Mr Market looking backwards rather than forwards.
"Continued uncertainty over DHSC dispute"
Novacyt Sa (LON:NCYT) has taken the conservative step of refusing to recognise the disputed £41m DHSC revenues. Hence from here there appears to principally be upside with regards this dispute.
"Investor sentiment - it seems that investor sentiment is really at an all time low".
More great news, investor sentiment also principally appears to be a one way bet, upwards.
The fundamentals are interesting:
As for most companies, there are competitive risks, not least given Novacyt Sa (LON:NCYT) s gross margins of 71% & EBITDA margins of 43%. But the p/e of 3.4x appears to be at least in part acknowledging this.
I've had a significant loss from Novacyt over the past year however I hold because of the growth of the market expected over the next 10 years.
Novacyt has proven it is well mamaged and can respond quicky to new demand. Antimicrobial rsistance should be a key area over the next 10-20 years for NCYT as the 'silent-pandemic' could be an opportunity for the business to become a much larger company internationally.