Stock Pitch - Ergomed (LON:ERGO)

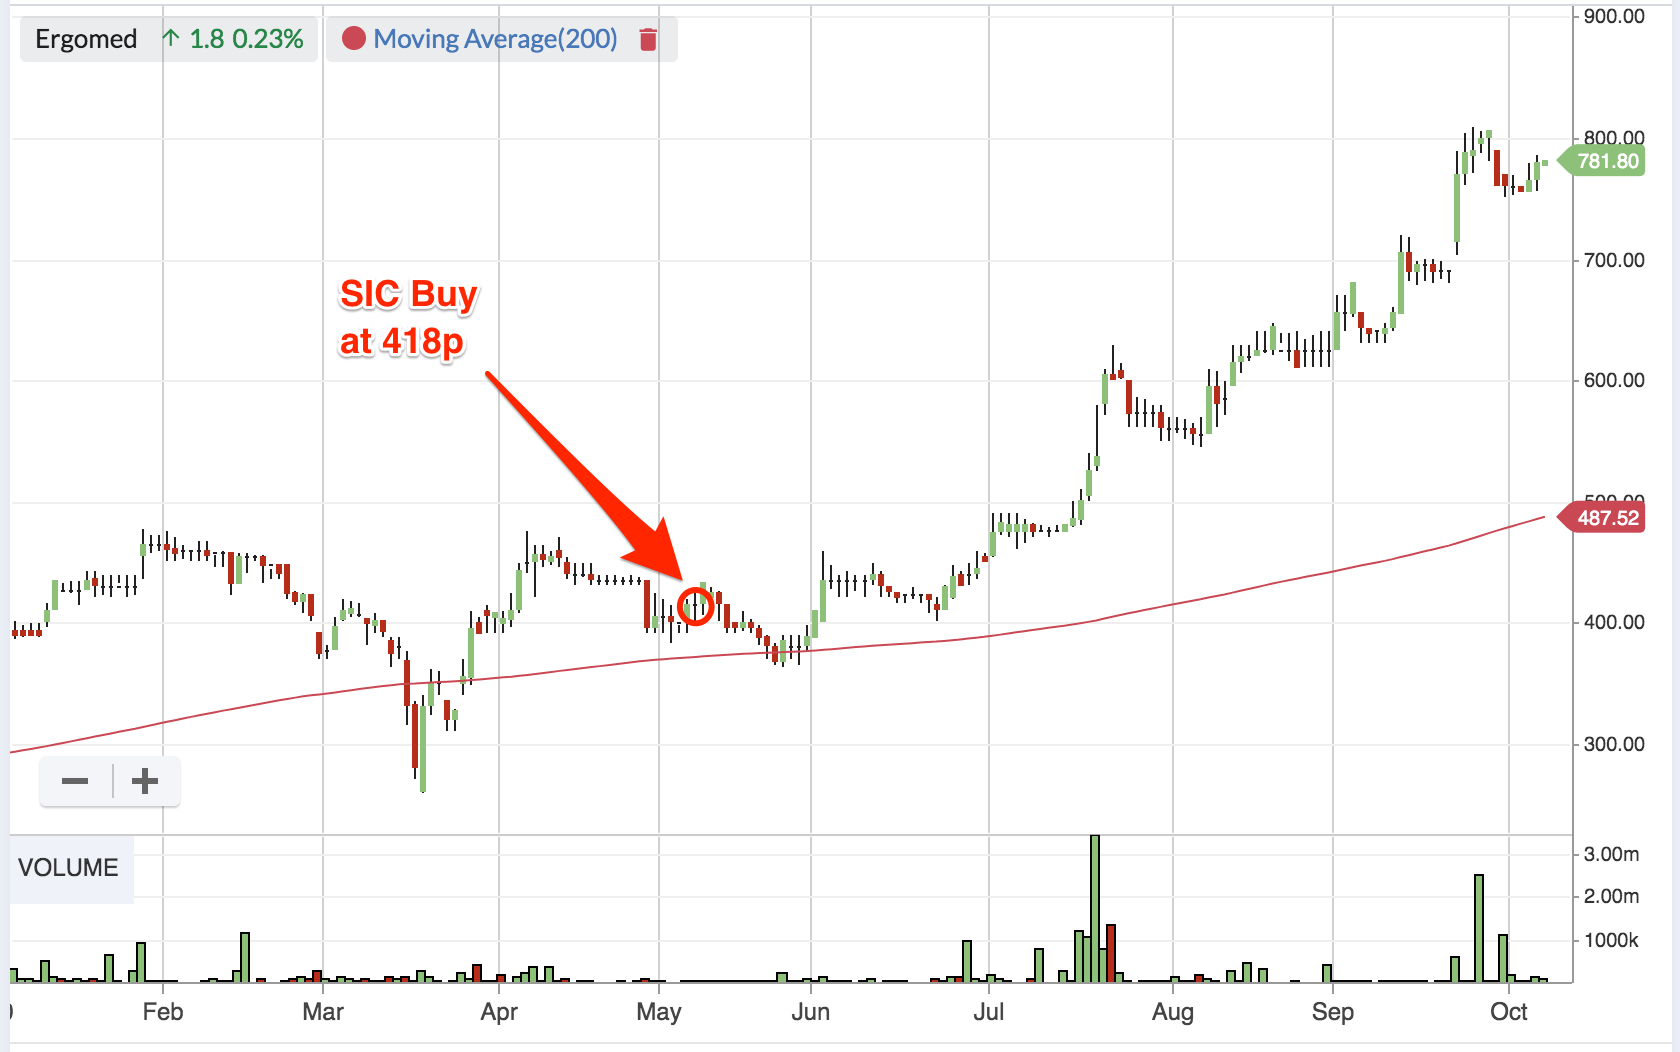
Ergomed was pitched to the Stockopedia Staff Investment Club (SIC) on 5 May 2020 and we bought a position two days later at 418p per share.
After being stopped-out of our initial positions in the market pull-back in March, Ergomed was the third share to be added to the folio (after BOTB and Codemasters).
None of us knew it very well but it passed our initial filters and looked interesting because it had pivoted to a new model and was starting to become profitable. Yet the market (and analysts) seemed to be slow catching on.
It has been one of our better performing holdings since then, and while there are uncertainties, you could argue that it's still early days and deserves to be held in the folio.
As always, these notes are a way for us to chronicle and share some of the thinking in the SIC and are not investment recommendations.
Pitch
Profile/Category/Style
Ergomed trades as ERGO on the AIM All Share Index (and is a constituent of the AIM 100 Index). It's in the Healthcare sector under Biotechnology & Medical Research and is classified as an Adventurous Mid-Cap.
Currently it trades at a share price of ~800p, giving it a market cap of ~£384.7 million. Between 1 May and 1 October 2020, the price rose from 405p to 760p, or ~88%. Average daily volume over 3 months is 219.7k (up from 119.9k back in May) - so average volume has been increasing recently. EMS is 3,000 shares. The free float is 66.8%
What is the opportunity style/type/classification?
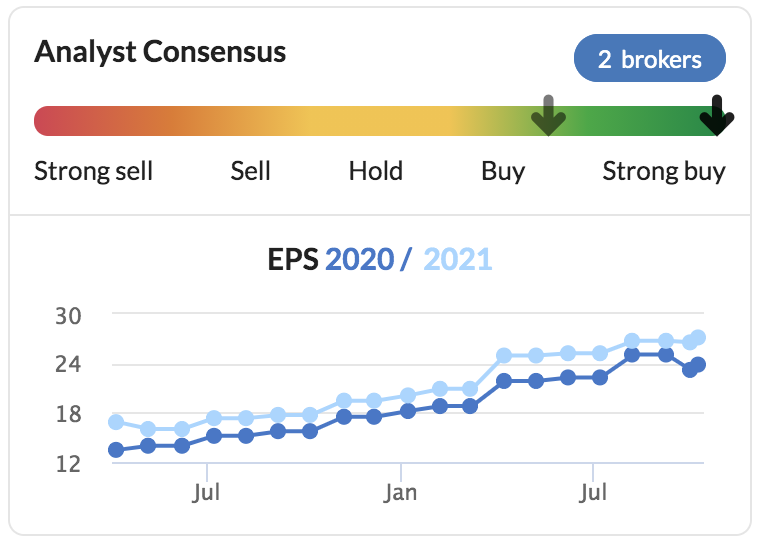
This is a High quality, high momentum, low value - making this a High Flyer. Signs that it might be a misunderstood growth stock and that analyst earnings forecasts are perhaps struggling to keep up with it as the growth accelerates. Importantly, it appears to be high quality - and the early signs are that it is getting more and more profitable after changes that have been made in the business in recent years. Momentum is positive at the moment. It delivered three earnings forecasts beats last year and has already done the same in its recent H1 2020 results. Brokers have been consistently upping their EPS forecast upgrades - and Ergomed has got a nice (albeit short) record of beating them.
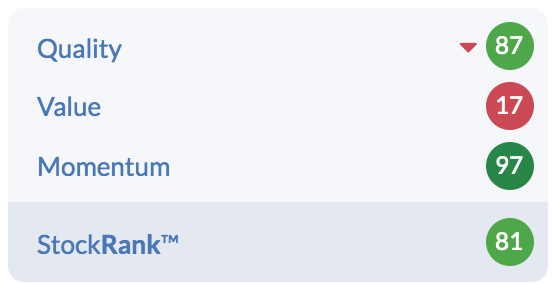
Ergomed StockRanks October 2020
Interestingly, Ergomed has had the High Flyer profile for over a year, and actually looked slightly more expensive 12 months ago, when all recent financial results were showing losses. So quality and momentum have been the strong factors here.
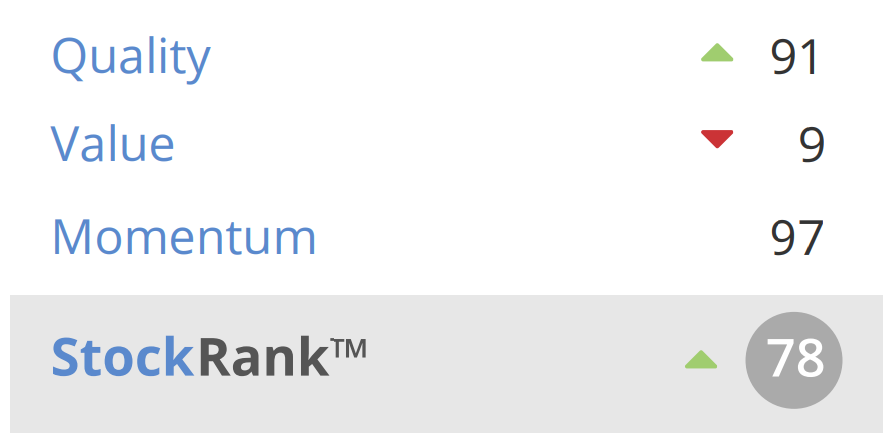
Ergomed StockRanks October 2019
Ergomed generally fits with Peter Lynch's idea of Fast Growers. Broker coverage remains relatively low (only two have forecasts), which means there's a case for believing it's not widely-understood, certainly in the PI space. That said, the there is already institutional interest from some managers, including small-cap growth specialist Mark Slater, who has a ~7.0% stake.
Business & Model
What does the company actually do, and what's its history?
Ergomed is a service provider to the pharmaceutical industry. It does three main things (although the main business is in 1 and 2):
- Clinical research - known as "Contract Research Outsourcing" (CRO) - which means it runs drugs trials and handles the clinical organisation and services for other companies’ drugs development. It specialises in specific areas like oncology, neurology, rare disease and immunology. These contracts can be worth a few million pounds each in revenue and typically run for two to three years.
- Pharmacovigilance (Ergomed calls this division PrimeVigilance) - which is mandated by regulators and involves making sure that newly developed treatments (by other companies) are closely monitored and don’t have adverse effects.
- Ergomed also has some interests (both wholly-owned and partnerships) in drug development.
Ergomed floated in 2014 with largely the same business model it has today, except that its drugs co-development business was a higher priority back then. It raised £9.7 million and used £6 million of it to buy PrimeVigilance in the US.
Importantly, Ergomed has been in transition over the past two or three years. It used to be heavily focused on co-developing new treatments, but there was a heavy R&D cost to that. It meant that over the past five years it moved from being barely profitable to consistently loss-making.
More recently it has stopped funding any new initiatives in that speculative part of the business to focus on the "services" side. It also introduced some cost-cutting measures early in 2018. That change led to a swing to profitability in the 2019 financials.
These days it's more interested in selling picks and shovels than doing any actual digging.
What is the company's business model? How does it make money?
The company makes money from service contracts. It seems to be quite well diversified in terms of income streams from different activities. Revenues were reasonably well split between the two main divisions in 2019.
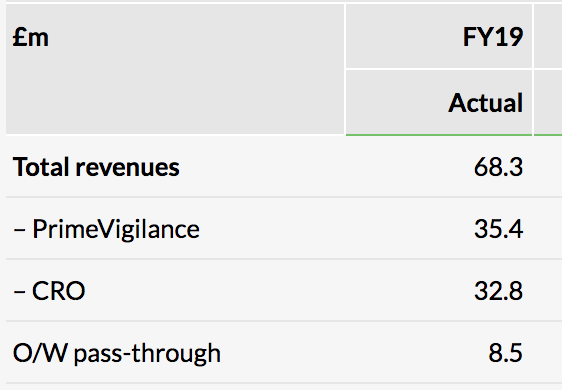
Source: Edison Investment Research (link)
Over the past three years, the fastest growth has been seen in Pharmacovigilance (PrimeVigilance):
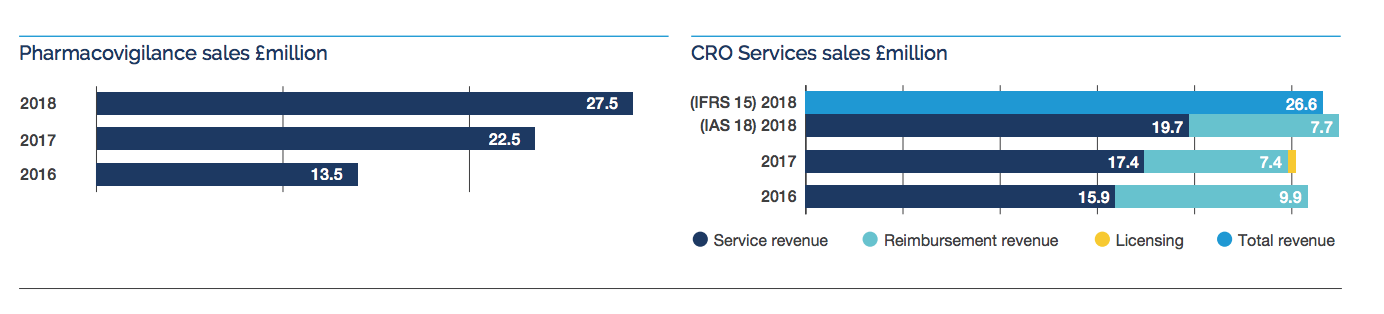
Source: Ergomed (link)
Key facts about the main divisions:
CRO
- 60+ active clients
- 70+ active studies underway
- 300+ employees
PrimeVigilance
- 160+ customers
- 700 employees
- Leading independent consultancy in this market
- Operates in 100 countries
- Has a very sticky customer retention. Each year, new new sales cohorts tend to remain as customers, while new ones are added on:
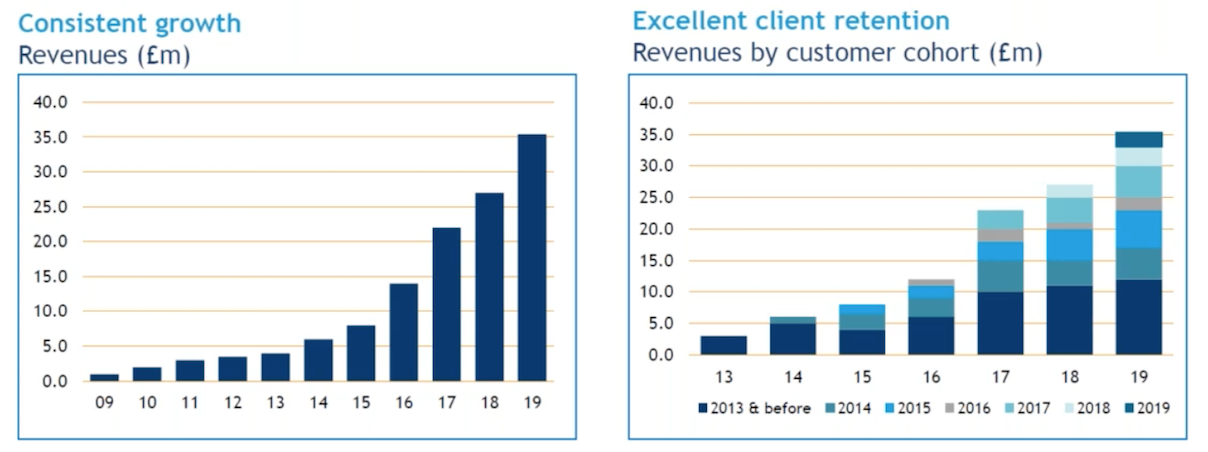
Source: Ergomed. Pharmacovigilance division growth
Market & Competition
What is the state of the company's market & competition?
According to Grand View Research, the global healthcare CRO (contract research organisation) market size was valued at US $37.1 billion in 2019 and is expected to see a CAGR of 6.6% out to 2027. One of the biggest markets in the world is the US - which is where Ergomed is focusing its expansion efforts.
Time and cost constraints for pharma drug developers is one of the main reasons this market is growing. It seems to be easier for them to outsource this work. Not only is it cost-effective, but CRO firms like Ergomed have very strong technical expertise.
There is competition in the market, and it is increasing, but Ergomed says it is becoming more competitive as a mid-tier player, and competing well against larger-tier firms too.
These are some of the company's core market areas and their expected growth rates:
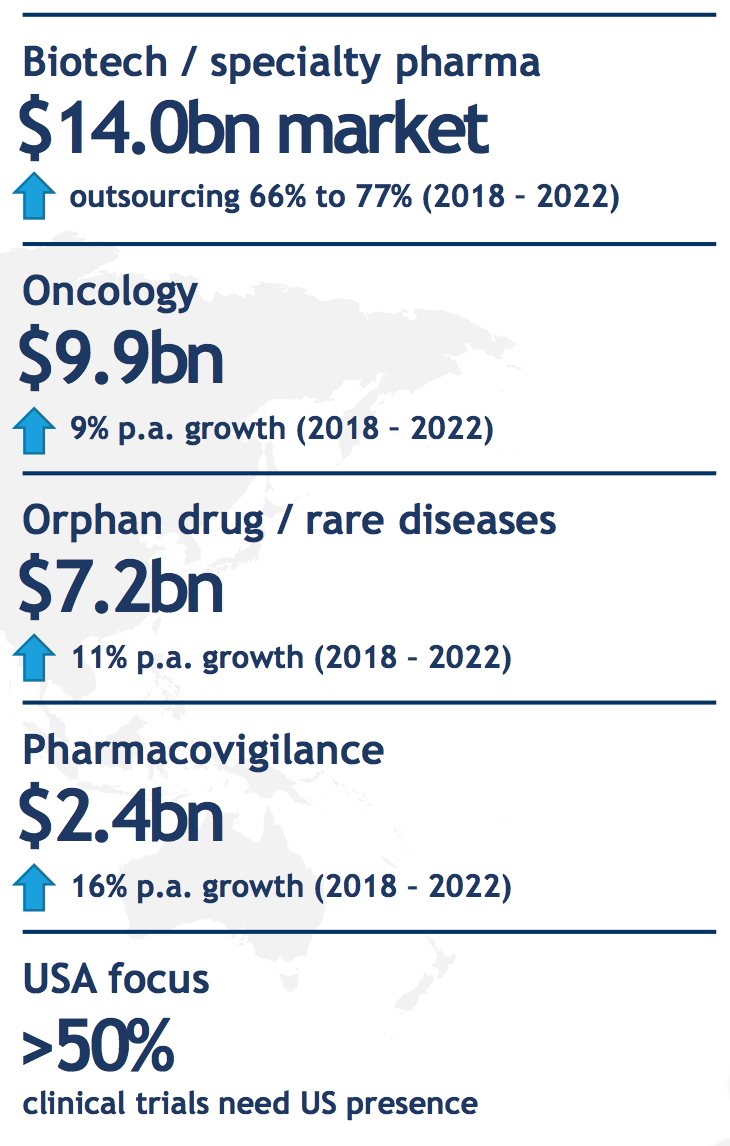
Source: Ergomed (link)
What is the company's strategy & competitive advantage?
Ergomed presents its advantage as being "expertise" and "speed" and its focus on specific medical areas. In particular it has strength in managing "orphan drugs", which are treatments for illnesses/diseases that are rare or unusual and may not have any other treatments.
Growth - it wants to increase exposure in North America. It recently acquired Ashfield PV Inc (for US$10 million (all cash)), which was immediately renamed under the PrimeVigilance brand. The aim is to expand its pharmacovigilance business in the US, and the CFO Richard Barfield has indicated that more M&A activity in the US may follow. Overall, it's planning to be a global business and already has offices in 16+ countries.
The Ashfield PV acquisition added 40 new customers to the group and came with a $9.8m contracted order book. It generated $11.6 million of revenue in 2019. Richard Barfield says the opportunity to cross-sell to the expanded client base was a major factor for doing the deal.
What trends is the company currently benefiting from that could provide a tailwind?
General industry trends for pharmaceutical companies of all sizes to call on specialist consultancies like Ergomed to handle drug development studies and manage ongoing pharmacovigilance.
Recent History & News
What is the company's track record of growth & profitability?
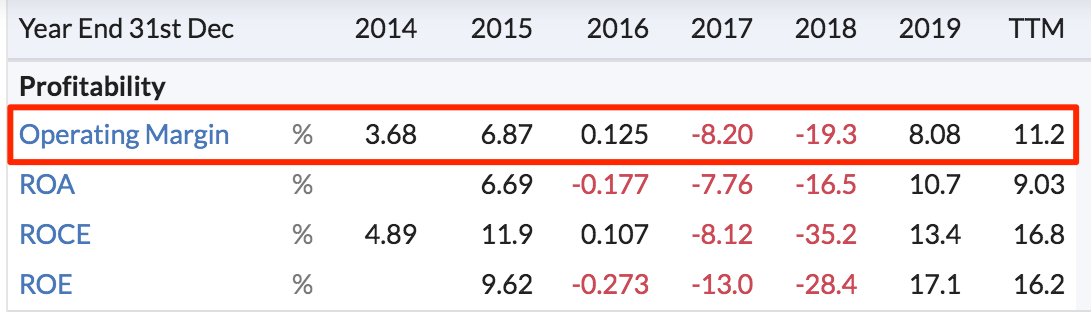
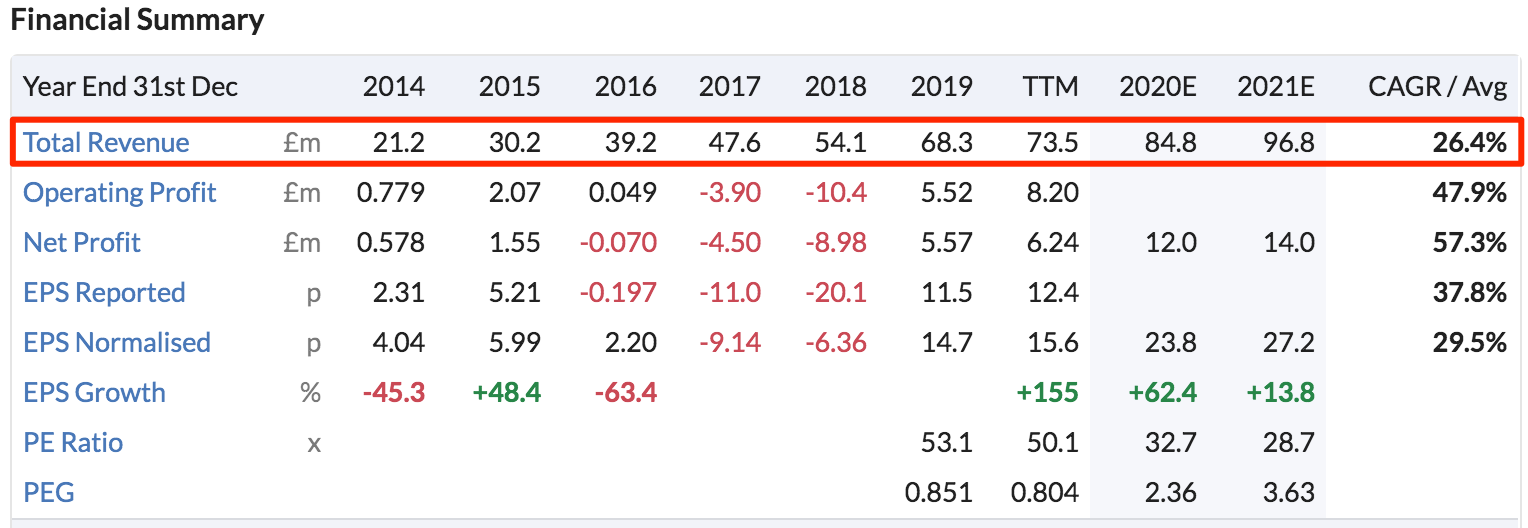
Between 2018 and 2019, the company saw normalised EPS swing from -6.36p to +14.7p. This has come from its pivot away from loss making development projects to a service-oriented model.
In the Financial Statement below you can see how this contributed to a swing to profitability in 2019.
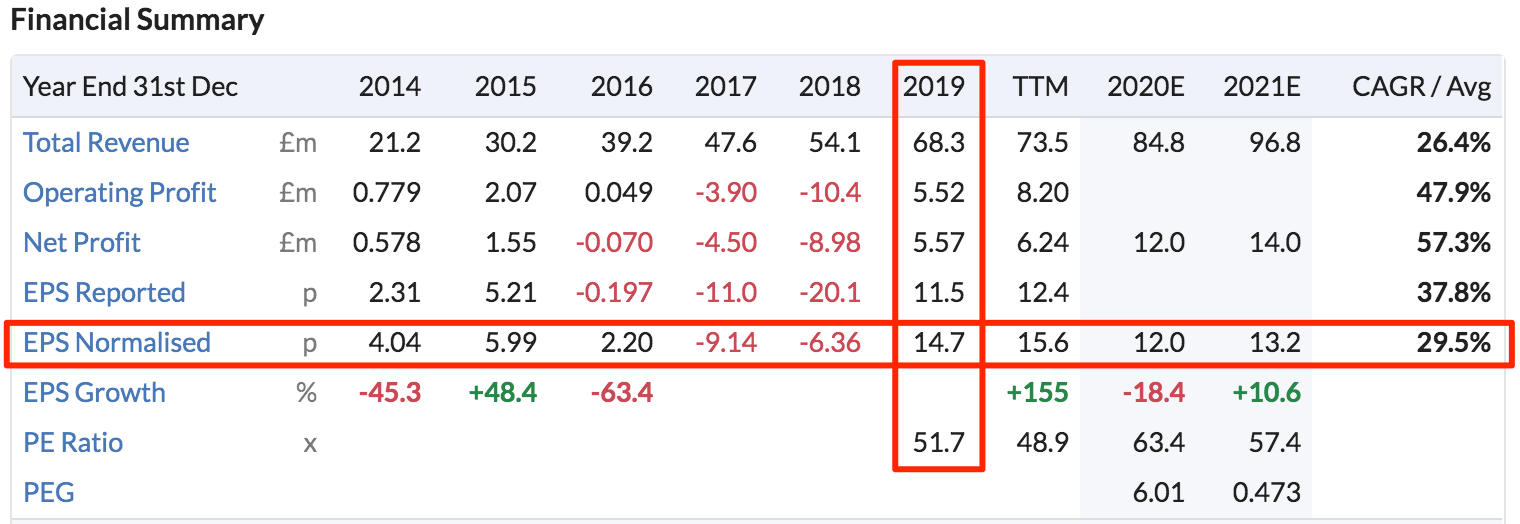
In the first half of 2020, Ergomed's revenues continued to grow and there are signs that it is becoming increasingly profitable (with signs of improving margins).
In its H1 2020 interim results, the company reported a slight decline in y-o-y revenues on the CRO side of the business. This was caused by delays to industry-wide pharma trials as a result of Covid-19. Richard Barfield suggests this was a good result under the conditions. Meanwhile, growth in the pharmacovigilance division continues to be strong.
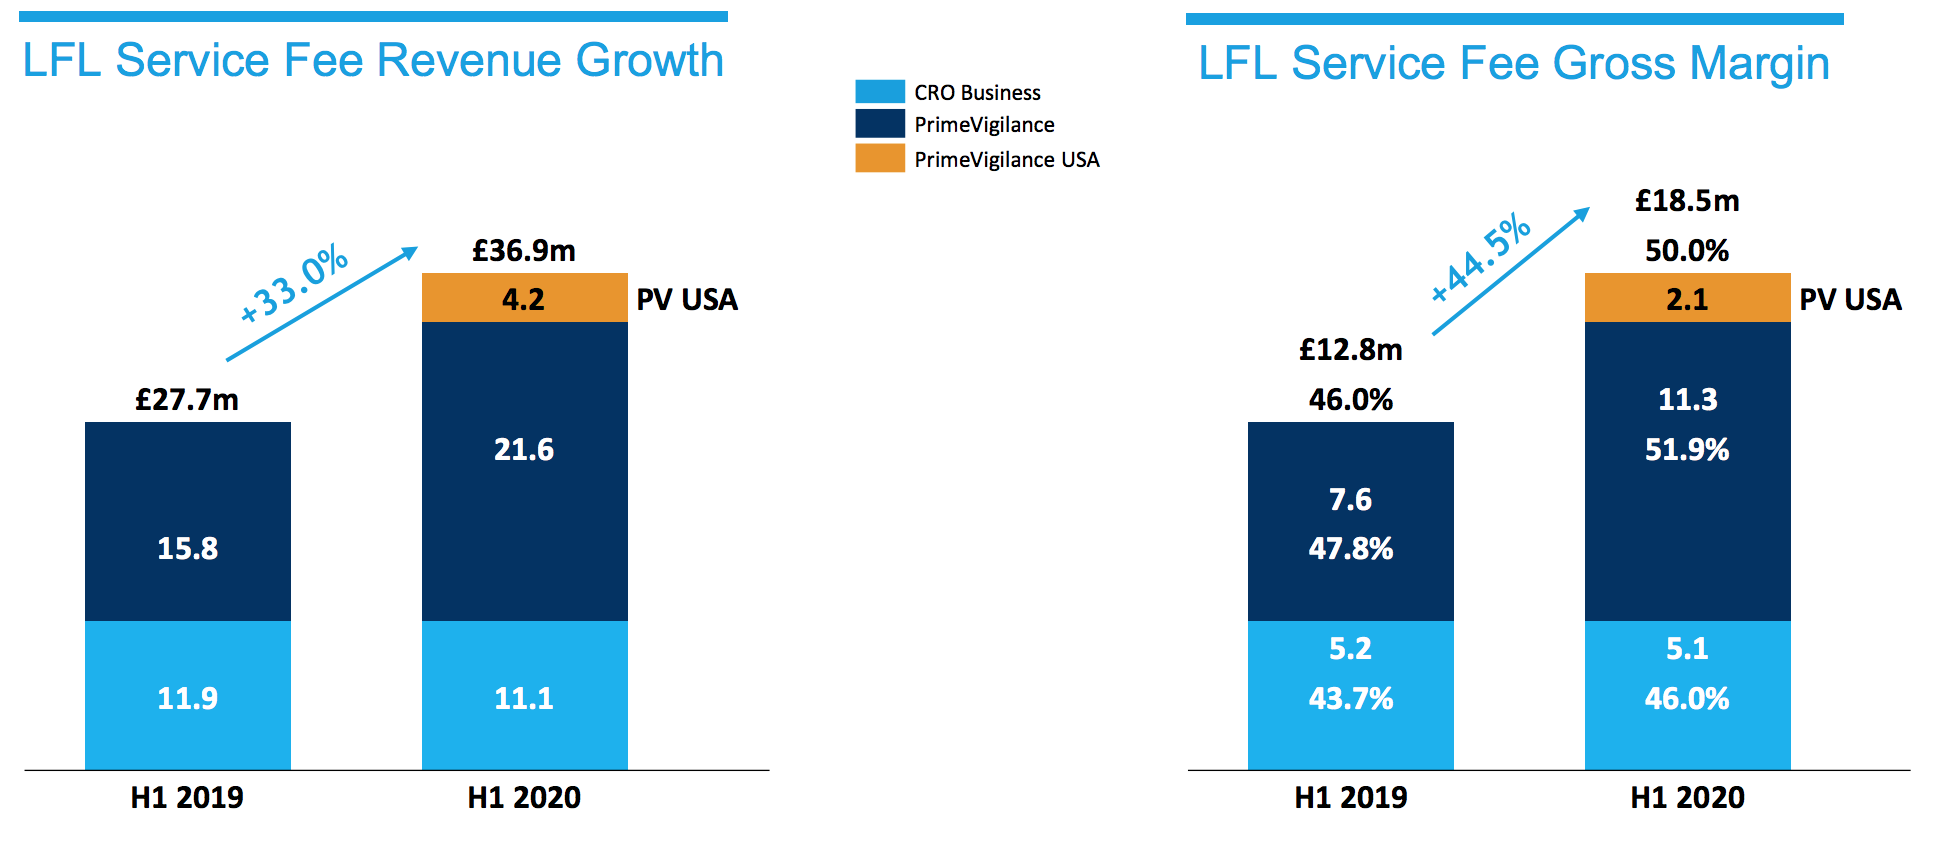
Source: Ergomed (link)
What's been happening in recent trading statements etc?
In its H1 2020 numbers, Ergomed reported a 14.8% y-o-y rise in sales to £40.4 million, and 74% rise in its cash position to £14.1 million. Its order book of future contracted revenue was up 28.0% to £151.4 million.
Because pharmacovigilance is mandatory for pharma companies to carry out, this side of Ergomed's business has apparently been resilient during the disruption caused by Covid-19 in 2020. Its overall employee headcount has grown from 850 to 1,000+ so far this year (all of them are remote at this time). Its involvement in what's regarded as essential medical research means that many projects and studies have proceeded as planned. It has also been involved in managing Covid-19 treatment studies.
More recently, the company has announced plans to do a capital reduction. Historically, losses and impairments have left a deficit in the retained earnings reserve in both the consolidated and company-level accounts. Having matured as a business, this kind of deficit is a blocker to things like paying a dividend. So the company has proposed a transfer to make the returned earnings reserve positive. If approved, it will have no impact on cash.
Catalysts & Risks
Are there any catalysts that could drive a rerating in the short or medium term?
The stock has already performed well over the past 18 months, but one question is whether the market really gets the story and whether institutions will become heavier buyers of the shares. There are signs (presentations, etc) that the company is working on this.
Small, speculative healthcare stocks (especially drugs developers) can be immediately ignored by risk-averse investors. But this is not a developer, it's a service business - and increasing recognition of this could be helpful.
Three earnings forecast beats last year and one already this year could be a catalyst for further momentum.
The capital reduction looks like a step on the path to future dividend payments from what is increasingly looking like a cash generative business. So that may catch institutional attention.
What are the biggest risks for the business?
The biggest risk to Ergomed's growth is competition and its ability to continue to win contracts.
Generally it is dependent on pharma companies continuing to outsource these operations - and revenues could be impacted if projects are delayed or cancelled.
Ergomed has hinted at plans for further acquisitions. It does have M&A experience on the executive team and the cash to do deals, but bolt-on acquisitions can fail.
In 2019, Ergomed's top 5 clients accounted for 28% of sales - so revenues could be affected if any major clients were lost.
Ownership, Management & Financial Strength
What is the ownership structure of the company, and do management or founders have significant stakes?
Miroslav Reljanovic, the executive chairman, founded the business in 1997 and still has a 22.5% stake.
The executive team (including Mr Cameron, COO and Mr Barfield, CFO) have interests in the shares as a result of Long Term Investment Plans.
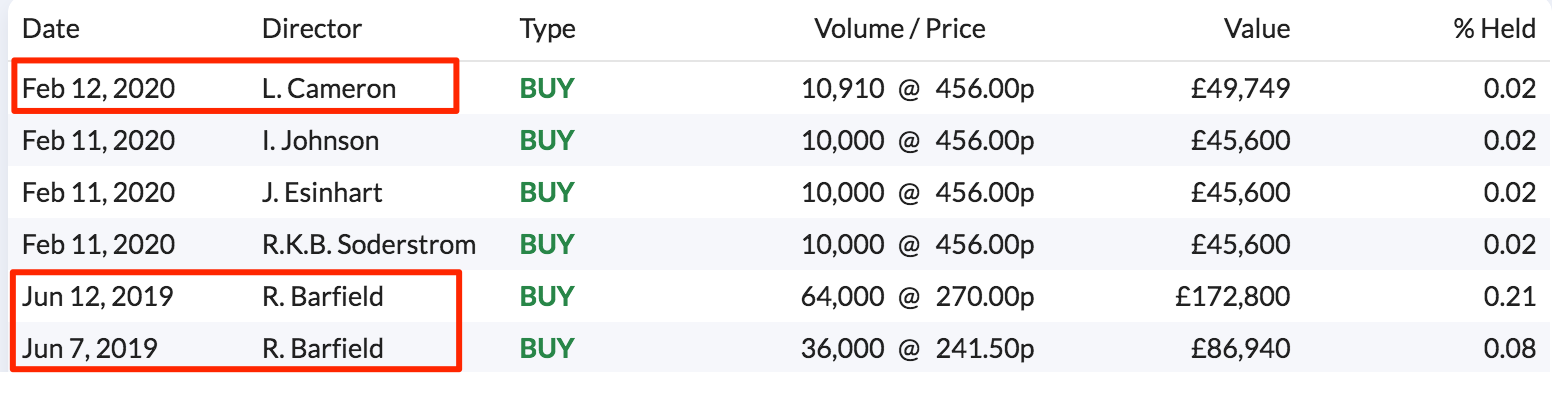
Has it a history of diluting shareholders, or (better) buying back shares?
There has been some dilution in the past. There was a £2 million placing in 2018 and the company has previously used shares as a component in some of its acquisitions. That now seems to have stopped. There has been very little dilution more recently.
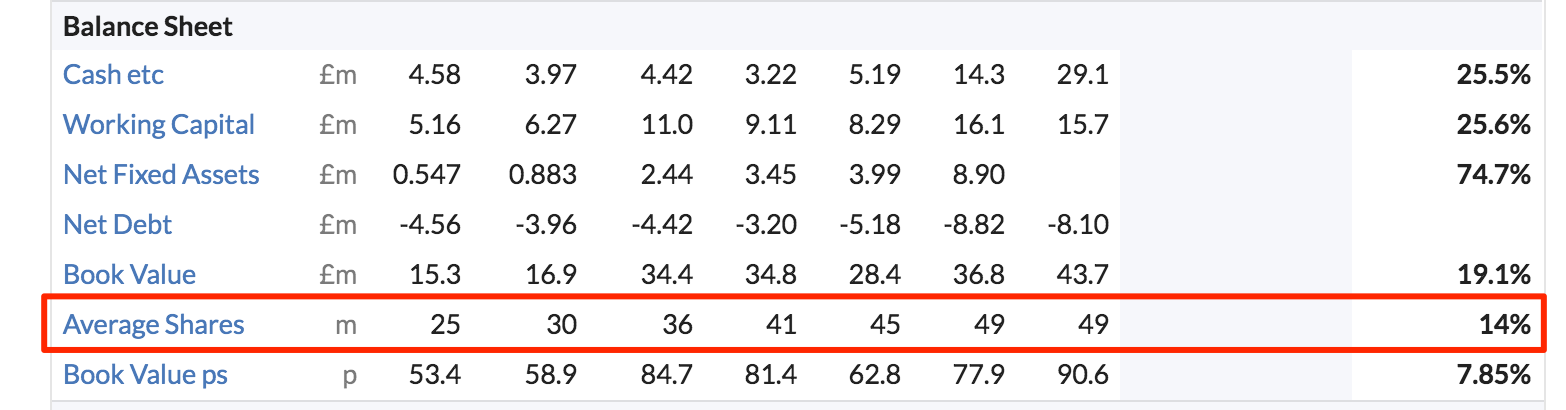
What is the company's financial status & balance sheet strength?
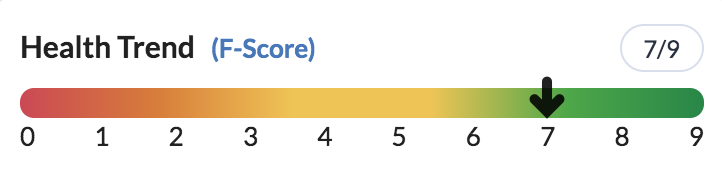
Debt free. F-Score is currently 7 and there are signs that may improve if the current financial trend persists through to the full year numbers. Either way, there are no obvious concerns here at the moment.
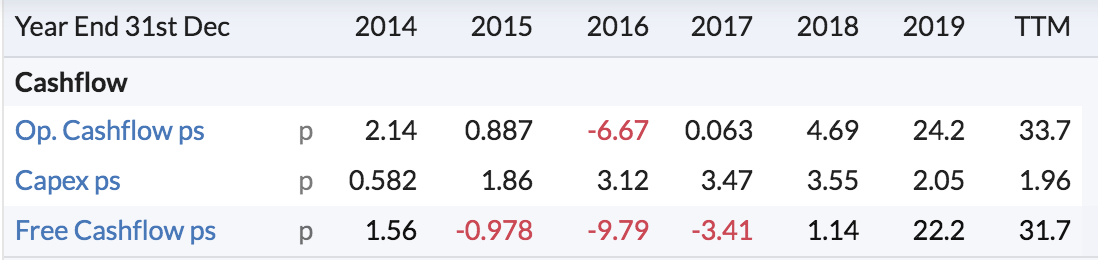
Cashflow has improved markedly over the past 2-3 years and the there are signs of an increasingly strong balance sheet. Positive cashflow enabled the all-cash acquisition of Ashfield PV.
Valuation
How is the company currently valued both absolutely and relative to its sector and the market as a whole?
Ergomed stock is relatively expensive, with a current Value Rank of 17. The trailing PE ratio stands at ~50x, with a forecast PE dropping to ~30x.
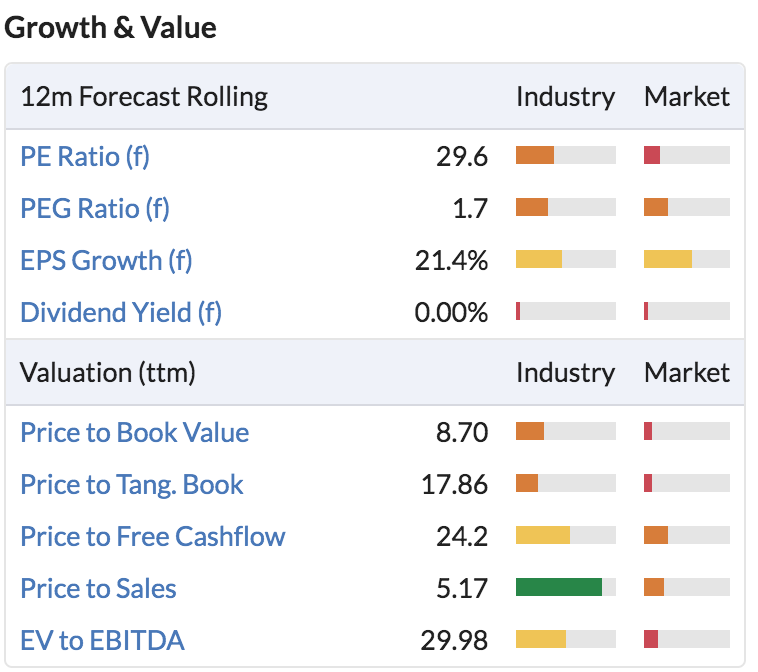
At this stage - so soon after a swing into profit - it's possible that the market might under-estimating future earnings growth, which could affect the valuation forecasts. On the back of H1 2020 results, normalised EPS forecasts for this year nearly doubled from 12.0p to 23.8p, suggesting that analysts have hitherto underestimated the company's future growth rate. But that may be sensible and it's difficult to make assumptions there.
It's also possible that the stock has attracted a growth premium over the past year, given the popularity of AIM-quoted small-cap growth shares in that time. That may be a risk.
After the H1 2020 results, Edison Investment Research upgraded their valuation to £409 million or 845p/share from £345 million or 713p/share previously.
It's notable that Ergomed has been growing revenues at 26% CAGR over the past six years, and that growth is forecast to continue. With the loss-making business now effectively closed-off, if it can get more of those sales dropping to the bottom line, the valuation may be reasonable. The management seem to think that a combination of organic growth and acquisitions will help them do that.
Sentiment
What do the brokers currently think?
EPS forecasts for 2020 and 2021 have been on an upward trend over the past 12 months - but there is low coverage from brokers.
What would the person selling to us be thinking and who are they?
Speculative and adventurous small-cap biotech and healthcare has been a relatively hot sector in 2020, but there are other shares that have been more explosive than Ergomed. Sellers could be those looking for dramatic gains in riskier stocks elsewhere in the sector.
After a solid run over 18 months, there maybe investors looking to bank profits and find other turnaround opportunities.
What is private investor sentiment at the moment?
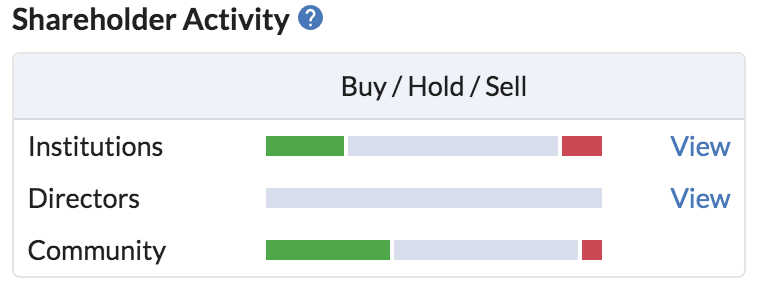
Institutional and Stockopedia Community sentiment are both currently net positive on the stock.
What do you think - has the market failed to grasp Ergomed's shift to a more service-led business model? And just how big is that market opportunity? We'd like to hear your views...
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

19 comments
Ergomed (LON:ERGO) is up 12% today on a strong end to the year - it's been a great compounder for the Club so far.
We've left a more in depth comment over in the SCVR: https://www.stockopedia.com/co...
I note Ergomed (LON:ERGO) is down over 10% today, I can't see any news, any ideas for the reason?
I have some and your in depth article confirms why I like
An excellent analysis. Thank you very much. The pharmacovigilance business looks particularly attracted but I will watch for a drop in the price before buying.
These investment club write-ups are first class. I very much like the detailed research. I am afraid my DYO research is very amateurish in comparison due to lack of time. The article has convinced me to have exposure to the medical/pharmaceutical industry. I have bought today.
Where do the Stockopedia community trading figures come from?
Do we really understand this company’s competitive advantage?
“Expertise” could mean almost anything. Does it mean superior knowledge of a particular area, if so what area is that, how does that translate into value for the customer? Is this expertise concentrated in a few key individuals who could leave and take the customers with them?
“Speed” is also a bit vague. Is that speed of recruiting patients for the trials? If so, how do they manage to do that faster than others? Or perhaps, it is speed of collating the results or perhaps speed of something else?
I don’t think there is a strong understanding here of what makes this company tick, so on that basis it can only be valued on the fact that it has changed its business mix to focus on the profitable activities. And that seems to already be in the price for now.
Been in since 300p ish and it's a long-term portfolio hold. Ergomed (LON:ERGO) and the CRO market is not straight-forward to understand but it's been a great growth sector driven by a number of macro tailwinds:
- Drug development has moved from discovery of the next 'blockbuster' by big pharma to providing treatments which are tailored to the individuals through providing a cocktail of different drugs at different times, to different people. This has driven the CRO market as the amount of testing, different delivery methods and dosages has increased the level of work required.
- US biotech growth which has led to lots of small pharma companies which look to outsource CRO work. Companies like Ergomed (LON:ERGO) can often earn-revenues through the full lifecycle providing some decent revenue visibility (Phase I-III and even some do the CDMO work in addition). This trend will have probably accelerated under COVID.
- UK is very well positioned to serve this market due to our heritage in pharma, same language as US and we are viewed as a low cost CRO market. It's a people business and a qualified bio-chemist in the UK can be ~25% of the price as one in the US. There has been a lot of sector consolidation and US / UK combinations are popular for this reason. #ERGO will remain an attractive takeover candidate imho which also protects the downside.
With Ergomed (LON:ERGO), i'm very much backing the ex-Chiltern team to replicate their success as they did phenomenally well with Chiltern before an overall exit delivering a very high money multiple / IRR.
Growth in these businesses comes from i) expanding / growing Pharma relationships; ii) increasing capabilities to cross-sell to existing clients; and, iii) M&A. Quite difficult to measure these KPIs from the outside but...
The strategy appears sound and they are delivering on the numbers and happy to back them to continue.
One of the higher quality UK small caps which happens to be in the right place at the right time.
Hi Graham,
Very good question - a specific competitive advantage is not easy to identify. They are winning and retaining business which suggests that they have a competitive proposition of service and price. The price and high margin is probably derived from their Eastern European resource base but their operational delivery capability must also be strong. They are developing technology to automate some processes to increase efficiency. This is visible in that they are adding revenue faster than adding to their headcount generating operational leverage.
However, from a strategic analysis view point I'm more interested in their Economic Moat which comes from the the long-run relationships that they have with clients. A very high proportion of their revenue is recurring and beyond this there is a very high likelihood that contracts will be further renewed. Once Ergomed (LON:ERGO) are supporting a drug programme - gathering, collating and managing the trial data - it would be a difficult exercise for a client to change suppliers.
So, I think that its the combination of operational efficiency and very sticky relationships that provides Ergomed (LON:ERGO) their competitive advantage. In a large and growing market competitive pressures will be low - so pricing will be less-keen than might otherwise be the case. This should thus deliver high margin, high revenue growth for a sustained period - which is why this is a major holding for me.
I think that this series of articles is very instructive. Thank you. I have for many years held shares in a German company called Evotec which took over Oxford Asymmetry, one of Oxford University's first spin-outs, a long time ago. its business model is somewhat similar to Ergomed's but without the pharmacovigilance. I live in hope that its hitherto lacklustre share price performance will some day take off in the way that Ergomed's has.
I like this format. Looking forward to reading more of these investment club write-ups.
A very comprehensive report and with it a convincing Buy. I thought the Ergomed (LON:ERGO) presentation video above was compelling too.
Could be confirmation bias, but I have doubled my holding this morning as part of a new increased Healthcare sector strategy.
Just a note on this... I don't want us to be accused of only writing up our winners! We are going to gradually get through all the Club's current holdings over time - while also writing up our meeting notes in real time - the portfolio, pitches and purchases.
We had a meeting yesterday. The club actually bought Novacyt Sa (LON:NCYT) this morning... there's a write up coming tomorrow.
I bought Ergomed on your coverage of this company. Up 75% to date. Thank you. I also invested in Novacyt on October 2nd with a distinct feeling of being late to the party but on the basis of a momentum trade and previous SCVR discussions. Up 37% in 6 days. I believe that's a great result for me and the value of Stockopedia.
TKS, KEEN TO READ Novacyt Sa (LON:NCYT) OPINION TOMORROW!!! THINKING TO BUY BUT WORRIED GAINS NO LONGER THERE AS PRICED IN
thanks for highlighting Ergomed. They're up 100% as of today for me.
it seems two executives were brought in from Competitor Chiltern International which saw revenues increase x6 while they were there. They seem to be replicating the success after two years of being at Ergomed. One of them, the CFO gave this presentation a couple of days ago:
I'm confident they'll continue to do well in the current environment
I keep trying to diversify my portfolio by adding plausible medical stocks. Big pharma and medical devices have successes but also issues (eg. failure of new drug development). Investment in companies providing support to these activities seems a safer approach. I bought into £ergo early in 2020 and share price progression has been very satisfying since. But current valuations look full and I would hesitate to buy at current valuations- though the cash plus business potential means I will continue to hold. The risks lie in the loss of two or three of the bigger contracts (a risk declining as the business expands), and in the application of AI- will larger competitors be able to manage this more quickly?
"Tomorrow will be a good Day" - Captain (Sir) Tom Moore (Age 100) What a great attitude
After a thoroughly irascible day on Stocko yesterday and some comments getting off the professional and onto the personal level this post has proven Sir Tom right! There is everything to learn from this series of posts under the Investment club Banner in how to chronicle a share when DYOR
Keep them coming, even the (in hindsight) poor choices please
The SP looks like its up to events with the FPE @ 30. The company's addressible market does look large though and its growing. I reckon the company has a great future, even if short-term its all, or mostly, in the price.