Stock Pitch - Novacyt (LON:NCYT, EPA:ALNOV)
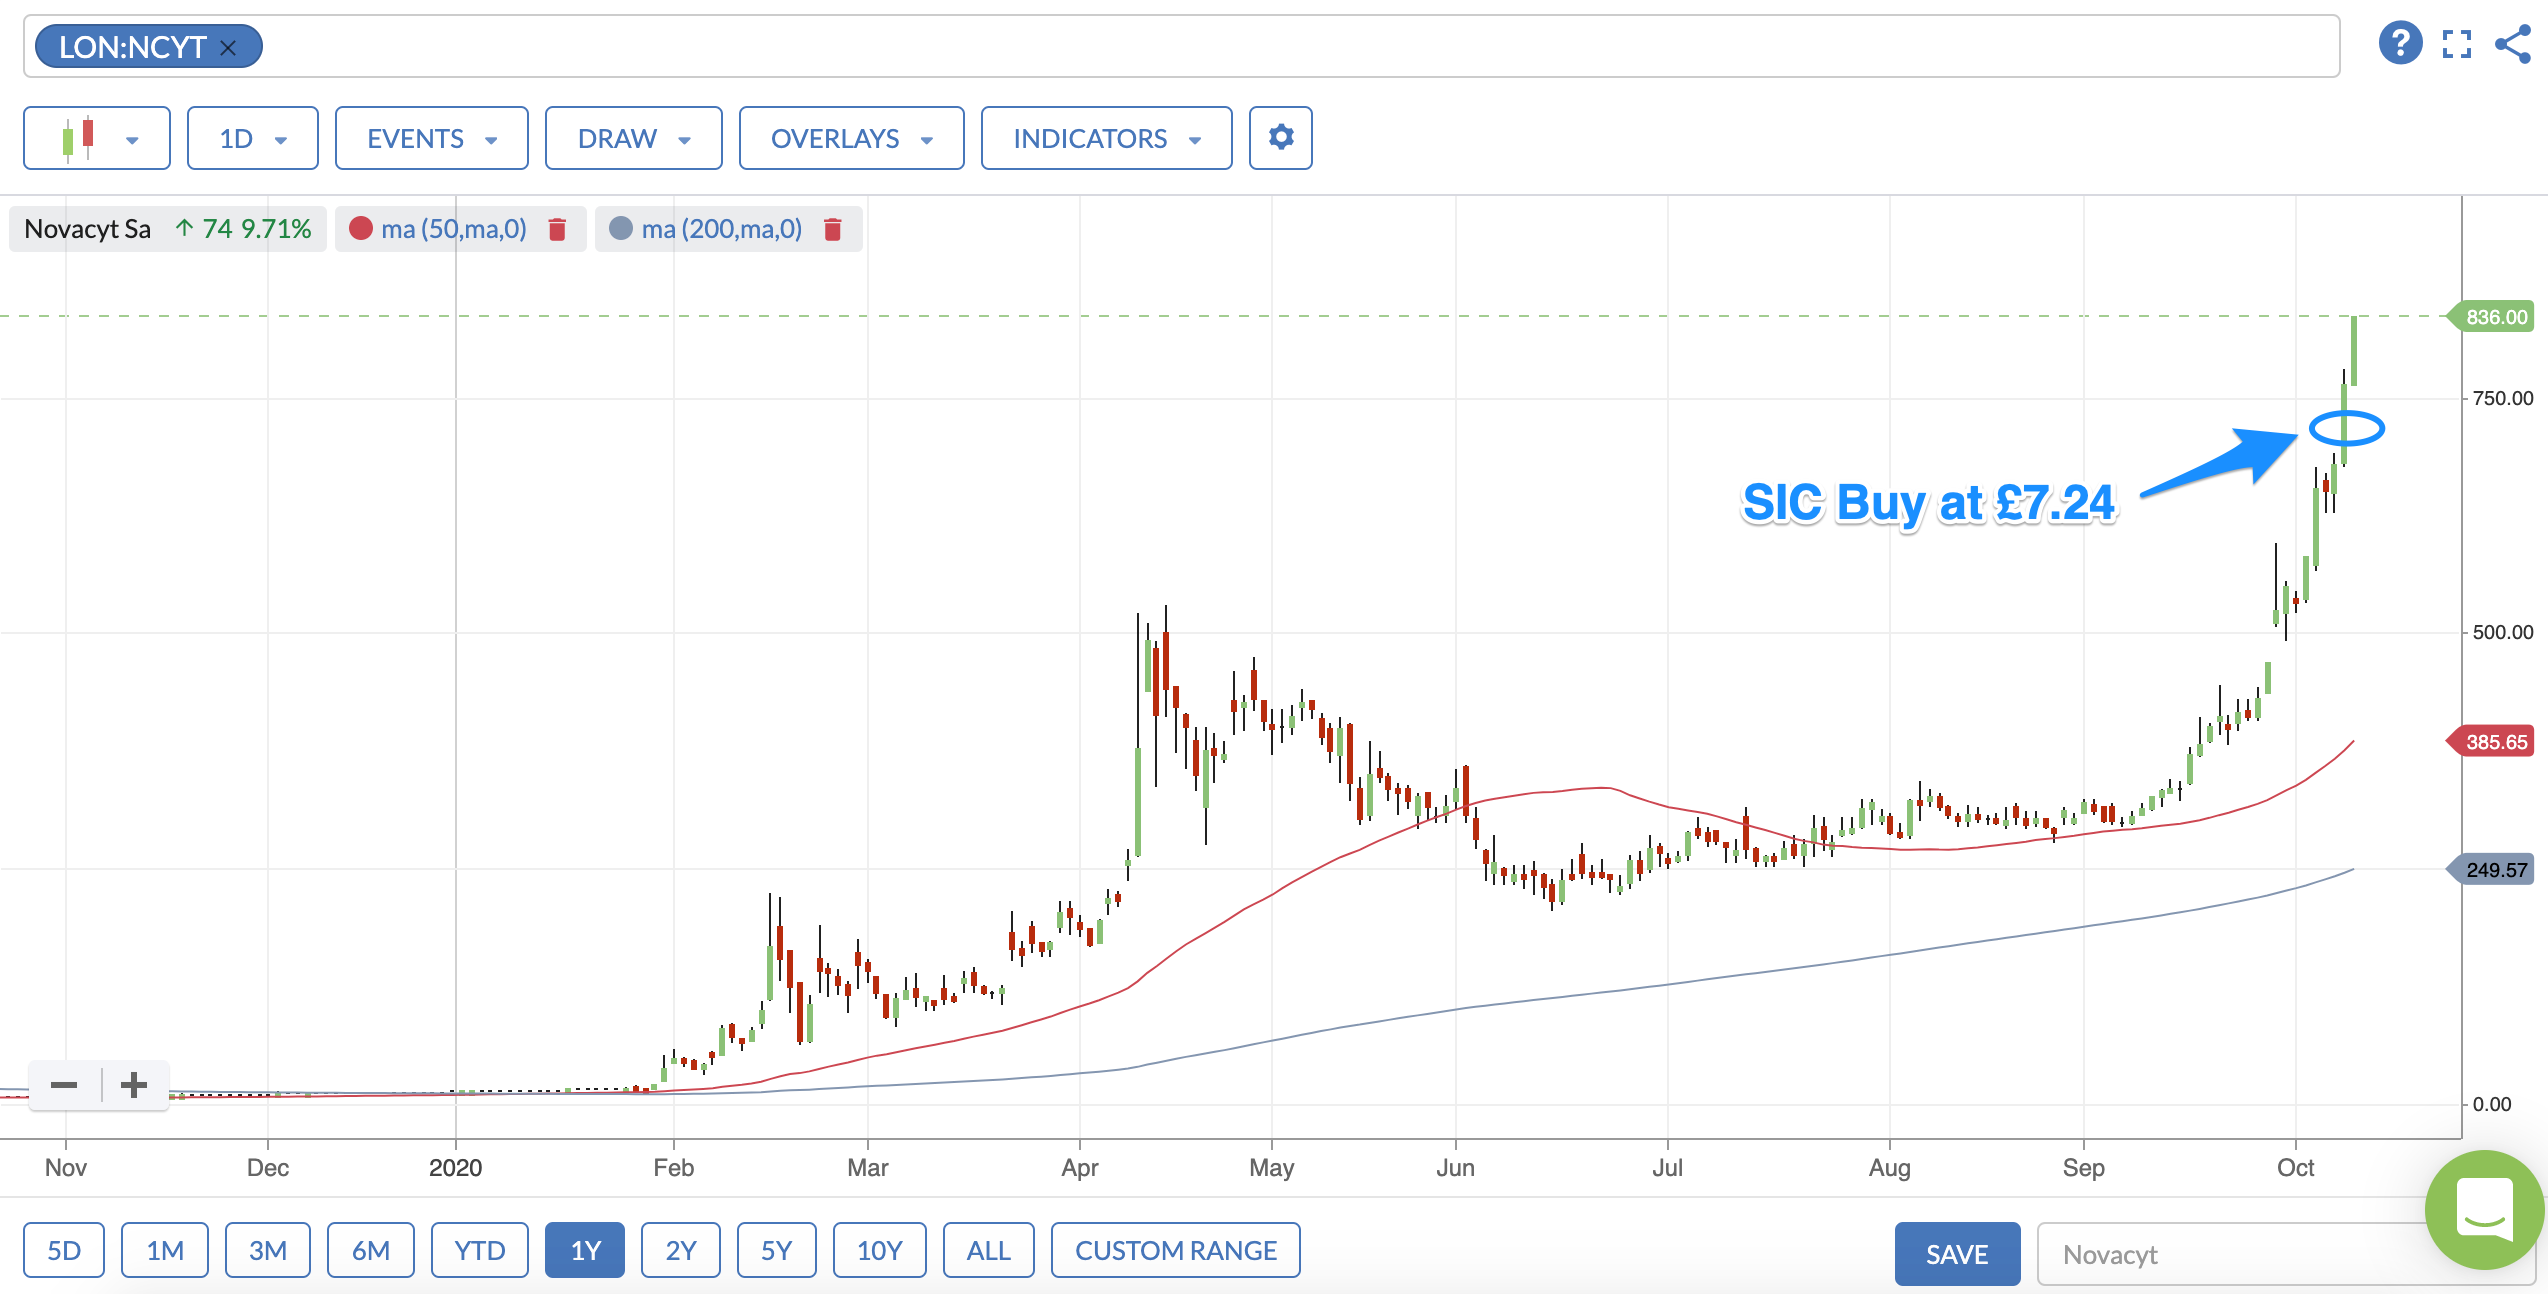
Novacyt was pitched to the Stockopedia Staff Investment Club (SIC) in early October. On Wednesday (8th October) shares were purchased for the club at the price of £7.24.
Novacyt has been the best performer on the UK market over the past 12 months. The shares have just reached all time highs, and shareholders this time last year have seen an astonishing 10,865% return on their investment.
The momentum has picked up in recent weeks, on the back of transformational financial results and a large contract win with the Department of Health and Social Care (DHSC) in the UK as noted in Jack’s Small Cap Value Report on the day.
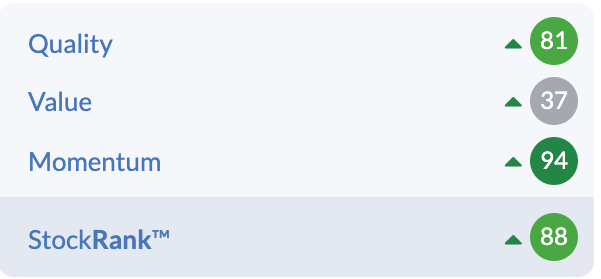
Novacyt looks to be a company at the forefront of our fight against the Covid-19 pandemic at the moment, and its impressive set of financial results saw its StockRank soar from 41 to 96 last month, which meant that the company finally met all of our SIC criteria.
As a highly speculative, high flying, mid cap, we will evaluate why we decided to add Novacyt to our SIC holdings, but also what potential risks may lie ahead.
Profile/Category/Style
The company’s name is Novacyt, ticker symbol LON:NCYT and EPA:ALNOV. It is dual-listed and trades on the London AIM market and French Euronext exchanges (share capital currently split 30% UK & 70% France). The company operates in the Healthcare sector, more specifically the Biotechnology & Medical Research industry.
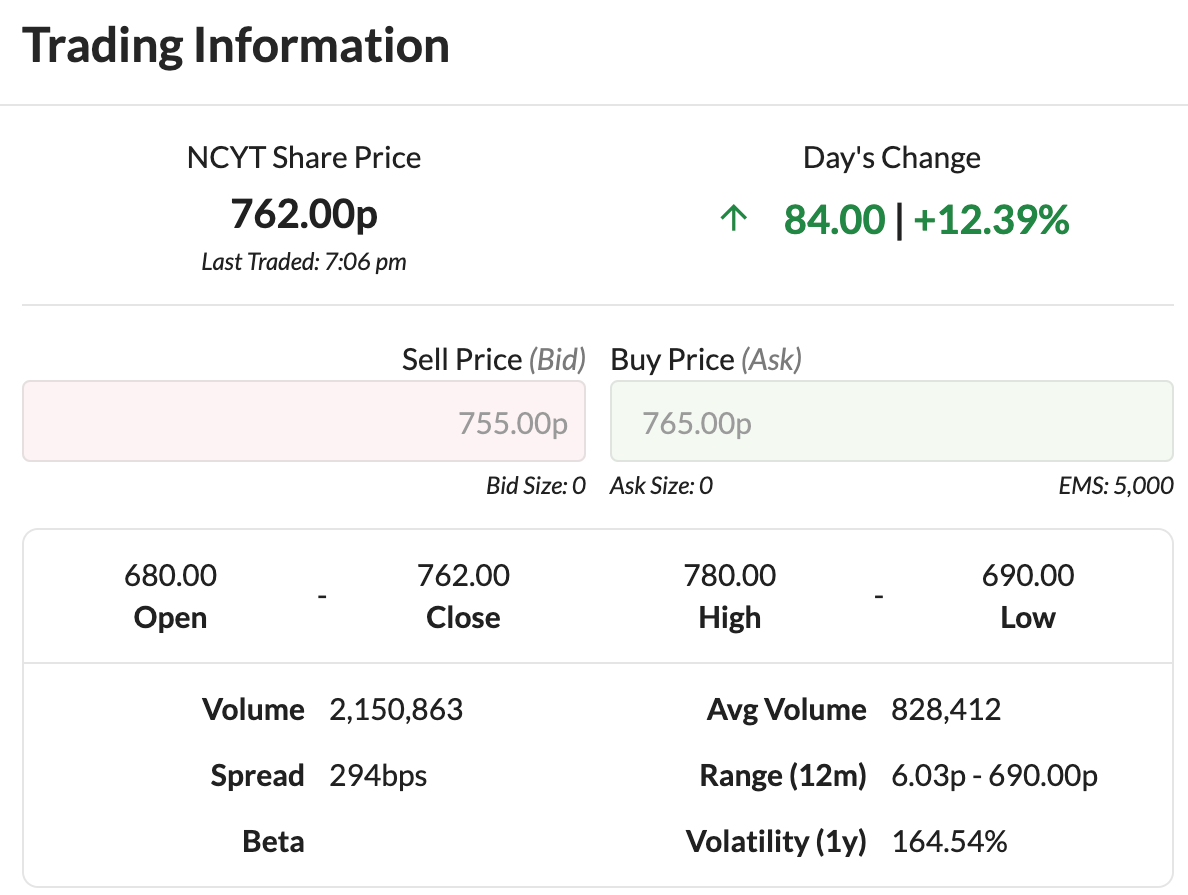
After a stellar year, the shares are trading just off their all time highs, at 762p at the time of writing. The total market capitalisation has just reached £538 million, putting it comfortably in the UK mid cap size group. Liquidity is not a major issue, with an exchange market size (EMS) of 5k meaning that you can invest just over £38,000 (5000 * £7.62).
The stock is categorised as Highly Speculative according to our risk ratings. So potential investors should be wary of share price volatility.
What is the opportunity style/type/classification?
Due to the strong price momentum and excellent profitability metrics, Novacyt currently qualifies as a High Flyer. However, whilst the Value Rank may languish behind the high Quality and Momentum Ranks, this might improve in the near future.
Novacyt comfortably qualifies for Greenblatt’s Magic Formula screen, with a Return on Capital (TTM) of 182.6% and an Earnings Yield (TTM) of 9.32%.
Business & Model
Novacyt was established in 2006 and has made a series of acquisitions in recent years. The timeline below gives you a historical overview of how the company has evolved.

Source: Novacyt
The Group now operates through 3 main subsidiaries: Primerdesign, Microgen Bioproducts and Lab21 Healthcare.
Primerdesign is a world leader in qPCR assay development used for diagnostics. The company was one of the first in the world to produce a highly accurate Covid-19 test in January and quickly received CE certification and FDA approval. It also became one of the first recommended tests to use by the World Health Organisation.
Ongoing evaluation of Covid-19 mutations has tracked over 84,000 unique SARS-CoV-2 (Covid-19) viral sequences and the test is still demonstrating 100% accurate detection. It is one of the most sensitive and specific tests on the market.
A series of new innovative products have been launched by the company in recent months, a list of which can be seen below:
- Exsig™ Direct, Exsig™ Mag and COVID-HT were developed to help support laboratories to improve workflow efficiency and help address the shortfall in global manufacturing and supply of reagents. This has helped to increase output and speed up testing turnaround times.
- Launch of a 2 gene test for specific markets (France, India, UAE) which require this. 100% detection maintained.
- Development of a Near Patient Testing (NPT) system, using the company's q16 and q32 testing instruments. The q16 allows for 14 tests to be carried out at a time (2 for controls) with results within an hour. Average 4m 30 seconds per test. The q32 allows for 30 tests to be carried out at a time (2 for controls) with results within an hour. Average 2 minutes per test. This system is portable and can be plugged into any laptop for results. Tests do not need to be sent to a lab and no lab professional is required.
- Saliva testing products have also been developed to support easier patient sampling and lower levels of discomfort.
- Winterplex™ test developed to diagnose and distinguish between Influenza A&B, RSV and COVID-19 ahead of flu season. One contract has already been signed with UK DHSC, more on this later.

Source: Primerdesign
Microgen Bioproducts is more focused on the development of high quality diagnostics products. Its Food & Industrial microbiological products include Biochemical Identification Kits, Bacterial Typing Antisera and Pulsifiers to name a few.
On the Clinical side the company’s PathFlow Rapid Tests, which can be used for the detection for Influenza A&B, Mononucleosis, Adenovirus and much more, typically generate results within 5-15 minutes. There are many other products available such as pregnancy tests, fungal serology and more recently a new SARS-CoV-2 IgG EIA test.
The SARS-CoV-2 IgG EIA test is a serology (antibody) test that has been developed with a partner to detect past infection of Covid-19. This will be vital in not only identifying general levels of immunity amongst the population but also in evaluating the success of vaccine trials. The focus on IgG antibodies (which appear after 2 weeks of infection) has allowed the company to develop a highly accurate test (100% sensitive and 99.4% specific), whilst many competitors have been unable to replicate this success.

Source: PR Newswire
Specialising in the manufacturing and sale of reagents and test kits for In Vitro Diagnostics and blood grouping applications, Lab21 Healthcare has an expansive product portfolio. Infectious diseases, thyroid function and fertility products are some of those offered by Lab21.
What is the company's business model? How does it make money?
In the UK the company sells directly to leading organisations such as the NHS. It is currently one of the leading suppliers of Covid-19 tests to the DHSC, having signed a contract back in April this year (initially committed to supply 288,000 tests per week to the DHSC for use in the NHS, with the option to expand the agreement).
Novacyt also forms a key part in the provision of testing equipment and expertise to the national Lighthouse labs. The company is in partnership with major pharmaceuticals such as AstraZeneca and GlaxoSmithKline for work in the Lighthouse labs, which are crucial to the national testing effort. In fact, Novacyt's Covid-HT test, which allows for higher throughput on AZN's testing platforms, was seemingly designed for this purpose.
It also supplies testing to the private sector. The new decentralised testing systems developed means that medical professionals are no longer required, and the tests do not need to be sent back to labs. This is ideal for sports venues, mining sites, airports and care homes to name a few. Primerdesign has also created an app to assist clients with their testing needs.
Novacyt currently distributes its products in over 130 countries around the world. It has a sophisticated OEM distribution network, which has allowed the company to rapidly expand its presence in key markets without being overstretched.
Market & Competition
The In Vitro Diagnostics (IVD) global market is expected to be worth $69.5 billion in 2020. This excludes Covid-19 testing, which is estimated to be worth an additional $20 billion this year.
The demand for Covid-19 testing looks like it will dramatically increase in the coming months. The WHO message to world nations remains "test, test, test" regardless of the degree of symptoms.
With the flu season coming up in the Northern hemisphere, the company's Winterplex test will be vital in assessing Covid-19 and flu trends across the population.
If you think about the current world population (over 7.8 billion) and multiply this by the number of times each individual might be tested (for work purposes, international travelling, sporting/social events, symptoms, pre-surgery, care home visits etc.), you can see the scale that might be needed for testing in the short-term.
Taking a longer-term view, the diagnostics market is likely to play a greater role in our society. The IVD market has been growing at a CAGR of 5% over the past 5 years, with some analysts expecting the IVD market to be worth $110 billion by 2030. Growth drivers, as listed by the company in its Annual General Meeting include:
- ageing world population
- increased technological innovation
- rising living standards in developing countries
- industry consolidation
- an increase in the incidence of chronic and infectious diseases
The UK has also stated that it wants to become an international leader in the diagnostics market in the years to come, it has launched initiatives such as the five pillar testing strategy to try and achieve this.
Competition
The global IVD market is highly fragmented with many players around the world, both large and small. It currently looks as though that even with new entrants and existing expansion of manufacturing by the larger players, capacity will still remain well below global demand.
In the UK, the direct competition, especially with regards to Covid-19 testing remains: Avacta, Genedrive and Omega Diagnostics. These companies all have their own merits and drawbacks. Each is at a different stage of the development cycle, with slightly different science & technologies being used, but definitely worth bearing in mind if venturing into Covid-19 focused stocks.
Internationally, some of the main players in the market include: Abbott, Qiagen, Roche and Thermo Fisher Scientific.
What is the company's strategy & competitive advantage?
Novacyt's vision is 'To become a market leader in Respiratory and Transplant clinical diagnostics'.
The company's foresight to rapidly develop a Covid-19 test in late 2019, after the virus first emerged in China, meant that it had a CE accredited, FDA and WHO approved product, which it could start to sell by the end of January. This first-mover advantage has allowed the company to establish key strategic relationships with governments, OEMs and private institutions around the world.
The revenues generated from the early sales of Covid-19 tests has also enabled the company to reinvest into significantly growing manufacturing, recruiting personnel and expand R&D efforts to stay ahead of the competition. Manufacturing capacity has been increased by 100 times since the start of the year and the supply chain has been improved and de-risked. The company has also strengthened its commercial support structure by hiring an additional 60 new roles through the first half of the year.
The company derives its competitive advantage from the rigorous clinical evaluation of its products and constant R&D innovations, making their tests some of the most reliable on the market.
The role the company now plays in assisting governments and various national organisations also gives it enhanced insight as to which products should be developed or focused on moving forward.
As can be seen by the quality metrics below, the margins in the diagnostics industry are very attractive. The company is in the top decile for Returns on Capital, Returns on Equity and Operating Margins when compared to its industry group.

What trends are the company currently benefiting from that could provide a tailwind?
According to a variety of news outlets, ‘Operation Moonshot’ is set to become the government’s main plan to get the economy and normal life functioning again as much as possible. The plans include testing up to 10 million people per day across the UK by early 2021.
The global demand for testing is also showing no signs of slowing down, with cases rising exponentially in many countries around the world. Research by McKinsey shows that ‘many regions around the world are experiencing a shortage of laboratory-based molecular-assay tests’.

The delays in the provision of a vaccine have also meant that the timeframes for Covid-19 testing have been significantly extended. Many firms are already reporting that testing contracts have been extended to at least half way through next year.
Recent History & News
Novacyt has seen a period of strong sales growth over a number of years. However, you can see how the pandemic has caused revenues to hit new heights after a record-breaking year. Indeed, the sales growth over the last 6 years now stands at a CAGR of 23.6%.

The company was loss-making until this year. However, given the profitability of current Covid-19 products and expansion of sales, the company will likely maintain a high level of profits moving forward.
What's been happening in recent trading statements etc?
Transformational financial results for H1 this year.
- Consolidated unaudited revenue increased over 900% to €72.4m.
- Gross margin strengthened to 83%, delivering gross profit of €60.3m.
- EBITDA profit of €49.4m.
- Profit after tax of €40.2m.
- Cash of €19.7m after settlement of all debt and investment in stock.
Great forward guidance for H2.
- Full-year revenues are expected to now significantly exceed €150 million given current visibility of orders and launch of new products.
- EBITDA to ‘significantly’ exceed €100 million.
New contract for DHSC.
- Six month contract in 2 phases to deploy up to 1000 q16/q32 instruments with full range of COVID-19 reagents across UK NHS.
- Phase 1, 300 instruments, for a duration of 24 weeks, expected to be worth a minimum £250 million.
- Optional phase 2, 700 instruments could be worth an additional £500 million.
Catalysts & Risks
The results from a 2,000-patient clinical trial by Queen Mary University of London using the Group’s innovative Near Patient Testing system, which finished in late September should be available soon. The trial was used to evaluate how effective the NPT system is in catering for outbreaks in care homes across the UK, of which there are currently over 2,000.
Management has reiterated its desire to develop & expand both its Covid-19 and non Covid-19 product portfolio. Microgen just recently added 5 new PathFlow products to its range, which can be seen here. The company is constantly innovating and more products will likely be launched in the coming months.
There could equally be new contract wins from key markets. Expansion in the US, which is considered a key market for future growth by the company, might also lead to a re-rating of the share price.
At the Annual General Meeting, management also discussed that acquisitions will most likely be made in the coming months. Investors may appreciate the future diversification of product revenues. The slide below is taken directly from the AGM.

Broker notes should also come out shortly, potentially leading to an increase in interest, particularly from institutions. Numis and ODDO BHF were recently appointed as new brokers in September to initiate equity coverage for the firm.
What are the biggest risks for the business?
Vaccine risk - The development of an effective vaccine would inevitably lead to lower levels of Covid-19 testing over the longer-term. Whilst industry analysts expect Covid-19 testing to remain at the forefront of our battle against the virus until the year 2027, an effective worldwide vaccination programme would mean there is really no need for testing vaccinated individuals (unless the vaccine only provides a temporary immunity boost).
Rapid Test risk - The company may suffer from a significant drop in revenues from the development of a vaccine, but it may equally do so if a competitor develops an ultra-rapid Covid-19 test, which delivers accurate results in minutes/seconds.
Acquisition risk - The company seems intent on making acquisitions to strengthen the company and avoid a significant drop off in revenues post Covid-19. Whilst these may pay off, they may equally prove costly down the road and become a burden.
Operational risk - Whilst rapid growth rates are what most companies dream of achieving, it can also sometimes create issues within an organisation. Smaller companies can benefit from more streamlined organisational structures, and are arguably more efficient as a result. The operational risk of expanding too quickly, or distractions from new unforeseen issues (such as IT issues, bottlenecks in production/distribution, hiring constraints etc.) is something that should be considered by investors.
Ownership & Management
Only a relatively small amount (8.5%) of the share capital is owned by management/founders.
However, there is a key share incentive plan in place linked to performance and directors have been buying in recent months though, as can be seen below.

Has it a history of diluting shareholders, or (better) buying back shares?
The company does have a history of issuing equity. However, given the current financial position of the company and net cash position, this is less likely to be an issue moving forward.
Valuation & Financial Strength
The current Value Rank of 38 does not reflect the relative valuation of the company. There is a lack of forecast estimates from brokers (which are used to compute the Value Rank) and the Value Rank might actually go up much higher once these are available.
Despite this, the company’s Price to Earnings ratio, Price to Free Cash Flow and Price to Sales all imply that the company is relatively undervalued when compared to its peers.
If we were to compute a rough forward P/E ratio ourselves, using the guidance the company has so far provided after its H1 results, the valuation looks even more compelling.
The earnings per share can be estimated at £1.67 (total earnings of £118 million for the full year / number of shares outstanding 70,626,248). If we take the current price and divide this by forward EPS ( £7.40 / £1.67) we get a forward P/E ratio of 4.43.
What is the company's financial status & balance sheet strength?
The company is in a strong financial position. Net cash currently stands at €19.7m (as at June 30th 2020) and the company also holds strategic inventory levels.
Its financials are also rapidly improving - the F-Score is a near perfect 8 out of 9, with profitability, leverage, liquidity and efficiency metrics all improving.
Sentiment
What would the person selling to us be thinking and who are they?
Investors who bought at high levels when the shares ran up to a price of £5.20 in April may be keen to take their profits. Equally, early investors may be happy with their astonishing returns.
It is worth keeping an eye on vaccine developments, as investors might start to panic sell should encouraging data be released.
What is private investor sentiment at the moment?
Very bullish, largely due to the recent coverage in the news and the government's testing plans going forward. The UK governments 'Operation Moonshot' seems to have peaked interest in Covid-19 testing companies. In this current climate Covid-19 focused companies are even being seen as 'safe havens' by some.
Technical Analysis
How strong is the relative uptrend/downtrend?
The stock is currently in a very strong uptrend, as can be seen in the chart on the first page, with the price well above both the 50d and 200d moving averages.
The stock does appear short term overbought - the RSI of the stock stands at 91, so it is quite possible that there may be a correction ahead. In spite of this, the Investment Club has initiated a position based on the strong newsflow, low valuation and size of recent contracts.

Conclusion
After the pitch, how did the investment club vote?

With the majority voting to purchase the shares, we acquired an average-sized portfolio position in Novacyt on the 8th October at a price of £7.24 per share.
Disclosure: I hold a long position in this share at the time of writing.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

123 comments
Hi, Does anyone know if the Club still hold this share? The recent news were bad however I believe ( hope) a recovery can happen and the risk/reward ratio is attractive. Cheers
Novacyt (which I hold) issued an RNS today with what I think is a very encouraging research and development update:
https://novacyt.com/wp-content/uploads/2021/02/Novacyt-RD-Update-24.02.2021-correction-ENGLISH.pdf
Novacyt's house broker SP Angel has issued a new note on the company following its recent trading update:
https://novacyt.com/wp-content/uploads/2021/02/SP-Angel-Update-04.02.2021.pdf
Thanks! I blow hot and cold . The savage drop around the recent trading update and lack of institutions buying-in dents confidence that this is more than a one-trick pony. Looking at the SP Angel numbers, a very crude, cautious, guestimate per share would be:
Cash at 31.12.20: 130p
'Underlying'/'Sustainable' business: EPS 65p x P/E 10 = 650p
'Windfall' 2021 EPS: 130p
which totals 910p, not a lot above the current 780-800p range.
Clearly the Windfall element could be a lot higher, but news on the large DHSC contracts is still awaited. Phase 1 may be extended; phase 2 might happen. Against that, there seems a clear push in the UK towards rapid LFT testing and the decline in new cases (now 20 to 25% a week, looking at Worldometers figures for each day compared with 7 days ago) is strong, despite the more transmissible new variants, and that's before the main benefit of the vaccination program. Margins I'd guess are more likely to fall than rise with any new contracts. The UK may wish to encourage more competition, given the publicity over some covid-related contracts. I know Novacyt Sa (LON:NCYT) say they have an LFT nearing release - this should be materially 'better' than existing LFTs (otherwise they would have stopped development). So they may have a new revenue channel for mush of 2021. PCR testing for travellers may also extend the runway and this should be a high-margin activity. International sales may take up a fall in UK revenues but international competition is surely strong. The Winterplex thing sounded a winner a few months ago, but flu sounds to have been largely eliminated this year, so perhaps there's not much demand.
As for the Sustainable element, there's massive uncertainty. They clearly have the ability to develop a suite of new diagnostic tests rapidly, but arguably are a new player in an existing pool, competing with established firms. SP Angel suggest somewhat north of 10% pa EPS growth after 2023 (which they project as slightly lower than 2022) and obviously a higher P/E would be warranted if they can achieve that - but I don't see it as a given that they will at this early stage. Interesting also to read the weak update from Yourgene Health (LON:YGEN) whose sp rose on covid testing hope sin the summer but has now dropped far back.
So I'm left thinking it's all too difficult - there's such a range of possible outcomes! Never say never, but I'd hope the downside isn't too far below the current sp.
As for 'Novacyt Insider ' - I'm very wary. Why should someone go to the expense of developing and updating a flashy website unless it's to ramp the share price? I don't see a lot of critical views. And 'Insider' is a worrying term in a share trading context!
I have been reading that it will take up to 7 years for the globe to reach herd immunity. That to me means we will still have travel restrictions and testing requirements for nearly the next decade. While that is a incredibly depressing thought, I guess it will be good for Novacyt.
Ref: https://www.bloomberg.com/grap...
Novacyt's new testing product, Promate, which is easier to use in non-laboratory environments, has now been validated by the UK government:
https://www.gov.uk/government/publications/assessment-and-procurement-of-coronavirus-covid-19-tests/coronavirus-covid-19-serology-and-viral-detection-testing-uk-procurement-overview#products-in-the-pipeline-tvg
https://assets.publishing.service.gov.uk/government/uploads/system/uploads/attachment_data/file/957995/TVG_Report-PROmate.pdf
As I wrote previously, there is a useful article about the significance of Promate here:
https://novacytinsider.com/promate-revealed/
In my opinion, this increases the probability of Phase 1 of DHSC's contract with Novacyt being extended and also of Phase 2 being awarded.
Here are links to last week's trading update from Novacyt (which I hold) and to an RNS it issued earlier this week about new test products it has created which can detect and distinguish between the new Covid variants:
https://www.stockopedia.com/share-prices/novacyt-sa-LON:NCYT/news/novacyt-sa-full-year-2020-trading-update-urn:newsml:reuters.com:20210129:nRSc2952Na/
https://www.stockopedia.com/share-prices/novacyt-sa-LON:NCYT/news/novacyt-sa-launch-of-pcr-assay-portfolio-urn:newsml:reuters.com:20210202:nRSB6347Na/
Novacyt (which I hold) is expected to provide information about its 2020 annual revenues before the end of January, i.e. sometime next week:
https://novacytinsider.com/2020revenue-expectations/
They have also released a new Covid testing product called Promate which is easier to use in non-laboratory environments:
https://novacytinsider.com/promate-revealed/
There was an RNS today saying funds managed by Blackrock now own 3.54% of Novacyt's shares:
https://www.stockopedia.com/share-prices/novacyt-sa-LON:NCYT/news/novacyt-sa-holdings-in-company-urn:newsml:reuters.com:20201202:nRSB3086Ha/
https://www.independent.co.uk/news/health/coronavirus-rollout-of-rapid-testing-machine-in-english-hospitals-to-be-halted-b1762732.html
Bit of a row going on about this article in the Independent. There is a statement in the article itself that the government refutes the headline, has no plans to replace the machines (which have been validated) and is continuing the rollout. One wonders how journalists can get away with it.
I am having difficulty obtaining information from Novacyt, and was wondering if anyone had worked out the correct figures concerning the payout on the LTIP? This is material, as profits made from COVID 19 could be considered a windfall/temporary, and the company was not profitable before COVID. I would like to estimate the amount of cash Novacyt will have when the bonanza is over so that I can value the company more accurately.
My best guess is here, but it may be materially off, and Novacyt has not directed me to the exact terms of the phantom option scheme. I worry that obfuscation is deliberate. Is there a regulatory reason why the company cannot give an accurate statement concerning the terms of its LTIP? —
A previous poster suggested that the phantom options issued to two directors were worth 4% of the company. I have not been able to verify this despite an extensive search. I am surprised that documentation is not available on the Novacyt website. I have verified that these options would be paid in cash around November 1st 2020 based on the grant price set on Nov 1st 2017. Novacyt opened at 61p on Nov 1st 2017 and opened at 10.50p on Nov 1st 2020. I’ll use these figures as they will be close. 4% of Novacyt was c. 1.5 million shares (…assuming that 4% of the company is correct, that this 4% was based on the share count on Nov.1st 2017 and not based on the market cap Nov 1st 2020, and is not altered by any warrants, convertible bonds, and contingent consideration, etc.). So 1.5 mil times (10.50-.61)= c14.8 million pounds payout in cash to two directors for the LTIP.
I have no doubt that the company could meet this bill on Nov 1st. I am slightly concerned about the size of the payout, but there is no question that management has been quick to seize an opportunity here. The company before COVID did not look like it would survive, and was riddled with dilutive warrants and convertible bonds, and burdened with loans and contingent consideration. Most, if not all of this has been paid off, unfortunately resulting in serious dilution.
Here is my correspondence with Investor Information at Novacyt, including information in italics taken from RNS:
Dear Mandy Cowling,
How much cash did the LTIP payout? I am having difficulty calculating this from available information.
Can you confirm that this was paid on November 1st?
Are there currently any other LTIPs in existence?
Thank you,
Laurie xxxxxx, private investor
Long Term Incentive Plan
Novacyt granted certain employees 'phantom' shares under a long term management incentive plan adopted on 1 November 2017. The exercise price is set at the share price on the grant date and the options will be settled in cash. The options will fully vest on the third anniversary of the grant date.
Dear Laurie,
The current LTIP scheme is explained in our Annual Report & Accounts (see 2019) https://novacyt.com/financial-reports/#1600339350926-e05b413e-b49a
The pay-out under this scheme in 2020 will be disclosed as part of the 2020 accounts.
Kind regards,
Mandy
Yes, I saw that, but there isn't enough information to work out how much the payout was. My estimates varied between £23million and a bit over £29 million paid to two directors this November. I suppose I can ask if my estimate is correct by posting on a bulletin board or public share blog, but I would rather have accurate info from the company. Was it 4% of Novacyt's market capitalization on Nov. 1st, minus c. 58p a share?
Long Term Incentive Plan Novacyt granted certain employees to purchase shares under a long-term management incentive plan adopted on 1 November 2017. The exercise price is set at the share price on the grant date and the options will be settled in cash. The options will fully vest on the third anniversary of the grant date. The payment expenses are calculated under IFRS 2 “Share-based payments”. The accounting charge is spread across the vesting period to reflect the services received and a liability recognised on the statement of financial position
Morning,
Apologies if our answer is not detailed enough but we are not prepared to disclose further details in relation to the LTIP at this stage. These amounts will be disclosed in full as part of the 2020 accounts when they can be viewed in the context of our overall financial performance.
If they turn in full year profits of £300m plus (might be £400m plus) then who is complaining? Not me. They have earned it in my view.
Here is some recent news about Novacyt (which I hold):
CEO acquires £497k worth of its shares:
https://www.stockopedia.com/share-prices/novacyt-sa-LON:NCYT/news/novacyt-sa-directorpdmr-shareholding-urn:newsml:reuters.com:20201112:nRSL0564Fa/
R&D update:
https://www.stockopedia.com/share-prices/novacyt-sa-LON:NCYT/news/novacyt-sa-rampd-update-urn:newsml:reuters.com:20201116:nRSP3501Fa/
To put the R&D update into some context, here is an article (on what some might consider to be a 'fanzene' website) about the interim results of the UK government's care home trial of Novacyt's products:
https://novacytinsider.com/carehome-interim/
Public Health England has published a tender notice for a National Microbiology Framework which will be worth about 22 billion pounds over the next two years:
https://bidstats.uk/tenders/2020/W45/738328646
I would expect some percentage of that money will be spent on equipment and reagents provided by Novacyt. Even a very small percentage of such a huge amount would be highly significant for Novacyt's profits.
There's an article published today on the Sharebuyers website with a list of ‘COVID stocks’ that the author likes and Novacyt is the first stock mentioned:
https://www.sharebuyers.co.uk/shares/the-rise-of-covid-stocks-big-likely-winners-revealed/
What do you guys think of Boris Johnson's speech talking about rapid covid tests being the way things will be progressing with testing ? negative effect on novacyt price ?
Imo, not long term, maybe short term wrt sentiment. Rapid testing will be LAMP based testing. Diagnostic confirmation will be via PCR testing. Primerdesign supply one of the two CE marked PCR tests being used nationally in the UK, afaik.
Based on the suppliers of these tests, it is likely they will be servicing worldwide demand.
I see another small UK testing company, SourceBio, is joining the covid-IPO bandwagon (sorry, for some reason this appears not to be a clickable link)
https://www.thebusinessdesk.com/eastmidlands/news/2042345-covid-19-testing-business-raises-35m-in-ipo?
I haven't dug deeper but assume they're more akin to Yourgene Health (LON:YGEN) than Novacyt Sa (LON:NCYT)
Imo, more like Randox than Yourgene.
Stockopedia at present says Novacyt's one-year volatility is about 165%, which is huge compared to most other stocks. For those people who may like Novacyt's prospects, but find the tremendous volatility in its share price difficult to cope with, a possible approach is to combine a holding in Novacyt with holdings in one or more of the following low-volatility multi-asset investment trusts:
Capital Gearing Trust, CGT (one-year volatility about 10%).
Personal Assets Trust, PNL (one-year volatility about 10%).
Ruffer Investment Company, RICA (one-year volatility about 16%).
This is just an idea, not a recommendation!
Why not just hold less of it in your portfolio?
"Why not just hold less of it in your portfolio?"
That is an option, of course. But if one thinks Novacyt will perform well in the long-term if one can cope with its volatility, why hold less?
relatively speaking those are low volatility but they are not really, volatile markets!
Here is a video that has just been posted of a discussion about Novacyt with Vadim Alexandre, who is a health-care analyst at one of Novacyt's house brokers:
https://www.youtube.com/watch?v=7T4J7hmNDgg
I found this article about the SETSmm system, which Novacyt is apparently now on, informative:
https://www.proactiveinvestors.co.uk/companies/news/81/idiots-guide-to-the-london-stock-exchanges-setsmm-0379.html
Very informative, thanks for posting. It does seem to suggest it’s only of real relevance if you’re trying to track the order flows to gauge whether to trade or not, or am I misunderstood?
I think SETSmm provides an alternative way of matching buyers and sellers to the market makers, so it reduces the risk to market makers of being stuck with large volumes of shares that are falling in price. From what I've read, this might reduce bid-offer spreads on average for stocks that are on SETSmm. Perhaps it might also discourage market makers from playing games such as "tree shakes", but I'm no expert on this.
Novacyt's share price dropped by 30% over the last three days and is up by about 10% this morning as I write. Some posters on LSE have suggested that the rise this morning is because its shares started to trade on SETS this morning. Does anyone think this is a plausible explanation?
It seems that Novacyt is on a massive recruitment drive, and with a more recent emphasis at their Camberley division (Microgen)
PDF showing recent adverts
https://filebin.net/6dcyu36u6g...
A former director of immunisation at the Department of Health says a targeted immunisation programme may offer some protection, but it will not deliver ‘life as normal’:
https://www.theguardian.com/commentisfree/2020/oct/21/covid-vaccine-immunisation-protection
Which implies Covid testing will be needed for quite a while, even if vaccines are available soon.
Any 'vaccine' will not be a true vaccine anyway. A true vaccine is administered once then you have immunity from the disease for life.
Corona virus vaccines, such as the flu vaccine, are a mix of vaccines against the most virulent strains present in Asia the previous flu season. Usually 4 different ones combined and it changes annually. Therefore, imo, this will be an ongoing arms race: medical science vs the mutagenic potential of Sars-Cov-2.
Testing isn't going away any time soon.
Do I really need a flu vaccine every year?
Yes. CDC recommends a yearly flu vaccine for everyone 6 months of age and older with rare exception. The reason for this is that a person’s immune protection from vaccination declines over time, so an annual vaccination is needed to get the “optimal” or best protection against the flu. Additionally, flu viruses are constantly changing, so the vaccine composition is reviewed each year and updated as needed based on which influenza viruses are making people sick.
Please don’t conflate it with the flu virus. Coronavirus is a different category. Comparison to flu vaccine is completely misleading for that reason. Even comparing it to other coronavirus like the common cold, for which there is no vaccine, is misleading.
The concept of ‘true’ vaccine is fairly useless. There are many where you need a booster after a time and many that don’t give life long immunity, such as whooping cough, but we get herd immunity from the high numbers receiving the vaccine.
‘Corona’ is a category of virus.
Infuenza viruses are Corona viruses.
We have yet to develop a vaccine for SARS & MERS, please explain why a reliable one, that meets acceptable regulatory requirements for SARS-Cov-2, could come more readily?
Infuenza viruses are Corona viruses.
Are you able to provide a reference to a reliable source that supports that statement?
https://www.cdc.gov/coronaviru...
https://www.ncbi.nlm.nih.gov/b...
https://coronavirusexplained.u...
Metaphorically, I draw the comparison to flu to highlight the behaviour of the type of virus’. It will mutate and emerge in another form, as the flu does:
When the new strain emerges, Novacyt Sa (LON:NCYT) will get a sample and issue a new test.
None of those references support your statement, even metaphorically.
Why on earth has someone decided that DWit199’s post should be reviewed?
Your overtly pedantic response contributes nothing to this discussion.
Please explain why they do not, I have attached the definition of metaphor for you to review.
https://en.m.wikipedia.org/wik...
A down arrow is not an explanation.
"Squash the Sombrero" is an excellent metaphor but to claim that SARS-CoV-2 is a Sombrero would be absurd. There are many similarities between different respiratory viruses and drawing a parallel between them in a post or article is justified but to claim that an influenza virus is a corona virus is just plain wrong.
ps I didn't down vote your comment
I will defer to your pedantic, self righteousness on the precise point of my neglecting to use ‘like’ to ensure the metaphorical sense was fully conveyed as factually you are correct.
However, the context of my original point was a comparison of the mutagenic potential of the Corona & Influenza virus’ , in that sense they are quite clearly similar.
Forbsy
How do you know that the Covid-19 virus will mutate in a similar way to the influenza virus? Perhaps it will mutate like the common cold viruses, some of which are coronavirus (afaik). But perhaps less rapidly than either of those.
We cannot infer with any confidence what Covid-19 will do from what flu viruses do.
Graham,
As also highlighted by DWit, the virus was named SARS-Cov-2 (the disease it causes is called COVID 19).
By implication, the nomenclature is such that the scientific community clearly expects to have to deal with SARS-Cov-3 at some point in the future.
I'm not a virologist but have some knowledge in this area - happy to be corrected on any points of fact by anyone willing to state their credentials.
Of course I don't know exactly how it will mutate, but what I do know is that they are both RNA based virus categories and are therefore similar in their mutagenic potential.
https://en.wikipedia.org/wiki/...
An excerpt for you:
Mutation rates
RNA viruses generally have very high mutation rates compared to DNA viruses,[5] because viral RNA polymerases lack the proofreading ability of DNA polymerases.[6] This is one reason why it is difficult to make effective vaccines to prevent diseases caused by RNA viruses—diversity is their strength.
In my lifetime I have seen the identification of Bird Flu, Swine Flu, SARS, MERS & SARS-Cov-2.
Of course I don't know exactly how it will mutate, but what I do know is that they are both RNA based virus categories and are therefore similar in their mutagenic potential.
I'm sorry to have to say this but there are fundamental differences between corona viruses and influenza viruses. You need to research antigenic drift, random mutations which affect both, and antigenic shift which affects influenza as a result of the structure of its genetic material but corona viruses are unaffected.
Fair enough, you are getting a bit beyond my level of expertise and interest. Thanks for acknowledging the similarities.
you need to research antigenic drift, random mutations which affect both
I sold out of my Novacyt position today as seems to be hints we have a vaccine coming out and rolling out ... seems at break neck speed and abit scary healthcare workers will the the first in the trenches (why not our political elites ?); have done amazingly well on what money I've put in - better than any trade in my life actually; I find it very hard to value Novacyt and any company which will likely have ongoing short lived (but how short lived is the question ?) work into next year (this horrible little virus isn't going to go away without a fight); what are others thoughts ?
Hi Memoimoi2017,
You wrote:
"I find it very hard to value Novacyt and any company which will likely have ongoing short lived (but how short lived is the question ?) work into next year (this horrible little virus isn't going to go away without a fight); what are others thoughts?"
I suggest you read Vadim Alexandre's views on these questions at:
https://novacytinsider.com/vadim-alexandre-on-novacyt-and-peers/
although you should bear in mind that he works for Novacyt's broker, so his views might not be impartial. But I'm convinced enough by his arguments to continue holding Novacyt.
So far, it’s just pulled back to the 5 EMA on the weekly chart. Normal behaviour in a significant uptrend so no panic for me just yet!
A possible explanation for the significant pullback in Novacyt's share price over the last couple of days is a fund selling some of its holding in order to keep it within its allowed upper limit as a percentage of the fund, at least according to this article:
https://novacytinsider.com/oct-fund/
Another possible explanation is that some shareholders are concerned that press reports yesterday about a vaccine coming soon might adversely affect Novacyt's future revenues and have sold shares.
Here is a link to a broker note by SP Angel, who are one of Novacyt's two appointed brokers so they are not independent of Novacyt:
https://novacyt.com/wp-content/uploads/2020/10/2020_Oct_SP_Angel_Novacyt_Initiation_Note_21.10.2020.pdf
And here is the transcript of an inverview with one of the analysts who prepared that broker note, Vadim Alexandre:
https://novacytinsider.com/vadim-alexandre-on-novacyt-and-peers/
Here is a link to a PI World interview with two fund managers on 22 October in which they discuss Novacyt at about 34 minutes from the start:
https://www.piworld.co.uk/2020/10/23/piworld-interview-an-hour-with-andy-brough-richard-leonard/
What is predicted target price for NCYT ? Looks like i am too late to jump in. Thanks.
£15 is the short term target. It’s just broken £10 so I think it will get there. I’d expect more profit taking at £15 but I doubt it would drop back below £10.
£34 is the long term target And there is lots of news to come.
Numis predicting 2021 will be even bigger revenue and by December NCYT will have 200million cash in the bank. So they have the means to evolve themselves and diversify away from Covid reliance and into a leader in diagnostics
It would be really nice to have a sales update as so far all we are really aware off is the NHS contract.. But they are selling too 134 countries. Sales could be a lot larger than we have been led to believe.
so £9-15 depending on the NHS contract. £15 plus depending on acquisitions and other unknown positives
YouTube video of Novacyt's AGM on 29th September:
https://www.youtube.com/watch?v=amjoVe7ihck&feature=youtu.be
I think there is some useful information about Novacyt on this website, although it could be accused of being a "fanboy" one:
https://novacytinsider.com/
Yes that site was created by @TaylorQuant - a big NCYT promoter on Twitter. Novacyt Insider has definitely been set up with a single goal in mind - helping promote the NCYT story to retail investors. There do appear to be a variety of different contributors - some from the UK some from France. I do think it's a fan site created by a collective of Twitter connections who have been long NCYT from early on - although the whole "insider" label does make you wonder. How many listed companies have their own websites run by excited shareholders???
I remain long. Good session on NCYT at Mello last night... I was on the panel and three out of four of us voted "Buy" for NCYT, one voted "Hold". The audience - perhaps 300 members - all voted fairly similarly.
Hi Ed,
I was in the audience of the Mello session last night. I found the panel's discussion of Novacyt very useful and insightful. Thanks for your own contribution.
Here is an article about Numis's broker note:
https://www.sharebuyers.co.uk/shares/numis-broker-note-says-novacyt-share-price-could-quadruple/
The broker note is very bullish. However, one should bear in mind that Numis was appointed as a broker by Novacyt and the note says it is a "marketing communication".
Here is a tweet about a broker note by Numis about Novacyt which was issued today:
https://mobile.twitter.com/rick_shares/status/1317030953592684544
If anyone would like to learn about the differences between and the pros and cons of the various types of test for Covid, including PCR and LAMP, there's an article on this subject at this web page:
https://www.cebm.net/wp-content/uploads/2020/04/CurrentCOVIDTests_descriptions-FINAL.pdf
Yet another 5 minute test announced today, though still on the drawing board
https://uk.reuters.com/article...
Sounds LAMP based, not PCR. Personally, I'd like to know if NCYT have any LAMP based technology/tests in development - I can't seem to find anything to confirm one way or the other, if anyone has any info please add? If they don't, I'd instead like to see them add a company that has LAMP technology IP as part of their acquisition strategy.
quality has a price.If the Oxford reports are a measure of the virus profile , regular testing will become the norm.So just as we scan passports, instant testing and analysis will become the norm.As biometrics are incorporated in documents its clear that testing of the person will save lives and asdist in modelling future travel risk exposure. Given the global appetite the stocks not values based on reach so it looks like a bid target.
it may be irrelevant to today's RNSs but given the popularity of Novacyt Sa (LON:NCYT) here, and being bought in to Stockopedia SIC club at 724p, I would welcome and certainly appreciate thoughts of readers whether or not the recent pullback was healthy and the weak handed holders are off now, hence, price rise will continue? Cheers.
Mort1980,
You are most welcome to review & digest my research findings in order to come to a conclusion. https://filebin.net/obbxid0slw...
Plenty of other fish in the testing sea. From Ip (LON:IPO) RNS this morning (though a PI won't get direct exposure to Nanopore):
"IP Group plc (LSE: IPO) ("IP Group" or "the Group"), the developer of intellectual property-based businesses, notes that its portfolio company Oxford Nanopore Technologies Ltd ("Oxford Nanopore" or "the Company") has announced that it has raised an additional £84.4 million of new capital from existing and new investors including International Holdings Company (IHC) and RPMI Railpen.
The funds will be used to support the rapid acceleration of Oxford Nanopore's commercial and manufacturing operations as well as ongoing innovation in the field of nanopore technology. The round takes the amount raised this year by Oxford Nanopore to £162.1 million, following fund raisings in January and May of £29.3 million and £48.4 million respectively.
Following the capital raise, IP Group has a 15.0% undiluted beneficial stake in Oxford Nanopore, valued at £257.7 million. The directors will review the carrying value of Oxford Nanopore, as usual, as part of the Group's Annual Results for 2020 in light of this funding round and all other relevant information.
Last week, Oxford Nanopore announced that its LamPORE test is now CE marked for in vitro diagnostic use for the detection of the SARS-CoV-2 virus that causes COVID-19, using its GridION device. Its LamPORE test is now in the process of initial rollouts in the UK, Germany, Switzerland and the United Arab Emirates.
The Company previously announced that it had partnered with the UK's Department of Health and Social Care with an initial order of 450,000 LamPORE SARS-CoV-2 tests and the potential to increase to millions of tests per month as indicated by the recent publication of a contract award notice of £112.6m on the TED (Tenders Electronic Daily) website. Further regulatory approvals are being pursued in other countries, including Emergency Use Authorisation in the United States, and with its partner G42 in the United Arab Emirates."
I think we need to understand the differences and likely applications of both types of tests, LAMP based and PCR based. LAMP based is fast and requires a lot less equipment so is well suited to point of use /field setting applications.
However, until/if the LAMP based tests can match the 100% specificity achieved via PCR based tests, they will, for me, be utilised mainly in social settings to allow the economy to open up. PCR based tests are still likely to be used to confirm a clinical diagnosis following any positive LAMP tests.
"Scientists from the University of Oxford’s Nuffield Department of Medicine, Public Health England Porton Down (PHE), the University of Sheffield, Sheffield Teaching Hospitals NHS Foundation Trust have today published their evaluation of LamPORE, Oxford Nanopore Technologies’ SARS-CoV-2 detection assay. The paper is available at MedRxiv, the preprint server and studies more than 500 clinical samples.
The positive clinical specimens came mostly from patients with symptomatic infection, and among these LamPORE had a diagnostic sensitivity of 99.1% (i.e. it was positive in 226 of 228 samples positive by RT-PCR). Among negative clinical specimens, including 153 with other respiratory pathogens detected, LamPORE had a diagnostic specificity of 99.6% (i.e. it was negative in 278 of 279 samples negative by RT-PCR). Overall, 1.4% of samples produced an indeterminate result on first testing, and repeat LamPORE testing on the same RNA extract had a reproducibility of 96.8%."
https://nanoporetech.com/about...
The small percentile of cases not identified by LAMP is still too large when we consider the level of infectiousness this virus has shown, but the speed of testing provided by PCR alone is also inadequate to allow economies to open with consistency, therefore imo we are unlikely to be fully reliant on one test method over the the other for now.
Hi Wilbraham and Forbsy,
Thanks for both your posts about the positive news for Oxford Nanopore and explaining the difference between LAMP based and PCR based tests.
Prompted by this news, I have just bought a small position in the IP Group (which has a significant holding in Oxford Nanopore) to complement my recently purchased small position in Novacyt. So I now have small stakes in both the LAMP and PCR camps as hedges for each other. They are speculative investments, but I think the commitments from the UK government to the products of both companies reduce the uncertainty in their short-term prospects, and both their share prices have had positive momentum over the last few months.
760p today. What's that old saying? As soon as everyone is talking about a stock, that is the time it will fall? Too many people in at much lower levels in my view; although I am sure plenty will buy in if this fall continues.
Great research on £ncyt , thanks.
I bought in at 122p in March after my pf crashed and am glad to have done averaging up over the last 7 months.
I think that this one is a gem and my price targets have been shifting upwards as I let a good un run.
For me they consistently under promise and over deliver so I’ll be in a bit longer and I think it’ll thrive as we see more funds/institutional investors coming in.
I note the Twitter hype but a small group of posters do there pretty good research. just keeping an eye on the fundamentals and it still looks like it has legs for a while.
Herbie - the difference is that NCYT are generating massive revenues at high margins - DDDD and AVCT are not.
Certainly a rollercoaster ride, open at 875p then upto 970p and now back down to 860p.
I agree with Ed, this could crash like others with similar rises such as 4D Pharma (LON:DDDD) and Avacta (LON:AVCT) have done recently.
Hit 795p. I hold but long since on a freeroll having bought initially at 73p. I could easily see this tumble back to 600p or even lower as holders sitting on huge profits exit. It has risen from just six pence after all. Very volatile with very high volume.
On twitter the "noise" has actually stopped and a number of the strongest supporters have now sold; some as it got near ten pound. I personally think it will go higher in time but that short term it is perhaps up with events for now.
Price Target: €0.85(90.75%below Price), A little bit overpriced also ;)
I'd be just a touch wary of piling the truck up deep should it spike much further. Those with memories longer than a couple of weeks will recall the long drawn out NCYT 50% decline in late spring. My own recollection is fading but I suspect it was from an over-hyped rise coupled with the French govt refusing reimbursement for a single-gene test (now resolved). Bear in mind there's minimal institutional investment so far to give stability (obviously that could be a positive should it change) and there's huge (overwhelmingly bullish) chatter amongst the pis on advfn - sometimes 200 posts/day. Some talk of a pe of 10 which sounds weird for a stock with windfall revenues. Others claim the demand for testing will remain at current levels even after the roll-out of a vaccine, as folk will need to be tested regularly to check they still have antibodies - I accept there will be some testing of vaccinated patients but surely the purpose of the trials is to establish the durability of the immune response?
Finally, remain alert for novel, better solutions, eg the 30 second breath test announced last week https://seekingalpha.com/news/... which I assume is this https://www.israel21c.org/brea... Indeed I heard on the radio a moment ago that Ireland is to introduce airport testing but haven't established who the tester is.
NCYT was one of my half-dozen healthcare crapshoot/moonshot stocks in the spring. Overall they've done me well, at the cost of significant volatility, despite one major fail last week (4D, which had grown to my largest such position, fell 30% overnight on a poor IBS trial and has now been usurped by NCYT). Position sizing is key!
Good luck all.
Hi Wilbraham, many thanks for the link to seeking alpha. I have just read the article regarding the 30 second breath test for coronavirus and if this test becomes the new norm, then I believe Novacyt Sa (LON:NCYT) shares will collapse as quickly and as spectacularly as they rose. Let's hope NCYT is researching something similar to prop up it's share price for the future.
This kinda analysis is exactly what I've been looking for and offers me a fantastic blueprint going forwards.
Thank you for your thorough and in depth analysis.
We're all really bad at predicting the future - but I do think that Covid-19 will change the behaviour of western governments and pandemic mitigation funding for the next 50 years. Testing is here to stay, and the budgetary allocation to it (for Covid - or anything else) will be many, many multiples of what it was historically.
So while there is a temporary outsize earnings opportunity, I'm pretty sure we'll see the permanent creation of multi-billion cap companies in this arena. Whether NCYT is included in that or not, or whether they drop the ball remains to be seen.
NCYT's breakout after the last (astonishing) RNS was a classic QM Minervini/O'Neill setup with the benefit of a StockRank of 90+. I went long with 10% of my portfolio at £5 - I knew I should have gone larger - but risk management & downside protection is key. I'm finding in these markets that I'm doing far more discretionary stock picking than usual.
Hi Ed, can you please pass on my thanks to Keelan for an excellent piece of work, one of the best pieces of work I've seen regarding research and analysis. Obviously, it would have been nice if this report had appeared a while back but then again with the amount of detailed work which has gone into researching £NCYT I assume it has been a time intensive project. I am trying to work out if the stock will now take a breather for some air and whether a few sellers will now appear due to the recent meteoric rise in the share price. I too believe there will be more testing for viruses in the future, whether it be Covid or anything else. I believe we have been fortunate in this country that most virus have remained in Far East Asia and not reached us before.
Hi Ed,
You wrote:
"NCYT's breakout after the last (astonishing) RNS was a classic QM Minervini/O'Neill setup with the benefit of a StockRank of 90+. I went long with 10% of my portfolio at £5 - I knew I should have gone larger - but risk management & downside protection is key. I'm finding in these markets that I'm doing far more discretionary stock picking than usual."
If you put 10% of your portfolio into NYCT at £5, I guess that NYCT at £8.80 now represents about 16% of your portfolio. At what percentage of your portfolio would you start top-slicing NYCT for the sake of risk management and downside protection?
@pka - I'm not as bullish on this as Keelan or, to be honest, most of the private investor community - as there's a huge amount of risk in all directions. But I am planning on running the position next week. If something silly happens like it pops to £15, then I think it would be daft not to take the original stake off the table. But I'll definitely let the rest run and see what happens.
To be clear I'm expecting a nasty correction at some point. This kind of meteoric rise always comes with nasty pullbacks. The annualised volatility of this share is a ridiculous 165% so anything can happen. We classify as 'Highly Speculative' all shares above a 70% volatility. It just goes to show how uncertain the market is about the future outcome here. Twitter is a riot about NCYT at the moment.. which is a worry. The crowd tend not to be that wise... but occasionally, just occasionally they can be right on a share. We shall see.
Regarding rumours of institutional buying - the pound value traded has certainly spiked recently. £180m of shares have changed hands in the last 3 weeks. It will be interesting to see if any new funds appear on the major shareholders page soon or declare their interest.
Hi Ed, "Twitter is a riot about NCYT at the moment.. which is a worry".
I agree with your comment.
It might be my sense of humour but I find that when the office cleaner starts to talk about a particular share, eg, such as Novacyt Sa (LON:NCYT) or discuss Bitcoin, etc then it is time to get out!
Edward, I share your sentiment on £NCYT.
I've tried to model a spike in revenue for FY21 & 22 scenario and Novacyt Sa (LON:NCYT) potential valuations and a return to normal, assuming COVID-19 was no longer an issue by FY22. (see numbers and graph below).
Sales Forecast FY20-25
What valuation might look like with a 2020 and 2021 spike in revenues
The share price momentum has probably further to go and the valuation will look reasonable for the next few years, but not a share I would want to get involved with personally.
DYOR
BSV
do you still hold Ed? And do you think Novacyt Sa (LON:NCYT) is topped out (as Minervini puts it)?
thanks for your thought.
Yes, I still hold. I've made my views clear. I do think there are very binary outcomes on this share. It's highly speculative. I think there may be positive newsflow in this share through to the year end. But there could also be negative newsflow due to external factors - e.g. instant saliva tests from competitors, or vaccine success - or an unlikely swing in the collective's mentality where they suddenly say "the emperor, covid, has no clothes".
I do also think there's a silly speculative fervour developing in equity markets right now that has the potential to create some extreme bubble scenarios in certain sectors. This has been fueled by extreme fiscal stimulus which has whipped up retail investor interest - see the big moves in Nasdaq and in AIM stocks etc. There's going to be even more fiscal & monetary stimulus in the coming months. I would imagine the beneficiaries will continue to be technology, healthcare and probably precious metals stocks. What that means for NCYT - no idea - but I really wouldn't be surprised to see even more extreme blowoff tops in some stocks in the Covid sector. NCYT seems to me to be the safest bet due to the sales/earnings already booked - and the expected expansion in book value.
There's a saying in technical analysis that previous resistance becomes support - so nobody should be surprised if NCYT gets whacked to £5 again. This share is indeed that volatile. But also nobody should be surprised if they see this at £15 some time.
The most important thing is to manage one's risk. Never get over exposed - sell to the sleeping level. Rule #1 - don't lose money.
Cheers Ed.
Just to mention that Novacyt is one of the four companies that will be analysed in our MelloBASH (Buy, Avoid, Sell or Hold) at our next MelloMonday on the 19th October so only a week to go. The five strong panel of fund managers, analysts and experienced investors will include Stockopedia SCVR writer Paul Scott and Leon Boros who often invests in companies with excellent returns on capital.
The events are very popular and you can obtain a half price ticket via Stockopedia using the code MMStocko21
Just go to https://melloevents.com/ for more info and a full programme for the evening which lasts 3.5 hours.
David
Hi David, seems very interesting. Having got a ticket, do you get a chance to watch a recording of the event afterwards or do you need to commit to that 3.5 hours and take notes as you go? :)
So long as you are a ticket holder or annual pass holder you will be sent a link to watch the cleaned up ie. edited version of the show about one or two days later. Investors that cannot attend do like to watch it at leisure afterwards.
Some sessions are very interactive and far better to watch live and naturally you may want to invest so seeing it live may be time critical for you if a company is very popular. You will see the number of participants appear on the screen but the BASH for example will have over 300 watching live.
Annual pass purchased. Thanks for responding.
Excellent write up summation of £NCYT. Thank you.
On the PE:
"The earnings per share can be estimated at £1.67 (total earnings of £118 million for the full year / number of shares outstanding 70,626,248). If we take the current price and divide this by forward EPS ( £7.40 / £1.67) we get a forward P/E ratio of 4.4".
The only thing I would add is that my feeling is that P/E to be of much value assumes that current profits etc continue in to the future and here that is not certainty.
If I find over the weekend I want to try and predict e for the next five years. Not to the nearest million but on the Graham basis of "you need to know a how much someone weighs to know he is over weight".
On the future I would have thought that there was a high probability that Novacyt will be taken over by one of the big players at some point in the future.
I hold, third largest holding, 9.87% of portfolio.
Regards
Michael
PS Surprised that there are not more comments!
Well Shaunm has already covered it in his thread, so there’s some overlap.
My view is that while trying to pick a winner in Covid testing was a gamble, with this company that risk is now minimal. The risk is more in the duration of the bonanza and even if other more attractive test techniques or vaccines arrive the market for these existing tests will not dry up overnight.
By contrast, the government could shut down the hospitality sector again with almost no warning so any stocks in that sector are barge pole stocks to me and only for those wanting to take a massive gamble.
I haven't got it and far too volatile for me. I think the price is being set by day traders not fundamental value investors like the commentators here who are buy and hold. To work out the intrinsic value of the share you have to make an assumption about what happens to the cash flows. The danger is you make the assumption that the reinvested cash flows make the same rate of return as the current equity which is likely impossible..
The critical questions are can they deliver the contracts; how sustainable are the earnings and do they have the management capacity to handle the explosive growth. Have a look at the annual report. I did and have my doubts.
great article. Love this series of article. They have really me structure my own analysis. This article in particular was very thorough and well laid out. Thank you and keep up the good work. Look forward to more articles in this series.
Excellent. That's what i call a thorough analysis. A bench mark for most of us.
dfs12 mentioned this company in a thread on Sept 17 so I made a small investment thinking that the City Boffins had already priced in the latest news but I was wrong about that. Still the 100% increase pays the Stockopedia subscription for a few years to come!.
Great piece on NCYT. Was interested to read about the potential risks identified too and particularly noted this section below:
"Rapid Test risk - The company may suffer from a significant drop in revenues from the development of a vaccine, but it may equally do so if a competitor develops an ultra-rapid Covid-19 test, which delivers accurate results in minutes/seconds."
I'd be interested to know if you came across any indicators that NCYT are, have, or could be, developing any testing protocols based on LAMP (Loop Mediated Isothermal Amplification) technology? This appears to be the direction that testing is moving in as this technology eliminates the need for a thermocycler.
Anyone interested in a synopsis of competitor mentioned by Keelan, Genedrive (LON:GDR), could have a look at my post here:
https://www.stockopedia.com/co...
Admittedly not as thorough as Keelan's excellent piece here, but it gives some background on the company for those who haven't come across it before, please note GDR are not in the LAMP development space as far as I know.
Keelan,
Yes great analysis. Please do mention to Ed that I think interins should be suitably rewarded when their work, "significantly exceed expectations"! Ian
@Ian - I'm sure Keelan will greatly appreciate a 5% cut of your profits from NCYT !
Ed, That would be too much, but I will forward £50 via HQ for a decent lunch and my thanks with pleasure.
Brilliant analysis. Thanks Keelan.
I first purchased after half year results. Sales were around £63million but June sales alone were £22m. So my estimate for second half sales was £150m and second half Ebit of £100m ( 65% margin) giving full year EBIT of around £140m. Cash at half year was around 20m after paying off all the loans so year end cash estimate £100m or around £1.5 a share.
Since then they have developed Winterplex ( to check if illness is flu or covid), an antibody test and signed a new contract with DHSC of which £150m should come in second half. Ignoring other new sales, that should give another say £80m (allowing say £20m for extra overheads ,bonuses etc) of EBIT giving total Ebit of around £220m. Cash I estimate at say £170m so Enterprise value at £8 of £390m (70m shares at £8 minus cash of £170m) giving EV/EBIT ratio of less that 2 . Separate calculation I estimate a prudent profit after tax of £160m (tax rate of 12 % due to patents) or eps of around 220p per share so at £8 PE of less than 4.
Even if a vaccine is developed it will take a time to roll out and testing will be needed but the mention of a vaccine may mean private investors take profits. Another bear point is institutional shareholders seem to be lacking but company recently appointed Numis as second broker maybe to try and address this.
Great analysis Tariq.
I don't think many would dispute the current year PE is probably sub 4 or even sub 3 at the current price, the question will be about the e in 2021, 2022, 2023 and onwards.
Can any form of prediction be made for future years? I am going to try and find time to figure that out but I am not sure whether that wil be beyond me.
I hold third largest position and 9.8% of pf.
Regards
Michael
Good comments Tariq & Michael
I agree that the word "vaccine" may make some investors to take profits, however the name may help to produce some curves in the share price, providing temporary opportunities.
Many Newspapers will carry "potential good news", however no vaccine has been produced for a Corona virus, and the shortest time to produce a validated vaccine, was for mumps - over 4 years
see https://www.history.com/news/m...
https://en.wikipedia.org/wiki/...
Any chance to share portfolio? I am newbie here and only subscribed for 2 days.
Thanks very much Keelan very in-depth and professional. I think the risks are: foolish acquisitions to safeguard/diworsify the company for life after the COVID cash cow and of course there is a chance govts might decide to go “herd immunity” together with ring fencing the “at risk” thereby going without tests as normal flu is treated. Incoming M&A is an interesting one, I imagine it would be hardfor the predator’s management to justify after such a meteoric rise in NCYT to here.
I read an article recently which suggested that even when vaccines for Covid are approved and become generally available for use, they won't be a complete prevention for the disease and testing for Covid is likely to continue to be required in huge amounts for the forseeable future. If that's correct, then it should be helpful for Novacyt's longer-term prospects.
I think this entirely fair. After all, Influenza is a closely related virus, we have had vaccines for many years but I see no sign of the virus having been eradicated, nor of deaths having been stopped.
Somehow Governments and health establishments have too much riding on the virus, so re testing I don’t think we have reached the peak yet. Once we have peaked, I suspect testing will still have a very long and slow wind down.
Frankly, watching this stock go up in value helps me keep my sanity, when the world seems to be going mad re Covid. Yes it will come to an end, but metrics look very good for the moment.
I bought some at 73p sitting in Waterstones visiting the eldest in Uni in Winchester in February. They promptly fell to about 58p then rallied to above 100p where they did little for weeks. Little did I know then that trip would be my only trip outside Sussex for over 8 months. I sold some yesterday and am looking for £10 to sell more. I see £15 as a possibility but that will mean 250 times the year low and a mkt cap of over £1 billion. Not impossible at all but I just don't see NCYT as a long term investment. A vaccine may not mean the immediate end but it may see the beginning of the bull case. Nothing bad to say about NCYT of course.....been a fantastic run. The management should take a big bow for seeing the opportunity and being there first. Just that this note seems a bit late in the cycle to me.
Excellent reporting
A really good, comprehensive analysis. It will be interesting to see where this share goes from here.
Ive held this share since £1.70 and the longer I seem to hold it the more convinced I am that its got further to go. There are not many shares doing this well given the pandemic and brexit factors at play. Great write up.
Great analysis, i'm personally heavily invested in £avct & £odx but scraped enough together to buy 2000 shares in £ncyt @ £2.90 that appears to have been one of my better decisions.
Comprehensive and excellent report !
I would just add this could well be a takeover target to.
Very well structured analysis Keelan - I would have been in the 15% who wanted to wait for a correction..shows how much I know! I sincerely hope Stocko has a permanent role for you after your studies.
Excellent and balanced analysis of a classic PEAD (Post Earnings Announcement Drift) type share.
Far superior info to the likes of IC and Shares mags! Ian
Hi iwright7,
Thank you for your kind words! It's great to hear that you are enjoying this kind of analysis. We'll keep doing our best!
Kind regards,
Keelan
excellent article
Fantastic article. I will sleep better tonight as I bough some 2 days ago and was worried they might be getting over priced. Thanks for this in depth article about a very interesting company. Lets have more!
Brilliant. Just what I needed. Thank you very much. Excellent analysis and commentary.
Excellent article and I really enjoy the stock pitches. Many thanks.
I'm loving these articles, especially the standard sections on each pitch. Food for thought on how to analyse a stock
Hi nanotrader,
Thank you for your comment. There's a lot more to come on this front in the coming months. Stay tuned!
Kind regards,
Keelan