Stock Pitch - Spectra Systems (LON:SPSY)

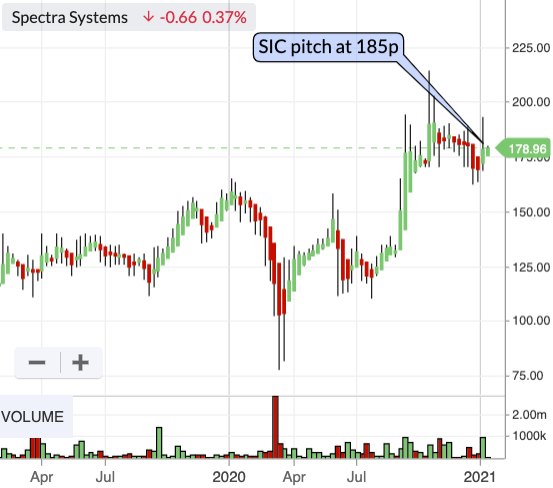
Spectra Systems (LON:SPSY) was pitched to the Stockopedia Investment Club on the 7th of January 2021, at a share price of 185p.
This is a patent-backed authentication materials company that spends millions every year on ground breaking research and development, founded and run by an ex-NASA laser scientist who also owns 5% of the company.
Alongside that colourful context and growth potential, you have reassuringly solid operating characteristics: double-digit six-year profit and earnings per share CAGRs, multi-year double-digit returns on capital and operating margins, healthy dividend payouts and share buybacks, and strong free cash flows.
So is Spectra the next big thing, or could this promising company fail to meet expectations in the years ahead?
Summary
Bull Points - it's a high QM profitable, cash generative, dividend paying small cap with high ROCE and margins; intellectual property, patents, and trusted long-term relationships with clients; strong R&D track record and scope for additional products; positive news flow of contract wins and market expectation beats.
Bear Points - Its products and businesses can be hard to understand; significant customer concentration; potential for delays to contracts; could fail to realise growth potential; subjective revenue recognition policies.
Profile
Spectra Systems (LON:SPSY) is a Speculative Small Cap High Flyer listed on the AIM market with a market cap of around £80m. It is classified as a US security, meaning certain accounts may not be able to hold these shares or might have to fill out additional forms, so check with your broker.
The group's core profit and cash engine is longer term contracts providing products and services to help authenticate and process banknotes.
Spectra supplies an impressive list of clients, including national central banks, global security printers and papermakers, nationally approved lottery operators, passport makers, and multinational consumer product companies.
Its shares are relatively illiquid, a 541 bps spread, and an EMS of 1,000 meaning you can only be sure of buying around £2,000 at the market price.
The valuation metrics are mixed, though: a forecast PE ratio of 21.9 is on the face of it justified by historical growth, but those compound growth rates are skewed by some large single-year gains, and a forecast PEG of 4.9 highlights the lacklustre projected 4.6% earnings per share growth.
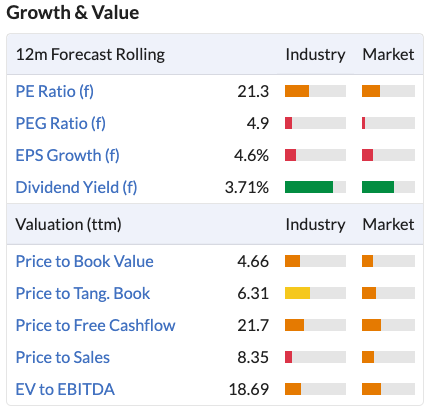
Forecast earnings growth aside, Spectra pays a useful forecast dividend of 3.58%, and its respectable StockRank of 85 is made up of:
- A Quality Rank of 93,
- A Value Rank of 36, and
- A Momentum Rank of 83
About the opportunity
Spectra faces multiple growth opportunities based on its proprietary, patented authentication materials and technology. If it can successfully commercialise its research & development pipeline, it has the potential to develop into a high QM compounder.
Its intellectual property and margins are 'comprehensively protected by over 100 patents'. It has long term relationships with central banks built on a high level of trust with potentially high switching costs.
Its relationships with clients give it good visibility in terms of what to prioritise in research and development, on which it spends millions of dollars annually. You might take the view that this is evidence of further widening of an economic moat.
Potentially lumpy contract revenue and a Speculative RiskRating suggest it could be a bumpy ride, but the company itself says it benefits from 'predictable long-term income streams'.
Spectra's track record of double-digit returns on capital suggests it can continue to effectively allocate growth capital. The initiation of dividend payments in 2017 might be taken as another sign of management confidence in future prospects. The group also occasionally buys back shares and pays special dividends.
Alongside its core banknote authentication business and other applications in tobacco packaging, disposable coffee cups, and online lottery software, Spectra is also beginning to invest in early stage companies in the high growth healthcare, biotechnology, and energy sectors.
Business & Model
What is the company history & what does it do?
Spectra was founded in 1996 by current president, CEO, and 5% shareholder Nabil Lawandy. Prior to Spectra, Lawandy conducted pioneering research into lasers at NASA and earned a tenured professorship in Engineering and Physics at Brown University.
Spectra’s core business is longer term contracts providing products and services to help authenticate and process banknotes - but it also provides a number of other product quality and security services to end markets like lotteries, tobacco manufacturing, and disposable coffee cups.
What are the key business segments and revenue breakdown between them?
As of FY19, the group reported two operating units:
- Authentication Systems - $11.83m of revenue (89%) and $4.16m of operating profit (94.5%). Revenue was up 5.6% year-on-year and operating profit rose by 12.8%.
- Secure Transactions Group - $1.41m of revenue (11%) and $0.24m of operating profit (5.5%). Revenue grew by 8.9%, although operating profit fell by 3.8%.
Authentication Systems
This is by far the most material segment. Revenue is driven by sales of 1) covert materials and associated equipment and services, 2) optical materials, and 3) license royalties.
Spectra sells covert materials directly to one G7 central bank and indirectly to 19 other central banks through supply and licensing agreements with a major banknote supplier and printer. This important area continues to offer good growth potential.
Spectra has executed a key exclusive supply agreement to provide the first and only machine-readable polymer banknote substrate. This is called the MR-BOPP product. It gives Spectra the ability to supply more than 2 billion banknotes per year immediately, growing to potentially 10 billion per year.
The group says this is a 'key development that could increase authentication revenues by an order of magnitude'. Spectra expects this to be available for the next central bank bidding tenders in 2021.
The group has also been contracted by a long standing central bank customer to develop a new technology for relatively rare and exotic counterfeits, which could further grow its machine-readable sales opportunities for upcoming tenders.
The group's TruBrand authentication product was seen on over 6 million packs of cigarettes in 2019. Once a Covid-delayed trial is completed, Spectra expects 'hundreds of millions of packs to follow'. The company is also identifying additional applications for its TruBrand tech.
Its single-use coffee k-cups business continues to grow and Spectra is in trials with a new and larger supplier here.
Secure Transactions
This division is formed around various gaming technology acquisitions made in 2012*.*
Spectra recently won a new contract with a major European lottery, bringing its international customer base to three lotteries 'and increasing its profile on the international stage as more jurisdictions consider outsourcing the internal control function'.
Four lottery contracts were renewed in the first half of 2020, 'demonstrating the stickiness of our lottery customer base'.
Market & Competition
What is the state & size of the company's market?
Spectra currently sells into, and is targeting, multiple large markets.
The main one is banknote authentication. There are over 150 billion banknotes manufactured annually worldwide. Despite the rise of digital payments over 85% of all transactions continue to be made with banknotes.
In fact, one report from Smithers (The Future of Banknotes to 2023) finds that the global market size for banknotes is forecast to increase from $9.7 billion in 2018 to $11.1 billion in 2023; an annual growth rate of 2.7%.
The internet-based lotteries market is in growth, as is the single-use coffee k-cups market: single-serve coffee machines appear to be taking market share in the coffee market, with recent figures from Statista showing that single-serving coffee brewing machines such as Keurig were the second most popular brewing system in America, with 27% of American coffee drinkers using them in 2020.
And, despite the understandably negative headlines, the global tobacco market remains vast, with BATS estimating global annual sales of some $814 billion.
Spectra does face competition, but the nature of its business is based on relationships with central banks and other top tier clients that value trust and security highly - as such this is a potential barrier to entry.
How does it derive its competitive advantage (if any)?
Spectra has spent millions in research and development over the past decade - about $22m or so. We can see the fruits of that labour in the group’s double-digit returns on capital and expanding operating margins.
You can see this in the group's 10Y Income Statement.
R&D spend as a % of revenue | |||
Year | Annual rev ($m) | R&D spend ($m) | R&D as % of rev |
2010 | 7.28 | 1.46 | 20.1% |
2011 | 7.42 | 1.67 | 22.5% |
2012 | 9.38 | 2.08 | 22.2% |
2013 | 11.6 | 2.85 | 24.6% |
2014 | 16.9 | 3.03 | 17.9% |
2015 | 14.1 | 2.55 | 18.1% |
2016 | 11.1 | 2.35 | 21.2% |
2017 | 12.2 | 1.77 | 14.5% |
2018 | 12.5 | 1.83 | 14.6% |
2019 | 13.2 | 1.74 | 13.2% |
The group has more than 100 patents protecting its intellectual property around materials, optics, and software for authentication markets.
In terms of the Economic Moat Framework, Spectra has intangible assets and possible switching costs.
Is the competitive advantage durable and is there any evidence of one in the financials?
On balance, this appears to be a reasonably durable competitive advantage given:
- The company's internal expertise, know-how, and connections,
- Its patents and proprietary products,
- The long-term nature of certain contracts and relationships with top-tier banking customers that value multi-decade stability, security, and trust.
Financials & Ownership
What is the record of growth & profitability?
Bumpy, but this has been as a result of activity that entrenches them with G7 customer.
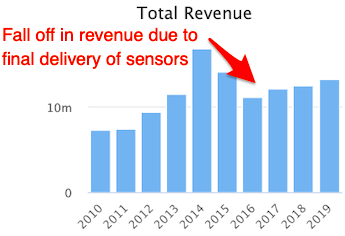
This temporary decline in revenue actually coincided with increasing profits - and sales have since increased every year thereafter.
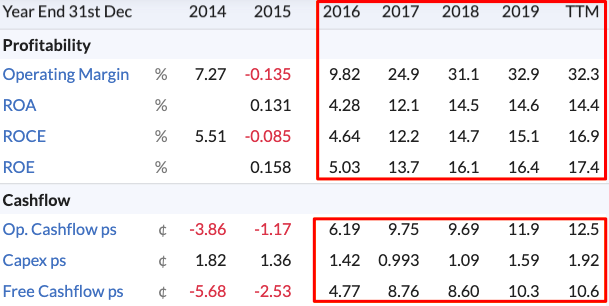
Note the transformed double-digit profitability metrics and healthy free cash flow in subsequent years:
What is the state of the balance sheet?
It's a net cash balance sheet, which is a good tick for quality. The latest is TTM net cash of $10.9m.
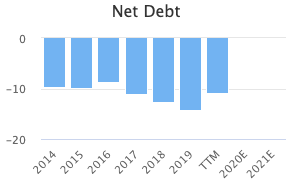
The liquidity ratios are all strong and there is no pension fund to worry about either.
And an F-Score of 6 is borderline good, especially as the checks it fails are still quite strong. It flags up a static ROA of 15% and the current ratio has fallen from 7.6 to 7.1. There's also a drop in gross margin from 70.9% to 69.7%.
What is the ownership structure of the company and do management have stakes?
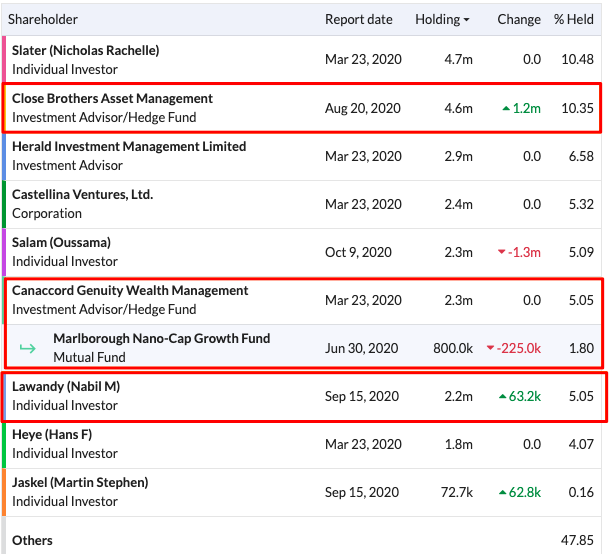
Mixed insights from Major Shareholders. Perhaps the key takeaway is that Lawandy has been increasing his c5% stake.
Apart from that, it looks like smaller less well-known names on the register save for some exceptions like Canaccord and Close Brothers.
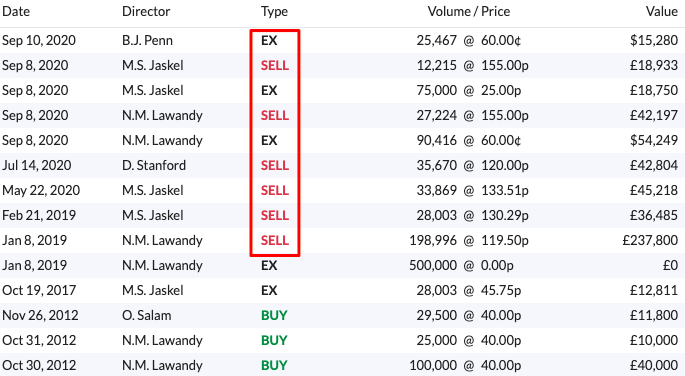
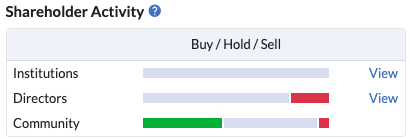
Directors on the whole have been selling rather than buying recently.
Valuation
How does the relative valuation compare versus industry and sector?
Relative valuation is not Spectra's strength, but this misses Spectra's growth potential. The forecast dividend yield is useful.
Spectra has a good chance of developing into a materially larger business on, say, a five-year view because:
- It has a good foothold in the banknote authentication sector, where it continues to innovate and bring new products to market.
- TruBrand can ramp up its tobacco packaging operations and the company has identified other potential applications for this tech.
- Spectra's Keuring coffee cup business continues to grow, and it is slowly winning more lottery contracts as well.
- Its stake building in other, smaller companies is still at an early stage, and it's too early to gauge success here, but the group continues to devote sums of money to research and development, which should drive revenue in the years ahead.
Trends & Catalysts
Are there any catalysts that could drive a rerating in the medium term?
Spectra has been buying back shares and has several possible operational catalysts. It splits opportunities between short term (2020-2022) and longer term (2023-2025).
Short-term opportunities:
- Large orders for materials to, and research funding from, central bank customers;
- A multi-million dollar sensor development contract with a central bank customer;
- Increased tobacco packaging sales in China with TruBrand;
- Adoption of phosphors for a supplier to a major Asian central bank;
- Expansion of K-cup sales;
- Sales of Spectra’s newest patent pending phosphor product; and
- Sale of its first Aeris banknote decontamination system to a gaming casino.
The longer term opportunities are:
- A licensing and supply agreement for polymer-based technology;
- Supply of upgraded sensor capability to a central bank customer; and
- Sale of secure polymer substrate to central banks.
The group itself believes this combination of initiatives should be enough to continue revenue and profit growth through to 2025 while providing organic funds for investment in cutting edge technologies.
Risks, Threats & Hurdles
What are the biggest risks, threats or hurdles that the business may face?
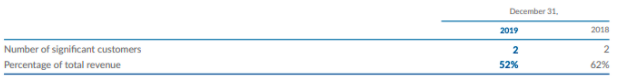
- Customer concentration risk - this is a key risk. Spectra has something like 50% of business with two customer. A counterpoint is that Spectra's relationships appear quite long-term and entrenched, based on trust with central banks etc.
- The company is a bit of a black box. It's smart, with a lot of IP, spending a lot on R&D with the green shoots of double-digit ROCE... But it's not the easiest company to wrap your head around
- Key person risk - Lawandy et al are a smart bunch driving innovation across authentication products. A part of the bull case relies on key personnel continuing to innovate and add value.
- Expiry of patents - US patents have an expiry of 20 years.
- Revenue recognition - its long term and complex contracts result in several instances of revenue recognition requiring 'significant judgement'. Spectra adopted ASC 606 "Revenue from Contracts with Customers" in 2018.
- As a US security, there may be tax and administration implications to bear in mind.
Recent Trading & News
There has been a consistent trend of good news and significant events that could be triggers for future growth:
- 05 Jan 2021 - share buybacks
- 14 Dec 2020 - two lottery renewals worth $1-1.25m of revenue
- 14 Dec 2020 - c47% stake in Solaris. Lawandy is the principal shareholder here.
- 18 Nov 2020 - strengthened TruBrand patents
- 21 Oct 2020 - substantial central bank contract ($1.9m for Phase 1; three major additional phases which include a $5.6m Phase 2 development through 2023, as much as $34m for the delivery of an as yet unspecified number of sensors, and a service component worth approximately $7.5m)
7 September 2020 - Interim report
The Board therefore believes that the Company is on track to achieve record earnings for the full year and expects both revenue and earnings to significantly exceed market expectation for the full year.
23 March 2020 - audited results
The Board believes that the Company, by achieving key business milestones, will continue to perform well and will exceed market expectations for 2020.
Sentiment
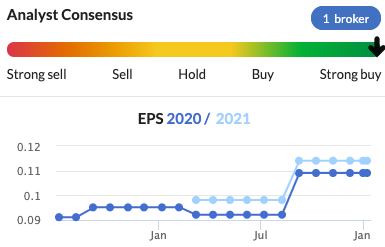
Brokers have been upping their EPS forecasts.
The community has been buying, and Spectra also figures in Top Picks of the 2021 Stock Picking Challenge.
Conclusion
It is currently against Club rules to buy stocks classified as US securities, as this would entail extra admin for the SIC. Therefore no buy or sell action was proposed regarding Spectra. The Club is open to amending this policy in future, if low-admin solutions can be found.
What do readers think: does this mean the SIC misses out on one of the more promising growth stories on AIM, or have you seen something here that rings alarm bells?
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

20 comments
Hi Jack
Spectra Systems (LON:SPSY) is an intriguing company and as you state is somewhat of a black box. However it does appear to have significant potential and it appears too good at least not to buy a ticket. I have therefore bought a small opening position, a little prematurely perhaps as the share price has come off recently. Depending on how the situation evolves I may make a further purchase. But for the time being I shall hope that my 'ticket' is akin to one of Willy Wonka's rare golden tickets.
I bought the shares in my Halifax ISA as I would the shares of a UK based company, so I assume that at one time I must have completed a W-8BEN form, although don't remember doing so. As one of the contributors to this thread commented it is the type of share to buy and forget about in the medium term.
Incidentally I have a substantially larger holding in De La Rue (LON:DLAR), which in my view is undervalued by the market. Therein lies the opportunity perhaps and I have added recently.
Thank you for the great write up on Spectra Systems (LON:SPSY)
Thanks for the great analysis. Is there a reason that you didn’t mention the Spectra Systems (LON:SPSC) shares? They seem to be a historic oddity and convertible to Spectra Systems (LON:SPSY) only if held as certificates. BTW, the FD replies promptly to emails.
@Jack, great work. Does De La Rue (LON:DLAR) not operate in this space too or I am mistaken? they have made a good progress in organising themselves. Authentication business is huge for them too.
Hi curiousturtle (solid name),
You are correct that De La Rue (LON:DLAR) would be a very interesting counter-pitch. It passes all the Club rules and generates far more revenue that £ SPSY , so I wouldn't be surprised to see it get pitched at some point in the future.
Perhaps their technology could be called upon to validate proposed “vaccination passports”, if so then quite a growth opportunity.
Great piece of research. Many thanks.
Nice write up Jack, I hold.
For me this a quality/niche operator with upside optionality on the new products.
I think trubrand especially has a lot of potential especially as online grows and companies (sellers and IP owners) want to protect authenticity of their products.
That said it is a black box and I am not sure why they are UK listed, although it goes way back. Also, I am reticent (in general) when they buy/invest in related companies.
Thst said, I think the reports do a good job of explaining the opportunity and business and they tend to execute on what they say. I also understand why there might be substantial confidentiality/security considerations around their product operations. Steph McGovern (think that's her name) said she had a tour of DeLaRue and mentioned that it was the most insane security she ever experienced (Have I got news for you, DeLaRue not getting UK passport contract).
Separately, for those that do want to hold this or any US security, suggest doing so in a SIPP, because the 15% withholding tax on dividends doesn't apply (it does in the ISA) and doing an admin transaction with this spread is a pain in the proverbial and wallet
Hi Jack
Amazing analysis. I must adopt this as a template for my own.
Quick question if US quoted stocks are a no go for the club (assuming members know this) why did a member pitch it rather than one that could be given a thumbs up or down?
Thx.
Regards
Michael
Thanks Michael,
Ed actually wrote up the Template here - we are continuing to refine it, and we find that we drop certain sections and expand on others depending on the company. But it's a great way for making sure you thoroughly and methodically 'kick the tyres' for a stock.
There's a couple of reasons Spectra Systems (LON:SPSY) was pitched:
Best,
Jack
Thank you Jack and for the link.
Does
SPSY qualify as an aim stock eligible for Inheritance Tax relief?
Yes according to Investors Champion
We know how to do them but I would not want to have to them for around 18 persons.
Hi Guys,
Interested on comments regarding W-8BEN form. I've previously had one years ago due to sharesave from an American company I worked for a number of years ago and thought I'd see how hard it might be.
Just filled out on my HL account by clicking about 5 or 6 bullet point answers and was then allowed to enter a fill or kill order immediately for Spectra. Don't see the problem :-) Remember it was easy the last time too, give it a whirl...
fantastic analysis Jack. I have been a holder for a few years. Now I know why!
the broker forecasts are from contracted revenue, nothing in the forecasts from all the opportunity's listed in this stock pitch.Think this is a company where you take the p.e with a pinch of salt,so much going on also opps in Sellophane and tyres ect as well.
Spectra Systems (LON:SPSY)
Hi Jack
Wow that's some analysis - already hold this share and you have certainly increased my knowledge - thank you. One small matter I'd like to raise, when you say;
'It is currently against Club rules to buy stocks classified as US securities, as this would entail extra admin for the SIC. Therefore no buy or sell action was proposed regarding Spectra. The Club is open to amending this policy in future, if low-admin solutions can be found.'
I am a newbie - just over 6 months investing. However, when I bought these shares (Broker - Hargreaves Lansdown) they have a link to the W-8BEN form. As you can see from the link I have attached from the IRS website in the US it is a very simple form to fill out and lasts for 3 years.
Am I missing something? As that's not a lot of admin where I come from...and that's Norfolk!
Form W-8 BEN (Rev. July 2017) (irs.gov)
That form is for an individual, it maybe more difficult doing it for a club?
Some brokers are better than others, at doing the withholding tax and paying dividends, some brokers won't trade Somero Enterprises Inc (LON:SOM) presumably for tax reasons.
I can see why that rule is there.
As for missing out, I'm not sure, it has been on my watchlist for a while, I did hold once but sold out for a loss when it was falling. It's the sort of share to buy and then forget about for a few years. The spread is quite wide, the shares go up on good news and then drift back down again. I may pick some up if do fall some more.
Yes - unfortunately we have to fill out the form for every club member and then go through a lot of onerous verification processes. To keep it admin light we decided we'd pass on international shares for the time being.
Good Afternoon Ed and thanks for taking the trouble to reply.
Just want to take this opportunity to let you know that you, your staff, your videos, your site, in fact everything Stockopedia has taken my knowledge from zero to successfully investing. Huge thanks for all the hard work and dedication, I literally would not have known where to start without it.
Best regards
James