Stock Pitch - Tharisa (LON:THS)
Tharisa was pitched to the Stockopedia Investment Club (SIC) on 7th January 2021.
The Metals & Mining industry has been one of the strongest performers over the past year, rebounding strongly from the March 2020 lows. One particular subset of the mining sector, which has performed exceptionally well is the Platinum Group Metal (PGM) producers. Buoyed by surging demand from the automotive industry, PGM prices have soared.
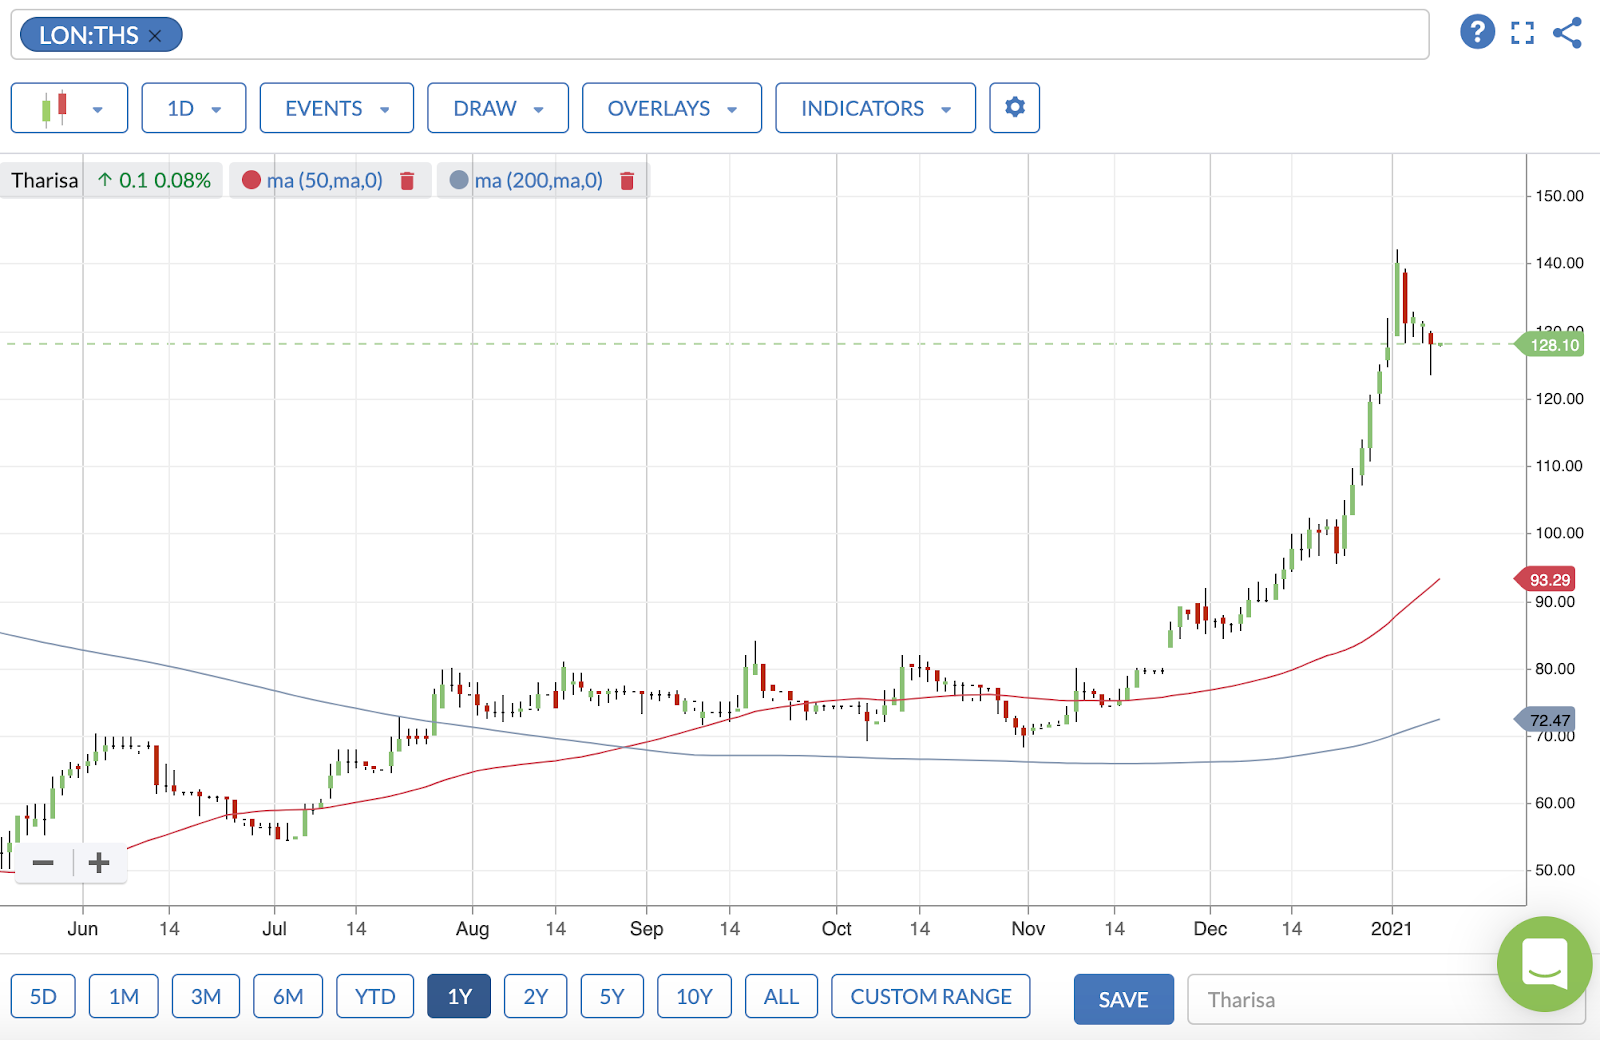
As a PGM & Chrome producer, Tharisa, has seen plenty of catalysts for a re-rating of its share price as well as its StockRank. Despite the pandemic, the shares are up by over 50% over the last year. This strong momentum, combined with its high quality metrics and attractive valuation now classes Tharisa as an adventurous, small cap, super stock.
Given the strong share price run recent weeks, has the easy money been made or is this the start of a more meaningful commodities rerating?
Summary
Bull Points - Rapidly growing revenues & profits, great exposure to PGMs & Chrome, Rhodium prices currently at $19,000, near-term production expansion, plans for asset & geographical diversification.
Bear Points - Cyclical nature of the industry, Electric Vehicles currently using other metals, South African volatility (currency, politics, Covid restrictions).
Profile
Tharisa (LON:THS), which trades on both the London (AIM) and South African (JSE) exchanges, operates within the Basic Materials sector. The company is a producer of Platinum Group Metal (PGMs) and Chrome concentrates from its mining operations in South Africa.
Tharisa currently trades at a price of 128p per share, giving the company a market capitalisation of £331 million. As a Small Cap, Adventurous, Super Stock, the shares have seen a fair amount of volatility over the past year, despite the impressive performance. An Exchange Market Size of 2,000 means that liquidity may be an issue for larger transactions.
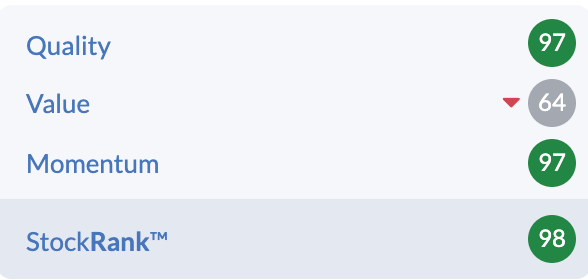
A StockRank of 98 is a testament to the strong all round fundamental characteristics of the company. The Quality and Momentum Ranks both currently stand at 97, whilst the Value Rank has now dropped to 64.
The 12m forecast P/E ranks as one of the lowest in the industry at 5.6 and the forward dividend yield is 3.14%.
Tharisa’s quantitative attributes means that it currently qualifies for 6 Guru screens, including the Piotroski High F-Score screen and James O’Shaugnessy Cornerstone Growth screen.
Business & Model
What is the company history & what does it do?
Established in 2006, the company owns over 70% of the highly prospective Tharisa mine, located in South Africa’s Western Limb of the Bushveld Complex. The Tharisa Mine has a mining life of 14 years open pit and 40 additional years as an underground mine and is one of the largest Chrome resources globally.
The company is engaged in the production and sale of Platinum Group Metals, such as Platinum, Palladium, Rhodium, Iridium and Ruthenium in addition to Chrome concentrates. Tharisa is currently the 6th largest PGM producer and 4th largest Chrome producer in SA. The image below highlights the scale of the company’s PGM and Chrome operations.

Source: Tharisa Investor Presentation (December 2020)
What are the key business segments and revenue breakdown between them?
Tharisa generates the majority of its revenues from the production & sale of PGMs. In its full year 2020 results, the company disclosed its PGM revenue breakdown, which can be seen by the image below.

Source: Tharisa FY 2020 Annual Report
Rhodium now makes up over 50% of PGM revenues, realising an average price of US $8,348/oz over the course last year. Since this time, Rhodium prices have surged further to $19,000 an ounce. If production were to remain at the 13,500 ounces produced last year, this would equate to revenues of $256,500,000 for Rhodium alone. Given current Platinum prices of over $1,060 an ounce and Palladium prices of $2,400, revenues are likely to exceed last year’s revenues of $406 million from its PGM production alone.
Whilst the PGM basket now accounts for a larger proportion of the company’s revenues, Chrome is still a key contributor, accounting for just under a third of revenues. Demand from China remains robust and overall demand is expected to rise in the coming years, principally due to the rise in the demand for stainless steel products.

Source: Tharisa Investor Presentation (December 2020)
What is the business model? How does it make money?
Tharisa owns several subsidiaries, which allows it to extract maximum value from its mining operations. Once the PGM & Chrome is mined, the company processes the majority of these at its Genesis & Voyager Plants. Through its 100% ownership of Arxo Resources & Arxo Logistics, it is then able to sell its refined mining output directly to customers around the world.
Market & Competition
What is the state & size of the company's market and who are its competitors?
The global PGM market is vast, with many large global players such as Anglo American, Sibanye-Stillwater & Norilsk Nickel. There are also plenty of smaller producers such as Sylvania Platinum & Jubilee Metals listed on the UK market.
South Africa currently produces around 60% of global PGMs. The country introduced strict lockdowns throughout 2020, which greatly affected mining activities. This affected the PGM supply from mines in the region.
Platinum metal reserves worldwide as on 2019, by country (in metric tons)*

Source: Statista
In addition to this, the lack of exploration that has taken place in recent years and technical difficulties to rapidly expand production, combined with growing demand from the automotive industry, has created a serious supply deficit of PGMs.
According to Heraeus, one of the world’s leading refiners of PGMs, the Rhodium market is expected to move into a deeper deficit in the coming years, reaching 411,000 ounces by 2024.
What is the company's strategy?
The group plans on expanding its near-term production target to 200 koz of PGMs and 2.0 Mt of Chrome concentrates per annum.
Tharisa also plans to diversify into a multi-asset, multi-commodity and multi-jurisdictional business. In recent years, the company has acquired interests in Karo Mining Holdings and Salene Chrome, which will diversify its regional exposure by giving it exposure to a new growing PGM and Chrome frontier in Zimbabwe.
The Vulcan project, which has received considerable investment over the past year, is also being developed to enhance the recovery process of fine Chrome. The R&D stream highlights this below.

Source: Tharisa Investor Presentation (December 2020)
How does it derive its competitive advantage (if any)?
One of the company’s key competitive advantages is its cost-management. Currently operating from an open-pit mine, the costs of extraction are very low. The company also carries out its processing and refining operations at two independent integrated plants, which places Tharisa’s mining operations in the lowest cost quartile of operating costs in South Africa for both PGMs and Chrome.
Is the competitive advantage durable and is there any evidence of one in the financials?
All the financials point towards the competitive advantage being durable. A perfect Piotroski F-Score of 9, Return on Capital and Operating Margins of over 20% and in the top quartiles of the market are testament to this.
However, the company performance, as is the case with any mining company, is still largely reliant on the price of metals. While the fundamentals for PGMs and Chrome remain strong, unanticipated shocks should always be considered.
Financials & Ownership
What is the record of growth & profitability?
Due to the cyclical nature of commodity prices, revenue growth & profitability has fluctuated over time. However, tightening control over costs and productivity improvements, combined with soaring commodity prices, notably in PGMs, means that revenues & profitability are forecast to reach record levels in the coming years.

What is the state of the balance sheet?
The balance sheet is in good overall health. At the end of 2020, the company held $19.2 million in net debt. Given last year’s Free Cash Flow generation (US$43.8 million), this will most likely turn into a net cash position this year.
The current ratio and quick ratio highlight no issues with regard to liquidity, and the Z-Score indicates that the company is in good financial health.
Is there evidence of historic share dilution or buy backs?
There has been very little dilution in recent years, most of which is likely tied to management/employee benefit schemes.
What is the ownership structure of the company and do management have stakes?
The company is majority owned by institutional investors and other corporations. The largest shareholders account for 78.22% of all issued share capital. Phoevos Pouroulis, the CEO of the company owns just under 3% of the company.

It is worth noting that there has been some director selling in recent months though.
Valuation
How does the relative valuation compare versus industry and sector?
Tharisa ranks as one of the cheapest companies in the Metals & Mining industry. Its forward P/E ratio of 5.6 and PEG of 0.2 are amongst the best in the industry. The strong earnings growth, free cash flow generation and dividend yield make Tharisa a stand-out candidate in the PGM space from a valuation point of view.

Trends & Catalysts
Are there any significant macro trends that the business is benefiting from?
Platinum Group Metals have been some of the best performing commodities over the past year. After a prolonged bear-market cycle, these metals look like they are breaking out. This is due to a number of factors, most notably the change in global focus on environmental sustainability.
New regulations have come in place to place more stringent measures on vehicle pollutants. Catalytic converters (made of PGMs), which help to reduce the pollution from vehicles, are seeing more and more demand due to this.

Source: Tharisa Investor Presentation (December 2020)
PGM’s may even be used to replace the cobalt-nickel element in EV batteries. Testing is currently being carried out by Lion Technologies in the US to prove this new patented technology.
Are there any catalysts that could drive a rerating in the medium term?
Tharisa will announce its Q1 production figures on the 12th January 2021. Further PGM price rises are also likely to provide further catalysts for the stock in the medium term.
Risks, Threats & Hurdles
What are the biggest risks, threats or hurdles that the business may face?
Operational Risk - As with all mining operations, there are serious operational risks. Whilst operating an open pit is less likely to lead to any fatal injuries, mining operations still pose a risk to individuals. Machinery issues could also lead to lost days of production.
South Africa has also experienced issues in the mining sector in the past, strikes have been problematic and are important to bear in mind.
Market Risk - PGMs have been on a strong run over the past year and whilst this is largely expected to continue, much depends on automotive demand moving forward. Should the worldwide economic recovery start to slow, or fall once again, this could impact the automotive industry, which in turn will negatively affect PGM prices.
Exchange Rate Risk - A weaker dollar versus the South African Rand increases the cost of operations for Tharisa.
Recent Trading & News
Summarise the most recent announcements, news and trading statements and market reaction to them?
Annual Financial Report FY 2020 - The last major new announcement was the FY 2020 annual results, an overview of which, can be seen below.

Source: Tharisa Investor Presentation (December 2020)
Sentiment
What do the brokers currently think and are they upgrading estimates?
Brokers are optimistic about Tharisa’s prospects, with EPS forecasts for 2021 rising sharply in recent months.

What is private investor sentiment at the moment?
36 people picked Tharisa in the Stockopedia Stock Picking competition! Bulletin boards & Twitter are relatively quiet at the moment, but this could lead to greater share price movement once interest builds.
What would the person selling to us be thinking and who are they?
It is fair to assume that there will be some profit taking, with the stock nearly having trebled since the March lows. Investors may also be prioritising other green metals investment such as Copper, Cobalt and Nickel.
Conclusion
After evaluating the stock pitch, the SIC voted in favour of purchasing Tharisa shares. On the 8th January, the club proceeded with the purchase of shares in Tharisa at a price of £1.29.

We now have a fair amount of PGM exposure in the Stockopedia Investment Club portfolio, due to our positions in Tharisa & Sylvania Platinum. Does the PGM rerating have legs or is the Club investing at the top of a bubble?
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

17 comments
Really impressive results today and I am so pleased that I continued to hold in spite of the large sell off in last 6 months . I am based in South Africa and this company has an outstanding safety and production record with very good staff relations .
Hi
Hope someone can advise on the following!
Non-Controlling-interests
Just looking through the interim report and am struggling with reconciling the profit back to the EPS
Profit for the year attributable to:
Owners of the company $m57 439
Non-controlling interest $m18 224
Total $m75 663
The EPS is only calculated based on the owners of the company 57439000/268000000 = 21.4 cents per share
Why is the non controlling interest not part of the EPS ie 75663000/268000000 = 28.2 cents per shares
In reality as shareholders is the 28.2 cents the more relevant figure when working out the PER?
Cheers
El
I'm a strong believer in both the sector and the company . Over the last months I have increased my holdings of Tharisa in various portfolios. I follow the company presentations which always define a clear line of travel. It will be interesting to see if a low company valuation based on P/E produces outside interest .
Hi Great report, Trying to work out the basket mix percentage, but cannot find it in the results. You mention 13,500 oz of Rhodium. Where is this figure from? Cheers
Hi eltorero,
Thank you for your comment! You can find more details on Tharisa's basket mix percentage (prill split) in the company's investor presentations. I have attached a link to this below. You'll be able to find all the details (including Rhodium production) on page 4 of the most recent presentation.
https://www.tharisa.com/ovr-pr...
Hope this helps!
Kind regards,
Keelan
Thanks Keelan
In its most recent public statement the company mentioned the risk of the South African government introducing an export tax on chrome. One of the company's complaints is that there is a lack of detail and when or if such a tax will be imposed. To what extent could this threat impinge on this company's performance?
Hi Bluntnib,
The company did make some interesting points with regard to the proposed SA chrome ore tax in its AGM statement. It does appear that the South African government is receiving strong backlash from producers, which includes the likes of Anglo American Platinum, Impala Platinum & Sibanye-Stillwater.
Tharisa made sure to add that the independent third party analysis carried out on the proposed chrome tax has highlighted that the potential tax benefits for the government are far outweighed by the risks, and could even breach international trade regulations (which SA will likely be unwilling to do).
South African chrome ore currently accounts for 83% of China's total chrome imports. Should the proposed export tax go ahead, China might retaliate with its own export taxes, making this a potentially costly decision for the South African government.
Whilst the tax is also expected to help boost the domestic ferrochrome industry, the rise in overall chrome prices may mean that China and other nations begin to look elsewhere to secure chrome ore supplies.
It is hard to predict what might happen here, but with the rise in PGM prices, which now account for the majority of group revenues, Tharisa is in a strong position to weather the impacts of any proposed chrome tax.
Kind regards,
Keelan
Hi Keelan,
Thanks for a really good write up. I had a question on the relative valuations and wondered if you ever did comparisons to other companies based on their characteristics in terms of cash flow, growth rates etc as opposed to industry comparisons?
Hi Keelan, has the Investment Club carried out any country diligence on South Africa given the concentration of the portfolio in South Africa PGM, to assess country risk?
I also bought Tharisa (LON:THS) in December, not sure I would be buying now. I do hold Sylvania Platinum (LON:SLP) and Jubilee Metals (LON:JLP) also.
I think commodity prices are very fickle, gold was down 4% and silver down 8% last Friday. Platinum was also down a fair amount.
Directors sales at Sylvania Platinum (LON:SLP) seem to be share options.
Surprised to see this share part of the Investment club as it has Sylvania Platinum (LON:SLP) already.
Conclusion should of course read that they bought in January 2021 (not July).
I hold. I was most impressed with the recent Tharisa video presentation (just before the actual results I think). As ever an excellent analysis. The thing that I noticed from Tharisa presentation that is not fully reflected here, is that they are coming to the end of a major capital programme that has seen them restructure access and organisation of the open cast mining site, plus some state of the art processing plant. So there plans for expansion appear to be very well grounded.
I wonder if the Director selling is a custom and practice issue in S Africa as I have also noticed that there have been loads of Director sales for Sylvania Platinum (LON:SLP) through a year of tremendous share price growth for them...strange.
Hi Martin VT,
Thank you for pointing this out. I have duly amended the date of purchase.
It does appear as though the Capital Expenditures over the past few years will start to bear fruit in the near future. The company has underlined its focus on operational excellence and innovation several times throughout presentations and you are right in highlighting the state of the art processing plants.
The Director selling may require some further investigation, but there haven't been any considerable-sized sales for some time.
Kind regards,
Keelan
Have the committee considered Jubilee Metals (LON:JLP), as it is a slightly different business model to THS, which is similar to SLP?
Hi smose,
Jubilee Metals (LON:JLP) was actually on the shortlist of stocks to consider. However, its StockRank has just dropped below the 75 level, which is where we have set the cut off point for our portfolio.
Very interesting company though, with some nice Copper & Cobalt exposure as well!
Kind regards,
Keelan
I hold. Bought in December and am happy. I do consider the share quite risky though. The parent company is Cypriot. There's the threat of the mandatory rate of 'local' ownership being increased from the current 26%. There's the risk of the South Africans imposing a Chromium export tax. Biggest risk though is the proportion of Rhodium in the recovered metals declining. If they can maintain the current high rates the share is a bargain. If they'd just struck a lucky patch for a while and they get through to ore with less Rhodium then the figures won't look quite so good next year.
Hi JCPr,
Thank you for highlighting some very interesting factors to bear in mind. Will be interesting to see the metal recovery rates in tomorrow's Q1 production report.
Kind regards,
Keelan