Stock Pitch - Yellow Cake (LON:YCA)

Yellow Cake (LON:YCA) holds uranium and provides direct equity exposure to this neglected energy source.
Uranium has been in a bear market for a decade but is that about to change? It has fallen behind other recovering commodities, and an increase in spot price here would lead to an increase in YCA's net asset value.
This is a low-cost source of renewable energy. Structural shifts towards these renewable energy sources and greater global electricity demand suggest that it has to be a part of the mix going forwards. Indeed ascending powers like China and India are building many tens of new reactors.
But languishing spot prices mean uranium remains effectively below its cost of production. With a lack of new mine capacity, recovering demand could see uranium prices rising sharply in the medium-term.
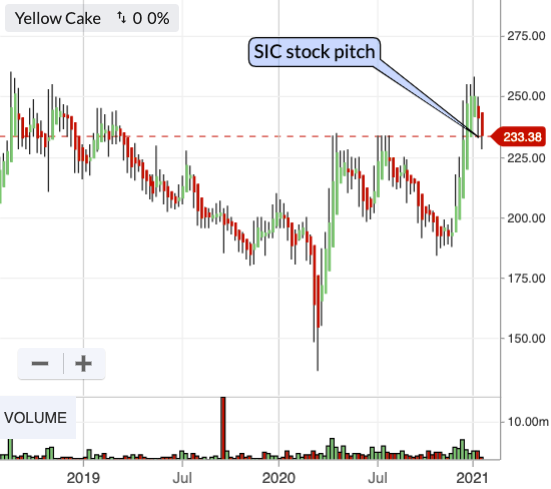
Yellow Cake was incorporated in 2018 on the view that uranium is structurally undervalued. It was pitched to the Stockopedia Investment Club on the 19th of January 2021 at a share price of 230p.
The Club currently has no exposure to the Energy sector - but is a company that simply offers exposure to a certain asset class the kind of company the SIC wants to invest in?
Summary
Bull points: direct exposure to the uranium spot price; lack of new mine production + rising demand suggests favourable outlook; YCA has been buying back shares; Balanced RiskRating could offer portfolio diversification benefits
Bear points: gap to NAV has closed; technology makes uranium last longer and holds back prices; political risk (Fukushima); opaque market dominated by a few key players; no operating aspect - YCA just holds uranium
Profile
About the Stock:
Yellow Cake is a small cap holding company listed on AIM and headquartered in Jersey. It has a market cap of c£200m and is classified in the Energy sector as part of the Uranium industry group.
The shares have good liquidity, with an exchange market size of 3k allowing for a c£7,000 buy or sell fairly easily.
The StockRank is 84 (Q Rank 49; V Rank 87; M Rank 73). It has a Balanced RiskRating and is currently Style Neutral.
About the Opportunity:
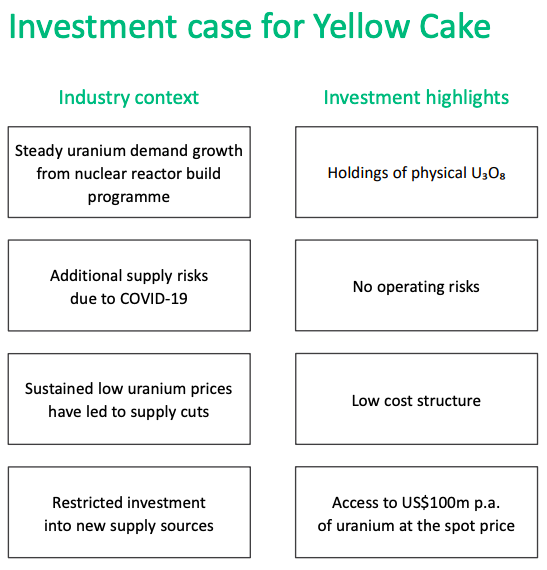
- The medium term supply-demand dynamics of the uranium market look favourable for holders of uranium
- It has lagged other recent commodity reratings and the low spot price makes for a lack of new mine development. As demand picks up, spot prices should benefit from the structural shift towards renewable energy sources.
- While the US continues to be a large market, demand is growing quickly in other geographies such as China.
- Yellow Cake's Balanced RiskRating means it might play a useful diversifying role in a portfolio.
January 2021 company presentation
Business & Model
What is the company history & what does it do?
Yellow Cake's sole operating segment is simply for 'the holding of U3O8 for long-term capital appreciation.'
It came to market in 2018, with management seeking to take advantage of what they viewed as favourable uranium prices.
What is the business model? How does it make money?
Yellow Cake has a long-term contract with Kazatomprom, the largest world's largest producer of uranium.
This contract enables YCA to acquire uranium at a pre-agreed price and allows shareholders to benefit from any uplift.
This long-term Framework Agreement was negotiated by 308 Services and enables Yellow Cake to access up to $100m of uranium annually from Kazatomprom at the spot price until 2027. In aggregate, Yellow Cake has the option to acquire around $1.1bn of U3O8 from Kazatomprom through the Kazatomprom Contract.
The group has a strategic relationship with URC. URC is an experienced uranium royalty and streaming company, with its headquarters in Canada. As part of the relationship, URC must inform YCA of potential uranium purchasing opportunities. In turn, YCA must alert URC to any uranium royalty or mineral stream opportunities. URC can acquire up to 50% of any such opportunity.
In addition, URC an option to acquire between $2.5m and $10m worth of U3O8 per year in each of the nine years from January 2019, up to a maximum aggregate amount of $31.25m worth of U3O8.
The uranium is stored in Canada at Cameco’s Port Hope / Blind River facility. YCA also now has 600,000lb of uranium in Orano's Malvesi and Tricastin storage facility in France under location swap agreements.
Yellow Cake’s management team is supported by 308 Services, a uranium specialist focused on the uranium commodity markets. This team supports Yellow Cake in its procurement of uranium.
Market & Competition
What is the state & size of the company's market?
According to the World Nuclear Association (WNA), between two-thirds and three-quarters of uranium supply is produced in three countries: Kazakhstan (39%), Canada (22%) and Australia (10%).
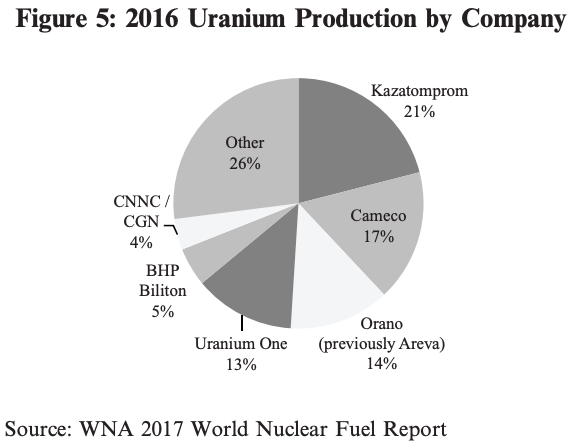
Production and marketing is dominated by four companies: Kazatomprom (21%), Cameco (17%), Orano (previously, Areva) (13%), and ARMZ – Uranium One (13%).
Yellow Cake Admission Document
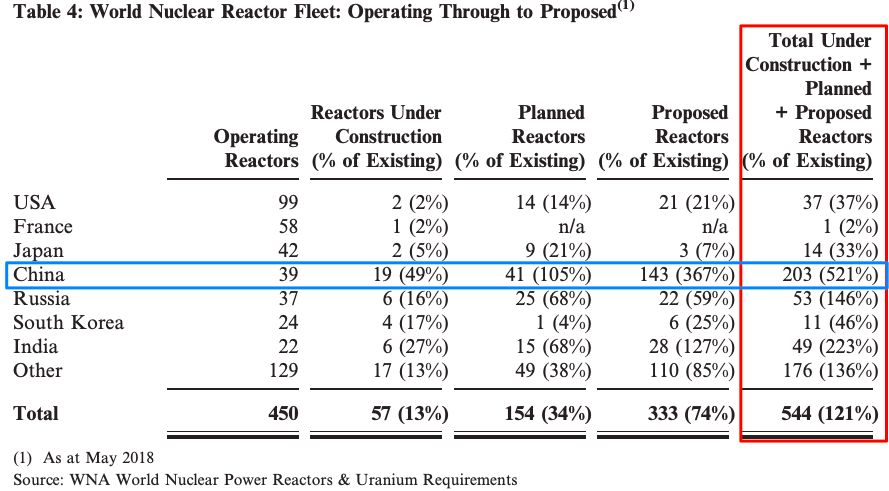
Historically, the nuclear power sector, and therefore uranium demand, has been dominated by the US and France. However Chinese demand is growing and the nation has overtaken Russia in terms of uranium demand.
Uranium can be mined through traditional open pit or underground methods. It can also recovered through In Situ Recovery (ISR), whereby oxygenated groundwater is pumped directly into the orebody and the minerals are recovered from the solution.
There are also various secondary sources including:
- Recycled uranium and plutonium from used fuel, as mixed oxide (MOX) fuel.
- Re-enriched depleted uranium tails.
- Ex-military weapons-grade uranium, blended down.
- Civil stockpiles.
- Ex-military weapons-grade plutonium, as MOX fuel.
These developments have delayed the demand for new plants but the World Nuclear Agency projects that the uranium supply of 189 mmlb in 2017 will decrease to 165 mmlb by 2035, and supply from current production sources is expected to decrease by 24% over the same period.
And yet without a significant improvement in the uranium price, few new mining projects are expected to be developed. What's more, obtaining the necessary approvals for developing and commissioning a uranium mine could cause delays.
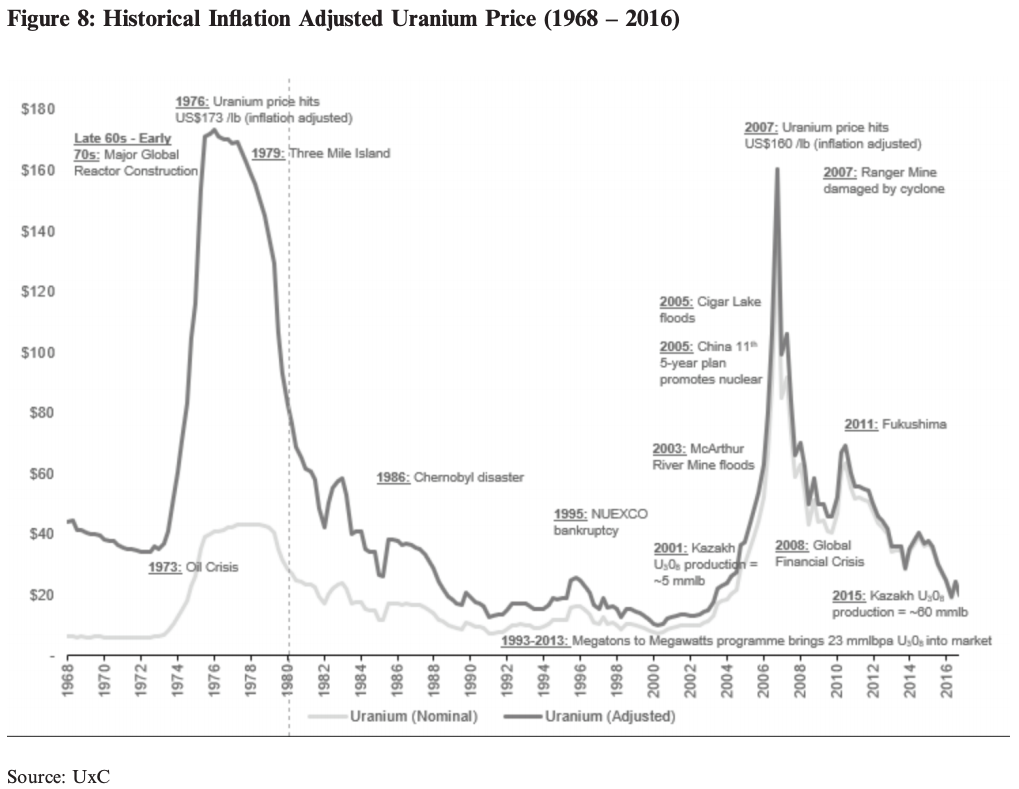
Therefore Yellow Cake expects that producers may consider purchasing U3O8 in the spot market to meet their contractual obligations, rather than produce U3O8 themselves at a higher cost.
What is the company's strategy?
Yellow Cake holds uranium 'to deliver maximum exposure to [the] expected resurgence in the uranium market,' while avoiding the operational risks that come with mining.
Its cooperation with URC allows Yellow Cake to diversify its sources of physical U3O8, and provides access to a variety of additional financing structures including:
- the lending of U3O8, and
- the acquisition of production or synthetic production interests in uranium via commodity streaming, royalties or similar mechanisms.
How does it derive its competitive advantage (if any)?
Its key contracts and sector expertise provide a strategic advantage. To summarise the contracts again, Yellow Cake has:
- the 10-year Framework Agreement with Kazatomprom that enables YCA to purchase up to $100m of U₃O₈ each year from 2019 to 2027 at spot price,
- the Cameco Storage Contract, where Yellow Cake holds 8.72mlb of U₃O₈ in a storage account,
- the Orano Storage Contract - In 2020, 600,000lb of U₃O₈ was transferred into a storage account at Orano Cycle’s Malvési/Tricastin storage facility in France under location swap agreements,
- the 308 Services relationship - 308 supports Yellow Cake in procurement and other uranium transactions,
- and the URC strategic relationship.
Financials & Ownership
What is the record of growth & profitability?
Revenue growth and traditional operating metrics are probably less applicable here - what is important to note is that the company trades at around NAV despite uranium being 'structurally under-priced'.
What is the state of the balance sheet?
Financial health is good, with a net cash balance sheet, a 5/9 F-Score, and a strong Z-Score.
Is there evidence of historic share dilution or buy backs?
Yellow Cake has issued shares before. It seems likely that it could issue more if it takes up the Kazatomprom contract to buy more uranium. So far, the company has made the following moves:
- In July 2018, YCA raised $200m in its IPO to purchase 8.1mlb of U3O8 at $21.01
- In August 2018, it purchased an additional 350klb at $23.30
- In April 2019 $33.9m was raised
- In June 2019 1.175mlb U3O8 was purchased at $25.88/lb
- In January 2020 YCA announced its share buyback programme
- In July 2020 YCA sold 300klb U3O8 for $33.20/lb and announced a larger $10m share buyback programme. The group also earned $2m for its location swap.
What is the ownership structure of the company and do management have stakes?
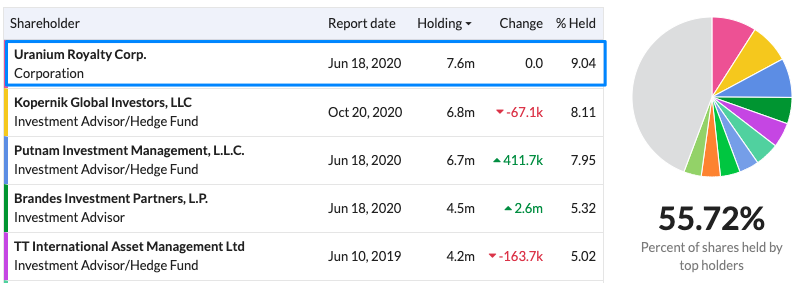
URC is YCA's top shareholder, with a 9% stake.
Valuation
What is the intrinsic valuation of the business?
As of January 2021, YCA held 9.32 million lb of U3O8. The group acquired this at an average cost of USD 21.71/lb. The uranium spot price is currently around $30.20, per Cameco.
This means Yellow Cake currently has a net asset value of around $281m or £205m. The market cap is currently £194m, with a £6.4m net cash position as of the most recent interim results. That makes for a price to NTAV of 0.94. If you account for the cash then this falls to 0.92.
A precise forecast of the uranium spot price is tricky but let's assume that the price rises to $40/lb over the next three years. That is a 32.4% increase in spot price, or +9.8% per year, and is very achievable given that the spot price increased 22.6% to $30.20 in 2020 alone.
This would give YCA a net asset value of $372.8m or £272.1m in three years' time. If you solve to get the discount rate that arrives at today's market cap, that's a discount rate of nearly 12%, which some might view as conservative.
Of course, the entire investment case revolves around the uranium spot price. So if spot prices fall, then so will YCA's net asset value.
Trends & Catalysts
Are there any significant catalysts or macro trends that the business is benefiting from?
There is a structural shift towards renewable energy.
China is leading the charge for new reactors, with other economies like India also growing quickly.
Some argue that uranium is structurally underpriced given expected demand increases and supply reductions, coupled with expected delays once planning for new mines begins.
While mining remains unprofitable, suppliers will be incentivised to fulfil long term contracts by purchasing on the market.
Risks, Threats & Hurdles
What are the biggest risks, threats or hurdles that the business may face?
Uranium price risk - there is no guarantee that the price of uranium will rise.
Key personnel and potential conflicts of interest - Baccus Capital advised in Yellow Cake's IPO. It also set up Yellow Cake, as well as 308 Services.
Counterparty risk - YCA's key partners (Kazatomprom, Cameco, and Orano) may become unable to fulfil their contractual obligations.
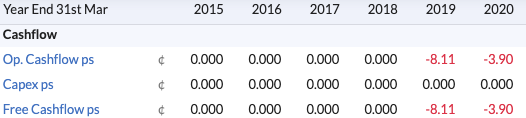
Cash flow risk - YCA is unlevered and has low operating costs - but it does struggle to generate cash.
Regulatory risk - there is potential for changes in laws around the ownership of uranium, or increased regulation or change in government policy around uranium and nuclear power generation.
Political and country risk - Kazakhstan may be at risk of political and/or social instability.
Environmental risk - Nuclear accidents could impact the future prospects for nuclear power.
Recent Trading & News
Summarise the most recent announcements, news and trading statements and market reaction to them?
Interim results (10 December 2020)
Global demand is currently outstripping supply and we expect utilities to re-enter the long term contracting market in 2021 in order to secure future commitments of uranium supply. As a result, we remain very confident in the outlook for uranium.
January 2021 Investor Presentation
Several market sources indicate that nuclear utilities are beginning to focus on the long term uranium market and expectations remain for long-term uranium contracting to increase during 2021 as utility fuel managers pursue forward uranium coverage.
Sentiment
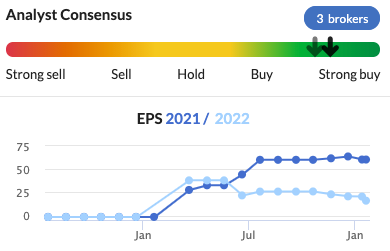
Analysts have been upgrading their EPS forecasts and the community has also been buying.
What would the person selling to us be thinking and who are they?
There are a number of reasons why people might be selling Yellow Cake.
- Investing in the uranium market is fraught with environmental, political, and regulatory risk.
- YCA's fortunes are tied to the uranium spot price, which is beyond management's control.
- YCA's share price has been relatively rangebound and sits just 10% above its IPO price after three years.
Conclusion
Yellow Cake is an intriguing company and an unusual pitch given its lack of any real operations.
The SIC portfolio leans towards Speculative and Highly Speculative stocks and has no Energy exposure, so Yellow Cake could play a useful role in portfolio diversification given its ownership of uranium and its Balanced RiskRating.
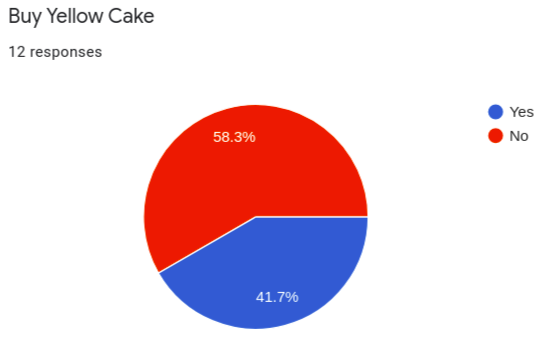
Ultimately the Club voted against buying, although it was a close-run thing. There is a lack of operational control here, and there are also multiple risks to consider despite the (so far) stable share price.
A controversial pitch and we're keen to get views on this company. Will it ultimately rerate? And can it play a useful role in a diversified portfolio, or are those benefits overstated given the associated risks?
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

65 comments
Sprott recently bought URNM (Sprott Uranium Miners ETF). Current dividend is 7% p.a with the Uranium price dropping. I'd argue that URNM is a good way of gaining leveraged exposure to Uranium.
difficult to buy from the UK unless you fill in all the paperwork to class yourself as a “professional Investor”.
The paperwork that I have faced in attaining 'professional investor' status has been pretty minimal and quick and straightforward to complete. I felt comfortable that I ... honestly and truthfully ... met the stated criteria.
I did feel a little uncomfortable that it would have been easy to clear the same hurdle dishonestly and untruthfully. But ... to what lengths are we supposed to go to protect idiots from their own greed-driven reckless stupidity?
Hi Roodini.
Really, I didn't know that.
I bought it via IBKR (Interactive Brokers), I didn't have to fill anything out. Perfectly straightforward.
Ikbr message said something similar for me aswell but I filled in the paperwork for Ajbell to buy it, and watched it crash for the past few weeks
With IBKR, I originally just setup my account to trade everything possible (except futures). It only involved clicking some checkboxes and agreeing to sign my life away w.r.t their derivative instruments (actually now that I think about it, I did have to sit a quick/simple online test for the derivative products).
Surprised to see Yellow Cake (LON:YCA) down 10% this morning and some other Uranium stocks also down, is this to do with the attack on the nuclear power station in Ukraine?
As Yellowcakes main supplier of uranium is a neighbour and ally of Russia, its long term contract could be shaky right now!
Thanks but this was known about yesterday? So I don’t understand the large falls today, Geiger Counter (LON:GCL) is down 15%.
"Uranium Stocks Explode As WallStreetBets Goes Nuclear"
Link to article
"As Sprott Goes 'Hunt Brothers' On Uranium, A Copycat Joins The Squeeze To Force An Explosive Move Higher"
Link to article
for anyone wanting some alternative uranium exposure, Power Metal Resources (LON:POW) have just announced an exploration claim in Canada..
https://www.stockopedia.com/sh...
What do you say about the approx 99% dilution over 5 years? Has it been productive?
With so many exploration initiatives globally how will Power Metal Resources (LON:POW) finance progress so as to keep it licenses and progress resources to be able to sell to developers?
There are literally thousands of these types of exploration plays in Canada and Australia that eat up capital and never hi big. If you must invest in these pick ones with decent proven deposits and a rising price on the asset…
I hold substantial stakes in Canadian,US, Australian, Chinese and London listed uranium stocks and they have already made me life changing returns and uranium is only just above$40 a lb! Yellow cake will go up in line with uranium price as it is driven up by sput and probably others. But the major returns are through the miners and explorers. Paying brokerage and foreign exchange fees pale into insignificance against daily gains we have had and will experience in this bull run. This is a once in a generation opportunity. Do your own research . We are still early but the big investment houses are flooding capital into a tiny sector for a good reason.
Tip ..check aura energy on lse over a one bagger in a week with plenty more to run yet.!
As and when U.Un /Sprott lists in the US I can see it taking a bigger piece of the global uranium investment pie, but as it stands they’re roughly the same order of magnitude (both market caps c.£500m, Sprott currently about 30% bigger than Yellow Cake (LON:YCA) ). Given both are essentially simple stockpiles of uranium (Yellow Cake (LON:YCA) will claim a USP in its relationship with Kazatomprom, Sprott is a much bigger player in commodities/fund management generally and being USD denominated doesn’t have the added complication of currency translation issues) I can see there is room for both.
Personally, it’s more expensive/cumbersome to hold/trade Canadian stocks so I will probably stick with Yellow Cake (LON:YCA) although I’ll be watching both closely and will be interested to compare their respective costs going forwards (Sprott charge a management fee of 0.35%pa plus expenses; not sure quite what the Yellow Cake (LON:YCA) AIC is but suspect it will be substantially higher) and also their respective discounts/premia to NAV. Sprott is currently at an 11.4% premium (as per their website https://sprott.com/investment-... ) whereas I calculate Yellow Cake (LON:YCA) is at about a 7.6% premium). Hopefully over time smarter players than me will arbitrage out any meaningful difference between the two and keep them on comparable valuations. A bit of healthy competition might also keep Yellow Cake (LON:YCA) honest about their charges. I guess time will tell.
Gus.
Some useful information on the Yellow Cake (LON:YCA) website for those who may not have seen it including a quick summary of Sprott’s MO, general uranium market commentary and a matrix for measuring the Yellow Cake (LON:YCA) NAV. Based in Friday’s closing uranium price and assuming none of the other variables (such as cash balances) have moved too much in the past month, £CYE NAV is about 288p per share at the moment.
https://www.yellowcakeplc.com/...
Gus.
I don't know if someone else here pointed out that the new Sprott uranium fund (U. UN) is a game changer for uranium investment. That is to say, U. UN is now the world's largest physical uranium fund (it has shot up over 20% in the last couple of weeks) . This fund is essentially unwelcomed competition from a Yellow Cake investors perspective I fear.
https://sprott.com/investment-...
Hi Alphaflight.
Wonder why you see the Sprott fund as ”unwelcomed competition from a Yellow Cake investors perspective”. So far as I can tell there seems to be a big new speculator in the market hoovering up a growing proportion of the global production of uranium. Given Yellow Cake (LON:YCA) already has quite a sizeable uranium stockpile itself and a contractual supply arrangement to buy future output from Kazatomprom one of the world’s largest and lowest cost producers, surely Sprott’s activities in the market will enhance Yellow Cake (LON:YCA) ‘s value if they drive up demand/reduce the available supply for uranium end users and thereby push up its price.
Gus.
That’s what I thought…?
I predict that Uranium investors (mainly North Americans) will prefer to buy Sprott's U.UN fund over YellowCake [especially when the fund gets its NYSE listing in the near future].
I think gus' point was more that the Uranium spot price market is now essentially governed by two participants who control the majority of annual supply, and will be happy to drive up prices to suit themselves.
This is true although I can't imagine why anyone would buy YellowCake now that Sprott have just come in to the market place and allowed for physical Uranium spot price purchases. Sprott was the largest buyer of physical silver of 2020, I really wouldn't be surprised if they become the largest buyer of physical uranium in 2021...
"Uranium Soars After Sprott Massively Upsizes Buying Program By $1BN To $1.3BN"
Link
Thanks for all the info and research in this thread. I have dipped my toe in the water on PrimaryBid today.
Another PrimaryBid offer announced just now, Yellow Cake (LON:YCA) shares offered at 250p against today’s close at 267p. May close early if heavily subscribed.
https://www.stockopedia.com/sh....
Gus.
I changed my view on yca a couple of weeks ago... added it to my uranium portfolio and it made me a nice bundle
hi... thanks for the piece... after Yellow Cakes recent stock placement and purchase and the subsequent price actiopn I claculate its now trading at a premium to NAV... have i got my calculations wrong? $YCA
thanks
The cost of mining for new uranium is well below its break even price.This in theory means it should be 99% certain that the price of uranium will rise.In practice uranium bulls have been waiting a long time for the uranium price to rise
If anyone has been thinking about dipping a toe/topping up on Yellow Cake (LON:YCA) , they have just announced after market close today a fund raise of up to USD110m including a retail offer through Primary Bid at a slight discount to the closing price at 223p per share.
https://www.stockopedia.com/
Proceeds are intended .... to buy more uranium (no big surprise there). Here is the link to the PB website:-
https://primarybid.com/
I’ve used this as an opportunity to take a small opening position. Roughly a 5% discount and no brokerage or other dealing costs.
I think the placing is perhaps a bit opportunistic, as the uranium price seems to be falling quite a bit at the moment and if that falls further then the NAV of Yellow Cake (LON:YCA) will fall too
Note how uranium miners etc are doing compared to yca this week.....
I have an investment in approx 12 uranium sector stocks. From a capital cycle perspective I see this as one of the best opportunities globally. Not as good as finding a mega growth stock....but I believe more predictable in that the cycle wheel needs to turn in uranium to make the sector viable. That it turns is near inevitable...put aside whatever prejudiced you may have against nuclear and note that the number of power plants is growth steadily and in the West we are realising the energy hubris of shutting down and not replacing with decisions to extend life not uncommon.
The most interesting and persuasive reason to look at uranium sector is that Cameco the primary Western uranium miner has reduced mining and being fulfilling its long term contracts by buying in spot market. They believe it doesn't make long term economic sense to deplete their assets at prevailing prices. Kazatomprom the Kazakh biggest producer in the world has also been committed to price discipline after listing. Together these two dominate production.
There's been massive under investment in capacity replacement with the market supply now moving into sustained and growth deficit (there's a current spike in deficit as covid shuts down mines too).
The problem? The area looks so bad and messy that the individual companies look awful through a backwards financial lens. Its not a comfortable investment and expect volatility and some/many cos to be losers (why I've got a basket).
Yellow Cake (LON:YCA) is sensible exposure to spot uranium and it could see high price rises in future. Spot will likely got through forward. I'm not expert but a double in price at least seems likely. However, the miners and industrial specialists are where the leverage to prices rises are. Some element of resource acquisition and consolidation is also likely. Some small miners likely to be big risers (not all though)
This tweet thread may be informative for people in Yellow Cake too as a cautious perspective
https://twitter.com/Cure4LowPr...
My personal favourite in the sector is a US stock - Centrus Energy $LEU (I hold). It’s a small cap so price movements are a bit lumpy and spread can vary wildly. I first entered last year and flipped for a 40% gain, I have since reentered around the $22 area.
Well worth a look if interested in the Uranium sector. More of a picks and shovels kind of play imo as the uranium must be enriched to be commercial useful. This is the old us govt facility divested and they supply worldwide.
$LEU Not a very good 1Q update yesterday, shares are down 25% as I type, I hold, not sure whether to top up or not.
I don't currently hold, I exited fully on 25 Mar as the price fell below $35. The current level of $25 looks to be reasonably well supported but, personally, I'd be wary at this juncture.
Fundamentals are still excellent imo, therefore I will definitely look to re-enter when the chart signals to do so; which it may just have done looking at that pinbar candle from Friday.... Clearly a lot of buying at that level!
However, the liquidity shelf is between $20-$29 so I'd prefer to wait for a break higher out of this zone. It could fall to the $10 area yet dependent on market conditions in the US. At that level I'd be backing up the truck I think.
Slow but steady progress continues in fusion, the caderache facility and the global research wrapped around it continues. There is also talk of “dustbin” sized self contained reactors that could power districts or households, a “sealed for life” unit dug up after 25 years, similar tech to nuclear submarines. Possibly Yellowcake might be a safe and steady bet, which could go up if political instabilities restricted supply, or the Chinese might just buy them?
Interesting to see so little comment on Fusion possibilities .. someone at Saxo Bank seems excited by research at MIT on SPARC fusion reactor designs .. and the moment that becomes a commercial possibility then how valuable will Uranium be ?
We have some really forward thinking UK based Fusion Energy development from Tokamak Energy. They're capitalising on the modular small form-factor reactors; look them up, astounding test development happening, with lots of private money pouring in.
If it had the vast capital to privately invest in them, then I'd certainly do it.
I prefer the URA uranium miners ETF for leverage
The uranium bull story is out of the gates already. URA was around 11 last October then lept to 17 on uranium bull talk and has now softened to 15.4 so we have already had a fast run up.
If the bull talk subsidies and URA reverts down to a reasonable level, I will buy a few.
It's all contingent on China building a load of reactors. We are in the bottom of the cycle with some miners having taken supply off-line so the upside is there. But, reactor owners tend to buy through long term contracts not the spot market, so it's not like copper etc.
Uranium is also used for X-rays and treatment of certain cancers.
I once dealt with a firm specialized in transporting spent uranium from Canada to Japan for the above.
Thank-you all, I learned a lot when I thought I knew a lot. Investment Club maybe made a good decision as YCA seems to be a one-trick-pony formed for an eventuality that has not materialized (yet?). There have been many false dawns. I held GCL (Geiger counter) before the last sunset. CCO ( (TSE) Cameco) reached 60$ in 2007 and then 40$ in the 2011 commodities boom. It has bumped along between 10$ and 15$ since 2016.
This time seems worth trying.
URNM (U.S. dollar accounts) (thanks bsharman) has all the players including YCA (Yellow Cake).
Uranium Participation TSE:U answers more of my criteria than URC (Uranium Royalty). APF and RR. also interesting.
The case for this is really nothing to do with the merits of nuclear versus other forms of power in my view.
Rather, it is highly dependent on the demand for uranium.
The World Nuclear website says this
“ Looking ten years ahead, the market is expected to grow. The reference scenario of the 2019 edition of the World Nuclear Association's Nuclear Fuel Report shows a 26% increase in uranium demand over 2020-30”
26% growth over 10 years is definitely not a rapid increase in demand for the product.
So, if that demand projection is accurate, ignoring short term volatility, for the uranium price to increase at a fast rate supply needs to be especially constrained in some way. I don’t see strong evidence of that fast dynamic change in the availability.
It might eventually work out but it could be a long wait and there is an opportunity cost to that.
I have significant exposure to uranium through Canadian, Australian and USA stocks. Yellow Cake is similar to a USA stock called uranium participation, which is I think a better play if you want to bet on uranium spot price. Geiger counter a sort of uranium sector fund has very partial coverage and high fees.
If you believe the likes of Rick Rule we are already in the beginnings of a uranium bull market as demand increases, spot prices are hugely below production costs, mines are closing or shuttering operations. In addition there are nuclear plants coming on line and others having their life extended. Many term contracts are coming to an end and it is not in the interest of producers to renew them at prices lower than production costs. Cameco has now stopped producing and is now buying uranium on the spot market to meet its contracts.
The rise of renewable energy sources will need baseload to support electricity grids which will come under increasing pressure from things such as electric vehicles and the variable nature of solar and wind power.This requirement will not be met by coal as thermal power stations are being shut down as probably will be gas power stations in due course. Hence the need for nuclear power which largely relies on uranium.
There are plenty more arguments to support this bull case over the next few years. However, uranium companies either producers, developers or explorers are extremely volatile. In my opinion there is currently an asymmetrical risk reward ratio with the potential for many 30+ baggers for those who are patient and risk tolerant over the next couple of years.
Anybody not buying the recent dip in yca missed out big style! Btw my other uranium stocks up 25% in five days. Aura energy up 25% on Friday an still undervalued !
I think this may have something to do with it:
https://www.reddit.com/r/walls...
Could be a wild ride over the next few weeks...
aura up another 25% today!
I would use this more as a diversifier in my portfolio. With the risk of increased inflation I believe this type of commodity will provide uncorrelated returns. Not too worried if it goes north or not.
Few facts solar is not expensive, China has driven the price down significantly. Pre FIT it cost me £18000 to put up 4kw, that is now sub £6000. Equally I have never heard of wind turbines affecting the local micro environment. I visited a community near Nottingham who are living entirely sustainable lives and they have a big turbine. It neither is noisy, nor kills birds nor any of the other strange accusations I have heard about it.
have noted many flowers in my garden blooming out of their normal season (I had Daffodils before Xmas!!!) but this is a result of climate change not wind turbines.
I think Uranium has a role to play given the need for a stable power source which is not hydrocarbon based. I like Simec Atlantis' wave technology which would help in this area but unfortunately I think we will need a source like this as a back up. Always concerned about anything that leaves a poinsonous deposit behind.
let me explain what I mean by micro climate.Plants make food by photosynthesis and co2 .The wind turbines harness wind power into electrical energy.When you create this artificial source
Micro climate ,
Waves from the blades of the wind turbines disrupting the air pocket above the trees and plants.You can see summer flowering roses flowering now.I don't think its only due to global warming ,that plays a part as well as the wind turbines.
Harnessing Solar energy into electrical energy and storing it into special cells so that electrical energy can be used when sun is no longer shining.Again we will need to dispose off battery that it self can have a environmental impact.Disposing off large nos.
Don't forget the sun moves. Rises from the East ,moves to the south ( mid day sun ) is the strongest and stays there the longest and finally sets in the west.If the solar panels are on the north facing roof top the capacity to generate reduces considerably.When the initial solar panel scheme started the subsidy was a lot then as time went by it reduced.I don't know how much each household puts back unused electricity into the grid.These panels produce far less than the daily consumption per household..The winter sun is lower ,dust ,fog can have an impact along with the angle of the sun rays striking the face of the panel .Gcse physics angle of reflection and angle of refraction.You want all the sunlight to refract so that it can be converted into electrical energy.
Elon Musk has taken the EVs to the next stage of development. The environmental impact is still there.
As a student I remember doing a case study on Chernobyl disaster and the environmental impact it had.The safety inspectors asked the management again again over many years to look into the problem. Which they ignored until the disaster happened.I can't remember whether it was ignored due to lack of knowledge or lack of resource.The result was quite devastating.
I am sorry ,I was just trying to point out what I had observed.Sometimes addressing the issues earlier on can stops ir reversal damage to the environmental which we are all trying to preserve for our next generation and future generations.
I hold Canada's Uranium Participation (U).it is the only ranked Superstock in the Uranium sector and some Elliot Wave technicians give it a potential upside of 800%
It is important to look at the whole picture.Fossil fuel has impacted the environment long term.We feel obligated to switch to green energy like Solar and Wind.If we take solar ,it is expensive to generate electricity.The factors being Sun does not shine at night, winter sun is quite low ,harnessing the solar can be a problem (battery)can be expensive, fog ,dust can reduce the efficiency of the panels.Therefore making it expensive.Once the subsidy finishes it may not be as popular.
Wind has its own problems, wind turbines built inland can affect the micro Climate .I have observed this in my garden, the bulbs that are supposed to come out are delayed by a month or two .Some summer plants are flowering in Winter, the whole ecosystem is affected.If plants are flowering at the wrong time when there are no bees or birds there fore affecting pollination.We may be affecting the environment in a big way thinking that we are protecting the environment.We can do irrevesible damage to the environment without knowing.
Finally ,Nuclear energy, we can generate large amounts of electricity in nuclear reactors using uranium ,however disposal of radioactive waste is far more expensive than generating electricity by Nuclear.If these nuclear plants are left in a state of disrepair like Chernobyl ,this could lead to an environmental disaster.The cleaning up is far more expensive and could affect the environment far greater than fossil fuel.
The cost of generating electricity using nuclear will not only depend on cost of Uranium but disposal of radio active waste which will be very expensive and have far greater impact on the environment if it is not properly disposed.The cost of uranium is small compared to other factors.
I am sure all these factors are important consideration when choosing the type of energy replacing fossil fuel.
Excellent article Jack and thanks for spending the time to look into this market and Yellow Cake (LON:YCA)
I have been following the Uranium market for a couple of years and recently there have been quite a few very bullish reports (Bank of America Merrill Lynch for example have it as their #2 top tactical theme).
The upside potential in my opinion is huge but this depends on when the utilities come to market and the market is very opaque but the consensus is that they will need to very soon to avoid future outages. The bull thesis is that there is a massive supply shortage and most mines require a much higher spot price to generate a profit.
I own Yellow Cake (LON:YCA) , Geiger Counter (LON:GCL), $UUUU and URA (ETF)
It is a shame in the UK we cannot buy $URNM (North Shore Global Uranium Mining ETF) as I would be using this to diversify risk. However readers may like to look into the Investment Trust Geiger Counter (LON:GCL) , which is a specialist Investment Trust under the banner of CQS
www.ncim.co.uk/geiger-counter-ltd
Happy Investing !
Ben
Factual point - Uranium is NOT a renewable resource although it is a low carbon one.
Separately, I have held Cameco for nearly 7 years awaiting price recovery as investment stalled and 2y sources were expected to be used up. It hasn't happened!
I now expect genuine renewables (Wind, Solar + Battery) to become so cheap within 5-15 years that the business case for nuclear will disappear and many of the planned sites will not be taken to completion and may even become become stranded. Certainly the cost of abandonment in democracies will become very low. Only retaining existing capacity + for nuclear weapons seems likely.
So a quick spike up is possible for maybe 5-10 years but this is a narrow, risky window to aim at for an investment. As said, I hold but am very likely to sell out of Cameco.
You need to bear in mind that a grid system must have large rotating generating plant to operate. The physics of power generating and distribution make this compulsory. Wind, solar and battery will not provide this, so nuclear is essential and will never lose its business case.
GE are deploying a quite cool “spinning reserve” machine for grid support, so big spinning alternators not needed. As far as I know, they have the lead on this!
"Factual point - Uranium is NOT a renewable resource"
I was just about to make that very point.
Do think renewables will meet damage with the switch to electric cars and data storage? Heating is also switching from gas to electric, although this may take many years.
Most of the UK nuclear power stations will be closing down by 2030.
Fossil fuels are also being phased out.
China is building or planning to build over 200 nuclear power stations.
Fair point Zipman, should be careful with the language. Perhaps 'sustainable' is a better word, the key point being that it is expected to last for the period of human history that needs it, ie. depletion is not a concern.
Interesting point on wind, solar, and battery. On a more general note, these comments around the article are packed with value-added contributions, some really fascinating community insights here.
"Fair point Zipman, should be careful with the language. Perhaps 'sustainable' is a better word, the key point being that it (uranium for nuclear) is expected to last for the period of human history that needs it, ie. depletion is not a concern"
Depletion is also not a concern these days on coal (and arguably oil !!) . Most people now agree most remaining coal will be left in the ground as it is i) expensive vs alternatives (in most places now and increasingly everywhere) ii) polluting iii) has a huge tailrisk (Chernobyl in Somerset). In the same way as coal, I think most potential uranium will be left in the ground. (Note whilst a environmentalist, I have supported nuclear for 20 years - it is just that the cost/benefit equation has changed)
The financial and environmental risk you have to take on to build a multi-billion dollar, 30+ yr minimum life cycle nuclear power station is huge. It is showing fewer signs of benefitting from the kind technology led efficiency improvements that solar + battery combinations offer long term. This mean only very long term governments with very large capital budgets can afford nuclear - that means China becomes an ever larger player. France/Japan will struggle to replace its current fleet, the US has enough of solar/wind/battery potential to vastly exceed current needs including electrification of transport and heating; who else has the money !!
Facing China as a monopsonist buyer willing to buy its entire needs from state controlled entities in Kazakhstan seems like a tough place to be for a listed intermediary. Hope Yellow Cake (LON:YCA) is a trading idea not an investment!
That maybe the case in the UK and the Europe but not in China, Russia, Australia and India, global coal production is not forecast to peak until around 2035. Even the USA produces and uses a lot of coal although that may change under Biden.
I am not sure I agree. Trump was explicitly pro-coal but coal stilled declined rapidly. China is leading the green energy world and sees pollution as a key political issue as well as an economic issue.
I expect lower costs/jobs potential of green energy to drive out coal quite rapidly even where govt/popn do not care about the externality costs of pollution. Obviously, where mine/jobs exist, these will tend to linger since there, fixed costs are (literally) sunk and politically closing mines is very visible. However, investing in new mines is a different story.
On the other side, every man and his dog now wants a "giga-factory' for batteries and EV cars now have lower lifetime costs than ICE, adequate range and close to parity acquisition costs (esp with PCP leases). At the micro level jobs are being created in large quantities in installing & maintaining green energy. The political winds are blowing strongly in this direction everywhere. Even Boris now has a 10 point green plan (although as someone interested in environmental economics for >30yrs, I question his understanding and commitment to it!!).
The whole world is going to experience a classic total market disruption like when cars replaced horses (in the then developed world). It seemed impossible until it happened very quickly!
Everyone has their favourite 'ideas' source. Th Economist cites Keynes in 1936 ."Practical men, who believe themselves to be quite exempt from any intellectual influences, are usually the slaves of some defunct economist" . Madmen in authority, who hear voices in the air, are distilling their frenzy from some academic scribbler of a few years back.”
As someone whose posts I respect, as usually on point and factually based, I recommend looking at the Rethinkx series of white papers led by Tony Seba eg the one on energy. https://www.rethinkx.com/energ...They made me change my investment portfolio - a clear sign of myself being persuaded by them. Thought provoking at worst!
I hold. Great summary. Compelling for me is the huge, global momentum toward renewables and with it the pressure on existing power sources. Rolls-royce Holdings (LON:RR.) may also be a way to play this with its modular reactors.
I am not clear what one gets by buying Yellow Cake rather than Kazatomprom apart from a SR of 81 rather than a SR of 50 ... it is bascially an outright punt on the Uranium price and I am so happy I put my money into Sylvania rather than Yellow Cake
To digress slightly, you can get some Uranium exposure via UK listed: £APT
They have 9% exposure to Uranium. See here: https://www.anglopacificgroup....
£APF £ APF u meant?
Then again - they have exposure to thermal coal too
Having looked at a few of the company's presentations they put together a very strong case for why uranium prices should rise sharply (a supply pinch), but so far this has not happened. Prices not really moved in 3 years, so things probably not turned out as they would have hoped when they IPOd (although this could change of course). Don't have anywhere near enough expertise to understand what drives commodity prices, but seems to be a disconnect between where prices should be and where they actually are.
Should the pitch date be 19th January 2021 rather than 2020?