Strix - modest valuation and long term growth potential

About three months ago I covered Strix (LON:KETL) (here) . Quite a lot has transpired since then.
The group has just released its FY20 annual report and I’m interested to see how it is getting on in this COVID-19 era. In my view Strix is a very promising company and could become much larger in time.
I think this because:
- Strix occupies an important position in the global domestic appliance value chain,
- It has world class facilities,
- It has patents that it vigorously defends, and
- It is investing millions in research and development,
The group has a total of 14 new products set to be launched in the coming year. With a market cap of less than £400m, I think there is plenty of scope for steady growth.
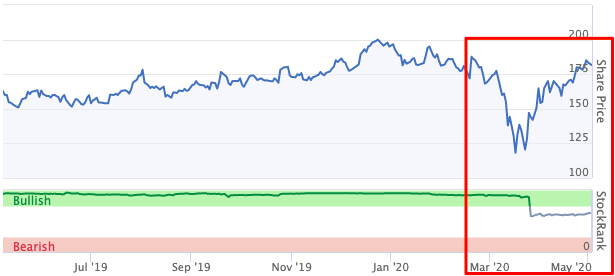
In the meantime, this is a high quality, cash generative, modestly valued company that rewards shareholders with an attractive yield and is well placed to defend its favourable market position. Its shares have rebounded strongly after tumbling in late March and its StockRank is also showing signs of recovery.
What can we take from the FY accounts?
Headline results
FY19 has been a continuation of established trends. Growth has been lacklustre and even negative on an unadjusted basis:
- Revenue +3.3% to £96.8m
- Operating profit -6.1% to £24.2m
- Adjusted earnings per share +2.1% to 15.2p (adjusted PE ratio of 12x)
- Total dividend per share +10% to 7.7p (4.2% dividend yield)
The company has strong long term prospects though thanks to its entrenched market position and increasing levels of research & development spend (in both relative and absolute terms):
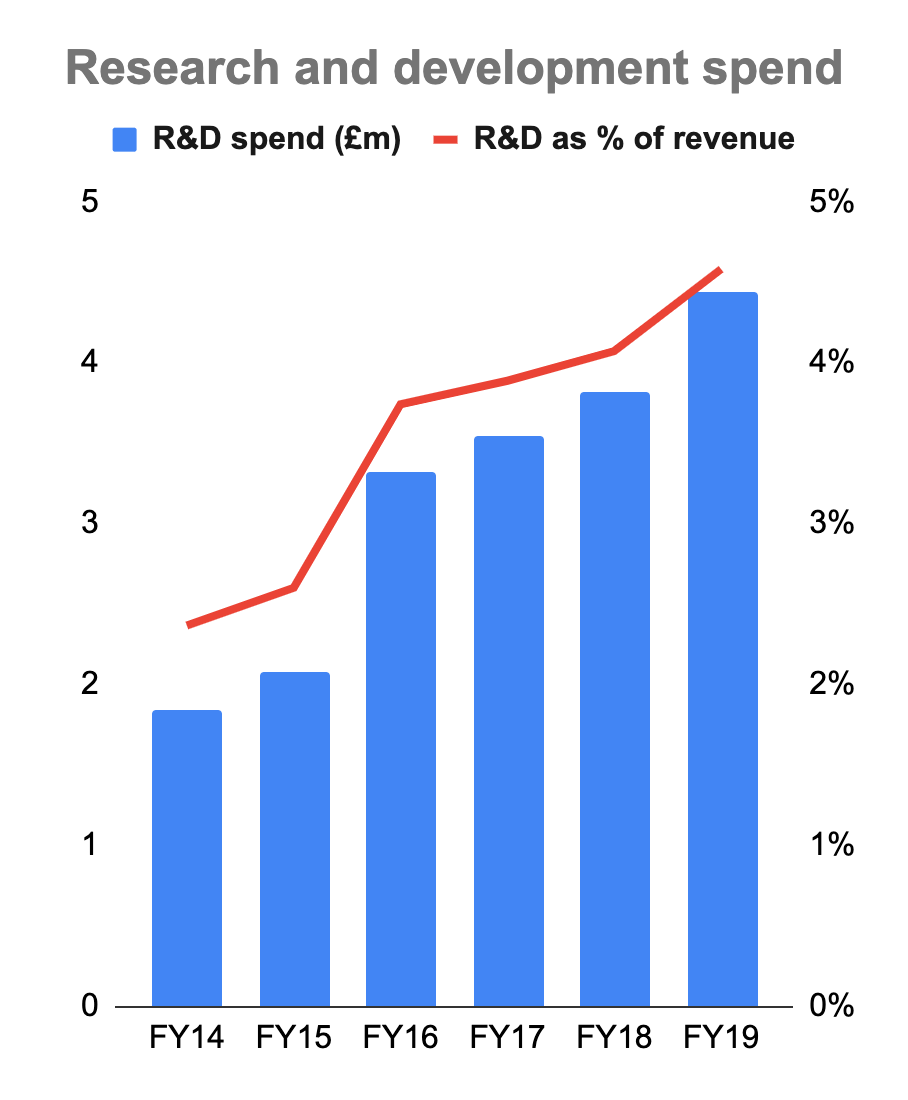
With 14 new products slated for FY20, investors will be expecting to see signs of growth in the next year or two.
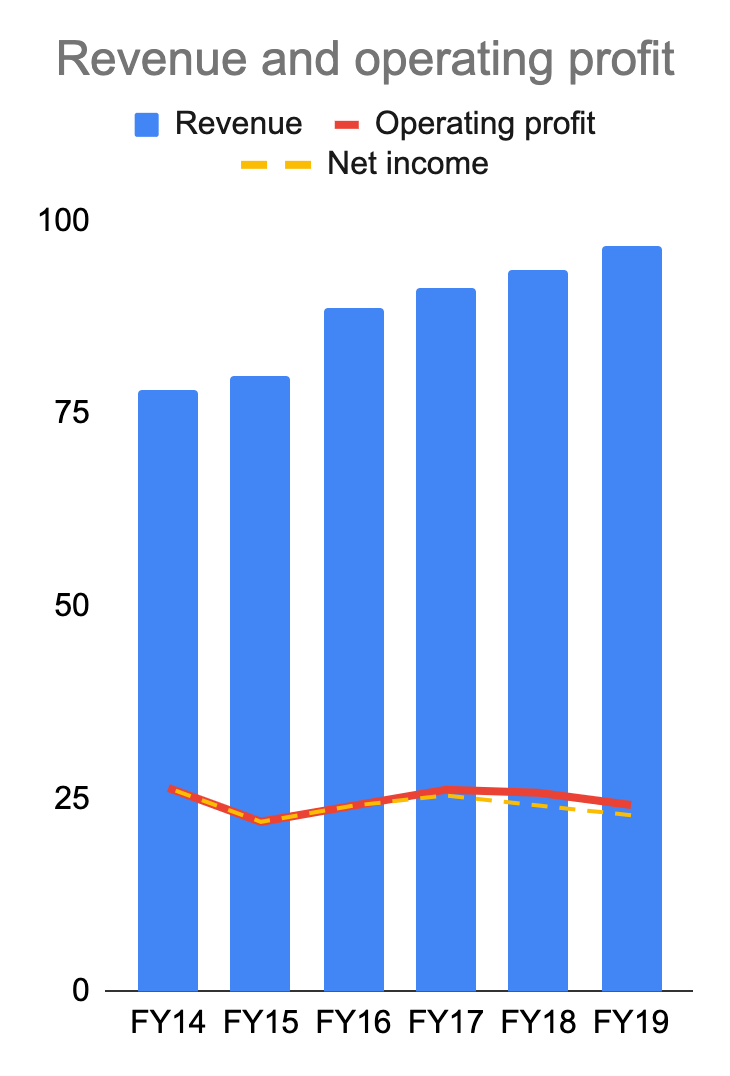
I’m not overly concerned with the current lack of profit growth because of the following points:
- Strix is high quality - it is financially sound, cash generative, and profitable,
- It is expanding its operations, investing in R&D, and bringing down net debt,
- Its market position is strong and is backed up by valuable IP that is vigorously defended,
- The group pays out an attractive and comfortably covered dividend to its shareholders, and
- New product launches are imminent.
COVID-19 (lack of) disruption
It is perhaps surprising that the two companies I have recently looked at with large manufacturing bases in China - Strix and Volex - both appear to have bounced back remarkably well, leaving more UK-focused companies in the dust.
To recap, Strix currently has:
- Its head office and a manufacturing facility on the Isle of Man,
- A sales function in the UK,
- Sales and manufacturing in Shanghai, China,
- Its main manufacturing base in Guangzhou, China, and
- Sales and finance operations in Hong Kong
The impact on Strix has thus far been limited with the Guangzhou manufacturing facility operating at 96% resource levels as at 18 March 2020. Its top 20 largest OEM customers have resumed production and are continuing to increase capacity.
Strix is providing medical supplies such as face masks, thermometers and sterilisers to its Guangzhou factory employees. Perhaps we will soon be seeing UK-based companies taking the same measures...
Its new factory within Zengcheng district is on target to be fully operational by August 2021 and remains on budget at the previously guided £20m. This new site should be an important source of operational cost savings and productivity gains in the years ahead.
What is the company doing to grow?
Strix operates three segments: Kettle controls (88.6% of revenue), water filtration (10.2% of revenue) and Appliances (1.2% of revenue). Its core products are safety controls for small domestic appliances (mostly kettles), which are responsible for disconnecting the power to heating elements at the point of boiling water.
There are 14 product launches coming up in FY20:
- Two new products in Kettle,
- Seven new products in Water Filtration, and
- Five new products in Appliances.
We can see that the group’s Kettle segment continues to dominate revenue:
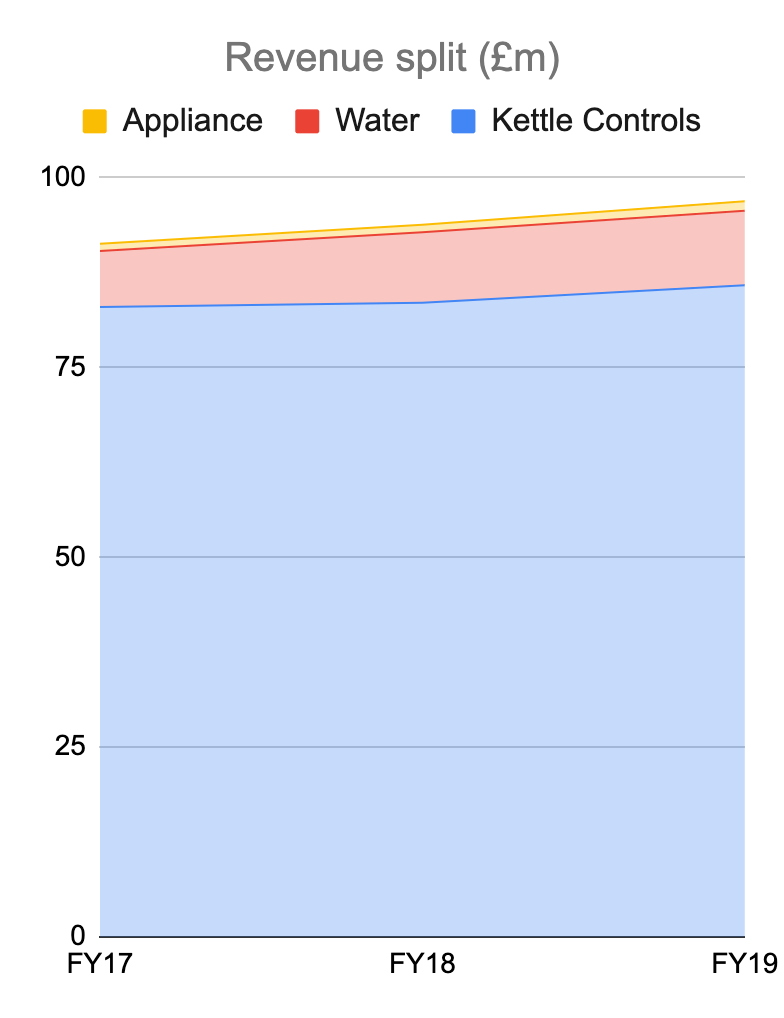
This graph obscures the strong progress being made in the Appliance category due to its small overall size, however. In FY19 Kettle Controls grew 3%, Water grew 6% and Appliance grew by 26%.
Strix is actively seeking niche acquisition or technology opportunities “to further enhance the Group’s growth potential within the water and appliance categories”. The long-term vision is to diversify its revenue streams across the three core categories.
Kettles
It is estimated that the value of the global kettle control market grew c.3% to c.£160m in 2019 as more households around the world (c38%) benefit from electric kettles increased. Within this market, Strix maintained global market value share of kettle controls at c.54%.
Breaking this down:
- Regulated market share was maintained at 73%,
- Less Regulated market share was maintained at 34%, and
- China market share increased to 49%
Water filtration
The group’s water category reported 6.1% growth in revenue in 2019.
The Aqua Optima brand is strategically positioned to take advantage of the market shift towards trade-brand filters and it concluded a number of sales and partnership initiatives in 2019 “which are expected to lead to expanded distribution opportunities into new markets.”
The Astrea brand acquired from HaloSource in March 2019 is collaborating on a new Philips co-branded water bottle globally outside of North America and is launching two other products.
The HaloPure brand is focusing on new business development related to the sterilisation industry. The brand achieved positive testing results and strong interest from customers in the farming and medical sectors and is seeking government approval for a sterilisation product license within China.
Although the acquisition of certain assets from HaloSource adds “significant R&D capabilities and commercial opportunities”, this business contributed an adjusted total comprehensive loss of c.£2m.
This is in line with management expectations, apparently, but is probably worth keeping an eye on.
Appliances
The appliance category reported a 25.9% growth in revenue in 2019 and further product innovation is in the works, with a particular focus on baby care and ‘hot water on demand’.
- The latest version of Tommee Tippee’s appliance was awarded the Mother & Baby gold award for ‘innovation of the year 2019’
- The group signed a development agreement to launch two new products in 2020 with a leading Asian mother and baby brand,
- Strix launched the Zwilling Water Dispenser in April 2019 which uses its patented instant flow heater ‘IFH’ technology, and
- It launched the Mr. Coffee HotCup unit, designed as a pod-free single-serve brewer featuring Strix’s patented kettle-heating technology.
Net debt and cash generation
Strix has a net debt position of about £27m but this is more as a result of previous private equity ownership rather than ongoing operations. I believe net debt will come down in the coming years. There is evidence of this happening in FY19.
As a result of strong cash generation, the Group managed to:
- Improve its net debt position to £26.3m (2018: £27.5m),
- Increase dividend payments by 10%, and
- Spend more on investing activities.
Automation and operational efficiency
Lean and continuous improvement initiatives have continued to be a key focus for Strix. A total of £0.2m of savings were generated in 2019 from a total of 17 projects.
Impressively, some 521 million parts were manufactured at Strix’s factory in Ramsey by a team of just 37 people in FY19. The group’s existing facilities are world class and the group’s new factory in Guangzhou will further cement this position.
The relocation of manufacturing facilities in China will support the future growth ambitions of the business and enable the Group to maximise the benefits of automation. This important project is on schedule to meet the August 2021 completion with costs in line with expectations.
The group continues to increase production volume, quality control and reliability via higher levels of automation. This also gives it more control over costs (in particular rising wage costs in China). This investment in automation has helped drive an improvement in the production efficiency of core kettle products by 5% to 98%.
Conclusion - modest valuation, quality characteristics, and growth potential
This is a solid performance from a company that I believe can create meaningful value for shareholders in future.
Strix is holding up well despite the recent global turbulence. It is testament to the group’s defensive, high quality business model and the genuine value it provides to various stakeholders in its domestic appliance markets.
Its core kettle control market is growing and resilient and it is working hard to drive growth within the water and appliance categories. This will not just add to profits in time but will make for a more diversified and balanced company.
New products are in the works and Strix’s manufacturing operations in China have recovered with a c.100% production capacity and operational supply chain which is sufficient to meet customer demand.
What’s more, profits are protected by IP - in FY19 the group again took action to limit online sales in Europe of products that infringe IP, resulting in the taking down of 17 electronic kettles. With management now free to focus on growth opportunities and exciting innovation projects, I think the future is bright.
A PE ratio of c12x and a dividend yield of more than 4% strikes me as undemanding given its leading position in a growing and resilient domestic appliance market, even after the recent recovery in share price.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

22 comments
Strix (LON:KETL) beginning to look interesting. Possible breakout soon?
have held strix for over one year. where its based in china hasn't really been effected with virus. its only challenge is chinese companies trying to make fake similar items. but patents have held up. and stopped with compensation.. all depends how long patents are valid for. but strong company
Been watching it for a while now, may dive in next week.
Very interesting, potentially useful and clearly some people were aware of this report as early as 4 May, presumably those already watching the stock. Still, your email alert to it, received today, would have been potentially more advantageous the day before the ex-divi date than the day after… Ho hum.
A great article Jack. Strix (LON:KETL) is a core holding of mine, so I am clearly biased. Just a quick heads up that they go ex-dividend for 5/7ths of their overall annual dividend this Thursday, 7th May.
Cheers,
Simon
Stephen English is a great fan of Strix (LON:KETL)
( https://www.stockopedia.com/content/stephen-english-piworld-webinar-a-plague-on-all-our-houses-how-to-repair-some-of-the-damange-590268/ is worth watching)
I keep meaning to look at this! It was linked in the previous article comments as well so must be worth a watch.
Hi Jack
Should have replied to you directly re my previous post.
Great write up on Strix but any thoughts/concerns on earnings manipulation risk being flagged as high on Stocko ?
Thanks Andy
clarea, if you go to the Strix (LON:KETL) stockreport and click on the m-score link it will take you to a breakdown of the M Score. There are two factors marked with a red cross, depreciation and receivables which are major contributors to the poor score.
The depreciation is explained in the annual report "Depreciation increased to £4.2m (2018:£3.2m) as a result of the adoption of IFRS 16 which incurred £1.3m of right of use asset depreciation"
I can't see a reason for the increase in receivables relative to sales.
Many thanks for the steer presuming risk is profits could be being booked on receivables before the money has actually been banked ?
In the 1999 paper Beneish says of the DSRI,
"This variable gauges whether receivables and revenues are in or out-of-balance in two consecutive years. A large increase in days sales in receivables could be the result of a change in credit policy to spur sales in the face of increased competition, but disproportionate increases in receivables relative to sales may also be suggestive of revenue inflation. I thus expect a large increase in days sales in receivables to be associated with a higher likelihood that revenues and earnings are overstated."
Reviewing my comments on depreciation I realise that the situation is rather more complicated than I initially thought and the explanation I came up with is wrong. I will ponder it a little longer.
Hi Andy,
Apologies for the delay here - it actually prompted some unscheduled investigation on my part...
The receivables figures for 2018 & 19 were not comparing like with like for a little while last week. Our data provider was giving us a gross figure for 2019 and a net figure for 2018. It gave the impression of a big gap up in receivables year-on-year.
You will notice now that our data provider has corrected this. The 2019 net receivables figure has gone from c£9m to c£6m and KETL passes the earnings test as a result.
Thanks for pointing this one out!
Thanks for getting back to me Jack keep the articles coming a lot of the stocks you review come up in my quant screen so good to have another more experienced pair of eyes input.
Appreciate your input
Andy
Would there be any chance of getting your latest views on Strix (LON:KETL): after the update today Jack.
Regards Andy
Thanks Jack, delighted to log in and see this as I bought in to Strix this morning on the opening bell!!
I think the PE ratio shows the company priced currently at fair value when you look across the Industry and historic PE metrics, but the potential for growth and ongoing operational excellence makes me a buyer.
14 new products point to not only a diversified product portfolio as you mention but the potential to find new revenue streams and when you look at the award winning stays these are achieving it can only bode well for future sales.
Operational excellence through not just ‘Lean’ but combined with ‘continuous improvement’ initiatives alludes to an operational culture where all minds within the business are engaged in waste reduction and value creation, from shop floor to CEO and should lead to improved margin and ability to compete on price & quality in new markets.
Thanks again for the write up!
A very good interpretation on a company based where I live. I would agree there is a brilliant future
Great write up Jack do you have any thoughts/worries on Stocko flagging earnings manipulation risk as high ?
@ Clarea - Odd. I'm looking on the main Stocko page for this stock four days later (Friday 8 May) and that metric is rated as 'low'? How did it change so rapidly?
Just had a look your correct very odd
The Annual Report was published on 4 May. Following this, the Stockopedia figures were updated, which is what caused the change. I am slightly surprised by this as the StockReport for Strix had already been updated after the final results were published on 18 March. What changed between the results and the annual report?
Earnings manipulation risk is high again.
Net goodwill has jumped from zero to almost 10m. Net intangible assets have tripled. 2020 sees deferred income tax appear on the balance sheet for the first time.
It's going on my short sell watch list.
Isn't that just all a consequence of one recent acquisition (I haven't checked)? Probably more meaningful to consider the pros/cons of the acquisition.