SUL: Super performance and still cheap(ish)

Super Retail (ASX:SUL) began life as SuperCheap Auto and listed in 2004. The well known chain of car parts and supplies is still the largest component of the group, making up 38% of revenue. The name was changed to reflect the growing diversity of the business as a retail group. It is now focused on four main brands including BCF, Rebel and Macpac.
Over the last 20 years the business has grown from a market capitalisation of $210 million and sales of $383 million to market capitalisation and sales of $3.8 billion each today.
Focusing on the last five years they have sustained a sales CAGR of 8.5%. Sales jumped 22% in 2021 as they benefited from the Covid boost that saw many retailers experience bumper sales as governments handed out money and consumers had limited ability to spend on travel or experiences.
They have not only held onto these gains, but experienced further growth in 2023 of 7%. A number of other retailers, including Harvey Norman Holdings (ASX:HVN) and Temple & Webster (ASX:TPW) experienced sales declines in 2023. Growth is forecast to continue in 2024, whereas for others such as Nick Scali (ASX:NCK), JB Hi-Fi (ASX:JBH) and Harvey Norman, sales are forecast to decline.
In mid January they issued a trading update for the first half of the year which was very well received by the market. It showed a positive result of overall sales growth of 3% and like-for-like sales growth of 1%. The Christmas and Black Friday period saw robust trading despite cost of living pressures.
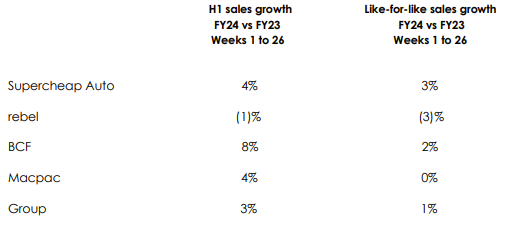
Source: Super Retail Group, Trading Update, 15/1/24
What was more impressive was the profit before tax figure expected to be between $200 and $203 million. This was well above market expectations. Gross margins are expected to have improved since H1 FY23 but the cost of doing business (CODB) has increased as had been previously foreshadowed.
Rebel sales were a bit soft in the most recent half, but they had strong like-for-like sales growth in FY23 of 9%. In October they launched a new customer loyalty program. Rebel are investing in their stores, with a focus on upgrading them to the rCX (rebel customer experience) format. These are large format stores with a wide range of products. They also include experience zones such as indoor basketball and football and gaming consoles. These upgraded stores have shown significantly improved sales performance of 50%. There are now 15 of these stores (18% of the total) and they are planning to upgrade another four in FY24.
SuperCheap Auto is the largest division by revenue. It accounts for 38% of the Group’s revenue and also has the highest operating margins at 15.2%. There are 331 stores with plans for another eight this year and 40 upgrades.
Rebel is the second largest division with 34% of revenue followed by BCF with 22%. BCF is the least profitable segment with operating margins of 7.3%. Strategies in place to try and address this include building out more Superstores which have proven to be a lot more profitable.
Overall the business achieved an operating margin of 11.1% slightly higher than the average for the last five years of 10.2%. The average net profit margin over the last five years has been 6.3%. As is often the case with retailers these margins are quite tight, but they are fairly typical for the industry.
Super Retail have a Quality Rank of 88. This reflects a really solid balance sheet. The bankruptcy risk is low and the health trend is high.

They hold no bank debt and had a cash balance last June of $192m. The debt shown on their balance sheet is for capital leases, that is secured leases over the properties that they use for stores and warehouses.
Super Retail is one of the stocks that was included in the NAPS portfolio for 2024. That is because it was the highest ranked Consumer Cyclical stock of sufficient size (National Tyre & Wheel (ASX:NTD) ranked higher but was too illiquid). Since the portfolio was rebalanced on 1 January, they have issued a trading update as mentioned above. This has resulted in the expected decline in earnings per share contracting from 15% to 10%. It will be interesting to watch how that changes over the coming six months.
The question mark for the stock moving forward is the value rank, with the stock having rallied by 35% in the last six months there has been pressure on the value rank. It has declined by 1 since the start of the year, but 82 is still a very good rank. The forecast rolling PE ratio is 15.2 which is certainly not excessive.
The business was founded in 1972 by Reg and Hazel Rowe. Reg Rowe retired from the board in 2023 but remains the largest shareholder in the group with the family holding 29% of the issued shares.
With SUL having been included in the NAPS portfolio we will be keeping a very close eye on it over the next 12 months.
Important Information: Stockopedia Ltd ABN 39 757 874 670 UK business registration number 0637267 (“Stockopedia”) is an Authorised Representative of Daylight Financial Group Pty Ltd ABN 77 633 984 773 (“DFGPL”) which is the holder of an Australian Financial Services Licence (AFS Licence No. 521404).
Information in this commentary is current as at date prepared unless otherwise stated. However, please bear in mind that investments can go up or down in value, and that past performance is not a reliable indicator of future performance. For more Important Information please refer to the Disclaimer section of this website.
This communication may contain general financial product advice. It has been prepared without taking into account your personal circumstances, and you should therefore consider its appropriateness in light of your objectives, financial circumstances and needs before acting on it.
If our advice relates to the acquisition or possible acquisition of a particular financial product, you should obtain a copy of and consider the Product Disclosure Statement (PDS) before making any decision.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
No comments yet
No one has commented here yet! Why not be the first one?