Summer Value Stocks, including Molins, Hellenic Carriers, Johnston Press, Mouchel Group and Record

I secretly love the sort of declines we've seen in the market over the last few weeks. Obviously, portfolios take a battering, which is never a nice feeling - but it's from the wreckage that the best bargains are often found, and while I've no idea which direction the market may go in the coming few months, I am willing to wager I can find some fallen stars in the investing landscape right now. I don't indulge my curiosity in guessing which direction the market in general will move - there are far more experienced people attempting that sort of thing (and their success is debatable!) - and so I tend to disregard the level of the indices when looking at individual stocks. Sure, the prices may continue to tumble in the next couple of weeks. But equally, they may well start to rise - meaning I've missed the boat. If you're able to tell me with any certainty which it is, I advise you to stop reading blogs and start printing money! While it'd be great to look at all the potential investments in the market, it just isn't a feasible prospect; particularly at the moment. Hence, I scan down my screens and look for a few specifics to analyse. Usually I discard the ones I don't have time for, or stick them on a watchlist to see if they decline further and become even more interesting - but that always seemed a little wasteful. So, assuming I manage to keep this up, I'll aim to semi-regularly (read: at least monthly, sooner if the stocks are changing rapidly!) publish a list with a few that are particularly interesting to me at the moment - ones which I'm considering writing about. The list will be compiled completely unscientifically - I don't look at my screens and pick the top 10%, for instance. It's simply a case of looking for numbers which seem to glue together for an interesting story and keeping some sectoral diversity - it's when one really interests me that I start looking at its competitors and their valuations, and hence it makes sense for me to cast my net wide at this point. I should stress the list will be a tiny proportion of the great number of stocks which look interesting; once again, it's just a case of picking a few. Without further ado, here's mid-August's longlist!
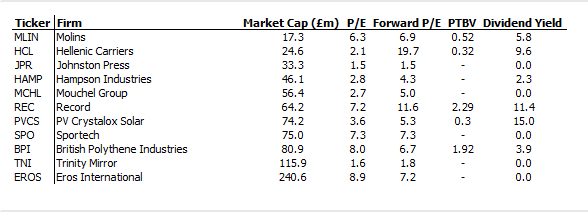
Molins (LON:MLIN): Molins engineers and manufactures specialist machinery for the 'fast moving consumer goods' market. An IMS confirmed they were trading in line with last year, where they earned enough to put them on a low P/E of 6.3. Their financial position seems very strong - if they were able to claim back all their receivables, and sell all their inventory at the cost it's recorded at on the balance sheet, they'd more or less be able to pay off all their debt and be sitting on their £14m cash pile for distribution to share holders. That sort of 'winding up' scenario is probably a little harsh, though - they still seem to be earning good money, so it's more likely that the strong book value simply gives the investor a big margin of safety. They've a long and profitable history, barring a short mid 2000s blip, though revenues do seem to be in long term decline - probably explaining their valuation both in earnings and assets terms.
Hellenic Carriers (LON:HCL): Hellenic Carriers predominantly interest me by the strength of their book value and the previous operating performance - though it doesn't take a rocket scientist to figure there's probably some pretty bad news in a stock trading on such a minuscule P/E. Even for an outsider, the story in general is fairly easy to understand - they ship things from point A to point B, and the biggest measure for the cost of shipping (the Baltic Dry Index) is rather changed from their previous operating performance. Some writers have suggested that, given their operating costs last year, it seems impossible for them to continue to make a profit. If one forecasts a reversion to anything like previous prices (or the huge prices pre-recession!) the upside potential is huge - but given further capacity coming online in the sector (most operators expanded when rays of economic recovery started hinting at a recovery in shipping) the fact is that Hellenic may remain squeezed for the foreseeable future.
Johnston Press (LON:JPR) and Trinity Mirror: Philip O'Sullivan piqued my interest in the publishing groups with his paragraph on Trinity Mirror. Put like that, it certainly does seem tempting! I've grouped Johnston and Trinity Mirror together as they're ostensibly similar stocks on similar metrics, and for a summary it's probably fair. They're in a dying industry - we all know that much - but is it dying enough to justify a valuation of less than 2 times both forward and historic earnings? Well, several factors cloud the picture. Both groups have some kind of debt or fixed obligations. The problem isn't as big in Trinity Mirror's case, but Johnston Press list ~£780m of liabilities against ~£250m of tangible assets. Debt normally isn't as big a problem in growing businesses - it is, after all, what helps them increase their revenue/profits; which in turn reduces the burden of the debt. In declining industries, though, the opposite happens - and I'm left with a timeline (perhaps 10 years?) with which this debt must be paid off out of reducing revenue streams. I have to forecast £530m (liabilities - tangible assets) of profits before an equity holder can see a penny. Still, as I say, Trinity is in a more comfortable position with regards to its debt pile; and while I've outlined the bearish story above, one has to remember that we're in a depressed market for advertising too. It's plausible we may see an improvement in that market in the next few years. The market is pricing in rather a horrendous crash-and-burn in the near future; all I have to do is see it earning a few more years of decent money and there's a huge upside on the 1.6 P/E. There's a lot of judgement decisions in an investment like this, though.
Hampson Industries (LON:HAMP): Hampson have fallen fairly steadily since the start of the financial crisis - from a share price of 200p to 16p now (I haven't checked for dilution) while their revenues have continued to rise. Profits have slipped due to the recession - but this sort of continuing revenue growth vs. a recession induced margin decline does hint at the potential for a sharp improvement once recovery really kicks in. Somewhat similar to Molins above, they produce machinery and tooling - but Hampson are focused on the aerospace and defence sectors; and we all know what's currently happening to those. Their real profit figures are actually deeply negative, but this is largely due to the impairment of goodwill - and as I strip it out from the value of their book, it hardly seems fair to include it when discussing their profit. The balance sheet looks neither flimsy nor solid. While the recent management statement could best be described as 'weak', this is one of the factors pushing it back down into value territory - and if you see any sort of resumption of pre-crisis levels in the sector, Hampson present a huge opportunity at the multiples they're trading at.
Mouchel (LON:MCHL): Mouchel are a 'consulting and business services' group - with divisions in rail, water, highways and management consulting, to name a few. That little list brings one phrase to mind - 'public sector' - and that's obviously something I'd have to look into given the cuts forecast for the next few years. It may well be that they're indispensable - but a voice in my head tells me that nothing is indispensable in a tight fiscal environment! Still, as before, brokers are forecasting good profits even allowing for the cuts - and as they're realigning their cost base, that figure may improve going forward even given no noticeable revenue increases. A particularly big point of interest is the takeover speculation earlier this year - with an offer valuing Mouchel at roughly 140p a share (current price: 50p). After consultation, the 'largest shareholders' rejected this offer, which seemed to me to be more than generous. Perhaps they know something I don't!
Record (LON:REC): Record Plc are a financial services group operating 3 different currency-related products - the first is what I would term a vanilla hedge, the second they call a 'dynamic' hedge and the third straight up speculation. The dynamic hedge, if you're wondering:
"... Record seeks to eliminate the impact of currency movements on elements of clients' investment portfolios that are denominated in foreign currencies when these movements are expected to result in an economic loss to the client, but not to do so when they are expected to result in an economic gain..."
Effectively more speculation, then! After a sharp fall in revenues into the financial crisis, the company seems to have now stabilised, with assets under management staying flat for the last few quarters. One obvious benefit of selling 'intangible' products such as financial services is the low cost base off which they can do it - they earn margins of around 50%. Their balance sheet also looks solid, with a large amount of cash on hand - perhaps explaining the sky-high dividend yield, as they may be returning this to shareholders. I like the look of the numbers, but financial services firms always leave me a little wary - they take more time than usual for me to understand, as exposures to various counterparties and financial instruments can be potentially extremely important.
PV Crystalox (LON:PVCS): PV Crystalox Solar has been on the value investing scene for a while now - I remember posts from 4-5 months ago questioning its valuation. Since then, it's bombed - and it now appears to be a fabled net-net; whereby the market cap of the business is less than simply the value of its net current assets ( current assets - total liabilities). Put simply, if the company sold all its current assets and paid off all its liabilities, it could give shareholders more than the current share price - and that's before even looking at their property plant etc. There's several complicating factors, but it does indicate that the stock is very cheap. They produce wafers - components in solar cells - and appear to be trading on small multiples of earnings, too, but I have more than a few misgivings about the business. 'Current pricing pressure', they note, means they'll probably dip into an operating loss in the second half; and I wonder whether this isn't simply a transitory stage, but is rather indicative of the ongoing commoditisation of the sector. They operate factories in England, Germany and Japan - presumably because the component they're producing was previously quite complex and specialist. If this has changed, as I suspect it has, the market could have been flung open to cheaper competitors, and their time could be up.
Sportech (LON:SPO): Sportech operate in a sector that's been downright shaky since the start of the recession, too - gambling. Even against a tough backdrop, though, they've reported good earnings figures - once you strip out the exceptionals and amortisation of intangibles. Again, given my treatment of intangibles on the balance sheet it's hypocritical for me to dislike them taking out amortisation from the income statement, so that's fine by me - but on the other front, exceptionals seem to be more the norm! They've reported considerable 'exceptional costs' in several of the last 4 years, which may be perfectly reasonable, or may be indicative of other worrying trends; more research is certainly needed there. Regardless, a P/E of 7 in the current environment does seem very cheap, and may mean the business is positioned well for when the general economy picks up again. The company is based on a tiny pool of tangible assets, which is unsurprising but makes it slightly less safe that it otherwise might be. Be it Sportech or otherwise, gambling is certainly a sector I'm interested with at the valuations it's trading at.
British Polythene Industries (LON:BPI): BPI have a rather impressive track record - they're the largest producer of polythene film in Europe, having earned revenues in excess of £300m for the last 10 years. Over that time they've consistently reported decent operating profits and paid a good dividend, though this was cut in the crisis. For that track record, the company looks cheap - at a P/E of 8, and a forecast P/E of 6.7. One of the reasons, I suspect, is the sizable pension deficit, which always tend to swing around and deter investors. There's also an ongoing EU probe into the business - though the scope of the potential punishment and the likelihood of that is far beyond my current level of knowledge - that's an area I'd have to go into should I delve a little deeper. Apart from the pension scheme, the balance sheet doesn't look too bad - borrowings are relatively low and are fixed on a sizable amount of property. One thing I find interesting with businesses with a history of performance is looking back at the share price - and BPI peaked at almost 700p in 2006. While that's significant upside, it doesn't look like BPI ever traded at particularly high multiples of their earnings - and so it seems they offer a lower risk and correspondingly lower reward than some of the others listed here.
Eros (LON:EROS): And for those of you disappointed with the unexciting list above, I finish on a slightly more exotic note - Eros, the producer/importer/distributor of Bollywood films. While considerably larger than some of my other picks, they do share two important factors- they trade on a very low multiple of last year's earnings and appear to have a good balance sheet. While PTBV is obviously negative, a huge amount of equity is in their substantial film library - and unlike other forms of intangibles, (for example goodwill) this is a type that can probably fairly readily be valued and sold. Indeed, straight price to book value is closer to 1. The business's cash flow sheet is a mine of information - the operating line lists operating cash flow of something like £70m - a huge figure, though even more than this is plowed back into the investing line, with the purchase of film rights. How long these assets will continue to earn them money and whether the expansion of the film catalogue will really boost investor returns are questions I'm curious about - but there's certainly a lot of potential here if the figures fall into place. If the growth potential of their market is as big as they say it is, Eros could have a bright future indeed - but being so far out of my comfort zone, the potential for error is higher.
So there we have it - a slice into my mind as I size up the current list of potential bargains. If you have any burning desire to see me take a look at one of these, or indeed any others (suggestions are welcome!) - e-mail me - and if I've made any glaring errors or omissions about the above businesses, comments from those with more knowledge about these businesses than me always goes down well.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
No comments yet
No one has commented here yet! Why not be the first one?