SVW: A diversified industrial

Seven group (ASX:SVW) is controlled by billionaire Kerry Stokes with his son Ryan Stokes as the CEO. The Stokes family own 57% of the shares on issue. It is classified as an industrial stock. There are two commonly used definitions of an industrial stock. The broad definition is that all stocks that are not resource stocks are termed industrial stocks. The narrow definition is where stocks are classified into sectors. In Stockopedia there are 10 main sectors, one of which is Industrials. There are 23 stocks in the S&P/ASX 200 Industrials index, which is based on the GICS classification system, and Seven is the 6th largest.
Seven Group Holdings (SGH) is a diversified operating and investment group. It owns businesses and investments in industrial services, media and energy. Some of these businesses are owned outright. In others they own a controlling interest and a non-controlling interest in some others.
It is important not to confuse Seven group (ASX:SVW) with Seven West Media (ASX:SWM). Seven West Media is a separate listed business that owns media assets including the Seven television network and a newspaper and publishing company. However SGH also holds a 40% stake in SWM.
In FY23 SGH generated total revenue of $9,627 million. The major contributors to the revenue result were:
Westrac 51%
Coates 12%
Boral 36%
Westrac is wholly owned by SGH. They are the sole authorised dealers of Caterpillar equipment in WA, NSW and ACT. Caterpillar make large mining trucks and other mining equipment.
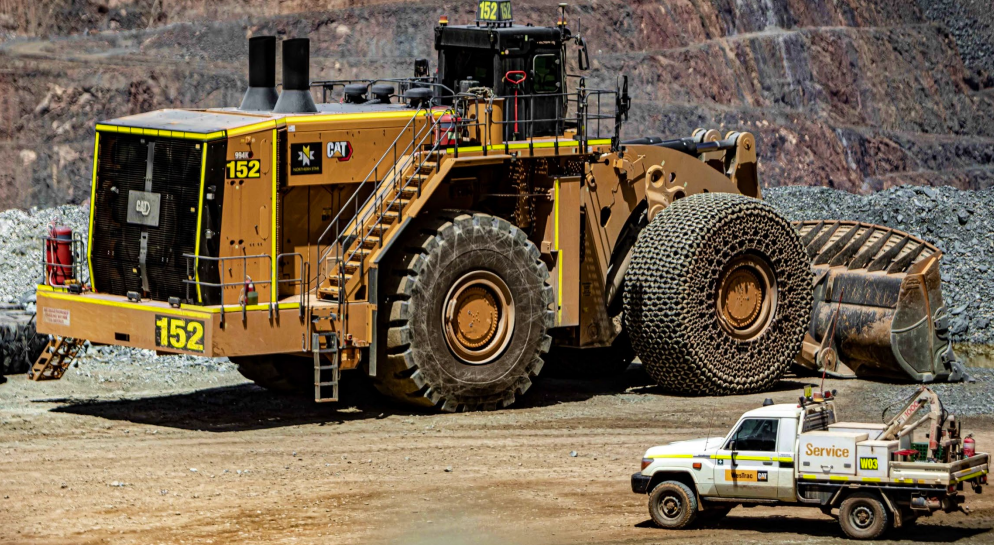
Source: Seven Group Holdings, FY23 Results presentation, 17/8/23
SGH also owns the whole of the Coates equipment hire business. Coates hire out equipment used for construction and engineering projects and are a top tier equipment hire business with approximately 27% market share.
Boral (ASX:BLD) is an independently listed company on the ASX, however SGH owns 72% of the shares on issue, giving them a controlling stake. Boral supplies building materials, specifically cement, concrete and asphalt.
These three businesses are the primary contributors to SGH’s top line revenue, but not the only contributors to its bottom line profits. This is due to the fact that they control these businesses and therefore they consolidate all of the revenue onto their Income Statement. For example, with Boral, despite only owning 73% of the business as at 30 June, they brought 100% of Boral’s revenue into their income statement, as is required by accounting standards when consolidating an entity’s subsidiaries. An adjustment is made to the profit line to account for minority interests.
This differs to the treatment of the businesses where they do not have a controlling stake. For example, the 40% investment in SWM is not consolidated as they do not exercise control over that business. Therefore it is accounted for on the income statement using the equity accounting method. Put simply, this means 40% of SWM’s profit is added to SVW’s bottom line, but there is no inclusion at the revenue line.
In addition to the Industrial services and media businesses, they also operate in the energy segment, with a focus on gas and LPG. They own some assets directly, and they also have a 30% interest in ASX listed Beach Energy (ASX:BPT). Ryan Stokes is interim chairman of Beach’s board of directors.
The chart below illustrates the main contributors to Seven’s business.

Source: Seven Group Holdings, FY23 Results presentation, 17/8/23
As described above, not all of the business units contribute to the revenue line, so to get a better understanding of the contribution of each business unit, it is helpful to review their contribution to earnings. The chart below shows how much each business unit contributes to EBIT as well as the growth or decline in earnings over the last year. At the group level, EBIT grew by 20% in FY23.

Source: Seven Group Holdings, FY23 Results presentation, 17/8/23
Industrial services businesses are growing strongly. This was facilitated by elevated activity across mining production, infrastructure and construction which enabled margin expansion.
Westrac is the biggest contributor to revenue and earnings and saw strong EBIT growth of 18%. Westrac sales were up 24%, broken down into two components, machine sales and product support. Machine sales were up 25% and support up 23%. Further growth is expected in FY24, including growth coming from the mining of battery metals. EBIT in the industrial services businesses is forecast to grow about 10%.
Earnings from the media business declined in FY23. In addition, they wrote down the value of their investment in SWM by $76m this year, on top of the $83m writedown last year. They are expecting TV earnings to stabilise in the coming year. The share price of SWM fell sharply in August following the release of their results.
At the group level SVW are expecting EBIT growth in the high single digits. In August they sold 1% of their holding in Boral to capitalise on the strong share price appreciation.
Dividends have been maintained at 46c for the last three years, fully franked. The historical yield is 1.7%. The forecast DPS for FY24 of 50c would provide a yield of 1.9%.
In summary, these strong results have resulted in a high StockRank of 89, bolstered by the Quality score of 94. The Quality score has been assisted by improving cash generation which has been used to pay down debts.

Looking at the Value score, it is fair at 59. It is supported by a relatively low PE ratio, but hampered by a high price to tangible book ratio of 8. They carry a large amount of intangible assets on the balance sheet, including over $1 billion in goodwill from the acquisition of Coates in 2017.
The Momentum score is good, but has declined a bit recently following the price retracting 14% since its recent high. SVW is down more than double the market over the last month, however over 3, 6 and 12 months it has outperformed the market strongly, so this may just be a correction.
Any decision to invest in SVW needs to be made with the understanding that the business is controlled by the Stokes family and you are therefore aligning yourself with them. That said, they have a pretty strong track record of generating wealth. The prospects for the industrial services side of the business look strong, although that industry always carries a bit more risk. Energy markets can be volatile,and media is still an industry in transition. There is a lot to like about the business, provided you are cognisant of the risks.
Important Information: Stockopedia Ltd ABN 39 757 874 670 UK business registration number 0637267 (“Stockopedia”) is an Authorised Representative of Daylight Financial Group Pty Ltd ABN 77 633 984 773 (“DFGPL”) which is the holder of an Australian Financial Services Licence (AFS Licence No. 521404).
Information in this commentary is current as at date prepared unless otherwise stated. However, please bear in mind that investments can go up or down in value, and that past performance is not a reliable indicator of future performance. For more Important Information please refer to the Disclaimer section of this website.
This communication may contain general financial product advice. It has been prepared without taking into account your personal circumstances, and you should therefore consider its appropriateness in light of your objectives, financial circumstances and needs before acting on it.
If our advice relates to the acquisition or possible acquisition of a particular financial product, you should obtain a copy of and consider the Product Disclosure Statement (PDS) before making any decision.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
2 comments
Generational skin in the game at Seven group (ASX:SVW) is one of Anthony Deden's must-haves. Also a highly sort after condition of entry for Buffy & Mungo.
It generally creates good incentive alignment with other shareholders, provided it is not run as a personal fiefdom.