Taking advantage of current market conditions: stocks due a bounce

Investors will have noticed how strong many UK stocks have been over the last couple of months. Take Volex (LON:VLX) , for example. The share price here has almost doubled from April lows:

The reasons are written in the DSMRs over the past year. The market experienced indigestion as Volex attempted to acquire TT Electronics in November 2024 in a deal that would involve part payment in Volex equity. Despite this being rebuffed, the market never recovered. Then, in April this year, the market worried that Volex would be severely impacted by trade tariffs. When the risk of the worst tariff levels subsided and Volex clarified that they would successfully pass on any tariff-related costs, the shares made a slow recovery. Last week's beat of expectations caused a significant rise that completed the share price recovery to levels before all this began.
The most interesting part, at least for me, is that this recovery goes against the long-term trend in fundamentals, as measured by future year broker EPS forecasts:
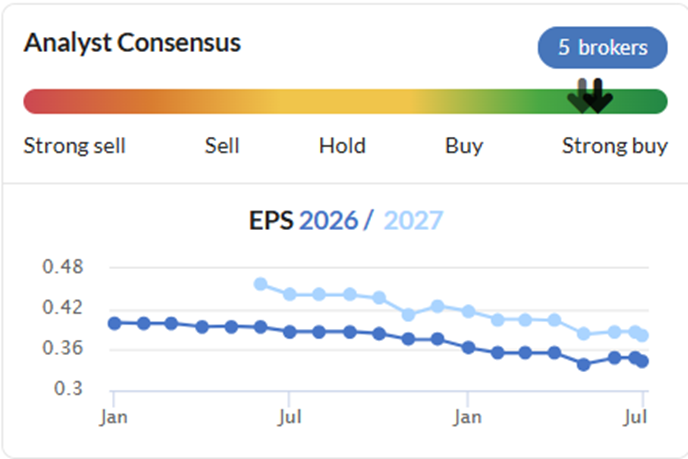
The individual share price movements here may be logical based on the news. However, collectively, they mainly represent the shifting sentiment toward the stock, rather than any fundamental change in future expectations. The stock sold off until it was simply too cheap, and the improvement in sentiment has generated an almost 100% return to shareholders who bought when the tariff news looked bleakest.
Subscribers will undoubtedly have their own stories to share about this momentous period. If such swings can occur in a £700m market cap company, such as Volex, some of the moves in smaller companies will have been even more substantial. Many stocks have followed a similar pattern of recovery as investors became more enthusiastic about the prospects for the UK following the US trade deal. However, such moves have been far from universal. There have been a few reasons for this:
1. Profit warnings
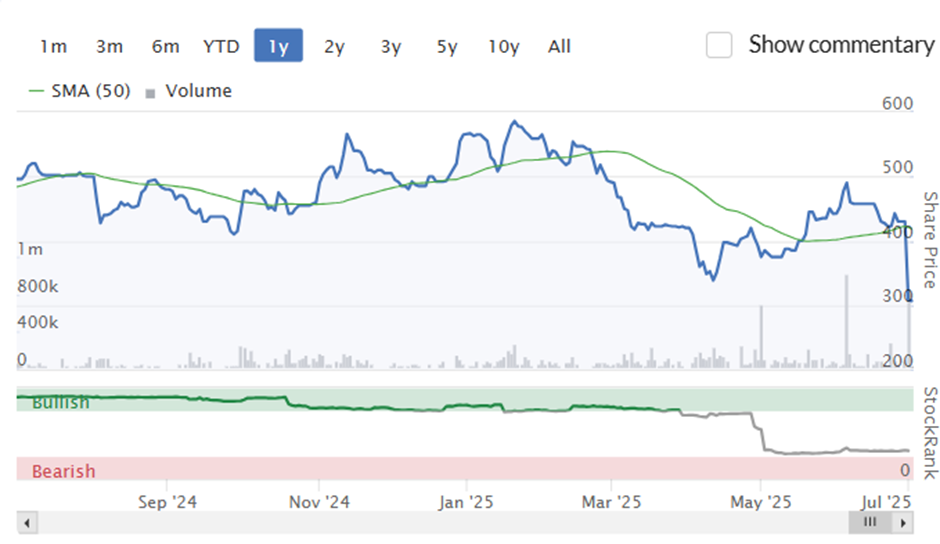
Let's face it, conditions are still tough out there for a number of businesses. Any UK company with retail, hospitality or even industrial exposure is likely to have struggled recently. It's not just limited to the near term, either. This week, MPAC (LON:MPAC) issued a profits warning due to a weak Q2 order book. This meant that full-year revenue forecasts were cut by 24%, with EPS reduced by a similar amount. However, the impact is not expected to be a one-off, and brokers have reduced 2026 and 2027 estimates by even greater amounts. In such a situation, it doesn't seem unreasonable to me that the shares fell around 30% on the news. Although the share price experienced a market-led bounce from mid-April to the start of June, it now trades below its April level:
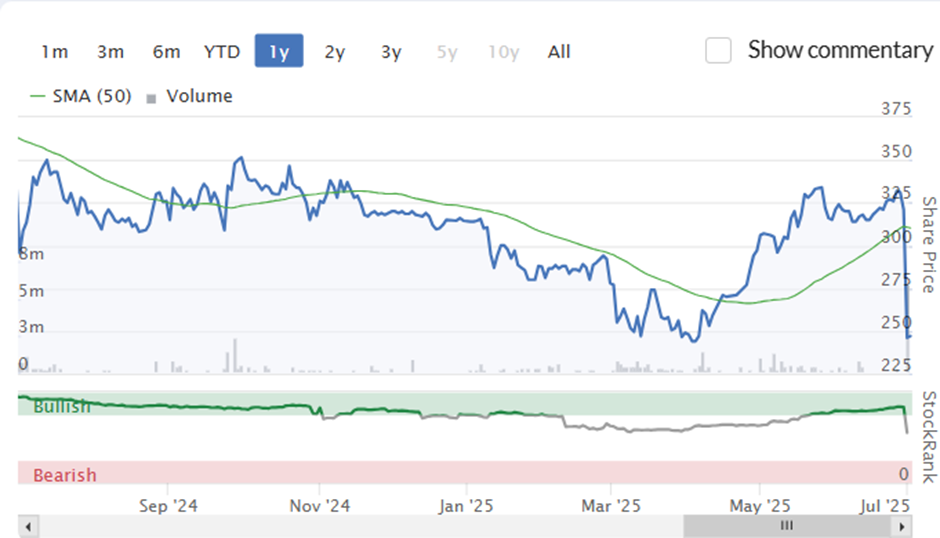
Also warning this week was Kitwave (LON:KITW) . Although the downgrades are less severe here, it looks like investors were unduly optimistic in bidding the shares up following April lows:
The Stockopedia research into profit warnings shows that it takes much longer for companies to recover from shocks to market expectations than the slow decline of multiple but minor broker adjustments we see at Volex
2. Illiquidity
Global funds network, Calastone, tracks UK fund flows, and apart from one anomalous month in 2024, these are consistently negative to the end of May. This means that institutions continue to be net sellers of UK equities.
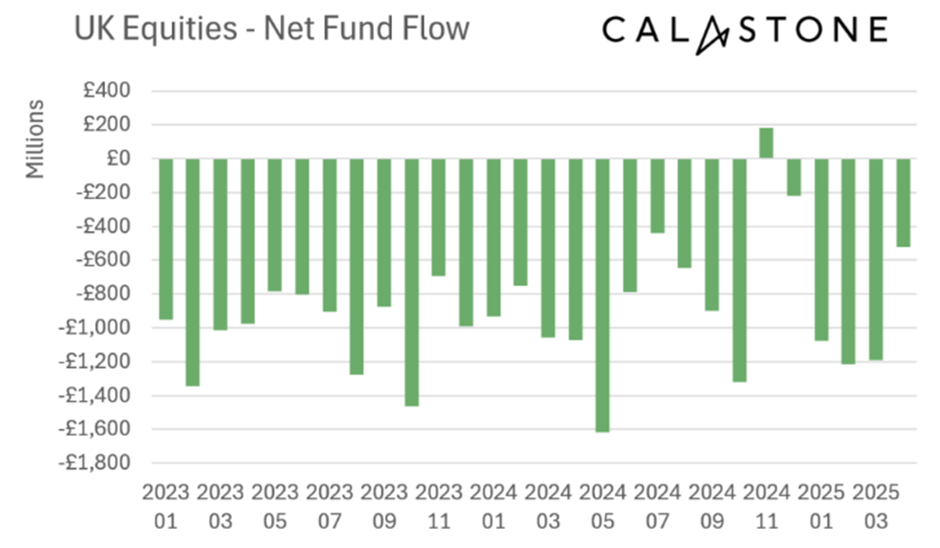
Where institutions aren't selling, very few are buying. This means that UK markets are surprisingly illiquid. Individual investors buying smaller amounts can move the markets.
3. A high degree of uncertainty
The investment outlook is still highly uncertain in the UK. Take retail, for example. Some companies have successfully mitigated the rise in National Insurance and other costs. Value retailers such as Card Factory (LON:CARD) or Works co uk (LON:WRKS) appear to have largely mitigated this. While others in the same space, such as Shoe Zone (LON:SHOE), appear to have suffered. This doesn't appear to be wholly related to management quality, suggesting that there is a large degree of randomness in which companies will do well and which will struggle.
What does this mean for investors?
Given the factors above, and that current UK markets things have been so cheap for so long, many investors are looking for confirmation that things aren't going to get worse. They often look for that reassurance from other investors and, in particular, a rising share price. The belief is that others have identified a company that will surpass expectations or is attracting takeover interest. Sometimes, there may be truth in these assertions, but often the initial move is just noise. The outcome is that in current markets, once a stock starts to move, investors jump on that and take the stock much higher and more quickly than they would in more normal market conditions. Stocks that show no upward movement in their share price remain becalmed, floating about, waiting for fairer winds. This makes which stocks soar and which remain unloved almost completely random (or at least subject to whims like newspaper tips).
It is tempting to think that institutional investors are more rational and less susceptible to this type of behaviour. However, the incentive structures around jobs and bonuses in an industry that has seen significant reductions in headcount may make this even more likely. As John Maynard Keynes once said, “Worldly wisdom teaches that it is better for reputation to fail conventionally than to succeed unconventionally.” In a world of fund redemptions, the temptation to wait for initial moves and jump on the bandwagon, so that fund investors see the fund manager holding “winners”, may be too much for most to resist.
Finding opportunities in the current markets
One way that investors may take advantage of these factors affecting the current UK stock market is to look for turnaround stocks, those that have a high VM-Rank. I wrote about that strategy here.
However, my favourite way is to return to an old friend: The 52-week low screen. The theory is that, in a strongly recovering UK market, if investors can find stocks that have been overlooked for no good reason, they may be getting a bargain which is poised to soar when other investors notice this anomaly.
It's a strange market phenomenon that buying stocks at 52-week highs or at 52-week lows are both winning strategies. This works for behavioural reasons. Investors often take profits when stocks make new highs. This means that stocks performing well may be slow to react to positive news and represent undervaluation. For stocks making 52-week lows, it is more likely to be a buyers' strike. No one likes to be the chump who buys just before the profits warning, so everyone fears that something is wrong, or that the price will keep going down. However, in a 2009 paper, Steven Huddart, Mark Lang, and Michelle Yetman found that buying a basket of stocks that hit 52-week lows outperformed the general market. It appears that, on average, investors overestimate the likelihood of something being wrong with companies that have weakly performing share prices. The authors also found that the excess returns were focused on the smaller stocks, suggesting that these may be more susceptible to this bias.
Screen Criteria
The good news is that it is relatively easy to screen for such ideas. Here are the criteria I used last time I wrote about this type of screen:
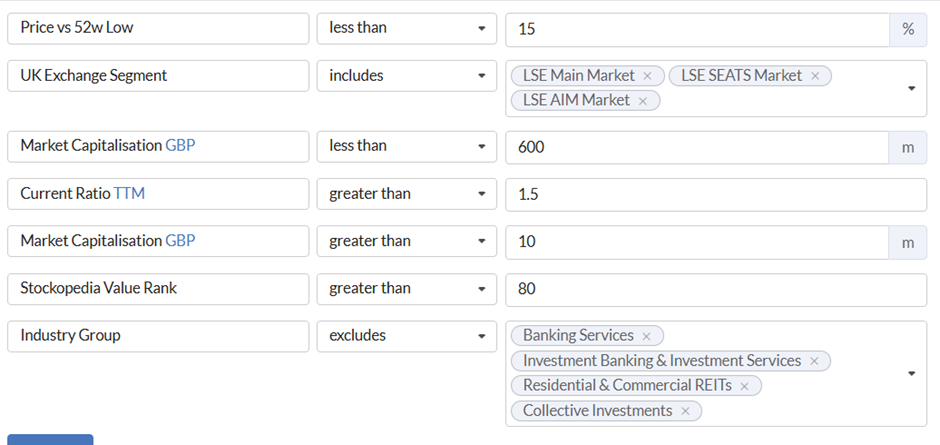
As well as simply being within 15% of 52-week lows, I added criteria to ensure that we were looking at smaller stocks, that they were not at high risk of near-term financial collapse (current ratio > 1.5), and they were relatively cheap (Value Rank > 80).
The problem is that this screen currently only generates 10 results:
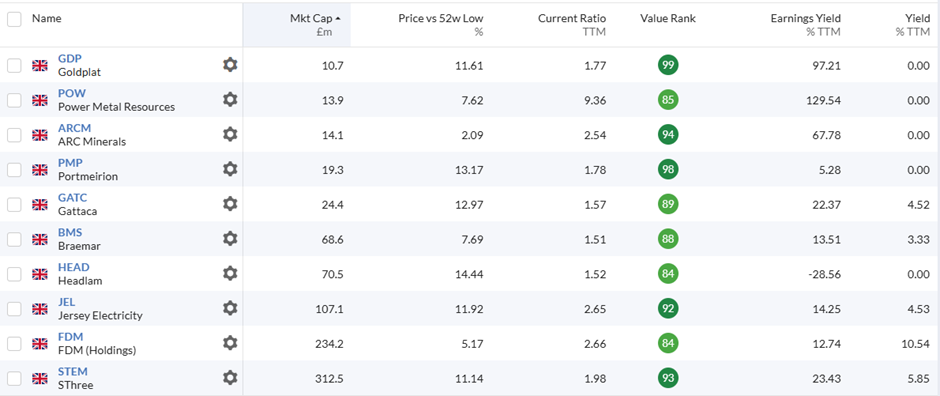
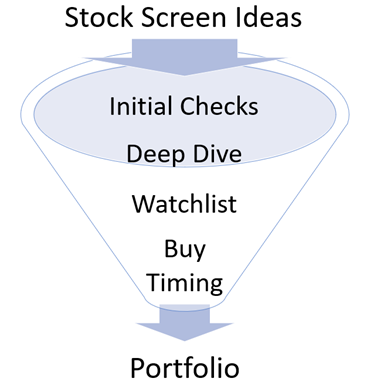
These may be some great ideas. Several of these I hold or are on my watchlist. However, it is likely that we may be missing some ideas by being too strict in the current markets. The reason is that there may still be cheap stocks that have sold off with the wider market in April, have recovered modestly, but still remain cheap by historical measures. When generating ideas using the Stockopedia Stock Screener, I like to view these as the input into my investing funnel, which narrows down to the few investments that may make it into my portfolio:
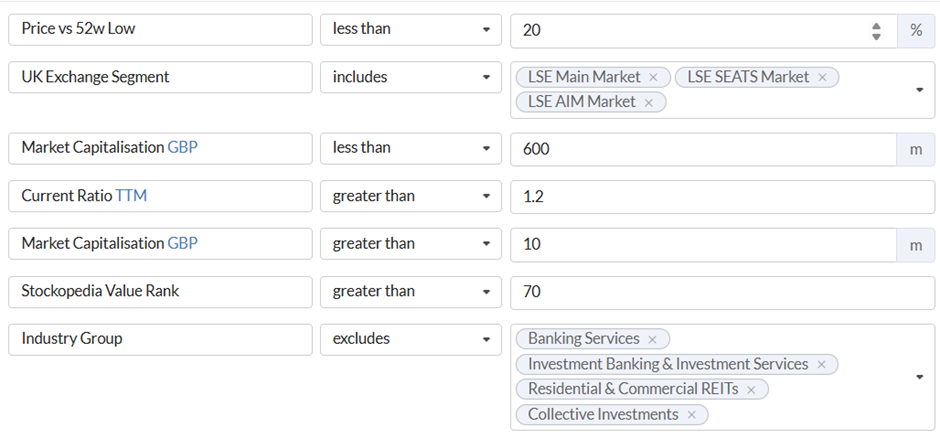
With this in mind, when I find a screen has very few hits, I weaken some of the criteria slightly. In this case, the proximity to the 52-week low, current ratio and Value Rank may be relaxed slightly:
Screen Results
This gives a more reasonable 25 results to go into the top of my funnel:
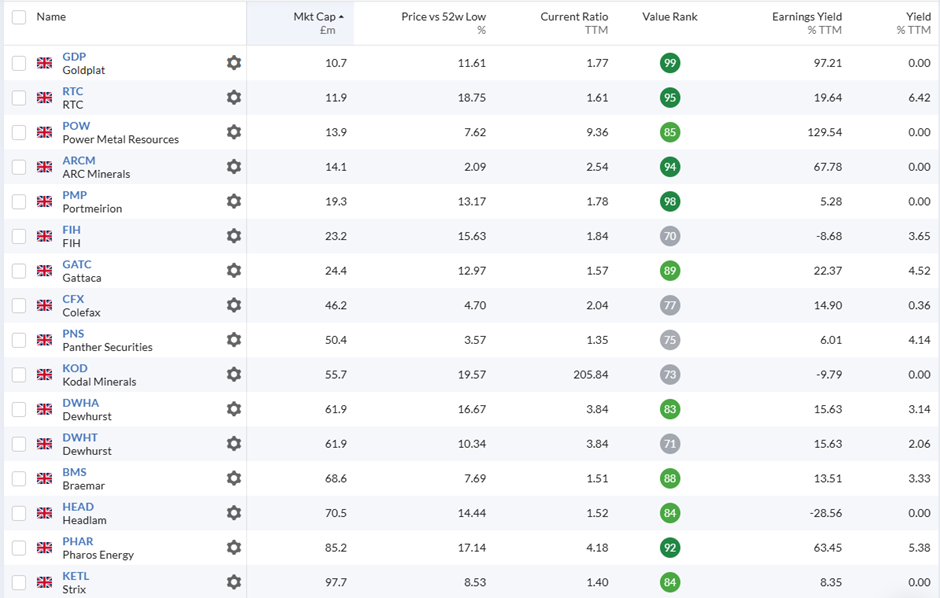
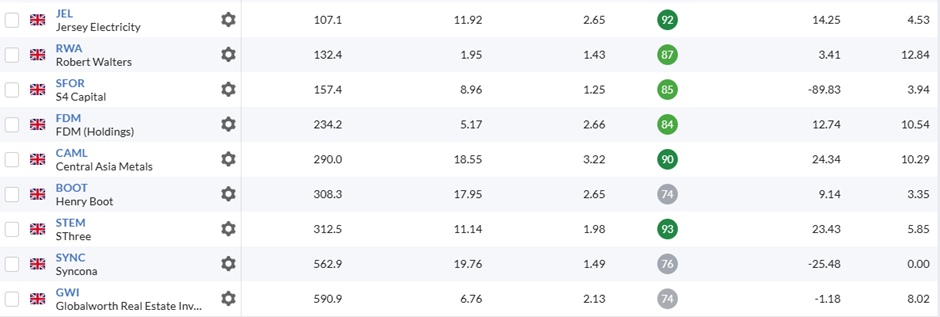
It seems likely that at least some of these are overlooked bargains ready to bounce, rather than stocks that are cheap for a reason.
A corollary
The final thing to note about the current markets is that investors may want to be quicker to take profits than usual. Especially if a large rise isn't backed up by positive moves in fundamentals. As MPAC (LON:MPAC) and Kitwave (LON:KITW) show, a rising share price does not preclude a profits warning. It is a hard balance to get right. After all, UK investors have become so accustomed to weak valuation metrics that even a modest multiple may seem excessive, and investors may be selling just as a multi-year rally gets going. As always, selling strategy is a difficult discipline to get right. However, investors don’t need to reduce their equity exposure overall. With the help of screens like the one above, they can redeploy that capital into cheap shares that haven’t bounced and where a short-term reversal would be a good thing rather than a bad one.
[Disclosure: Mark owns shares in Card Factory (LON:CARD) Colefax (LON:CFX) Gattaca (LON:GATC) Goldplat (LON:GDP) ]
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

10 comments
this is really helpful. Thx.
Thanks Mark. Very interesting.
I hold Colefax (LON:CFX) yet I can understand the stock trading at a 12 month low. Management give very few updates (outside half-year/ full-year) - so the market has had no update on trading since 22 Jan.
Headwinds are the weak USD (with most revenues in USD but a fair chunk of costs in EUR/GBP), tariffs, and poor read across from Sanderson Design (LON:SDG) .
Maybe you are right that this provides the opportunity as it takes a brave (or it that reckless) investor to buy on the absence of an update.
On the upside, I would not be surprised if there was another buyback in the autumn, given the low take-up on the autumn 2024 buy-back. (Maybe they will go back to a traditional tender).
Hi Wimbledonsprinter,
Colefax (LON:CFX) is another one where I have bought a small position recently so will be proven either reckless or brave in due course! Partly this was on the strength of the Sanderson Design (LON:SDG) update and reaction there., but also because Colefax have impressed with their execution, and they have a long-term mindset which I like (tenders and buybacks tend to be around the current price, mopping up keen sellers, rather than chasing the price.) The downside of this is that we are unlikley to see them focusing on improving the short-term share price with their buybacks (unlike almost every other struggling company!) and, of course, the illiquidity. These mean that this is unlikly to ever be a significant position for me, even though it looks cheap.
Cheers,
Mark
Another excellent article Mark. I was a buyer of Volex (LON:VLX) and Kitwave (LON:KITW) in 2024 only to lose my nerve as the market drifted down later in the year. Both were bought (in my opinion) on excellent fundamentals. However, I allowed 'noise' and 'emotion' to doubt my analysis and sell at a loss. The % losses differed greatly because I sold Kitwave (LON:KITW) late 2024 as the 20 week MA slipped below the 50 week MA for a minor loss. My 'belief' in the Volex (LON:VLX) fundamentals made me hang on until 'fear' made me sell out and the bottom. Yesterdays article about the NAPS portfolio reinforced my learning to have 'emotionless' sell triggers. The 12 month rule in the NAPS case and using MA's in my case. The beauty of Stockopedia is the ability to use historic data to back test and reflect on individual investment styles.
Sorry meant 200 wk MA not 50wk MA.
Hi Kev,
Yes, knowing when to sell when something looks like going wrong is one of the trickiest things to do in investing and I doubt any of us get it right much of the time. However, you are right, it is one of the benfits of rules-based investing. As long as the rules make sense, it takes the emotion out of it and, on average, we mae better decisions. And that is whta Stockopedia is all about.
Cheers,
Mark
Hi Mark - great article as always.
Do you know where Calastone usually publish that chart you've reproduced? It would be useful to bookmark.
Thanks Tortoise investor,
Here's the link: https://www.calastone.com/cate...
It's a free sign up.
HTH,
Mark
Thank you Mark. We've recently bought into Card Factory, are long term underwater holders in Braemar and took profits on Portmeirion Wickes and Volex of which only the first looks sensible! For what it's worth we also recently bought or added to RWS GSF Trifast Capital Mincon Sanderson Design and Ultimate Products.
Hi JASVFS,
I've also only recently bought a small position in Card Factory (LON:CARD) - it doesn't seem to have bounced with the rest of the market and they have been very good at mitigating cost rises so far. I would sure they were going to miss last year after a weak H1, and then they proved me wrong and hit their forecasts, yet the price never recovered. The risk is that they H1 looks weak again and the market takes further fright. However, managmemnt hav ebuid confidence that they are able to forecast well. I guess we'll see what comes this year.
Mark