Taylor Maritime - a solid investment?

On 27 May 2021 Taylor Maritime Investments (LON:TMIP) (previously a privately owned Hong Kong-based company) raised $253.7m in an oversubscribed issuing to list on the London Stock Exchange. Proceeds were to be used to buy 23 secondhand handysize and supramax bulk carriers, with an average age of 11 years.
"Maritime Investments Limited is an investment company with a diversified fleet in the geared Handysize and Supramax segments of the global shipping sector. Geared vessels have their own loading equipment and, given their flexibility, versatility and port accessibility, we consider them to be some of the most attractive in the market. For our investors, we are targeting stable cashflow generation with quarterly dividend payments representing an annual yield of 7% on the IPO price of $1.00, with a targeted NAV return of 10-12% per annum."
On the first day of dealing Taylor Maritime Investments (LON:TMIP) reported:
“The Company is pleased to announce that the Initial Seed Asset Acquisition Agreements will complete today. These agreements relate to 17 vessels being acquired for an aggregate consideration of US$182.8 million, part-financed by the issue of 93,678,485 Ordinary Shares. The Remaining Seed Asset Acquisition Agreements comprising six vessels are currently expected to complete between July 2021 and February 2022. The consideration of US$81.3 million will be part-financed by the issue of a further approximately 13.3 million Ordinary Shares which will be admitted to listing and trading upon completion.”
On 16 June Taylor Maritime Investments (LON:TMIP) reported the ”acquisition of two geared Handysize bulk vessels completes deployment of IPO proceeds”
The company gave a trading update for the initial period to 30 June 2021 on July 2021:
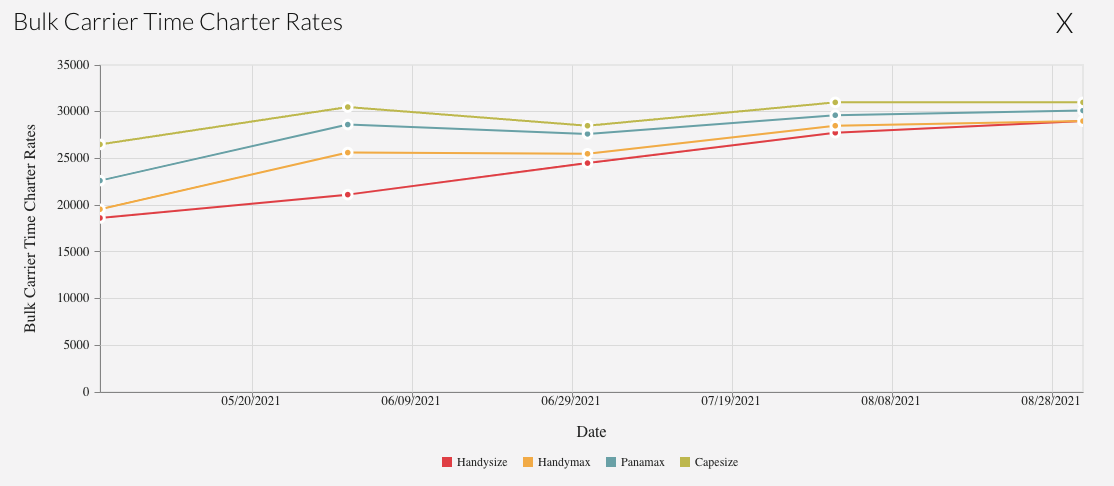
- Net time charter rates up over 30% since 7 May 2021, the date of the Company's IPO prospectus (the "Prospectus")
- Portfolio valuation (25 vessels including those delivered and committed) up US$33.3 million (10.5%) as at 30 June 2021 over the aggregate vessel purchase price
- Delivered fleet (17 vessels as at 30 June 2021) yielding annualised unlevered gross cash yields of more than 20%
- Implied dividend cover on the delivered fleet of c.2.7 times which is expected to rise materially once the remaining eight vessels are delivered (two of which have since been delivered)
- Market rates strengthening faster than ship prices giving rise to attractive investment opportunities
On 19 July the company successfully conducted a further placing of new ordinary shares that raised gross proceeds of US$75 million. These proceeds were to be “immediately used to acquire up to six Handysize vessels.”
A US hedge fund (SteelMill Master Fund LP, managed by Delaware, US-based PointState Capital) and Germany’s Christian Oldendorff (owns the Reederei Nord Group shipping company) are two of the key stakeholders
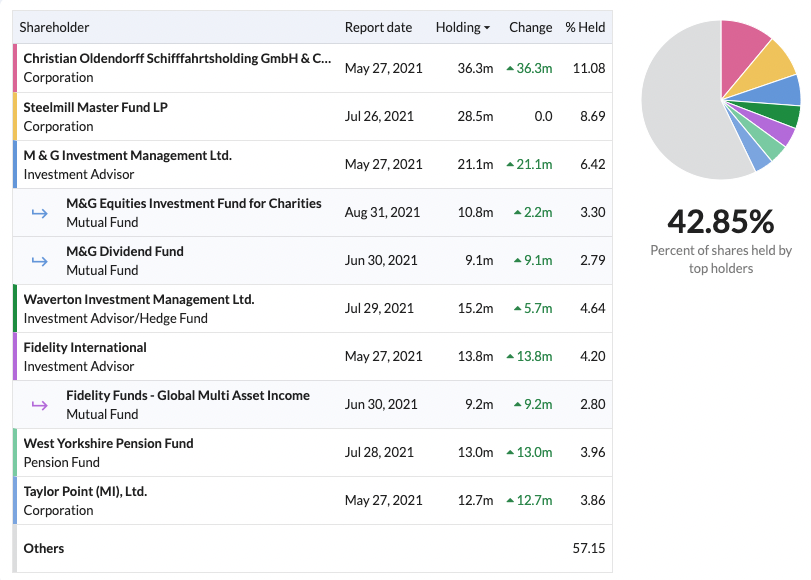
With rates for supramax and handysize bulk carriers on the increase, and bulkers and containers being in high demand (perhaps due to rising commodities prices and increased grain shipments to Asia), could Taylor Maritime Investments (LON:TMIP) be in the right place at the right time?
Note: Taylor Maritime is listed under two tickers, TMIP, and TMI, one is in sterling, and the other is in dollars. (I have taken a small initial position)
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
20 comments
Director/PDMR Shareholding
The Company announces that Edward Buttery, Chief Executive Director, has purchased 200,000 ordinary shares in the capital of the Company ("Ordinary Shares @ 0.98USD
Good upward momentum
Another director buy reported today:
"The Company announces that Christopher Buttery, Non-Executive Director, has purchased 53,278 ordinary shares in the capital of the Company"
SP motoring up nicely, up 14% since I posted this on Jan 26 2004: "It would seem Taylor Maritime Investments (LON:TMIP) are doing well and on course to do better."
I continue to hold.
The recent 100k purchase by Buttery has certainly helped give Taylor Maritime Investments (LON:TMIP) SP a further upward momentum.
Taylor Maritime aims to create value for investors by "focusing on an area of the market which is inherently robust. It is centred around continuing, steady demand for necessity goods, leveraging TMI’s proven track record and deep market knowledge to secure attractively priced vessel acquisitions, and competitive charter rates with high quality charterers."
Another positive note is Taylor Maritome's carefully assembled fleet consists of "high quality predominantly Japanese built second-hand ships which, under experienced management, can operate relatively efficiently compared to peers."
Kepler Research comments: "One of the attractions of TMI is it offers the opportunity to invest in the shipping industry alongside an established team with strong connections. On the other hand, as an internally managed company, there is not the independence of the board that is common across the investment trust sector. TMI was established by Ed Buttery, who has 20 years’ experience in the industry; his father, Christopher Buttery, who established Pacific Basin in 1987, sits on the board as a non-executive director. Ed started his career at Pacific Basin, where he was a chartering manager before serving as deputy COO of Asia Maritime Pacific and then working at Nordea Bank, where he lent senior debt to shipping companies. He set up shipping management company Taylor Maritime in 2014, from which 17 of TMI’s 23 seed assets were already under commercial management. Taylor Maritime also managed other ships from the seed portfolio and those bought with the proceeds of the July 2021 placing. It was appointed by TMI to run its portfolio after TMI launched and has now been bought by Grindrod, bringing it in-house at TMI.
Ed is the key manager of the portfolio, leading the executive team, and serves as chief executive officer on the board. The board contains independent non-execs, including the chairman, while Christopher Buttery also serves as a non-executive director. Ed is joined on the executive team by Alexander Slee, deputy CEO, who has 15 years of experience in the industry, including Pacific Basin and then as deputy CEO of Taylor Maritime. Camilla Pierrepont, Ed’s sister, is the chief strategy officer and head of investor relations. She has experience in the LPG carrier company Epic Gas as well as in the venture capital industry. Chief financial officer Yam Lay Tan also worked for Epic Gas and joined Taylor Maritime in 2019. Carl Ackerley, with more than 30 years’ dry bulk industry experience, is the most recent addition to the executive team, having joined from Grindrod following the acquisition and currently serves as joint chief operating officer across both companies.
The directors and management team own shares in TMI, and benefit from a long-term incentive plan which sees them rewarded with equity based on three-year NAV performance. This provides alignment of interests with other shareholders, although arguably targets linked to share price would bring more alignment, as performance awards can be received based on NAV performance even while the shares sit on a wide discount."
With signs of emerging positivity in dry bulk handysize/ultramax shipping, I think there is decent upside at the current share price.
7 March 2024: Director/PDMR Shareholding
"The Company announces that Christopher Buttery, Non-Executive Director, has purchased 100,000 ordinary shares in the capital of the Company ("Ordinary Shares")."
Very encouraging to see Buttery executing a healthy share purchase at £0.72
(I continue to hold).
Encouraging to see Director buy of 115,000 shares. Tentative signs Taylor Maritime Investments (LON:TMIP) share price on an upward trend.
Taylor Maritime Investments (LON:TMI) making good progress:
"The shipping industry has passed through a rough patch over the summer, but TMI continues to support an attractive dividend while Ed Buttery, CEO of TMI, has fashioned a fleet that looks to be in a strong position to deliver value over the long run. The deleveraging process has proceeded at great pace, and it is encouraging to see the market provide liquidity close to carrying value, even in a falling market. We also think it is promising to see dividends continuing to be paid at the current level despite a fall in cash generation over the summer due to weak charter rates. We understand that at the time of writing [16 Jan 2024] cash generated by the combined fleet on an ongoing basis has returned to almost the level at which it covers interest costs and dividend" Kepler Trust Intelligence
1 March 2024
TR-1 notification reporting Christian Burchard Max Oldendorff have increased their holding from 10.635932% to 15.308147%
Some highlights from the latest Quarterly Factsheet:
Commenting on the trading update Edward Buttery, Chief Executive Officer, said:
"We are harnessing the operatingleverage of the Grindrod transaction which has delivered a younger, more efficient combined fleet, an increased carrying capacity and expected synergies and cost efficiencies to drive earnings power into a firming charter rate environment. Reducing debt remains a strategic priority and further progress has seen debt to gross assets fall below 25% at quarter end. We took advantage of strengthening market conditions towards the end of the period with 13 month index highs and locked in higher charter rates on a portion of the fleet.
Tight supply-demand fundamentals for the geared dry bulk segment continue to drive positive forward sentiment. The management team remain closely aligned with shareholders and maintain strong conviction in the Company's prospects as reflected by a purchase by the Principals of the original Taylor Maritime group of a further 3.9 million shares during the period. There remains plenty to do in 2024 and I am confident of achieving our goals."
It would seem Taylor Maritime Investments (LON:TMIP) are doing well and on course to do better.Gearing being reduced to below 25% set target set earlier is great news (I hold)
Link to Factsheet
Nice to see at least one of my holdings on the up, especially as it's during the recent sell-off everywhere else in my porfolio.
Interesting writeup on Taylor Maritime Investments (LON:TMIP) by David Stevenson:
Great results from Taylor Maritime
Commenting on performance in this first interim period, Nicholas Lykiardopulo, Independent Chair, said:
"As a specialist owner of Handysize vessels, the workhorses of the dry bulk shipping trade transporting necessity goods around the world, TMI has made a strong start as a listed company, delivering on its investment thesis by growing the fleet at attractive prices. We are focused on high-quality, fuel-efficient vessels which we can operate in an increasingly sustainable way as we transition towards alternate fuels. TMI has built a strong foundation since IPO, with an excellent fleet and highly cash generative charters which will allow us to deliver predictable long-term income to shareholders".
Edward Buttery, CEO, added:
"This has been a formative, dynamic period following our well-received IPO, a period of milestones and momentum - efficient deployment of IPO proceeds through new vessel acquisitions, successful chartering balancing attractive rates and visibility, and a strong investment position marrying agility with financial discipline. TMI is on a firm footing, operating in a clearly defined niche of a market with systemic demand".
Outlook
Given buoyant markets, the highest demand and charter rates seen in a decade and attractive opportunities for the specialist vessel buyer, we anticipate continued market strength for the coming two to three years. The favourable combination of slowing fleet growth, healthy demand for commodities, likely slower operating speeds for the global fleet and muted ship ordering arising from evolving emissions regulations will benefit our earnings, secondhand asset values and shareholder returns. The Board remains committed to meeting its stated target dividend commitments, but will consider the company's financial position at the year end and the potential for an additional extraordinary dividend.
* QUARTERLY OPERATING PROFIT 33 MILLION USD
* INTERIM DIVIDEND OF 1.75 CENTS PER SHARE DECLARED
* AS AT 31 MARCH UNAUDITED NAV WAS $1.74 (+22% SINCE 31 DEC 2021)
Commenting on the trading update, Edward Buttery, Chief Executive Officer, said:
"I'm delighted that we have delivered a first year of solid financial results and cash generation with 4.0x baseline dividend cover. We have created a differentiated shipping investment opportunity offering growth and attractive shareholder returns as well as effective recycling of capital. This is in the context of our continued anticipation of two to three years of further strength in the market."
Interim Results Statement
Interesting recent newsflow might explain the upward movement in the share price:
9 March 2022: ...agreed to sell one 2006 built Handysize vessel and one 2011 built Supramax vessel for a combined $33.3m of proceeds. The transactions represent IRRs in excess of 100% for each vessel and a MOIC of 1.4x and 1.7x respectively.
29 March 2022: Waverton Investment Management Limited discloses increase in TMIP holding from 4.64% to 5.0057%
30 March 2022: ...agreed to sell a 2004 built Handysize vessel for $11.6 million. The vessel was an IPO seed asset and the sale is expected to complete in Q2 2022, generating an IRR in excess of 200% and MOIC of 1.6x. The vessel, at 18 years old, is the oldest vessel in TMI's fleet and the sale is part of the Company's stated policy to improve the efficiency of the overall fleet.
Could this become one of my long-term hold shares?
Have to say found it difficult so far to initiate a trade.A J Bell only offered trade at best which given quite a wide spread is not for me.If i can find a broker who offers a limit trade then would consider TMIP .
In my writeup on Taylor Maritime Investments (LON:TMIP) I wrote "could Taylor Maritime be in the right place at the right time?"
It would seem that Jeremy Gordon writing at Citywire yesterday agrees when he says "It has been a case of right place, right time for the fund run by Ed Buttery."
Link to article 'Big gains on the high seas' (you may have to register - free)
"‘With second-hand ships continuing to transact at above-depreciated replacement cost and average net charter rates having increased further over October to $19.5k per day, further valuation increases are likely,’ said analyst Conor Finn."
Brief soundbites from Buttery https://www.investmentweek.co....
Why does Stockopedia class this share as a Collective Investment and give next to no data? Maybe I'm old-fashioned but I think of Collectives as companies that primarily hold shares (quoted or unquoted) in a range of separate other businesses, like traditional investment trusts. As I see it, Taylor Maritime Investments (LON:TMIP) buys physical assets (boats), perhaps renovates them, then rents them out, maybe sells them afterwards. Rather like REDDE or HSS but with bigger ticket items.
Also, any thoughts on whether holders through a UK brokerage have to do anything to get the forthcoming dividend paid in GBP rather than converted from USD at the broker's sometimes penal FX terms?
Quarterly NAV Announcement, Publication of Factsheet and Trading Update
Quarterly factsheet for the Company available here
Key Factsheet Highlights
Post-Period Trading Update (Since 30 September 2021)
A useful summary, thanks. I've been squirrelling this away since July and have enough for now. The Board sound experienced though there's a degree of 'keep it in the family'. I read the prospectus initially but can't remember what size fleet they plan to grow to - they made a point of buying their initial ships at a decent discount on the second hand market and achieving gross rental yields up to 20% pa. My understanding is their focus is mainly grains/ soft commodities so they're not into the current 'container space' boom (and subsequent bust.....?). That said, I expect it will turn out to be quite a cyclical business.
FT's David Stevenson recently compared Taylor Maritime Investments (LON:TMIP) to Tufton Oceanic Assets (LON:SHIP) and came out mildly in favour of the latter, based partly on a longer track record http://www.adventurousinvestor...
From coverage of the IPO by Hellenic Shipping News, 28/5/2021:
A Guernsey-incorporated spin-off of Hong Kong’s privately-owned Taylor Maritime Investments, TM initially planned to sell 250m new shares at US$1 each on the premium segment of the LSE’s main market in that exchange’s first major maritime IPO since that of Tufton Oceanic Assets’ in 2017. Such was the interest in the offering, TM ultimately issued, in a deal brokered by Jefferies, 253.7m shares, comprising 160m shares to investors and 93.7m shares issued to fund the acquisition of a seed fleet of 23 handysizes and supramaxes bulk carriers.
Handysize vessels have a carrying capacity of 15,000 to 35,000 DWT and length from 130m to 150m with a 10m draught. They typically contain five cargo holds for diversified storage with four on-deck cranes. Their shallow draught and small size allow them to operate in most ports across the world, making them the most common bulk carrier over 10,000 DWT. They can carry a variety of dry bulk cargo, including iron ore, coal, cement, phosphate, finished steel products, wooden logs, fertilizer, and grains. These vessels are typically built in Japan, South Korea, China, Vietnam, India, and the Philippines.
Supramax vessels are medium-sized vessels with a carrying capacity between 48,000 and 60,000 DWT, with a typical draught of 12.2m and 199m length. Because of their smaller size, Supramax vessels can enter and exit smaller ports.