Ten small-cap value and growth ideas: 2025 review

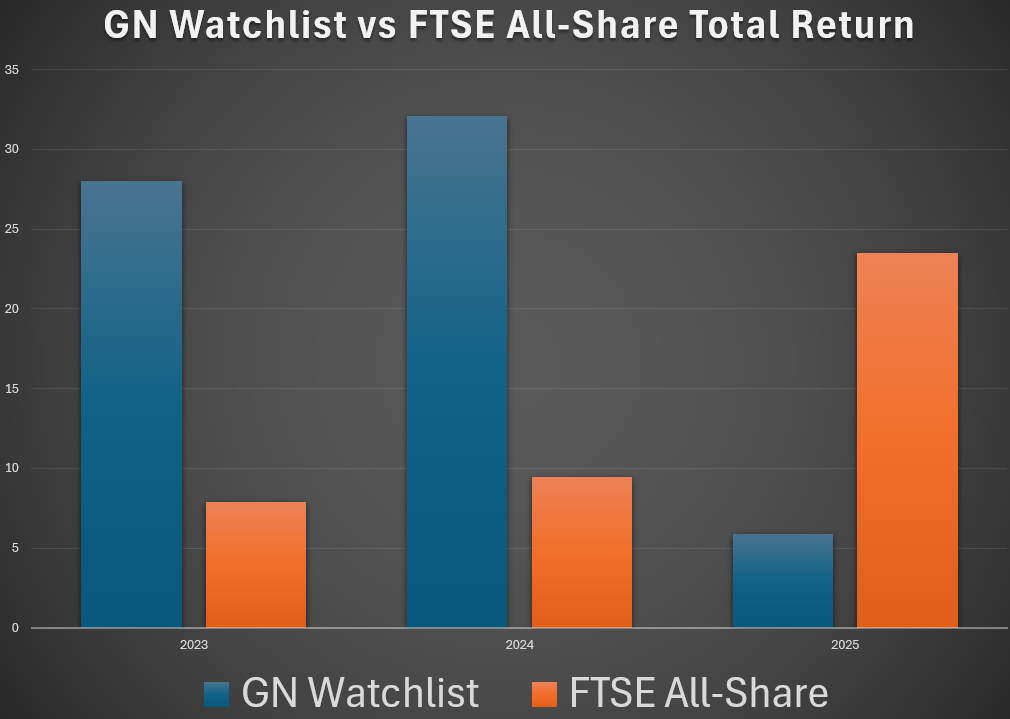
2025 was a year in which the return of my watchlist finally reverted to mean, after a few years of exceptionally strong performance. It was a period of substantial underperformance against the FTSE All-Share Index.
In 2025 so far (as of 21st December), my watchlist has generated an average total return of 5.9%, significantly underperforming the FTSE All-Share’s 23.5%.
Here are the returns of my watchlist vs. the FTSE All-Share and the AIM All-Share over the past three years:
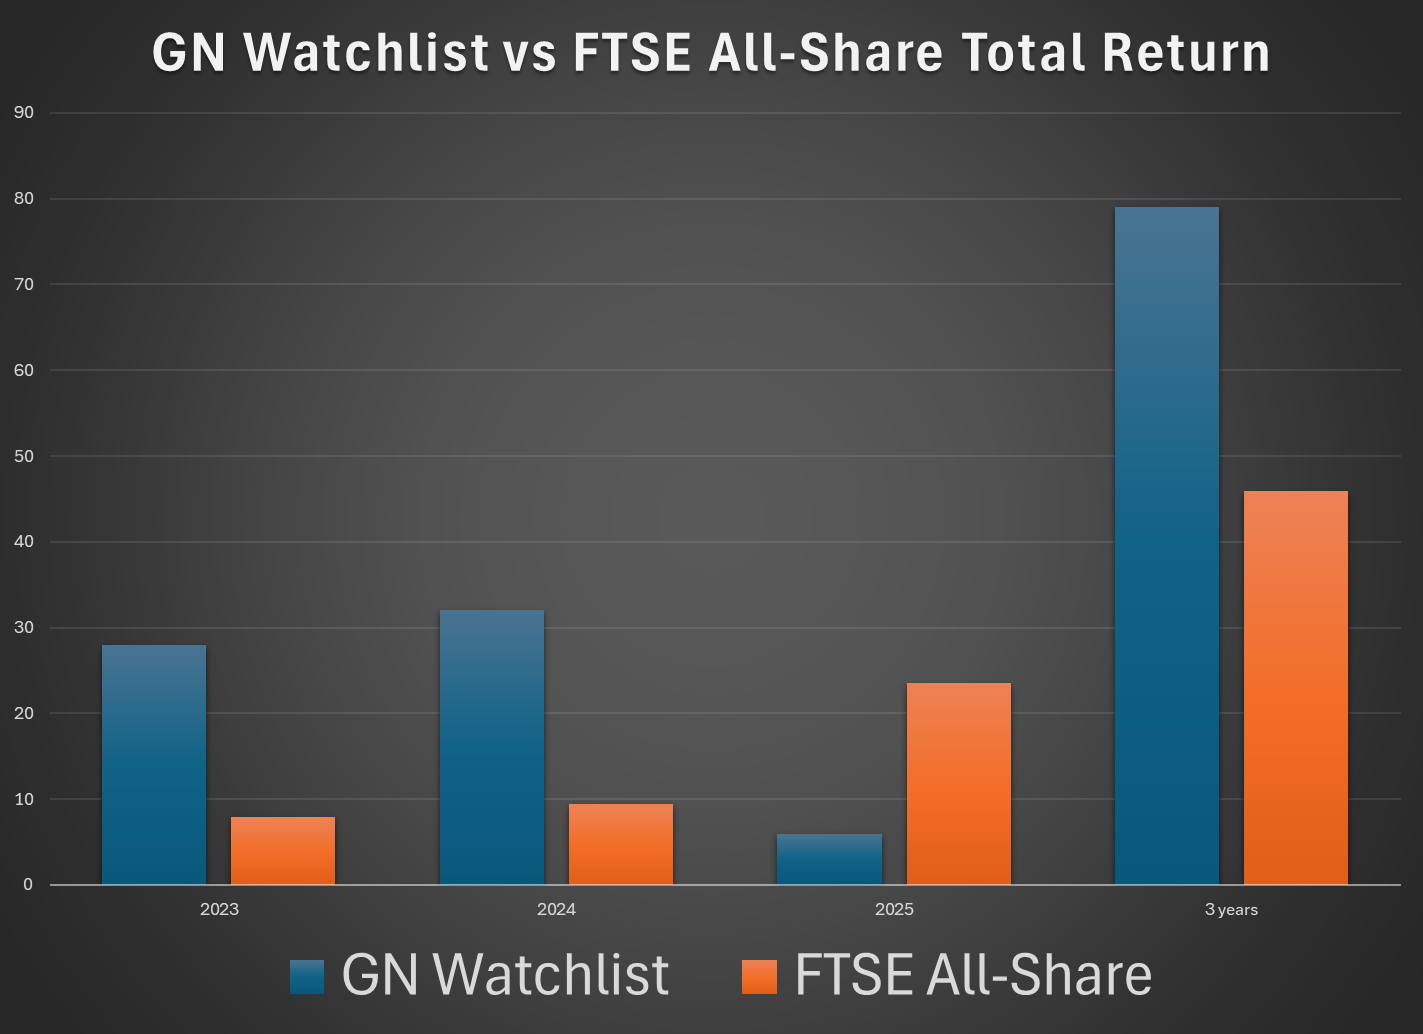
It looks better if we include the compounded return over the three years:
It’s time for a post-mortem: what went wrong in 2025? What went right? This will tee us up nicely for my 2026 watchlist.
Please note that I won't be going into the stories in detail - that is for the daily report!
What went wrong?
This is going to be the longest section.
1. PayPoint (LON:PAY)
Total Return YTD -33%.
Market cap as of writing: £294m.
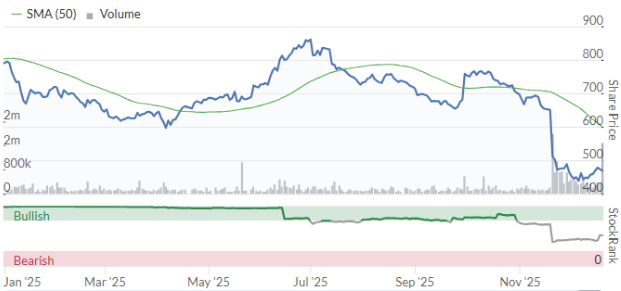
Much of the return from PayPoint comes in the form of its enormous dividend yield, but that was not enough to offset a very weak share price performance.
I covered the company's November profit warning here.
Two major issues were identified: 1) reduced volumes through the parcel service Collect+ due to problems at its courier partner Yodel/Inpost. 2) difficulties in growing the obconnect business (where PayPoint is the majority shareholder).
I lowered my stance on PayPoint to neutral, which is standard operating procedure in our daily reports after a profit warning.
However, as I said in our daily report on the day, I find the potential value here tempting:
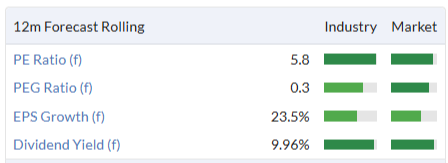
The profit warning reduced the FY27 earnings estimate from 102p to 83p:
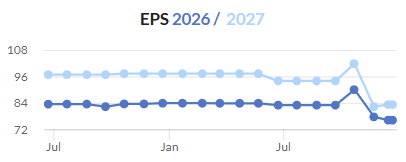
The problems at Collect+, as far as I can tell, were the fault of Yodel/Inpost, not PayPoint. PayPoint’s error was accepting commercial terms which assumed higher volumes, as those volumes did not materialise.
But has this changed the long-term opportunity at PayPoint and its Collect+ business? I’m inclined to think not. It will be very helpful when we learn of the performance at this division during the peak Christmas period.
Two other points to which I’d like to draw your attention:
1. International Distribution Services (Royal Mail) invested nearly £44m in Collect+ in September, taking a 49% share and triggering a special dividend from PayPoint. This transaction deepens the strategic relationship: Royal Mail branding and over-the-counter services are being rolled out to 8,000 Collect+ sites. This also reminds us that PayPoint as a group is not dependent on the profits of any one of its divisions.
2. A £30m buyback is ongoing, part of the company’s long-term plan to buy back £100m+ of its shares over a four-year period. It plans to buy back £30m annually for the next three years. While the company may have overpaid with its initial buyback efforts, it is now buying back a substantial amount of shares at a very cheap earnings multiple, and intends to to continue doing so (depending on business performance, market conditions, etc.)
Net debt is only £84m, vs. annual operating profits of c. £80m.
My conclusion? I’m going to KEEP PayPoint on my watchlist for 2026.
2. Impax Asset Management (LON:IPX)
(At the time of writing, Graham has a long position in IPX.)
Total Return YTD -30%.
Market cap as of writing: £178m.
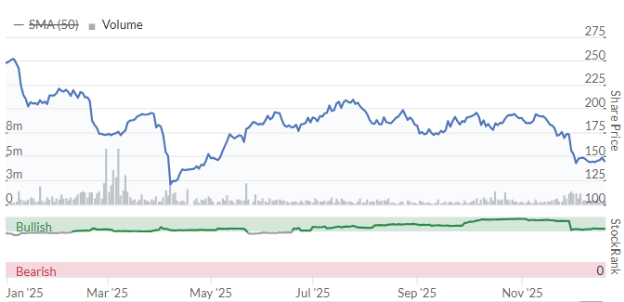
It was an annis horribilis for Impax, as it suffered £13 billion of outflows.
AUM finished the year at £26 billion, having started at £37 billion.
With AUM down 30%, perhaps it’s only right that the share price should fall 30%.
Unfortunately, as with PayPoint, this is a situation where the current value on offer is very tempting to me:
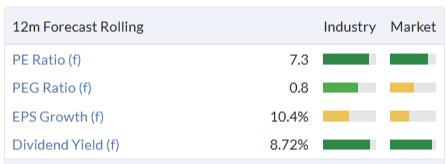
As with PayPoint, they have been buying back their own shares (a more modest £10m programme).
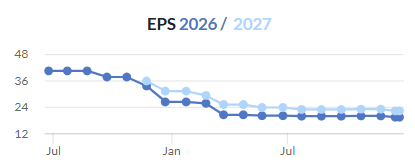
The sad reality is that EPS forecasts have halved:
3. Nichols (LON:NICL)
Total Return YTD -22%.
Market cap as of writing: £349m.
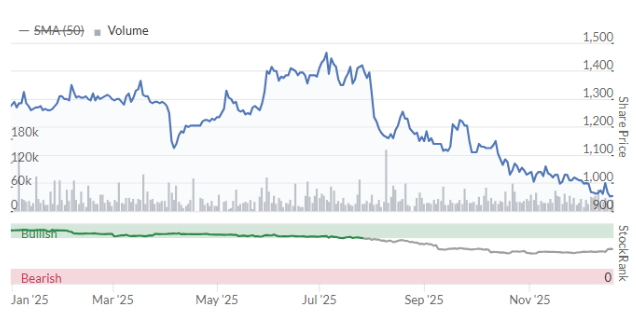
I’ve had this as an anchor of quality in the portfolio. However, despite earnings expectations standing firm, the market de-rated this one after its interim results in July.
EPS forecasts:
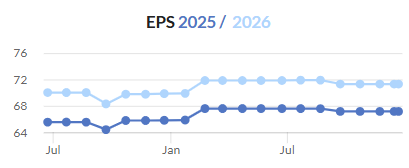
It turns out the market is not particularly interested right now in a drinks company generating only modest revenue growth (+1.8% at the interims, and only 3% forecast for 2025).
4. Peel Hunt (LON:PEEL)
Total Return YTD -3%.
Market cap as of writing: £115m.
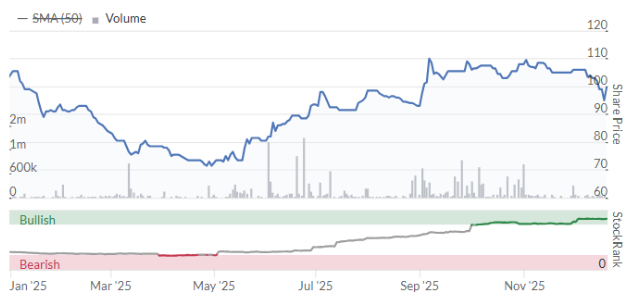
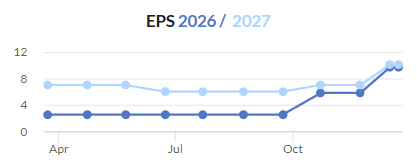
I’m surprised that this one didn’t do better. Recent interims showed revenues up 38% and H1 PBT of £11.5m (not a typo!)
The balance sheet alone is worth over £100m. It seems to me that the market is being overly cautious here.
Official forecasts are struggling to keep up with the improved outlook:
What did OK
5. Mercia Asset Management (LON:MERC)
Total Return YTD 7%.
Market cap as of writing: £127m.
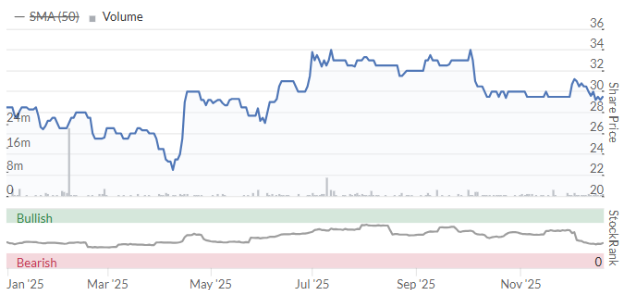
I still really like the opportunity at this growing fund manager. Its direct investment portfolio is thought to be worth £130m, about the same as its market cap, and it also has £34.5m of cash according to the Sep 2025 balance sheet, and that's before any value we might attribute to its core fund management business. I covered its interim results in detail earlier this month.
6. Cavendish (LON:CAV)
Total Return YTD 9%.
Market cap as of writing: £34m.
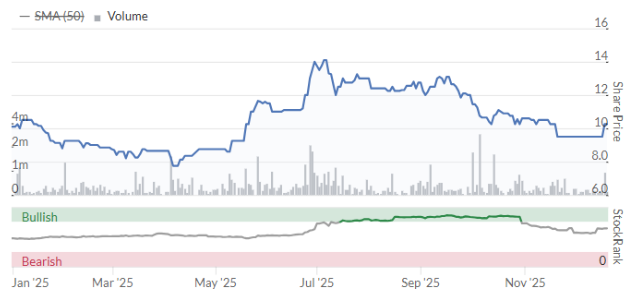
Results here have been less impressive than at Peel Hunt. The waiting game continues for London’s investment banks, big and small - when will the IPO market open up again? See here for Mark’s analysis of Cavendish’s interim results.
7. Polar Capital Holdings (LON:POLR)
Total Return YTD 11%.
Market cap as of writing: £498m.
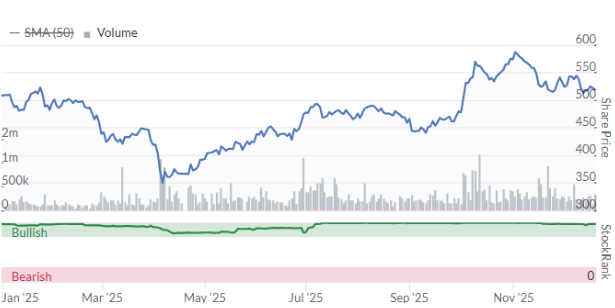
Polar has unusually suffered some quarterly outflows, including in its Q2 period (to September). The effect of this on AUM was masked by rising stock market indices.
The main vulnerability is to a tech sector sell-off, but I remain a fan of Polar and its respected specialisms (e.g. tech, healthcare, insurance). And I think it continues to offer value:
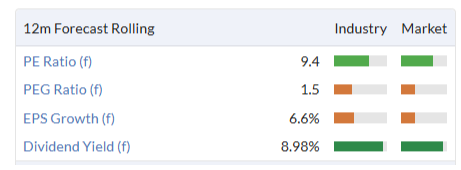
8. Mortgage Advice Bureau (Holdings) (LON:MAB1)
Total Return YTD 14%.
Market cap as of writing: £391m.
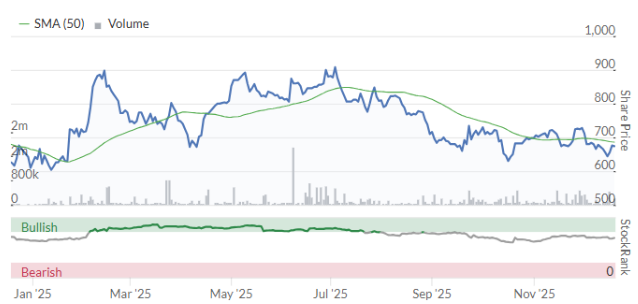
I view this as another quality anchor in the watchlist:
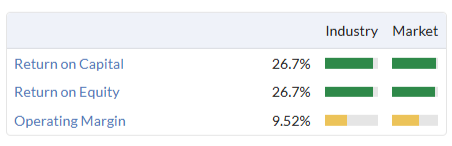
2025 has been an excellent year, with H1 PBT up 55% to £9.6m, while adjusted PBT grew to £14.5m.Conditions in the mortgage market improved considerably in 2025, and I’m happy to bet on more of the same in 2026 as interest rates continue their steady decline.
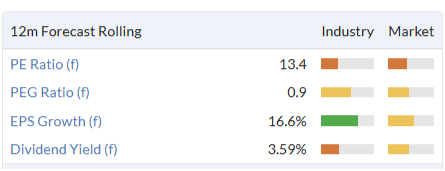
Valuation isn’t stretched yet, in my view, but do bear in mind that trading will always be somewhat cyclical:
What did well
CMC Markets (LON:CMCX)
Total Return YTD 27%.
Market cap as of writing: £818m.
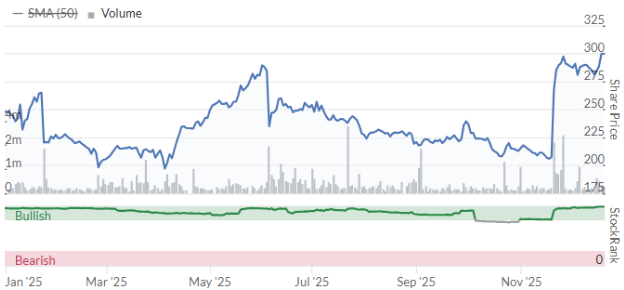
This has been in my watchlist every year, and after a stunning performance in 2024, it continued to do well in 2025. Recent results were ahead of expectations and I remain very satisfied with the outlook. Despite all of the share price gains seen here, this has been matched by earnings growth and the forward P/E multiple is still only 10x.
10. International Personal Finance (LON:IPF)
Total Return YTD 80%.
Market cap as of writing: £498m.
(At the time of writing, Graham has a long position in IPF.)
The two stocks I added to my personal portfolio late last year ended up being almost the best and worst performers in my watchlist: Impax and IPF.
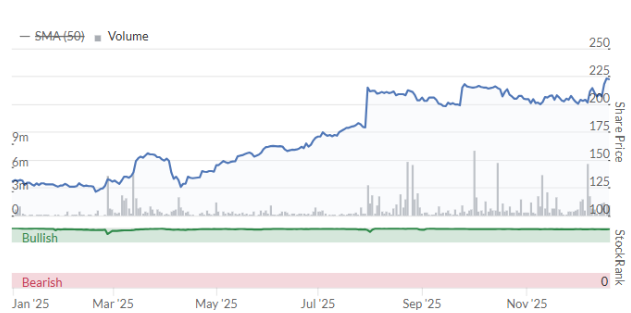
IPF’s management are happy to sell out to a New York-based buyer, if that buyer can come up with the necessary funds to get the deal over the line.
It’s still not clear if the bid is going to go through, but for the purposes of my watchlist let’s bank the gains and pick something new.
In my next article, I’ll show you my 2026 watchlist.
As far as the 2025 list is concerned, it was a disappointing year. There was only one blowout winner, and there were several poor performers in the mix.
However, I did fully expect that after two years of strong performance, and considering how few changes I make to my watchlist, that I was due to have a bad year.
And I’m still pretty excited about what most of the companies mentioned above could achieve for their shareholders.
And for the others… it’s time to move on! The substitutions and replacements will be disclosed in Part 2.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

5 comments
I guess if you do cash out now for International Personal Finance (LON:IPF) and the deal subsequently falls through (buyer can't stump up the cash etc) then the price will likely take a short term dump and you can buy back in cheaply in the knowledge that none of the fundamentals have changed.
Hi Graham.
Thanks for your review. Regarding PayPoint (LON:PAY) , have you come across any information as how much the Royal Mail services installed might be worth to top line profit? I remember reading the statements earlier in the year and felt left feeling quite in the dark as to how much this might be worth. In ther end, I sold PayPoint (LON:PAY) because of this uncertainty. I do certainly agree, that the valuation looks especailly attractive with the share buy back ( 33% or market cap at present price) and the unrealistically low metrics. It's also sporting a rather bowly bowl of late and feels like the only way is UP..but who knows. Still on my watch list.
International Personal Finance (LON:IPF) was a nice christmas present today though. It was after reading your artice earlier last year that I bought in and today i sold out at near the agreed price. Thanks for all your diligent work! Much appreciated.
You're welcome, Stonethecrows, and well done for profiting on IPF - it's your own DYOR research that makes it possible! As for PayPoint, I won't be able to answer that today but it's a good question re: Royal Mail, doubtless I'll be covering PayPoint (LON:PAY) again before too long. Happy New Year. G
Hi Graham,
Thanks for your review - it's always interesting to see how you fared as you have an excellent long-term track record and a near 80% 3-year TR is not to be sneezed at - great work.
I think what has saved me this year (I haven't done my review) is utilising a much more cut-throat stop-loss approach - for example, whilst PayPoint (LON:PAY) worked well in the 1HY I luckily cut it when it started to fall. I was extremely lucky as all of the indicators I use seemed to show it as having some good potential.
I worry that Mortgage Advice Bureau (Holdings) (LON:MAB1) could also be showing this similar trend - regular spikes upwards, but then a regular decline back down again - despite this I continue to hold as in a world of declining interest rates and hopefully soon housing recovery I would think it should do well.
Banking gains on short-term trades seems to have been quite an effective strategy this year.
But, the current market is so hard to read - a number of others on your watchlist "should" have done well in a trending market, but have shown little signs yet of positive movement. However, I am hoping that what this shows is that there is still plenty of growth to come in the UK market as other SP catch-up and I am hoping that 2026 will be another good year overall for UK stocks - the big question is whether we pick the winners, or will the market move positively whilst our chosen picks remain stuck.
Good luck in 2026 and I look forward to seeing your picks.
Thanks very much Kevin, and well done for exiting PAY so astutely! 2026 picks will be out on New Year's Eve. G