Ten small-cap value and growth ideas for 2025: H1 Review

It’s time to take a look at how my 2025 watchlist is performing so far this year.
My watchlist is my list of 10 stocks that I am particularly interested in or excited about each year.
This list generated a total return of 28% in 2023.
It generated a total return of 32% in 2024.
The return in H1 2025 was… (drumroll) 12%.
Before I go any further, I should add the disclaimer that I do not claim to be able to predict share prices over a six-month period. Or any period for that matter! I do think I have some ability to find interesting shares that can do well if held for a reasonable period of time (otherwise why bother studying them?)
So I’m not here to boast about picking stocks that generated a 12% return in six months.
What I would like to do is briefly review their individual performance.
I’ll go from worst to best.
Without further ado:
1. Impax Asset Management (LON:IPX) (I have a long position in IPX) - minus 14% (£258m current market cap)
I wrote about Impax already today - it has continued to suffer outflows, including very large outflows from St James’s Place. But AUM in Q3 (to June) was up, thanks to an acquisition and positive market movements offsetting modest outflows. The company mentioned having positive flows in June - so we can continue to dream that the string of outflows might end soon. I remain excited about the potential share price rebound in that scenario. For now, given the April profit warning, I’m relieved that this hasn’t fallen further. The unsustainable dividend has been cut but the company is now also buying back its own shares.
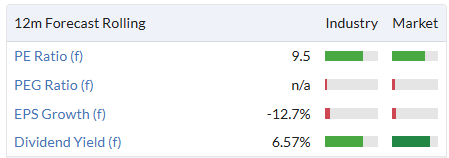
2. Peel Hunt (LON:PEEL) (£116m) - minus 9% (£108m)
I covered Peel Hunt’s AGM update recently, which said that Q1 revenue for the new financial year was “comfortably ahead” of the prior year. The company is also “mandated on a number of transactions that are expected to complete in the second half of the financial year”. So I’m excited that the return of animal spirits - as evidenced by the ongoing AI and bitcoin treasury manias - may translate to IPOs and other fundraisings that could boost the likes of Peel Hunt. While I wish the company was a little more disciplined on costs, I’m attracted to it by its top-notch reputation in equity research and its highly credible positioning as a broker for both small-caps and mid-caps. It has dozens of FTSE-250 clients and even some FTSE-100 clients, and says that it trades 17% of all volume on the LSE. So this is a very credible organisation and I do see it as a potential takeover target for a larger institution.
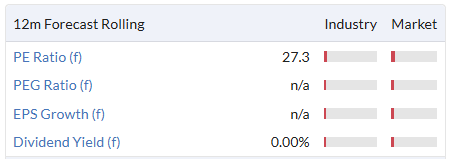
3. Polar Capital Holdings (LON:POLR) - minus 7% (£500m)
This was down by over 30% during the tariff tantrum, but has staged a very nice recovery since then. As with IPX, this is a fund manager where I’m AMBER/GREEN, as I acknowledge that the bull thesis is inherently contrarian. See my notes at the end of June. Full year results confirmed that net flows over the year were “broadly flat”, which makes Polar special: unlike other fund managers, where investors are hoping that the trend of outflows might come to an end, Polar continues to attract new money that offsets outgoings. Polar’s technology funds, and particularly its AI fund, are perhaps vulnerable to outflows if the market’s current love affair with technology turns cold, but at the same time that might offer an opportunity for outperformance (it’s not easy for active managers to outperform when markets are led by the performance of surging mega-caps). At the same time, Polar is enjoying very strong growth in its EM and Asia category. I rate this as a best-in-class fund manager, and its valuation does reflect this view.
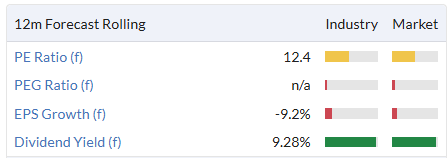
4. CMC Markets (LON:CMCX) - +2% (£695m)
We covered CMC’s results statement in June when the company posted £84.5m of PBT vs. £90.6m that had been expected (shares down 12% on the day). Mark provided detailed coverage of those numbers so I won’t rehash that here. Suffice to say that the profit figure at CMC is a volatile number, as the company tends to have quite a lot of operational leverage. Seemingly small differences in costs - particularly on IT spending - can have a large percentage impact on the bottom line. I remain comfortable with this on my watchlist, noting that Lord Cruddas continues as CEO and is still a 59% shareholder.
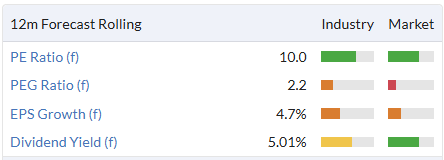
5. PayPoint (LON:PAY) - +10% (£581m)
See here for Roland’s coverage of PayPoint’s results in June. This is a company where I’ve been a long-term fan, admiring its excellent cash generation and being willing to look past the lack of growth in its core business. For me, the convenience store cash terminals are a fine example of a quasi-monopoly (it’s convenient for the majority convenience stores to keep using them), and this core business can power the company to reinvest elsewhere for growth. A good example of this reinvestment was the acquisition of Liverpool-based Appreciate Plc (now love2shop). The company has been getting a little more aggressive with its balance sheet recently, buying back shares and allowing net debt to rise to c. £100m. While conceding that there is increased financial risk, I don’t regret putting this on my watchlist.
6. Nichols (LON:NICL) +10% (£528m)
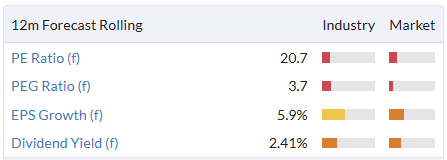
There hasn’t been too much news from Vimto maker Nichols recently. The AGM statement in April said that revenue was up 1.2% in the first three months, in line with expectations. Cash grew to £60m, and adjusted PBT expectations for the year were unchanged at £33.1m. This is probably one of the least exciting stocks on my watchlist, but sometimes boring is good! It does trade rather richly at a PER of 20x and perhaps I’ll have to consider taking it off the watchlist at the end of the year, if I can find other opportunities that are more compelling.
7. Mercia Asset Management (LON:MERC) +10% (£142m)
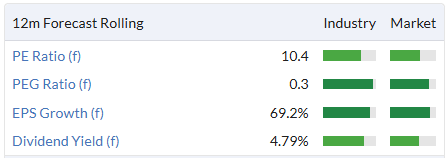
This is a fund manager focused on the UK’s regions, having pivoted from a model where it focused on investing its own capital. But it still has significant assets of its own, and indeed recent full-year results disclosed net assets per share of 43.6p (vs. a share price of only 33p). Tangible equity is £155m, vs. a market cap of £142m. The company certainly believes in itself, and has started buying back its own shares with a £3m buyback. The latest outlook statement mentions “the operational leverage and scalable profitability of the Group”, and I’m a believer. Assets under management have increased to c. £2bn and the company is already profitable.
8. International Personal Finance (LON:IPF) (I have a long position in IPF) +37% (£378m)
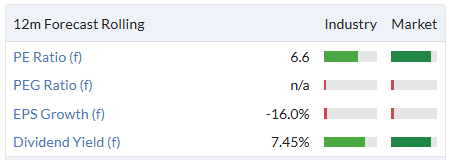
I’m a huge fan of this one. I see it as a responsible lender with an offering that is diversified geographically, and management have proven that they are capable of navigating changing regulations. Indeed, regulations have changed radically in recent years, particularly in Poland, and the company has pulled through. For recent news, see my coverage of their Q1 update in May. This is a risky play, seeing as it operates unsecured consumer lending in Eastern European countries, and increasingly in Mexico. It funds its activities with over £500m of borrowings (market cap: less than £400m). So it’s not for the faint-hearted. But I think investors are being adequately rewarded for the risk with a single-digit PER and a 7%+ dividend yield, even after the gains this year.
9. Cavendish (LON:CAV) +39% (£51m)
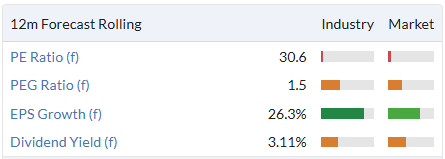
This is performing more like I hoped that Peel Hunt would. Cavendish is superior in the sense that it keeps excellent control over its costs when markets are quiet, but as a smaller company it’s more exposed to activity at the lower end of the market. One positive development has been its growth in private market M&A, helping to reduce the dependence on stock market sentiment. Recent results showed the company achieving breakeven (after share-based payments), which is why I say they keep better control over their costs. A £21m cash balance covers a nice chunk of the c. £50m market cap. There has already been bid interest in Cavendish’s M&A division, according to Sky News. I’m hopeful that a rising share price might help to keep unwanted bidders away!
10. Mortgage Advice Bureau (Holdings) (LON:MAB1) +47% (£468m)
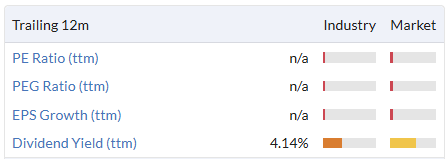
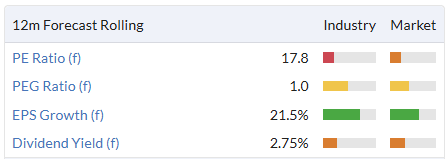
This has been on the watchlist for three consecutive years. It had a very strong 2023 and then gave back some of those returns in 2024. I’m pleased to see that it is back on top, with a fine return so far in 2025. As I noted in May, macro conditions have improved with falling interest rates helping to boost mortgage applications. The company does have significant macroeconomic exposure, but the main attraction is the franchise model which feeds through to high quality metrics (e.g. ROE 22%). I’d like to continue holding this until it enjoys a very supportive macro backdrop, and then I might look to “bank” the gains and take it off the watchlist at that point.
So there you have it, the performance of my list over the last six months.
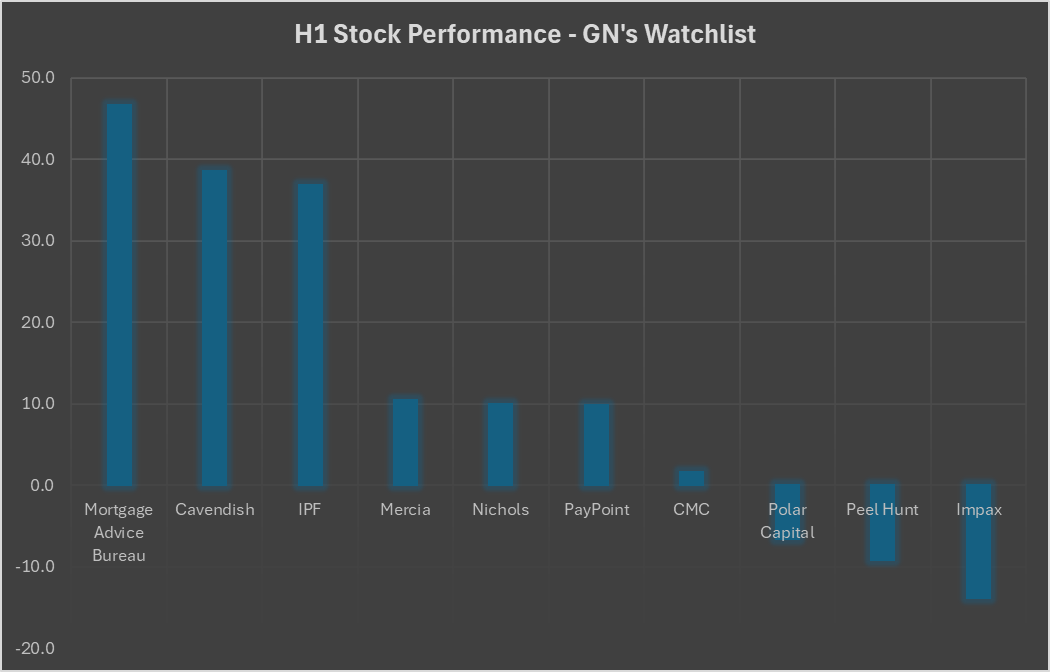
For what it’s worth, FTSE All-Share generated a return of 9% in H1, and I believe the FTSE Smallcap Index has generated c. 10% including its dividend.
I fully expect to have a period of underperformance before long, as the outperformance of my list over the last two and a half years cannot possibly last indefinitely.
But for now, I’m not complaining!
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

9 comments
Graham,
You've missed the SP gain/loss figure for Peel Hunt in your initial article text.
Fixed that belatedly Jeremy, thank you!
Well timed update on Polar Capital Holdings (LON:POLR) - they have just this morning issued positive update of AuM which have increased. See also update today from Liontrust Asset Management (LON:LIO) - not so good.
Yet Polar Capital Holdings (LON:POLR) -5%, Liontrust Asset Management (LON:LIO) +4%. Does not make much sense.
Polar Capital Holdings (LON:POLR) are ex-dividend today
Fair point, that would account for the fall but Liontrust Asset Management (LON:LIO) is now up over 7%. I hold Polar Capital Holdings (LON:POLR) not Liontrust Asset Management (LON:LIO)
Why would you back CMC instead of Plus 500? It can’t make any sense.
With the hot weather Nichols (LON:NICL) might be selling a few drinks possible big special dividend again what's it going to do with the cash? But yes boring.
Da77
From a previous life.... Soft drink sales suffer as the needle goes past 26/27C. Then Ice Cream wins hands down.