Ten small-cap value and growth ideas for 2026

In the previous article, I looked at what went right and what went wrong for my watchlist in 2025.
So without further ado, here is my watchlist for 2026.
Again, please note I'm not going into detail here - I endeavour to do that in the daily report!
1. PayPoint (LON:PAY)
The worst-performing share in my watchlist in 2025, I’m going to give it another chance.
Don't try this at home! This is a very contrarian pick - and the share is indeed categorised as Contrarian by Stockopedia’s algorithms. But I can’t resist it at this valuation, especially as it's buying its own shares.
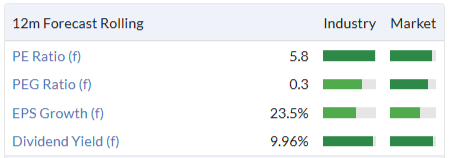
However, to demonstrate that I’m not going to be completely pig-headed about the badly-performing shares from my 2025 list, I’m going to remove Impax Asset Management (LON:IPX) (in which I have a long position) from the watchlist.
There are at least two good reasons for this. Firstly, the company’s EPS forecasts have genuinely been decimated by falling AUM.
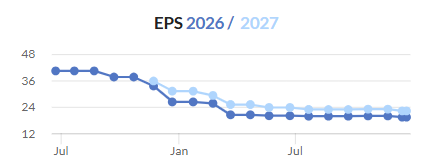
But perhaps more importantly, I already have two other fund managers - Mercia Asset Management (LON:MERC) and Polar Capital Holdings (LON:POLR) - and I think this level of sector concentration is not really necessary for what I’m trying to achieve with this watchlist. So Impax Asset Management (LON:IPX) is out.
2. Nichols (LON:NICL)
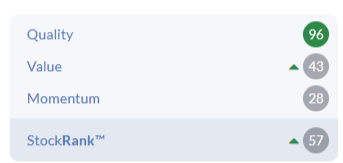
This Vimto maker might be the least exciting stock in the watchlist, but I like to have a boring, high-quality anchor. I also don’t want to “sell” it out of the watchlist at a moment when it offers more value than it usually does (it's usually .
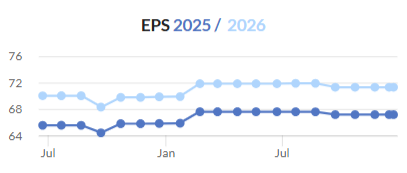
And it’s not as if it has been failing to maintain its earnings forecasts:
3. Peel Hunt (LON:PEEL)
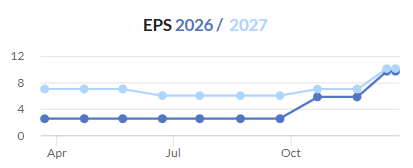
As noted in the 2025 review article, I don’t understand why the market is treating this so suspiciously. Profits in H1 were enormous relative to forecasts (more than 100% of the full-year forecast was already achieved!) and the estimates in the market are struggling to keep up:
I don’t think this one is priced correctly, so it’s staying on my watchlist.
4. Mercia Asset Management (LON:MERC)
Impax is out, but I’m leaving this one in. Mercia invests in private companies in the British regions outside London - perhaps this type of private equity business enjoys a more defensible moat than Impax's environmentalism?
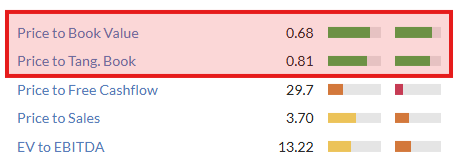
Please note that the PER is not too relevant for Mercia, as we can treat it as an asset play. The shares trade at a discount to book:
5. Cavendish (LON:CAV)
I’m happy to leave this one in for another year, as there are signs that the London IPO market might be opening up again. There were several large deals in H2 2025, and more are in the pipeline for 2026. Cavendish, as a boutique bank, depends on the small-cap market - but all ends of the market should benefit in an eventual IPO boom.
6. Polar Capital Holdings (LON:POLR), 7. Mortgage Advice Bureau (Holdings) (LON:MAB1), 8. CMC Markets (LON:CMCX)
These all did fine in 2025, and I have no reason to remove any of them, so they are staying in.
However, International Personal Finance (LON:IPF) is out, due to a potential takeover offer.
Two spaces have opened up this year. So I'm adding...
9. Hostelworld (LON:HSW)
(At the time of writing, I have a long position in HSW.)
This is a leading global online travel agent - with a market cap as I'm writing this of just £149m.
I had a negative reaction to their recent acquisition, as I thought that it might have been unnecessary to pay $12m for a tiny business which I thought they could have been able to replicate on their own.
However, I shouldn’t allow myself to get too caught up in this. The company is forecast to earn net income of €18m in 2026, so paying off the debt it took on to pay for this acquisition should not be a problem at all.
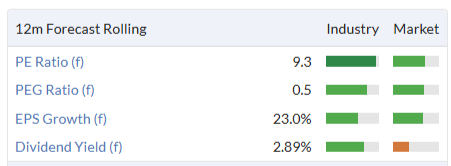
This shares offers a growing social network, a defensible niche in the online travel market, and improving quality metrics, all on a single-digit P/E multiple:
I covered it many times in 2025 - please see the daily report archives.
The StockRank is only 25 but I think a small part of my job is to point out where I think it’s possible for a human to spot something that the computers can’t! So I'm happy to add HSW to my 2026 watchlist.
10. B.P. Marsh & Partners (LON:BPM)
BPM has been one of my favourite shares for a long time, but this is the first time it gets onto my annual watchlist.
For 35 years it has been investing into the insurance sector, with a remarkable track record of success.
Founder Brian Marsh OBE has recently moved into a non-Executive position, with the long-standing and highly successful Chief Investment Officer becoming CEO. Meanwhile, the MD of 10 years has now become the Chief Operating Officer - this is a company that likes to keep its employees around for a long time!
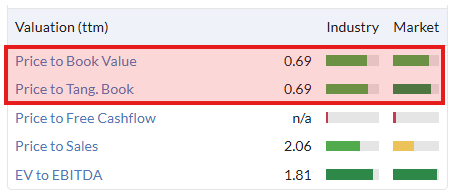
The shares trade at a material discount to NAV and given their excellent track record when it comes to growing that NAV, I’m happy to get this onto my watchlist at last.
So there you have it! The 2026 watchlist includes only two new names, as I try to demonstrate the ethos of sticking with companies for the long-term. Or maybe it’s just stubbornness!
B.P. Marsh & Partners (LON:BPM)
Cavendish (LON:CAV)
CMC Markets (LON:CMCX)
Hostelworld (LON:HSW)
Mortgage Advice Bureau (Holdings) (LON:MAB1)
Mercia Asset Management (LON:MERC)
Nichols (LON:NICL)
PayPoint (LON:PAY)
Peel Hunt (LON:PEEL)
Polar Capital Holdings (LON:POLR)
I'm not bringing a strong expectation of outperformance against the FTSE All-Share over the next 12 months, but I do hope that I've picked shares with reasonable risk/reward profiles. Time will tell! And as always, I look forward to your feedback.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

30 comments
Cavendish (LON:CAV) - TR-1 out yesterday showing Singer has taken 3.47% in Cavendish. Strategic toe-hold in a peer, positioning ahead of consolidation in the small-cap broker space or simply a straight financial investment? Curious what others think — passive stake, early-stage strategic positioning, or reading too much into it?
Stock ranks in the 80's except for low momentum rank. Look's decent value to me c/w nice divi.
One look at Nichols price chart reminds me why I'm not a value investor.
Thanks Graham, I have followed your stockpicks over the years and they have served me well. I own 5 of these and plenty more of others and enjoy your wise words and excellent judgement. Happy New Year and please keep up the good work, you are much appreciated.
Thanks for the comment, dulciemo!
I find it really interesting that stock ranks don't cut much ice with you. More than half of your selections have stock ranks below 65. One of them (HSW) is down at 25 and MERC is only 40.
I love the StockRanks but I think my job as a human analyst is to figure out what the computers might be missing or what they might be late on! Cheers.
Thanks Graham.
I haven't got the skill set to work it out but I would imagine if equally weighted the yield on Grahams portfolio would be fairly decent as an added kicker.
B.P. Marsh & Partners (LON:BPM) This is another investment company on a huge discount to NAV. However, the PE is about 5 and profits are increasing, I think EPS 140p, (80+?), so it is better than most other Investment companies. Also, the company SP has been depressed by a 20% shareholder selling all their share to fund another investment.
Thanks for your tip, IPF, last year.
B.P. Marsh & Partners (LON:BPM) is a superbly run company, making lots of deals over the year, however after 10 months of holding I sold as the share price went nowhere and there's hardly a dividend to get excited about. Definitely one for the patient.
One for the patient investor, and they are paying a special dividend next year of 22p so I expect a few more of those in the years to come. I hold for the long term.
B.P. Marsh & Partners (LON:BPM) The share price more than doubled from Jan 2023 to Jan 2025, so this year's consolidation is maybe to be expected. I don't own it and know little about it, but it does seem like an interesting company that could provide a good source of diversification to a portfolio.
I would have thought that a constructon company would have been on the list and perhaps a defence contractor, the list is a little too narrowly focussed.
Bp Marsh is a phenominal investment, they used to buy smaller underwriting compaanis and leverage them and sell at a profit, but in recent years they have been moving upmarket taking larger positions in major underwriting companies LON:BPM. As an investment trust check on NAV and discount as this varies over time.
Thanks Graham, I love the fact that there are not many new names, long term investing!
Thanks nanotrader! I love making a watchlist with only a few changes each year - helps to show people what sticking with ideas for the long-term can look like!
I really don't want to sound like The Grinch at Christmas so let me start by saying that I genuinely value the work that you, Mark et al put in to your Stockopedia writing throughout the year. It adds value and aids my investment decision making. However (and bear in mind that you did ask for feedback) this list for 2026 looks both uninspiring in its construction and its rationale.
Firstly, let's consider the composition of the choices. Out of ten selections you have two fund managers (having reluctantly removed a third), two stockbrokers and no less than seven stocks that could be categorised as 'financials'. I appreciate that your remit was not to offer a balanced portfolio but where are the interesting stocks in engineering, healthcare, technology etc etc?
Secondly, whilst acknowledging that you and the other members of the team put out quite prodigious amounts of content I think you still needed to add more colour to these ideas. For example, we all know that fund managers are 'cheap' because they are largely losing assets under management. We also know that stockbrokers are cheap because bumper profit years are usually followed by weak ones and so the earnings get rated accordingly. What you haven't done, Graham, is give much in the way of reasons why your individual selections should outperform the rest of their sector or the market. I like to see clear catalysts to drive a share price higher and I don't see them here. Sorry to be negative and good luck to all readers investing in 2026.
I said the same last year about too many "financials".
Sparkler, Graham feels comfortable looking at financials because he understands how to analyse them based on experience, I believe. I have no such understanding so its brilliant for me. He doesn't cover stuff he can't decipher. AI will give you an analysis on anything. I pay my sub because i know my own limitations. I think there are 4 different personalities writing the 12 days of Christmas stuff so you get more variety there. I think your comments are valid but your expectations are very high from one individual. The Stoko software is the whole market bit.
You seem to be ignoring Hostelworld (LON:HSW) here, also it's Graham's list. If he's more comfortable with them, naturally there are going to be more financials...
Also, I think that saying there is a lack of detail on the list here is unfair. They already cover all these shares in detail on the DSMR. So if you are interested in any of the shares on the list you can simply look at their latest commentary (which Stocko makes easy).
Hi sparkler, I'm always happy to be challenged although I can't promise that I'll reply quickly to comments, whether they are positive or negative! Thanks for this.
On your first point. The point of my watchlist is not to offer a balanced set of ideas. You acknowledge that my remit was not to offer a balanced portfolio. The point is that it's my watchlist, based on the research I've done this year. It is likely to be unbalanced. Some people may find it interesting, some may not!
Please bear in mind that I'm just one member of the team here. We have other writers who are confident in sectors where I am not. For more balanced sets of ideas, we have the 12 stocks of Christmas, the SIF Income Portfolio, the NAPS by Ed, various screens by Mark, etc. We also cover a wide range of different sectors every day in the daily report.
I'm simply not an expert in engineering, healthcare or technology and so when it comes to picking the stocks that I'm most comfortable with and therefore most genuinely excited about for the year ahead, I'm not likely to pick as many stocks from those sectors as I am from the financial sector.
But I don't just pick financials. And I don't just invest in financials. I had Trustpilot on my watchlist in 2024 and the stock went up by 100%. I have Hostelworld on the list this year and I own it in my personal portfolio. I have always owned a healthy selection of non-financial stocks in my personal portfolio.
Hopefully there comes a point when I no longer consider fund managers and stockbrokers to be undervalued (ideally because their share prices have gone up!).
So I hope that addresses your first point.
As for providing a more detailed rationale in this article, I have to hold my hands up and say that I did not manage to find the time to write a lengthier article than this one. Around the time I wrote this article I was also producing daily reports, the review article for the watchlist for 2025, my three "12 stocks of Christmas" articles, and so on. I have covered most of the stocks in this list on multiple occasions. So in fairness if I did write a lengthier article here, I would probably only repeat what I have already said elsewhere.
All the best
Graham
Not sure aboutMercia Asset Management (LON:MERC) . I held it for 2 years and it nothing. I think they are more interested in the VCT market as managers than in creating value in the portfolio. I would put it in the same category as Duke Capital (LON:DUKE) , sounds interesting but as an investment offers no return to shareholders.
Mortgage Advice Bureau (Holdings) (LON:MAB1) is down 18% over the last 2 years. Hopefully it will improve next year, l hold.
Fair argument Charles. What Mercia could really use is a few disposals from their direct investment portfolio. That would make the picture much more clearer. From their interim results:
"Our direct investment portfolio continues to mature, with several companies having appointed advisers as we, and they, look to consider opportunities for potential realisation events."
Graham, thanks for the update. A bit surprised that Hostelworld (LON:HSW) is included, you were quite negative back in October: "I’m inclined to sell my Hostelworld shares today, but I haven’t made up my mind yet.".
Yes rusty, I was quite amazed at the acquisition they made, but I've had a chance to cool down and reflect on it since! G
Morning Graham and thanks for all your work in 2025. I already hold four of ten you mention CAV, HSW, PEEL and POLR in fact from 2024 if not 2023. It’s been a long road, perhaps 2026 will see a long awaited return to value. All the best for 2026
Thanks Graham
Still grateful for your identification of International Personal Finance (LON:IPF) as a good investment.
PayPoint (LON:PAY) has had an awful year. Signs that the share price might be stabilising. The value is tempting but I am wary of the increasing debt, used to buy back shares and pay the large dividend, I believe. Do you think this is sustainable? The buyback makes more sense when the share price is suppressed.
Interesting that you feel the IPO scene is about to improve. What makes you think this? The papers will have us believe that businesses are running away from the UK at the moment. (Although it’s often a turning point when the papers are at their most negative).
Looking forward to many more great ideas and analyses for 2026. It’s a significant part of why I’m a subscriber. Thanks Again.
Hi revs8, thanks for this comment and apologies for the delay in getting back to you!
PayPoint (LON:PAY): PayPoint's net debt at the last results was £84m. They are looking to make buybacks of £30m annually. They've also been paying annual dividends of £28m. I can see how this might make people nervous.
Against that they are forecast to generate annual EBIT of around £80m in the short-term.
The big "if", as always, is whether these earnings expectations hold up. Based on current expectations, I do think the debt and their dividends/buyback plans are sustatinable. Of course, if there are multiple large profit warnings from here, I'll be wrong.
Management's target leverage mutiple (net debt/EBITDA) is 1.2x to 1.5x. I'm pretty comfortable with that, given the track record of the business.
As for IPOs, they are inherently unpredictable, but H2 2025 was the busiest six-month period for a while. There are indications of some more deals on the way.
Thanks again!
Graham
Hi Graham. Really impressed that you have replied, and on a Sunday. Thank you.
I did very well from trading PayPoint (LON:PAY) until the change in tone of the RNS's caused the drop in share price. Fortunately I was no longer a holder. Shows that a PI must never be wedded to a stock.
I don't have your skills in company analysis (which is why I am a subscriber) and very much appreciate your commentary.
I use the mystic arts (charting) to help me interpret the market and looking PayPoint (LON:PAY) chart it is either forming a bottom or a bear flag. IMO the latter is more likely and this is another distribution phase, but it is hard to tell.
PayPoint (LON:PAY) remains on my watch list but I need to see a clear break above 500p before I'll be tempted to buy.
Glad to hear the IPO market is improving.
Next week could be interesting. Possibly some downward pressure on stocks on Monday/Tuesday morning but then the US supreme court might rule that Trump tariffs need congressional approval. In which case we may get a US led rally. All fun of the game!
Thanks again.