The Week Ahead (10 – 14 Aug): Economic data points vs. Mid East drama

The week ahead will see the release of two important economic data points which, in the absence of Middle East conflict, would ordinarily take centre stage.
The US-Iran situation has been ongoing since the end of February, so I’ll put that to one side for the sake of this article.
US CPI
Inflation is always a hot topic and persistently above-target inflation is an important feature of the US economic and political landscape.
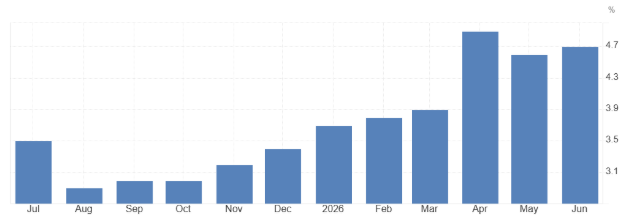
Wednesday will see the release of US CPI data for July. Here’s the year-on-year change in CPI:
Source: tradingeconomics.com
The impact of the Iran War became really noticeable in April, when US CPI growth surged to nearly 5%, and it hasn’t softened much since then.
The July reading is expected to remain flat at 4.7%.
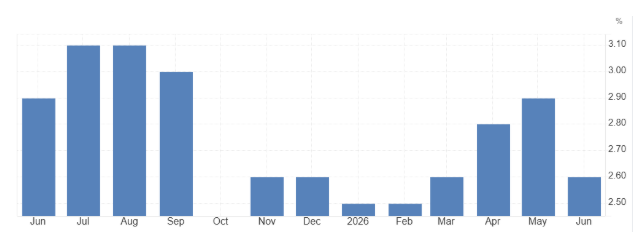
Core CPI, excluding food and energy, will be released at the same time on Wednesday. Here’s the same chart for core inflation:
Source: tradingeconomics.com
This is expected to come in at 2.5%, slightly lower than June’s 2.6%.
Without the impact of rising fuel, it’s a much gentler inflation rate, and much closer to the Fed’s 2% target.
However, the Fed doesn’t have much interest in either of these inflation rates. Instead, it follows the Core PCE Index (Personal Consumption Expenditures), a smarter measure of inflation that adjusts for consumers switching between cheaper and more expensive products.
The Core PCE Index is currently growing at a rate of 3.3%, and it is not getting an update this week. The next PCE release is on 26th August.
Nevertheless, we can expect the CPI release to help fuel speculation around the Fed’s next moves. At the most recent Fed meeting, three members of the committee called for an immediate 0.25% hike in interest rates. While the Fed cannot do anything about the supply of oil, the fact that inflation has been persistently above-target even excluding fuel and even prior to the Iran conflict is difficult to overlook.
UK GDP
On Thursday, we’ll have the UK GDP numbers for June at 7am.
The year-on-year growth rate is expected to come in at 1.2%, down from 1.3% the prior month.
Much like the Federal Reserve, the Bank of England has been in a holding pattern when it comes to interest rates. Official Bank Rate has been holding steady since December 2025:
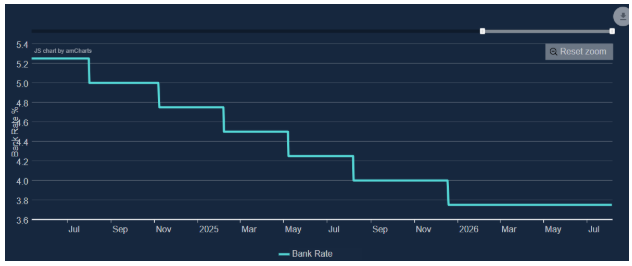
While one number in isolation can’t tell the whole story, a GDP growth rate of just over 1% is in that middle ground where it’s not clear what the Bank of England ought to do next - and doing nothing is a plausible decision.
These economic data points might well get overshadowed by more dramatic events in the Middle East - let’s see!
Economic Calendar
| Date | Country | Event |
|---|---|---|
Monday 10th August | Nothing of major significance scheduled. | |
Tuesday 11th August | ||
15:00 | US | Existing Home Sales |
Wednesday 12th August | ||
12:00 | US | MBA 30-Year Mortgage Rate |
13:30 | US | Inflation Rate |
Thursday 13th August | ||
00:01 | UK | RICS House Price Balance |
07:00 | UK | GDP Growth |
13:30 | US | Initial Jobless Claims |
13:30 | US | Producer Price Index |
Friday 14th August | ||
13:30 | US | Retail Sales |
Companies Reporting
| Date | UK Trading Updates & AGMS | UK Financial Results | International Financial Results |
|---|---|---|---|
Monday 10th August | None of major significance scheduled. | Caledonia Mining (LON:CMCL) (Interims) | None of major significance scheduled. |
Tuesday 11th August | CML Microsystems (LON:CML) (AGM) GlobalData (LON:DATA) (AGM) Public Policy Holding (LON:PPHC) (TU) Bellway (LON:BWY) (TU) | International Workplace (LON:IWG) (Interims) Intercontinental Hotels (LON:IHG) (Interims) Spirax (LON:SPX) (Interims) Lion Finance (LON:BGEO) (Interims) S4 Capital (LON:SFOR) (Interims) Atalaya Mining Copper SA (LON:ATYM) (Interims) | None of major significance scheduled. |
Wed 12th August | Mountview Estates (LON:MTVW) Safestay (LON:SSTY) AdvancedAdvT (LON:ADVT) | Bravura Solutions (LON:BVS) (Finals) Spirax (LON:SPX) (Interims) Coca-Cola HBC AG (LON:CCH) (Interims) Evoke (LON:EVOK) (Interims) CLS Holdings (LON:CLI) (Interims) | Tencent Holdings (HKG:700) Cisco Systems (NSQ:CSCO) HON HAI PRECISION INDUSTRY CO.,. (LON:HHPD) |
Thursday 13th August | Celebrus Technologies (LON:CLBS) (AGM) Revolution Beauty (LON:REVB) (AGM) | Rank (LON:RNK) (Finals) Savills (LON:SVS) (Interims) Antofagasta (LON:ANTO) (Interims) Costain (LON:COST) (Interims) Secure Trust Bank (LON:STB) (Interims) Amaroq (LON:AMRQ) (Interims) | Applied Materials (NSQ:AMAT) Brookfield (NYQ:BN) |
Friday 14th August | Xtract Resources (LON:XTR) (AGM) Bezant Resources (LON:BZT) (AGM) | Winking Studios (LON:WKS) | None of major significance scheduled. |
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

2 comments
The Saudi Aramco earnings early last week used fairly direct language....
"In May, we were clear that the trade disruptions are the most serious we have ever seen in the energy market, and that if the Strait did not fully open by the end of that month, the impact would continue well into 2027. As we have seen, trade flows via the Strait have not normalized since then, and the impact are even more severe. The measures taken by various industry participants, such as the use of inventories to mitigate the impact, have had short-term effects. The release of inventories have now been largely deployed and are not only more difficult to be maintained, but now need to be rebuilt from critically low levels. This would require a call on additional restoration of production, and that additional production also calls on access to reserves, where we had already highlighted before that the level of investment has been insufficient from many in the industry and needs to be addressed.”
“Moving to the macro environment and market dynamics, we see some clear themes. Global oil demand has remained resilient as the supply shock was masked by an estimated 9 million barrels per day of strategic petroleum reserves and commercial inventory withdrawals and around 2 million barrels per day in demand management. The unprecedented liquid supply loss has continued into Q2, and the world lost over 2.6 billion barrels of oil that was distinct to a number of critical industries such as food, semiconductors, mobility, and petrochemicals.”
“This has been partially offset by alternative flow bypassing Hormuz, the release of strategic petroleum reserves by government and the utilization of Aramco’s East-West pipeline, which resulted in reducing the net supply loss to currently around 1.8 billion barrels. The key element of these are, first, the IEA Emergency Release Program of 426 million barrels is coming to an end in August, and with it, a 2 million barrels per day cushion will likely come off the market. Second, after utilizing oil on water and SPR volumes, the world tapped into an estimated 600 million barrels, reflecting 6.5 million barrels per day between May and July of commercial inventories, the only remaining buffer in the system today. Third, within Asia, crude oil imports were reduced by around 6 million barrels per day through a combination of SPR release, drawdown from commercially refined products inventories, and demand management. The East-West pipeline has enabled Aramco to mitigate the impact of the disruption much more than the IEA Coordinated Strategic Reserve Release. All in all, significant drawdowns of commercial inventories have helped but not met end user demand.”
“The aggregate inventory level globally are not a proper reflection of the current physical market tightness…We see an apparent disconnect between future and physical markets as evident in the strong refining margins that reflect the market tightness. Margins are expected to stay exceptionally strong throughout the second half of 2026, supported by limited export availability from key regions like the Middle East, Russia, and Asia, resilient fuel demand, and persistently low inventories. The refining system today, excluding stranded Arabian Gulf and Russian refineries that have been under attack, is stretched and is operating at near maximum utilization rates. Currently flows through the Strait of Hormuz are a tenth of a pre-conflict level.”
“Let me be clear, demand remains strong and has not been met by supply in the first half of this year, but rather from commercial and strategic inventories…Demand in the 2nd half of the year is expected to be around 2 million barrels per day higher than the first half. Restoring commercial inventories and strategic reserves to pre-conflict levels will materially add to calls on crude oil throughout 2027 and likely beyond.”
“To put this into context, if the Strait of Hormuz was to open today, it would take up to 18 months at an average rate of 2.1 million barrels per day to replenish depleted inventories on top of demand.” I bolded to highlight.
A few US tech stocks with earnings this week that I'll be watching: Rocket Lab (Monday), CoreWeave (Tuesday), Cerebras (Wednesday), Nu Holdings (Thursday).