The Week Ahead (12th-16th January) - Defence stocks zoom higher

Hello and welcome to the latest edition of the Week Ahead!
The first full week of 2026 is behind us, and it has been a strong start for the markets.
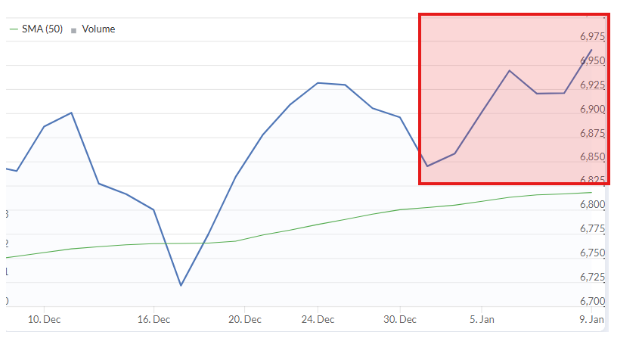
The S&P 500 is already up 1.3% year-to-date:
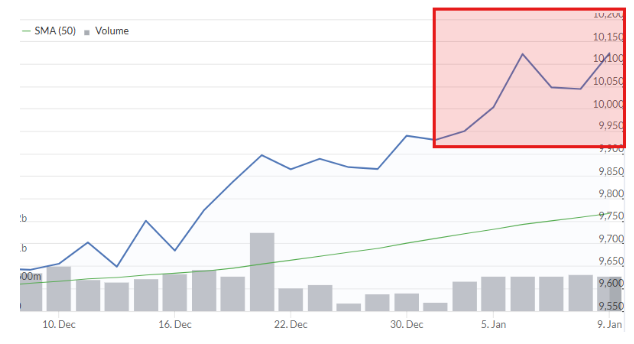
And the FTSE is already up 2%:
I’ve spent the past week or two trying to ignore global politics - particularly Trump’s intervention in Venezuela, and also the unrest in Iran.
The markets haven’t been ignoring it, however. And the ramifications of these events, however grisly this might be, have been positive.
BAE Systems (LON:BA.) , for example, is up by a remarkable 20% year-to-date.
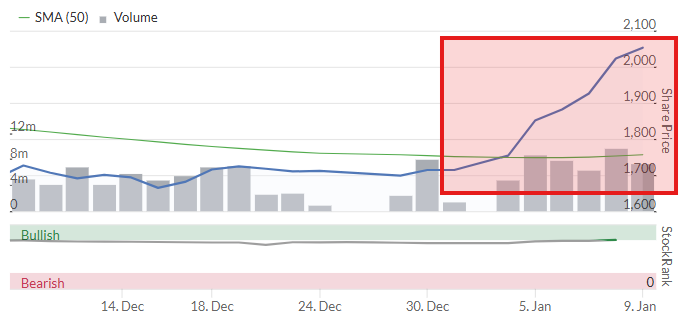
The saying “elephants don’t gallop” has never really been true, and certainly not for defence stocks during times of international tension.
BAE hasn’t even issued a relevant announcement - the price action of this £60bn stock has been entirely driven by external news. President Trump, in particular, has asked for US military spending to rise by over 50% to $1.5 trillion in 2027 (2026 budget: $901 billion).
Such a spending bonanza would ripple through the entire defence sector both in the US and internationally, generating windfall gains for these companies and their suppliers (if they even have the capacity to fill orders of this magnitude?).
Trump has argued that the spending could be paid for through tariff income. According to official figures, US Customs collected over $200 billion in tariffs in 2025, in a year when tariffs were not raised until April. So perhaps there is some plausibility to this claim?
Either way, there is a long road ahead for his defence spending idea: his administration first has to produce an actual proposal for FY 2027 (expected in early February), and then it will slowly work its way through Congress, perhaps being approved in time for the start of the new fiscal year in October. Although based on how previous budgets have been received, it could be quite a bit later than that.
For defence stocks this means a potentially long wait until we find out how realistic is Trump’s $1.5 trillion idea. But his intent is clear!
Looking ahead in the short-term, next week will see updates from various companies that we like to follow in our daily reports: the likes of Games Workshop (LON:GAW), MS International (LON:MSI) and Ramsdens Holdings (LON:RFX) are expected to publish results. There are also a healthy number of trading updates scheduled, including Ab Dynamics (LON:ABDP), Vistry (LON:VTY), and Whitbread (LON:WTB).
In short-term economic news, we already had US non-farm payrolls on Friday 9th: it came in below expectations at 50,000 new jobs, compared to 60,000 new jobs that had been forecast.
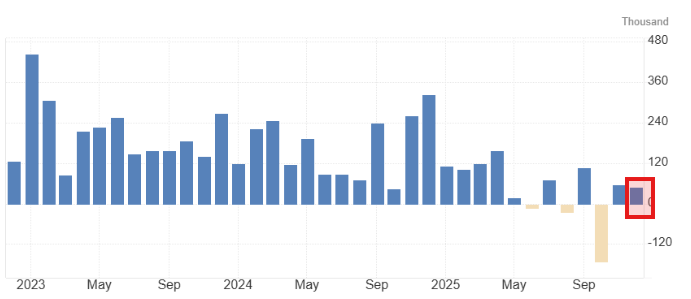
Source: tradingeconomics.com
This “low-hire environment” in the words of Fed banker Thomas Barkin, is due to a combination of economic uncertainty and higher productivity (AI, presumably?).
Whatever the reason, with inflation still above the target, the Fed is not expected to cut rates at its meeting on January 28th. Indeed, it is not expected to cut rates again before Chair Jerome Powell leaves office in May.
Interestingly, President Trump told the New York Times this week that he has in mind who he will nominate to be the next Fed Chair, but hasn’t said who it might be.
DefiRate, which provides data on prediction markets, says that the most likely nominee is Kevin Warsh, followed closely by Kevin Hassett. Between them, they have a 80% chance of getting the nomination: so we are very likely to be hearing one of these names for many years to come!
Closer to home, we should have monthly UK GDP data on Monday, with a consensus forecast of 1.1% year-on-year growth (unchanged from the prior reading).
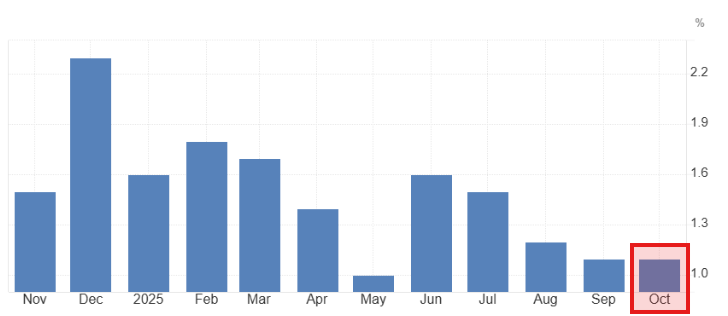
Source: tradingeconomics.com
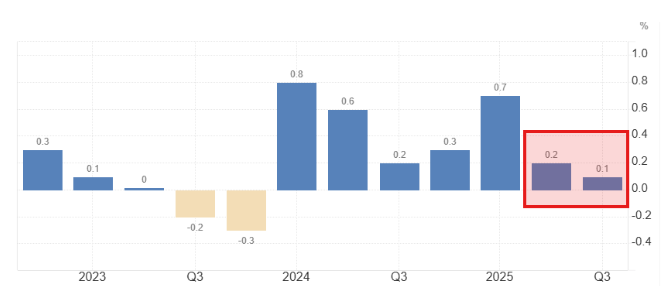
The quarter-on-quarter growth rates are what define a technical recession (when they are negative twice in a row), and they were dangerously close to being negative in Q2 and Q3:
Source: tradingeconomics.com
So the UK economy might not be in a recession, but it’s close - we can expect many companies to continue to say that the environment remains difficult.
Economic Calendar
| Date | Time (GMT) | Country | Event |
|---|---|---|---|
13 January | 00:01 | UK | BRC Retail Sales Monitor |
13 January | 13:30 | US | Consumer Price Index |
13 January | 15:00 | US | New Home Sales |
14 January | 12:00 | US | MBA 30-Year Mortgage Rate |
14 January | 13:30 | US | Producer Price Index |
14 January | 13:30 | US | Retail Sales |
14 January | 15:00 | US | Existing Home Sales |
15 January | 07:00 | UK | Gross Domestic Product |
15 January | 13:30 | US | Initial Jobless Claims |
Companies Reporting
| Date | UK Trading Updates and AGMS | UK Financial Results | International Financial Results |
|---|---|---|---|
Monday 12 January | Oxford Nanopore Technologies (LON:ONT) | Knights group (LON:KGH) | None of major significance scheduled. |
Tuesday 13 January | Gamma Communications (LON:GAMA) Grafton (LON:GFTU) Hunting (LON:HTG) Integrafin Holdings (LON:IHP) Nanoco (LON:NANO) (AGM) Pagegroup (LON:PAGE) Persimmon (LON:PSN) Whitbread (LON:WTB) | Games Workshop (LON:GAW) | JPMorgan Chase & Co (NYQ:JPM) |
Wednesday 14 January | Diploma (LON:DPLM) (AGM) Hays (LON:HAS) Pearson (LON:PSON) Tracsis (LON:TRCS) (AGM) Vistry (LON:VTY) | MS International (LON:MSI) Ramsdens Holdings (LON:RFX) | Boeing Co (NYQ:BA)C Wells Fargo & Co (NYQ:WFC) Citigroup (NYQ:C) |
Thursday 15 January | Ab Dynamics (LON:ABDP) (AGM) Dunelm (LON:DNLM) Fuller Smith & Turner (LON:FSTA) Oxford Instruments (LON:OXIG) Rathbones (LON:RAT) Robert Walters (LON:RWA) Taylor Wimpey (LON:TW.) | Safestore Holdings (LON:SAFE) Titon Holdings (LON:TON) | Taiwan Semiconductor Manufacturing Co (NYQ:TSM) Morgan Stanley (NYQ:MS) Goldman Sachs (NYQ:GS) Blackrock (NYQ:BLK) Citigroup (NYQ:C)FR |
Friday 16 January | Cab Payments Holdings (LON:CABP) | None scheduled. | None of major significance scheduled. |
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

4 comments
Friday is also Polar Capital Holdings (LON:POLR) Q3 update. Source: https://www.polarcapital.co.uk...
Would have thought the obvious 'beneficiary' of Trump would be gold and silver.
Will Trump put tariffs on foreign defence contractors?
Seeings as we are in the mood to discuss defence stocks ... BAE Systems (LON:BA.) I hold, but trimmed a little.
Up 73% over 1 year. Oh, that surprised me, I had assume it was more modest than that.
Pulling up the Stocko report from a year ago, i see BA was on a fwd PE of 16, with a Value score of 31. Fairly modest, actually. Another surprise looking back.
Fast-forward to today, and the fwd PE is rather more racy 24, and Value score of 17.
So, quite the re-rating.
Things have gotten worse (or better, depending on which way you're looking at it). It seems probably that BA will have plenty of growth ahead of it for the next few years at least, pretty much regardless of whether Ukraine is resolved (unlikely in 2026, IMV) or Trump eases up.
You never know, of course. Narratives have a habit of changing. And the rating of BA is fairly punchy. So some caution is warranted.
The risks of the new defence contracts will be higher than before due to the Trump administration's desire to punish delays and underperformance. Prohibition of share buybacks and dividends, and caps on executive pay have been mentioned. So get ready to run before the inevitable problems kick in...