The Week Ahead (13 – 17 Apr): UK GDP, US Employment, US Financials, Tesco, Dunelm

Most indices largely tracking each other this week, and marked by the big rise mid-week in response to the ceasefire announcement:
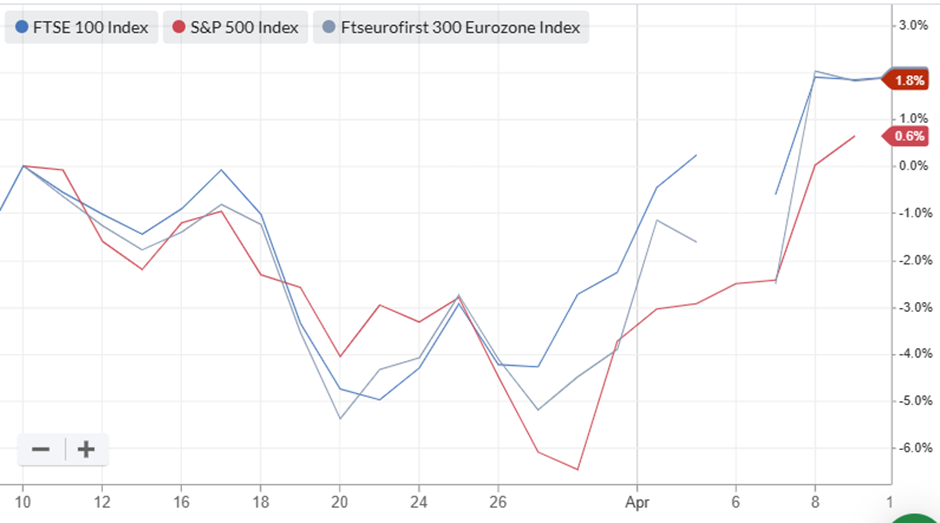
The truce holds, for now. But with both sides calling each other out for alleged violations of the deal they thought they'd agreed to, it would be unusual not to see more volatility ahead.
Here's what we can look forward to next week:
Economic Calendar
Monday 13 Apr |
||
15:00 |
United States |
Existing Home Sales |
19:00 |
United States |
Budget Statement |
Tuesday 14 Apr |
||
04:00 |
China |
Balance of Trade |
07:00 |
UK |
Retail Sales |
07:00 |
Germany |
Wholesale Price Index |
13:30 |
United States |
Producer Price Index |
Wednesday 15 Apr |
||
10:00 |
Euro Area |
Industrial Production |
15:30 |
United States |
Crude Oil Inventories |
Thursday 16 Apr |
||
04:00 |
China |
GDP |
07:00 |
UK |
GDP |
13:30 |
United States |
Initial Jobless Claims |
14:15 |
United States |
Industrial Production |
Friday 17 Apr |
||
10:00 |
Euro Area |
Balance of Trade |
UK GDP
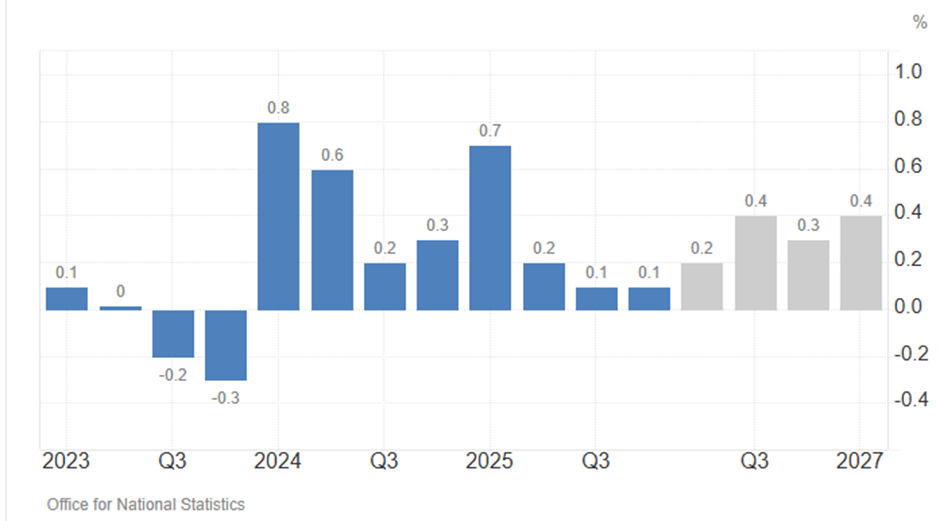
UK GDP growth has been weak at the end of 2025 and into 2026. However, it is forecast to pick up through the year:
[All charts in this section: Trading Economics]
However, global events have the power to upend these forecasts. This week's print may show early signs of the impact these are having.
US Employment
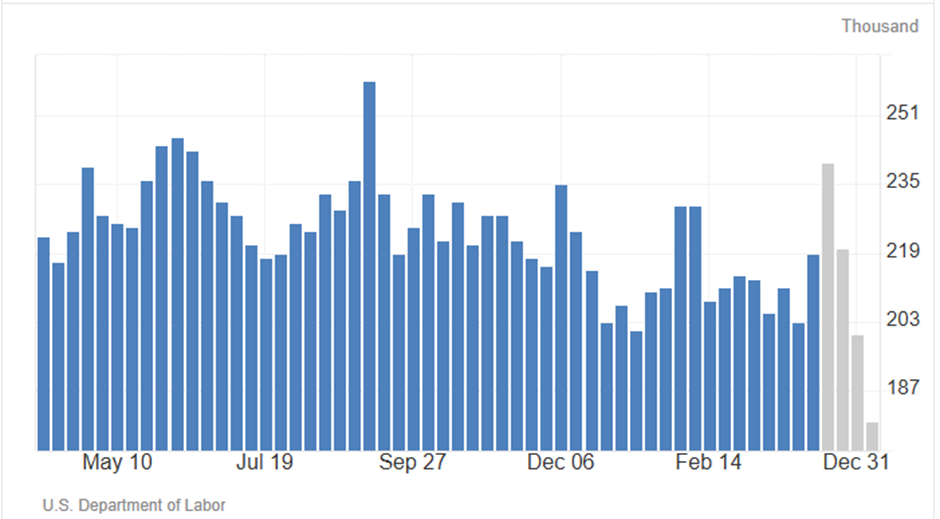
With higher fuel prices in the US affecting consumer sentiment, this will start to feed through to employment. Initial claims are expected to rise in the short term:
With a knock on impact on continuing claims:
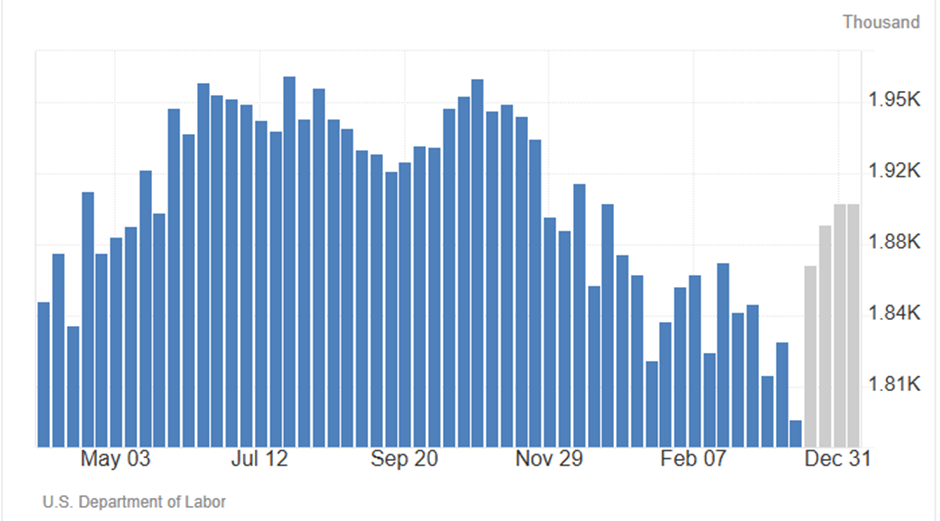
Forecasts are for claims to remain below the levels seen for most of 2025, so any unexpected spike in response to recent global events may be poorly received by markets (and the Trump administration!)
Companies Reporting
| Date | UK Trading Updates & AGMS | UK Financial Results | International Financial Results |
|---|---|---|---|
|
Monday 13 Apr |
Sirius Real Estate (LON:SRE) (TS) |
Churchill China (LON:CHH) (Finals) Concurrent Technologies (LON:CNC) (Finals) Cambridge Cognition Holdings (LON:COG) (Finals) |
Goldman Sachs (NYQ:GS) |
|
Tuesday 14 Apr |
Imperial Brands (LON:IMB) (TS) Oxford Instruments (LON:OXIG) (TS) Porvair (LON:PRV) (AGM) |
ACG Metals (LON:ACG) (Finals) Amcomri (LON:AMCO) (Finals) |
Blackrock (NYQ:BLK) |
|
Wednesday 15 Apr |
British American Tobacco (LON:BATS) (AGM) Barratt Redrow (LON:BTRW) (TS) Hunting (LON:HTG) (AGM) Onward Opportunities (LON:ONWD) (AGM) Rank (LON:RNK) (TS) |
Ab Dynamics (LON:ABDP) (Interims) ASA International (LON:ASAI) (Finals) Digital 9 Infrastructure (LON:DGI9) (Finals) hVIVO (LON:HVO) (Finals) Saga (LON:SAGA) (Finals) M Winkworth (LON:WINK) (Finals) |
ASML Holding NV (AMS:ASML) (Netherlands) |
|
Thursday 16 Apr |
AFC Energy (LON:AFC) (AGM) Dunelm (LON:DNLM) (TS) Rentokil Initial (LON:RTO) (TS) Schroders (LON:SDR) (AGM) |
Beauty Tech (LON:TBTG) (Finals) Tesco (LON:TSCO) (Finals) Zinc Media (LON:ZIN) (Finals) |
Alcoa (NYQ:AA) US Bancorp (NYQ:USB) |
|
Friday 17 Apr |
Telefonaktiebolaget LM Ericsson (STO:ERIC B) (Sweden) |
As usual, let us know via the comments if you think we've missed anything of note.
US Financials
This is a big week for Wall Street, with many financials reporting quarterly results. Here is a quick summary of things to look out for in this sector:
Goldman Sachs (NYQ:GS)
Goldman kicks us off and enters the quarter in strong form following a 2025Q4 beat.
Look out for:
- The growth rate of investment banking fees versus the stabilisation of NII
- Any updates on AI-driven productivity
- The strength of deal pipelines reported for the rest of 2026
JPMorgan Chase & Co (NYQ:JPM)
JPMorgan Chase follows on Tuesday. At its Company Update event in February, it raised its full-year 2026 NII guidance to approximately $104.5bn, up from $103bn guided in January.
Look out for:
- Jamie Dimon's tone on geopolitical risk, tariffs, and the economic outlook.
- Guidance on credit losses
Citigroup (NYQ:C)
Citigroup is the transformation story, putting paid to the old joke that the C in Citigroup is a soft one.
Look out for:
- Progress on medium-term ROTCE targets.
- Any update on the timeline for exiting remaining international retail banking operations.
Wells Fargo & Co (NYQ:WFC)
Look out for:
- Any update on the removal of the Federal Reserve's asset cap on Wells Fargo, which has constrained the bank's balance sheet growth.
Bank of America (NYQ:BAC)
The bank is expected to report its 16th consecutive quarter of year-over-year growth in trading revenue, bolstered by market volatility.
Look out for:
- NIM trajectory and deposit repricing dynamics.
- Any update on "Erica 2.0," its AI-driven customer assistant, and the operational cost savings it is generating.
Morgan Stanley (NYQ:MS)
Look out for:
- News on the launch of a spot Bitcoin ETF and a private-credit fund, both viewed as potential drivers for new fee revenue.
US Bancorp (NYQ:USB)
Look out for:
- Any signs of stress in commercial real estate and consumer credit.
Tesco (LON:TSCO)
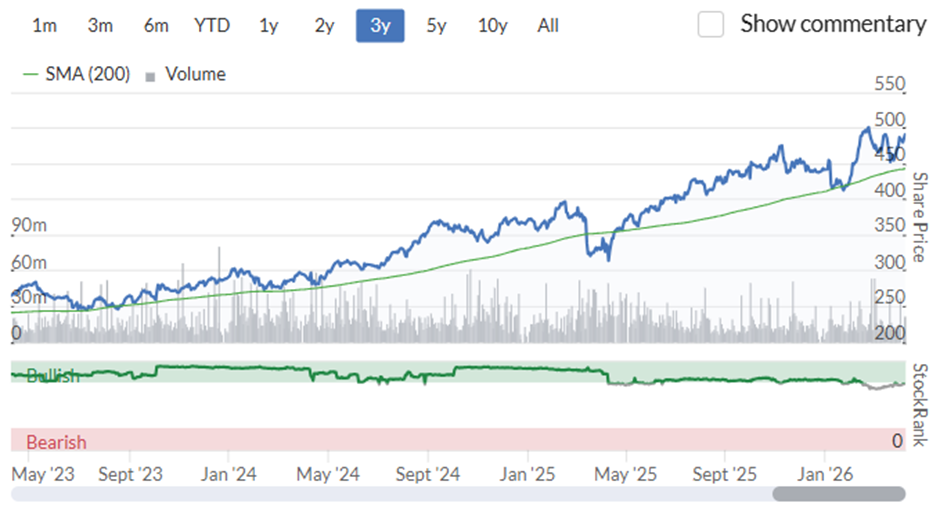
Given the potential for fuel and food inflation, it is perhaps unsurprising that Tesco has shrugged off recent market weakness and continued in its uptrend over the last few years:
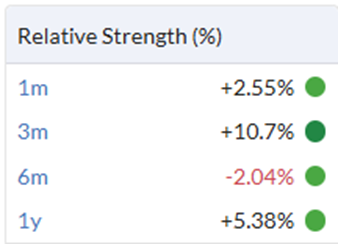
However, in some ways it has simply tracked the wider market and its 1-yr relative strength is now just +5%:
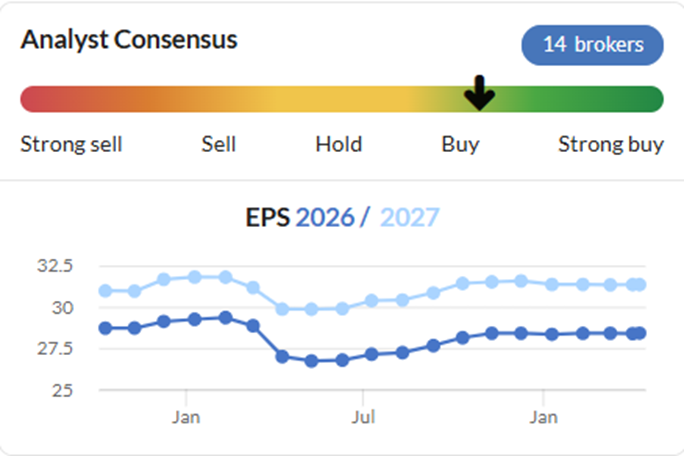
3-5 years of strong performance tends to be the warning sign for mean reversion, though, and the recent rises don't appear to have been backed by changes to consensus:
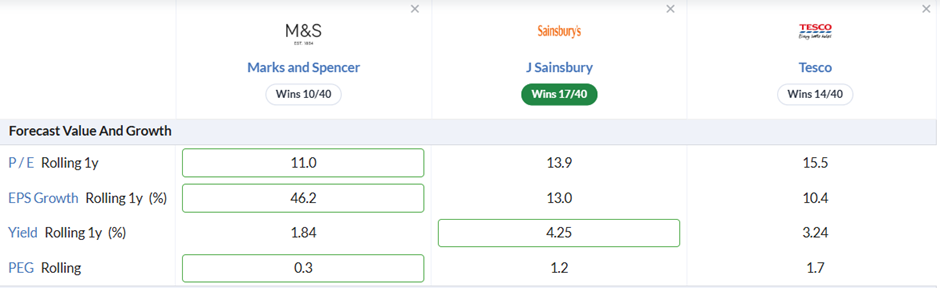
While its forward P/E isn't crazy, the company now trades at a premium to listed peers:
All of this leaves the company vulnerable to any negative surprises. These are the things to watch out for:
- Profitability: The company reported strong Christmas trading, so whether this translates into full-year adjusted operating profit at the top of the £2.9bn–£3.1bn guidance range may be key to further short-term share price gains.
- Booker & Central Europe: Softer performances from Booker and Central Europe have been a drag, driven by a decline in the tobacco market and a retail contract exit. Investors will want to see signs that positive action has been taken to improve the outlook for these parts of the business.
- Market share: The company has continued to take market share and, at 28-29%, is at its highest level in a decade, driven by Aldi price-matching and Clubcard deals. Can they continue to build share, or is this reaching structural limits?
- Costs: Tesco announced a 5.1% hourly wage rise for shop floor and warehouse staff from March 2026, costing £200m annually, so investors will be watching how successfully the company offsets this with cost savings elsewhere.
- Dividends & Buybacks: The interim dividend was lifted 12.9% to 4.80p per share. Will the full-year dividend be raised by a similar amount? In addition, a £1.45bn buyback programme was due to be completed by April 2026. Will this be extended, and by how much?
- Outlook: As always, the future outlook can be more important than the historical results. Investors will be looking for guidance, particularly around cost pressures and competitive intensity.
Dunelm (LON:DNLM)
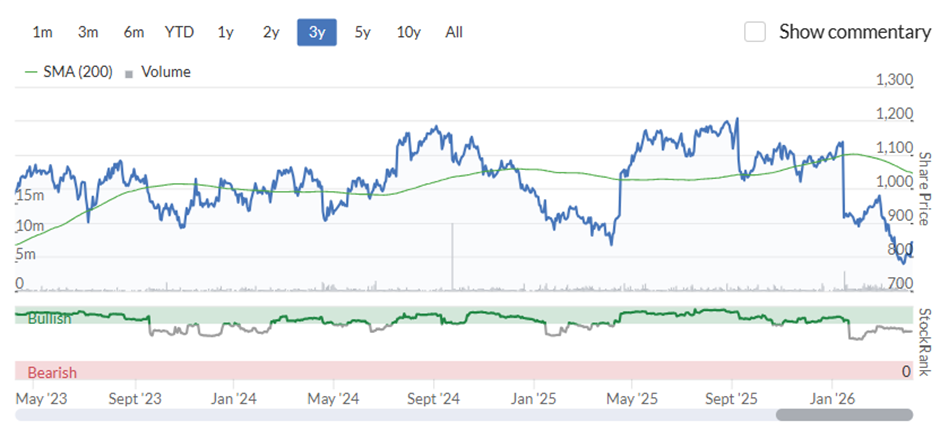
Staying with retail, Dunelm reports its Q3 trading on Thursday. The share price picture over the last few years has not been as rosy:
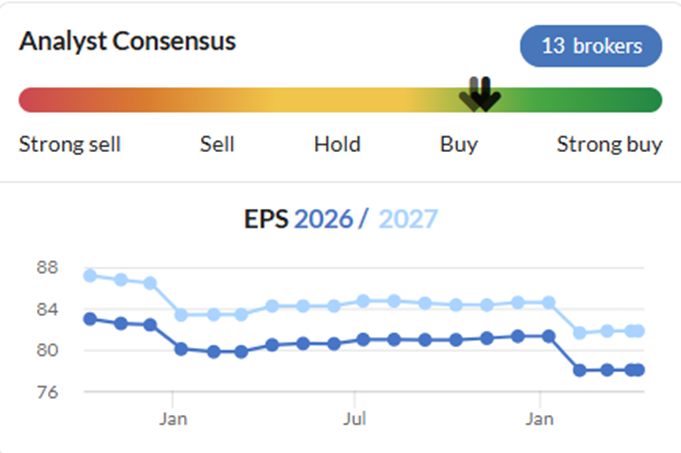
Recent consensus drops have taken their toll:
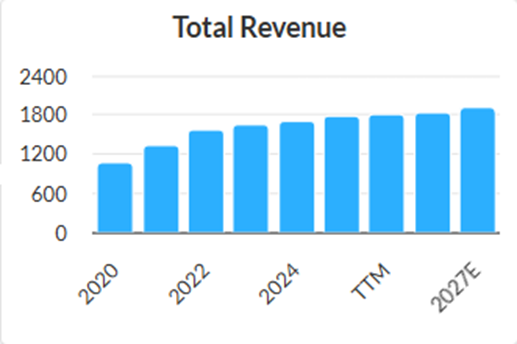
However, this remains a growing business:
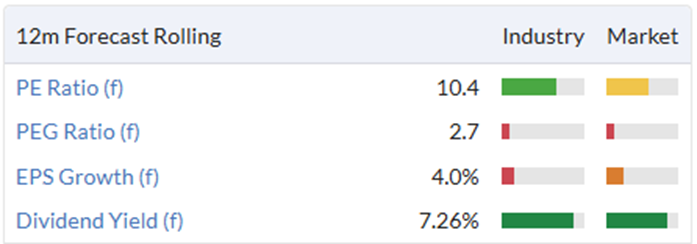
With a phenomenal return on capital, and some interesting value characteristics:
At the H1 results in February, new CEO Clo Moriarty provided an upbeat early read on Q3. She said the company was seeing stronger sales growth in early Q3 following a good Winter Sale and an encouraging response to new Spring ranges, with Q3 trading so far more in line with the first half overall. However, there is no doubt that homewares can be a discretionary purchase, driven by house moves, so this may be a casualty of recent UK Gilt rate rises.
These are the things to watch out for:
- Like-for-like sales growth: the market will want to see whether the Q3 bounce has been sustained
- Full-year profit guidance: Dunelm guided for full-year PBT within a range of £210m–£221m. Any revision to that range, up or down, will be the key market mover.
- Gross margin — FX headwinds and the need for promotional activity have the power to impact trends here.
- Online: digital sales have been a strong growth driver, so any update on delivery improvements will be of note.
- New store initiatives: Dunelm has been rolling out self-service tills across the estate, with plans to install them in over 100 stores by the end of FY26. Progress here will be important to efficiency gains.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

2 comments
Thanks to the Stockopedia Team for changing the daily email alerts to include percentage change instead of pence change, I can retire the calculator app on my iPhone now :-)
It will be interesting to watch the markets response this week. (Ignore the rhetoric - watch the markets).
IMO the breakdown in talks will result in a pullback in markets and many stocks. Question is, will we get higher lows or lower lows?
Oil price might bounce short term but prolonged high prices can be recessionary and then disinflationary in the longer term so at some point traders might start pricing in lower demand. In addition other oil producing regions are ramping up supply to make the most of the high prices (apart from the U.K.).
Borrowing costs (yield on bonds) may rise and value of existing bonds will fall. However at some point (if high prices persist) then traders will start to price in recessionary forces. I’m watching to see if we get new lows or if the market confirms that borrowing costs have peaked
Interesting week ahead.