The Week Ahead (13 – 17 Jul): US Inflation, UK GDP, US Banking, Ocado, Crest Nicholson

It's been a rather challenging week to be an equity investor. Things appeared to be getting back to normal for the major indices before Trump decided that the middle of the NATO summit was a good time to launch another surprise attack on Iran. The S&P 500 naturally took a dive in response on Wednesday:
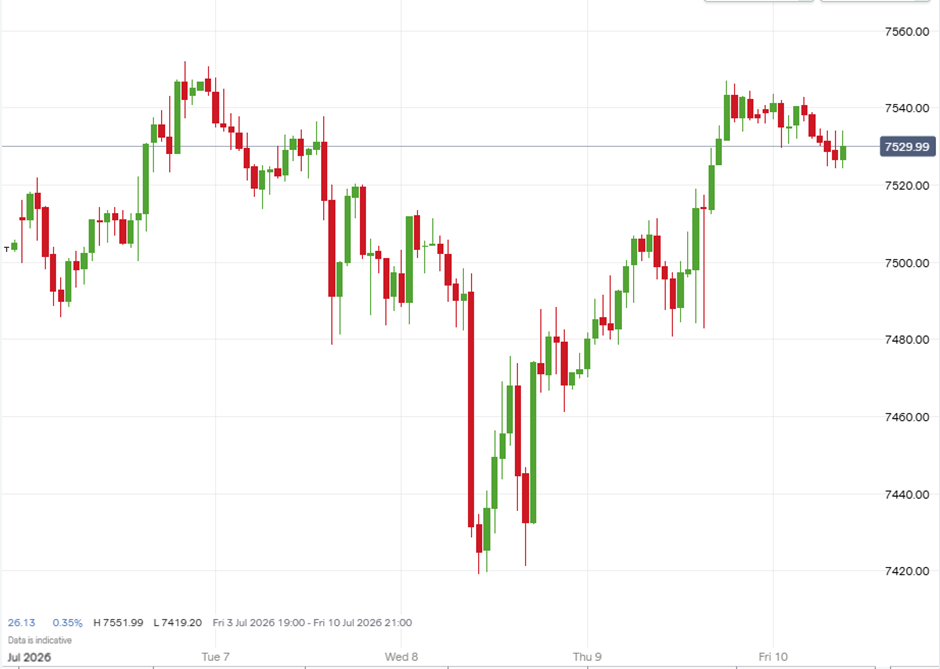
Perhaps the criticism over signing up to an MOU that pretty much gave Iran everything it wanted finally got to him?
Anyway, the markets promptly recovered when Trump claimed that "they want to make a deal so badly", and that the Iranian leadership had actually called him, trying to revive negotiations after the massive wave of US airstrikes. How true this is, or whether it's just another case of TACO, no one knows.
The oil price naturally went the other way:
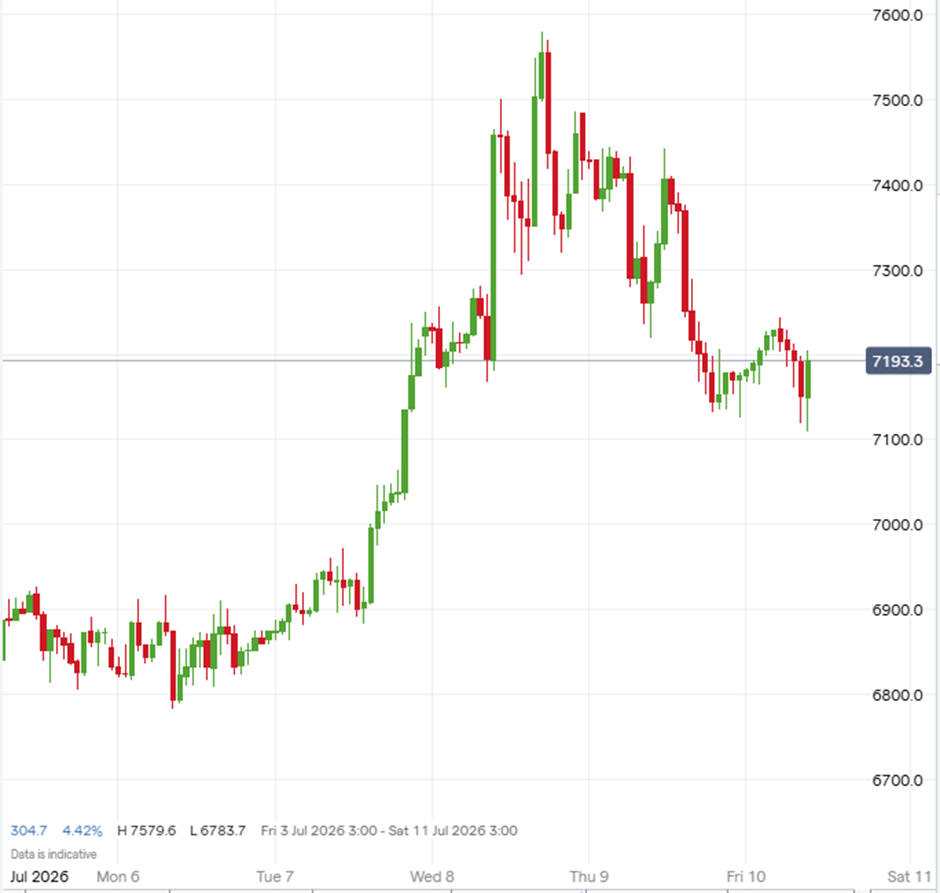
However, the price remains elevated compared to where it started the week, suggesting that the commodity markets don't think it is all over.
In the UK, matters have been complicated by news that Andy Burnham is almost certain to be the next Prime Minister, marking a change in government strategy that may affect UK-focused businesses. UK indices have generally responded in step with global trends this week, suggesting that this news is neither unexpected nor likely to be too onerous for UK equities.
Here's what we can look forward to next week:
Economic Calendar
Monday 13 July |
||
19:00 |
United States |
Monthly Budget Statement |
Tuesday 14 July |
||
04:00 |
China |
Balance of Trade |
07:00 |
Germany |
Wholesale Price Index |
13:30 |
United States |
Inflation |
Wednesday 15 July |
||
03:00 |
China |
GDP Industrial Production Retail Sales |
07:00 |
UK |
Index of Services Manufacturing Production Balance of Trade Industrial Production |
10:00 |
Euro Area |
Industrial Production |
13:30 |
United States |
Producer Price Index |
15:30 |
United States |
EIA Crude Oil Inventories |
Thursday 16 July |
||
07:00 |
UK |
Balance of Trade GDP Index of Services Industrial Production Manufacturing Production |
10:00 |
Euro Area |
Balance of Trade |
13:30 |
United States |
Initial Jobless Claims Retail Sales |
15:00 |
United States |
Business Inventories Pending Home Sales |
Friday 17 July |
||
13:30 |
United States |
Housing Starts Import and Export Prices Building Permits |
14:15 |
United States |
Industrial Production |
15:00 |
United States |
Consumer Sentiment |
US Inflation
We get the US CPI data for June on Tuesday. In May, headline CPI jumped to 4.2% year-over-year (the highest in years, heavily driven by energy sector pressures), while Core CPI was at 2.85%:
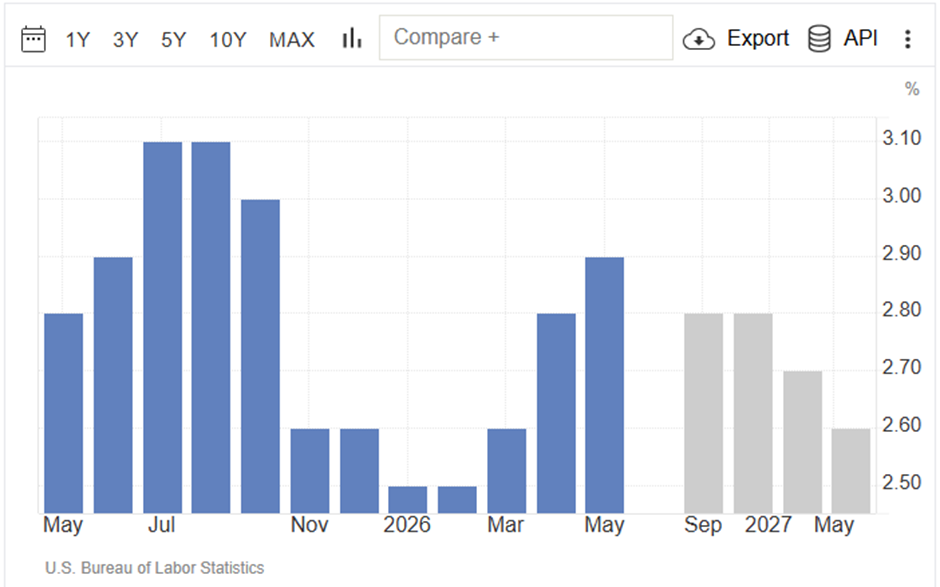
[All charts in this section: Trading Economics]
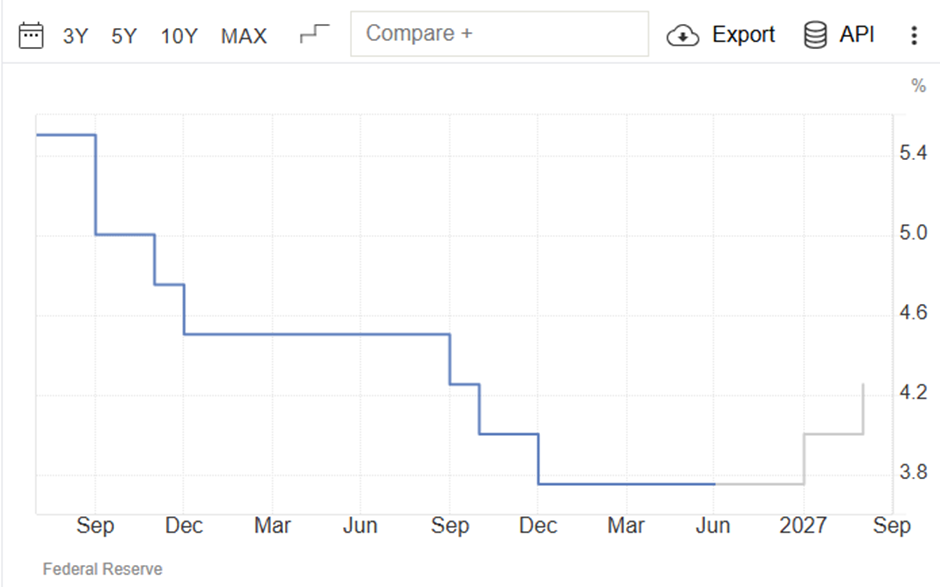
Core Inflation is the one to watch. Even excluding volatile food and energy, inflation has jumped in the US economy in response to global events. Forecasts are for the June core CPI to hover around 2.85% and remain there through the end of the year. However, core inflation coming in hot will almost certainly be an active trigger for a 25bps interest rate hike at the next Fed meeting on 29 July. A rise in rates is not currently forecast until 2027, so this has the power to upset the equities apple cart, if it happens:
UK GDP
The monthly GDP estimate for May will be released on Thursday. Q1 performance was surprisingly strong, with GDP growing by 0.6% in the first quarter, fueled by a 0.8% expansion in the services sector and a 1.6% jump in construction.
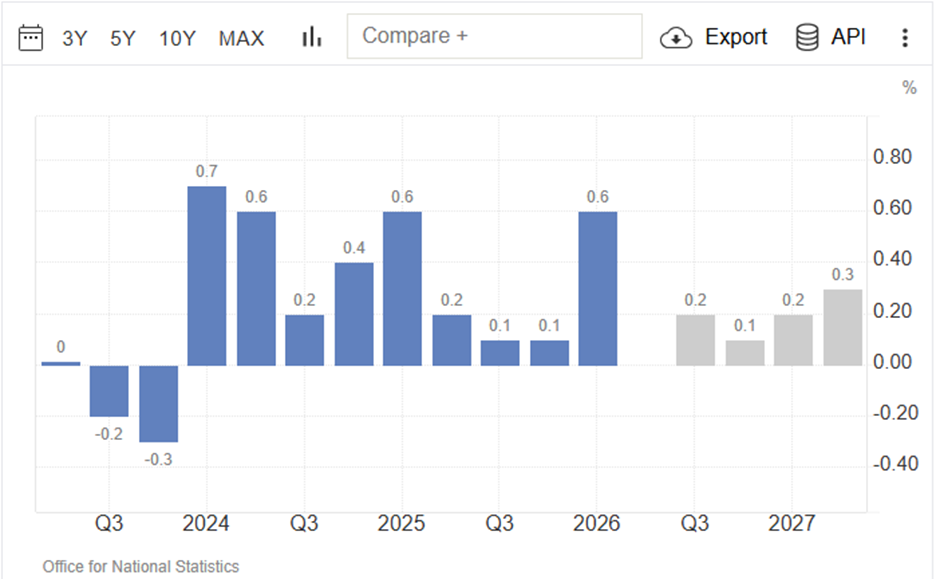
However, individual monthly data began to cool, with April's monthly GDP contracting by 0.1%. Retail and consumer services output will be key, as the risk is that spending on essentials such as energy will reduce discretionary retail spending. Forecasts indicate flat growth in UK business investment in 2026. The construction and manufacturing components of this GDP release will reveal whether companies are freezing capital expenditures amid macro uncertainty. The Bank of England is in a tough spot. Market expectations had previously priced in multiple rate cuts. Still, with energy-driven inflation projected to peak above 4% by winter, near-term interest rate cuts are unlikely unless the May GDP figures are very weak.
Companies Reporting
| Date | UK Trading Updates & AGMS | UK Financial Results | International Financial Results |
|---|---|---|---|
Monday 13 July |
Ampeak Energy (LON:AMP) (AGM) Grafton (LON:GFTU) (TS) Oxford Nanopore Technologies (LON:ONT) (TS) Pagegroup (LON:PAGE) (TS) |
ME International (LON:MEGP) (Interims) | Fastenal Co (NSQ:FAST) |
Tuesday 14 July |
Ashmore (LON:ASHM) (TS) Boohoo (LON:DEBS) (AGM) British Land (LON:BLND) (AGM) Hunting (LON:HTG) (TS) Integrafin Holdings (LON:IHP) (TS) National Grid (LON:NG.). (AGM) Rio Tinto (LON:RIO) (TS) Robert Walters (LON:RWA) (TS) |
Audioboom (LON:BOOM) (Interims) BRCK (LON:BRCK) (Finals) Celebrus Technologies (LON:CLBS) (Finals) Sosandar (LON:SOS) (Finals) Watches of Switzerland (LON:WOSG) (Finals) |
Bank of America (NYQ:BAC) Citigroup (NYQ:C) Telefonaktiebolaget LM Ericsson (STO:ERIC B) (Sweden) Goldman Sachs (NYQ:GS) JPMorgan Chase & Co (NYQ:JPM) Wells Fargo & Co (NYQ:WFC) |
Wednesday 15 July |
Antofagasta (LON:ANTO) (TS) 'Artisanal Spirits (LON:ART) (TS) Barratt Redrow (LON:BTRW) (TS) Bloomsbury Publishing (LON:BMY) (AGM) Burberry (LON:BRBY) (AGM) Ferrexpo (LON:FXPO) (TS) Galliford Try Holdings (LON:GFRD) (TS) ICG (LON:ICG) (AGM) Wynnstay Properties (LON:WSP) (AGM) |
Cohort (LON:CHRT) (Finals) James Cropper (LON:CRPR) (Finals) Gore Street Energy Storage Fund (LON:GSF) (Finals) |
ASML Holding NV (AMS:ASML) (Netherlands) Blackrock (NYQ:BLK) Cintas (NSQ:CTAS) First Horizon (NYQ:FHN) J B Hunt Transport Services (NSQ:JBHT) Johnson & Johnson (NYQ:JNJ) Morgan Stanley (NYQ:MS) M&t Bank (NYQ:MTB) Omnicom (NYQ:OMC) PNC Financial Services (NYQ:PNC) Skandinaviska Enskilda Banken AB (STO:SEB A) (Sweden) Svenska Handelsbanken AB (STO:SHB A) (Sweden) United Airlines Holdings (NSQ:UAL) |
Thursday 16 July |
Autotrader (LON:AUTO) (AGM) DCC (LON:DCC) (AGM) Diploma (LON:DPLM) (TS) Dunelm (LON:DNLM) (TS) Experian (LON:EXPN) (TS) Helical (LON:HLCL) (AGM) Johnson Matthey (LON:JMAT) (AGM) Premier Foods (LON:PFD) (AGM) Qinetiq (LON:QQ.). (AGM) RS (LON:RS1) (AGM) SSE (LON:SSE) (Q2 & AGM Trustpilot (LON:TRST) (TS) Wise (LON:WISE) (TS) |
Crest Nicholson Holdings (LON:CRST) (Interims) Ocado (LON:OCDO) (Interims) |
Alcoa (NYQ:AA) Abb (SWX:ABBN) (Switzerland) Abbott Laboratories (NYQ:ABT) Atlas Copco AB (STO:ATCO A) (Sweden) Biogen (NSQ:BIIB) Bankinter SA (MCE:BKT) (Spain) Blackstone (NYQ:BX) Citizens Financial (NYQ:CFG) Freeport-McMoRan (NYQ:FCX) General Electric Co (NYQ:GE) Investor AB (STO:INVE B) (Sweden) Intuitive Surgical (NSQ:ISRG) Kinder Morgan (NYQ:KMI) Netflix (NSQ:NFLX) Prologis (NYQ:PLD) PPG Industries (NYQ:PPG) Publicis Groupe SA (EPA:PUB) (France) Snap-On (NYQ:SNA) State Street (NYQ:STT) Seagate Technology Holdings (NSQ:STX) Tele2 AB (STO:TEL2 B) (Sweden) Truist Financial (NYQ:TFC) Tenet Healthcare (NYQ:THC) Unitedhealth (NYQ:UNH) US Bancorp (NYQ:USB) Webster Financial (NYQ:WBS) |
Friday 17 July |
Pulsar Helium (LON:PLSR) (AGM) Technology Minerals (LON:TM1) (AGM) Thalia Therapeutics (LON:THAT) (AGM) United Utilities (LON:UU.). (AGM) |
Assa Abloy AB (STO:ASSA B) (Sweden) Danske Bank A/S (CPH:DANSKE) (Denmark) Epiroc AB (STO:EPI A) (Sweden) Fifth Third Bancorp (NYQ:FITB) Interactive Brokers (NSQ:IBKR) Novartis AG (SWX:NOVN) (Switzerland) Roper Technologies (NSQ:ROP) Sandvik AB (STO:SAND) (Sweden) Skanska AB (STO:SKA B) (Sweden) SKF AB (STO:SKF B) (Sweden) Swedbank AB (STO:SWED A) (Sweden) Telia AB (LON:TEE^K07) (Sweden) Travelers Companies (NYQ:TRV) Volvo AB (STO:VOLV A) (Sweden) |
The bulk of the UK news flow at this time of year remains associated with AGM's, which often have accompanying trading statements. International newsflow looks to be picking up, including several large European companies reporting.
As usual, let us know via the comments if you think we've missed anything of note.
US Banking Sector
It is US bank reporting week, with all three Mega-Cap Diversified Banks (JPMorgan Chase, Bank of America, Citibank) reporting on Tuesday, together with Goldman Sachs. Wednesday sees the second investment bank titan, Morgan Stanley, release results. Here's what to look out for:
JPMorgan Chase & Co (NYQ:JPM)
The EPS consensus has been nudging higher recently, suggesting these results will be strong. Look for updates on their loan growth portfolio, which has accelerated faster than historical averages so far this year. Their net interest income guidance for the remainder of 2026 will heavily dictate the stock price movement.
Bank of America (NYQ:BAC)
Analysts expect steady, quiet growth, though its consumer-facing banking division faces minor pressure from flattening credit card spending. Global markets activity will be the engine here. Watch how much market share their equities trading desk clawed back and look for updates on capital allocation following late-June's successful Dodd-Frank stress test results.
Citigroup (NYQ:C)
Citigroup has seen the highest positive analyst revisions in the last quarter, up 4.7 %. The market has heavily discounted its stock against expected improvements in its Return on Tangible Common Equity. Execution of the ongoing restructuring program will be key. Any positive surprise in corporate banking fee income or lower-than-expected restructuring charges will likely move the stock price.
Goldman Sachs (NYQ:GS)
Expect stellar numbers from the capital markets division. The red-hot first-half IPO rush, headlined by the $86 billion SpaceX IPO, will have generated massive windfalls. Banks raked in an estimated $500 million in cumulative fees from that single deal. The Vampire Squid will have had its blood funnel hoovering up its share of those.
However, traditional M&A advisory remained underwhelming due to persistent geopolitical uncertainties. This may take the shine off otherwise strong reporting.
Morgan Stanley (NYQ:MS)
Morgan will be subject to the same factors as Goldman. However, its stickier wealth-management inflows may provide a more stable outlook.
Others
A few other super-regional and specialised commercial lenders are also likely to report next week, such as Wells Fargo & Co (NYQ:WFC) US Bancorp (NYQ:USB), M&t Bank (NYQ:MTB), Citizens Financial (NYQ:CFG) , State Street (NYQ:STT) and Bank Of New York Mellon (NYQ:BNY).
Across the sector, pay attention to the guidance on share buybacks. Because the Federal Reserve's annual stress test results in late June confirmed deep resilience across both the "Global Systemically Important Banks" and larger regionals, any bank that fails to announce an increased dividend or a beefed-up share repurchase program will likely be penalised by the market.
Ocado (LON:OCDO)
I think it is fair to say it has not been a great five years for the company:
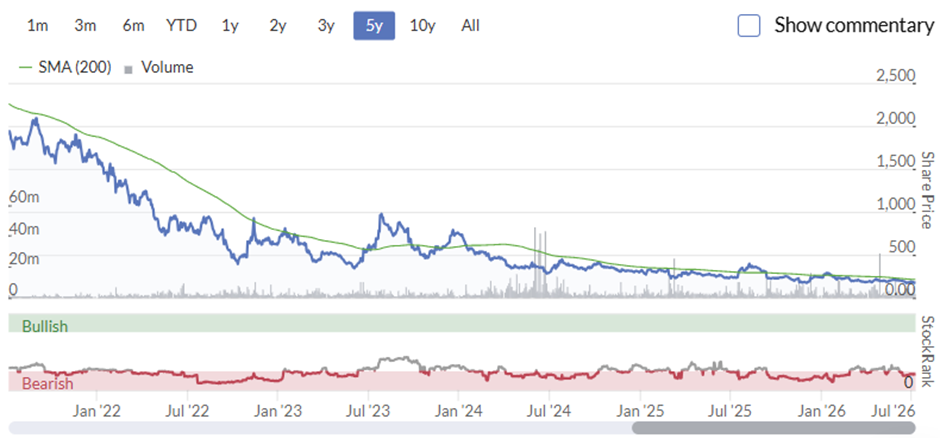
It has been continually loss-making, something that is not predicted to end any time soon:
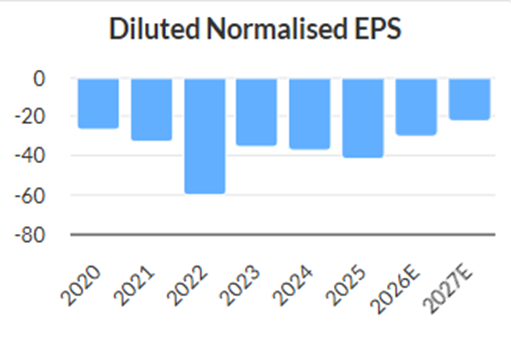
CEO Tim Steiner's ability to raise capital from the market to continue funding these losses continues to amaze me. This is one of the reasons the recent announcement detailing his planned leadership transition (stepping down to a Founder role by the start of the 2028 financial year) leaves the company at somewhat of a crossroads. Management previously set an ambitious goal to deliver roughly £150 million in cost savings across the year and turn free cash flow positive by the second half of 2026. Analysts are highly sceptical of this timeline. In the upcoming results, watch the free cash outflow figures closely. If the cash burn remains high, concerns regarding a potential capital raise or further investor dilution down the line will inevitably spike.
Other things to look out for are:
- Technology Solutions: This is Ocado's primary valuation engine, where it charges international third-party retailers to use its proprietary automated robotic "grid" systems. Investors need to see a robust pipeline of new CFC openings. If more partners delay or scale back their automation rollouts, Ocado's valuation will face immediate downward pressure.
- Ocado Retail: The UK consumer-facing grocery business, which is jointly owned with Marks & Spencer, has been the operational highlight of the business recently. It has successfully leveraged M&S's improved quality perception to acquire active customers and expand market volume share. Despite solid top-line revenue growth, this division has struggled to cross the threshold into true profitability. Investors will want to see if rising volumes have been enough to offset structural investment drags and marketing acquisition costs.
Crest Nicholson Holdings (LON:CRST)
The UK housebuilding sector continues to fascinate me. It is either a huge opportunity to buy cyclical businesses at mult-year lows, or a series of value traps which have overpaid for their land banks, and shareholders will be picking up the tab.
Crest Nicholson's interim results were originally scheduled for late April but were deliberately pushed back to mid-July. The delay was to give the housebuilder extra time to finalise an orderly covenant reset and conclude constructive discussions with its lenders regarding temporary covenant relaxation. When this was announced in April, the shares suffered a significant decline from worries about this, despite an already weak trend:
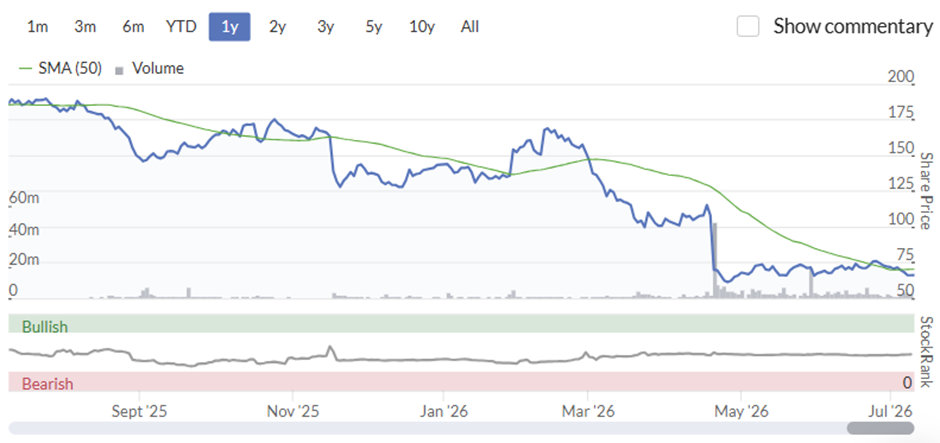
That Covenant waiver has not yet been forthcoming. However, we would expect any announcement to coincide with the appearance of results, or non-appearance and suspension. It is this binary nature of the outcome that I find particularly interesting and have a small controlled risk position here. It seems to me that they will either survive and recover from recent falls over time, or they won't, and the attraction of someone else taking the ultimate downside is strong.
Assuming they get the waiver, the market will want explicit confirmation that the covenant reset process has been completed with lenders and will look for the specific new terms or margins attached to their debt facility.
Other things to watch:
- Cost-Cutting Progress: The company has been navigating an aggressive "year of transition" aimed at restructuring the business to protect its bottom line. Investors will want to see whether recent overhead reductions and their strategic shift toward mid-market homes have begun to stabilise margins, or whether sticky build-cost inflation continues to erode profitability.
- Reservation Trends: While the structural headwinds are real, recent UK housing market indicators have shown early signs of stabilisation. The market will be particularly interested in the private reservation rate per site per week and the total value of the forward order book heading into the second half of the year.
[Disclosure: Mark has a long position in Crest Nicholson Holdings (LON:CRST)
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

10 comments
Re: banks, I hold Lloyds Banking (LON:LLPC) which gives me a decent yield from a reasonably conservatively run institution. I may add more at some point but remind myself that higher interest rates are bad for preference shares.
Re: geopolitics, I thought the following from Sky News was useful. It seems there is more than one route through the Strait of Hormuz and some tankers are switching off their tracking devices so the stats may not be 100% accurate. Plus there also appears to be a ferrying type of service between larger tankers either side of the 'crunch point'. Saudi Arabi looking to expand pipeline capacity to the Red Sea, UK buying jet fuel from the US and Germany signing a long-term deal with Canada for LNG. None of this is ideal but far from the disaster scenario of $200 per barrel.
https://tinyurl.com/zhryuhhz
Thanks all. Should have updated all those.
I've no idea why UK stocks beginning with C are defaulting to Citigroup. When I actually put Citigroup in the international bit, it defaulted to something else. Very annoying!
Thanks Mark. I believe Audioboom (LON:BOOM) will provide half year results this week, but I'm not sure which day. (A few weeks back they said 'on or around 16th July '. ) Also, I don't think Zotefoams (LON:ZTF) results are due until August, possibly 5th. Enjoy your weekend.
good write up Mark - will be very interesting to see how US banks do next week.
I'd put very interesting in capital letters. More important than some FED peanut raises etc and economic data which gets revised all the time.
The Banks will pull together so we will not know where their 'stresses' are. Need to tow Mr T's line and it's the great anniversary of 250 years of clearing the tax yoke of a British King.
All talk is of an AI 'bubble' and for 'value' followers has credence, but maybe 'its different this time' as they actually have cash coming, but maybe some 'rhyming' so a correction on the cards - 'healthy destruction' someone said.
If our portfolios are in good companies, turning a profit and have some moats for the future its all we can do. Diversify into Europe/UK and the US. I would love have access to Honk Kong and Japan but not through ETF's.
You only lose money when sell so if a good company then HODL.
I have 1 share in Space Exploration Technologies (NSQ:SPCX) (hero) because I actually believe it has substance and will be volatile once the funders make their dosh and move on.
Optimus robots - I want one - forget driving Teslas Astons Bentleys but a robot - housework, ironing, washing, driving, cleaning, gardening, and the Japanese are making them look nice. Plus in old age - can you imagine, I can.
Banks will play ball with Mr T next week and any 'cracks' but who would put their head above the parapet :)
Iran needs to get back in its box. A nut job islamic state cannot have weapons of mass distraction (spell check seems to be compromised). Give us dates or whatever and go away nothings.
I agree there is going to be value in UK housebuilders at some stage and indeed one house see Redrow Barrett as massively undervalued given it indulges in a huge buy back. Speaking as someone who sold out of Crest some while back I see it along with Vistry as frequently accident prone and with this in mind ( at some stage) there will be viable bottom fishing. Not sure we are there yet as I see land banks as facing write offs and who knows what Burnham and his cohorts will do about Starmer's unrealistic housing targets. To me the accent will be on social and affordable homes so yep look at the margins being squeezed further with the combination of building cost inflation and shortgage of skilled workers. Nothing is helped by the constant (understandable) legislation demanding new builds include renewables etc as part of a basic package.
Is this all yet discounted well perhaps not but some companies have strong balance sheets so can cope with write offs but thinner margins and lack of demand for larger properties remain the picture
Citigroup (NYQ:C) is definitely not a UK company! (reporting next wednesday)
ME International (LON:MEGP) interims are Monday. Let's see if the bad luck continues!
Been a howler for me second time around as you say going to be interesting to see if the rot has been halted if it hasn't you would think someone would hoover it up but guess difficult with the main man holding 30% ish.
I think Trustpilot have a TU middle of next week