The Week Ahead (14-18 Sep): Kevin Warsh's moment of truth

Next Wednesday: Fed Interest Rate Decision
The odds of a Fed rate hike next Wednesday had already moved higher, prior to the release of the August inflation numbers today (Friday 11th).
Swap traders had been pricing in a 70% chance of a hike. That has now shifted to 90%.
The reason is simple: the inflation numbers today included higher-than-expected core CPI. The debate among economists has therefore shifted to how many rate hikes the Fed should make in the short-term, rather than whether or not they should hike next week.
In today’s report, the headline inflation rate came in at 3.4%, as expected.
The core inflation rate is 2.4%, also in line with expectations.
But due to rounding, this hides the fact that monthly core inflation was higher than expected (0.3% vs. 0.2%).
This might not seem like a very big difference, but the Federal Open Market Committee had already been strongly contemplating a hike. At the last meeting: three of the 12 voting members (not including Chair Kevin Warsh) voted to increase rates from the current 3.75%.
There are of course many factors at play, but most of them seem to point towards the first hike since 2023.
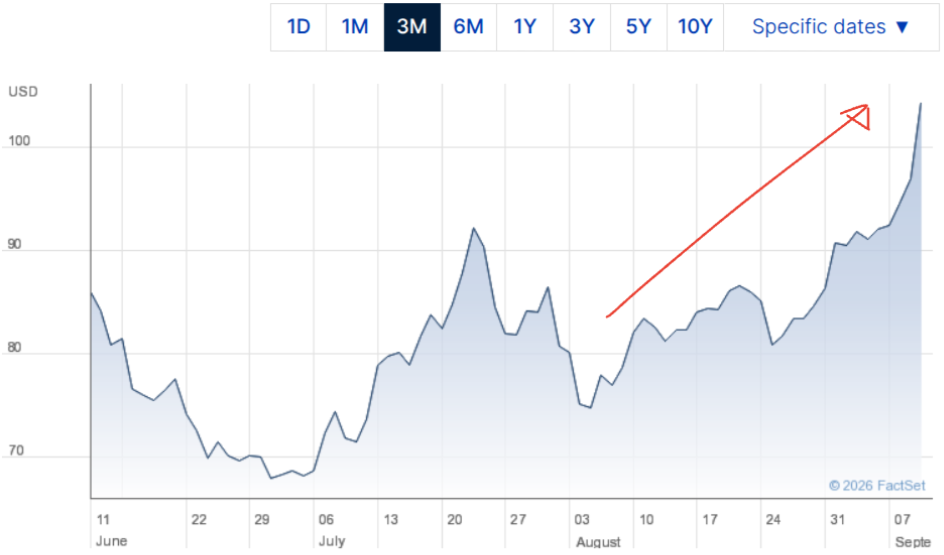
Oil price: the oil price has surged higher since the last FOMC vote at the end of July. While the Fed can’t reopen the Strait of Hormuz by itself, the generalised inflation caused by a supply shock can increase inflation expectations - and the Fed does attempt to manage inflation expectations. The increase in the price of oil is not limited to European Brent crude; West Texas Intermediate has also reached $100 in recent trading sessions.
Political intervention: President Trump has been making calls this week for a “patriotic” rate cut. Importantly, Kevin Warsh is his appointee: the chosen replacement for his monetary nemesis, Jerome Powell.
However, since his appointment, Warsh has maintained an appearance of independence from the President, and taken his own path in terms of the Fed’s communication with the media and general public.
If Kevin Warsh votes to raise rates, he risks the ire of the President. But he will also go a long way towards demonstrating the continued independence of the Federal Reserve.
Above-target CPI and PCE, both “headline” rates and core:
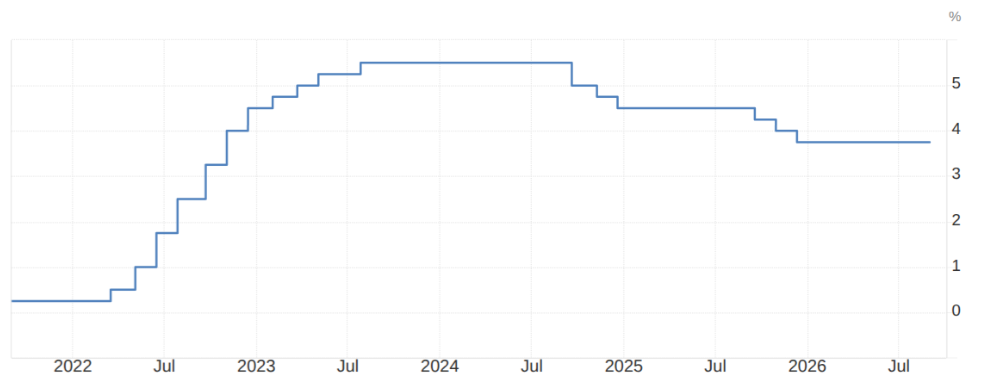
The Fed has held rates steady all year, having cut them from a high of 5.5% in mid-2023:
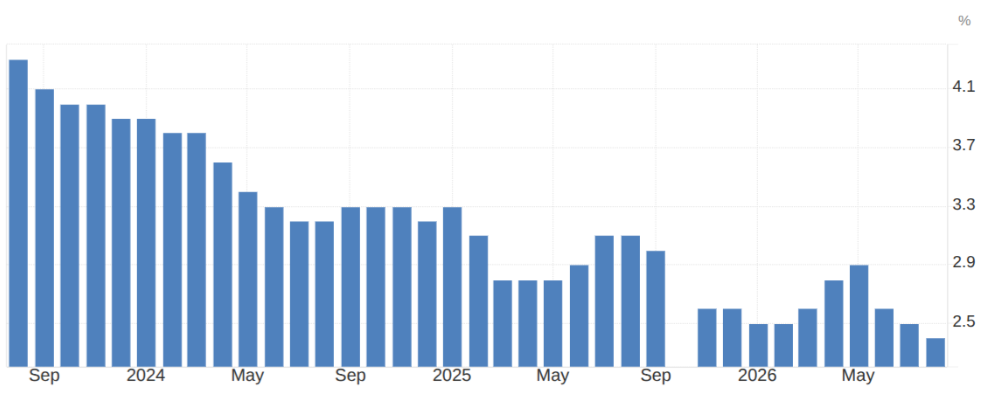
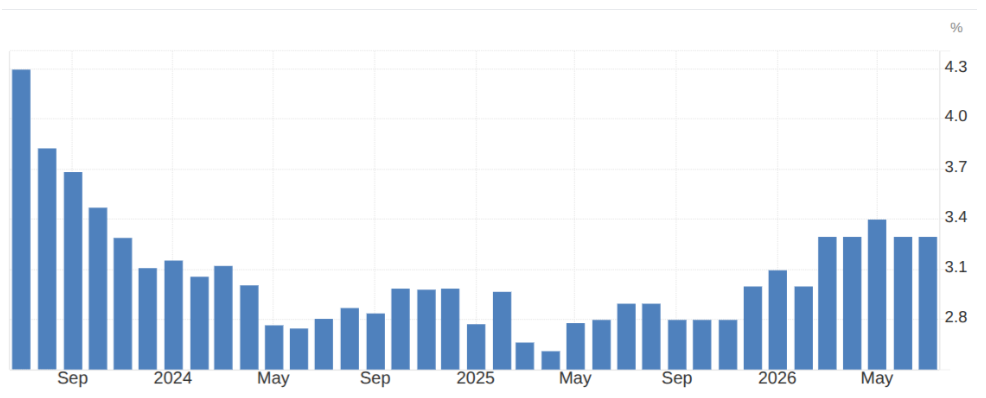
But inflation hasn’t played ball. Even excluding food and energy, both the CPI and the PCE (the Fed’s preferred measure of inflation) are ahead of its 2% target.
There has been movement in the right direction, for sure, but not quite enough.
Core CPI over the past 3 years:
Source: Trading Economics
Core PCE, a more sophisticated measure, is worse at 3.3% (the August reading has not been published yet):
Source: Trading Economics
So there is no perspective from which the Fed is currently achieving its inflation target. The 2% target has not been reached since Covid-era deflation.
Bond yields: government bond yields have been rising in a manner that raises serious questions about fiscal sustainability. The US 30-year yield has continued to rise since the last FOMC vote, for example:
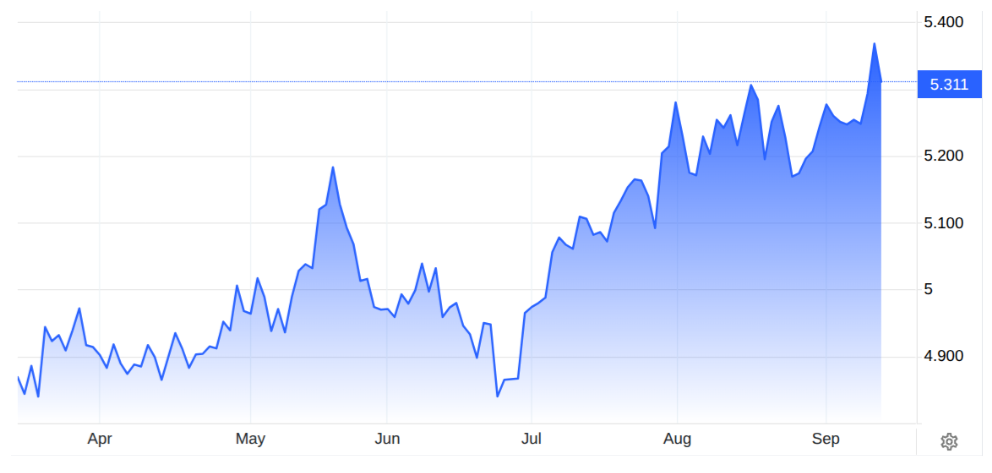
Source: Trading Economics
For equity investors, rate hikes are almost never a positive factor in the short-term. Interest rates are, after all, the financial gravity which in theory dictates the price of everything else.
For bond investors, however, even those at the long end of the curve, short-term rates are important when it comes to those inflation expectations we talked about earlier. Higher short-term rates help to signal that inflation will be controlled, which in turn improves the real returns on long-term bonds.
For what it’s worth, I’m all in favour of Kevin Warsh voting to hike rates next week. It will demonstrate that he considers current inflation rates to be unacceptable, whatever the cause. It will also prove that he is willing to do the opposite of what the President wants him to do. At the beginning of his tenure, these would be valuable signals for the markets.
Next Thursday: BoE Interest Rate Decision
It will also be a busy week for the UK’s central bankers, but they are expected to keep rates unchanged.
The possible curveball will be out on Wednesday morning: UK inflation data.
MPC members will cast their votes later that day, and their collective decision and their views will be published the following day.
So keep an eye out for inflation data on Wednesday morning. Similar to the US, the UK’s inflation rate has been running at 2.9%, ahead of target.
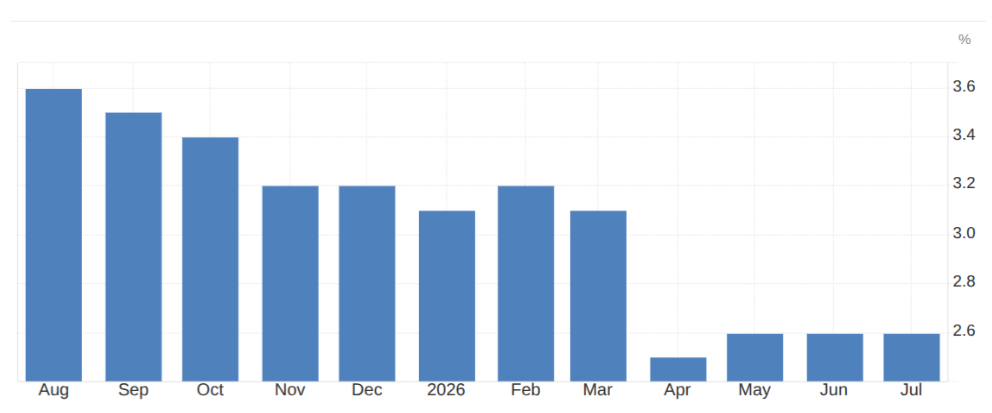
At the last meeting, three of the nine members of the MPC voted to raise rates. But most of the MPC thought that there was “little evidence” of “material second-round effects in price and wage-setting”, arising from higher energy prices. It will be interesting to see if they maintain this view next week.
Economic Calendar
| Date | Country | Event |
|---|---|---|
Monday 14th September | Nothing of major significance scheduled. | |
Tuesday 15th September | ||
07:00 | UK | Unemployment Rate |
Wednesday 16th August | ||
07:00 | UK | Inflation Rate |
13:30 | US | Retail Sales |
19:00 | US | Fed Interest Rate Decision |
Thursday 17th September | ||
12:00 | UK | BoE Interest Rate Decision |
13:30 | US | Initial Jobless Claims |
13:30 | US | Housing Starts |
Friday 18th September | ||
07:00 | UK | Retail Sales |
Companies Reporting
| Date | UK Trading Updates & AGMS | UK Financial Results | International Financial Results |
|---|---|---|---|
Monday 14th September | Power Probe (LON:PWR) (TU) | Fusion Antibodies (LON:FAB) (Finals) GlobalData (LON:DATA) (Interims) Greencoat Renewables (LON:GRP) (Interims) HgCapital Trust (LON:HGT) (Interims) Big Technologies (LON:BIG) (Interims) Keystone Law (LON:KEYS) (Interims) M P Evans (LON:MPE) (Interims) Pantheon Resources (LON:PANR) (Interims) | None of major significance scheduled. |
Tuesday 15th September | B90 Holdings (LON:B90) (AGM) BRCK (LON:BRCK) (AGM) Lindsell Train Investment Trust (LON:LTI) (AGM) Solid State (LON:SOLI) (AGM) | accesso Technology (LON:ACSO) (Interims) Alumasc (LON:ALU) (Finals) EKF Diagnostics Holdings (LON:EKF) (Interims) Everplay (LON:EVPL) (Interims) Eagle Eye Solutions (LON:EYE) (Finals) Fintel (LON:FNTL) (Interims) MJ GLEESON (LON:GLE) (Finals) hVIVO (LON:HVO) (Interims) Harworth (LON:HWG) (Interims) IP (LON:IPO) (Interims) Kier (LON:KIE) (Finals) MPAC (LON:MPAC) (Interims) Personal group (LON:PGH) (Interims) Springfield Properties (LON:SPR) (Finals) | None of major significance scheduled. |
Wed 16th September | Babcock International (LON:BAB) (AGM) BTG Consulting (LON:BTG) (AGM) Frasers (LON:FRAS) (AGM) Games Workshop (LON:GAW) (AGM) Gore Street Energy Storage Fund (LON:GSF) (AGM) Moonpig (LON:MOON) (AGM) | Facilities by ADF (LON:ADF) (Interims) Amcomri (LON:AMCO) (Interims) Artisanal Spirits (LON:ART) (Interims) Barratt Redrow (LON:BTRW) (Finals) City of London Investment (LON:CLIG) (Finals) Pan African Resources (LON:PAF) (Finals) Supermarket Income REIT (LON:SUPR) (Finals) | None of major significance scheduled. |
Thursday 17th September | Galantas Gold (LON:GAL) (AGM) Liontrust Asset Management (LON:LIO) (AGM) Mycelx Technologies (LON:MYX) (AGM) Sosandar (LON:SOS) (AGM) Supreme (LON:SUP) (AGM) SysGroup (LON:SYS) (AGM) | Next (LON:NXT) (Interims) Beauty Tech (LON:TBTG) (Interims) Trufin (LON:TRU) (Interims) | None of major significance scheduled. |
Friday 18th September | Inspiration Healthcare (LON:IHC) (TU) | None of major significance scheduled. | None of major significance scheduled. |
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

5 comments
I suspect with the Tide potentially receding due to the Mid Term elections Warsh will have an eye on his future standing rather than the whims of a possibly lame duck President? Interesting to see.
Jerome Powell was also a Trump appointment, during his first term.
Trump tried to bull him into reducing rates and he refused.
Interesting to see what happens with Mark 2?
2 of my holdings report this next week: HgCapital Trust (LON:HGT) interims and Supermarket Income REIT (LON:SUPR) finals. The former is recovering after the software sell-off in Jan/Feb and the latter pays a healthy 7% yield.
As per previous comments, I wish the central bankers would just get on with raising rates, head off inflation and force governments to do something about the debt piles. It's not just a US problem remember....
I agree Warsh needs to act to increase interest rates. Hard to see how taking no action ties in with a likely further rise in inflation and the Gas price. Whilst totally incoherent the Trump bribe would hugely stoke inflation and need rates ( based on any accepted/ conventional economics) to move sharply higher although one could argue the worst effects of this would not be felt until after DT has left office.
We are also going to see inflation in the UK move markedly higher if one bases assessements on the oil price and that at the pumps. I think a .25% increase in the base rate is needed given lower oil prices do not seem to be a short term expectation and further prices rises as a consequence of the blazing hot weather are ' baked in'
If Kevin Warsh does not raise rates next week he will have lost credibility just as he has starts his tenure.
I think the bond market will assume he is not serious about controlling inflation and the yield on medium and long bonds will rise. The opposite of what Trump wants.
It is not the first time that Trump's actions will have the opposite effect of what he thought they would.