The Week Ahead (14-18 Apr): US Financials, SBRY, CNC, BILN, HTG

After the huge volatility of the last week, investors will be hoping for calmer waters over the next week. The reality is that many of the moves in stocks have borne little correlation to any changes in fundamentals. In small caps, the biggest movers have been the popular stocks as individual investors get stopped out or panic-sell on the down days, before buying back into the very same few stocks on the up days. In mid and large caps, in both the US and UK, it is the high-beta stocks that have been seeing the biggest moves, suggesting funds are trading indices rather than individual stocks. If we get a period of US government policy stability, then we will see stocks more rationally priced according to stock-specific newsflow rather than sentiment-driven trading.
Here’s what we can look forward to next week:
Economic Calendar
Monday 14th |
||
Tuesday 15th |
||
07:00 |
UK |
Unemployment Rate |
Wednesday 16th |
||
03:00 |
China |
Industrial Production GDP Retail Sales Inflation |
07:00 |
UK |
RPI & CPI Inflation |
10:00 |
Europe |
CPI Inflation |
13:30 |
United States |
Retail Sales |
Thursday 17th |
||
13:15 |
Europe |
ECB Rate Decision |
13:30 |
United States |
Housing Starts Initial Jobless Claims |
Friday 18th |
||
00:30 |
Japan |
Inflation |
A relatively quiet week for economic news. We will see inflation data from the UK, Europe, China and Japan. The US and China also have Retail Sales data. It will be interesting to see how consumers in the world’s largest economies have responded to recent US policy announcements.
The only interst rate decision is in the Euro Area. The ECB lowered interest rates by 25bps on 6th March. At the time, the ECB said:
Staff now see headline inflation averaging 2.3% in 2025, 1.9% in 2026 and 2.0% in 2027. The upward revision in headline inflation for 2025 reflects stronger energy price dynamics. For inflation excluding energy and food, staff project an average of 2.2% in 2025, 2.0% in 2026 and 1.9% in 2027.
However, with oil prices having fallen since on Trump tariff announcements and the economic impact of those on the Euro Area increasing the recession risk, the FT reports that the ECB expected to cut rates again in April and June.
Companies Reporting
UK Trading Updates |
UK Financial Results |
International Financial Results |
|
Monday 14 Apr |
Barratt Redrow |
Concurrent Technologies (Finals) |
Goldman Sachs |
Tuesday 15 Apr |
IntegraFin Holdings |
S&U (Finals) Everyman Media (Finals) Tinybuild (Finals) Billington Holdings (Finals) |
Johnson & Johnson Bank of America Citigroup Interactive Brokers United Airlines |
Wednesday 16 Apr |
Hunting |
M Winkworth (Finals) WH Smith (Interims) |
Abbott Laboratories US Bancorp Travelers Companies Heineken Moncler |
Thursday 17 Apr |
Rentokil Initial |
Sainsbury’s (Finals) |
UnitedHealth Hermes International Blackstone Charles Schwab DR Horton |
Friday 18 Apr |
Schlumberger |
US Financials
Goldman Sachs
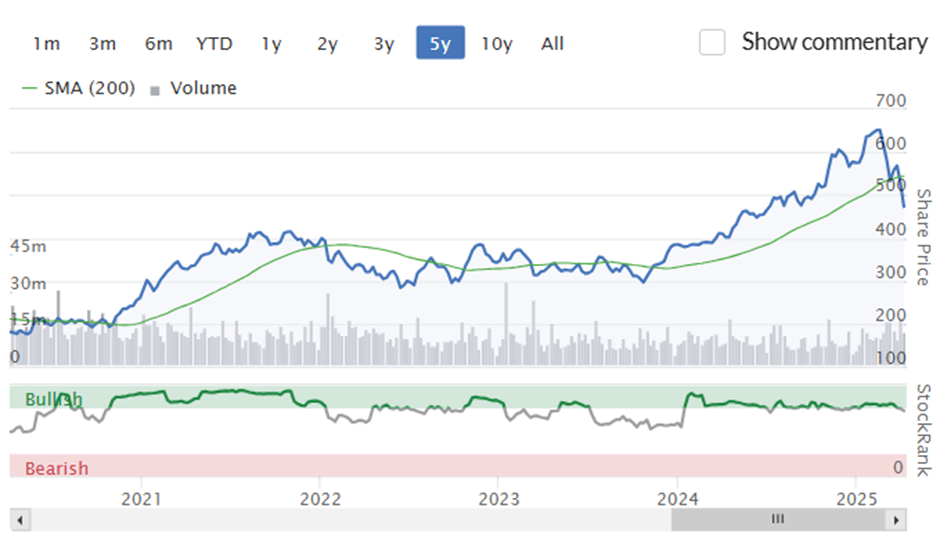
Banking will be a key focus next week in the US. Investment bank Goldman Sachs reports Q1 Earnings on Monday. Compared to UK investment banks, the ‘Vampire Squid’ has certainly been doing well, reflecting the strength of US markets:
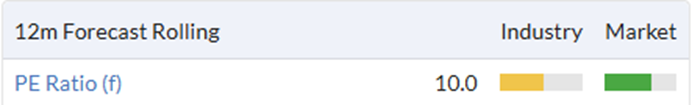
The company is still on a modest rating:
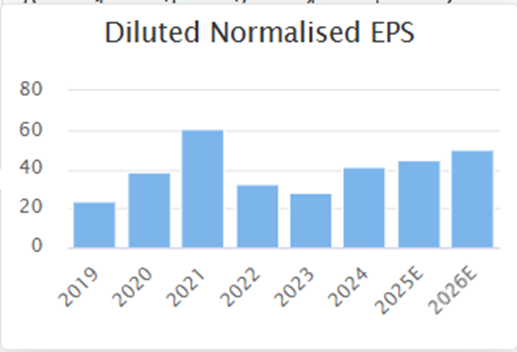
However, those returns have come mainly from a re-rating, not earnings growth. 2025 EPS is barely above 2020 levels:
This makes the company vulnerable to current market conditions, as we have seen from the more recent sell-off. These market concerns have only just started to be reflected in the EPS trend:
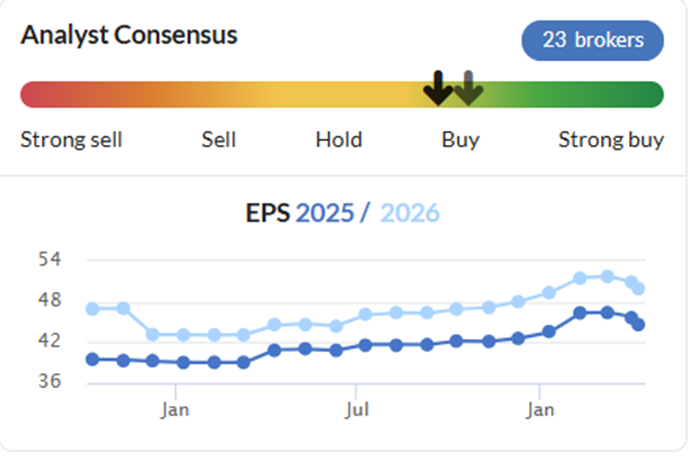
Investors will be looking to determine whether this is the start of a new trend or whether the company can fill its ‘blood funnel’ in bad times as well as the good.
Bank of America - Citigroup - US Bancorp
Three US mainstream banks report next week. It has been said in the past that the C in Citibank is a soft one. However, in this case, it appears to be the pick of the bunch, especially on the key metric of Price-to-Tangible-Book:
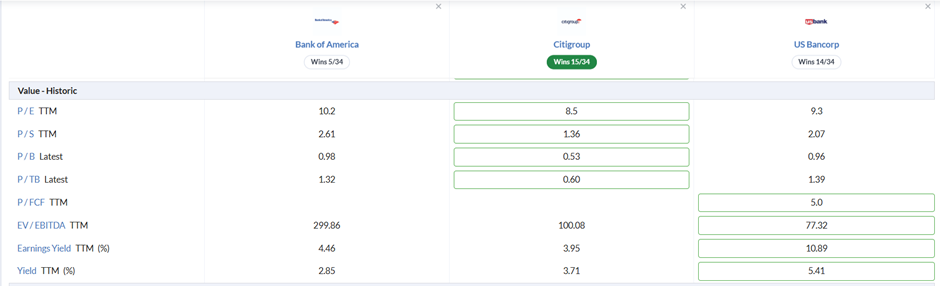
Cheapness won’t be the only thing on investors’ minds. The US is at risk of entering a major recession for the first time since the Great Financial Crisis. Unlike the brief COVID-19 decline in GDP, it doesn’t look like the Fed will rush to the rescue as inflation concerns will remain, especially driven by tariff-related price rises. This means that news on credit quality and capital ratios will probably be as important as earnings for the US banking sector this week.
Interactive Brokers
Cheap share trading service Interactive Brokers has had a volatile quarter for its stock price:
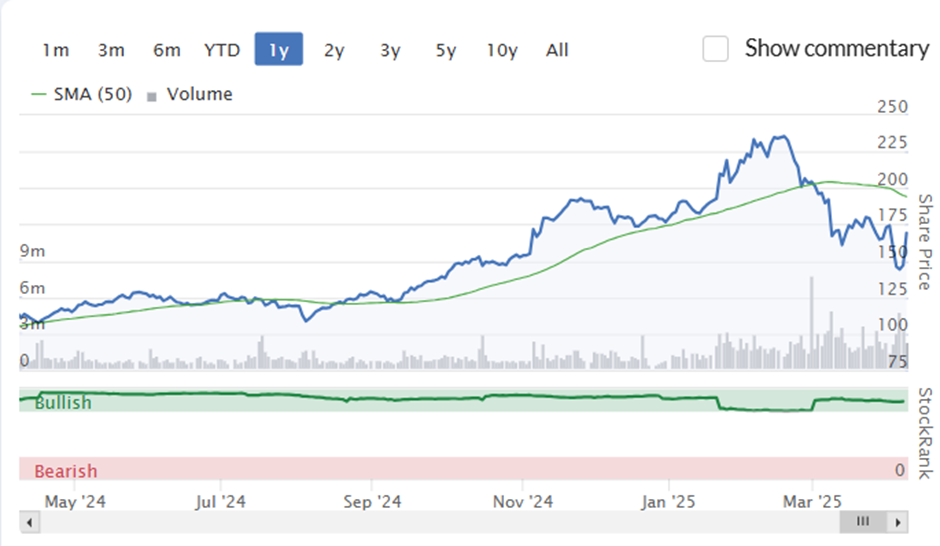
It’s not cheap on 19x forward earnings. However, I can’t help but feel that recent market volatility may actually drive more share trading, which will benefit this type of company. If they confirm this on Tuesday the shares may recover any recent falls.
Charles Schwab
Brokerage giant Charles Schwab also reports Q1 results next week. Shares here have been more rangebound in the past year:
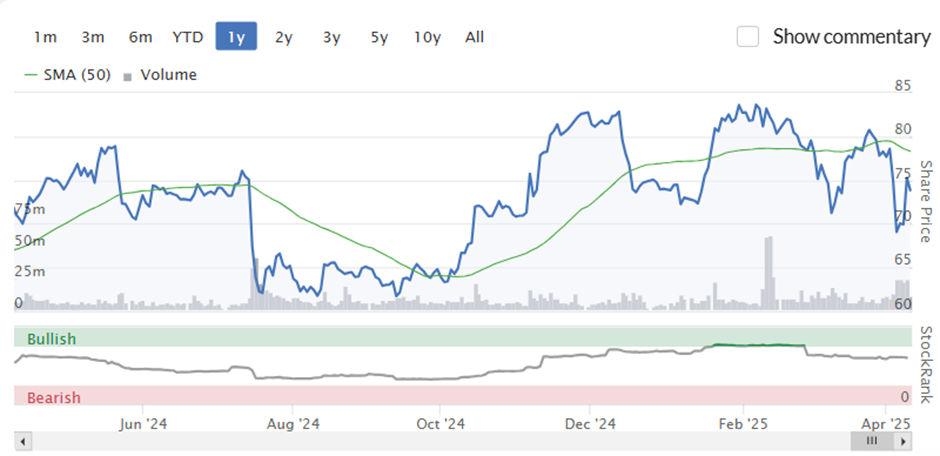
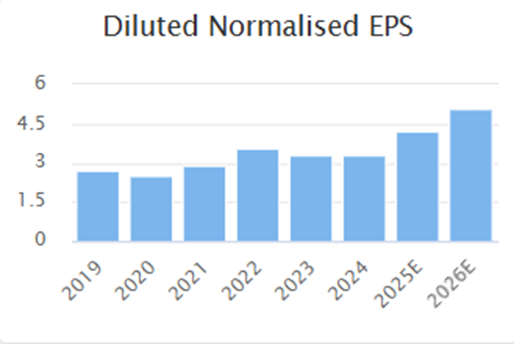
Its forward P/E is slightly lower, at around 17. However, EPS growth over the last 5 years has been just 4% CAGR compared to 28% for Interactive Brokers. Schwab needs to deliver on its forecast earnings growth, or perhaps even beat it to justify its current rating:
J Sainsbury (LON:SBRY)
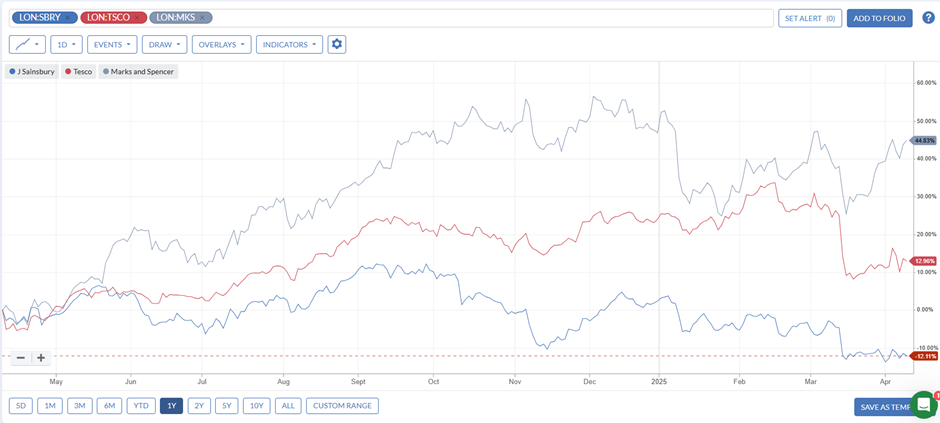
Sainsbury’s has underperformed rivals such as Tesco or Marks & Spencer over the last year:
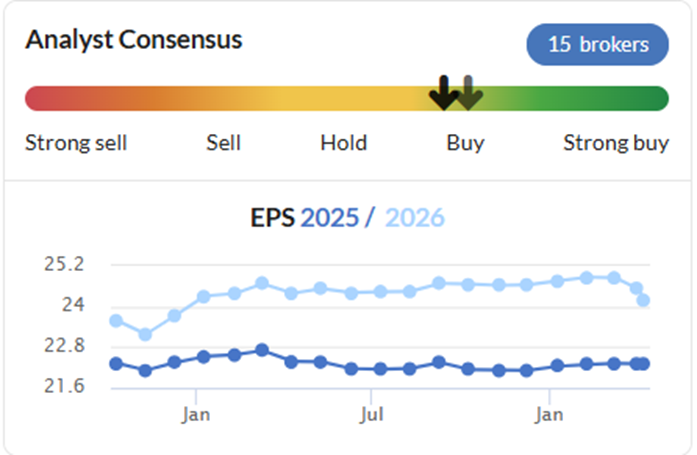
This largely reflects the move in brokers consensus which has been trending upwards for M&S, gently rising for Tesco but largely flat for Sainsbury’s:
All of these grocers took a tumble in response to ASDA’s profits warning in March this year, as the privately owned company declared its willingness to protect its recent gains in market share through “price investment” i.e. cost reductions.
Grocery retailing is a highly defensive business, and Sainsbury’s looks cheaper than both listed rivals:
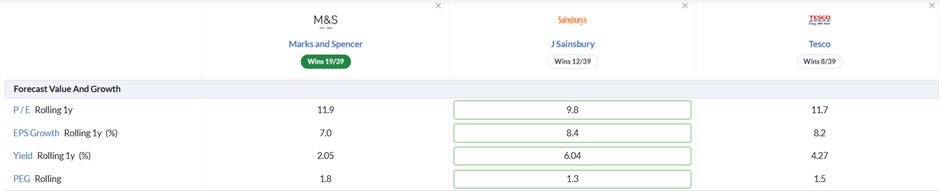
However, Sainsbury’s is likely to be the most squeezed by a move towards cheaper mass-market alternatives in currently weak economic conditions. (Assuming M&S Food or Waitrose customers are largely price insensitive!) Investors reacted negatively to Tesco’s results this week when the company warned that profit would likely fall this year due to increased “competitive intensity." Investors will be concerned that Sainsbury’s outlook will be even worse.
Concurrent Technologies (LON:CNC)
Concurrent is a popular stock amongst investors, probably because it is one of the few stocks that have performed well in the last year:
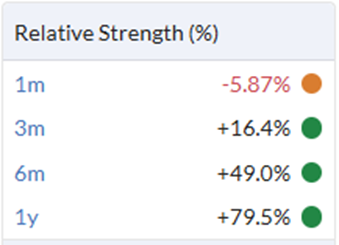
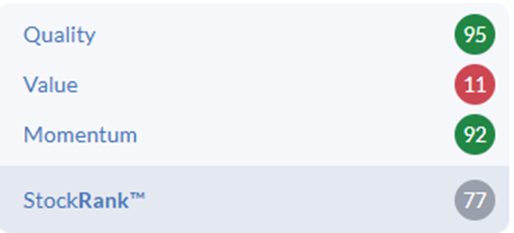
This has put it firmly in the High Flyer category:
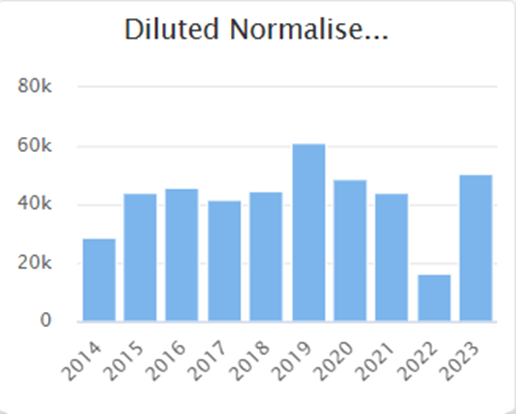
For a long time, it was a reasonably cash-generative business, but one that had gone nowhere quickly:
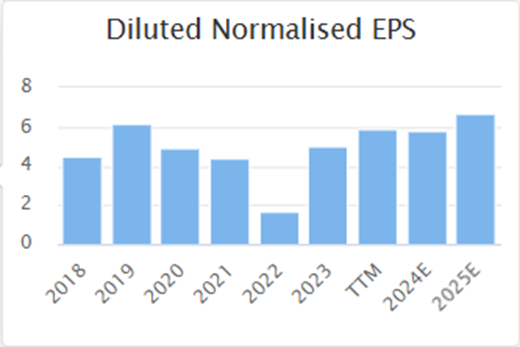
A new CEO was brought in in 2021, and the list of new products and contract wins points to a better future. Forecasts are for a reasonable 15% growth in EPS:
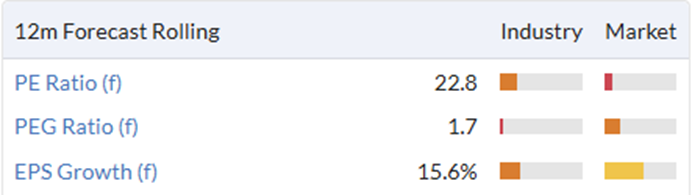
However, that still isn’t a particularly high growth rate compared to the current earnings multiple, meaning the algos rate the PEG ratio orange/red:
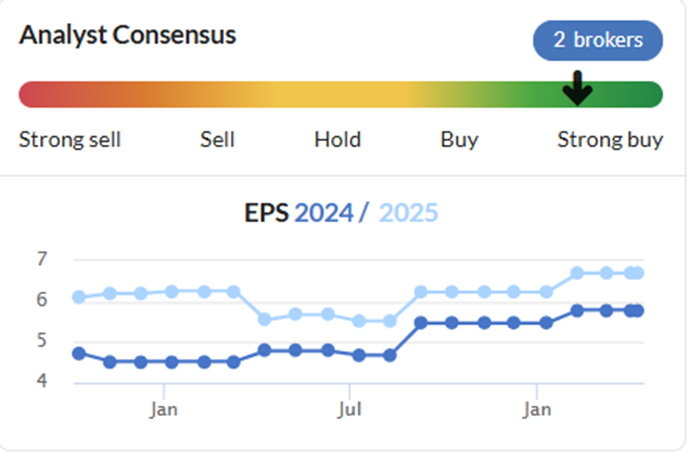
The analysts’ consensus has been trending up recently, which may mean the company is under-foecasting and over-delivering. Investors will want these forecasts to be beaten on Monday to justify the current high rating:
The new CEO didn’t immediately cover themselves in glory, as well. In 2021, the company put out an ahead statement, but this ended up as an EPS miss in the audited accounts. They had a qualified 2021 audit due to an inability to find out why there was a historical under-reporting of profits and assets. In September 2022, they announced that they would miss market forecasts, but this was 9 months into their financial year, which seems late to first realise they wouldn’t meet these. They had a qualified audit in 2022, as they couldn’t provide the paperwork for a write-back of payables. In 2023, they raised £6.8m at 65p, paying around £450k in fees to do so, in order to complete a £1.5m acquisition, while they reported £3m net cash on the balance sheet. This suggested that their working capital position was much worse than they were willing to admit to investors.
Given this history, investors will be hoping that they have put these types of issues behind them. The current rating leaves little scope for further accounting mishaps.
Billington Holdings (LON:BILN)
My personal focus next week will be on this key holding of mine. In normal trading conditions, this company generates very good returns on capital:
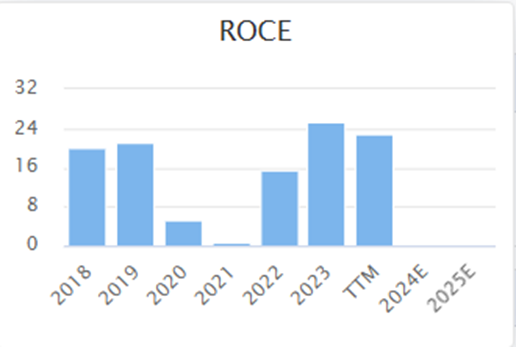
It is this dynamic that meant this was one of the multibaggers in the 2023 Stockopedia study. They are also very conservative in forecasting, with three upgrades to FY24 numbers in the last year:
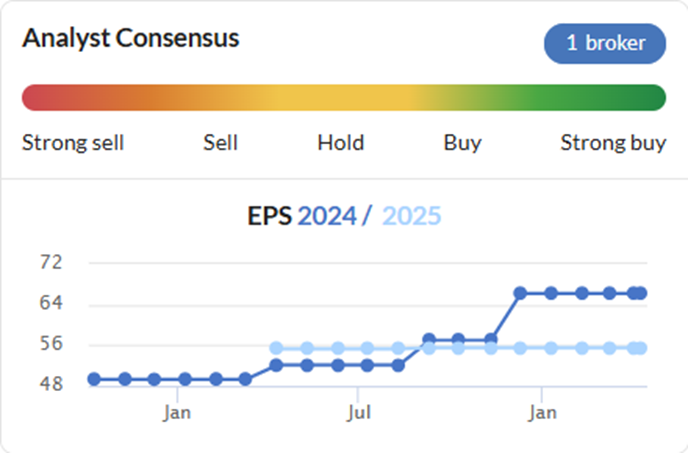
This makes the company appear to be a bargain on this sort of rating:

However, this is undoubtedly a cyclical business, as the lack of profits in 2020 and 2021 shows. Despite the upgrades to 2024 numbers, there was no upgrade to 2025. The big question is whether this is simply conservatism or a function of weak end markets. This is the oulook in their last trading update:
The Group has a strong order book spanning multiple market sectors, and has been successful in securing a number of significant, good quality contracts for 2025 and into 2026, particularly in sectors that require more complex solutions such as energy from waste, high-tech manufacturing and data centres. Whilst remaining mindful of ongoing challenging market conditions, Billington continues to trade well and is confident of delivering upon its market expectations for 2025.
I’m not sure that clears things up! So, investors will be looking for answers to that question in this week’s results. One of the big concerns is that major competitor Severfield has had two significant profit warnings so far. However, Billington issued an ‘ahead’ trading statement after the last warning, which gives some comfort that the issues may be specific to Severfield to some extent.
At the half-year, Billington had £21.9m net cash, excluding lease liabilities. Given the second-half weighting in profitability and fairly normal working capital profile, there is scope for this cash balance to build further, offset by an expected £1.5m of capex in H2. While it is nice that the company has a bullet-proof balance sheet at times like these, investors will also be looking at what they will do with this cash.
Hunting (LON:HTG)
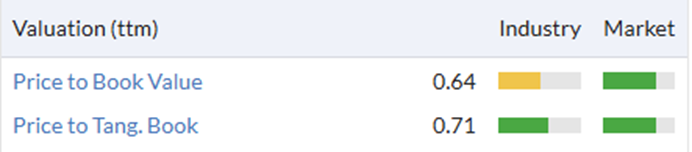
This is another value stock that I have held in the past, although I don’t currently. The standout metric is a big discount to tangible book:
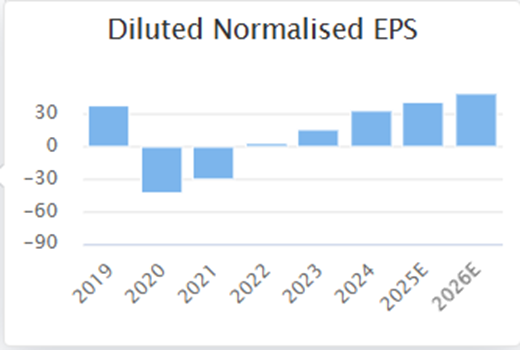
The bulk of the assets are inventory, making these more liquid than the average asset play. This is undoubtedly a cyclical industry, and the EPS trend suggests that there is more to come as part of a longer cycle:
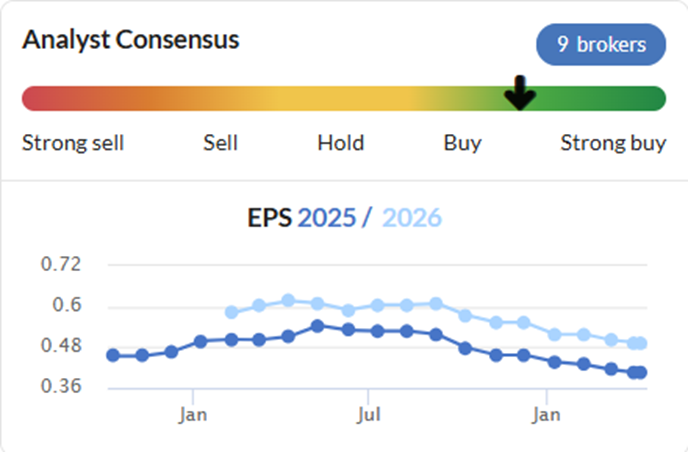
However, the company has rather blotted its copybook lately, with a series of small misses versus expactions:
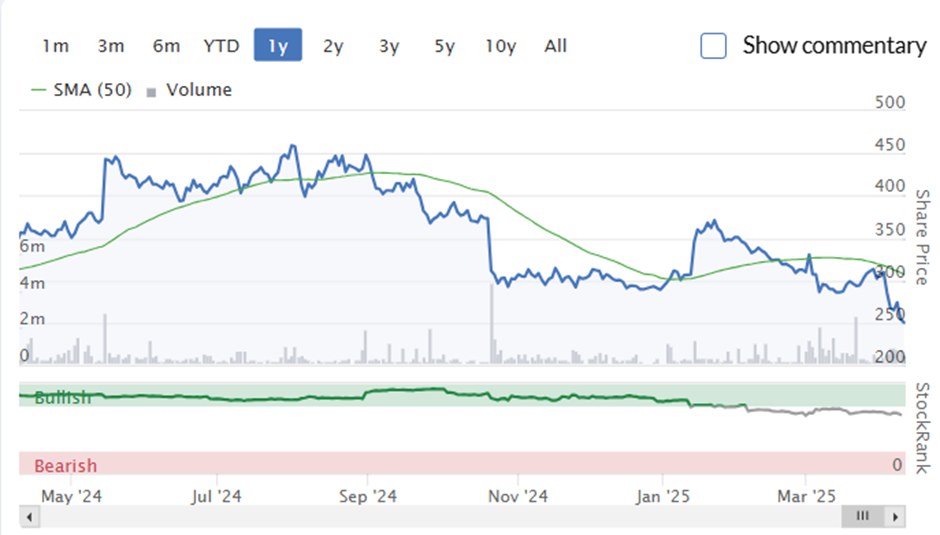
The recent share price shows market worries about lower oil prices weighing on the stock:
Investors will be looking for guidance to be at least held in next week’s trading update despite the weaker oil outlook.
[Disclosure: Markholds shares in Billington Holdings (LON:BILN) ]
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

4 comments
Good Mark, it would be interesting to hear your point of view on Hunting (LON:HTG) trading update today if you have time?
"All of these grocers took a tumble in response to ASDA’s profits warning in March this year, as the privately owned company declared its willingness to protect its recent gains in market share through “price investment” i.e. cost reductions."
I am not sure that ASDA has made any recent market gains? Its market share has hovered around 12.6 % for the last 9 months. A year ago ASDAs market share was 13.3 % and two years ago 13.9%.
Kantar, the go to industry analyst for market share has a very nifty website with slider so that market share for all the key players can be compared over various timescales...
https://www.kantarworldpanel.c...
ASDAs recent bold but vague price announcement comes off the back of an ALDI price match campaign. ASDA withdrew from this campaign so make of that what you will. I personally don't think that a new ASDA price campaign will have much effect on Tesco and Sainsbury. Both in my view have the firepower to fight back.
No interest in either Tesco or Sainsbury - but hold SUPR.
Billington
Bit of local intel for you .
I met a customer yesterday whose daughter works at Billington
He was saying how busy they were and had lots of big contracts coming .
I asked if these were already known about or new .
He mentioned a very big contracts at Sheffield forgemasters who are doing some major stuff, I know this because they bought some of my land for this project and i drive past every day .
Id say this is a major major contract win .
Total and pure speculation and hearsay with absolutely nothing substantial to back it up
Billington Holdings (LON:BILN) - Agreed, Forgemasters was a large win; however, this is one of the reasons for the downgrade on the 2025 numbers. Due to a redesign, the Forgemasters project has been delayed until the summer next year. This is one of the reasons that Billington have had to look for other 2025 projects at a time where the market is extremely competitive, which is frustrating.
The market is ultra competitive right now because of some economic slowdown but also because of Severfield's struggles. Severfield are desperately hunting for more work and therefore low balling tenders. This cost Billington about £1.2m of profit on one of the replacement deals.
The good news is that Severfield (LON:SFR) are in serious trouble and represent about 16% of the UK steel fabricator market. If they go under then it will be fantastic news for Billington who have tonnes of cash. By contrast, Severfield has a huge debt pile and has an unknown liability for mistakes that they made while fabricating weathered steel for bridges. Although Severfield has set aside £20m+, this is unlikely to be enough.... imagine the cost of replacing a bridge multiple times and then the cost of the train delays caused by the work...
Some contractors won't be working on bridges with Severfield again because of their financial struggles and this is again good for Billington.
Billington's management are conservative and have deliberately low balled the 2025 numbers with the belief that they can improve as the year goes on. There will be a weight to H1; however, a significant amount of profit will come in H2 from higher margin projects.
As you said they are very busy.
Net assets were £53.0 million at 31 December 2024... Market Cap is now £46m... = the shares are far too cheap