The Week Ahead (16 – 20 Feb): FOMC Minutes, UK Unemployment & Inflation, Garmin, Walmart, Transense Technologies

Markets
The UK Market has been the place to be so far this year, with the FTSE 100 making new highs again this week:
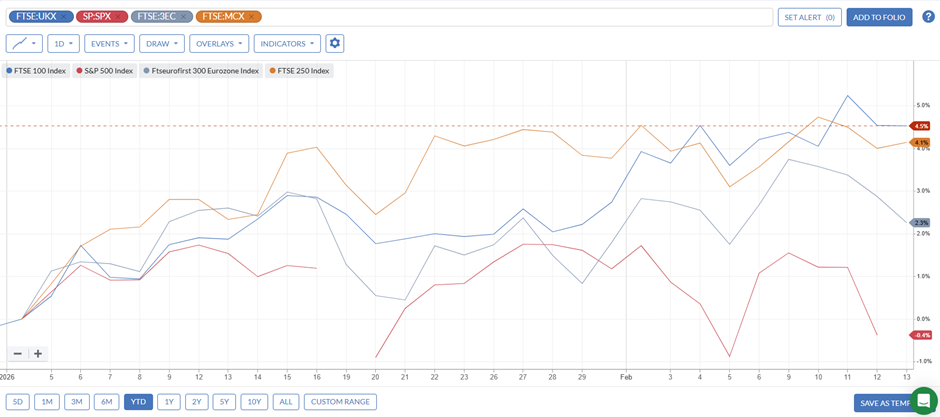
Pleasingly, the FTSE250 appears to have joined in the rally. However, as I am repeatedly pointing out, at the moment, valuations are still compelling the further down the market cap range, suggesting that the positive asset flows have yet to percolate throughout the UK market.
Here's what we can look forward to next week:
Economic Calendar
Monday 16 Feb |
||
10:00 |
Euro Area |
Industrial Production |
Tuesday 17 Feb |
||
07:00 |
UK |
Unemployment Rate Average Earnings |
13:20 |
United States |
Retail Sales |
23:50 |
Japan |
Balance of Trade |
Wednesday 18 Feb |
||
07:00 |
UK |
Inflation Rate Purchasing Index |
13:30 |
United States |
Housing Starts Durable Goods Orders |
14:15 |
United States |
Industrial Production |
19:00 |
United States |
FOMC Minutes |
Thursday 19 Feb |
||
13:30 |
United States |
Balance of Trade |
23:30 |
Japan |
Inflation Rate |
Friday 20 Feb |
||
07:00 |
UK |
Retail Sales |
13:30 |
United States |
GDP Q4 (Advanced Estimate) Personal Spending |
FOMC Minutes
These minutes have no immediate impact on U.S. interest rates, which were held at the last meeting at 3.75%:
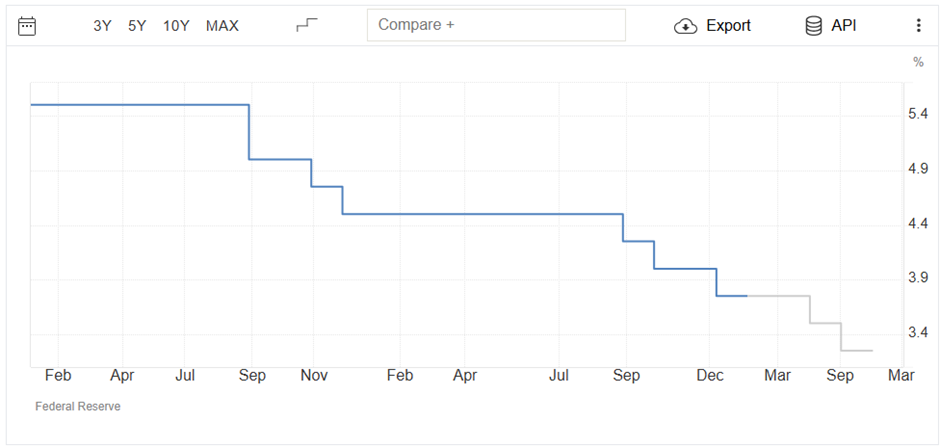
[All charts in this section: Trading Economics]
However, they can have a big impact on the market’s view on the future rate trajectory, impacting everything from long-term mortgage rates to equity valuations.
Recent public comments show a division between those on the FOMC committee arguing for slower easing or holding rates steady and those pushing for more cuts to support growth if inflation eases. Of particular note will be how policymakers discussed inflation trends, especially where they see risks to achieving the Fed’s 2% target.
UK Unemployment
Many analysts have also noted a softening jobs market, with concerns about layoffs in services and slower hiring. Therefore, markets will be concerned with a rate that continues near or above 5%. In terms of forecasts, things are expected to get worse before they get better:
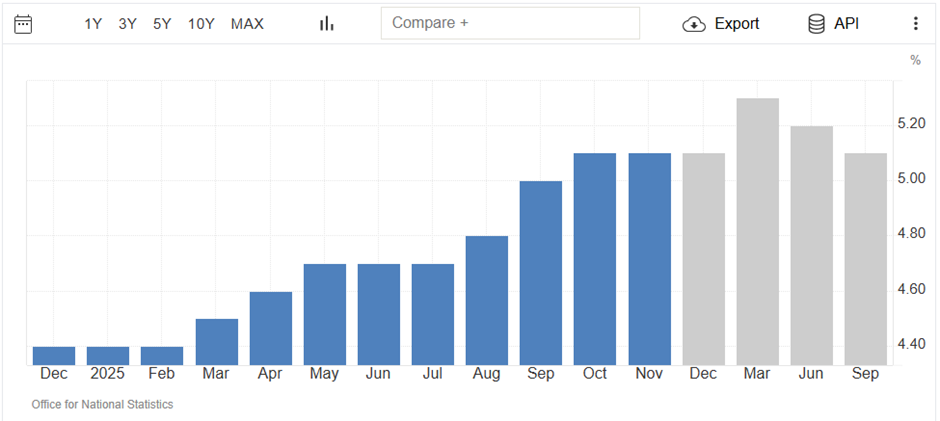
A weak jobs market could mean continued weakness in consumer spending.
UK Inflation
UK inflation has remained persistently high in recent times. However, it has been trending downwards, and is forecast to reach the BoE’s 2% target by the end of the year:
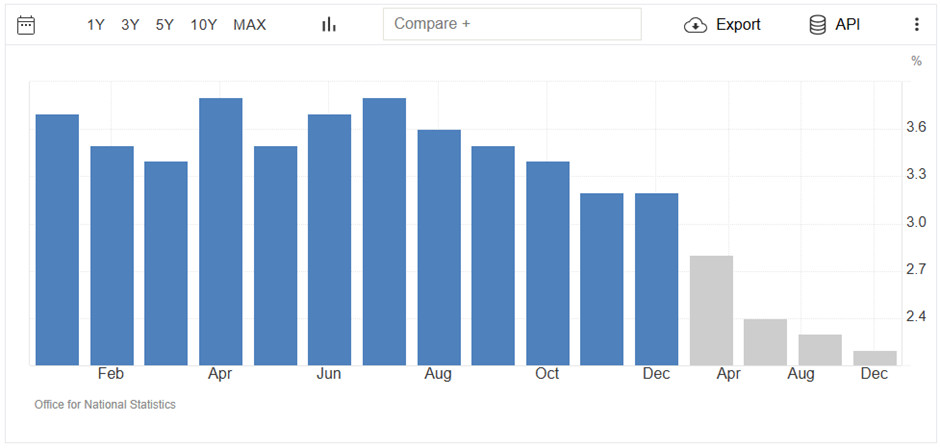
The headline number won’t matter as much as how the underlying components indicate that the 2% target can be reached in time.
Companies Reporting
The 16th of February is Presidents’ Day in the US, meaning markets will be closed, making it a slow start to the week:
Date | UK Trading Updates & AGMs | UK Financial Results | |
|---|---|---|---|
Monday 16 Feb |
International Financial Results | ||
Tuesday 17 Feb |
Ten Lifestyle (LON:TENG) (AGM) |
Antofagasta (LON:ANTO) (Finals) Coca-Cola Europacific Partners (LON:CCEP) (Finals) Feedback (LON:FDBK) (Interims) Intercontinental Hotels (LON:IHG) (Finals) Springfield Properties (LON:SPR) (Interims) Transense Technologies (LON:TRT) (Interims) |
Cadence Design Systems (NSQ:CDNS) Palo Alto Networks (NSQ:PANW) Republic Services (NYQ:RSG) Vulcan Materials Co (NYQ:VMC) |
Wednesday 18 Feb |
Tharisa (LON:THS) (AGM) Seeing Machines (LON:SEE) (TS) |
BAE Systems (LON:BA.) Conduit Holdings (LON:CRE) (Finals) CRH (LON:CRH) Glencore (LON:GLEN) (Finals) Pan African Resources (LON:PAF) (Interims) |
Analog Devices (NSQ:ADI) Booking Holdings (NSQ:BKNG) DoorDash (NSQ:DASH) Garmin (NYQ:GRMN) Moodys (NYQ:MCO) Orange SA (EPA:ORA) Occidental Petroleum (NYQ:OXY) |
Thursday 19 Feb |
BTG Consulting (LON:BTG) (TS) Ceps (LON:CEPS) (TS) Critical Metals (LON:CRTM) (AGM) Diales (LON:DIAL) (AGM) Red Rock Resources (LON:RRR) (AGM) Safestore Holdings (LON:SAFE) (TS) |
Centrica (LON:CNA) (Finals) Mondi (LON:MNDI) (Finals) Rio Tinto (LON:RIO) (Finals) |
Accor SA (EPA:AC) Airbus SE (EPA:AIR) Copart (NSQ:CPRT) Deere & Co (NYQ:DE) Consolidated Edison (NYQ:ED) Pernod Ricard SA (EPA:RI) Newmont (NYQ:NEM) Quanta Services (NYQ:PWR) Repsol SA (MCE:REP) Renault SA (EPA:RNO) Southern Co (NYQ:SO) Targa Resources (NYQ:TRGP) Wayfair (NYQ:W) Walmart (NSQ:WMT) |
Friday 20 Feb |
Chemring (LON:CHG) (AGM) |
SEGRO (LON:SGRO) (Finals) Anglo American (LON:AAL) (Finals) TBC Bank (LON:TBCG) (Finals) |
LAir Liquide Societe Anonyme Pour letude Et lexploitation Des Procedes George (EPA:AI) Danone SA (EPA:BN) Warner Bros Discovery (NSQ:WBD) |
As usual, let me know in the comments if you think I've missed anything definitely reporting next week
Garmin (NYQ:GRMN)
Garmin reports Q4 results on Wednesday, and seeing as I got a Garmin smartwatch for Christmas, I thought it would be interesting to see if the case for buying the equity matches that of the product.
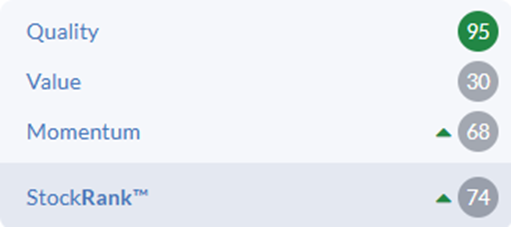
The algorithms rate it as a “High Flyer”:
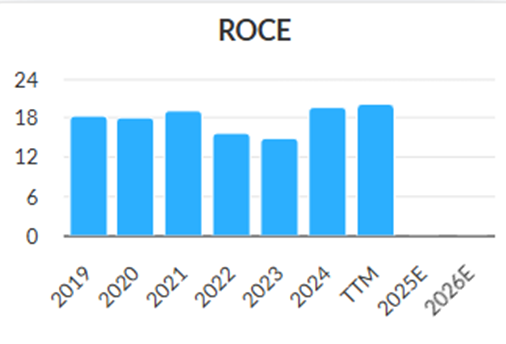
Consistently high returns on capital mark it out as a quality business:
And revenue growth has been pretty smooth:
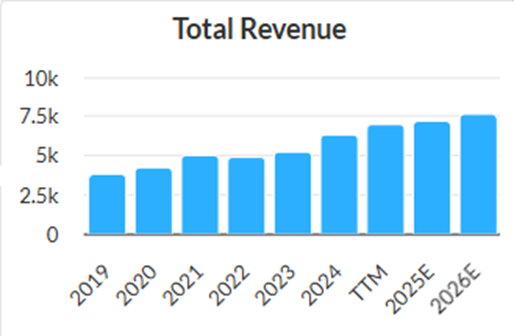
But at around 11% CAGR, it isn’t that great, and 5-yr EPS CAGR has only been around 8%:
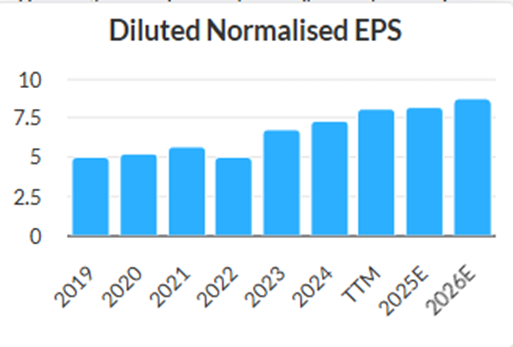
This suggests a lack of operational gearing, despite strong gross margins.
Forward estimates have EPS rising 12% for the year just gone, and 6% into the current year. These make the equity look expensive:
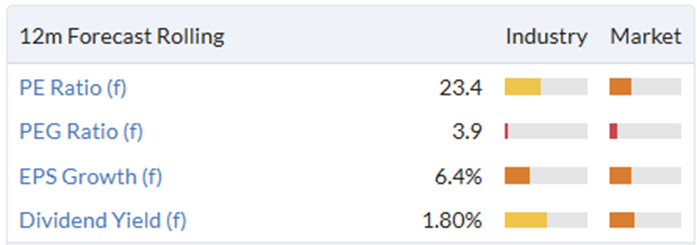
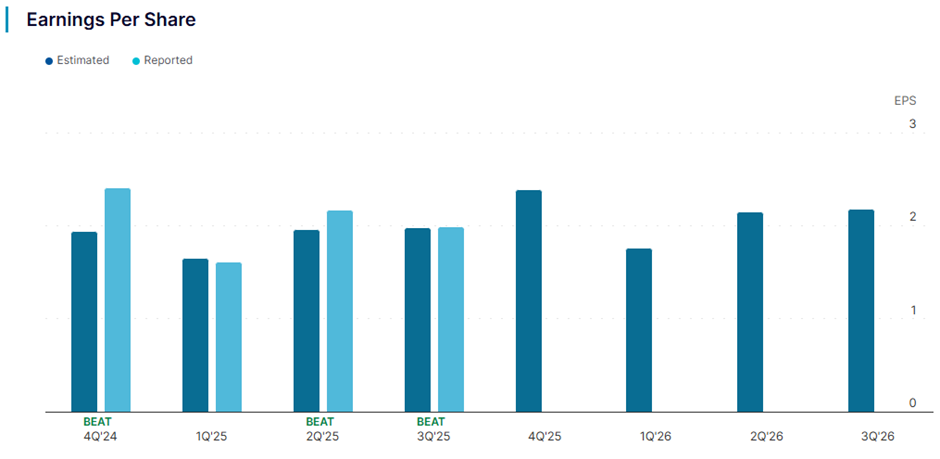
The company really need to be beating these forecasts to justify the current rating, let alone something higher. The good news is that 3 out of 4 of the last quarterly results were ahead of expectations:
Source: NASDAQ
However, the scale of the outperformance is not significant, and they would need to report signs of significant forward growth to tempt me to buy the equity, not just a watch. Other things to look out for are:
Fitness Segment: continued high growth in advanced wearables such as the Venu 4 and Forerunner series.
Outdoor Segment: a recovery in this sector, where tough comparables saw sales in Q3 come in below the previous year. Look for a return to growth in Q4, driven by the Fenix 8 series.
Margins: These remain very high at close to 60%, but have come under pressure recently. Investors will be keen to see if inflationary pressures and the strengthened Taiwan dollar are continuing to compress margins and how the continued impact of tariffs is being managed.
Walmart (NSQ:WMT)
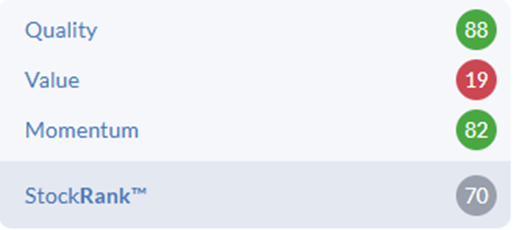
This retail giant is another stock classified as a High Flyer:
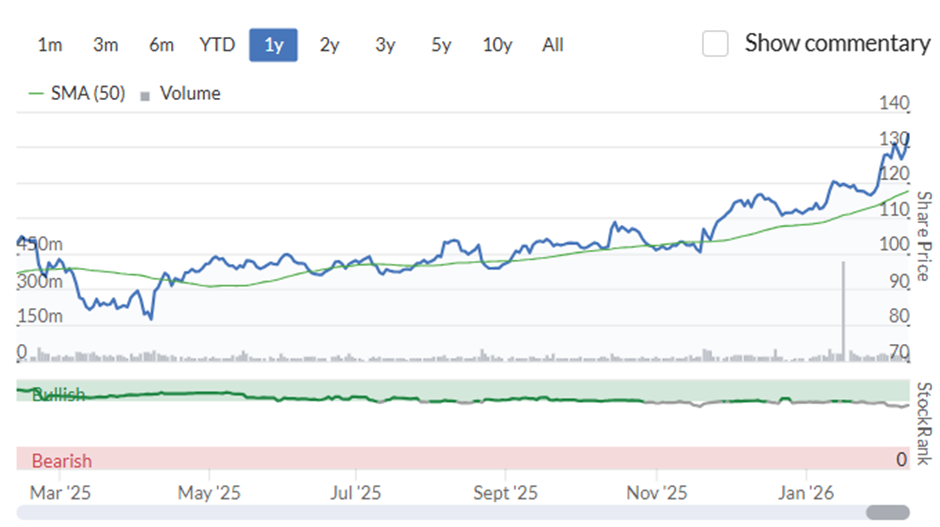
The shares have been making all-time highs this year:
However, this rise doesn’t seem to be backed by improvements in the outlook:
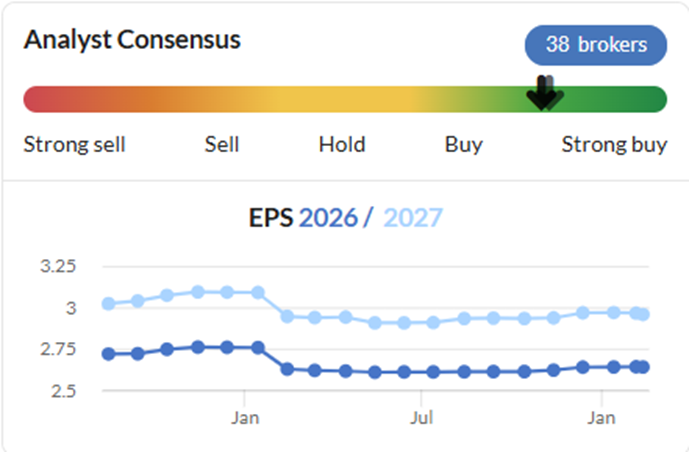
And with 5-yr revenue and EPS CAGR of around 5%, this sort of rating is looking a little ridiculous:
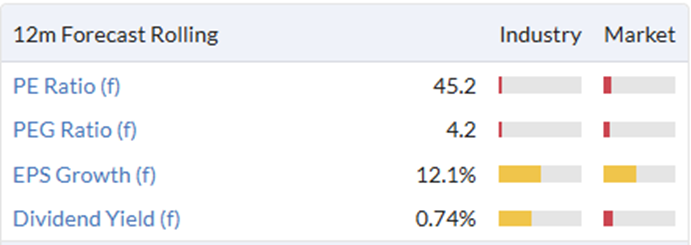
The company undoubtedly generates some competitive advantage from its huge scale, but even here, the returns on capital are not exceptional:
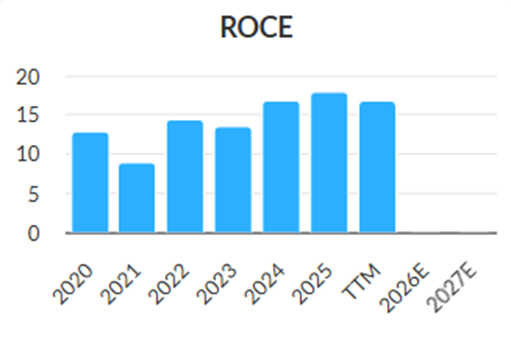
One of the reasons the market may be more optimistic than these figures suggest is that the e-commerce part of the business is growing much more quickly, with analysts expecting this to be 20% on the prior year's figures. Managing labour costs through automation will be key to seeing forecasts being met. Also in focus will be the potential impact of trade tariffs on inventory and labour costs due to shifting immigration or deportation policies. Overall, there looks to be more risk than reward at the current valuation to me, though.
Transense Technologies (LON:TRT)
It’s been a horrendous start to 2026 for this sensing technology company, which is what has brought it to my attention:
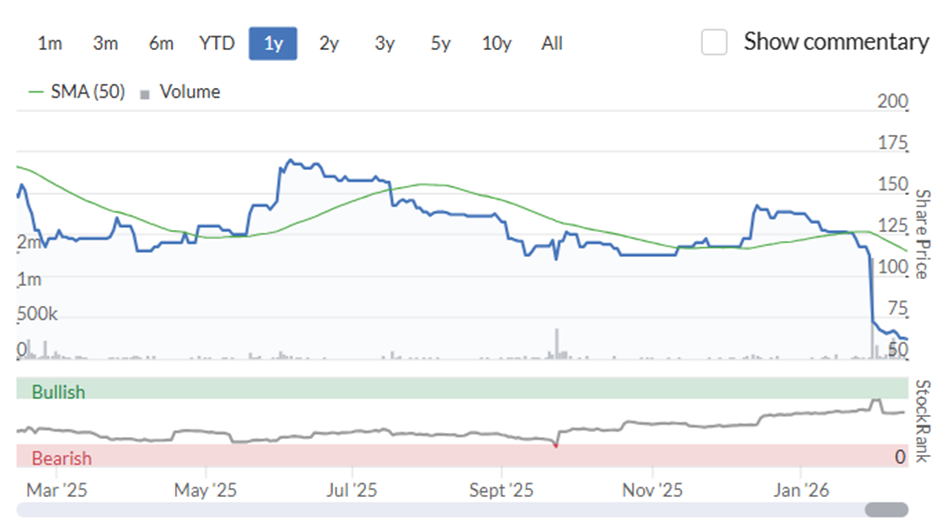
The trading statement that caused the damage reported delays to key new business wins:
Whilst both core trading divisions, SAWsense and Translogik continue to demonstrate increasing revenues, the pace of growth is below market expectations, primarily due to delays in customer on-boarding from their respective pipelines of new business. In addition, expected royalty income from Bridgestone iTrack is now considered likely to be approximately 10% lower than previously expected.
Leading to the dreaded words “materially below”:
Accordingly, the Company now expects that Group revenue for FY26 will be not less than £5.2m, including approximately £2.0m of royalty income. Revenues from the two operating businesses are expected to show composite growth of not less 30% for FY26. Whilst gross margins have been maintained, the impact of these lower levels of revenue than previously anticipated mean that profitability for FY26 is expected to be materially below current market expectations.
In response, their broker, Cavendish, reduced FY26 profit forecast by about 90%, and took 40% out of FY27. This suggests that this isn’t just about one-off delays. So all eyes will turn to the balance sheet. They reported net cash in their trading statement, so if this is strong enough overall to withstand this period of unexpectedly weak trading, investors may start to focus on the potential for recovery.
If the now-reduced FY27 forecasts are in the right ballpark, then this would be trading on a mid-single-digit P/E:
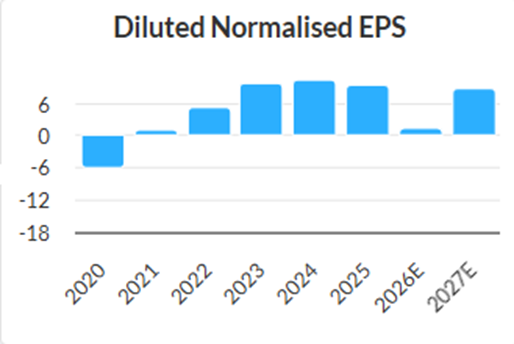
The Stockopedia research into profit warnings suggests that it is too early to consider something like this as a recovery stock, as the risk of further bad news is too high. However, if the HY results released on Tuesday don’t show any issues with the balance sheet, then it may be worth adding to investors’ watchlist for when that Momentum Rank starts to turn upwards:
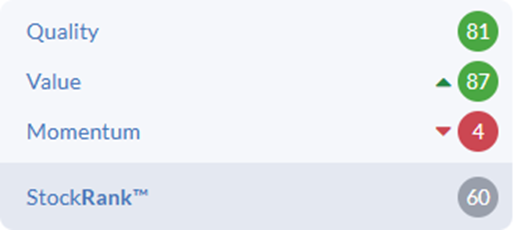
If the balance sheet looks weak on Tuesday, investors may want to exit and take any price they can get.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

1 comment
Add Checkit (LON:CKT) preclose (yr. end Jan.) Thurs. 19th.