The Week Ahead (16 - 20 Nov): Nvidia Without Jensen, Anthropic's IPO, and the UK Grows

[Disclosure: at the time of publication, James Fox has long positions in NVDA and JET2.]
1. Market Recap
Every time I write The Week Ahead, I feel a little guilty for not focusing on the UK, but it’s events outside the UK that are moving markets the most, even at home.
This week belonged to Nvidia, and not for the usual reasons. On Thursday the board announced that Jensen Huang had resigned as chief executive and left the board with immediate effect, days after admitting an affair with a woman US intelligence officials consider a suspected Chinese intelligence asset. In addition to his VP of healthcare (reportedly), Reuters reported a third relationship with another Nvidia employee on Thursday.
CFO Colette Kress is interim CEO, Harvey Jones becomes the company's first ever chair, and an internal and external search is under way – Trump has suggested Tim Cook.
On Thursday morning, the stock opened around $149 per share but clearly found a lot of support around that price. Shares now trade around 31% below the 6 October record, compounded by several brokerage downgrades. Lawmakers are now pushing to accelerate chip export restrictions to China and those who supported Huang’s view – make Chinese companies dependent on American AI technology – have now lost a critical ally.
Microsoft had its own bad Thursday. A Microsoft 365 outage that began around 1pm ET took down Outlook, Teams, SharePoint and Copilot into Friday, with Azure affected at the edges. Microsoft blamed “elevated load across multiple regions” after servers became unexpectedly unavailable and said there was no sign of malicious activity.
Despite this, during the week, parts of the AI trade found their feet. CoreWeave rose nearly 25% on Wednesday after a Q3 revenue beat although it’s still down around 60% from its highs – in my last The Week Ahead we covered how financing concerns were unraveling the neocloud investment thesis.
Meanwhile, Anthropic set the range for its IPO at $70–78 a share for 825 million shares, valuing the company at up to $1.4 trillion fully diluted, and began its roadshow on Tuesday. Pricing is expected on Wednesday 18 November, with Nasdaq trading under "ANT" from Thursday. Recent reports suggest the IPO is 6x oversubscribed – for context I applied for almost £20,000 of SpaceX shares on HL in June and received around £4,000-£5,000.
Inflation data was briefly on the radar this week but was overshadowed by events at Nvidia. October US CPI rose 0.4% on the month against 0.3% expected, with core at 0.3% against 0.2%; there is still no year-on-year figure because of the gap left by last year's shutdown. Dallas Fed President Lorie Logan said she sees a need for two more quarter-point hikes. Treasuries sold off into Thursday as oil rose.
Oil gave back some of its November fall. On Thursday Trump posted that the time for a deal with Iran “has long since passed” and that the US had “control of Iran's money and the Strait of Hormuz” – “we've got their Strait”.
The benchmarks are well off their highs, but it’s worth recognising that the landed cost of Middle East crude in China, for instance, is still very elevated due to freight premiums. VLCC freight rates to China have increased from around $4bbl to $37bbl. If Westminster ever needed the importance of domestic production being highlighted, here it is.
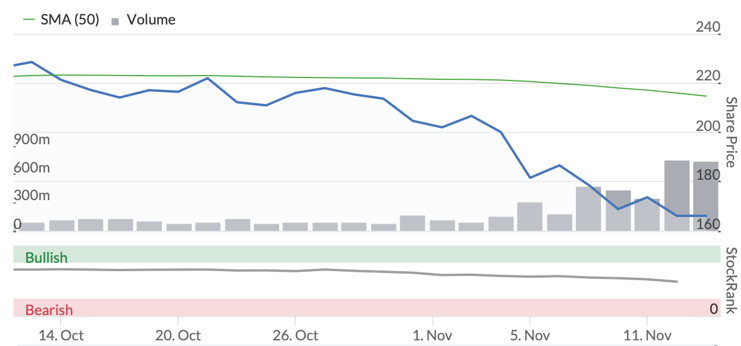
[Chart: Nvidia share price, past month. Source: Stockopedia]
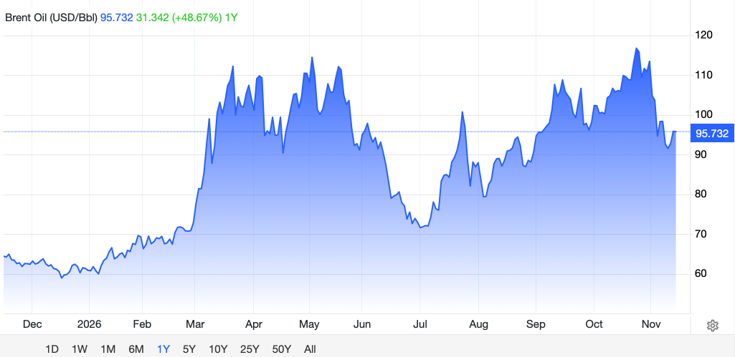
[Chart: Brent crude, past month. Source: tradingeconomics.com]
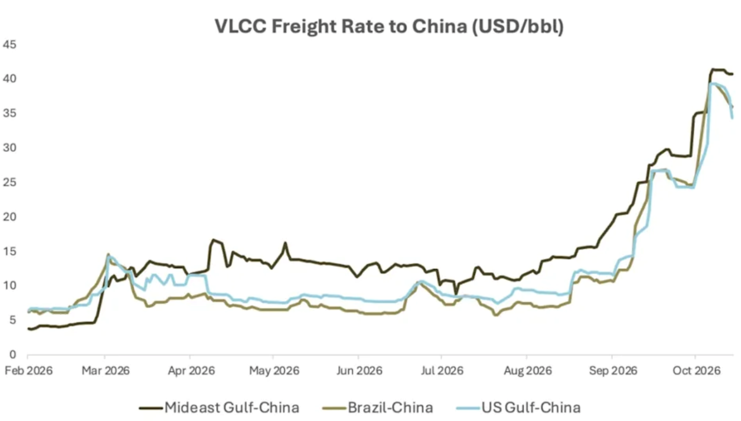
[Chart: VLCC freight rates to China. Source: Natalia Katona/Argus data]
At home, the news was better. Q3 GDP came in at +0.7% on Thursday, in line with forecasts and the strongest quarter since early 2024. More on that below.
2. Economic Calendar
The Fed is out of blackout and the October minutes land on Wednesday evening. In the UK, this is the first full set of post-Budget data: jobs on Tuesday, inflation on Wednesday, retail sales and the public finances on Friday. All times GMT.
| Date | Time | Region | Release |
|---|---|---|---|
Monday 16 Nov |
13:30 |
US |
Empire State manufacturing (November) |
Tuesday 17 Nov |
07:00 |
UK |
Labour market – unemployment, average earnings (3m to September) |
10:00 |
Eurozone |
ZEW economic sentiment (November) |
|
13:30 |
US |
Retail sales (October); import & export prices (October) |
|
14:15 |
US |
Industrial production & capacity utilisation (October) |
|
Wednesday 18 Nov |
07:00 |
UK |
CPI (October); PPI (October) |
10:00 |
Eurozone |
Final HICP (October) |
|
13:30 |
US |
Housing starts & building permits (October) |
|
15:30 |
US |
EIA crude oil inventories |
|
19:00 |
US |
FOMC minutes (27–28 October meeting) |
|
Thursday 19 Nov |
09:00 |
Eurozone |
Current account |
13:30 |
US |
Initial jobless claims |
|
Friday 20 Nov |
00:01 |
UK |
GfK consumer confidence (November) |
07:00 |
UK |
Retail sales (October); public sector finances (October) |
|
07:00 |
Germany |
PPI |
|
15:00 |
US |
University of Michigan consumer sentiment (final, November) |
3. Macro Theme Deep-Dives
The UK Is Growing. Who Knew?
Q3 GDP rose 0.7%, following 0.5% in Q2, and output is 1.9% higher than a year ago. Services grew 0.9%, and the ONS singled out computer programming and consultancy, up 4.4% in the quarter. September alone was +0.2% after a flat August.
The Bank of England has noticed. Its November Monetary Policy Report lifted 2026 growth to 1.6% from 1.1% in July and 2027 to 1.3%, and attributes “just under a fifth” of GDP growth since the start of the year to AI-related activity – most of it building and selling AI rather than using it. That is a better number than the OBR's 1.2%, published alongside John Healey's Budget on 28 October before the Q3 data was in.
There are caveats. The Bank also raised Bank Rate to 4% on 5 November, 8–1, with one member wanting 50bp, and expects growth to slow in Q4 and into 2027. The British Chambers of Commerce talks about a two-speed economy: a handful of large firms investing, most smaller ones not. Construction was weak and business investment softer.
Next week's data will, as always, contribute to the rate debate. Wednesday's CPI is the first post-Budget print and the one the Bank will be reading most closely – September's headline was 3.5% with core at 2.8%. Tuesday's labour market data will show whether last month’s 4.7% unemployment rate holds, and Friday's retail sales and public finances will tell us whether the consumer and the Treasury are keeping up with the headline number.
AI Without Jensen
Jensen Huang has been the poster boy of the AI revolution, leading a company he co-founded and delivering the narratives that moved markets. He’s also built relationships with world leaders, positioning himself as one of the industry’s most effective ambassadors and advocates. He was a salesman for the entire industry, and his departure leaves a vacuum.
Currently, it’s unclear who fills that void. Could it be his replacement at Nvidia? Someone like Rene Haas from Arm. Or could a Zuckerberg or Musk step up to the role?
Perhaps the bigger question is what happens to Nvidia's influence, or who inherits it. The company has become far more than a chip supplier, with investments, funding and strategic relationships that underpin parts of the wider AI industry. Huang's departure could therefore leave a gap well beyond Nvidia itself.
4. Companies Reporting
Another big week for companies reporting next week on both sides of the table, with the utilities and the asset managers reporting interims and JD Sports updating ahead of peak. In the US it is retail week – Home Depot, Lowe's, Target and Walmart – plus Nvidia on Tuesday and Anthropic's first day of trading on Thursday (expected). US consumer discretionary performed well around the midterms and investors moved away from tech – this narrative will be interesting to watch.
| Date | UK Trading Updates & AGMs | UK Financial Results | International Financial Results |
|---|---|---|---|
Monday 16 Nov |
Legal & General (LON:LGEN) (TS), ME Group (LON:MEGP) (TS), HICL Infrastructure (LON:HICL) (General Meeting), Angling Direct (LON:ANG) (General Meeting), European Smaller Companies Trust (LON:ESCT) (AGM), Mountview Estates (LON:MTVW) (AGM) |
Big Yellow (LON:BYG) (Interims), Applied Nutrition (LON:APN) (Finals) |
Nothing of note. |
Tuesday 17 Nov |
Fandango Holdings (LON:FHP) (AGM) |
Diploma (LON:DPLM) (Finals), Trifast (LON:TRI) (Interims), Gear4music (LON:G4M) (Interims), CML Microsystems (LON:CML) (Interims), Zegona Communications (LON:ZEG) (Interims) |
Nvidia (NSQ:NVDA) (Q3), Home Depot (NYQ:HD) (Q3) |
Wednesday 18 Nov |
Smiths Group (LON:SMIN) (TS)(AGM), ConvaTec (LON:CTEC) (TS), Hays (LON:HAS) (AGM), Genus (LON:GNS) (AGM), Fonix (LON:FNX) (AGM), Time Finance (LON:TIME) (AGM), Berkeley Energia (LON:BKY) (AGM), Sovereign Metals (LON:SVML) (AGM) |
SSE (LON:SSE) (Interims), Severn Trent (LON:SVT) (Interims), Jet2 (LON:JET2) (Interims), Peel Hunt (LON:PEEL) (Interims), SysGroup (LON:SYS) (Interims), TwentyFour Income Fund (LON:TFIF) (Interims) |
Lowe's (NYQ:LOW) (Q3), Target (NYQ:TGT) (Q3), TJX (NYQ:TJX) (Q3), Palo Alto Networks (NSQ:PANW) (Q1) |
Thursday 19 Nov |
JD Sports (LON:JD.) (TS), Close Brothers (LON:CBG) (AGM), J D Wetherspoon (LON:JDW) (AGM), Pan African Resources (LON:PAF) (AGM), Greatland Resources (LON:GGP) (AGM), McBride (LON:MCB) (AGM), Eagle Eye (LON:EYE) (AGM), Scancell (LON:SCLP) (AGM), Origin Enterprises (LON:OGN) (AGM), UIL (LON:UTL) (AGM) |
Halma (LON:HLMA) (Interims), Babcock (LON:BAB) (Interims), Investec (LON:INVP) (Interims), CMC Markets (LON:CMCX) (Interims), Liontrust (LON:LIO) (Interims), Mulberry (LON:MUL) (Interims), MHA (LON:MHA) (Interims), Manolete Partners (LON:MANO) (Interims), Sage (LON:SGE) (Finals), Grainger (LON:GRI) (Finals), Tracsis (LON:TRCS) (Finals) |
Walmart (NYQ:WMT) (Q3), Anthropic (NSQ:ANT) (first day of trading) |
Friday 20 Nov |
Atlantic Lithium (LON:ALL) (AGM), Provexis (LON:PXS) (AGM), Ferro-Alloy Resources (LON:FAR) (AGM), DP Aircraft I (LON:DPA) (AGM) |
Nothing of note. |
Nothing of note. |
As usual, let us know via the comments if you think we've missed anything of note.
5. Stock Deep-Dives
Nvidia (NSQ:NVDA)
Nvidia reports Q3 FY27 after Tuesday's close.
Guidance for the quarter was revenue of $108 billion plus or minus 2% and a non-GAAP gross margin of 74%, down from 75% in Q2. Consensus is around $108.8 billion and EPS of $2.47. The quarter ended on 25 October, before the scandal, so the results themselves should be clean. The bar has moved lower with the stock trading sub-10x forward earnings.
Things to watch:
- The succession: Kress is interim, the search is external as well as internal, and Trump has publicly floated Tim Cook. Any timeline will move the stock more than the revenue number.
- China: lawmakers want export restrictions accelerated. Whether Nvidia guides for any China revenue at all in Q4 is the question.
- Margins: management reportedly flagged a trough of 71–72% in the January quarter as memory costs rise. The market will want to know where it goes after that, and how Rubin changes the mix.
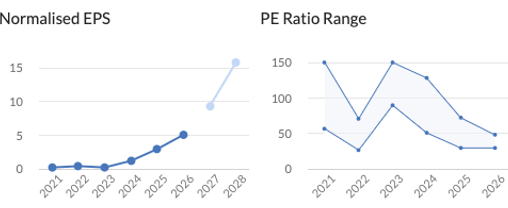
[Chart: NVDA EPS/PE. Source: Stockopedia]
Jet2 (LON:JET2)
Jet2 reports half-year results on Wednesday. The shares are towards the top of a 980p-1,612p twelve-month range, and the company has been buying back stock through November. It is in the process of moving from AIM to the Main Market, which it said in September it intends to complete before the end of its financial year in March.
The September AGM update gave us some strong data: summer 2026 capacity up 7.6% to 19.9 million seats, passengers booked up 8.8%, load factors 1.5 points ahead, and the Gatwick base ahead of plan with seven aircraft allocated for summer 2027. Winter 2026/27 capacity is up 8% to 5.9 million seats, most of it at Gatwick. Customers are still booking later – I’ve been hearing this for a while now though.
Things to watch:
- Fuel: What matters is the hedge position for FY28 and whether the "no fuel surcharges" guarantee for winter holds.
- Winter bookings: 5.9 million seats on sale is a lot of capacity for a late-booking customer. Any update on bookings will be useful.
- The Main Market move: any notes on timing, and whether it comes with any index-inclusion commentary.
- Guidance: FY26 operating profit was £439.6m, slightly below FY25 because of Gatwick launch costs. The FY27 guidance matters now.
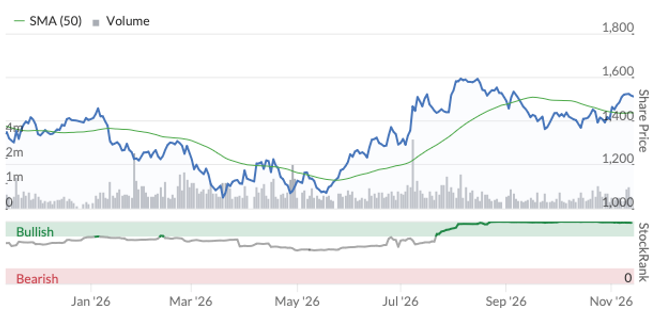
[Chart: JET2 share price. Source: Stockopedia]
[Disclosure: at the time of publication, James Fox has long positions in NVDA and JET2.]
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
3 comments
Jet2 already given main market timing update last week
Also have PayPoint (LON:PAY) giving their interim results on thursday 19/11/26, according to their website
NVIDIA (NSQ:NVDA) On several tenets the shares are extremely cheap but the whole scenario is classic copy of Musk i.e the key man is it and what is left behind if run over by a bus? Admittedly lots of negatives but would not be surprised if Hwang found his way back in the future. The cult of the personality is clearly not dead at this level of US business.