The Week Ahead (17 – 21 Aug): Japan Carry, UK Inflation, FOMC Minutes, US Retail, BHP, Hays

It's been a fairly buoyant week in the US. The S&P 500 rose above 7800 for the first time, as tame producer price inflation data supported expectations that the Federal Reserve will not raise interest rates at its September meeting. Strong forecasts in recent weeks from companies including Microsoft and Amazon have also reduced investors' concerns about massive spending on AI data centres.
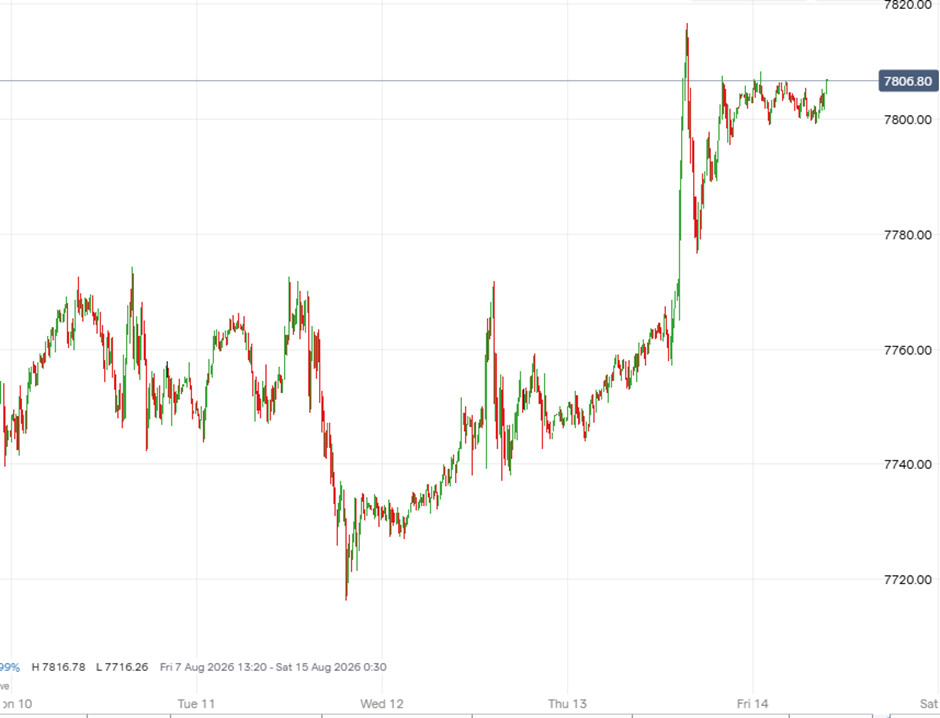
[All charts in this section: IG]
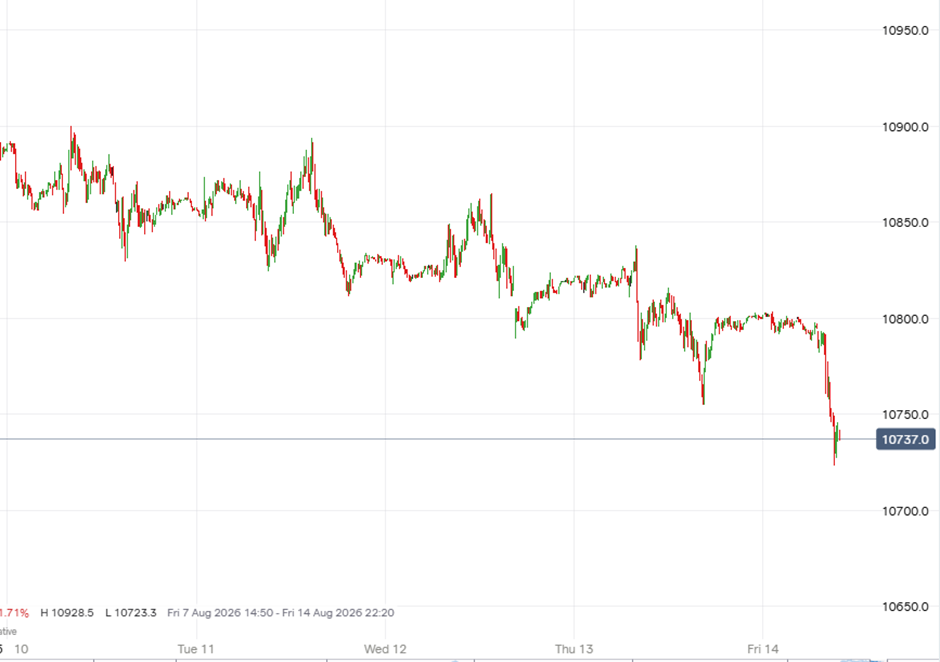
The FTSE 100 went the other way as investors worried about the impact of the ongoing Middle East tensions:
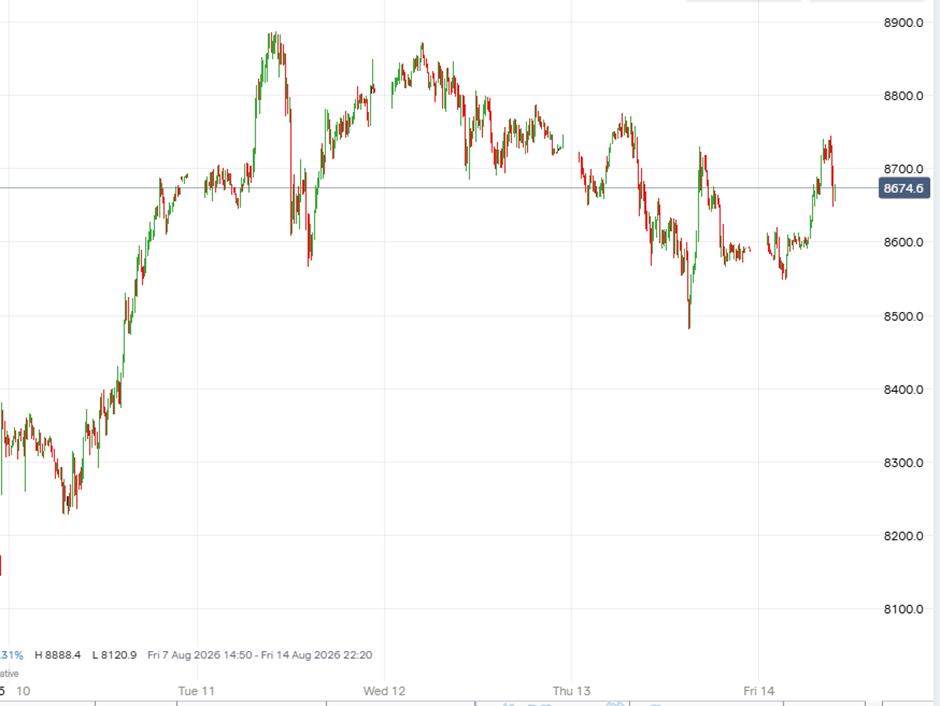
Brent Crude also reflected these worries. Starting the week at around $83/bbl, it peaked at close to $89, before retreating somewhat:
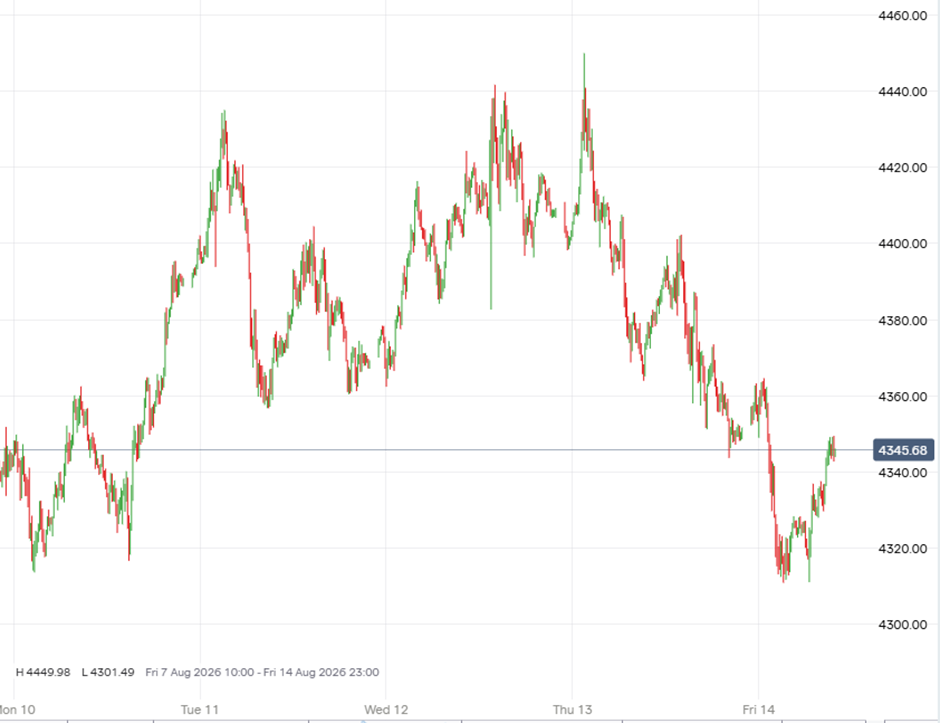
Interestingly, gold appears to have decoupled from its recent negative correlation with oil prices, perhaps suggesting that the dollar liquidity requirements of oil-export-constrained Middle Eastern countries have eased. Gold looks like it will end the week flat, but holding on to last week's gains:
Here's what we can look forward to next week:
Economic Calendar
Monday 17 August |
||
00:50 |
Japan |
GDP |
03:00 |
China |
Industrial Production Retail Sales |
15:00 |
United States |
NAHB Housing Market Index |
Tuesday 18 August |
||
07:00 |
UK |
Average Earnings Unemployment Rate |
10:00 |
Germany |
Economic Sentiment |
13:30 |
United States |
Housing Starts Building Permits |
Wednesday 19 August |
||
07:00 |
UK |
Inflation |
15:30 |
United States |
EIA Crude Oil Inventories |
19:00 |
United States |
FOMC Meeting Minutes |
Thursday 20 August |
||
00:50 |
Japan |
Balance of Trade |
13:30 |
United States |
Initial Jobless Claims Continuing Claims |
Friday 21 August |
||
00:30 |
Japan |
Inflation |
07:00 |
UK |
Retail Sales |
08:30 |
Germany |
Manufacturing PMI Services PMI |
09:00 |
Euro Area |
Manufacturing PMI Services PMI |
09:30 |
UK |
Manufacturing PMI Services PMI |
14:45 |
United States |
Manufacturing PMI Services PMI |
Japan GDP, Inflation & Carry
Japan reports the first preliminary estimate of Q2 GDP on Monday. Consensus points to annualised growth of around 2.0%, which would mark a third consecutive quarter of expansion and build on Q1's stronger-than-expected 0.5% q/q print.
National CPI is released on Friday and comes on the back of the important Tokyo inflation figures, which accelerated in July to 2.0% headline (from 1.7% previously). The BOJ's own commentary framed this as "increasingly sticky" inflation, pushed up by elevated energy prices and a yen that touched 40-year lows during the month. The national core CPI had been running at 1.6% in June, below the BOJ's 2% target for five straight months, so a similar national jump would bring it much closer to the target and reinforce the case for further tightening after the 25bp hike to 1.0% in June.
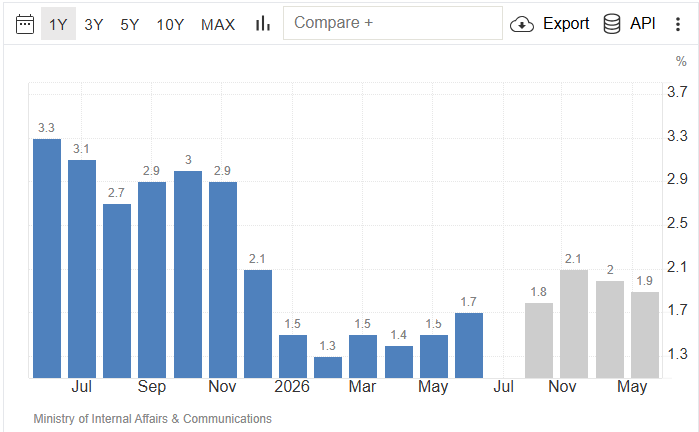
[All charts in this section: Trading Economics]
The CPI figure is particularly important for the Yen carry trade. The USD/JPY currency pair has been trading near 159–162, close to 40-year highs, on a Fed funds rate of 3.50–3.75% against a BOJ policy rate of just 1.00%. This gap has been narrowing but is still wide enough to keep the classic trade alive: borrow Yen cheaply, buy higher-yielding dollar assets, pocket the spread. Japan's Ministry of Finance has historically intervened around these levels, reducing the exchange rate risk.
Tokyo's July CPI is already running hot, and the BOJ warned at the July 31 meeting that core inflation could exceed its 2% target. So if national CPI follows a similar path, it firms up expectations of a hike, compressing the rate differential that makes the carry trade profitable. A hot CPI print combined with any dovish surprise from the Fed could set the carry trade unwinding in motion, with a knock-on impact on global equities.
UK Labour Market and Inflation
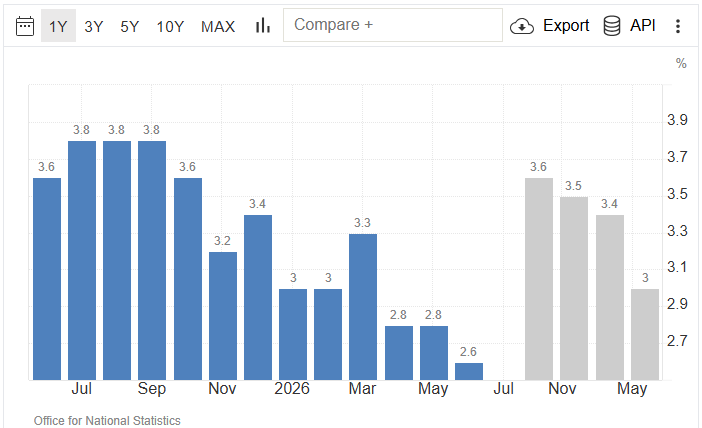
Tuesday brings the ONS's labour market overview, covering average earnings and unemployment for the three months to June. The unemployment rate held at 4.9% in the latest (March-to-May) reading, unexpectedly defying forecasts of a rise to 5.0%. A similar performance would support the view that the labour market is cooling gradually rather than cracking.
Wednesday's inflation report is the bigger event. Headline CPI eased to 2.6% in June, its lowest since March 2025, with core CPI unchanged at 2.6%. The Bank of England's most recent forecast pencilled in CPI creeping back up to "a little under 3%" in the third quarter and "a little over 3¼%" in the fourth, so a firmer July print would not come as a great surprise, and would reinforce the case for holding Bank Rate at 3.75% for a while longer.
Friday's retail sales will reinforce the picture of how the UK economy is holding up into the autumn.
FOMC Minutes
Wednesday evening brings the minutes from the Fed's July meeting, the first chaired by new Fed Chair Kevin Warsh, who has so far adopted a notably quieter public communication style than his predecessors. At that meeting, the Fed held its policy rate. Still, three members wanted a 25bps hike, the widest split on the committee since 2016, reflecting concern that inflation, still running above target, could reaccelerate.
The minutes will be pored over for any sign that the committee is close to actually acting. A hawkish set of minutes would likely weigh on equities and support the dollar, while a more dovish tone would have the opposite effect. Last week's tame CPI print has already taken some heat out of the debate, but the question of whether the Fed's next move is up or down remains open.
Companies Reporting
| Date | UK Trading Updates & AGMs | UK Financial Results | International Results |
|---|---|---|---|
Monday 17 August |
Telecom Plus (LON:TEP) (AGM) Ukrproduct (LON:UKR) (AGM) |
MTI Wireless Edge (LON:MWE) (Interims) Optima Health (LON:OPT) (Finals) Thungela Resources (LON:TGA) (Interims) |
|
Tuesday 18 August |
Cavendish (LON:CAV) (AGM) Syncona (LON:SYNC) (AGM) |
BHP (LON:BHP) (Finals) Cambridge Nutritional Sciences (LON:CNSL) (Finals) Synectics (LON:SNX) (Interims) |
Home Depot (NYQ:HD) Jack Henry & Associates (NSQ:JKHY) Keysight Technologies (NYQ:KEYS) Toll Brothers (NYQ:TOL) |
Wednesday 19 August |
James Latham (LON:LTHM) (AGM) Oryx International Growth Fund (LON:OIG) (AGM) |
Ithaca Energy (LON:ITH) (Interims) Kenmare Resources (LON:KMR) (Interims) Oxford Nanopore Technologies (LON:ONT) (Interims) |
Analog Devices,. (NSQ:ADI) Estee Lauder Companies (NYQ:EL) Jyske Bank A/S (CPH:JYSK) (Denmark) Lowes Companies (NYQ:LOW) Nordson (NSQ:NDSN) Rockwool A/S (CPH:ROCK B) (Denmark) Target (NYQ:TGT) The TJX Companies,. (NYQ:TJX) |
Thursday 20 August |
JD Sports Fashion (LON:JD.). (TS) Potter & Moore (LON:PAM) (AGM) |
Hays (LON:HAS) (Finals) |
Deere & Co (NYQ:DE) Orkla ASA (OSL:ORK) (Norway) Ross Stores (NSQ:ROST) Walmart (NSQ:WMT) |
Friday 21 August |
MHA (LON:MHA) (AGM) |
Hunting (LON:HTG) (Interims) |
Nibe Industrier AB (publ) (STO:NIBE B) (Sweden) |
It's a quieter week for UK corporate news as we would expect from the mid-August lull. It is much the same Stateside, with only the big-box retailers Home Depot, Lowe's, Target and Walmart of note. As usual, let us know via the comments if you think we've missed anything of note.
US Retail
US news will be dominated by Q2 results from the retail sector, with Home Depot, Lowe's, Target, and Walmart between them covering most of what American consumers spend day to day.
Home Depot (NYQ:HD)
Home Depot reports before the bell on Tuesday. They go into these results having dropped 30% over the last year, following a consensus downgrade at the end of last year.
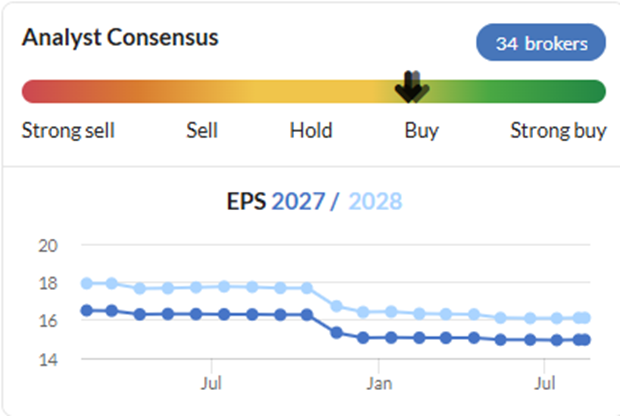
Management's full-year guidance is based on an increase in storm-related repair activity in the second half rather than a broader recovery in big-ticket renovation spending, so the read-through for comparable sales (guided to flat-to-2% for the year) and professional and contractor demand will matter most.
Gross margin remains under pressure from the mix, and tariffs remain a cost headwind, so look out for commentary on both.
Lowes Companies (NYQ:LOW)
Lowe's follows on Wednesday, and has similarly suffered from downgrades over the past year:
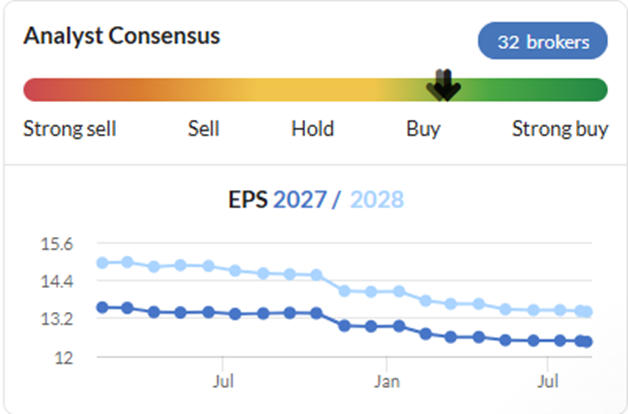
As with Home Depot, the market will be looking past the headline number for signs of stabilisation in housing turnover, which has weighed on large-ticket DIY and renovation spending for the best part of two years.
Again, margins may be key rather than sales (which are expected to be largely flat). The operating margin holding up despite fuel costs and tariff pressure would validate the $1 billion productivity program that management has been pursuing.
Target (NYQ:TGT)
Target also reports Wednesday and remains under the most pressure of the group to show it can arrest recent share losses to Walmart. Comparable sales trends and any change to full-year guidance will be the focus.
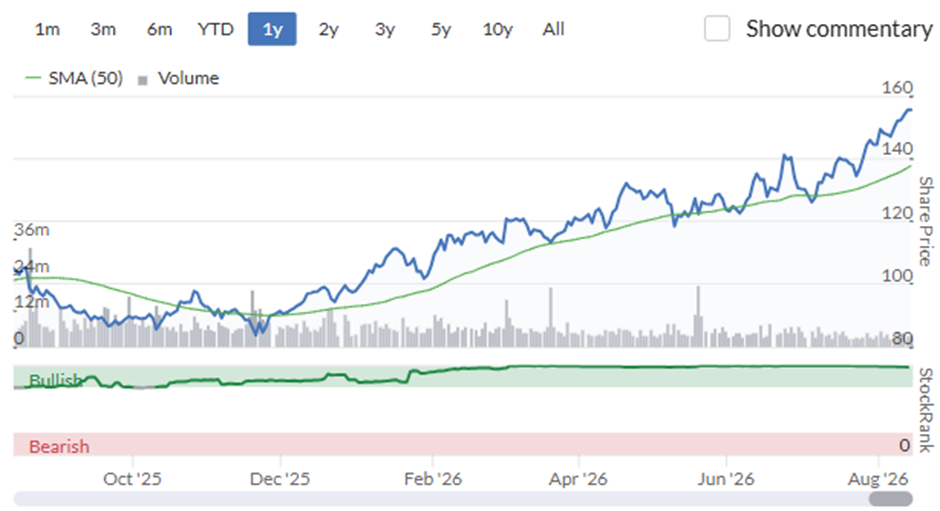
Not that this competitive threat is visible in the recent share price, which now trades above the average analyst price target of $141:
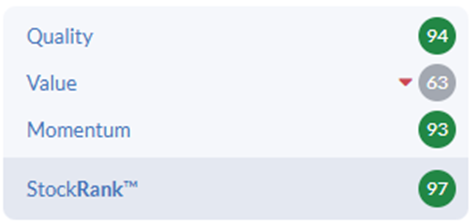
The Stockopedia Algorithms like it, though, and management will be keen to show they can keep that recent momentum going.
However, the market has now already priced in a good chunk of the turnaround story, so Q2 may need to show accelerating improvements to justify the recent run, or the stock risks disappointing even on a modest beat.
The TJX Companies,. (NYQ:TJX)
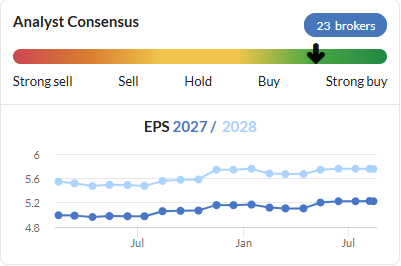
The dicount clothes retailer has seen some variation in broker consesnus over the past year:
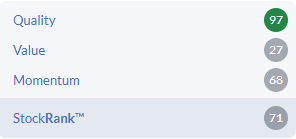
It remians a high quality compnay generating strong returns on equity, but isn't cheap:
Q1 significantly beat expectations. In a difficult consumer market, JX's "treasure hunt" value model is pulling shoppers across income levels, including a pickup in younger, higher-income shoppers who'd normally shop full-price retail. However, the flat share price suggests some caution on behalf of investors going into Q2. Elevated fuel costs and incremental payroll expense are expected to cause some SG&A pressure this quarter, offsetting the merchandise-margin and gross-margin expansion expected. The precise dynamics of these are key to the share price reaction.
Walmart (NSQ:WMT)
Walmart is the behemoth in the sector, with a market cap of close to $1tr, and closes out the week's retail earnings on Thursday. The group has consistently taken share through the downturn thanks to its grocery weighting and fast-growing advertising and membership income. The consensus is for adjusted EPS of around $0.74, up from $0.68 a year ago.
But it remains at a huge valuation premium to the sector and market, given that its scale limits its ability to grow:
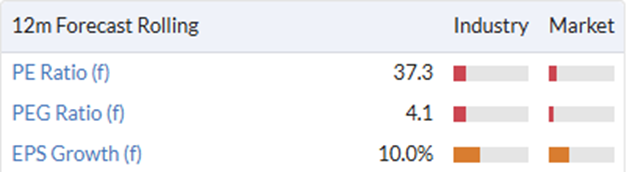
5-year CAGR sales growth is just 5%, and EPS is effectively flat over the same period.
The story is that e-commerce and advertising growth will start doing the heavy lifting. So these trends, plus membership income and any commentary on tariff-related cost pressure, will be the key threads to watch.
BHP (LON:BHP)
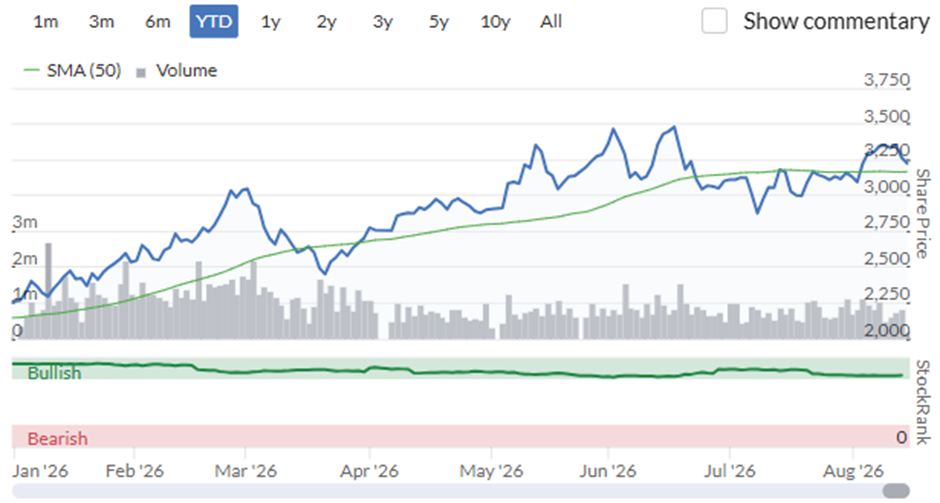
BHP reports full-year results for the year ended 30 June 2026 on Tuesday. Its operational update in mid-July already flagged a record iron ore performance of 265Mt (+1%). Copper output topped 1.9Mt for a second straight year and within the raised 1.9-2.0Mt guidance range, although at 1,953kt it slipped 3% year-on-year. Coal volumes were good, with BMA up 3% and NSWEC up 9%, both ahead of guidance.
The market didn't react to this guidance, with the share price already strong this year on the back of improved commodity pricing:
However, it's not exactly cheap anymore for a commodity producer, and the algos rate it a high flyer:
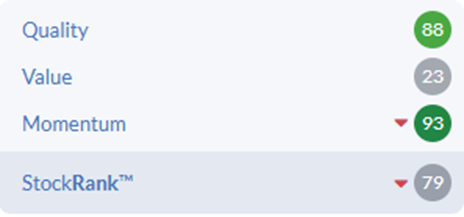
If the financial results disappoint, that Momentum Rank could start to look a little shaky.
These are some things to look out for:
- Copper's growing weight: in the half-year results, copper contributed more than half of group EBITDA for the first time (51%), with realised copper prices up 35% year-on-year at $5.74/lb, a huge tailwind. Investors will want to see that milestone confirmed for the full year, and hear more on how BHP plans to keep copper as its highest-conviction growth commodity.
- China and iron ore demand: with Western Australia delivering record volumes, management commentary on Chinese steel and property-sector demand will be key to the near-term iron ore price outlook.
- Capital allocation and Jansen: the Jansen potash project remains BHP's single biggest capital commitment, with first production expected in mid-CY27. Investors will want to see costs controlled and the timeline intact. While no longer relaly a high-yielder, the dividend payout may be an important signal, given how capital-intensive the growth pipeline has become.
Hays (LON:HAS)
Hays reports full-year results to 30 June on Thursday, alongside what management has flagged as a fuller strategic update on cost savings and capital allocation. July's Q4 trading statement showed like-for-like net fees fell 5% in the quarter, with permanent recruitment still the weak spot. Still, consultant productivity rose 8%, and the group delivered £50m of annual structural savings, ahead of schedule. Management guided full-year pre-exceptional operating profit to the top of the £37m-£46m consensus range.
Like most of the recruiters, Hays has struggled to take costs out faster than revenue has declined over the past few years. However, this small recent bright spot has led to the market pricing that the bottom is in for the sector and the share price has doubled:
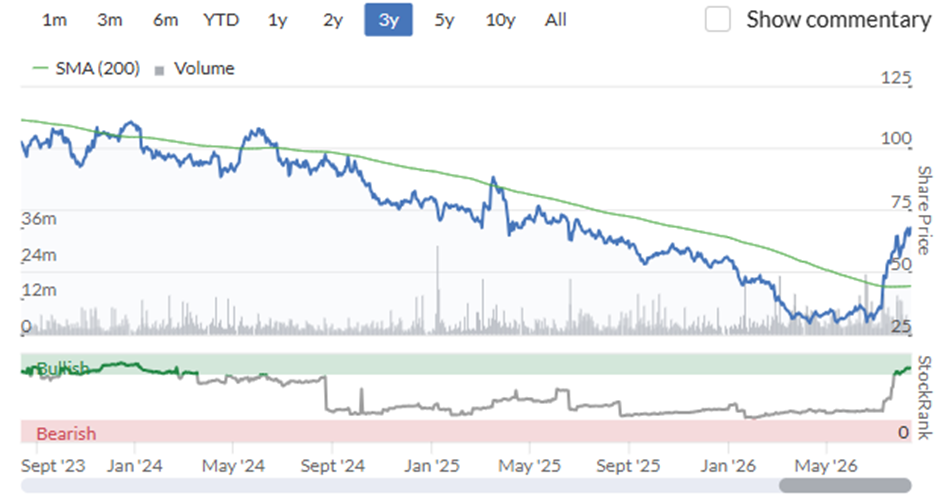
Markets often consider it better to travel than arrive. However, the pressure is on for management teams across the sector to show that the direction of travel really has reversed, and not just by (ironically) firing employees to cut costs.
Things to watch in these results:
- Portfolio reshaping: Hays has already exited six European countries and is reviewing seven more (Belgium, Brazil, Greater China, Malaysia, the Netherlands, Singapore and the UAE). Investors will want clarity on the costs and expected savings from any further exits, and reassurance that this process is closer to the end than the start.
- Permanent vs temp: temporary and contract activity has held up far better than permanent placements as employers remain cautious about headcount. Any sign of stabilisation in perm fees would be a welcome signal that hiring intentions are turning.
- Dividend and capital return: after a sharply reduced interim dividend earlier in the year, the market will be watching whether the improved cost base and cash generation support a more confident tone on shareholder returns from here.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

5 comments
Cavendish (LON:CAV) AGM on Tuesday and goes ex div for a 5% payment on Thursday. Depending on the AGM statement it may result in an interesting day on Wednesday. (I hold).
Last year Cavendish (LON:CAV) did not make an agm statement.
The Japan carry trade is potentially serious. Each time the BoJ and US support the yen it takes less time for the effects of the support to fade. It’s sending out the signal that, eventually, market forces will win out and they will have to raise rates in Japan. The question is whether this happens in an orderly or disorderly way.
If Japanese institutions find themselves needing to repatriate funds in a short timeframe, then it would have a sharp negative impact on bonds and equities.
The artificial supporting of a currency reminds me of the UK exit from the exchange rate mechanism. Eventually market forces will win out.
Speaking of recruiters, Gattaca (LON:GATC) is also due to publish a trading update on Monday: https://www.gattacaplc.com/inv...
Thanks, I should have been aware of this one as I hold, but hadn't realised they'd given a specific date for the scheduled TS, so that's very helpful.