The Week Ahead (1st - 5th December): The small but surprising market impact of the Budget

It has been a dramatic week in politics, with a fiery Budget and a fiery response to that Budget in the House of Commons. Politicians will be politicians.
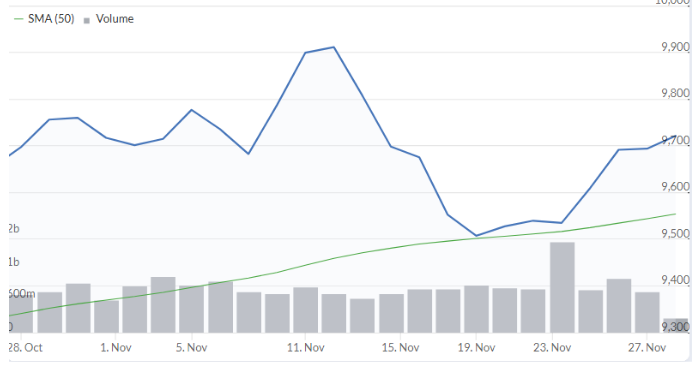
The markets have been less dramatic, once you take a step back: the FTSE rose 2% this week, which seems at odds with what you might have expected, given the headlines.
About half of those gains were racked up prior to the release of the Budget. The market then briefly wobbled during the speech, before continuing its rally.
On a 1-month view, little has changed for the FTSE:
Perhaps in even better news for the ordinary person, the pound has been strong. Here’s a 1-week view (source: xe.com), with the pound gaining more than 1% against the dollar:
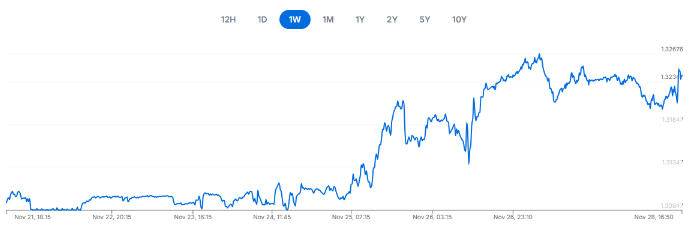
Prior to the Budget, the FT suggested that traders were betting heavily against the pound.
However, the tax-raising nature of the budget, and the increase in fiscal headroom accompanying it, says that the government’s borrowing needs will be lower than expected. This in turn strengthens the pound, forcing currency traders to unwind their bets as the market moved against them. Spending will be funded through higher taxation rather than through borrowing and printing.
Consistent with this logic, 10-year gilt yields have fallen post-Budget, from about 4.5% to 4.44%.
The conclusion? No major impact on markets.
For markets, the main conclusion is that government borrowing needs will be lower.
The Budget was of course a big story for individuals and for households - the lifting of the two-child benefit cap, the imposition of a mansion tax, and so on. The freezing of tax thresholds until 2031. The shrinking of cash ISAs to £12k for the under-65s. But these do not directly impact most companies and markets.
When it comes to the potential for more interest rate cuts, inflation has been a sticky subject. And the OBR has just revised up its average CPI forecast from 2.6% to 3.0%, for the period 2025-2029. But in the same paragraph, they said: “Policy measures in this Budget reduce CPI inflation by 0.3 percentage points in 2026.”
Therefore, while inflation is stubbornly remaining above the Bank of England’s 2% target, this year’s Autumn Budget is thought to be deflationary in nature. Taxation is deflationary, after all.
The impact on rate cut forecasts was to increase the likelihood of a BOE rate cut in December, from 85% to 95%.
Overall, therefore, the Budget gives us a slightly stronger pound, and more certainty that a rate cut will happen in December.
The best thing about the Budget is probably that we can all stop talking about it! We can all now plan ahead for the next year without trying to guess what’s in it.
For the next week, I’m not expecting any major macro news, but we will have plenty of interim reports and AGM statements to review.
Economic Calendar
| Date | Time (GMT) | Country | Event |
|---|---|---|---|
1 December | 09:30 | UK | Mortgage Approvals |
1 December | 15:00 | US | ISM Manufacturing PMI |
2 December | 07:00 | UK | Nationwide House Prices |
2 December | 10:00 | EU | Inflation Rate |
3 December | 12:00 | US | MBA 30-Year Mortgage Rate |
3 December | 13:30 | US | Import/Export Prices |
3 December | 14:15 | US | Industrial Production |
3 December | 15:00 | US | ISM Services PMI |
4 December | 09:30 | UK | S&P Global Construction PMI |
4 December | 13:30 | US | Initial Jobless Claims |
5 December | 07:00 | UK | Halifax House Price Index |
5 December | 13:30 | US | Unemployment Rate |
5 December | 15:00 | US | Michigan Consumer Sentiment |
Companies Reporting
| Date | UK Trading Updates and AGMS | UK Financial Results | International Financial Results |
|---|---|---|---|
Monday 1 December | Croma Security Solutions (LON:CSSG) (AGM) PCI- PAL (LON:PCIP) (AGM) Quantum Base Holdings (LON:QUBE) (AGM) | Impax Asset Management (LON:IPX) Peel Hunt (LON:PEEL) One Health (LON:OHGR) Solid State (LON:SOLI) ECO Animal Health (LON:EAH) | |
Tuesday 2 December | PRS Reit (LON:PRSR) (AGM) Crystal Amber Fund (LON:CRS) (AGM) | Topps Tiles (LON:TPT) Victrex (LON:VCT) Treatt (LON:TET) Gooch & Housego (LON:GHH) On Beach group (LON:OTB) Foresight group (LON:FSG) Discoverie (LON:DSCV) Celebrus Technologies (LON:CLBS) System1 (LON:SYS1) Mercia Asset Management (LON:MERC) Severfield (LON:SFR) IG Design (LON:IGR) Vianet (LON:VNET) Tpximpact Holdings (LON:TPX) Newriver Reit (LON:NRR) Augmentum Fintech (LON:AUGM) | Crowdstrike Holdings (NSQ:CRWD) |
Wednesday 3 December | Cordel (LON:CRDL) (AGM) Schroders (LON:SDR) (AGM) | Paragon Banking (LON:PAG) Victorian Plumbing (LON:VIC) NextEnergy Solar Fund (LON:NESF) SDI (LON:SDI) Ondo InsurTech (LON:ONDO) SysGroup (LON:SYS) | Salesforce (NYQ:CRM) Royal Bank of Canada (NYQ:RY) Industria de Diseno Textil SA (MCE:ITX) AIA (HKG:1299) Snowflake (NYQ:SNOW) |
Thursday 4 December | Ruffer Investment (LON:RICA) (AGM) YouGov (LON:YOU) (AGM) Volta Finance (LON:VTA) (AGM) Supply@Me Capital (LON:SYME) (AGM) Bioventix (LON:BVXP) (AGM) Doric Nimrod Air Three (LON:DNA3) (AGM) | Future (LON:FUTR) SSP (LON:SSPG) Premier Miton (LON:PMI) AJ Bell (LON:AJB) Mind Gym (LON:MIND) | Toronto-Dominion Bank (NYQ:TD) |
Friday 5 December | James Halstead (LON:JHD) (AGM) Associated British Foods (LON:ABF) (AGM) |
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

29 comments
Tim/ Sam
Thanks for the responses. The only thought that I had was the scrutiny of ISAs would improve with this measure below, plucked from the Government website.
Digitalisation of ISA reporting
Following industry feedback and internal analysis, the government has decided to postpone mandatory digital reporting under digitalisation of ISAs until April 2028.
To make sure of a smooth transition and minimise disruption for savers, ISA reform (cash limit change) will proceed from April 2027, using existing reporting methods, while digitalisation of ISA reporting mandation will follow one year later.
This staged approach reflects industry concerns and supports effective delivery of measures designed to boost investment and improve returns for consumers.
As we work towards April 2028, HMRC will continue to work closely with industry to support preparations ahead of the start of the test period in Autumn 2026.
Like yourselves, I think it all looks a mess.
Intuitive
Thanks I missed the gratuitous ageism bit. Can't imagine that ISA/SIPP providers will be up for offering different product specs for different ages. I'd think they will simply impose restrictions on which securities can be held so as to avoid the issue. Don't get me wrong I'm the wrong side of the age gap, so would be exempt, but I would be surprised if providers can be arsed to layer in the complexity required. easier for them to just exclude "cash like" securities.
Paul Walton
Complexity indeed. So the age of the account holder would determine the process to be followed - age when the security goes ex-dividend? age when the divi is paid? age when it is credited? cleared? what if the security is sold just before it goes ex divi? do they pretend the sale price does not include implied divi?
And what stops the various "cash like" securities from simply converting to accumulation shares where all income generated simply rolls into the unit price so is not classed as income for the shareholder?
What a shambles.
Victoria (LON:VCP) half year results December 1st.
Pubs and hotels really getting hit in the budget, surprised this has not been mentioned: https://www.bloomberg.com/news...
Won't be many pubs left soon, already got hit by last years budget.
Not a sector l invest in.
Its sad...a British institution that is disappearing.
Reeves said that “cash like” instruments would not be permitted in stocks and shares isas. Not clear exactly what she means. Bonds? Money market funds? Pref shares? Gilts?
Also suggests that cash held in S&S isas will be restricted/penalised.
I do not systematically hold cash in ISAs but often have substantial balances as result of timing issues between exiting and reinvesting.
It looks like no cash like instruments and tax payable on any interest earned from cash held.
I suspect every investor will at some point have held cash or a MM fund to ride out an expected downturn or whilst pound cost averaging in, these being disciplined approaches.
Will this potential change either put nervous investors off or encourage more risky investing? What would happen if brokers started to offer 0% interest on cash (perversely, weren’t they forced to increase interest rates not so long ago?).
Currently a ‘consultation’ so hopefully brokers will point out the obvious and enough investors will contact their MPs etc.
It looks like no cash like instruments and tax payable on any interest earned from cash held.
Hi Paul
Ahead of the consultation it's guesswork as to how this will work, although the idea seems to be that interest on "cash-like instruments" will be taxed, which would be easy enough to do as it's clearly impossible to stop people holding cash in an ISA for some period of time. That wouldn't stop anyone holding cash in a Stocks and Shares ISA for the purposes you mention, but would stop anyone doing so in order to emulate a Cash ISA, which is the intent.
ISAs were always intended as a mass market product for unsophisticted investors. I doubt the minority of private investors who think this is an issue are going to be a consideration for the government no matter how many complain to their MPs.
Overall the government's attempt to persuade people to move some of the £1 trillion sitting in cash into the stockmarket is to be applauded. Sadly the methods suggested amplify how restricted they are in terms of money to invest - the stamp duty holiday for new listings is good, but a permanent removal would have been better, and the EIS / VCT changes are a mixed bag, although it'll be interesting to see what the definition of "knowledge intensive businesses" ends up as.
timarr
Is this on new investments? I have quite a bit of cash at the moment in my S&S ISA plus some "cash like" investments. Cash was getting 4% interest probably a bit less now. In HL l can just transfer cash into a cash ISA but IG group (LON:IGG) probably not so easy.
This could turn into a real mess. If l make an investment how do you know if is 2026 money or from 2020? May need to use a different ISA for 2026.
Some further details about the treatment of cash within ISA's.
"HMRC closes cash ISA loopholes with new transfer ban and cash interest charge
HMRC has confirmed restrictions on ISA transfers and introduced a charge on cash held within investment ISAs, following warnings that existing rules could undermine the chancellor’s cash ISA cap.......
The government will block all transfers from stocks & shares ISAs and Innovative Finance ISAs into cash ISAs, introduce tests to determine whether an investment is “cash like” and levy a charge on any interest paid on cash held in a stocks & shares or Innovative Finance ISA......
Hollands said.....levying a charge on cash held within stocks & shares ISAs is yet another stealth tax that will impact genuine investors who sometimes decide to park money in cash for a period of time awaiting investment, or because they are nervous about the market environment,” he said.
“The ‘tests to determine whether eligible investments are ‘cash like’ will throw doubt about access to money market funds within Stocks & Shares ISAs and could even bring short-dated bonds into question......The measures will take effect from April 2027......"
source:- https://www.trustnet.com/news/...
Even more complexity which we dont need. What a mess
Re ISAs
Worth noting...my bold. Draw your own conclusions.
These rules will apply to investors under the age of 65.
Industry will be consulted on the draft legislation, which will be made by amendments to the ISA regulations, and laid before Parliament well ahead of April 2027.
"Industry will be consulted on the draft legislation"
At which point you would hope they will kick it out as unworkable/complex to the point of absurdity.
Sometimes I wish I was a tax lawyer, as I reckon the legislation is worth at least another 1000 pages in the UK's already ridiculously long tax law, not to mention years of follow on work on advising clients how to avoid it anyway!
I guess if I were to be affected by the upping of the dividend tax rate to 10.75% I would be looking towards VM shares.
One hesitates to demonstrate ignorance, but apart from a Korean company what are VM shares?
VM = Value/Momentum
I wonder how they will treat past ISAs? So I can put only £12K per year cash. But say someone has a £200K portfolio and goes to cash in a crash etc bear market then they can’t or they will pay a big fine? Seems clear as mud. So then they would taxing ISAs.
Don't worry, there's no hurry.
Only applies to new funds added. Many stocks and shares ISAs offer good interest on uninvested cash so you really wont lose out
Agree. If they don't offer a decent rate (or cap the amount that earns interest) then just park in a money market fund/ETF (CSH2, UESD, ERNS etc). I prefer ETFs as you can sell same day if you spot a sudden bargain.
How do you keep old / new funds separate 5 years from now.?
Complete ill thought out confusion as usual?
Why? So long as money as it remains in the isa wrapper, any gains remain free of tax
Not going forward. How will you identify which is new money or old, if you hold your ISA with the same broker? Easy if you set up a new ISA with a different broker. Will brokers mark the new funds somehow? What happens if l sell all my investments?
Whitbread (LON:WTB) warned today about the budget impact: https://www.stockopedia.com/sh...
Shares fell over 11%. Budget changes may have more impact than some think.
Thanks Graham.
I believe ZIGUP (LON:ZIG) report on Wed. 3rd and - probably of limited interest - American Eagle Outfitters (NYQ:AEO) on Tues. 2nd.
Have a good weekend.
There were more leaks than on a leek farm in Wales!
There were more leaks than on a leek farm in Leek, Derbyshire.
Umm, Leek, Staffordshire!
Andrew Neil DESTROYS Labour's Budget 'Nobody Voted For This'