The Week Ahead (2-6 Jun): ECB Rates, US Discount Retailers, UK Financials, Crowdstrike

Tariff-related news continues to dominate broader market moves. Last week, a post by Donald Trump on “Truth Social” accused the EU of not being serious about trade discussions and threatened sweeping 50% tariffs on the bloc. This prompted a market sell-off. Then, on Thursday, a US Federal trade court halted all of Trump’s tariffs, except for the 25% tariffs on the auto industry, which were implemented under a different Act. The rest of the tariffs would have ended in 9 days’ time. US stocks jumped in response to the news. However, the administration appealed the decision, and the order was stayed, causing further confusion. This adds to the uncertainty for businesses, who will be unable to predict what their costs might be at any point in the future.
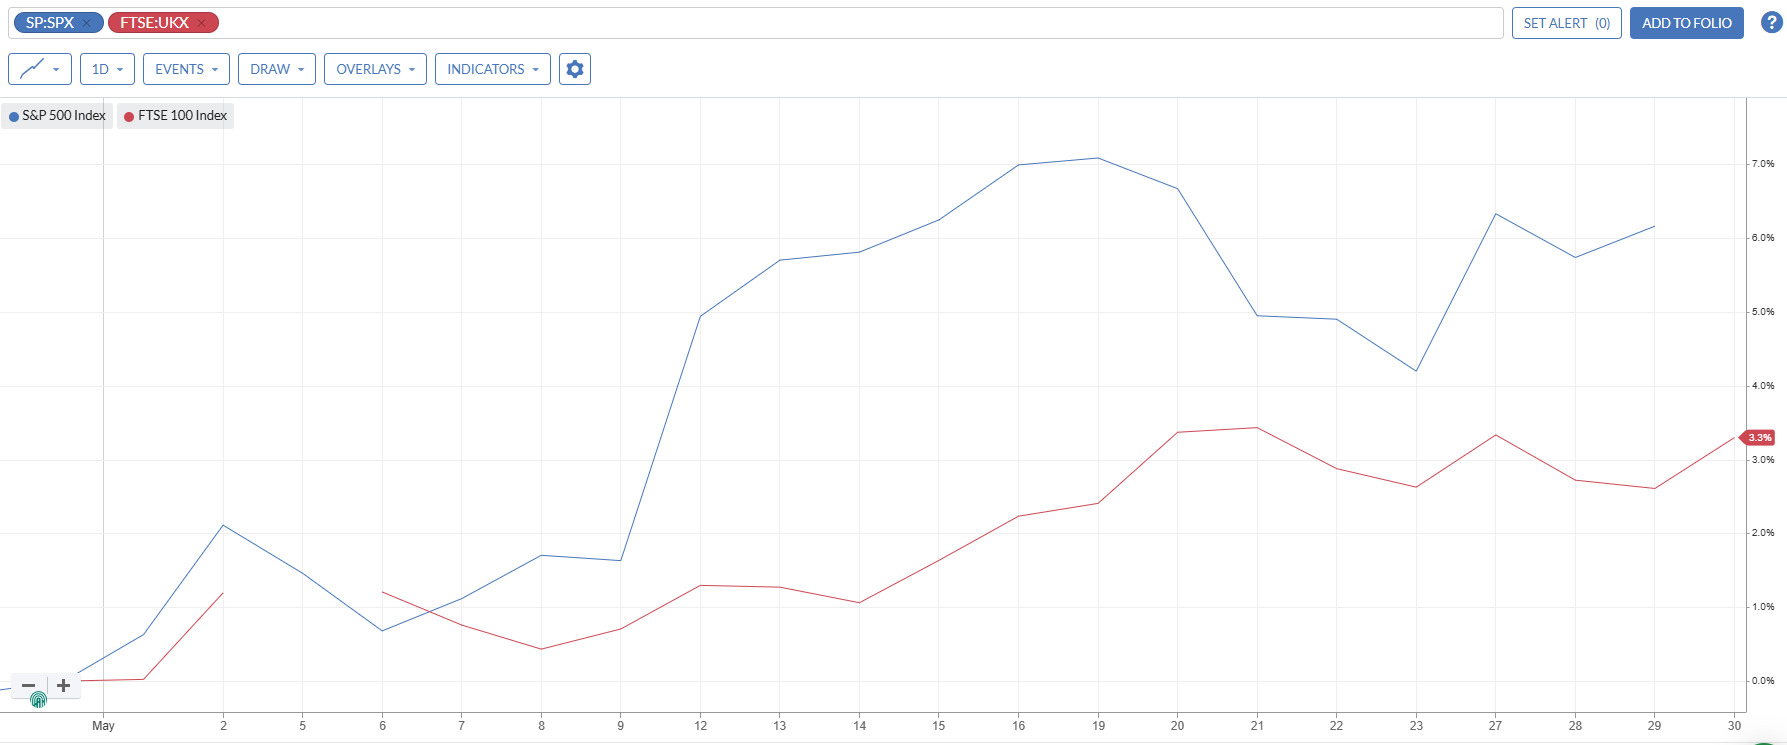
This rise in the last week means that S&P500 means that it is back into the lead over the FTSE on a 1-month view:
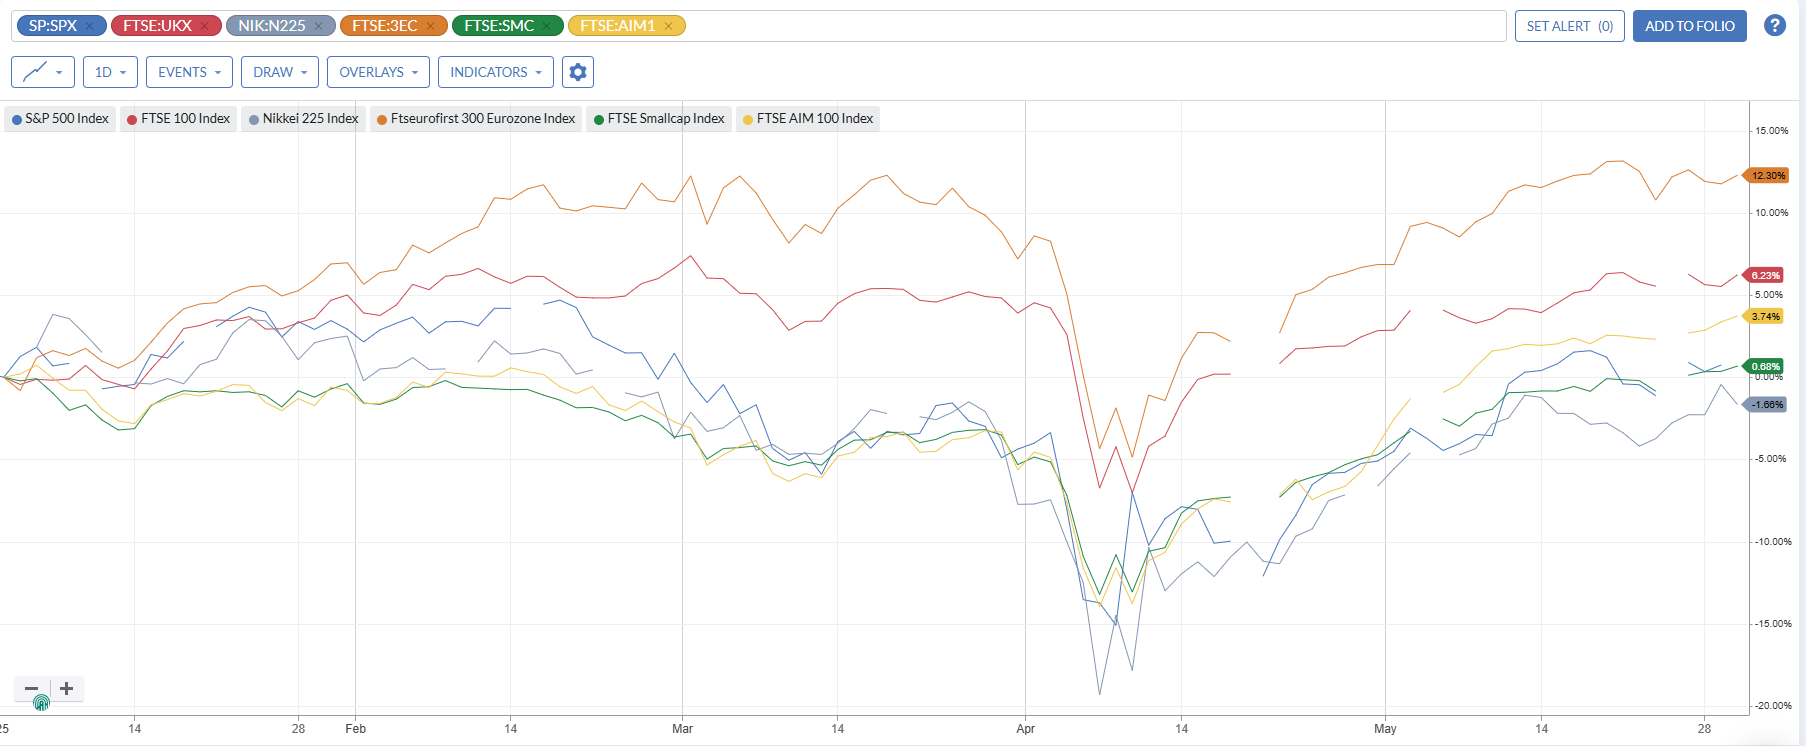
Although the FTSE100 and Euro indices are still winning YTD:
Investors in the coming week can expect more tariff-related news, even if it is just presidential comments on social media! Despite the uncertainty, options on US indices don’t look particularly highly-priced, with traders expecting volatility to remain relatively low, as indicated by the VIX:
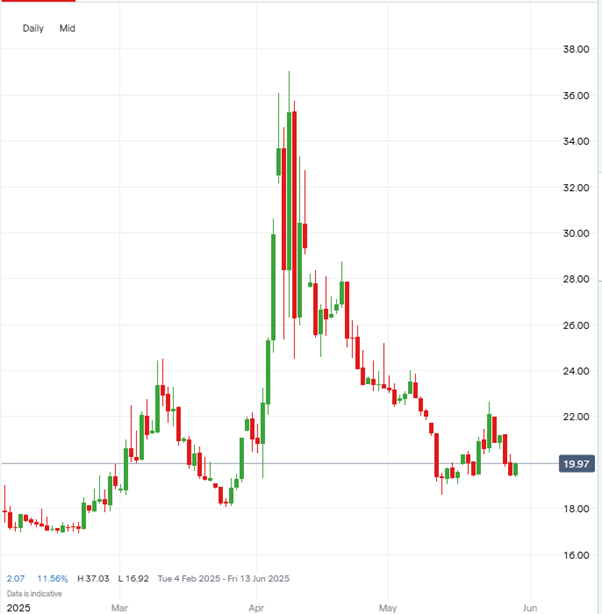
This may mean that investors can protect themselves from any tariff-related falls relatively cheaply at the moment.
Here’s what we can look forward to next week:
Economic Calendar
Monday 2nd |
||
09:30 |
UK |
BOE Consumer Credit Mortgage Approvals PMI Manufacturing |
15:00 |
United States |
Manufacturing PMI |
Tuesday 3rd |
||
10:00 |
Euro Area |
Inflation Rate |
15:00 |
United States |
Job Openings |
Wednesday 4th |
||
15:00 |
United States |
Services PMI |
15:30 |
United States |
Crude Oil stocks |
Thursday 5th |
||
13:15 |
Euro Area |
ECB Rate Decision |
13:30 |
United States |
Balance of Trade Initial Jobless Claims |
Friday 6th |
||
07:00 |
Germany |
Balance of Trade |
07:00 |
UK |
Halifax HPI |
13:30 |
United States |
Non-Farm Payrolls Unemployment Rate |
A relatively quiet week for economic news. The only interest rate decision is in the Euro Area. The ECB lowered interest rates by 25 basis points on 17 April. At the time, the ECB cited lower growth and inflation expectations due to global trade worries. Expectations are for an 8th 25bps cut in the headline rate for similar reasons.
Given the tariff backdrop and the reasons given for Trump’s tariffs, Balance of Trade numbers could also be in the spotlight. Finally, in the UK, the Halifax House Price Index is released on Friday, and we’ll find out what impact the market turmoil and budget changes have had on sentiment here.
Companies Reporting
UK Trading Updates |
UK Financial Results |
International Financial Results |
|
Monday 2 Jun |
ME Group |
Sirius Real Estate (Finals) |
Campbell’s Co (Q3) |
Tuesday 3 Jun |
Pennon (finals) Engage Xr (Finals) Theracryf (Finals) FD Technologies (Finals) Gooch & Housego (Interims) Chesterfield Special Cylinders (Interims) Ferguson (Q3) |
CrowdStrike (Q1) Dollar General (Q1) Hewlett Packard (Q2) Guidewire Software (Q3) |
|
Wednesday 4 Jun |
B&M (Finals) DiscoverIE (Finals) Ninety One (Finals Rtw Biotech (Finals) Paragon Banking Group (Interims) Ramsdens (Interims) Seraphim (Q3) |
Dollar Tree (Q1) GameStop (Q1) Oxford Industries (Q1) |
|
Thursday 5 Jun |
Mitie (Finals) CMC Markets (Finals) Wise (Finals) Wizz Air (Finals) Workspace (Finals) Dr. Martens (Interims) |
Broadcom (Q2) DocuSign (Q1) |
|
Friday 6 Jun |
Bango (Finals) |
US Discount Retailers
It is a quiet week for US reporting. However, discount retailers will be in focus as both Dollar General and Dollar Tree report Q1 earnings. They are the Poundlands of the US! Given my lack of knowledge of the US, I asked google AI what the difference between the two companies is, and this is what it said:
The main difference between Dollar Tree and Dollar General is their pricing structure and overall store focus. Dollar Tree primarily focuses on selling items at one price point, though they have expanded beyond the “$1” mark. Dollar General offers a wider range of items at varying prices, including items at a dollar or less, but also items with higher price points.
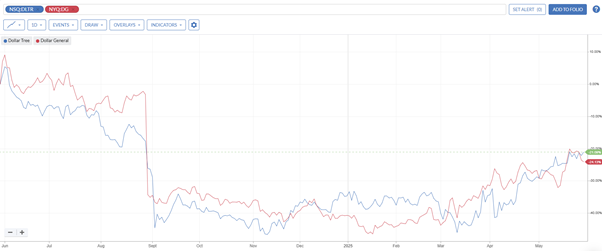
In reality, it seems there isn’t much difference, which is why the companies’ share prices have pretty much traded in step over the last year:
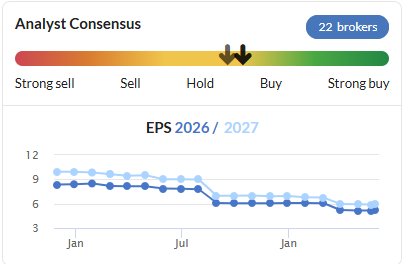
Both companies cut store sales and profit forecasts in September last year, citing that cost-conscious customers were cutting back spending on their higher-margin goods to prioritise essential purchases. As always, the share price fall looks more severe than the broker downgrades:
Dollar Tree
Dollar General
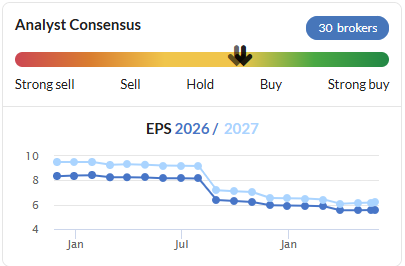
More recently, the broker consensus for looks like it has bottomed and is ticking up slightly. As has the share price of both companies. Investors will be looking for this recovery to be confirmed by the Q1 results.
In terms of the head-to-head, there is little to choose between the companies:
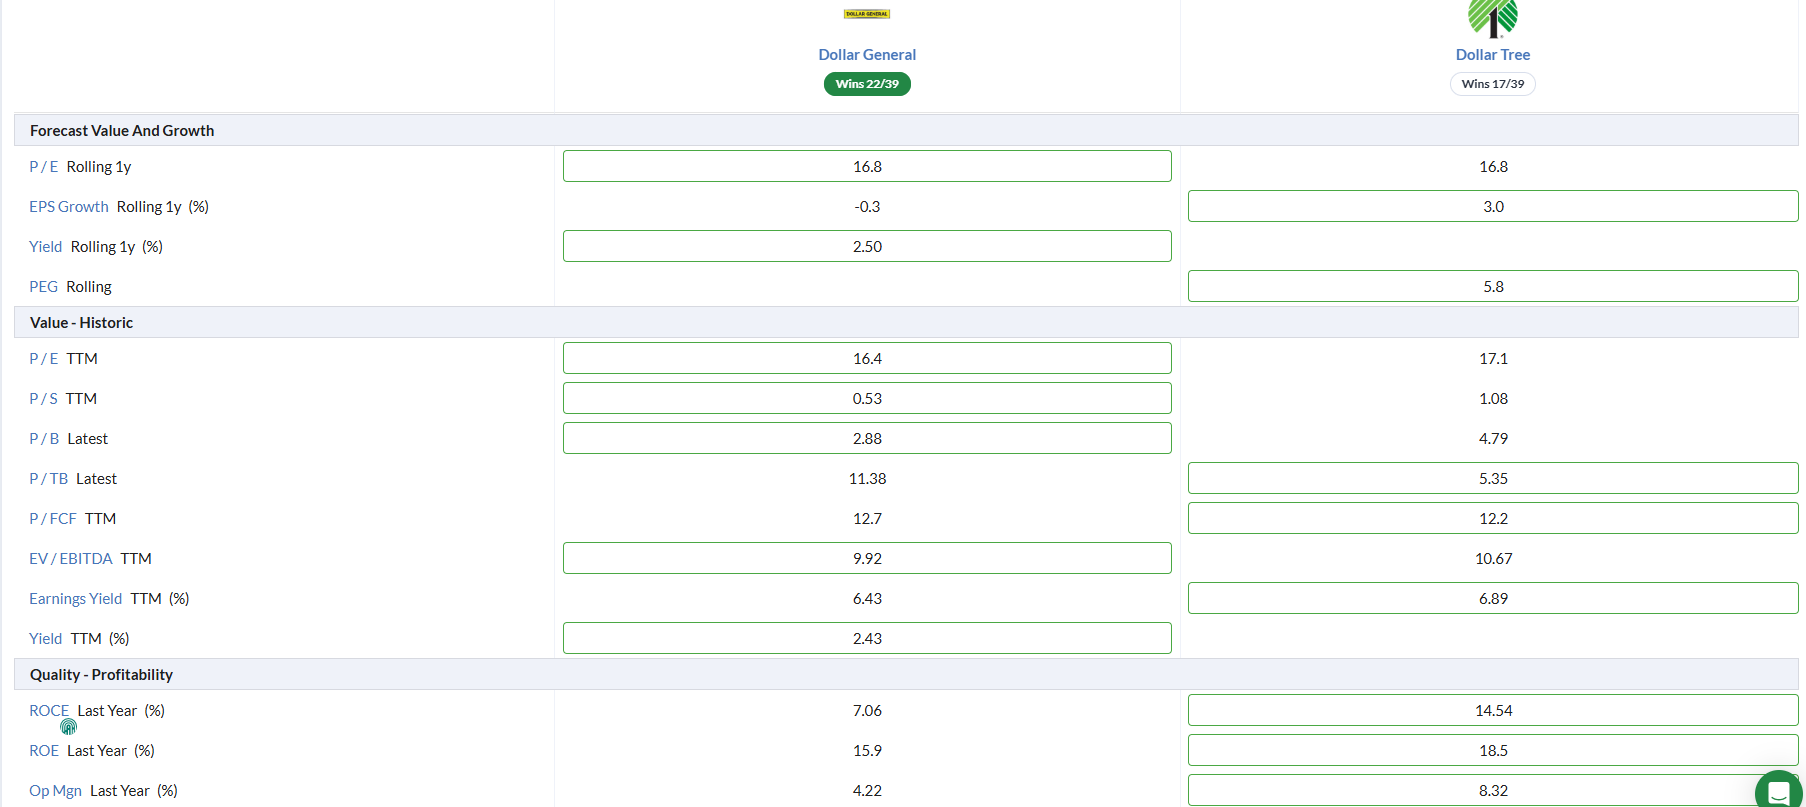
Both are on a P/E of around 17, EV/EBITDA of 10, and a P/FCF of about 12. Earnings for both companies are forecast to decline slightly this year before a modest recovery in 2026. Dollar Tree has double the operating margin and ROCE, but Dollar General pays a modest dividend.
In general, I can’t help thinking that these companies show the difference between US and UK valuations. A UK value retailer such as B&M is a much better company on most metrics than these US-listed businesses and is on a much cheaper multiple. Both US retailers need to start beating forecasts, not just meeting them to justify their current ratings on a global comparison.
UK Financials
CMC Markets (LON:CMCX)
CMC Markets is a fairly straightforward business, so we should not expect any surprises. They issued a trading update in January, saying:
The Group remains on track to achieve annual net operating income in line with previous guidance.
Management also remains confident in meeting its cost guidance of approximately £225 million, excluding variable remuneration and non-recurring charges.
Helpfully, they include the current analysts’ consensus on their website:
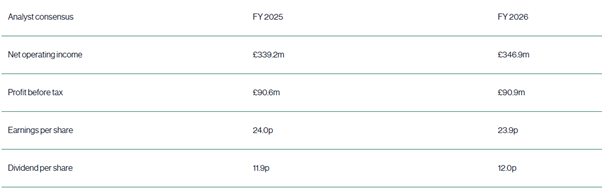
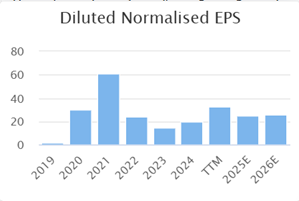
2026 estimates are currently for flat EPS, yet this is a business that should be benefiting from global market volatility.
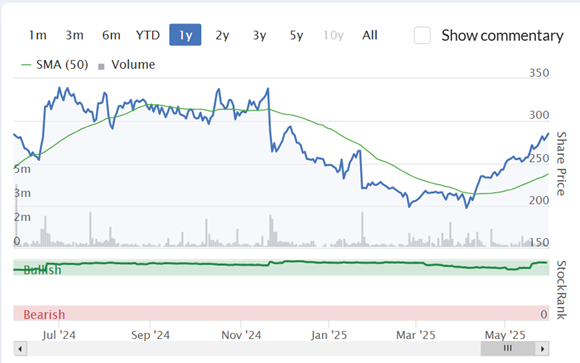
The long-term EPS trend, together with the current analysts’ consensus for 2026, makes the shares look fully valued on 12x forward earnings:
Competitor IG Index has a better long-term trend, benefits from similar market dynamics and is on a cheaper multiple:
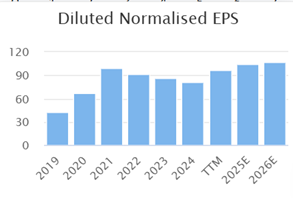
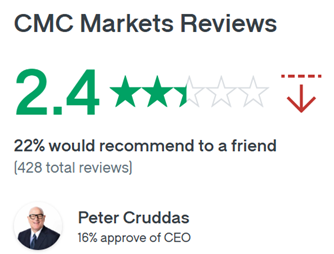
However, CMC Markets has the ability to outperform IG in the boom times, thanks to its more dynamic hedging strategy. If the outlook guidance for FY26 shows significant upgrades due to better market conditions, the company will look in much better shape. Complicating matters, CMC Markets lost its CFO earlier this year with immediate effect. This may be simply a clash of personalities with a rather unique founder-CEO. However, such changes remain a risk for a company that has very mixed Glassdoor reviews:
Wise (LON:WISE)
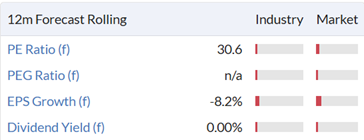
Wise is a much-loved money transfer and foreign exchange business that derives significant benefits from its scale. However, it is not cheap:
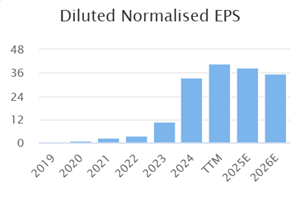
Especially for a company whose forward EPS trend looks like this:
However, the algorithms classify this as a High Flyer, and our research into these types of stocks shows that the Value Rank has little bearing on the short-term share price:
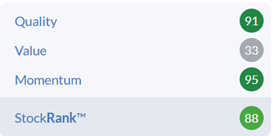
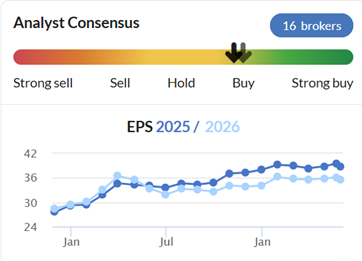
While the Momentum Rank remains high, investors usually do well by staying aboard. However, it is often better to sell quickly if the Momentum Rank takes a tumble. There are signs of some small downgrades in EPS consensus recently, so the outlook in the upcoming FY25 Results will be as important as the numbers themselves:
CrowdStrike
CrowdStrike is a US cybersecurity company, most famous in the UK for causing a global internet outage in July 2024! This is another High Flyer:
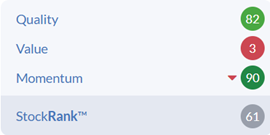
Again, the 120x P/E is not necessarily concerning to investors in this type of stock, particularly as it is backed by rapid sales and earnings growth. However, the falling Momentum Rank could signal problems ahead. The earnings trend looks a little worrying:
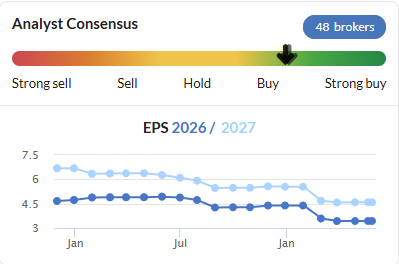
Q1 missed expectations, and Q2 is forecast to be weak:
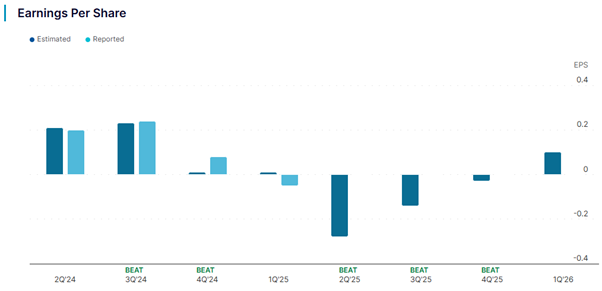
[Source:NASDAQ]
The company has recently announced layoffs in the US to improve its bottom line. Investors will be looking for signs that these are having a positive impact. Otherwise, any further deterioration of the Momentum Rank may mean the buying crowd go on strike.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

8 comments
Two that I will be following...
I would be interested in seeing how B&M is coping in a squeezed retail space.
Also Paragon, in my view the gold standard of BTL lending. I would be surprised if defaults were an issue but would be keen to see what the net Interest rate margin looks like.
Wise (LON:WISE) ”is much-loved”. By whom?
I’m a long term customer who bought the share partly on the back of the excellent service I have received from Wise all over the world.
First rate company on many levels in my opinion.
By people who use it. It seems to be top of the class. Many ex-pats use to transfer money.
I think card terms could be improved, £200 withdrawal from ATM per month, without fees, is far too low.
I use it also, but l don't have the card, there are better choices for me.
Chemring (LON:CHG) H1 results Tue 3 June
Thanks
Wise (LON:WISE) quoting a recent FT comment:
Barclays estimates that about 83 per cent of the market is still controlled by traditional banks, leaving plenty of space to build share even before factoring in any structural growth.
Progress has been slower in its “Platform” business, which involves white-labelling the company’s payment networks for established banks.
End of quote. Seems from that that there is plenty to go for. Plus the company is considering adjustments to allow inclusion in the FTSE100.
As a point of scuttlebut, i have used Wise abroad and they are very good.