The Week Ahead (2 – 6 Nov): UK Budget, Google & Bitcoin "crash", US Midterms, BoE Interest Rates, AAPL, AMD, ARM
The big news for UK-focused investors last week was the Budget. Many investors' worst fears were not realised. CGT rates were not touched, and the tax-free pension sum remained the same. It could be argued that the Chancellor's backtracking on limiting the cash component of an ISA was bad news for the stock market. Still, it also spared investors a complicated reporting system or rules to remember. In many ways this was a goldilocks budget: small, targeted cost-of-living measures may help consumer spending at the margin, but they weren't so generous that bond markets would take fright.
The targeted tax rises did hit some listed companies. Banks face a temporary increase in the bank surcharge from 3% to 6% for 15 months from January 2027. But because the rise was smaller than many investors had feared (reports had suggested 8%), UK bank shares actually rose on the day. Gambling stocks also gained: Machine Games Duty on higher-stakes machines will rise from 20% to 25%, but this was significantly lower than the doubling some had feared.
The net result was a flat FTSE 100 for the week, while smaller UK company indices rose.
The UK 5yr gilt yield retreated from its pre-budget peak and dropped below the psychologically important 5% level.
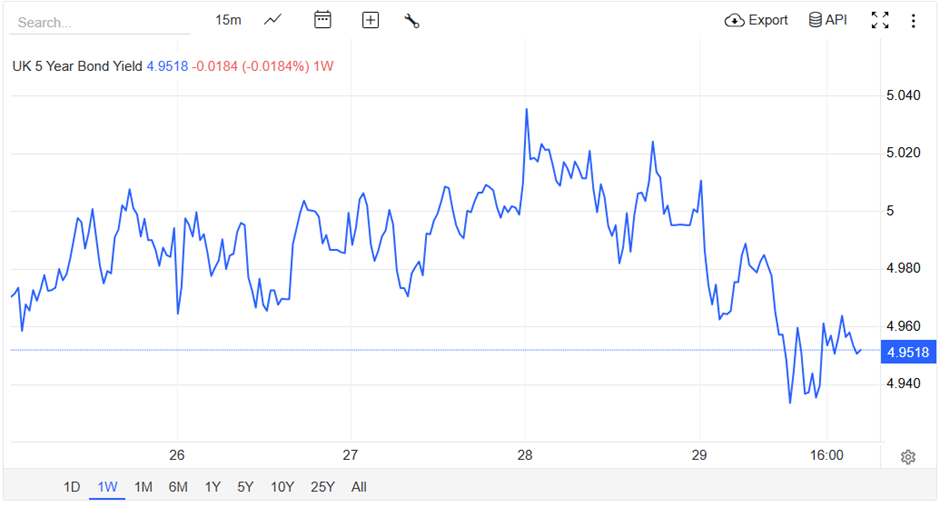
However, US bond yields also declined during the week, so this may be more a result of global trends than anything UK-specific.
Things have been far less calm for equity markets over the other side of the pond. One headline I read said that Google "crashed" due to concerns that Google's AI-generated summaries and conversational AI Mode are cannibalising traditional search advertising revenue. This certainly looks dramatic on a one-week chart:
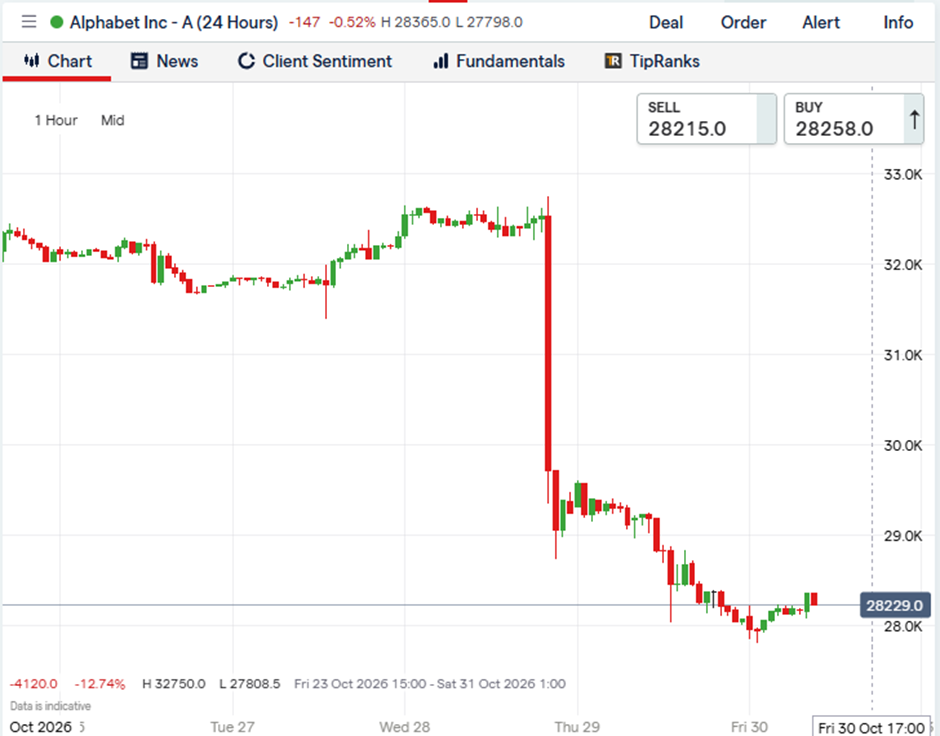
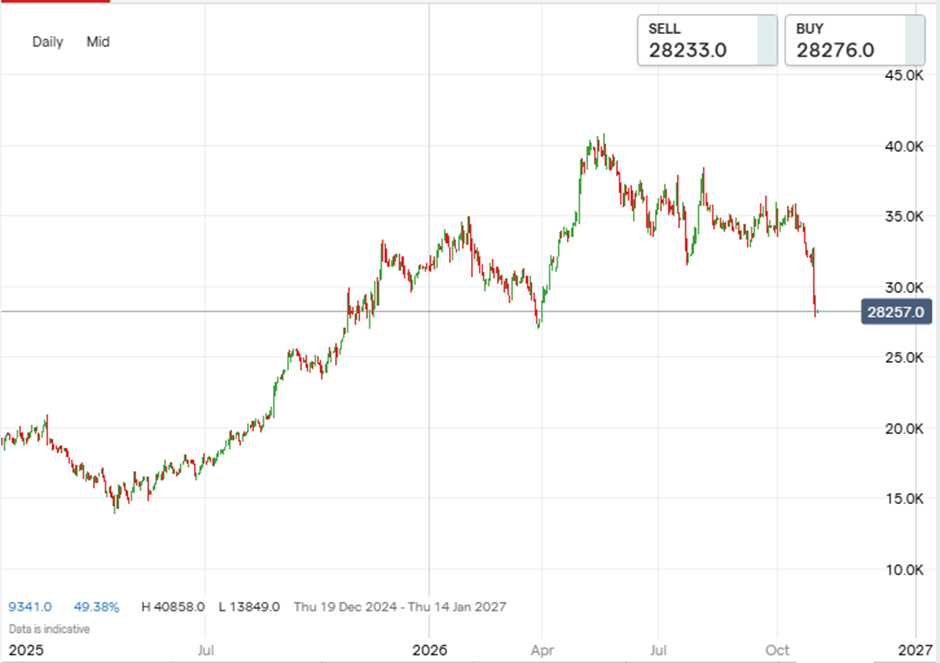
However, this is only 12% below where it started the week. Zooming out, the stock has yet to test the April lows, and is 46% above the share price at the start of 2025.
Many of us who tend to focus on smaller companies would love to see this sort of "crash" when our stocks release bad news!
The final market worry of note this week was the hacking of Binance by presumed North Korean hackers, with many describing it as "the largest bank heist in human history". The Binance founder has publicly said that "your money is safe, and we're covering every loss". However, bitcoin's price fell in response. There are a couple of reasons why:
- Binance initially responded by preventing deposits and withdrawals. This makes sense, but those who needed to convert to fiat currency quickly found themselves without funds.
- Crypto evangelists have described the industry as better than traditional banking because it is decentralised and can't be controlled by governments. However, many of the crypto platforms investors use for convenience are as centralised and controlled as conventional banking platforms.
- Binance certainly claims it can cover investor losses. However, until they do, there has to be some doubt, and who can say a larger hack in the future won't lead to losses beyond the platform's ability to compensate? There is no deposit protection or lender of last resort, and investors should treat cryptocurrency like a risky small cap equity - there's always a chance that it could go to zero tomorrow, with no warning – and position size accordingly.
Here's what we can look forward to next week:
Economic Calendar
Monday 2 November |
||
01:45 |
China |
Manufacturing PMI |
07:00 |
Germany |
Retail Sales |
15:00 |
United States |
ISM Manufacturing PMI ISM Manufacturing Employment |
Tuesday 3 November |
||
All day |
United States |
Midterm Elections |
15:00 |
United States |
Job Openings Factory Orders |
21:30 |
United States |
API Crude Oil Stock Change |
Wednesday 4 November |
||
01:45 |
China |
Services PMI |
10:00 |
Euro Area |
Inflation Rate Flash |
12:00 |
United States |
MBA 30-Year Mortgage Rate |
13:15 |
United States |
ADP Employment Change |
13:30 |
United States |
Balance of Trade |
15:00 |
United States |
Services PMI |
15:30 |
United States |
EIA Crude Oil Stocks Change EIA Gasoline Stocks Change |
23:50 |
Japan |
BoJ Monetary Policy Meeting Minutes |
Thursday 5 November |
||
07:00 |
Germany |
Factory Orders |
09:30 |
United Kingdom |
S&P Global Construction PMI |
12:00 |
United Kingdom |
BoE Interest Rate Decision |
13:30 |
United States |
Initial Jobless Claims |
Friday 6 November |
||
07:00 |
Germany |
Industrial Production |
07:00 |
United Kingdom |
Lloyds House Price Index |
10:00 |
Euro Area |
Retail Sales |
13:30 |
United States |
Non-Farm Payrolls Unemployment Rate |
US Midterms
It has seemed an incredibly long build-up to these elections, with what appears to be an increasingly desperate Trump, trying to put a brave face on his political missteps. The writing was largely on the wall when Operation Epic Fury quickly became Operation Epic Folly, as the Iranians blocked the Straits of Hormuz and kicked off a global inflationary spiral.
Prediction markets say the Democrats have about a 91% chance of winning the House and about a 65% chance of winning the Senate. The Senate odds have shifted from around 44% in March, showing how voters have become disillusioned with another foreign war and its impact on the cost of living.
A split government is strangely probably better for markets, as political inaction is often better than action. However, if the Democrats win both chambers, analysts expect the dollar to weaken moderately, although much of this is already priced in.
History points to a rally in the month after the vote as markets appreciate the uncertainty clearing. However, inflation and the Fed's next move should still matter more than the election.
BoE Interest Rate Decision
The most likely outcome next week from the Bank of England Monetary Policy Committee is a 25bps interest rate hike to 4.00%. Markets are almost fully pricing in this move, which comes on the back of recent interest rate rises by the other key global central banks:
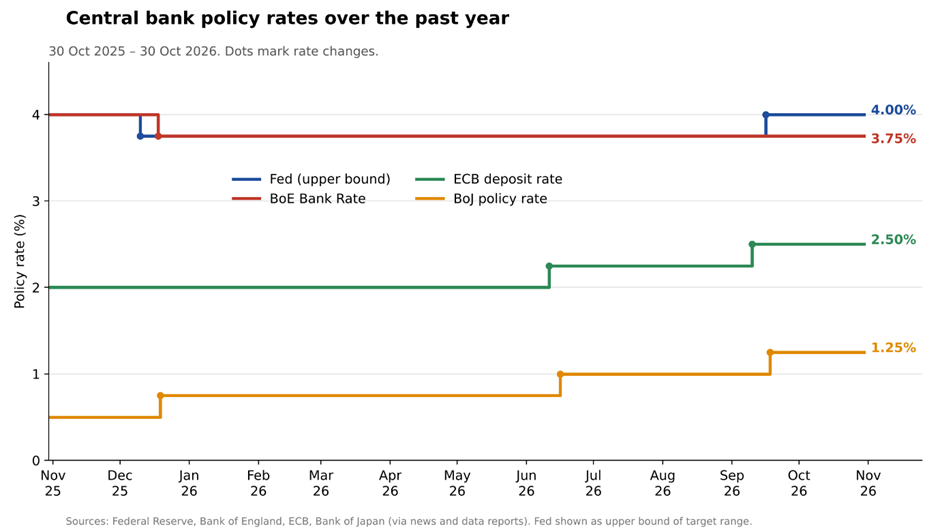
With the hike widely expected, the vote split and guidance will matter more than the outcome. In September, the MPC voted 6–3 to hold, with three members voting to hike. A similar split vote, but the other way, may be good for equities and short-term rates, but at the expense of longer-duration bonds, which may fear higher-for-longer inflation. Any comment on the pace or maturity mix of gilt sales could move long-dated yields.
The OBR now sees inflation peaking at around 3.75% early next year and averaging 3.4% in 2027. It doesn't reach 2% until 2028. Growth slows to 1.0% in 2027. However, recent budget changes removing VAT from electricity bills and the standing charge from gas bills will directly lower measured CPI. This may give the MPC breathing room to see how things pan out, rather than rushing to another hike.
Companies Reporting
| Date | UK Trading Updates & AGMs | UK Financial Results | International Financial Results (S&P 500) |
|---|---|---|---|
Monday 2 November |
Aberforth Geared Value & Income Trust (LON:AGVI) (AGM) Made Tech (LON:MTEC) (AGM) International Workplace (LON:IWG) (TS) JPMorgan Emerging Markets Growth & Income (LON:JMGI) (AGM) Malibu Life Holdings (LON:MLHL) (AGM) TP Icap (LON:TCAP) (TS) |
AdvancedAdvT (LON:ADVT) (Interims) Kosmos Energy (LON:KOS) (Q3) |
Apple (NSQ:AAPL) (Q4) Marriott International (NSQ:MAR) (Q3) ON Semiconductor (NSQ:ON) (Q3) Palantir Technologies (NSQ:PLTR) (Q3) Ryanair Holdings (ISE:RYA) (Q2) (Ireland) Vertex Pharmaceuticals Incorporated (NSQ:VRTX) (Q3) The Williams Companies (NYQ:WMB) (Q3) |
Tuesday 3 November |
International Workplace (LON:IWG) (TS) JPMorgan Emerging Markets Growth & Income (LON:JMGI) (AGM) Malibu Life Holdings (LON:MLHL) (AGM) TP Icap (LON:TCAP) (TS) |
Associated British Foods (LON:ABF) (Finals) dotDigital (LON:DOTD) (Finals) Focusrite (LON:TUNE) (Interims) Gattaca (LON:GATC) (Finals) |
Archer-Daniels-Midland (NYQ:ADM) (Q3) Advanced Micro Devices (NSQ:AMD) (Q3) Amgen (NSQ:AMGN) (Q3) Arista Networks (NYQ:ANET) (Q3) Apollo Global Management (NYQ:APO) (Q3) Bayer AG (ETR:BAYN) (Q3) (Germany) Booking Holdings (NSQ:BKNG) (Q3) Marathon Petroleum (NYQ:MPC) (Q3) Pfizer (NYQ:PFE) (Q3) Ferrari (BIT:RACE) (Q3) (Italy) Super Micro Computer (NSQ:SMCI) (Q1) Block (NYQ:XYZ) (Q3) Yum! Brands (NYQ:YUM) (Q3) |
Wednesday 4 November |
Barratt Redrow (LON:BTRW) (AGM & TS) Coca-Cola HBC AG (LON:CCH) (TS) Gem Diamonds (LON:GEMD) (TS) Hansard Global (LON:HSD) (AGM) Lancashire Holdings (LON:LRE) (TS) Manchester And London Investment Trust (LON:MNL) (AGM) Mendell Helium (LON:MDH) (AGM) Next (LON:NXT) (TS) Prudential (LON:PRU) (TS) Smith & Nephew (LON:SN.). (TS) J D Wetherspoon (LON:JDW) (TS) |
Lion Finance (LON:BGEO) (Q3) Braemar (LON:BMS) (Interims) Burford Capital (LON:BUR) (Q3) Marks and Spencer (LON:MKS) (Interims) Smith & Nephew (LON:SN.)WS (Finals) Trainline (LON:TRN) (Interims) |
Albemarle (NYQ:ALB) (Q3) Atlantic Lithium (LON:ALL) (Q3) Bayerische Motoren Werke Aktiengesellschaft (ETR:BMW) (Q3) (Germany) CVS (LON:CVSG) (Q3) Datadog (NSQ:DDOG) (Q3) Empresaria (LON:EMR) (Q4) Experian (LON:EXPN) (Q3) Leonardo (BIT:LDO) (Q3) (Italy) Mcdonald's (NYQ:MCD) (Q3) Metir (LON:MET) (Q3) QUALCOMM Incorporated (NSQ:QCOM) (Q4) Smith & Nephew (LON:SN.)AP (Q3) Uber Technologies (NYQ:UBER) (Q3) |
Thursday 5 November |
Ashmore (LON:ASHM) (AGM) Croda International (LON:CRDA) (TS) Diageo (LON:DGE) (AGM) Diageo (LON:DGE) (TS) Galileo Resources (LON:GLR) (AGM) Harbour Energy (LON:HBR) (TS) Hikma Pharmaceuticals (LON:HIK) (TS) Howden Joinery (LON:HWDN) (TS) M&G (LON:MNG) (TS) Metlen Energy & Metals (LON:MTLN) (TS) Osb (LON:OSB) (TS) Physiomics (LON:PYC) (AGM) Tavistock Investments (LON:TAVI) (AGM) Venture Life (LON:VLG) (AGM) Vistry (LON:VTY) (TS) |
Asos (LON:ASC) (Finals) Autotrader (LON:AUTO) (Interims) BT (LON:BT.A).A (Interims) Helios Towers (LON:HTWS) (Q3) National Grid (LON:NG.). (Interims) RS (LON:RS1) (Interims) Sosandar (LON:SOS) (Interims) Tate & Lyle (LON:TATE) (Interims) Time Finance (LON:TIME) (Finals) VAALCO Energy (LON:EGY) (Q3) Wheaton Precious Metals (LON:WPM) (Q3) |
Airbnb (NSQ:ABNB) (Q3) Axon Enterprise (NSQ:AXON) (Q3) COMMERZBANK AG (ETR:CBK) (Q3) (Germany) Cigna group (NYQ:CI) (Q3) Cummins (NYQ:CMI) (Q3) ConocoPhillips (NYQ:COP) (Q3) DHL AG (ETR:DHL) (Q3) (Germany) Deutsche Telekom AG (ETR:DTE) (Q3) (Germany) EOG Resources (NYQ:EOG) (Q3) Live Nation Entertainment (NYQ:LYV) (Q3) AP Moeller - Maersk A/S (CPH:MAERSK B) (Q3) (Denmark) Rheinmetall AG (ETR:RHM) (Q3) (Germany) The Trade Desk (NMQ:TTD) (Q3) |
Friday 6 November |
MJ GLEESON (LON:GLE) (AGM) Schroder Japan Trust (LON:SJG) (AGM) |
International Consolidated Airlines (LON:IAG) (Q3) Record (LON:REC) (Interims) TBC Bank (LON:TBCG) (Q3) |
Brooks Macdonald (LON:BRK).B (Q3) Daimler Truck Holding AG (ETR:DTG) (Q3) (Germany) Humana (NYQ:HUM) (Q3) Moderna (NSQ:MRNA) (Q3) Vistra (NYQ:VST) (Q3) |
Apple (NSQ:AAPL)
Apple reports fiscal Q4 numbers after the US close on Monday. It is the first report under John Ternus, who took over from Tim Cook at the start of September.
Here are the key themes to watch:
- Memory & Margins: Apple has taken a capital-light approach to AI, partnering with Google to power Siri rather than building frontier models and data centres itself. As a result, its capex is around a fiftieth of the other US tech giants' combined spend. Investors increasingly see this as discipline, though it began as Apple playing catch-up. However, this doesn't mean it has been unaffected by the secondary effects. Cook called memory pricing a "100-year flood", said costs rose in the March and June quarters, and would climb again in September. The company's 47–48% gross margin guidance includes about one point of tariff refunds, so the adjusted midpoint is near 46.5%. A headline number below 47% due to further memory inflation would be viewed badly by the market.
- iPhone 18: Apple guided iPhone revenue growth in the mid-teens, despite FX headwinds and supply constraints, so demand seems strong. However, the quarter only captures the first nine days of iPhone 18 Pro and Pro Max sales. So commentary on current demand matters more than this quarter's reported number.
- Outlook: As always, the outlook can make or break the historical results. The upcoming quarter is a seasonal peak and the first full quarter for the iPhone Duo, Apple's first foldable. However, the company is suffering from supply constraints and cost inflation. Any comments on when supply may ease and on iPhone pricing in the face of memory inflation will be watched closely.
The variant strategy means the stock has not suffered from the recent AI sell-off:
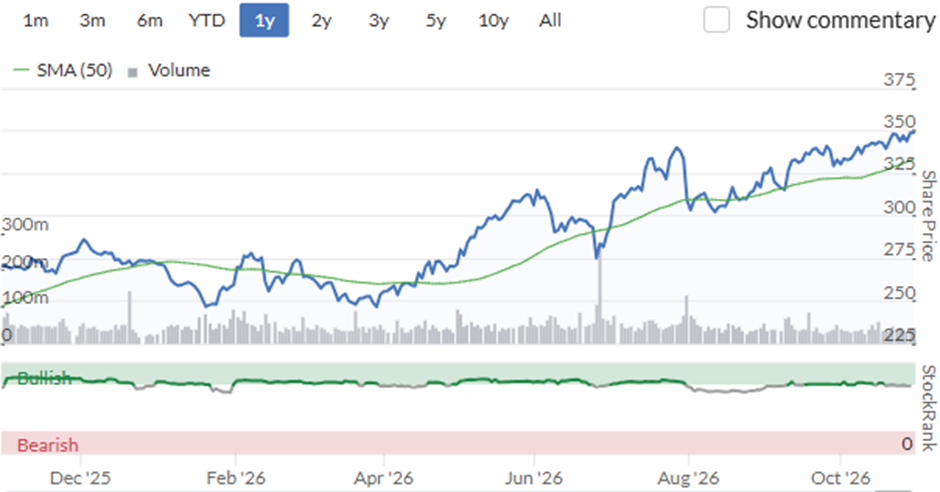
However, at close to 40x forward earnings, it is no longer the bargain that Buffett once saw.
Advanced Micro Devices (NSQ:AMD)
AMD reports their Q3 on Tuesday after US close. AMD is the clear number two in AI chips. However, Nvidia still holds more than 95% of the data centre GPU market, according to Futurum Group, with AMD at about 4.5%. AMD's pitch has three parts:
- Lower total cost of ownership and the lowest cost per token.
- More memory per chip, which matters for running large models.
- Open standards, such as UALink, compared with Nvidia's closed NVLink ecosystem.
The big question is whether it can turn a string of big customer commitments into real share from Nvidia next year. The key risks are around software (analysts consistently say AMD's hardware is roughly on par with Nvidia's, but Nvidia's CUDA ecosystem is far more mature than AMD's ROCm) and execution for Helios, AMD's first rack-scale product, at huge scale.
Things to watch:
- AMD said MI450 revenue would start in Q3 and reach significant volume in Q4, and that customer pull for Helios was running ahead of its initial forecast. Any hint of slippage would be a major setback.
- A multi-year deal with OpenAI covers 6 gigawatts of GPUs, starting with 1 gigawatt of MI450 servers in the second half of 2026. Investors will want to see this ship on time.
- Margins: Gross margin has been expanding despite the AI ramp, helped by high-margin server CPUs. However, early MI450 volumes may dilute this. Commentary around gross margins will be key to show revenue growth is benefiting the bottom line.
The rating may be high here, but this is backed up by strong growth expectations, given a PEG of less than 1:
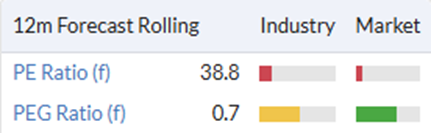
This means there may well be value here despite a Value Rank of just 3. The company need to deliver this growth, though, and the market will be sensitive to any sign of a slip-up.
Arm Holdings (NSQ:ARM)
UK-based but US-listed ARM reports after US close on Wednesday. Revenue is guided to rise 22%, with licensing revenue up around 30%. However, Royalties have been relatively weak, with the full-year royalty growth outlook cut from about 20% to the high teens. Q2 Royalty growth was in the low teens, with memory-price-driven handset weakness across all tiers blamed. Apple's quarterly report on Monday (see above) may give advance notice of where these trends are heading.
Here are some other key figures to watch:
- - Data Centre royalties: Although handset royalties showed weakness recently, cloud and data centre royalties are still more than doubling year on year. Investors will be looking for that point of inflexion, where hyperscaler chips built on Arm designs replace lost mobile growth.
- - Own chips: In the last set of quarterlies, Arm cited more than $2B of customer demand for its own AGI CPU across fiscal 2027 and 2028. Updates on supply, customers and margin impact will be closely watched as Arm moves from licensing directly into silicon.
The share price has been volatile. After falling about 34% in July on AI-chip valuation worries, it jumped 17% in early August on the Q1 beat. Indeed, Arm has beaten consensus EPS in each of the last four quarters, often by 25% or more. However, the valuation leaves little room for a soft royalty number or a cautious outlook:
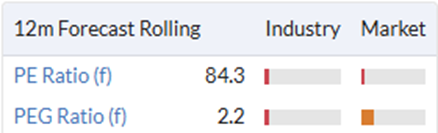
With a Value Rank of just 1, investors may see this as a great company but a poor investment at current levels.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
3 comments
Superb analysis and very helpful for me. Thank you.
Great summary as always. I was reading the note with interest about Google and how AI Mode is cannibalising traditional search advertising revenue. I have noticed that the majority of people would previously say, let's Google it , whereas now everyone is saying "AI says"... , I think its fair to say there is some brand equity dilution going on, everyone is now saying "Google" less and "AI" more, and of course there as several credible AI choices vs Gemini. Just a thought for a Friday.
Great round-up Mark, thank you. There's certainly plenty to watch next week particularly in the US, Netanyahu fought his election on attacking Iran again and one way or another, he always takes a willing Trump and reluctant America with him (I'm aware Netanyahu has to form a coalition, but neither him nor Trump let political niceties get in their way). The Middle East and much of the rest of the world do not want the Straits fully blocked again and Allies there attacked, but sadly it's beginning to look increasingly likely.