The Week Ahead (20 – 24 Oct): Gold, Inflation, TSLA, US Defence, SCT, GATC

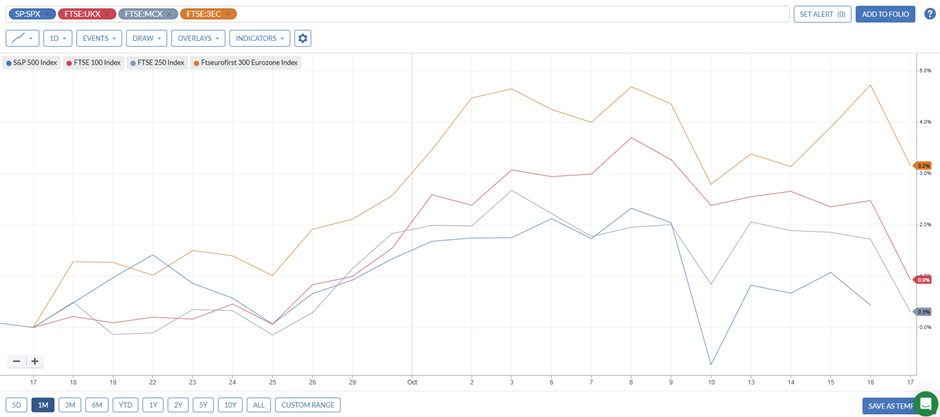
It has been a risk-off period for US and global indices lately, as concerns about U.S. regional bank problems and renewed U.S.–China trade tensions have weighed on sentiment. This has reversed generally positive trends for the rest of the month:
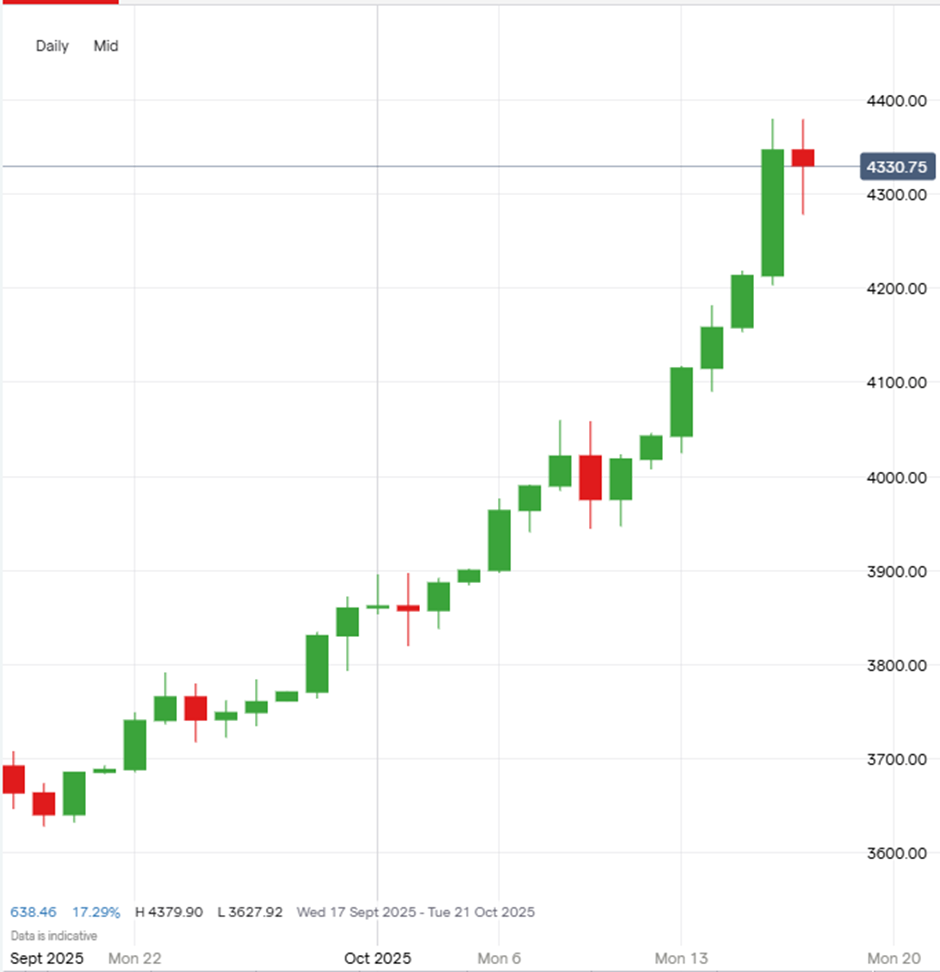
The biggest moves have been in the commodity sector, with oil down but gold making a huge weekly gain and surging to new highs above $4,300/oz as investors fled to safe havens amid banking and geopolitical worries.
Investors interested in learning more about investing in gold producers can read my two-part introduction to the sector here & here.
Here's what we can look forward to next week:
Economic Calendar
Monday 20 Oct |
||
03:00 |
China |
GDP Growth Industrial Production Retail Sales |
07:00 |
Germany |
Current Account |
09:00 |
Euro Area |
Producer Price Index |
Tuesday 21 Oct |
||
07:00 |
UK |
Public Sector Net Borrowing |
Wednesday 22 Oct |
||
00:50 |
Japan |
Balance of Trade |
07:00 |
UK |
Consumer Price Index (CPI) Retail Price Index (RPI) Producer Price Index (PPI) |
15:00 |
United States |
Crude Oil Inventories |
Thursday 23 Oct |
||
13:30 |
United States |
Initial Jobless Claims Continuing Claims |
15:00 |
United States |
Existing Home Sales |
15:00 |
Euro Area |
Consumer Confidence |
Friday 24 Oct |
||
00:30 |
Japan |
Inflation (CPI) |
07:00 |
UK |
Retail Sales GFK Consumer Confidence |
08:30 |
Germany |
Manufacturing PMI |
13:30 |
United States |
Consumer Price Index |
15:00 |
United States |
New Home Sales |
UK & US inflation
UK September CPI is due from the ONS on 22 October. Expectations are for the CPI to peak around 4.0% year-on-year, driven by higher food & services inflation and sticky wage growth. This is clearly above the BoE's 2% target, which is why the bank has been cautious about further cuts in interest rates.
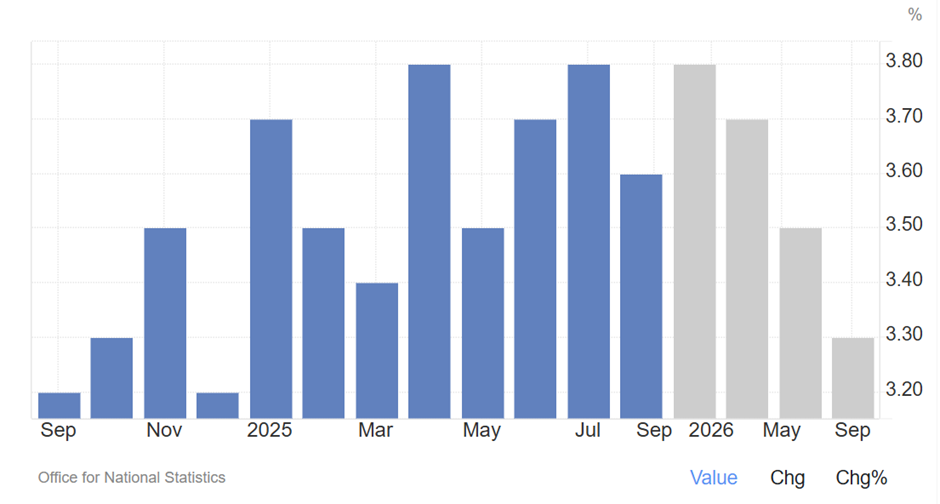
[All charts in the section: Trading Economics]
This is more likely to surprise to the upside than the downside in the near term due to services & food momentum. We shouldn't be counting on UK interest rate cuts soon, despite many companies reporting weak consumer and business confidence.
In the US, September CPI data has been delayed by the BLS from 15 to 24 October because of the government shutdown. Inflation is expected to start to trend down in the US:
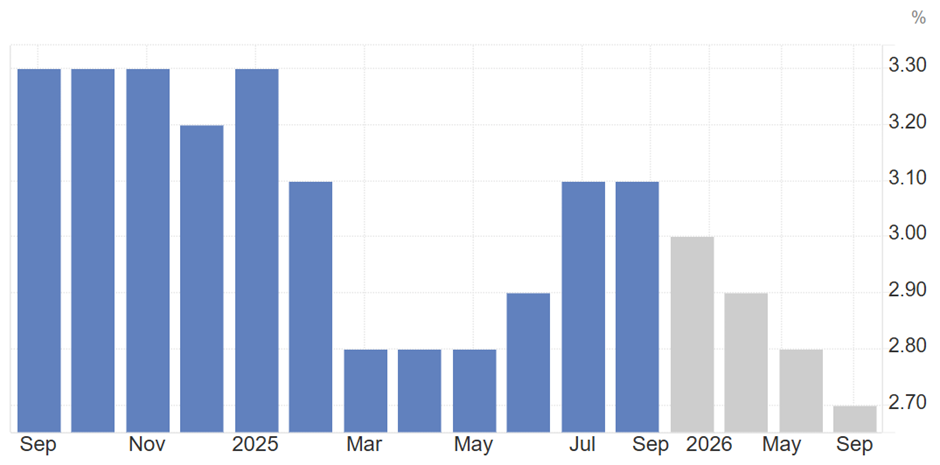
Hence, futures and market signals continue to price some Fed easing in 2025. But the uncertainty from the shutdown raises the risk of an out-of-consensus print, and a surprise could have an outsized impact on any Fed cuts.
US housing & jobs
The other major economic news this week is around US housing and jobs. US initial jobless claims are expected to rise going forward, having been rangebound this year:
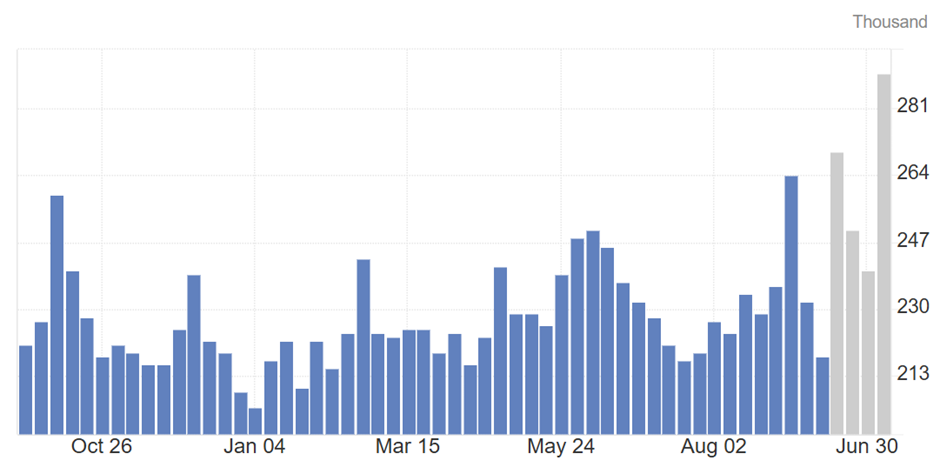
The risk of higher claims also looks high here due to soft private indicators, and the threat from the Trump administration to use the current government shutdown to increase public sector layoffs.
In housing, both existing and new home sales will be reported next week. Forecasts are for modest rises in volume, but prices may be more important than the sales numbers:
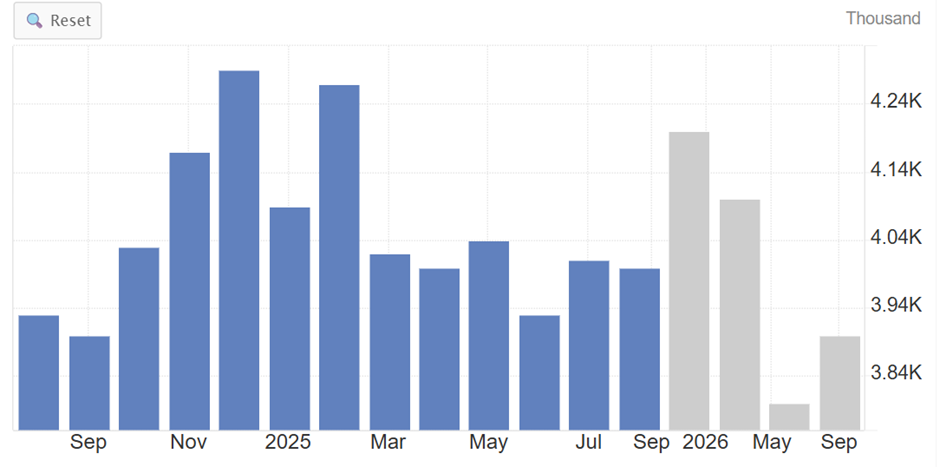
Again, the risk looks to be to the downside, as weaker employment prospects and long-term interest rates weigh on buyers' minds.
Companies Reporting
UK Trading Updates |
UK Financial Results |
International Financial Results |
|
Monday 20 Oct |
Redcentric (AGM) |
Seraphim (Finals) |
Sandvik (Sweden) |
Tuesday 21 Oct |
Segro (TS) XP Power (TS) |
Bellway (Finals) BP Marsh (interims) |
3M (Q3) Assa Abloy (Sweden) Capital One (Q3) Chubb (Q3) Coca-Cola (Q3) Danaher (Q3) Elevance Health (Q3) Equifax (Q3) Halliburton (Q3) General Electric (Q3) General Motors (Q3) Intuitive Surgical (Q3) Lockheed Martin (Q3) NASDAQ (Q3) Netflix (Q3) Northrup Grumman (Q3) Philip Morris (Q3) Raytheon Technologies (Q3) Texas Instruments (Q3) |
Wednesday 22 Oct |
Anglo Asian Mining (AGM) |
Barclays Pensionbee (Q3) Softcat (Finals) |
Akzo Nobel (Netherlands) (Q3) AT&T (Q3) BASF (Germany) (Q3) Boston Scientific (Q3) IBM (Q3) Hilton Worldwide (Q3) Moody's (Q3) SAP (Q3) Svenska Handelsbanken (Sweden) (Q3) Teledyne Technologies (Q3) Tesla (Q3) Thermo Fisher Scientific (Q3) United Rentals (Q3) Westinghouse Air Brakes (Q3) |
Thursday 23 Oct |
Aberdeen (TS) ACG Metals (AGM) AJ Bell (TS) BHP (AGM) Hunting (TS) Inchape (TS) InterContinental Hotels (TS) Lloyds (IMS) Newmark Security (AGM) Relx (TS) Rentokil Initial (TS) South32 (AGM) Spirent (TS) Thruvision (AGM) Tufton Assets (AGM) Unilever (TS) |
Gattaca (Finals) NCC (Q3) Sareum (Finals) Wynnstay Properties (Interims) |
Baker Hughes (Q3) Blackstone (Q3) Dassault (France) (Q3) Ford (Q3) Linde (Germany) (Q3) Hasbro (Q3) Honeywell International (Q3) Intel (Q3) Mastercard (Q3) McDonald's (Q3) Newmont Corporation (Q3) Nokia (Q3) T-Mobile US (Q3) Union Pacific (Q3) Southwest Airlines (Q3) Western Digital (Q3) Verisign (Q3) |
Friday 124 Oct |
Alumasc (AGM) Knights Group (KGH) |
Natwest |
AbbVie (Q3) Chevron (Q3) Eni (Italy) (Q3) Exxon Mobil (Q3) General Dynamics (Q3) P&G (Q3) Porsche (Germany) (Q3) Sanofi (France) (Q3) |
As you may expect, given the timing, we are well into the international Q3 reporting season. In the UK, few companies report quarterly, so it is relatively quiet. However, the US will have a huge number of companies reporting, and I've had to limit the list above to the most well-known companies.
Tesla (NSQ:TSLA)
Tesla is often a bellwether for investor confidence in the tech sector. They announced record deliveries of 497k vehicles in Q3, so many may be expecting upside on the $25-26bn revenue and $0.48–$0.54 range for EPS. This is likely behind the recent share price rise to $450:
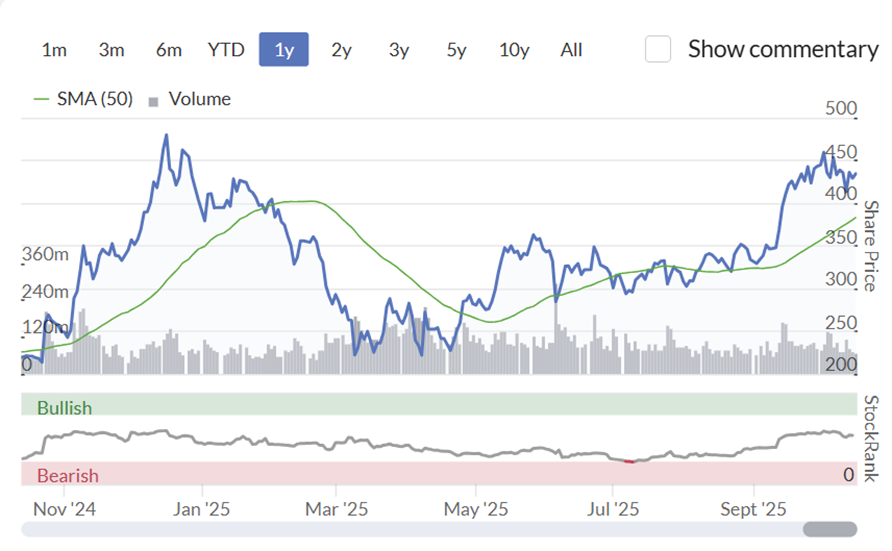
However, volume isn't everything, and many will be watching the automotive gross margin as this will show whether Tesla's price cuts and mix changes are structurally damaging profitability or whether cost and capex improvements have offset average selling price pressure. Another thing to watch for is any inventory movements to non-arm's-length buyers. For example, recent press coverage revealed deliveries of unsold Cybertrucks to Musk's private companies. This may hide real demand weakness.
Of course, none of this is really going to impact the fundamentals, which reveal that the investment case remains largely an act of faith in Musk to deliver on all of his (much delayed) promises, such as robotaxis and self-driving:
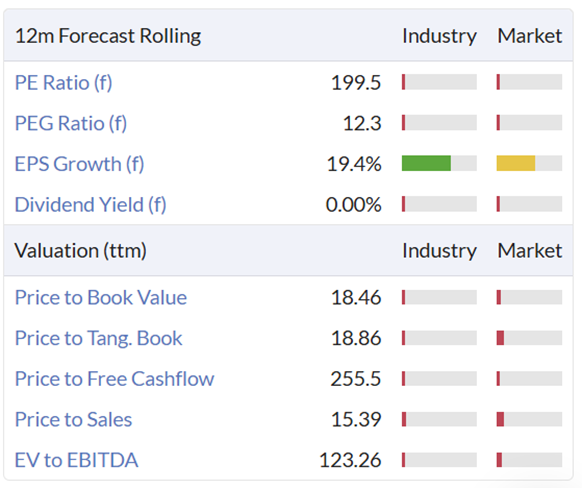
Unsurprisingly, the StockRanks show a High Flyer:
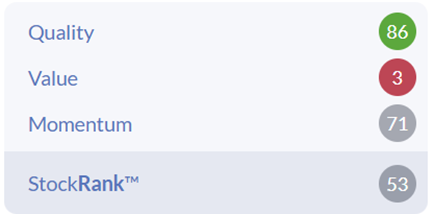
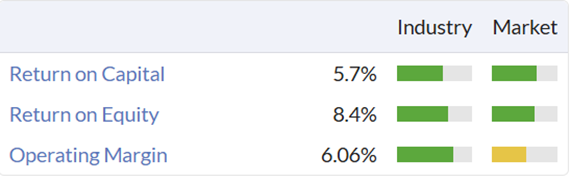
Although I have to doubt how high a quality it is when margins and ROCE are in single figures:
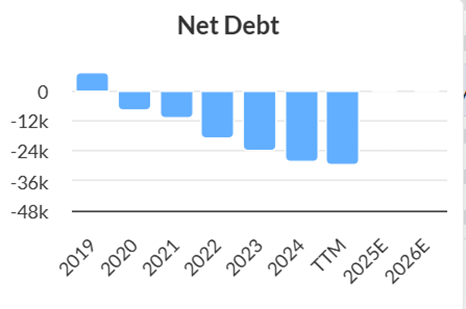
It probably isn't a good short, though, either. A growing cash pile means it is unlikely to face financial pressures in the short term:
And Musk's ability to sell the story and raise capital when needed seems undiminished.
US Defence Stocks
Several of the major US defence stocks will report next week:
Company |
Products |
Lockheed Martin (NYQ:LMT) |
Major US defence contractor; fighter jets, missiles, space systems. |
Northrop Grumman (NYQ:NOC) |
US defence and aerospace, UAVs, stealth aircraft, space systems. |
Rtx (NYQ:RTX) |
Missiles, defence electronics, military aerospace. |
General Dynamics (NYQ:GD) |
Tanks, submarines, nuclear systems, aerospace. |
Here is how these line up in the Stockopedia head-to-head:
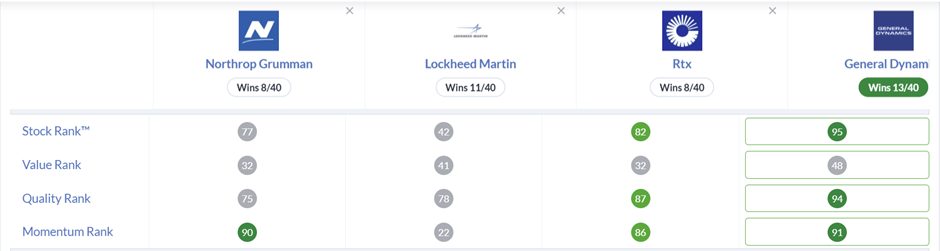
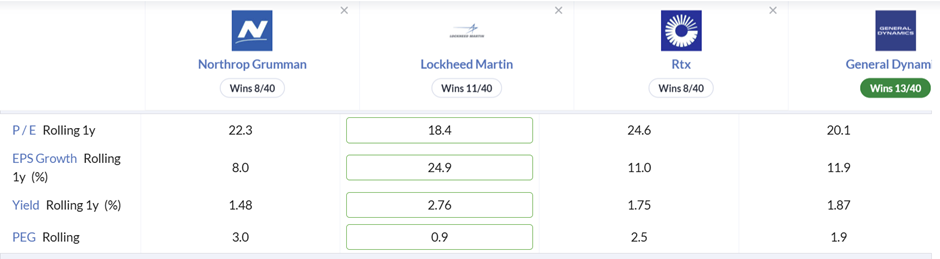
General Dynamics wins with the highest StockRank, but I don't think we can write off even Lockheed Martin, which has the lowest StockRank. This is the cheapest on forward earnings, despite having the fastest growth. Indeed, it is the only stock with a PEG lower than 1:
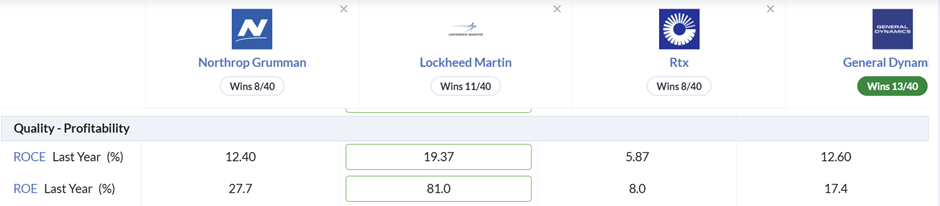
It also has the highest historical returns on capital, something that will only improve in the short term if earnings grow:
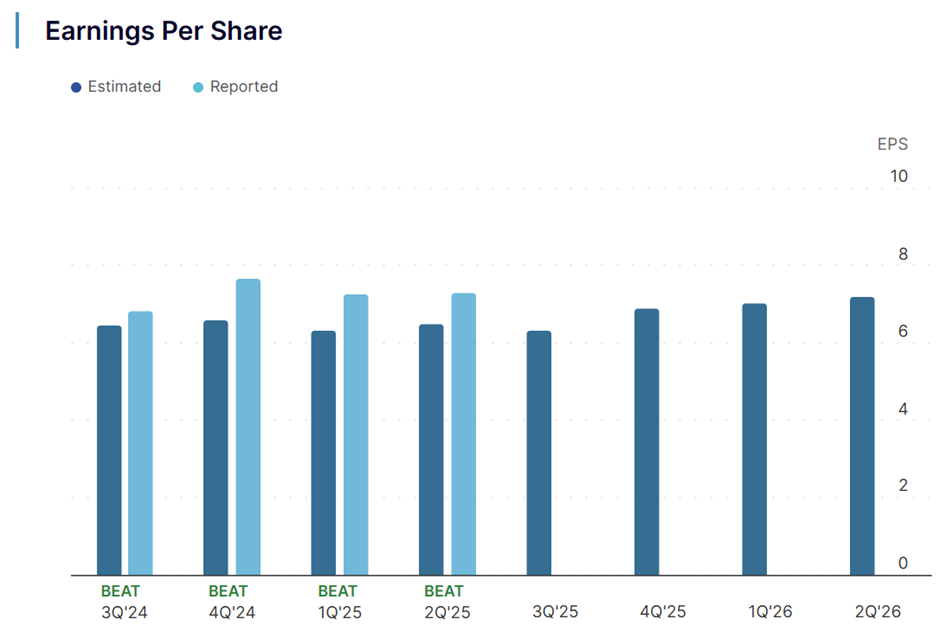
Lockheed Martin also seems to have one of the best recent records of beating expectations:
[Chart: NASDAQ]
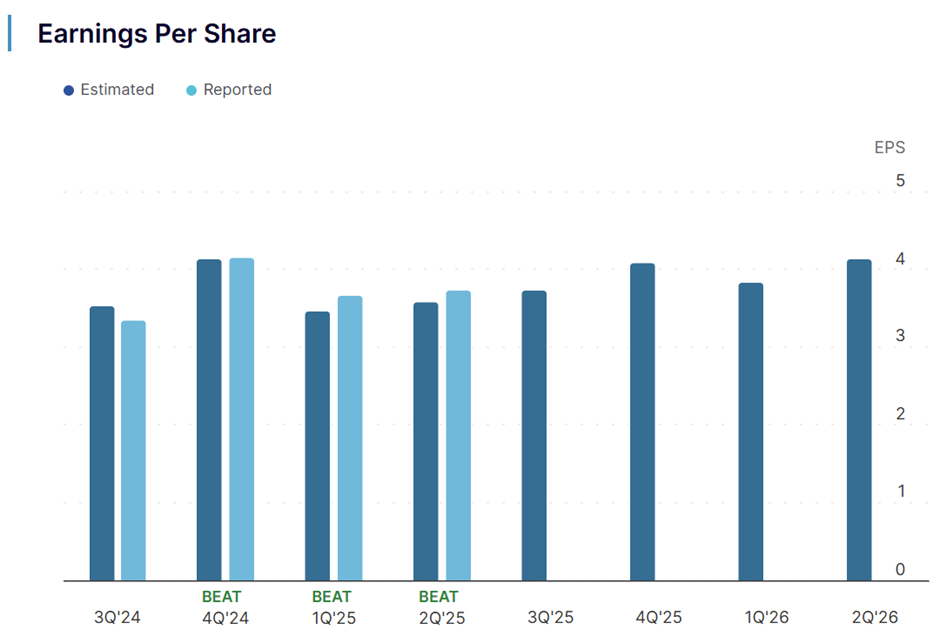
And while General Dynamics might have a much higher Momentum Rank, this is backed up by the same record of beating expectations:
[Chart: NASDAQ]
As well as how these companies perform against expectations, there will be key project-related news. At Lockheed Martin, investors will examine the cost and volume dynamics of the F-35 and Sikorsky programs, as well as the conversion of earnings to free cash flow. At Northrop Grumman, investors will be looking at the B-21 production cost trajectory, as any cost overruns here would be material to the economics. RTX has commercial aviation (Collins, Pratt & Whitney) as well as missile defence (Raytheon), so the balance between the two segments will matter. Likewise, General Dynamics produces Gulfstream jets, so deliveries here may matter as much as the profitability of their combat systems.
Overall, this appears to be a sector with high StockRanks, and in an increasingly perilous world, may have much further to go.
UK Stocks
Softcat (LON:SCT)
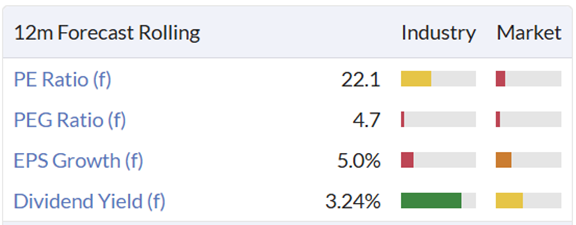
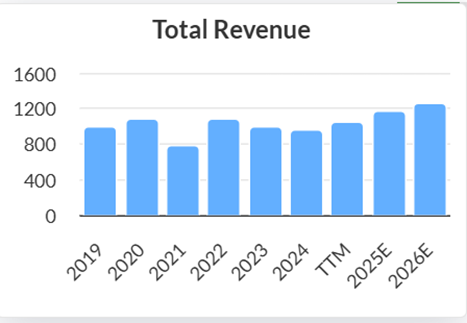
Softcat is a provider of IT infrastructure, IT solutions and software licenses. They will release their full-year results for the period to July 31st on October 22nd. At the half-year, revenue was up around 17% to £545.6m; however, lower gross margins, combined with higher cost growth, meant that operating profit rose just 10% to £73.7m. In their Q3 trading statement, they said that the business delivered "strong double-digit year-on-year growth in gross profit and operating profit," and management lifted their guidance for FY25 adjusted operating profit from "low double-digit" to "low-teens growth".
This sounds reasonable, but they are on a forward P/E of 22, meaning that the PEG ratio is significantly above 1:
Their revenue growth is a bit lacklustre:
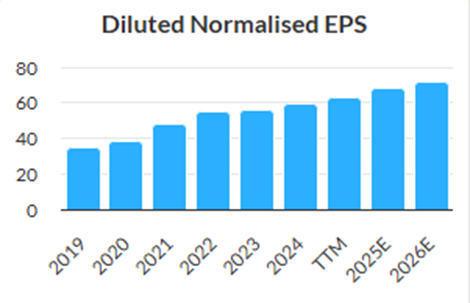
But they have managed to turn that into 11.5% CAGR EPS growth:
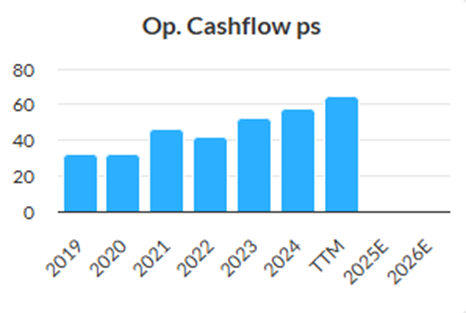
Cash conversion is high, meaning that the underlying performance may be a little better than this:
However, despite the upgrade being reflected in brokers' forecasts:
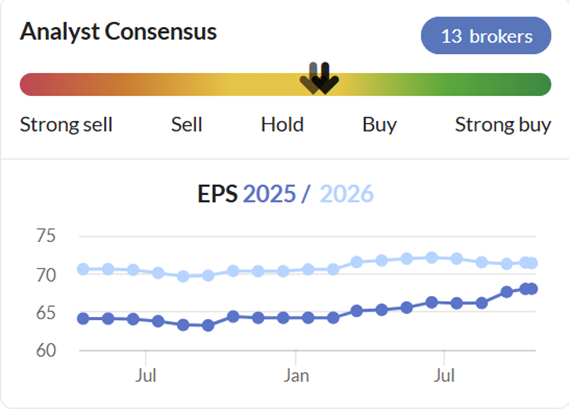
…there is caution from analysts. For example, JPMorgan flagged that recent earnings growth has been aided by large, one-off deals concentrated in a few customers, which may not fully repeat, thus making FY26 comparisons more challenging. They placed Softcat on a "negative catalyst watch."
As with many similar businesses, they have strong returns on capital:
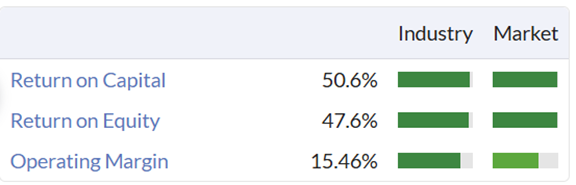
So if they can grow more strongly in the future, this probably won't require much additional capital. There is also a reasonable cash balance, but not so much that it changes the valuation case significantly:
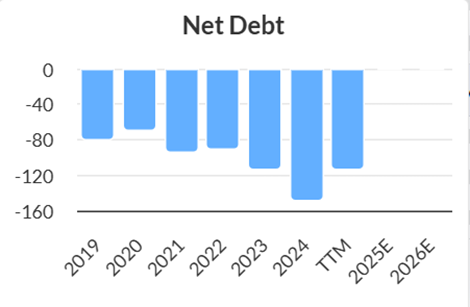
At the end of the day, the valuation is full but not totally bonkers. It prices in continued outperformance, so investors will be keen to see signs of this realised in the upcoming results to prove brokers wrong and keep holding.
Gattaca (LON:GATC)
Personally, my focus next week will be on holding Gattaca. This has done well recently, with smaller specialist recruiters such as this significantly outperforming larger peers in recent times. Indeed, in their recent trading statement, they said:
Improved margin conversion, due to a focus on costs and improved productivity, will result in FY25 Group underlying Profit before Tax in the range of £3.1m to £3.3m (FY24: £2.9m), marginally above current guidance of £3m.
This resulted in a slight increase in FY25 numbers. However, this also saw a reduction in FY26 estimates. To be fair, almost 100% growth in EPS in 2026 always looked out of place in current recruitment markets.
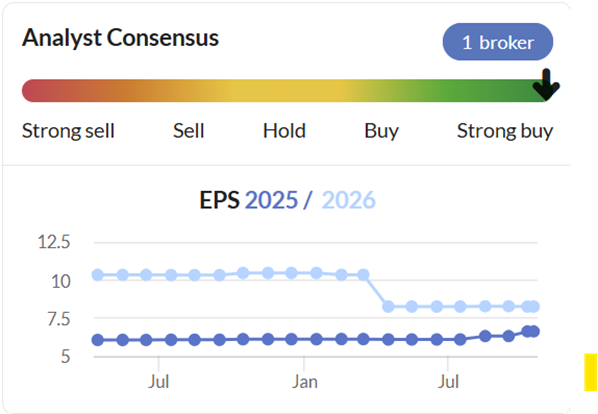
The current forecast of 25% EPS growth looks both more reasonable and achievable. Something they confirmed in their most recent trading statement:
Whilst market conditions continue to be challenging, Gattaca remains focused on its core markets, continuing to improve consultant net fee productivity and the Group's back-office efficiency. As a result of continued demand and enhanced operational efficiencies, the Board expects the Company to perform in line with current market expectation of £4m underlying Profit before Tax for FY26.
For me, the standout metric is this:
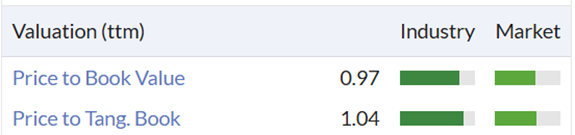
Very few recruiters are trading well and are on a discount to TBV, which means the StockRanks marks this out as a SuperStock:
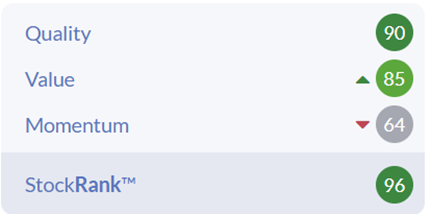
The momentum rank is the weakest as the stock has not been immune to sector-wide worries that have hit the share price recently:
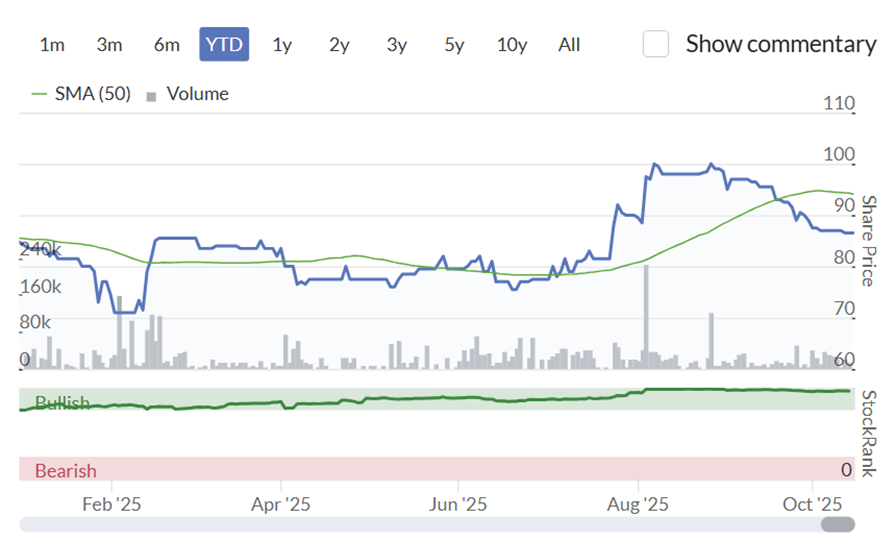
However, Gattaca has bucked that trend for a while now, and confirmation of further in-line trading will likely be greeted positively. There is also the likelihood of brokers introducing FY27 forecasts, and if these show further growth, this may focus investors' minds on the low valuation.
[Disclosure: Mark owns shares in Gattaca (LON:GATC) ]
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

9 comments
Tesla (NSQ:TSLA) Tesla Q3 2025 Earnings Review (generated by Grok)
Tesla reported its Q3 2025 earnings after market close on October 22, 2025, delivering a mixed bag: record revenue and deliveries beat expectations, but earnings per share (EPS) and profits missed due to higher costs, tariffs, and lower regulatory credits. The company emphasized its pivot to AI, autonomy, and energy, with CEO Elon Musk highlighting progress on robotaxis and Optimus during the call. Below is a detailed breakdown, followed by current market views as of October 23, 2025.
Key Financial Metrics (Q3 2025 vs. Q3 2024 and Estimates)
Tesla achieved record revenue of $28.1 billion, up 12% year-over-year (YoY), beating consensus estimates of $26.4–26.6 billion. However, net income and margins declined amid pricing pressures, higher R&D/tariff costs, and a 43% drop in regulatory credits to $417 million. Free cash flow hit a record $4.0 billion, bolstering a $41.6 billion cash position.
Highlights and Forward Guidance
- **Operational Wins**: Record deliveries across regions, despite Q3 production dip; energy segment shone with Megapack 3 and Megablock unveilings for faster deployments. Launched affordable Model 3/Y variants (starting $36,990–$39,990) and a 3-row Model Y Long Range in China to boost accessibility post-U.S. EV tax credit expiration. Supercharger network grew 18% YoY to 73,817 connectors.
- **AI and Autonomy**: Expanded AI compute to 81,000 H100-equivalent GPUs; FSD v14 rollout with improvements; Robotaxi ride-hailing launched in Bay Area, driverless in Austin by year-end, expanding to 8–10 cities by 2025. Over 4 billion FSD miles driven; Samsung partnership for U.S. AI chip production.
- **Robotics and Future Products**: Optimus V3 unveil in Q1 2026; Cybercab, Tesla Semi, and Megapack 3 on track for 2026 volume production.
- **Guidance**: No specific Q4 numbers; volume tied to macro/trade policies and autonomy ramps. Focus on cost reductions, AI/software profits, and product evolution. Strong balance sheet to fund growth amid uncertainty. Musk noted potential Q4 dip from tax credit expiry but emphasized accelerating production for autonomy.
Current Market Views (as of October 23, 2025)
Market reaction has been negative in the short term, with shares down 3–4% in after-hours and pre-market trading on October 23, dipping to ~$412–424 from a $426 close (a ~3.3% decline). This reflects the EPS miss and muted guidance, though the revenue beat and record metrics provided some cushion. Broader sentiment is divided: bulls focus on long-term AI/energy potential, while bears highlight near-term profit pressures and valuation risks (forward P/E remains ~150x).
Analyst Reactions**: Split, with some upgrades on AI outlook and others downgrading on misses.
- **Bullish**: Dan Ives (Wedbush) calls it the "most undervalued AI name," says "worst in rearview," maintains $500 target. Tom Nash predicts $900 in 12 months. Piper Sandler: "Top idea" for autonomy.
- **Bearish/Neutral**: UBS holds $215 "Sell"; some analysts cut to "Sell" citing 60% downside on valuation disconnect and tariff hits. Consensus price target ~$327 (26% downside from $426), but shifting bullish on AI.
- **Overall Consensus**: Revenue beat praised, but EPS miss and vague Q4 outlook (potential dip from tax credits) disappoint. Focus shifts to November 6 shareholder meeting for Musk's $1T pay package vote.
- **X (Twitter) Sentiment**: Generally optimistic long-term despite the dip, with posts emphasizing records in deliveries/energy and AI catalysts (e.g., Robotaxi expansion, Optimus V3). Some frustration over margins and guidance, but bulls see it as a "conviction hold" with "inflection point" ahead. Short-term: "Shares slip on tax-credit uncertainty"; long-term: "AI pivot intact."
In summary, Q3 showed operational strength but profit challenges, leading to a stock dip. Market views are polarized: near-term caution on margins/guidance, but enthusiasm for AI/energy future. The November 6 meeting could be a catalyst. This is not financial advice; consult professionals.
Bioventix (LON:BVXP) reports on Monday. Very high quality small cap with a commendable long term record, albeit recent share price weakness
Bioventix (LON:BVXP)
Monday is the 20th. According to https://www.bioventix.com/inve... they report on Monday 27th.
Ahh true, thank you
Mark - add Bloomsbury Publishing (LON:BMY) Interims on Thurs. 23rd.
On the same day you have NCC Q3. Where did you get that from? They have never done a Q3 and we have been waiting a month for the preclo for 12 months to end Sept. However it is complex because they have extended the reporting period and we are now in a 16 month year. At the same time they may sell off one or both parts of the company and so are in an official offer period!
No reply from Mark but I have found where he got NCC Q3 on 23rd. from - it is not NCC (LON:NCC) but Swedish builder Ncc AB (STO:NCC B) so is in the wrong column.
I am still puzzled by the UK NCC - the 16 month year I mentioned last time did in fact end on 31/9 last year with prelims on 11/12/24. Now we have the SR showing on 10/10/25 archive:
Monday, October 13th 2025 Full Year 2025 NCC Group PLC Earnings Release
On or before the 17th that was changed to Tuesday, October 21st 2025
Google AI tells me "There are no NCC results scheduled for Tuesday, October 21st, 2025"
We will find out tomorrow.
Thanks for listing which UK shares are trading statements (assuming this is what TS means) and which are AGMs. Not convinced 100% of AGMs are relevant but trading updates certainly are, so this is a huge improvement. Maybe you should do this every week as your week ahead updates are more thorough.
Thank you Mark, it's all useful and Gattaca looks very interesting.
Hi Mark,
Thank you for this work. I am happy to start to see coverage of US shares on Stockopedia. It is the biggest market with loads of opportunities.