The Week Ahead (21 – 25 Sep): Xi/Trump Summit, PMIs, Costco, Luceco, JD Sports, Warpaint

Last week's economic news centred on central bank moves. In the US, the FOMC increased interest rates for the first time since 2023, much to the ire of President Trump, who clearly has one eye on the big losses coming for Republicans in the November midterms. On the plus side, Warsh was Trump's pick for the role, and his willingness to go against the president's wishes reinforces central bank independence, which reassures markets.
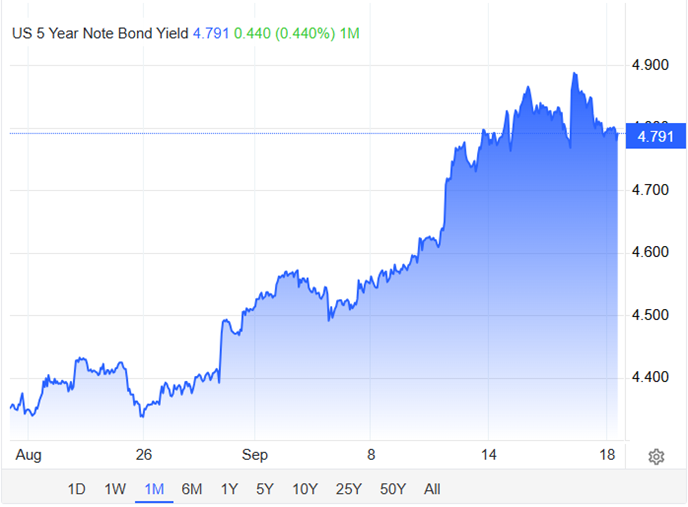
The US 5yr ends the week marginally higher than where it started, although some 50bps higher on the 1-month view:
[All charts in this section: Trading Economics]
The BoJ followed suit, raising its policy rate by 25bps to 1.25%, the highest in 31 years, following persistent inflationary pressures and a weak yen.
In the UK, interest rates were held. However, the commentary was undoubtedly hawkish, with BoE Chairman Andrew Bailey saying that future rate rises were likely if global energy price volatility persists and continues to push up inflation.
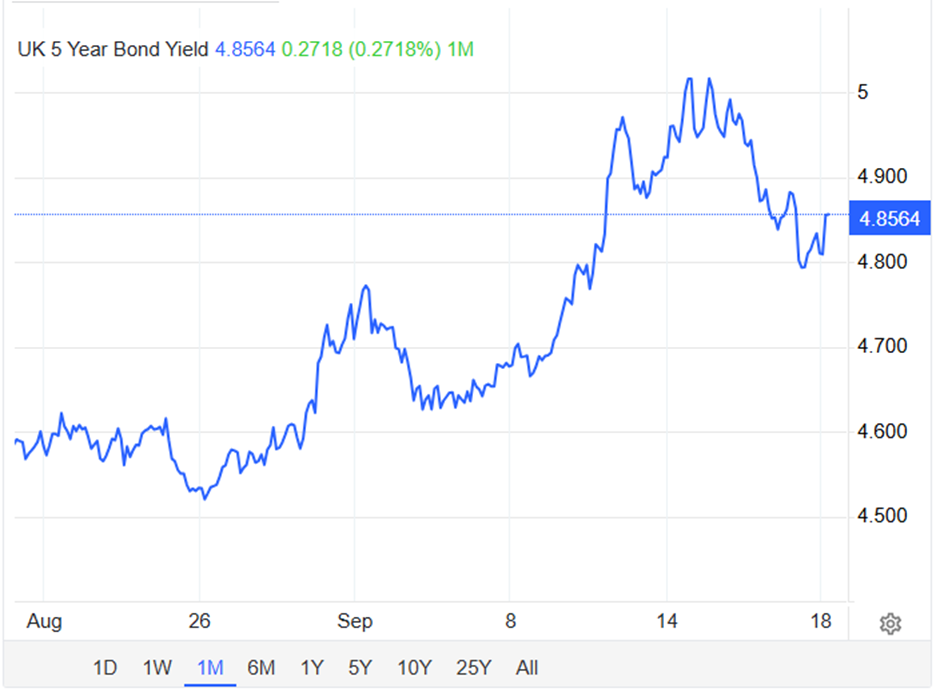
However, in a move with a far greater short-term impact, the BoE also announced it would stop selling government bonds held on its books. Stopping quantitative tightening had a positive impact on 5-year notes, which had risen above 5% mid-week:
Here's what we can look forward to next week:
Economic Calendar
Monday 21 September |
||
02:15 |
China |
Loan Prime Rates |
Tuesday 22 September |
||
11:00 |
UK |
CBI Industrial orders |
15:00 |
Euro Area |
Consumer Confidence |
21:30 |
United States |
API Crude Stocks |
Wednesday 23 September |
||
09:00 |
Euro Area |
Purchasing Managers' Index (PMI) |
09:30 |
UK |
Purchasing Managers' Index (PMI) |
12:00 |
United States |
Mortage Rates |
14:45 |
United States |
Purchasing Managers' Index (PMI) |
15:30 |
United States |
EIA Crude Oil Inventories |
Thursday 24 September |
||
01:00 |
United States/China |
Trump/Xi Summit |
01:30 |
Japan |
Purchasing Managers' Index (PMI) |
13:30 |
United States |
Initial Jobless Claims Continuing Claims |
15:00 |
United States |
New Home Sales |
Friday 25 September |
||
07:00 |
UK |
Consumer Confidence |
07:00 |
Germany |
Consumer Confidence |
13:30 |
United States |
Durable Goods Order |
Trump/Xi Summit
Xi arrives in Washington on September 24 for his first White House visit in a decade, but it's their second meeting this year, following their May summit in Beijing. Beyond the usual global tensions over Taiwan and Iran, an awkward backdrop looms. China appears to be delivering a $1 trillion trade surplus for a second straight year, while Trump is dealing with the Iran war and low approval ratings.
The big economic question is whether the tariff truce will hold. Markets will be watching for signs that the agreement reached in South Korea last October will be extended. That original deal cut US tariffs on Chinese goods and paused Chinese rare-earth export curbs. Ahead of next week, US Trade Representative Jamieson Greer said the two sides will make "some announcements on agriculture and non-tariff barriers," with traders watching for progress on an agreed $30 billion mutual tariff reduction, something China could most easily deliver by cutting duties on US farm imports. Washington is also still pressing China over incomplete compliance with last year's agreement, while Beijing is pushing for further tariff relief.
Trump will also want trade wins locked in before November's midterms, including big-ticket Boeing aircraft purchases and agricultural buys. China seems to be bringing a large business delegation, which bodes well for detailed discussion of an aircraft deal that has stalled for years over Trump's threats to cut off spare engine parts.
Rare earth elements and chip export controls are at the core of the standoff. Beijing wants Washington to further delay a rule that would bar thousands of Chinese firms from advanced US technology. In return, the US wants China to ease shipments of rare earths and critical minerals used in autos, aerospace and defence manufacturing.
Purchasing Managers' Index
With little in the way of other substantive economic news this week, the Purchasing Managers' Index (PMI) will receive increased focus. The UK, US and Euro area all report their numbers on Wednesday, and Japan on Thursday. This monthly survey-based indicator measures the prevailing direction of economic activity in the manufacturing and services sectors. It's compiled by asking purchasing managers at a few hundred companies a simple set of questions: Is business better, worse, or the same as last month across things like new orders, output, employment, supplier delivery times, and inventories?
Each of these subcomponents gets compiled into a single PMI number, where anything above 50 indicates expansion and anything below indicates contraction. It is worth bearing in mind that this is a relative index; it tells you whether things are improving, but says nothing about the absolute level of economic activity. However, investors like the PMI because it is fast, forward-looking and globally consistent.
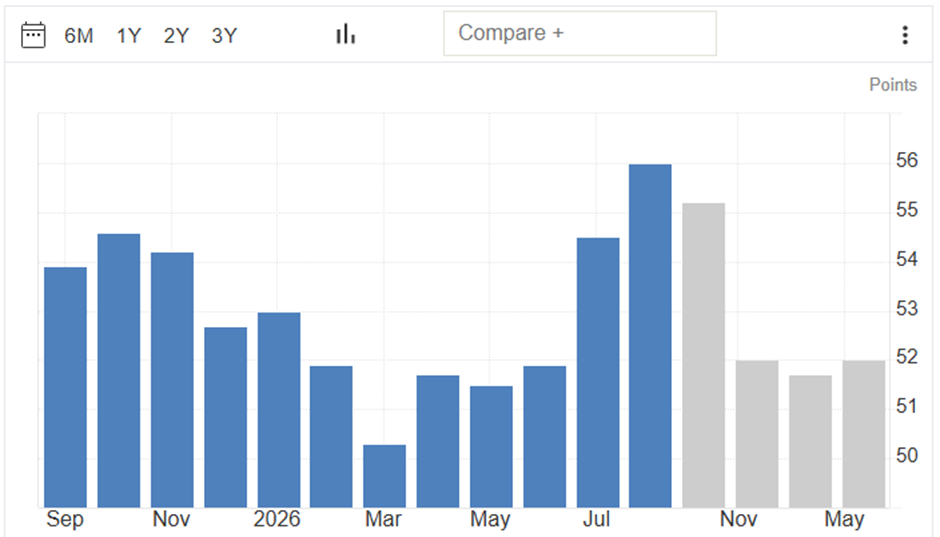
In the US, the PMI has been consistently showing expansion, although the rate of that improvement is expected to moderate going forward:
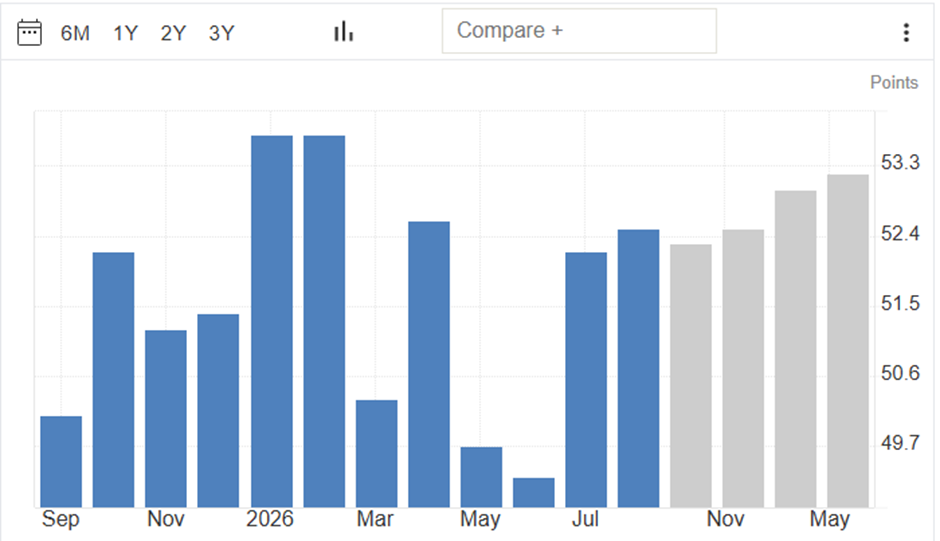
In the UK, the data has been noisy, but with little sign of expansion or contraction:
While the Euro Area has been fairly gloomy of late:
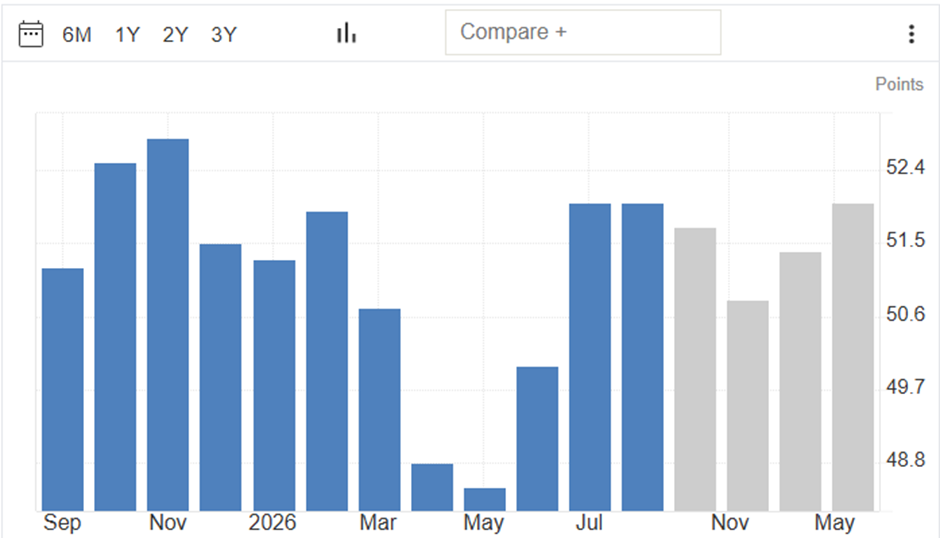
In the current environment, market moves can often run opposite to what you might expect from an economic growth indicator. A "hot" PMI print increases the market's view on the likelihood of a further near-term rise in interest rates, which is often viewed negatively for equity returns.
Companies Reporting
| Date | UK Trading Updates & AGMs | UK Financial Results | International Financial Results |
|---|---|---|---|
Monday 21 September |
B90 Holdings (LON:B90) (Interims) Craneware (LON:CRW) (Finals) |
||
Tuesday 22 September |
Altitude (LON:ALT) (AGM) Baker Steel Resources Trust (LON:BSRT) (AGM) Chariot (LON:CHAR) (AGM) Defence Holdings (LON:ALRT) (AGM) Ilika (LON:IKA) (AGM) Kainos (LON:KNOS) (AGM) Mila Resources (LON:MILA) (AGM) Optima Health (LON:OPT) (AGM) PHSC (LON:PHSC) (AGM) Porvair (LON:PRV) (TS) SThree (LON:STEM) (TS) |
Diaceutics (LON:DXRX) (Interims) Fonix (LON:FNX) (Finals) Henry Boot (LON:BOOT) (Interims) Kingfisher (LON:KGF) (Interims) Luceco (LON:LUCE) (Interims) Microlise (LON:SAAS) (Interims) Midwich (LON:MIDW) (Interims) Mortgage Advice Bureau (Holdings) (LON:MAB1) (Interims) Oxford BioMedica (LON:OXB) (Interims) PCI- PAL (LON:PCIP) (Finals) Puretech Health (LON:PRTC) (Interims) Smiths (LON:SMIN) (Finals) Mission (LON:TMG) (Interims) Transense Technologies (LON:TRT) (Finals) Yu (LON:YU.). (Interims) |
AutoZone (NYQ:AZO) (Q4) KB Home (NYQ:KBH) (Q3) |
Wednesday 23 September |
Autins (LON:AUTG) (AGM) Baltic Classifieds (LON:BCG) (AGM) Cambridge Nutritional Sciences (LON:CNSL) (AGM) SDI (LON:SDI) (AGM) Tpximpact Holdings (LON:TPX) (AGM) |
Ceres Power Holdings (LON:CWR) (Interims) Chapel Down (LON:CDGP) (Interims) Digitalbox (LON:DBOX) (Interims) Ingenta (LON:ING) ) (Interims) JD Sports Fashion (LON:JD.). (Interims) Judges Scientific (LON:JDG) (Interims) Kooth (LON:KOO) (Interims) Portmeirion (LON:PMP) (Interims) Renishaw (LON:RSW) (Finals) Time Finance (LON:TIME) (Finals) Warpaint London (LON:W7L) (Interims) |
Cintas (NSQ:CTAS) (Q1) General Mills (NYQ:GIS) (Q1) Paychex (NSQ:PAYX) (Q1) TUI AG (ETR:TUI1) (Germany) |
Thursday 24 September |
AO World (LON:AO.). (AGM) Cohort (LON:CHRT) (AGM) IG Design (LON:IGR) (AGM) FIH (LON:FIH) (AGM) First Property (LON:FPO) (AGM) Frp Advisory (LON:FRP) (AGM) Halma (LON:HLMA) (TS) Kropz (LON:KRPZ) (AGM) Mercia Asset Management (LON:MERC) (AGM) Mothercare (LON:MTC) (AGM) NWF (LON:NWF) (AGM) Polar Capital Holdings (LON:POLR) (AGM) |
Biopharma Credit (LON:BPCR) (Interims) Capricorn Energy (LON:CNE) (Interims) CVS (LON:CVSG) (Finals) DFS Furniture (LON:DFS) (Finals) iFOREX Financial Trading Holdings (LON:IFRX) (Interims) InvestAcc (LON:INAC) (Interims) On Beach group (LON:OTB) (Finals) Raspberry PI Holdings (LON:RPI) (Interims) tinyBuild (LON:TBLD) (Interims) Vistry (LON:VTY) (Interims) |
Costco Wholesale (NSQ:COST) (Q4) H and M Hennes and Mauritz AB (STO:HM B) (Sweden) |
Friday 25 September |
Accsys Technologies (LON:AXS) (AGM) iomart (LON:IOM) (AGM) Ondo InsurTech (LON:ONDO) (AGM) System1 (LON:SYS1) (AGM) |
Bango (LON:BGO) (Interims) |
Costco Wholesale (NSQ:COST)
Costco reports fiscal Q4 and full-year 2026 results on Thursday after market close. The share price has been weak over the last year, lagging the wider US indices by around 20%.
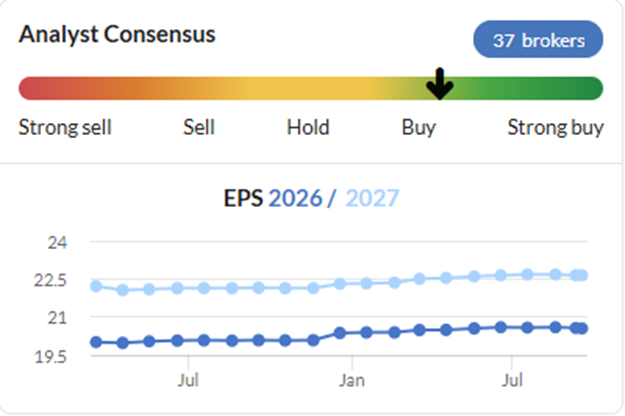
While investors like the recurring revenue model of the membership scheme, the earnings consensus has been largely flat:
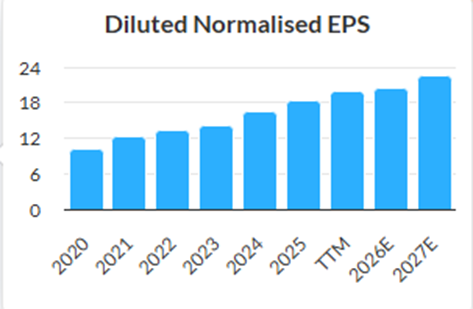
Earnings are forecast to continue to grow at the historical low-double-digit percentage rates:
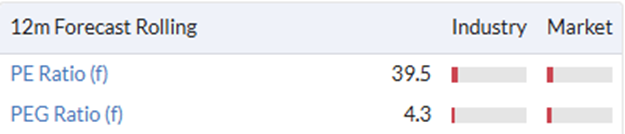
However, the rating isn't exactly cheap, meaning that perhaps a PEG ratio of over 4 becomes increasingly hard to justify, despite obvious quality attractions:
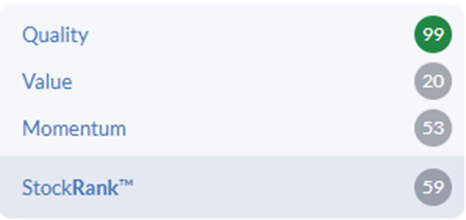
This is reflected in the Stock Ranks, where a 99 Quality Rank is let down by Value and Momentum, meaning the overall Rank is relatively lacklustre:
Here's what to look out for in next week's results:
- Sales and Footfall: comparable sales excluding fuel were up 6.6% in July; the market will want to see that hold as the year reaches tougher comparables. Investors will want to see this driven by increased visit frequency, not just promotional activity.
- Membership renewal rates: US and Canada renewal rates slid from 93.0% in Q2 FY2025 down to 92.1% by Q2 FY2026. There were early signs of stabilisation last quarter, but any further erosion will be taken badly by a market pricing in strong renewal rates.
- E-commerce: digital sales were up 18% in August and 21% for the full fiscal year, still a genuine growth engine alongside the warehouse business. Continued strong numbers here may be needed to convince the market that there is still growth potential.
Luceco (LON:LUCE)
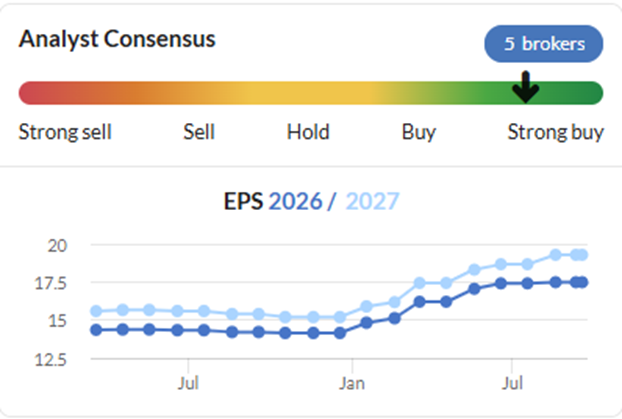
This electrical wiring accessory and LED lighting manufacturer and distributor has performed admirably this year, in tough end market conditions:
However, after a strong start, the share price topped out:
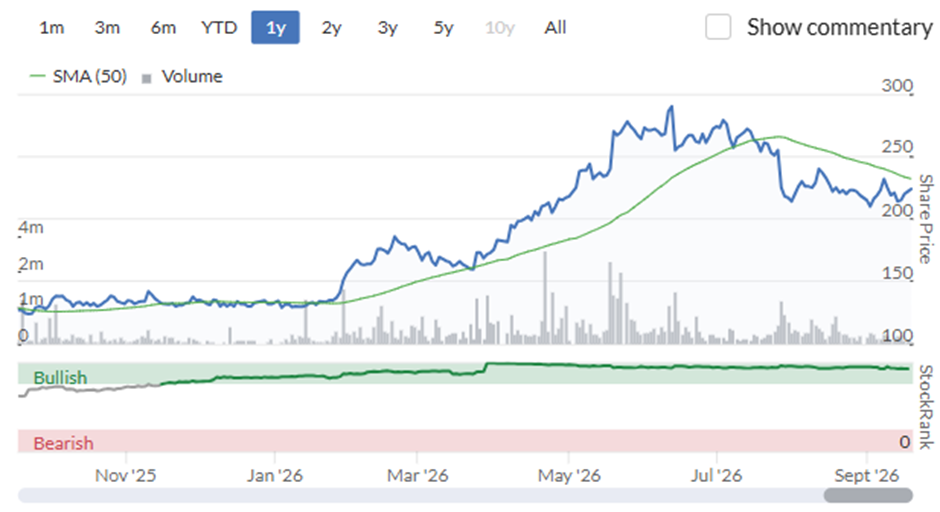
This may be because the share price had more than doubled on a 25% upgrade to EPS, or because long-term CEO and major shareholder John Hornby retired and sold some shares.
Also of concern may be that the strong performance was almost entirely due to demand for EV chargers. The core business saw far more lacklustre performance.
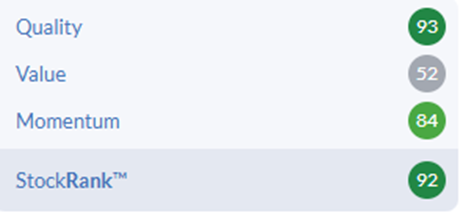
The net result is that the company remains a "Super Stock". However, this is driven far more by its QM characteristics than its value credentials:
With this backdrop, the company is under pressure to maintain that momentum into this week's Half Year Results. From the trading updates, we already know that Revenue will be around £143m, up 13% year-on-year, with growth accelerating through the half. Energy Transition revenue is the standout growth driver, up around 120% year on year.
These are things to look out for:
- Second-half guidance: only £15.8m of operating profit was booked in H1 according ot the trading statement, so Luceco needs more than £24.2m in H2 to clear the £40m full-year guidance. That's a normal seasonal skew for this business, but it means commentary on H2-to-date trading will matter.
- Adjustments: Luceco's results consistently show a gap between adjusted and statutory results; the size and nature of these matter for the business's true underlying performance.
- Cash generation: Luceco built inventory ahead of H2, so watch whether working capital unwinds and cash conversion improves, especially with leverage sitting at 1.5x. Historically, acquisitions have been a key growth driver, and high leverage will constrain this potential.
JD Sports Fashion (LON:JD.)
JD Sports Fashion reports its half-year results on Wednesday. The share price has been on a bit of a rollercoaster this year:
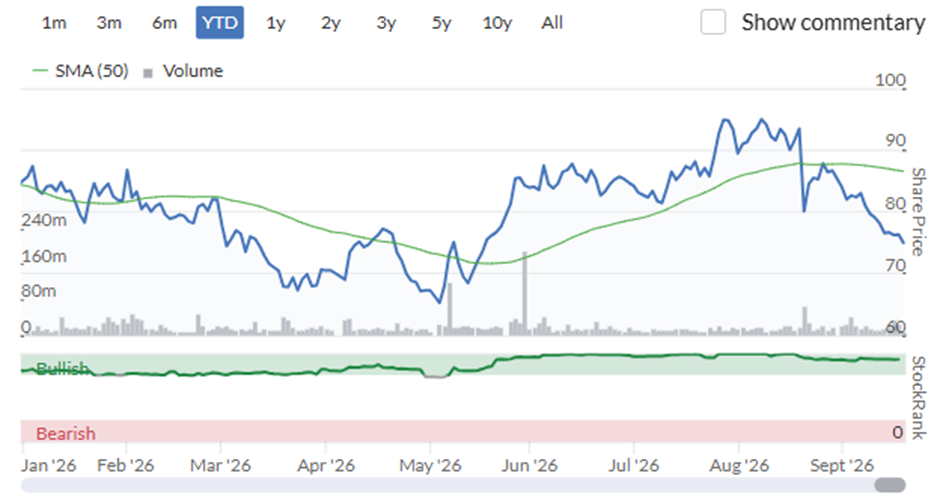
Concerns over a shift from key supplier Nike to a more direct sales route have overshadowed the business for some time. So the recent announcement that that strategy was not delivering for Nike and a shift back should be positive for JD.
However, continuous broker downgrades, including a profit warning last month, can't help but take their toll:
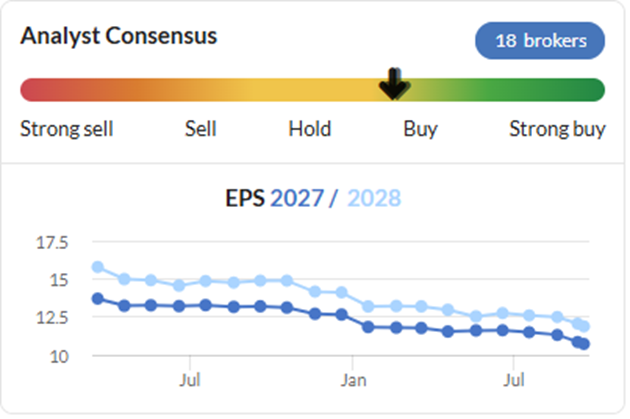
From the Q2 trading statement and profit warning, we already know
- Q1 (13 weeks): group like-for-like sales -2.5%, organic sales -0.1%
- Q2 (13 weeks to 1 August): group like-for-like sales -3.1%, organic sales -1.3%
- North America (JD's largest market at 35% of sales) took the brunt: organic sales -4.5%, like-for-like -6.8%.
- UK and Europe improved, helped by apparel/accessories, strong football replica kit sales, an improved Outdoor business, and resilient Sporting Goods trading.
The warning said that as a result, FY2026/27 profit-before-tax-and-adjusting-items guidance was cut to £700m–£800m, down from £750m–£850m. But free cash flow guidance was left unchanged at £460m–£520m
What to watch for next week:
- North America stabilisation: Any evidence that the decline eased into August/September (particularly newer footwear product and back-to-school catch-up) would support the idea this is a timing/product-cycle issue rather than something more structural.
- Nike (40% of sales): Commentary on Nike's product cycle and "high-heat" release calendar matters.
- Management tone: Does CEO Régis Schultz indicate that the slowdown is temporary or more prolonged?
Warpaint London (LON:W7L)
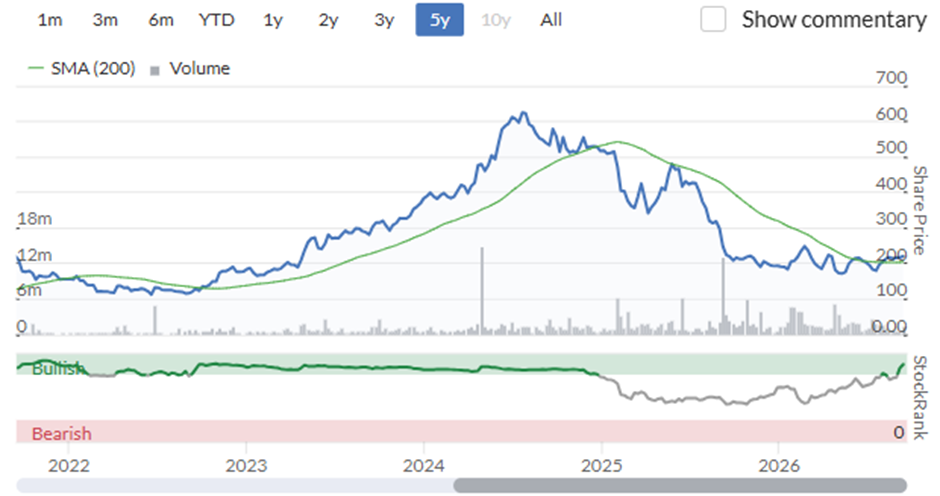
A lot has been written on Stockopedia about Warpaint's transition from a value pick to a High Flyer and back down again, which I won't do it justice here:
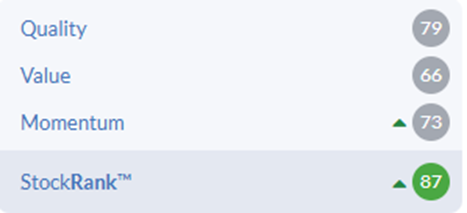
However, I note this is back as a Super Stock:
Not everything is rosy, though, as the broker consensus remains highly negative:
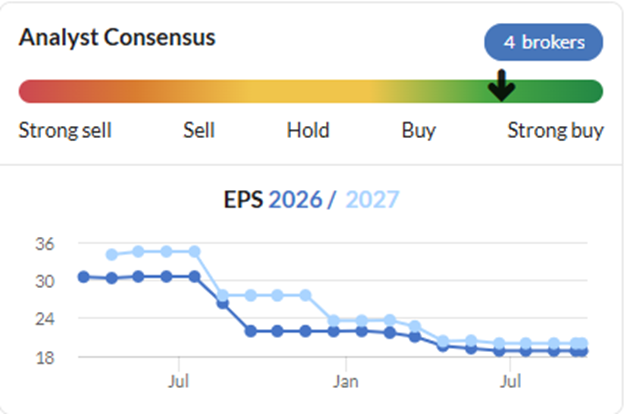
However, in their AGM statement in June, they said:
- The [challenging] trading conditions seen in 2025 continued into Q1.
- Trading remains difficult, but Q2 sales from 1 April - 31 May are ahead of the same period last year.
- Overall group sales are at "an improved margin" compared to 2025.
- The group has "significant planned expansion opportunities" for later in 2026 and expects further margin improvement.
- · Expectations for the full year remain unchanged.
The rating is not excessive, but the PEG ratio is unimpressive unless growth can accelerate from here:
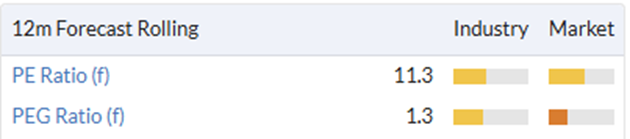
In light of this, the key points to watch will be:
- Sales Momentum: Full-year guidance was maintained, but 2026 is expected to be more second-half weighted, leaning on two specific new rollouts: Dirk Rossmann in Germany and an online Christmas gift range with Ulta Beauty in the US. Has the positive Q2 trend continued into Q3?
- Margins: These have been the one consistent bright spot even as top-line growth stalled. Have margins continued to improve?
- Tone on full-year guidance: After multiple guidance cuts in the last 18 months, the market will be reading closely for any hedging language versus a firmer reaffirmation that a recovery is underway.
- Shareholder returns: The company reported about £20m of cash in June, and the forward yield is around 6%. Investors will want to see cash continue to build and an increased interim dividend to add confidence to any forward-looking statements.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

14 comments
The Mello shows are coming thick and fast in September. On MelloMonday next week, #IPO & #TPFG present, Stuart Widdowson #OIT joins us for an interview and the BASH (Buy, Avoid, Sell, Hold) rounds off the show. Lots to cover and plenty for investors to enjoy.
MelloMonday 21st September from 5pm: https://www.melloevents.com/mm210926
Use code MMSTOCKO50 for 50% off. If you are a shareholder in any of the presenting companies, you are eligible for a free ticket for this webinar with code SHMM26
Full MelloMonday agenda (subject to minor change):
5:00pm Company Presentation from IP (LON:IPO)
5:30pm Company Presentation from Property Franchise (LON:TPFG)
6:10pm Interview with Stuart Widdowson Odyssean Investment Trust (LON:OIT)
6:40pm Company Presentation from Getech (LON:GTC)
7:10pm Mello BASH (buy, avoid, sell, hold) panel with Bruce Packard covering Manolete Partners (LON:MANO) & Richard Crow aka Cockney Rebel covering James Cropper (LON:CRPR)
Hope to see you on Monday evening. If you cannot join LIVE, please feel free to register and the recording will be distributed to you within 48 hours.
David
Am finding these week ahead reports really useful thank you. Also finding Ed Croft’s email reports very good too - keep up the great work!!
Glad to hear you are enjoying them - am wondering whether I should publish the newsletter introductions on the site too - they have evolved into complete articles now - on the other hand, if they are unique to email there's more reason to open the email ! So I'm in 2 minds. Any thoughts?
Personally I’d rather see them on the platform. I get so many emails by the time I open it it’s too late.
Ideally both on email and on the site would be great.
On site gets my vote.
Easy to miss emails. Plus allows users to discuss. Maybe within their own section to easily discover week to week.
On the site for sure - I have literally just been flicking between the really useful email you sent and the site - so in one place would be a winner for me!!
What emails? Not sure I am familiar with these.
Hi Kevin,
I think the reference here is to the Fri/Sat emails from Ed. Always an enjoyable read along with the free emails from PensionCraft and Cockney Rebel on Saturday mornings. Maybe check your spam ? They come from email address support@stockopedia.com
The most recent one was sent at 8am Saturday 19th....
I like the email. Wouldn’t hurt to then post in the site for anyone who missed it ( or a second read because they are so insightful ;) )
Anther vote for the site too. Would encourage weekend comment/discussion when there is no news.
Getech HY also on Monday. We should have sold years ago but didn't. We now have a lot of shares worth very little, somehow they're still surviving the costs of being listed and have recurring revenue. it's probably too small to make the Agenda.
Getech GTC are presenting on the Mello Monday show tomorrow evening
Add Elixirr International (LON:ELIX) Interims Mon. 21st