The Week Ahead 22-26 September: RPI, CWR

Reading the financial results of UK economic ‘bellweather’ Next should be done with the knowledge that the company’s chief executive Lord Simon Wolfson is a Conservative peer. He’s not using his statement to take a pop at the government (Lord Wolfson is cautious about the outlook for the economy no matter who is in power), but he is definitely unconvinced about the current government’s approach to economic policy.
I can’t say I blame him. Additional taxation and consistently high interest rates, policy decisions which create more red tape for British businesses, and untenable public sector spending requirements, don’t do much to instill confidence.
Next says the outlook for the UK economy is “anaemic at best”. A statement that seems to have been backed up by a mega profit warning from Pets at Home. It’s not a good sign when people aren’t willing to splurge on their pets like they did in the days of plenty.
Is this downbeat retail outlook a side effect of the continued high interest rates? It surely can’t be helping. In August, food price inflation rose for the fifth month in a row to 5.1%. Although a decline in the pace of growth of other items (airfares for example) left overall inflation unchanged from the 3.8% July figure.
With inflation still uncomfortably high, the unsurprising decision by the Bank of England this week was to keep interest rates firm at 4% and to slightly curb the quantitative tightening programme. The total value of government bonds up for sale has been lowered from £100bn to £70bn as the Monetary Policy Committee attempts to put a lid on rising bond yields. The market remained unmoved by this announcement. There aren’t a lot of surprises coming out of the central bank these days.
It’s far more interesting at the company level though, where results season in the smaller cap space continues apace next week.
And there are more companies with cyclical exposure gearing up to release their numbers. Kingfisher, for example, which owns B&Q and Screwfix in the UK and therefore has unavoidable exposure to the housing market. Hilton Food Group, which is exposed to pricing pressure from its supermarket customers, could also deliver something of interest, after its ‘not-a-profit-warning’ earlier in the month. In the energy space, we’ll have numbers from Yu Group, which features in both Roland’s and Ed’s portfolios this year.
The full table of results is below as usual, but do let us know in the comments if there are any that you think we have missed.
Economic Calendar
Tuesday 23 | ||
08:30 | Germany | Manufacturing PMI |
09:30 | UK | Manufacturing and services PMI flash data |
Wednesday 24 | ||
15:00 | US | New home sales |
Thursday 25 | ||
07:00 | Germany | Consumer confidence |
13:30 | US | Initial jobless claims |
13:30 | US | GDP growth rate |
Friday 26 | ||
13:30 | US | Personal spending and personal income |
Companies Reporting
UK Trading Updates and AGMs | UK Financial Results | International Financial Results | |
Monday 22 | Wilmington (WIL) AOTI (AOTI) Creo Medical Group (CREO) Elixirr International (ELIX) | ||
Tuesday 23 | Calculus VCT plc (CLC) Capital Metals plc (CMET) FRP Advisory Group plc (FRP) Ilika Plc (IKA) Kainos Group plc (KNOS) MyCelx Technologies Corp (MYX) Taylor Maritime Limited (TMIP) Zigup Plc (ZIG) | Fonix (FNX) Smiths Group (SMIN) Transense Technologies (TRT) Amcomri Group Plc (AMCO) Boot (Henry) plc (BOOT) Diaceutics Plc (DXRX) Hilton Food Group Plc (HFG) Hvivo Plc (HVO) Keystone Law Group plc (KEYS) Kingfisher (KGF) Mpac Group plc (MPAC) Octopus Renewables Infrastructure Trust plc (ORIT) Oxford Biomedica plc (OXB) Raspberry Pi Holdings plc (RPI) Real Estate Investors Plc (RLE) The Mission Group (TMG) YU Group plc (YU.) | Micron Technology (MU) |
Wednesday 24 | Accsys Technologies plc (AXS) Baker Steel Resources Trust Ltd (BSRT) Baltic Classifieds Group plc (BCG) First Property Group plc (FPO) Gateley Holdings plc (GTLY) IG Design Group plc (IGR) SDI Group Plc (SDI) System1 Group plc (SYS1) Zegona Communications plc (ZEG) | Avingtrans plc (AVG) Redcentric plc (RCN) Time Finance (TIME) Directa Plus plc (DCTA) Everyman Media Group plc (EMAN) Gresham House Energy Storage Fund Plc (GRID) NAHL Group plc (NAH) Pinewood Technologies Group plc (PINE) Saga plc (SAGA) | |
Thursday 25 | Altitude Group Plc (ALT) Babcock International Group (BAB) Cambridge Nutritional Sciences plc (CNSL) Cohort plc (CHRT) HSS Hire Group plc (HSS) Intercede Group plc (IGP) Iomart Group (IOM) Mercia Asset Management plc (MERC) PHSC plc (PHSC) Sorted Group Holdings plc (SORT) TPXImpact Holdings (TPX) Van Elle plc (VANL) Wise plc (WISE) Zoo Digital Group (ZOO) | DFS Furniture plc (DFS) Seeing Machines Ltd (SEE) Glenveagh Properties Plc (GLV) Polarean Imaging Ltd (POLX) STV Group plc (STVG) | Accenture (ACN) Costco Wholesale (COST) |
Friday 26 | Baillie Gifford US Growth Trust plc (USA) Carclo plc (CAR) | ASA International Group Plc (ASAI) Ceres Power Holdings (CWR) |
Raspberry PI Holdings (LON:RPI)
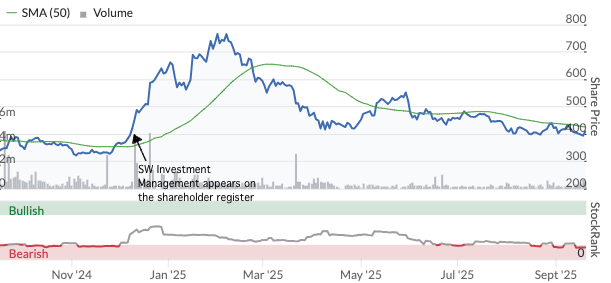
After just over a year as a listed company, Raspberry Pi’s share price chart teaches us an important lesson: simply following a US investor onto the shareholder register isn’t a good medium term investment strategy.
After spiking to a peak market capitalisation of more than £1bn, the short-term excitement for the stock has tempered a little. Probably not helped by a 57% decline in pre-tax profits in the 2024 financial year - a performance that the company described incredibly optimistically as “resilient”.
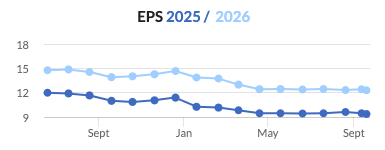
I fully understand the concerns flagged by both Paul and Graham about this stock. Namely that a £790m market capitalisation is an awful lot for a company which has reported declining profits and limited free cash flow. Brokers aren’t especially positive either, with EPS expectations declining repeatedly in the last few months.
But I am still interested. Not interested enough to have bought just yet, but interested enough to keep a look out for a change in the direction of profit growth.
Raspberry Pi has a dedicated following of customers and is hugely respected within the computing and electronics market, which gives it a pretty impressive moat. The company compares itself to the “other fruit company” or “ofc” and I do see the similarities. Like Apple, Raspberry Pi is building itself a walled garden. Software engineers who like the tech stack for their own personal use will take the technology into the workplace. And with an incredibly competitive pricing point, borne out of the company’s efficiency, Raspberry Pi is not finding it difficult to grow its customer base.
I’ll be watching next week’s interim results with interest to look for signs of a change in the direction of profits.
Ceres Power Holdings (LON:CWR)
The share price of hydrogen fuel cell specialist Ceres Power leapt 45% in July on the news that a customer in South Korea had taken the products for which it uses Ceres’ tech into commercial production.
That is a whopping movement and the continued momentum has meant the price has just about recovered to the level it was at in February, when the stock dropped 40% in a day after the loss of a big contract with Bosch.
And therein lies the problem with investing in Ceres Power. A lack of profits (which has lasted for the entirety of the two decades that Ceres has been listed) means the fortunes of the share price are almost entirely hinged on the company’s ability to sign and then commercialise partnerships with other companies. And this South Korean contract is the very first which will see a product that contains Ceres technology become actually commercially available.
It’s a big moment for investors who have followed the company’s various tribulations for a long time. But does it represent a turning point?
I am not sure. Next week’s results no doubt contain much of the same information that we already know. The company is still loss making, but management will almost certainly be saying lots of positive things about the potential for its solid oxidation technology in a market which is desperate for alternative fuel sources.
Back when I covered small cap stocks for Investor’s Chronicle I spent some time trying to understand the technology that Ceres specialises in and I can see that it is potentially exciting. Alternative fuel sources are going to have to become more readily available (despite the fact that green investing isn’t quite as stylish as it was a few years ago). And from a financial perspective, as long as the losses can be kept in check, the company should be ok with the cash it has available for a while longer.
Celebrating Britain and its technology
I watched an interview that Raspberry Pi’s chief executive gave to Peel Hunt earlier this year. He says a lot of interesting things about the company, but one sentence stood out: “every company should be listed.”
Last year when Raspberry Pi came to the market, it did a lot of good to ease investors’ concerns that London may never attract an exciting tech company again. And it’s good to see that the price remains above the IPO price, even though the first year hasn’t been massively exciting.
As for the notion that every company should be listed. I like the attitude. I firmly believe that more people in the UK should engage with the capital markets and the more exciting companies like RPI and Ceres Power that we can attract, the more people we will be able to engage in the stock market.
The trouble is that investors want results, often far quicker than a company can deliver them. And in Britain those results normally look like growing profits and a healthy dividend.
In this article I have chosen to look at two companies which I am genuinely fascinated by. They have brilliant technology and seem to be being run pretty sensibly at the moment. But I haven’t invested. And neither my colleagues or the algorithms at Stockopedia seem to be suggesting that these are good potential investments.
So what to do? How can London hope to attract more exciting companies, when the ones that we have remain firmly in the “too risky for me” group of listed stocks. I wish both Raspberry Pi and Ceres Power well and hope that they can start to deliver the kind of results that stock market investors want from their investments.
But I also hope that more investors and journalists are willing to talk and write about these kinds of stocks. Because they are doing exciting things. And however much I like the honesty and diligence with which Simon Woolfson puts together his financial results statements, I don’t think the phrase “anaemic growth” being splashed all over the financial media is going to do much to promote a recovery in London’s stock market.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

6 comments
On Beach group (LON:OTB) is also due to give a trading update on Wednesday https://otp.tools.investis.com...
Hi Megan
I believe JD Sports is due to give half-year report on Wed 26th
Thx
Excellent thought provoking read ... thank you.
I believe TT electronics (LON:TTG) will report interims on Wed 24th & IG group (LON:IGG) will provide a Q1 trading update on 25th
Add Journeo (LON:JNEO) Interims on Thurs 25th.
Megan you make a good point about floating.I ran a successful small cap.broker and lived in Cambridge. The reason a lot of small caps do not float is their accountants in particular would rather book a big fee selling to an American company and booking a huge fee.I could give examples but the list would be too long.
However it is also true that some companies sell out who do not have a sufficient range of clients,are dominated by an individual who cannot delegate, or on a long term "sucker stock" trip as a loss maker.
RPI is in the first category and an upturn in floats is on the way in 2026 to follow Wall Street so hopefully we will see a few more.
If Ken Clark had followed through with a second 0.5% cut in stamp duty it would have helped !
Ken Ford