The Week Ahead (22nd - 26th December) - Dovishness prevails at the Bank of England

This will be a mini-version of The Week Ahead, seeing as almost nothing is scheduled for this week.
Therefore, instead of looking ahead, I’m going to review the Bank of England’s interest rate decision on Thursday.
Bank of England decision
On Thursday, as expected, the Bank of England cut rates from 4% to 3.75%.
It was another tight decision with a 5-4 split on the Monetary Policy Committee.
Decisions have been very close in recent times, and the minutes now include the views of each individual member of the committee.
So how can a rate cut be justified when inflation remains above the 2% target? This is how:
CPI inflation has fallen since the previous meeting, to 3.2%. Although above the 2% target, it is now expected to fall back towards target more quickly in the near term. Reflecting restrictive monetary policy, and consistent with evidence of subdued economic growth and building slack in the labour market, pay growth and services price inflation have continued to ease.
In other words: the Bank is basing its decision on medium-term inflation forecasts, not the current inflation rate.
Indeed, the Bank is confident enough in these predictions that it is willing to guide for a continued “gradual downward path” in rates.
Some key data points mentioned in the release:
CPI inflation has reduced from 3.8% (September) to 3.2% (November).
It’s expected to fall further to 3% in Q1 2026.
The recent Budget is considered likely to lower CPI inflation from April by 0.5%.
Combining the effects of the Budget, recent CPI data and oil and gas prices, BoE staff now expect CPI inflation to fall closer to 2% by Q2 2026.
With CPI therefore on the way to target, the Bank is able to continue with its transition into a “less restrictive” monetary policy.
Let’s see what the dissenters had to say, with a few snippets:
Megan Greene:
As Bank Rate approaches neutral, the contribution of monetary policy versus structural factors to disinflation could become harder to discern. This warrants a more cautious cadence of easing.
Clare Lombardelli:
The Budget should mechanically reduce annual inflation in salient categories, reducing the risk of second-round effects, but in absolute terms underlying inflation is still well above target-consistent rates.
Catherine L Mann:
…Despite the Budget’s expected mechanical reduction in near-term inflation, this may not be enough to rein-in elevated household inflation expectations that have formed during a prolonged high‑inflation environment. CPI inflation remains above target, services inflation remains high relative to international peers, and core goods inflation is well above historical target‑consistent rates.”
Huw Pill:
I continue to judge the risk of inflation stabilising at above-target levels owing to structural changes in price and wage-setting behaviour as greater than the risk of inflation undershooting the target owing to weak demand.
I’m not an economist, but I do try to follow the Bank of England to the extent that it’s necessary to understand the stocks that we follow here.
And as someone who tends to be wary of economic forecasts, my instincts are with the dissenters. I’d wait for the target to be hit first, rather than acting on the basis that it will be hit.
The red line is the target:
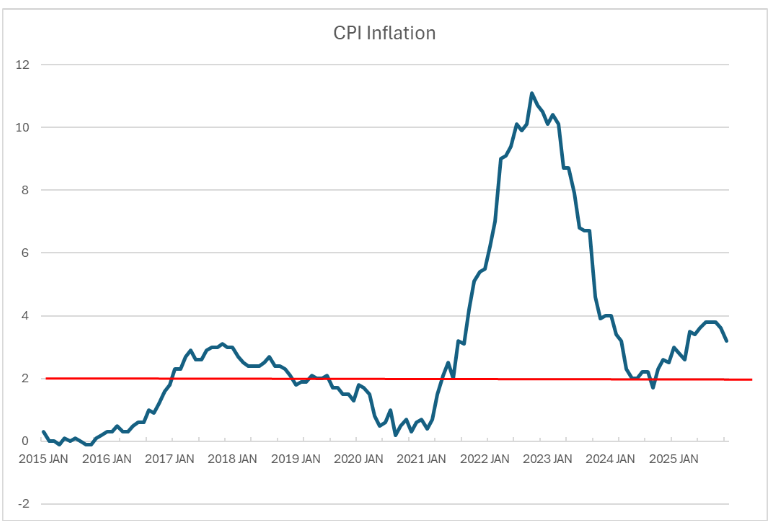
Suppose that the Bank of England was a mid-cap company aiming for a particular profit margin. Suppose that it had only rarely achieved this profit margin in recent years, but it forecast that it would hit it at some point in the current financial year.
In that context, would we be happy for the company to start taking various actions pre-emptively, on the basis that the target would be hit? For example, paying performance-based stock options or declaring special dividends? Maybe, but personally I’d want to see the target get hit first, before I was happy for the company to start celebrating.
Looking forward, the Bank has signalled more cuts and the City expects another two cuts early next year, bringing the rate down to 3.25%.
What it all means for shares: interest rates are gravity for share prices, and in simple terms lower rates should boost asset prices.
Reality is more complicated than that: the stock market never responds to only one variable alone. And anything that is public has probably already been priced in - such as anticipated rate cuts.
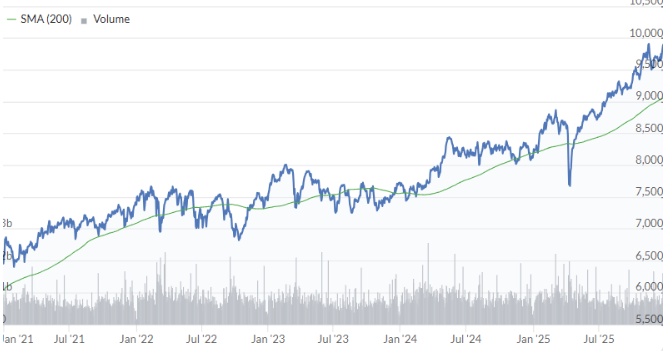
In that regard, the FTSE has had a remarkably positive year and trades on a historically high trailing P/E ratio of about 19x. So perhaps the pleasant downward trajectory of interest rates is fully priced in here?
N. B. There will be almost no company news this week, and the London Stock Exchange will close early at 12.30pm on Christmas Eve (Wednesday!)
Economic Calendar
| Date | Time (GMT) | Country | Event |
|---|---|---|---|
Monday 22 December | 07:00 | UK | Current Account |
Tuesday 23 December | 05:00 | EU | New Car Registrations |
Tuesday 23 December | 13:30 | US | Gross Domestic Product |
Wednesday 24 December | 12:00 | US | MBA 30-Year Mortgage Rate |
Wednesday 24 December | 12:00 | US | Initial Jobless Claims |
Companies Reporting
| Date | UK Trading Updates and AGMS | UK Financial Results | International Financial Results |
|---|---|---|---|
Monday 22 December | Gelion (LON:GELN) (AGM) Grit Investment Trust (LON:GRIT) (AGM) | None scheduled. | None of significance scheduled. |
Tuesday 23 December | None scheduled. | None scheduled. | None of significance scheduled. |
Wednesday 24 December (UK Market closes 12.30pm) | Beacon Energy (LON:BCE) (AGM) | None scheduled. | None of significance scheduled. |
Thursday 25 December (UK Market closed) | None scheduled. | None scheduled. | None of significance scheduled. |
Friday 26 December (UK Market closed) | None scheduled. | None scheduled. | None of significance scheduled. |
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

2 comments
Graham (and Roland, Mark, Ed, Megan and the team) thanks for all your commentary this year - have a good Christmas, and best wishes for 2026.
Thanks so much Tim. Have a lovely Christmas yourself!