The Week Ahead (24 Aug – 28 Aug): Nvidia & Warsh's Jackson Hole Debut – Twin Tests for the AI Trade
1. Market Recap
The bond market has set the tone this week. The 30-year Treasury yield pushed to its highest level since 2007 and the 10-year to its highest since January 2025, as fading hopes of a US–Iran resolution lifted oil and investors grew nervous about the sheer volume of long-dated supply – government borrowing and the AI investment boom are now competing for the same pool of capital, raising the cost of it for everyone.
Equities took the bond moves badly. The S&P 500 fell for a third straight session on Tuesday, which also brought the week's ugliest showing: the Philadelphia semiconductor index tumbled 5% as investors fled the AI trade, with the Nasdaq down 1.3%.
Wednesday's session was heavy for AI names again, but there was a brief reprieve – yields fell as the US Treasury said it would at least double the size of its buyback operations in longer-dated debt (to at least $4bn per operation). The 10-year and 30-year yield pulled back from highs and global markets rallied on Thursday morning (Korea's Kospi closed up 5.9%).
That didn’t last long. Treasury yields reversed course on Thursday afternoon. Stocks were largely negative by the time US markets opened.
During the week, gross federal debt crossed the $40trn mark, with $3trn added in the last year alone according to FT calculations – that’s the fastest pace ever outside of the pandemic years. Buybacks seemingly aren’t enough to temper worries about the sheer size of the debt.
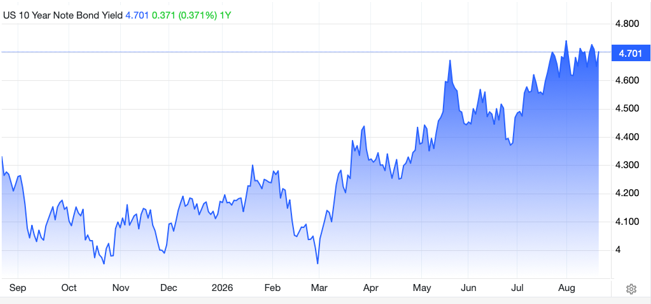
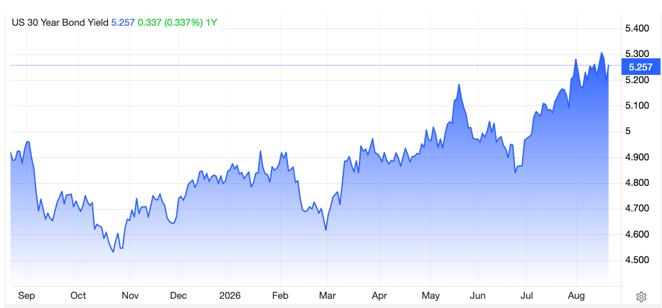
[Chart: US 10-year and 30-year Treasury yields, past month. Source: TradingEconomics]
The week's other big story was in healthcare. On Wednesday, Moderna and Merck said their personalised mRNA cancer vaccine (intismeran autogene, paired with Keytruda) met its main goals in a Phase 3 melanoma trial – the first neoantigen vaccine to succeed at that stage.
Moderna, one of the market's most heavily shorted large caps, rose about 177% in a single session and Merck added 12%, with short covering rippling across the wider biotech segment. Analysts put peak annual sales above $6bn for melanoma alone. Moderna has lung, kidney and bladder trials to come, all utilizing the same personalised mRNA mechanism to target highly responsive tumours. Interesting read for markets, hopefully far bigger news for medicine.
The wider backdrop:
- “Economic D-Day”: Trump has vowed tougher economic measures on Iran, implying a deal is not at hand. As a result, oil has ground higher, but Brent – the seaborne benchmark – sits just above $90. Axios reports that the US has established a shipping corridor out of the Strait of Hormuz, presumably skirting the Musandam peninsula. Two Chinese tankers reportedly U-turned in the strait, while Beijing has bought millions of barrels of Saudi crude via a rare tender – seemingly evidence that the US may be gaining the upper hand.
- Yields and the “hyperscaler debt” question: the selloff wasn't only about oil and inflation. The AI build-out is increasingly debt-funded, and long-end investors are demanding compensation for the extra supply – a theme that runs straight into Wednesday's Nvidia print (see below). July’s Fed minutes referenced AI tech 19 times as officials debated whether the boom could stir inflation.
- UK CPI at 2.9%: July inflation rose from 2.6% to a four-month high, in line with forecasts, driven by Ofgem's 13% energy price cap hike – gas prices rose 14.7%, the largest increase since October 2022. The FTSE 100 barely reacted, holding around 10,735 as miners rallied. Nothing here to change the Bank of England's “no cuts” stance. The pound has hit 1.36 versus the dollar.
Here's what we can look forward to next week:
2. Economic Calendar
It’s looking like a quiet week for UK and European data -- the calendar is dominated by the US, with Wednesday's GDP second estimate and PCE price data the main scheduled releases before the Fed's Jackson Hole Symposium (27–29 Aug). All times BST (UK time).
| Day | Time | Region | Release |
|---|---|---|---|
Monday 24 Aug |
– |
– |
Nothing major scheduled |
Tuesday 25 Aug |
15:00 |
US |
CB Consumer Confidence |
Wednesday 26 Aug |
13:30 |
US |
GDP Q2 (second estimate) & PCE price data |
Thursday 27 Aug |
All day |
US |
Jackson Hole Symposium begins (27–29 Aug) |
Friday 28 Aug |
All day 13:30 |
US Canada |
Jackson Hole – Warsh keynote (15:00 UK) GDP Q2 |
3. Macro Theme Deep-Dives
Jackson Hole: Warsh's Debut
The Kansas City Fed's Jackson Hole Symposium runs Thursday to Saturday under the theme “Financial Innovation: Implications for Payments and Policy” – but nobody is going for the payments papers. Kevin Warsh will deliver his first Jackson Hole keynote as Fed Chair, 19 days before the 16 September FOMC decision, and with the dot plot still implying a hike rather than a cut, the market wants to know how firm that bias really is after the soft summer payroll prints.
Warsh has hinted at a “big picture” speech and says he is not “constrained by market prices”. As we’ve discussed before, he’s more interested in the number on the left side of the decimal point than the right. By abandoning the tradition of telegraphing every policy shift, Warsh is injecting volatility into near-duration assets, forcing a fundamental reassessment of short-term risk. Supporters will say tolerating near-term volatility is exactly how he caps 30-year yields.
Bonds vs the AI Trade
This week's selloff posed the question that will hang over Nvidia's results: can equities keep rallying while long-end yields grind higher?
BlackRock's Global Chief Investment Strategist Wei Li offered a useful framework this week: looking across past rate shocks (the euro sovereign crisis, the taper tantrum, 2018, COVID), she argues the speed of rate repricing and rate volatility mattered as much as rate levels; credit spreads are the cross-asset confirmation to watch when equities sell off; and starting valuations determine the severity of any drawdown, not just its direction.
She concluded that strong earnings momentum, well-behaved credit spreads and contained rate vol keep her comfortable overweight equities “at this moment”.
And this brings Nvidia’s results into sharper relief. If Nvidia delivers and spreads stay calm, this week's wobble looks like an air pocket – one of many.
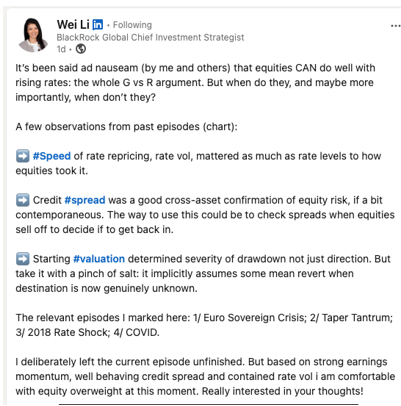
Source: Wei Li / BlackRock, LinkedIn]
4. Companies Reporting
| Date | UK Trading Updates & AGMs | UK Financial Results | International Financial Results |
|---|---|---|---|
Monday 24 Aug |
Union Jack Oil plc (LON:UJO) (AGM) |
PDD Holdings (NSQ:PDD) |
|
Tuesday 25 Aug |
Duke Capital Limited (LON:DUKE) (AGM), Livermore Investments Group Ltd (LON:LIV) (AGM), Tortilla Mexican Grill Plc (LON:MEX) (AGM), Volex Plc (LON:VLX) (AGM) |
Chesnara (LON:CSN) (Interims), Gulf Keystone Petroleum (LON:GKP) (Interims) |
|
Wednesday 26 Aug |
Cadence Minerals plc (LON:KDNC) (AGM), Oxford BioDynamics plc (LON:OBD) (AGM) |
Central Asia Metals (LON:CAML) (Interims), Empresaria Group (LON:EMR) (Interims), Faron Pharmaceuticals OY (LON:FARN) (Interims) |
Nvidia (NSQ:NVDA) (Quarter 2), CrowdStrike (NSQ:CRWD) (Quarter 2) |
Thursday 27 Aug |
DSW Capital plc (LON:DSW) (Trading announcement) |
Prudential (LON:PRU) (Interims), MacFarlane Group plc (LON:MACF) (Interims), PPHE Hotel Group Ltd (LON:PPH) (Interims) |
Royal Bank of Canada (NYQ:RY) (Quarter 3) Marvell Technology (NSQ:MRVL) |
Friday 28 Aug |
London Btc Company Ltd (LON:BTC) (AGM), FIH Group (LON:FIH) (AGM) |
Beowulf Mining plc (LON:BEM) (Quarter 2) |
As usual, let us know via the comments if you think we've missed anything of note.
5. Stock Deep-Dives
NVIDIA (NSQ:NVDA)
Nvidia reports Q2 FY27 results after Wednesday's close (release ~21:20 BST, call at 22:00 BST) – and it carries a lot of macro weight. It lands a day before Jackson Hole begins, into a market that spent this week questioning whether the debt-funded AI build-out is what's pushing long-end yields to cycle highs.
Consensus sits at roughly $92.05bn of revenue and EPS of $2.06, with 32 upward revisions in the last 90 days and just one downward. Data centre is expected to contribute $85–87bn – roughly 90% of the total – driven by the continuing Blackwell ramp across hyperscale and enterprise deployments. It’s still not particularly expensive at 24x forward earnings, and 17x FY28 earnings.
Things to watch:
- The Q3 guide: as ever with Nvidia, the print matters less than the guidance. A beat-and-raise keeps the AI trade's earnings-momentum leg intact. Anything seen as deceleration hits a market already on edge.
- Hyperscaler capex commentary: any colour on customers' spending intentions – and how that spending is being financed – speaks directly to this week's bond market anxiety. Commentary on $500bn of funding for hyperscalers is also expected.
- Blackwell supply and margins: whether supply, not demand, remains the constraint, and what the ramp is doing to gross margins. China/export commentary is still something of a wildcard.
[Chart: NVDA EPS, P/E. Source: Stockopedia]
Crowdstrike Holdings (NSQ:CRWD)
CrowdStrike also reports Q2 FY27 on Wednesday, after the close, and it goes in priced for perfection: the stock is up 91% in 2026, sits near its 52-week high around $207–213, and trades at roughly 163x forward non-GAAP earnings. Last quarter it beat estimates and the shares still fell 6.5%.
Consensus is for around $1.44bn of revenue. The number that matters is net new ARR: management guided $284m–286m, and analysts are looking for a print above that range to confirm organic ARR growth is reaccelerating towards 29%.
Things to watch:
- Net new ARR vs the guide: a beat meaningfully above $286m validates the reacceleration story and probably lifts the stock despite the multiple; anything in-line risks a “good quarter, wrong price” reaction like last quarter's.
- The AI security narrative: commentary on AI-driven module adoption (and anything on agentic-AI security demand) underpins the premium multiple.
- Sector read across: reporting alongside Nvidia makes Wednesday evening a referendum on the AI/tech trade. A double beat could be the tech momentum catalyst while a double miss into Warsh's Jackson Hole debut is the bear case for the week.
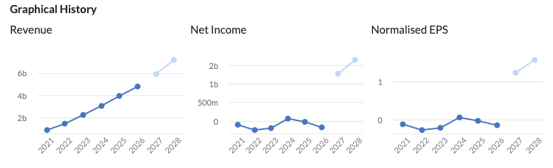
[Chart: CRWD revenue, net income, EPS. Source: Stockopedia]
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

2 comments
Excellent summary for next week!
All the best
Thank you :) Really kind