The Week Ahead (25 – 29 Aug): House Prices, NVDA, AT., HTG

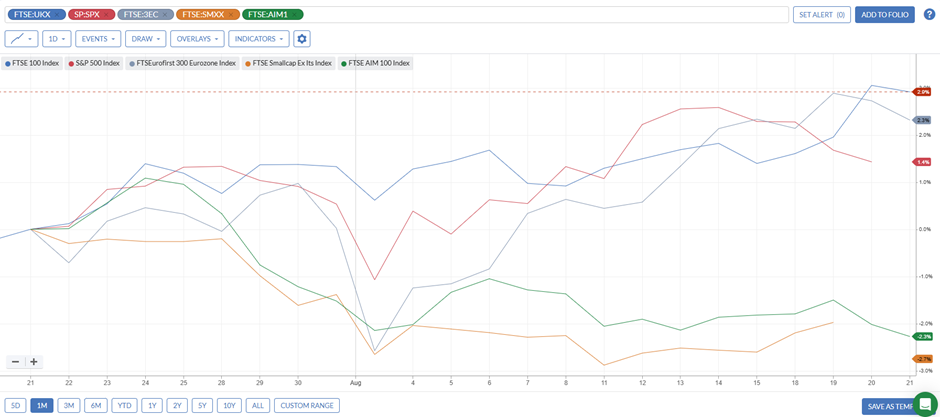
It is likely to be another quiet week for results, given the Summer holidays in the Northern Hemisphere and the UK Bank Holiday on Monday. The Summer malaise doesn't seem to have impacted broader indices, with the FTSE, S&P and Eurozone indices all gently rising over the last month. However, small caps and AIM stocks have wilted in the heat:
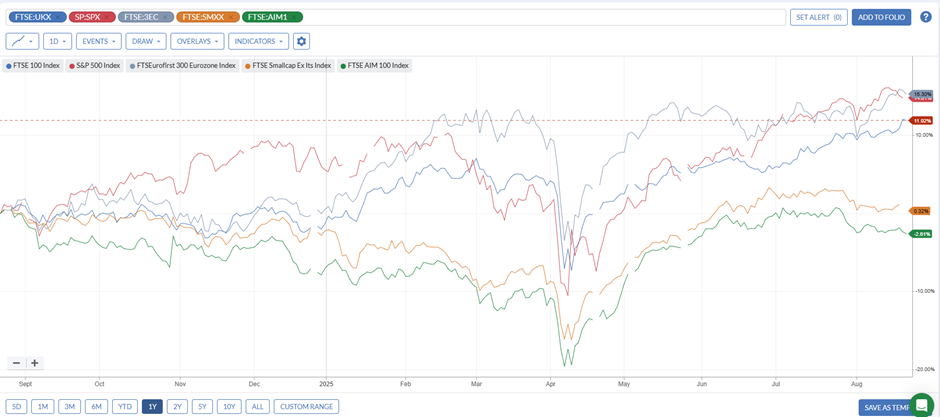
With large caps again dominating returns over the last year, investors must be wondering when, if ever, this trend will reverse:
Here's what we can look forward to next week:
Economic Calendar
Monday 25th Aug |
||
Tuesday 26th Aug |
||
13:30 |
United States |
Durable Goods Orders |
14:00 |
United States |
House Price Index |
15:00 |
United States |
Consumer Confidence New Home Sales |
Wedensday 27th Aug |
||
07:00 |
Germany |
Consumer Confidence |
15:30 |
United States |
Crude Oil Stocks |
Thursday 28th Aug |
||
09:00 |
Euro Area |
M3 Money Supply |
10:00 |
Euro Area |
Consumer Confidence Economic Confidence |
13:30 |
United States |
Initial Jobless Claims |
Friday 29th Aug |
||
07:00 |
UK |
Nationwide HPI |
07:00 |
Germany |
Import Price Index Retail Sales |
13:30 |
United States |
Balance of Trade Personal Spending Personal Income |
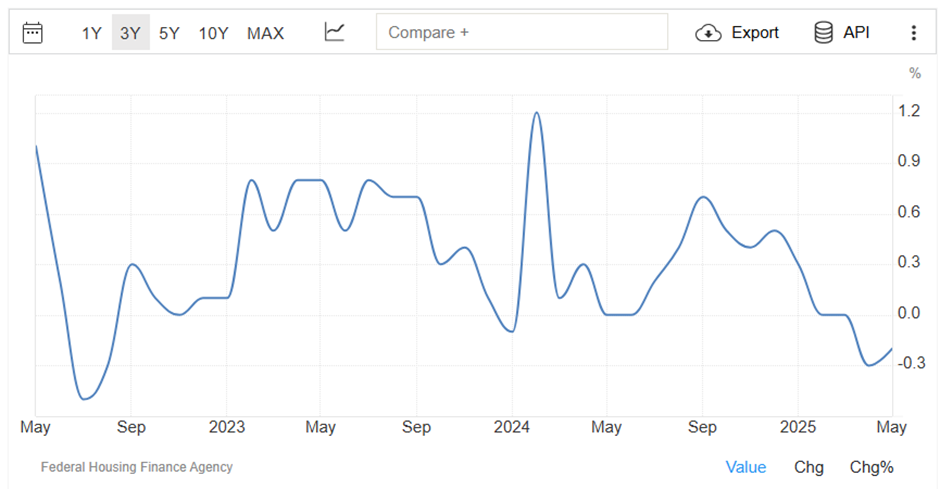
This week's economic news will be dominated by house price data. The US appears to be reacting to tariff uncertainty and rising long-term interest rates, dipping into negative year-on-year in April and May:
[Graph: Trading Economics]
This may be a bellwether for general consumer confidence, and a further negative print on Tuesday could indicate further economic pain to come.
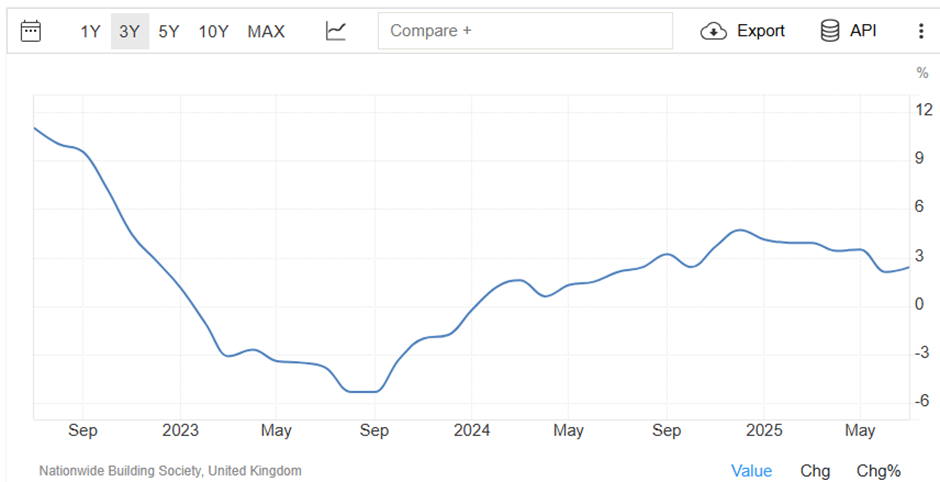
Closer to home, Nationwide reports its latest index figures on Friday. June figures came in at 2.1% annualised, versus a 3.3% consensus, suggesting that things are getting worse:
[Graph: Trading Economics]
Forward indicators are mixed. BOE mortgage approvals appear to have stabilised:
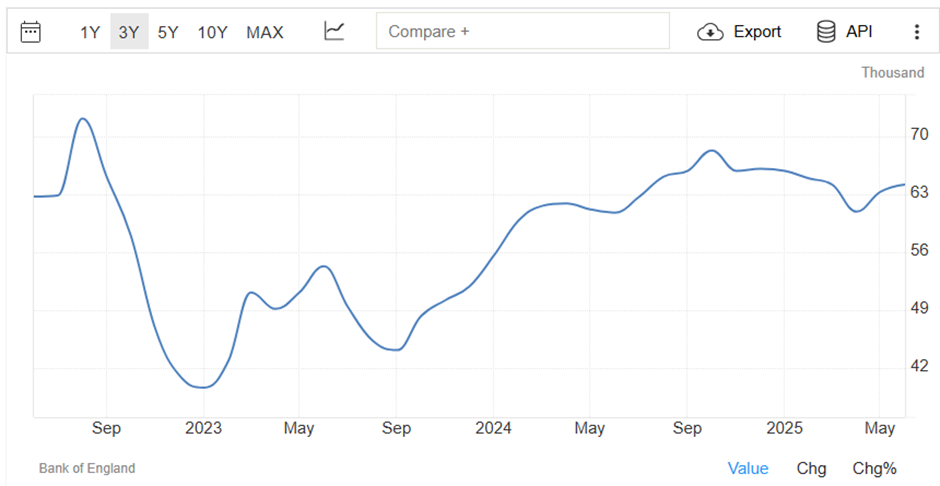
[Graph: Trading Economics]
Whereas RICS survey data indicates further pain ahead:
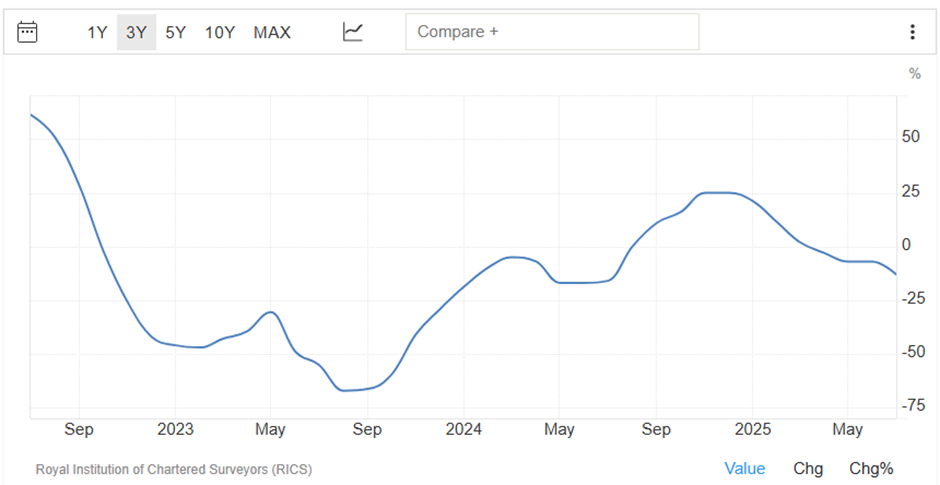
[Graph: Trading Economics]
Whatever the figures are, they are unlikely to be great for property investors in the short term.
Companies Reporting
UK Trading Updates |
UK Financial Results |
International Financial Results |
|
Monday 25 Aug |
Advancedadvt (AGM) |
|
|
Tuesday 26 Aug |
Livermore (AGM) Crism Thera (AGM) |
Ashtead Technology (Interims) Mti Wireless (Interims) |
HP (Q3) Okta (Q2) Veeva (Q2) |
Wednesday 27 Aug |
Falcon Oil (AGM) |
Sydbank (Interims) |
Abercrombie & Fitch (Q2) Agilent (Q3) Autodesk (Q2) Burlington Stores (Q2) Campbell's Co (Q4) CrowdStrike Holdings (Q2) Dollar General (Q2) NetApp (Q1) Nvidia (Q2) |
Thursday 28 Aug |
Creightons (AGM) |
Chesnara (Interims) Electrica (Interims) Hunting (Interims) Macfarlane (Interims) Pphe Hotel (Interims) PureTech (Interims) South32 (Finals) |
Dell (Q2) Pernod Ricard (Finals) |
Friday 29 Aug |
Cake Box (AGM) |
NVIDIA (NSQ:NVDA)
Nvidia has been a stellar performer over the last few years, on the back of the AI adoption wave:
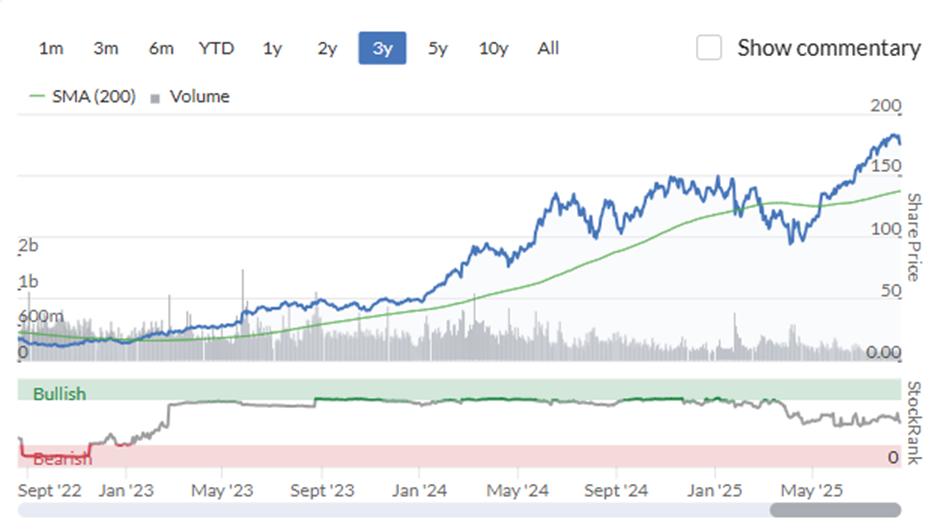
This has propelled it to the largest US company, with a market cap of over £3 trillion:
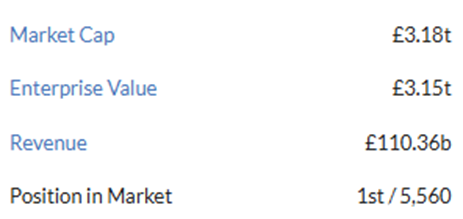
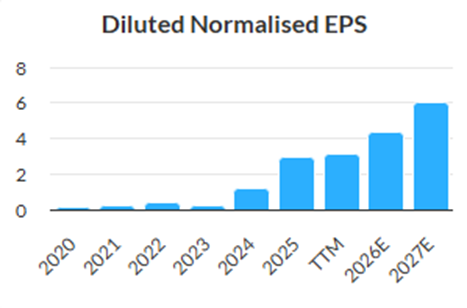
The rise has been backed by a huge rise in EPS, as demand for its chips for AI data centres has soared:
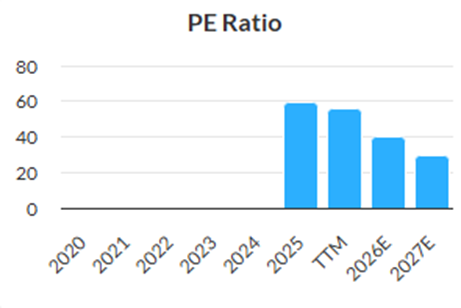
This means that, despite this meteoric rise, the forward P/E looks pretty reasonable:
Brokers have continually upgraded expectations, meaning that more could be to come:
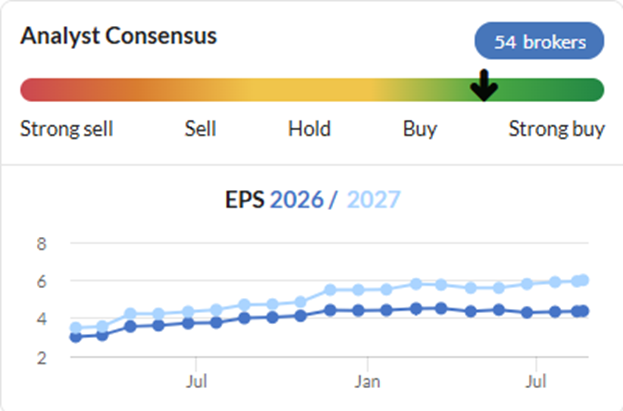
Perhaps elephants do gallop?
However, there are also some reasons to be cautious. Such cycles tend to have a rush of demand, followed by a lull while customers figure out what to do with the hardware they have bought. Nvidia was also accused last year of lending money to customers to buy their chips, which would likely bring forward demand if true.
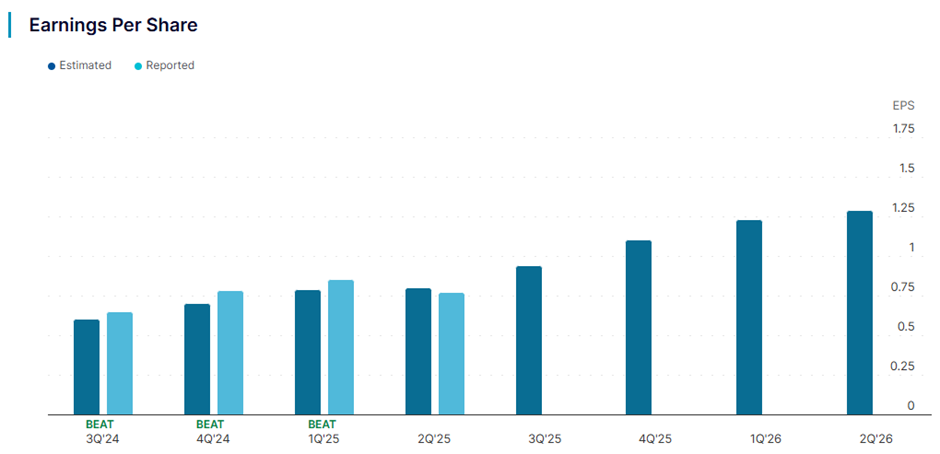
Despite the shares hitting all-time highs recently, the earnings declined in Q2 and missed expectations:
[Source: NASDAQ]
Backing up this caution is a Momentum Rank that should probably give investors in High Flyers pause for thought:
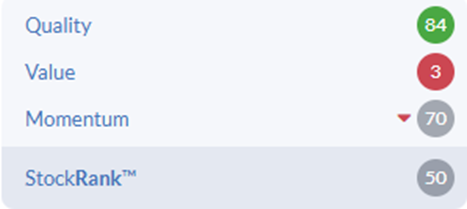
So a lot is riding on Thursday's quarterly numbers. If the company is back to winning ways and beating expectations, then we can expect the shares to make new highs. If this is the second miss in a row, the market may suspect a trend is forming, and the sell-off could be brutal. Given this is currently around 8% of the S&P500 on its own, this will probably impact the wider indices, either way.
UK Companies
Personally, I will be closely following two mid-cap UK companies that are reporting interim results this week, Ashtead Technology and Hunting.
Ashtead Technology Holdings (LON:AT.)
The company issued a trading statement on 17th July, which means the revenue figures for H1 are already known:
The Group delivered revenues of approximately £99m in the first half of 2025, representing growth of 23% over the prior year on a reported basis (down 6% on a pro-forma basis). A combination of the challenging geo-political environment, significant disruption in the US market and a small foreign exchange headwind, together with a focus on higher quality rental revenues and pro-actively reducing exposure to cross hire and low margin equipment sales, resulted in lower revenues than initially expected.
Sales disappointed, but the EBITDA margin held up:
Adjusted EBITA margin performance during the period has been resilient and is expected to be c.27.3% (H1 2024 pro forma: 26.1%), consistent with the Group's medium-term target of high 20%'s.
Doing the maths, we get around £27m EBITDA for the half. We also know that:
Cash generation in the first six months was in line with expectations, and the Group expects pro forma net debt leverage at 30 June 2025 of c.1.6x.
24H2 adj. EBITDA was £38.1m, so this means TTM EBITDA is around £65.1m and net debt is around £104m. If this calculation is done on the same basis, this represents a decline from the £128m net debt reported on 31st December. It is still higher than their 1.3x leverage target for the end of the year, though.
However, the trading statement also came with a profit warning:
Through the remainder of the year, the Company will continue to focus on project delivery and strategic growth whilst maintaining cost control. In this business environment, the Board now expects high single digit percentage growth on first half revenues in the seasonally more significant second half. The Board's view is that full year Adjusted EBITA will be modestly below its previous expectations whilst its expectations for adjusted profit before tax remain unchanged.
If we take "high single digit" as 8% then this is £107m for H2 and £206m for the Full Year, which is exactly the consensus in Stockopedia:

Even though the company kept PBT guidance the same, the brokers took the opportunity to apply some minor downgrades:
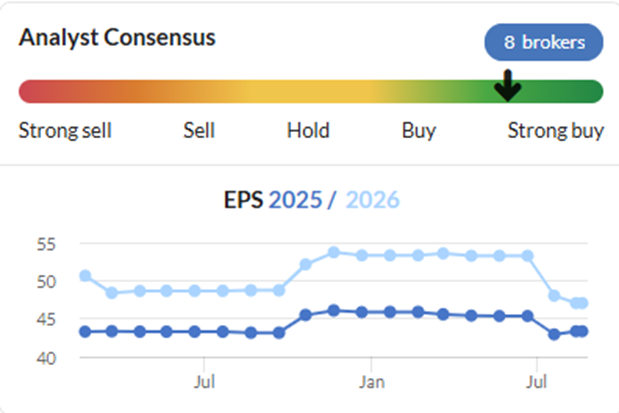
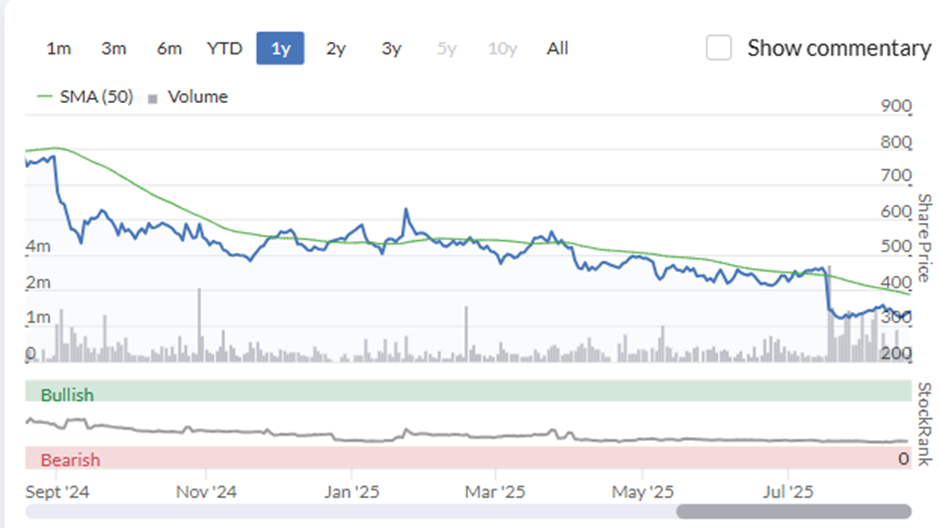
Most significantly, they reduced 2026 EPS by around 10%, and an already declining share price took a big hit:
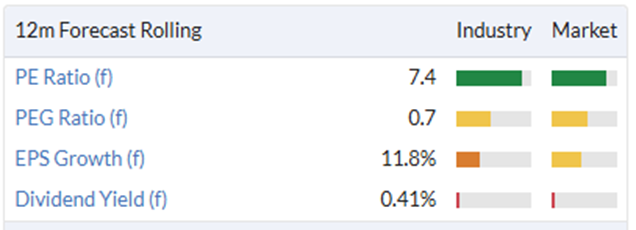
This leaves the stock pretty lowly rated, at least on a P/E ratio:
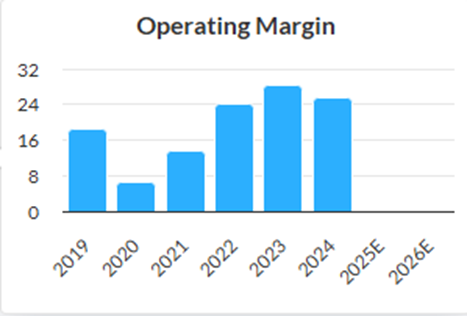
Especially for a company that has recently had 20%+ operating margins:
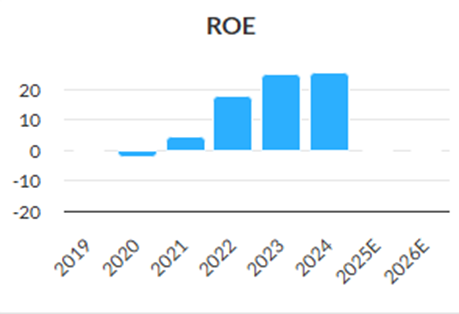
And 20%+ ROE:
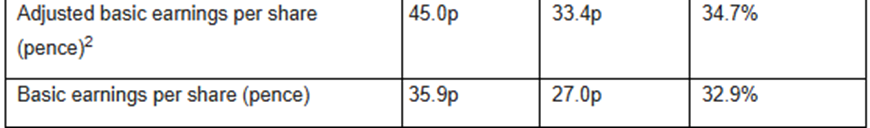
However, it is worth noting that there is a big gap between adjusted and basic earnings:
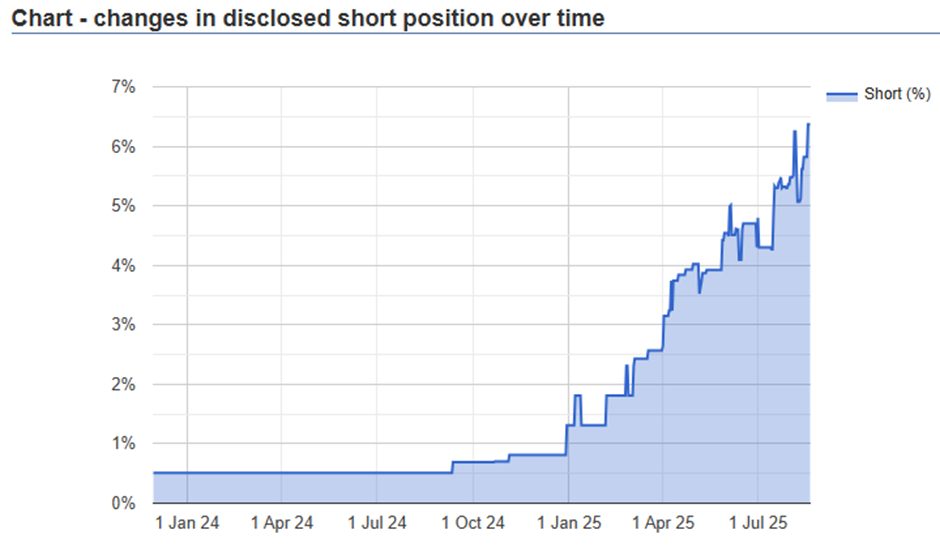
In addition, some savvy investors clearly think that another profits warning is on the way, as the short interest has been rising significantly this year, making it one of the most shorted UK stocks:
[Source:shorttracker.co.uk]
The hedge funds that make these sorts of bets tend to know what they are doing. However, they are not infallible. These interim results will likely reveal if they are right or not. If they are, then the shares are likely to take a further lurch downwards. If they aren't, then a short squeeze is possible.
Hunting (LON:HTG)
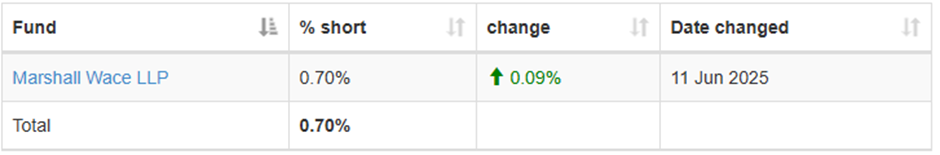
Hunting is another company with declarable short interest, although on a much smaller scale, and a single fund:
[Source:shorttracker.co.uk]
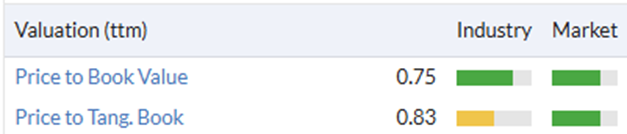
Marshall Wace say they "manage quantitative, systematic and fundamental strategies, specialising predominantly in long/short equity." So this may well not be them taking a fundamental view on the business. However, with the shares trading at a discount to TBV, they are not the most obvious quant short to me:
Investors are more likely to be focused on earnings in the upcoming results. However, this is another company where the headlines are largely known. In their H1 Trading Update, they said:
- Good year-on-year growth in EBITDA to c.$68-$70 million in H1 2025, up c.16% from H1 2024, led by a robust contribution from the OCTG product group.
- EBITDA margin of c.13% generated in the period.
This time, we can infer the revenue is around $530m for the period from simple maths. This means it will be up around 7% from H1 last year. This appears to be running ahead of the forecast run-rate for the full year:

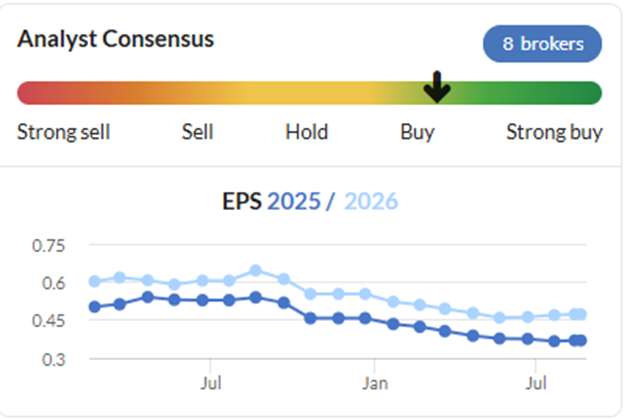
Although they say they were in line with expectations less than two months ago, it is probably too soon to expect an upgrade in EPS:
Based on these trading results, the Directors remain comfortable with full year EBITDA guidance of c.$135-$145 million, in line with market expectations. Year-end total cash and bank / (borrowings) position is expected to be c.$65-$75 million, before the proposed Share Buyback and any other possible M&A.
Indeed, the longer-term picture shows initial upgrades around 18 months ago, entering a downgrade cycle since the interim results last year:
The other big news with the trading update is a change in capital allocation policy. Firstly, there is an acceleration in dividend increases:
At the September 2023 Capital Markets Day ("CMD"), Hunting announced its long-term dividend policy, whereby total dividend distributions would increase at a minimum rate of 10% annually to 2030.
Reflecting the Company's strong cash generation since the CMD and pivot to longer cycle sales, the Directors have decided to raise the targeted annual increase in dividends to 13% following the capital allocation policy review.
Followed by a large buyback:
The Directors regularly review the Group's cash performance and ongoing capital requirements within the capital allocation framework. The Board concluded that it is currently appropriate to undertake a capital return of up to $40 million (excluding stamp duty and expenses) through a Share Buyback.
This seems reasonable as they would be currently buying back their own shares for less than Tangible Book Value. Despite being announced with the trading update, the buyback isn't due to start until after these results are announced:
Hunting proposes to commence the Share Buyback on Thursday 28 August 2025 when it publishes its 2025 half year results and exits its current close period. The Directors anticipate that the Share Buyback, if implemented in full, will take up to 12 months to complete.
Although the holding is hard to track because it is split across multiple vehicles, Wikipedia suggests that the Hunting Family still own around 27% of the equity here. On top of that, the EBT owns around 4% of the equity, and management owns about 1%. Larger institutions have about 29% between them:
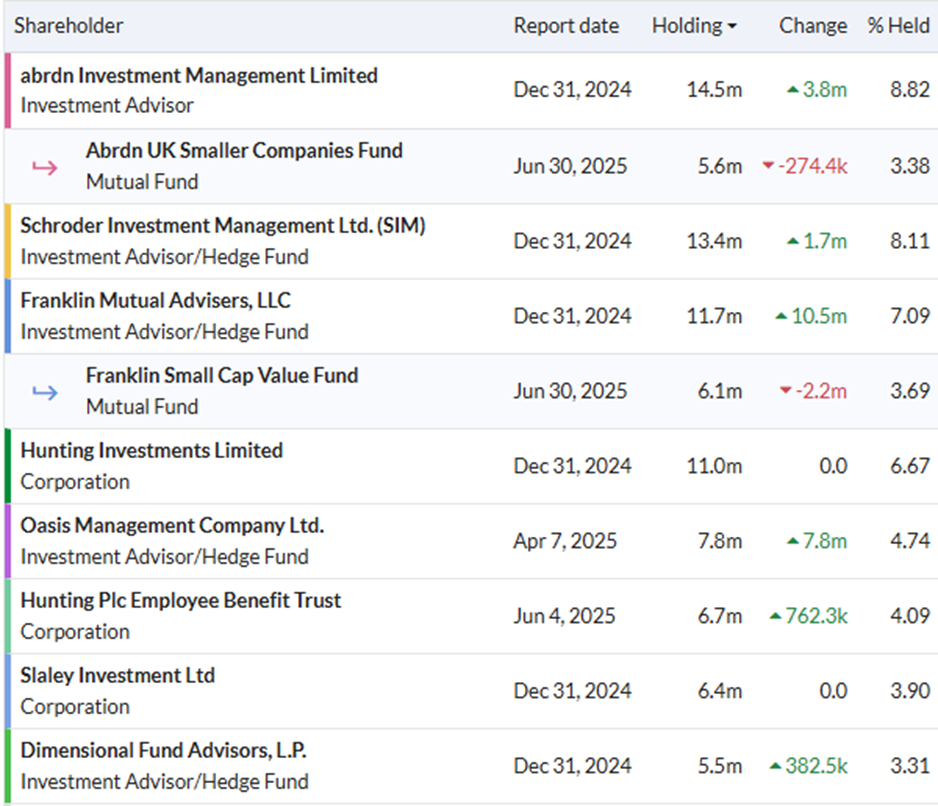
If we make (what seems a fair assumption) that none of these are keen sellers around the current price, we get to a free float of only around 40% of the equity. A $40m buyback in a year would therefore reduce the free float by around 15% at current prices. In reality, it may reduce it by less as the share price is slowly driven upwards.
[Disclosure: Mark owns shares in Hunting (LON:HTG) ]
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

4 comments
Thanks Mark
This kind of summary is really helpful and gives insight that may be helpful when Hunting (LON:HTG) reports
Thanks Mark for your excellent summary for next week.
Great summary mark there was a late cost saving statement by htg last night also.
Thanks David, I'm not sure how to take that announcement. Obviously, it is better to cut costs than have an unprofititable business. However, the fact they feel necessary to do this, means there is no chance of a swift recovery for this sector, to the long-term detriment to the business (and the UK.)