The Week Ahead (26 – 30 Jan): US Interest Rates, UK Housing, Mag7, Payment Networks, LLOY, STEM

Markets
It has been a hectic news week, with many companies releasing end-of-year or Christmas trading updates. Given the worrying economic backdrop, it is surprising the number of companies that are beating expectations. In many cases, I can’t help feeling that companies may have guided conservatively in order to beat. The lack of market reaction to many “ahead” statements backs up this assertion.
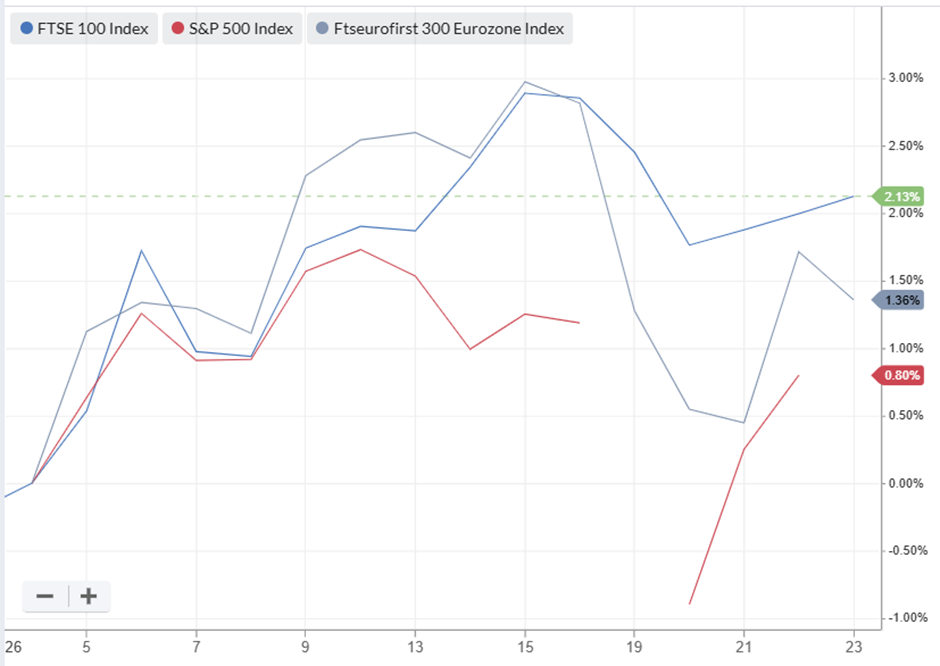
Given all the political noise, it has been surprising how well the major indices have held up so far this year:
However, that uncertainty has certainly helped gold to continue to shine:
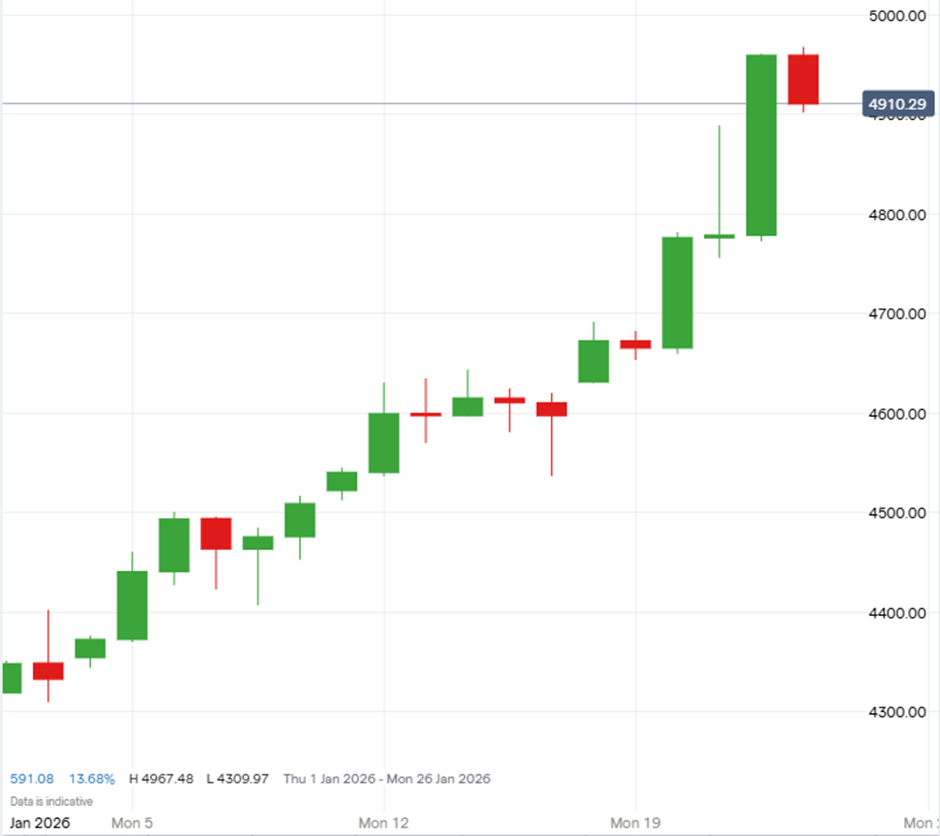
I’m no great chartist, but it feels like it will take quite some push for the gold price to clear $5k/oz. However, I certainly wouldn’t bet against the barbarous relic, at least in the short term.
Here's what we can look forward to next week:
Economic Calendar
Monday 26 Jan |
||
13:30 |
United States |
Durable Goods Orders |
Tuesday 27 Jan |
||
14:00 |
United States |
Case-Shiller Home Prices |
23:50 |
Japan |
BoJ MPC Meeting Minutes |
Wednesday 28 Jan |
||
07:00 |
Germany |
Consumer Confidence |
19:00 |
United States |
Fed Interest Rate Decision |
Thursday 29 Jan |
||
05:00 |
Japan |
Consumer Confidence |
13:30 |
United States |
Balance of Trade Initial Jobless Claims |
Friday 30 Jan |
||
07:00 |
UK |
Nationwide HPI |
09:00 |
Germany |
GDP Growth |
09:30 |
UK |
Mortgage Lending Mortgage Approvals BoE Consumer Credit |
US Interest Rates
The US Federal Funds Rate is forecast to be held at 3.75% on Wednesday. This should be a pause before continuing its downward trajectory later in the year:
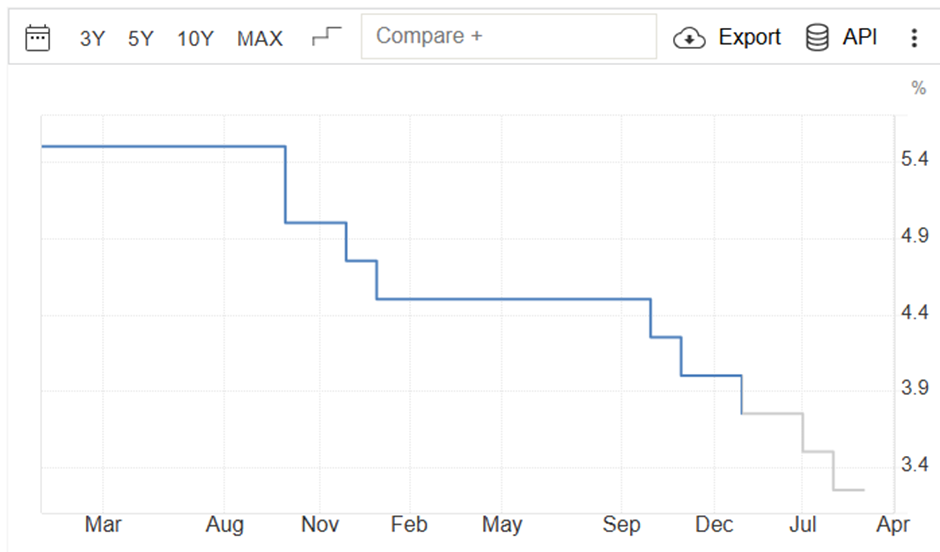
[All charts in this section: Trading Economics]
There is considerable political uncertainty surrounding the Fed, with Trump being highly critical of Jerome Powell. His administration even appears to have instigated a criminal investigation against Powell in order to try to force him to lower interest rates. This seems to have exasperated a normally calm and restrained public servant who isn’t budging on rates. Powell’s term is up in May, so Trump may well get his wish – a dovish, compliant Chair. However, at what cost? The independence of Central Banks has been one of the main concepts that gives their pronouncements authority. If markets view this as ending in the World’s largest economy, the impact could be huge. It is no wonder that gold is so popular at the moment.
UK Housing
Lots of UK Housing Market Data is released on Friday. We find out the current state of house prices from the Nationwide HPI. Annual rises dropped to 0.6% in December, barely above zero nominally, and a fall in real terms, making quite a gloomy picture:
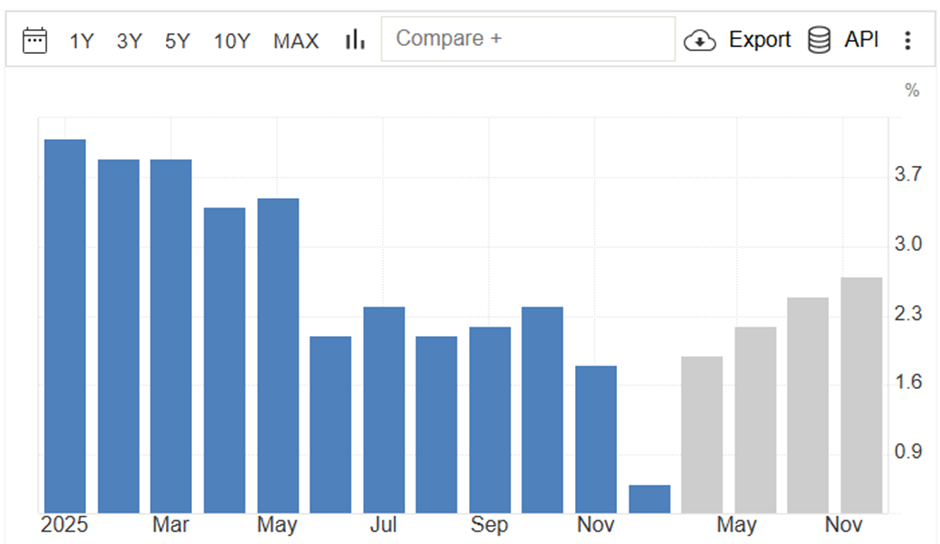
However, forecasts are for this to bounce back in January, rising to a 1.4% annual rise and further strengthening in the year on the back of recent interest rate drops.
We also get mortgage lending data from the BoE. Mortgage Approvals, in particular, are known as a leading indicator for house prices, as they gauge early demand. Similar to the house price index, these are forecast to be weak in the short term, but much stronger in the medium term:
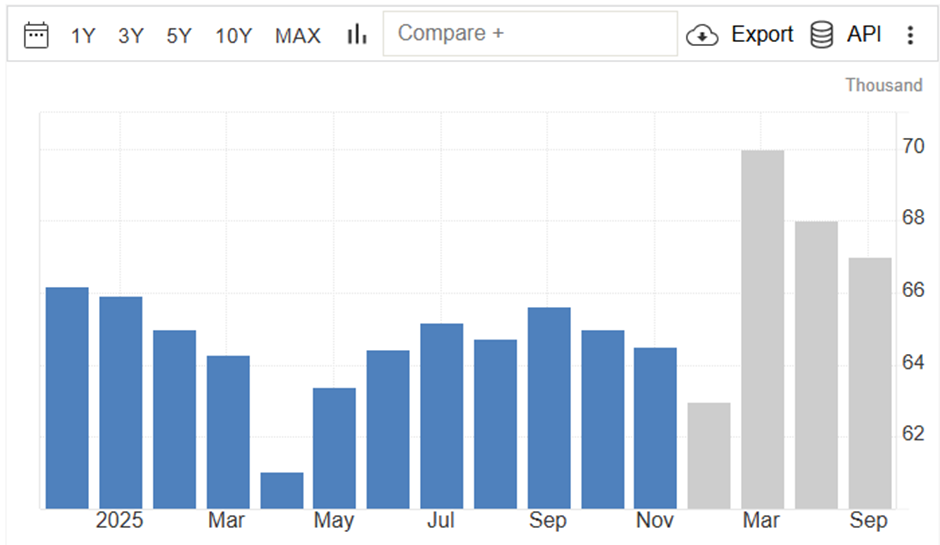
Housing and building products companies are often popular with individual investors, given their often cheap multiples. Many will be eying this week’s housing data for signs of a recovery in these data points, which may be reflected in the share prices of housing companies.
Companies Reporting
| Date | UK Trading Updates & AGMs | UK Financial Results | International Financial Results |
|---|---|---|---|
Monday 26 Jan |
Costain (LON:COST) (TS) Oxford Biodynamics (LON:OBD) (AGM) |
Van Elle Holdings (LON:VANL) | Ryanair Holdings (ISE:RYA) Nucor (NYQ:NUE) Crane Co (NYQ:CR) Epiroc AB (STO:EPI A) |
Tuesday 27 Jan |
Cranswick (LON:CWK) (TS) Dr Martens (LON:DOCS) (TS) Evoke (LON:EVOK) (TS) MITIE (LON:MTO) (TS) Ovoca Bio (LON:OVB) (AGM) Sage (LON:SGE) (TS) |
SThree (LON:STEM) (Finals) Time Finance (LON:TIME) (Interims) Velocity Composites (LON:VEL) (Finals) |
Atlas Copco AB (STO:ATCO A) Boeing Co (NYQ:BA) General Motors Co (NYQ:GM) HCA Healthcare (NYQ:HCA) Kimberly-Clark (NSQ:KMB) Invesco (NYQ:IVZ) LVMH Moet Hennessy Louis Vuitton SE (EPA:MC) NextEra Energy (NYQ:NEE) Northrop Grumman (NYQ:NOC) PACCAR (NSQ:PCAR) Roper Technologies (NSQ:ROP) Sandvik AB (STO:SAND) Shield Therapeutics (LON:STX) Sysco (NYQ:SYY) Texas Instruments (NSQ:TXN) Unitedhealth (NYQ:UNH) Union Pacific (NYQ:UNP) |
Wednesday 28 Jan |
Computacenter (LON:CCC) (TS) Imperial Brands (LON:IMB) (AGM) Kazera Global (LON:KZG) (AGM) Paragon Banking (LON:PAG) (TS) PayPoint (LON:PAY) (TS) Pets at Home (LON:PETS) (TS) |
Hargreaves Services (LON:HSP) (Interims) |
Automatic Data Processing (NSQ:ADP) Ameriprise Financial (NYQ:AMP) Amphenol (NYQ:APH) Danaher (NYQ:DHR) Argo Blockchain (LON:ARB) Fair Isaac (NYQ:FICO) General Dynamics (NYQ:GD) GE Vernova (NYQ:GEV) Corning (NYQ:GLW) Hartford Insurance (NYQ:HIG) H & M Hennes & Mauritz AB (STO:HM B) International Business Machines (NYQ:IBM) Las Vegas Sands (NYQ:LVS) Meta Platforms (NSQ:META) MSCI (NYQ:MSCI) Microsoft (NSQ:MSFT) Nasdaq (NSQ:NDAQ) ServiceNow (NYQ:NOW) Otis Worldwide (NYQ:OTIS) Progressive (NYQ:PGR) Starbucks (NSQ:SBUX) Swedbank AB (STO:SWED A) AT&T (NYQ:T) Tesla (NSQ:TSLA) Valero Energy (NYQ:VLO) Western Digital (NSQ:WDC) Waste Management (NYQ:WM) |
Thursday 29 Jan |
Alfa Financial Software Holdings (LON:ALFA) (TS) Antofagasta (LON:ANTO) (Q4 Prod) Botswana Diamonds (LON:BOD) (AGM) Glencore (LON:GLEN) (Q4 Prod) Greencore (LON:GNC) (AGM) Hollywood Bowl (LON:BOWL) (AGM) 3i (LON:III) (Q3 Ops) Jarvis Securities (LON:JIM) (AGM) Orcadian Energy (LON:ORCA) (AGM) Renew Holdings (LON:RNWH) (AGM) Smiths News (LON:SNWS) (AGM) Adalan Ventures (LON:ZAIM) (AGM) |
Crest Nicholson Holdings (LON:CRST) (Finals) easyJet (LON:EZJ) (Q1) Hilton Food (LON:HFG) (Finals) ITM Power (LON:ITM) (Interims) Lloyds Banking (LON:LLOY) (Finals) Rank (LON:RNK) (Interims) Wizz Air Holdings (LON:WIZZ) (Q3) |
Apple (NSQ:AAPL) Abb (SWX:ABBN) Blackstone (NYQ:BX) Caterpillar (NYQ:CAT) Comcast (NSQ:CMCSA) Deutsche Bank AG (ETR:DBK) Honeywell International Inc (LON:HON) ING Groep NV (AMS:INGA) KLA (NSQ:KLAC) Lockheed Martin (NYQ:LMT) MasterCard (NYQ:MA) Altria (NYQ:MO) Parker-Hannifin (NYQ:PH) Ferrari NV (NYQ:RACE) Royal Caribbean Cruises (NYQ:RCL) Banco Santander SA (NYQ:SAN) SAP SE (NYQ:SAP) Southern Copper (NYQ:SCCO) Sherwin-Williams Co (NYQ:SHW) Stryker (NYQ:SYK) AT&T (NYQ:T)MO Visa (NYQ:V) |
Friday 30 Jan |
Avon Technologies (LON:AVON) (AGM) essensys (LON:ESYS) (AGM) |
Airtel Africa (LON:AAF) (Q3/Q1) |
Air Products and Chemicals (NYQ:APD) Aon (NYQ:AON) AXP Energy (ASX:AXP) CaixaBank SA (MCE:CABK) Colgate-Palmolive Co (NYQ:CL) Chevron (NYQ:CVX) Regeneron Pharmaceuticals (NSQ:REGN) Visa (NYQ:V)Z Exxon Mobil (NYQ:XOM) |
There’s a vast number of US companies reporting their quarterly results to the end of 2025, so we can expect it to be a busy week for international investors. It looks quieter in the UK, but there may well be plenty of companies still to issue an end-of-year trading statement that haven’t committed to a specific date.
As usual, if any investors think I've missed some upcoming news or included a red herring, then feel free to correct this in the comments.
Mag 7
Four of the largest companies in the world report next week, and given the concentration in the US, the results have the ability to cause increased volatility in global indices. For Microsoft and Meta, the focus will be on how effectively they are monetising their AI investments. Apple investors will be particularly keen to gauge how the iPhone 17 sales have performed over the key Christmas period. While at Tesla, investors will be keen to learn how much the 16% decline in vehicle deliveries in 2025 has impacted the bottom line.
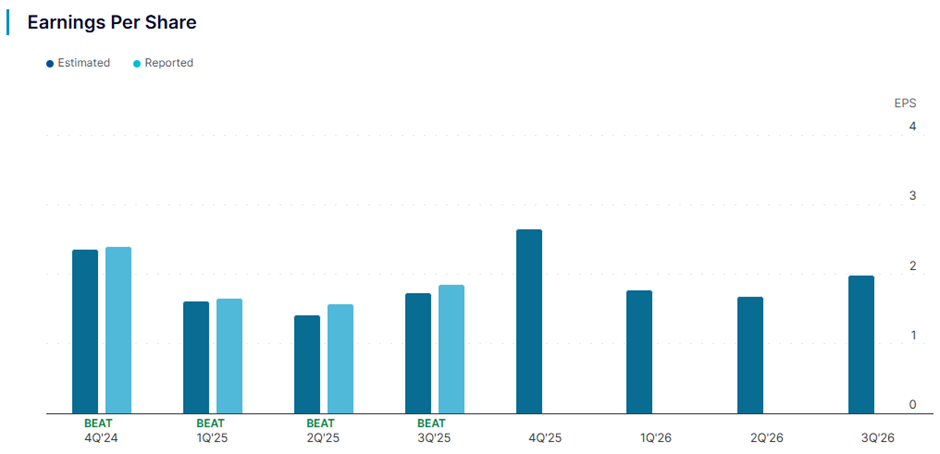
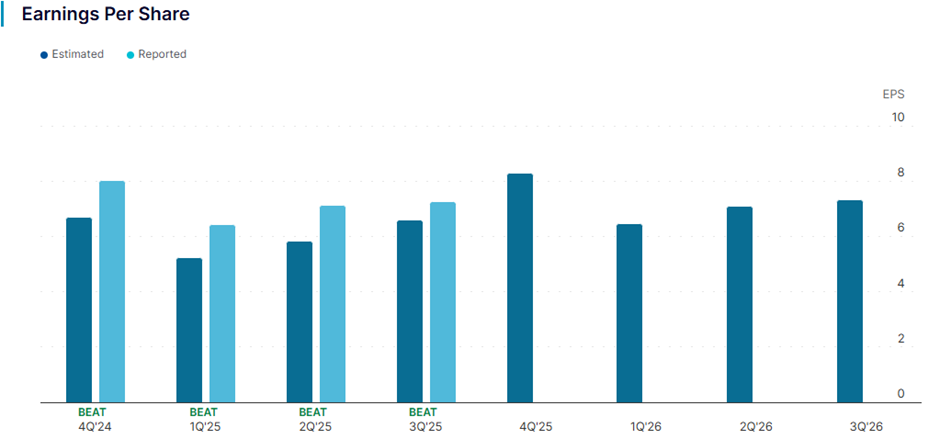
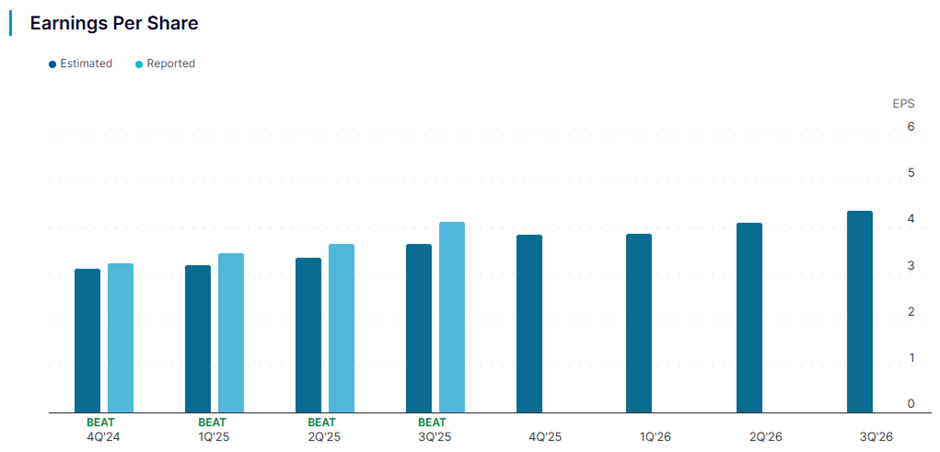
Apple, Meta and Microsoft have all been beating expectations recently, suggesting they know how to guide analysts conservatively:
Apple (NSQ:AAPL)
Meta Platforms (NSQ:META)
Microsoft (NSQ:MSFT)
Tesla (NSQ:TSLA)
In contrast, Tesla has developed a habit of missing expectations over the last three quarters:
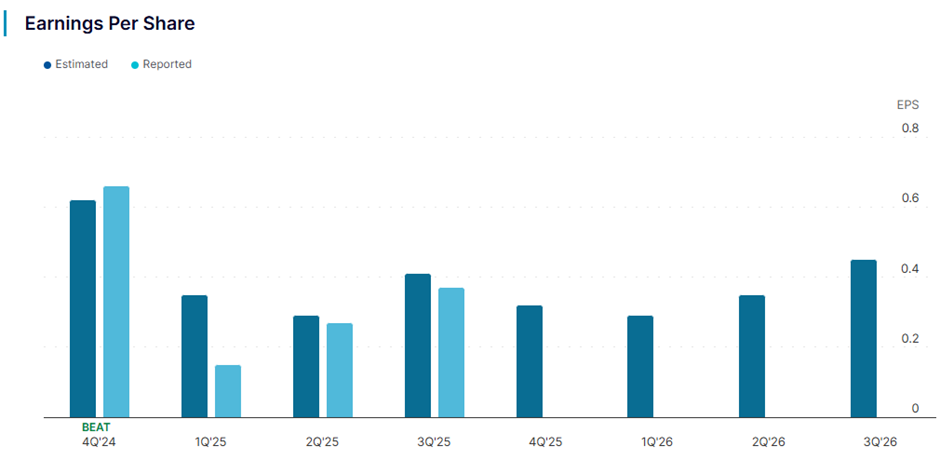
Not that it appears to matter to the share price, which is up 30% in six months:
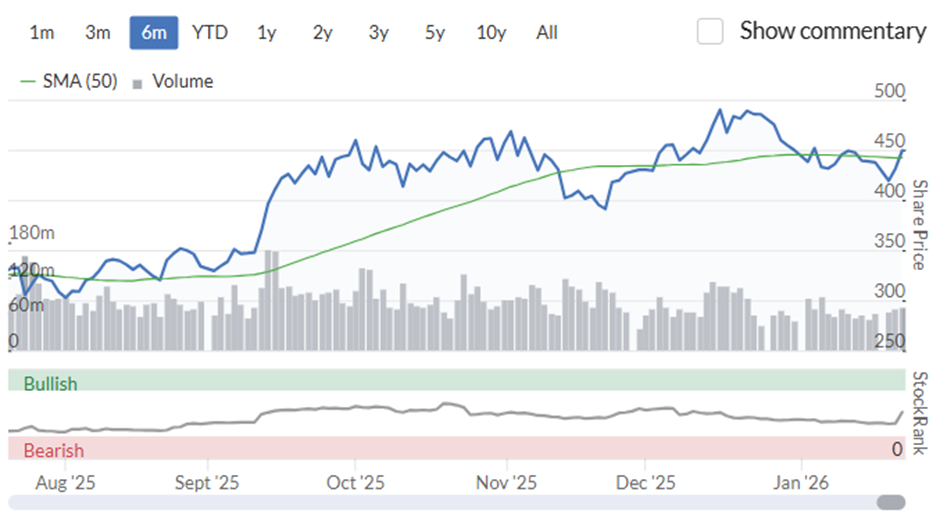
Financials don’t seem to matter here, where investment flows, and the latest pronouncement from their “charismatic” CEO appear to matter more than any real numbers.
Valuation
Of course, none of these are cheap stocks. Although the forward P/E ratios are not crazy, apart from at Tesla:
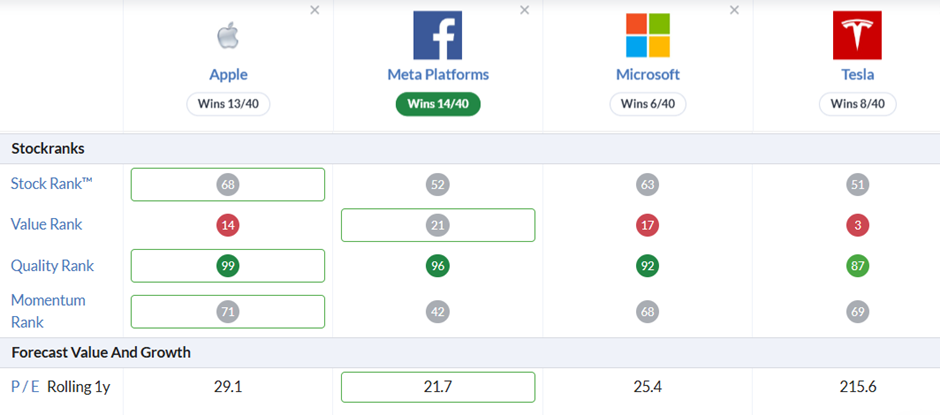
None of them has a PEG less than one, meaning that all of these need beat expectations over the medium term to justify their current valuations:
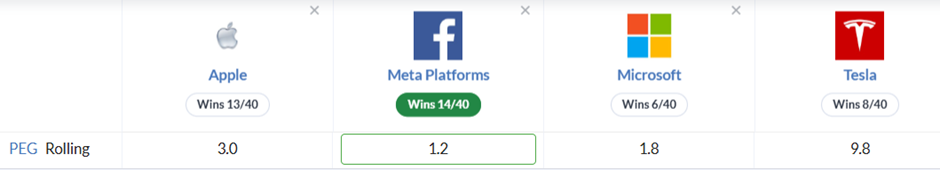
Recent history suggests this will be easier to do for the first three of these.
Card Payment Networks
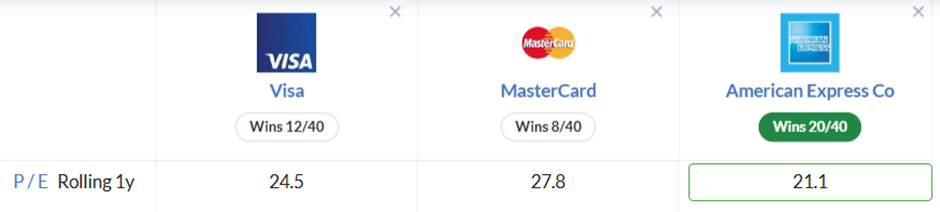
All three global card payment networks are reporting next week, and again, these are not cheap stocks:
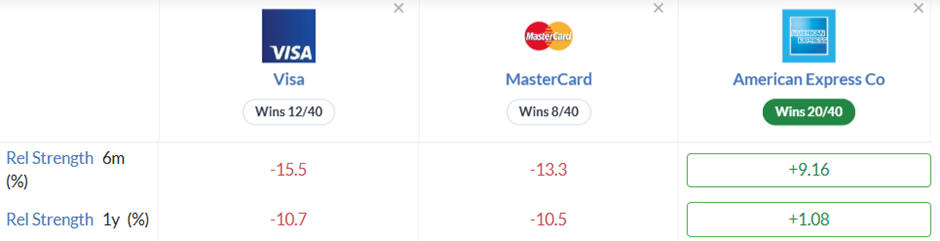
This is perhaps why they have struggled over the last year, with only American Express outperforming the wider market:
As well as a rich valuation, these have faced regulatory headwinds in the last year. Trump announced a 10% cap on credit card fees. This may or may not happen in reality, and the companies themselves don’t directly lend money, but this could impact how many cards are issued and borrowing limits.
In November, Visa and Mastercard reached a settlement to end a 20-year antitrust battle with U.S. merchants. This included fee caps for five years, and allows merchants to charge higher customer fees for cards that have higher charges.
On top of this, there is increased competition from fintech companies and innovative financial networks. With all this going on, investors may be as interested in the companies’ response to these challenges, rather than just the pure numbers.
UK Stocks
Lloyds Banking (LON:LLOY)
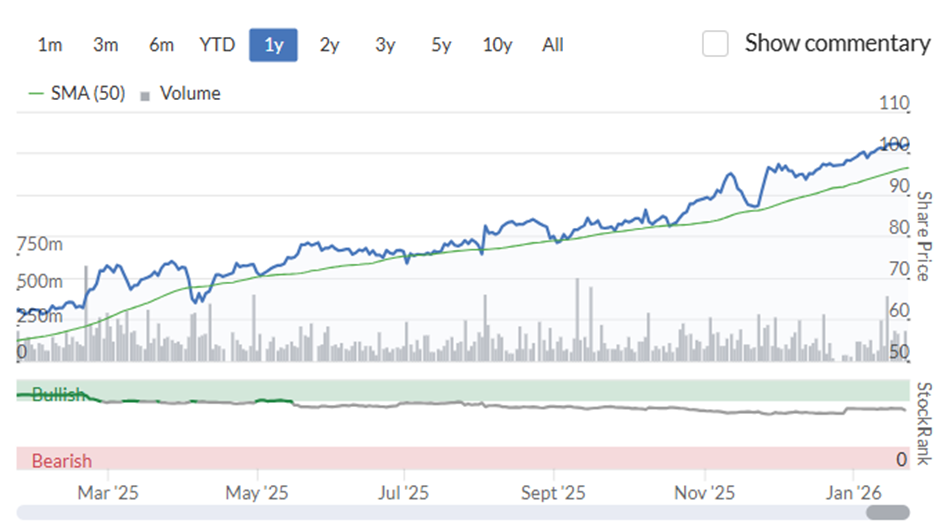
Lloyds has had a tremendous run over the last year, and is hitting the psychologically important £1 price level:
This gives the company a strong momentum rank:
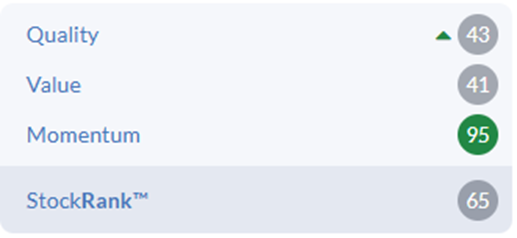
However, it is no longer good value compared to the sector, meaning it needs to show signs of outperformance on its Returns on Tangible Equity to justify a 1.55x TBV rating.
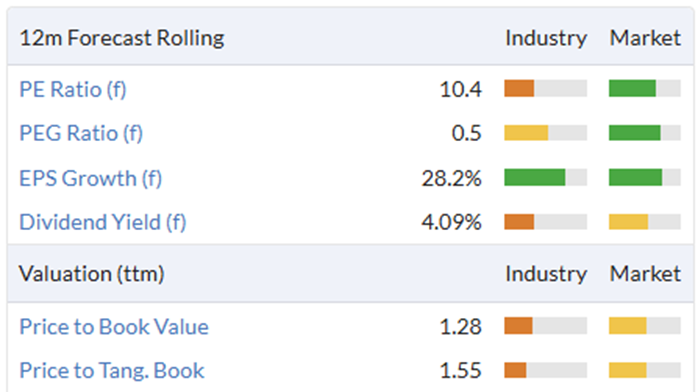
Things to watch:
- Return on Tangible Equity (RoTE): Management has guided for a target of 13.5%, but some analysts believe that by investing deposits into higher-yielding assets, this could head toward 15% in the near term.
- What adjustments they make to their provisions for motor finance redress. A big number here would overshadow otherwise strong results.
- News on any renewal or increase to share buybacks
- Net interest margin – analysts expect them to be able to roll maturing low-interest hedges into higher market rates, increasing NIM.
SThree (LON:STEM)
Like many recruiters, SThree has had a poor year:
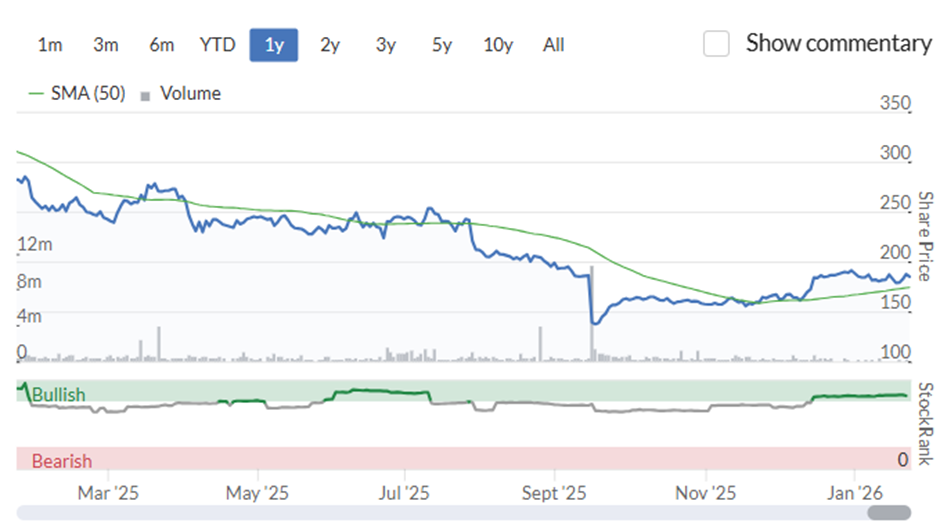
While their Q3 Trading Statement in September confirmed that they were trading in line with expectations of £25m PBT for FY25, it also slashed FY26 expectations, with them saying:
Persistent softness in new business activity is expected to impact FY26 PBT consensus(5) by c.£20 million due to the Group's operational gearing. This alongside our investment initiatives, which are fully funded through careful cost management in FY25, is expected to result in a FY26 PBT of c.£10 million.
Since then, the share price has staged a modest recovery. However, brokers’ forecasts for FY26 have continued to decline:
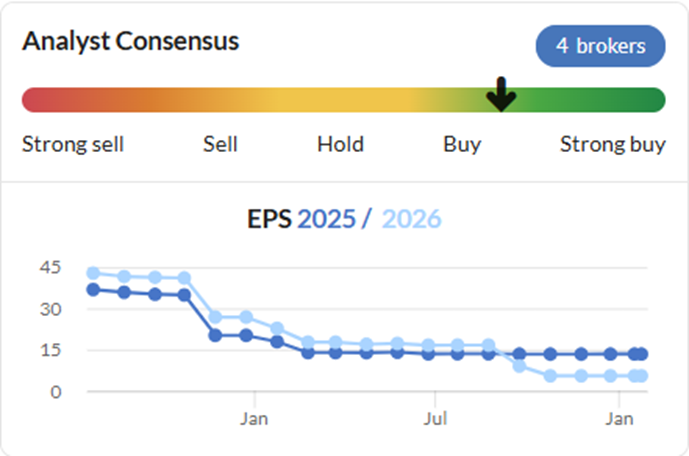
This divergence makes the outlook more important than the actual results. The shares are not obviously good value on forward earnings, so any further deterioration in outlook may be poorly received by investors:
Things to watch:
- Europe and the UK have been the laggards, whereas the US has returned to growth. The breakdown between regions may matter as much as the overall figures.
- Any commentary on the order book. It currently stands at £157 million (roughly 5 months of visibility). This may give an early indication of the direction of travel for this year.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

7 comments
Morning Mark, I would expect a trading update from Halfords (LON:HFD) some time this week based on previous announcements.
Thanks for the update Mark, always appreciated.
The free weekly Pension Craft email had a couple of good charts this week, very high level but relevant I think....
Would be interesting to see metrics around investment flows from the US to the UK (if this exists)....
Calm analysis in a 'mad' world. It's hard to keep dispassionate - hat off to you sir.
I would be sad to see Mr T moved on and usher in the grey dead world of socialism or its badder uncle but the grand decline in the dollar and fiat is a train in motion.
Amazon reducing head count for jobs that can be done by a bot or AI.
Lets see how many hundreds of government and local authorities can remove such dead weight and improve services (apparently their aim). Where will they go? Home? well do that already lol.
I think Oil and Gas is on the rise from being the 'bad boy'. So Friday Chevron (NYQ:CVX) and Exxon Mobil (NYQ:XOM) will be of interest.
Forget Venezuela - there is a reason its not commercially viable even with decayed production facilities and confiscated assets from the oil majors due to socialist ideology - they wont return without recompense and guarantees. It's liquid tarmac anyway so a long way from putting into the car.
Greenland or is it Iceland - anyway somewhere hard to get it out of the ground, wherever it is.
No idea why in the focus? if ask Greenlanders want a US Green Card (duh!) then suspect a done deal. It's not sovereign Norway anyway I thought so the EU shut up.
All noise and fun. Buy Silver and Gold - if have the cash and somewhere to store it. Harder done that said
Re silver and gold. My preference on bullion is via a dealer who can offer the storage as well. Major benefit of that being you won’t pay the VAT so long as you never take delivery. And presently, the storage costs are almost irrelevant given the increased value of the metals. My coins i hold myself.
Mark, l thought Computacenter (LON:CCC) reported yesterday?
Yes, you are right. My mistake.
Thanks Mark, another busy week coming up.
Meta Platforms (NSQ:META) appears at the top of the securities mentioned panel on the page, and I couldn't help noticing the stocko ranks - it has moved to a Falling Star, with Momentum/StockRank dropping by 15-25 in the last 30 days. Clear sell signal...