The Week Ahead (26 – 30 Oct): Interest Rates, UK Budget, US Hyperscalers, UK Oil Majors

Another poor week for the major global indices. Most of this week's damage came on Thursday. The S&P 500 fell 1.2%, and the Nasdaq dropped 2.6% as chip stocks slid. AI spending worries hit chip names in Asia and the US.
Oil rose to a five-month high on Thursday:
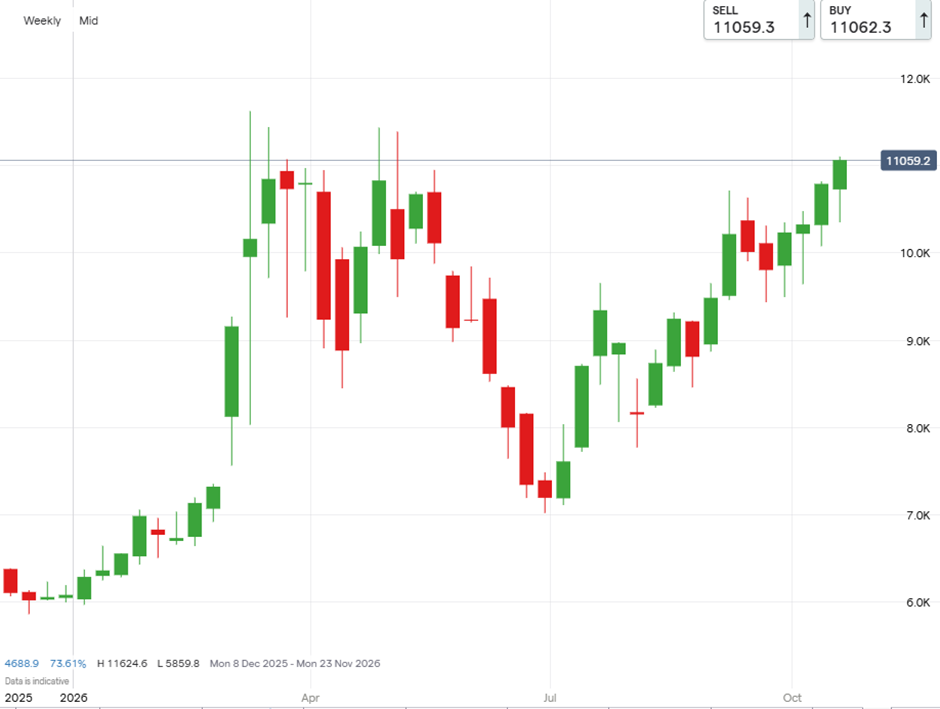
Traders were adding a geopolitical risk premium after Houthi attacks, on top of the ongoing Strait of Hormuz disruption. The 10-year Treasury yield has been hovering around 5%, and uncertainty over the Fed's rate path has made expensive growth stocks more vulnerable.
However, this appears to be more of a rotation rather than a broad sell-off. Money moved out of tech and into defensive sectors, with US consumer staples posting their best day since July on Thursday.
Here's what we can look forward to next week:
Economic Calendar
Monday 26 October |
||
09:30 |
Germany |
Ifo Business Climate |
Tuesday 27 October |
||
12:30 |
United States |
Durable Goods Orders Ex Transp |
13:00 |
United States |
S&P/Case-Shiller Home Price YoY |
14:00 |
United States |
New Home Sales CB Consumer Confidence |
20:30 |
United States |
API Crude Oil Stock Change |
Wednesday 28 October |
||
07:00 |
Germany |
GfK Consumer Confidence |
11:00 |
United States |
MBA 30-Year Mortgage Rate |
12:30 |
United Kingdom |
Autumn Budget 2026 |
12:30 |
United States |
Wholesale Inventories Goods Trade Balance Retail Inventories Ex Autos |
13:45 |
Canada |
BoC Interest Rate Decision |
14:30 |
United States |
EIA Crude Oil Stocks Change |
18:00 |
United States |
Fed Interest Rate Decision |
Thursday 29 October |
||
05:00 |
Japan |
Consumer Confidence |
09:30 |
United Kingdom |
BoE Mortgage Lending BoE Consumer Credit BoE Mortgage Approvals |
12:30 |
United States |
Personal Spending Initial Jobless Claims Core PCE Price Index GDP Growth Rate Personal Income PCE Price Index |
13:15 |
Euro Area |
ECB Interest Rate Decision |
23:30 |
Japan |
Unemployment Rate |
Friday 30 October |
||
03:00 |
Japan |
BoJ Interest Rate Decision |
07:00 |
United Kingdom |
Nationwide Housing Price Index |
10:00 |
Euro Area |
GDP Growth Rate Flash |
13:00 |
Germany |
Inflation Rate |
Interest Rates
Central Bank policy rate decisions are the biggest macro news next week, with the Fed, ECB, and BoJ all announcing their decisions.
All three Central Banks are expected to hold rates constant. However, each is in a tightening cycle that markets expect to continue in December, so guidance matters more than the decision, unless there is a major upset.
In the US, September CPI rose to 3.7% year on year, but most of that was energy. Core CPI is 2.6%. Payrolls rose only 29,000, and unemployment is 4.2%, while Q3 GDP is tracking strong at about 3.5% annualised. The risk is that the energy-driven inflation feeds through to wage inflation and then core CPI. So far, Kevin Warsh has said little about when the next hike will come. If he clearly signals December, Treasury yields and the dollar would likely firm. If he stays vague, yields could ease, and the yield curve steepen.
Going into this ECB Rate Decision in late September, markets priced in a hike, giving it a 60% chance. However, over the last couple of weeks, the consensus has shifted towards a hold. Euro inflation jumped to the same 3.7% figure as the US in September, similarly driven by energy. However, the energy rise isn't feeding much into underlying prices, and firms' selling-price expectations are falling. Lagarde was hawkish in September, but other Governing Council members have since been softer, citing weaker demand.
The BoJ raised rates to a 31-year high in September. However, economists don't expect the next hike until December, with the Japanese interest rate cycle expected to peak at a modest 1.75% compared to 1.25% today. The key question is whether the BoJ says underlying inflation has reached 2%. It has never said that since adopting that explicit target in 2013. September core-core CPI jumped to 2.4%, so a "hawkish hold" is the likely outcome. That would support the yen and push JGB yields higher. Two members appointed under Takaichi dissented against September's hike. More dovish dissent would weaken the yen. A vote for a hike from Takata would strengthen it.
UK Budget
Closer to home, many investors will be watching the UK Budget, due Wednesday. It is the first with a new chancellor under the Burnham premiership. While it hasn't had the same sense of chaos that surrounded last year's Budget, the pattern has been similar. Lots of policies are floated in the press and then denied when they prove to be unpopular. In this environment, then it is unsurprising that investors often make decisions "just in case". I think at least some of the weakness in UK small caps has been down to this effect, although some of the most impactful measures, such as CGT normalised with income, have been ruled out.
The word "Headroom" will take centre stage: the buffer between the government's plans and its fiscal rules, and the number the market watches most. A Reuters poll of economists found it has roughly halved since March, to around £10–12bn from £23.6bn. The implication is that Healey should rebuild it to about £15–16bn to keep bond investors onside. However, estimates of that headroom vary widely, and messaging may matter as much as the numbers in keeping bond investors on side.
On the wider macro issues surrounding Gilt yields and interest rates, investors expect a cautious, uneventful Budget. Such an outcome should be mildly positive for domestic, rate-sensitive stocks such as housebuilders, REITs and the FTSE 250.
These are the current sector-specific expectations:
Banking: This has been the clearest target for tax rises. The bank surcharge is reportedly set to rise from 3% to 8%. Reversing Jeremy Hunt's cut from when he was chancellor would raise more than £2bn a year. Estimates suggest Barclays would see net profit cut by 2-3%, with a larger 7-8% impact for Lloyds and NatWest. Some campaigners want a full windfall tax instead. If the Budget delivers just the 8% surcharge, the news is largely priced in at this point. However, a windfall tax or an interest rate levy would hit Lloyds and NatWest afresh.
Gambling: Healey is expected to announce a new tax on gambling machines, expected to raise about £500m. The industry is lobbying against the proposed doubling of the machine games duty to 40%, arguing that recent duty rises have targeted the sector enough. However, it is hard to argue that this industry is a social good that shouldn't face increasing taxation. Rank Group is the most exposed listed name to this type of rise.
Housebuilding: Housebuilder shares surged in late September after the government confirmed a new first-time buyer support scheme for this Budget. However, major reforms to stamp duty and council tax have reportedly been delayed. The "mansion tax" threshold may instead be reduced.
Energy: Healey has promised targeted, temporary support with energy bills. He is expected to reject removing all levies from bills because of the cost. That is good news for gilts and energy suppliers.
Defence: The FT reports that the 3% of GDP defence target will be deferred to next year's spending review. The Budget is instead expected to fill an equipment funding gap of almost £5bn. Where that spending falls may affect UK-listed defence firms.
Personal taxation: CGT changes seem to have been ruled out. One plan reportedly under consideration would charge income tax, not CGT, when owners pass companies to their children. This could impact AIM-listed family firms. LSE chief Julia Hoggett has suggested scrapping stamp duty for pensions and ISAs. However, the optics probably rule this out, even though the argument is strong.
Companies Reporting
|
Date |
UK Trading Updates & AGMs |
UK Financial Results |
International Financial Results (S&P 500) |
|
Monday 26 October |
City of London Investment (LON:CLIG) (AGM) Marechale Capital (LON:MAC) (AGM) |
AMC Entertainment Holdings (NYQ:AMC) (Interims) Greatland Resources (LON:GGP) (Q3) Quadrise (LON:QED) (Finals) |
Cadence Design Systems (NSQ:CDNS) (Q3) Hartford Insurance group (NYQ:HIG) (Q3) Nucor (NYQ:NUE) (Q3) Public Storage (NYQ:PSA) (Q3) Verizon Communications (NYQ:VZ) (Q3) Welltower (NYQ:WELL) (Q3) |
|
Tuesday 27 October |
CRISM' Therapeutics (LON:CRTX) (AGM) Luceco (LON:LUCE) (TS) Reckitt Benckiser (LON:RKT) (TS) RWS Holdings (LON:RWS) (TS) |
HSBC Holdings (LON:HSBA) (Q3) Inspiration Healthcare (LON:IHC) (Interims) Revolution Beauty (LON:REVB) (Interims) Shearwater (LON:SWG) (Finals) Ultimate Products (LON:ULTP) (Finals) |
American Tower (NYQ:AMT) (Q3) Boeing (NYQ:BA) (Q3) Baker Hughes (NSQ:BKR) (Q3) Ecolab (NYQ:ECL) (Q3) Freeport-McMoRan (NYQ:FCX) (Q3) Corning Incorporated (NYQ:GLW) (Q3) HCA Healthcare (NYQ:HCA) (Q3) Hilton Worldwide Holdings (NYQ:HLT) (Q3) Robinhood Markets (NSQ:HOOD) (Q3) Illinois Tool Works (NYQ:ITW) (Q3) Johnson Controls International (NYQ:JCI) (Q4) Coca-Cola (NYQ:KO) (Q3) Novartis AG (SWX:NOVN) (Q3) (Switzerland) Nxp Semiconductors NV (NSQ:NXPI) (Q3) PayPal Holdings (NSQ:PYPL) (Q3) Royal Caribbean Cruises (NYQ:RCL) (Q3) Sherwin-Williams (NYQ:SHW) (Q3) S&P Global (NYQ:SPGI) (Q3) Seagate Technology Holdings (NSQ:STX) (Q1) United Parcel Service (NYQ:UPS) (Q3) Visa (NYQ:V) (FQ4) Waste Management (NYQ:WM) (Q3) |
|
Wednesday 28 October |
Elementis (LON:ELM) (TS) Hargreaves Services (LON:HSP) (AGM) Hunting (LON:HTG) (TS) OCI (AMS:OCI) (TS) S4 Capital (LON:SFOR) (TS) Springfield Properties (LON:SPR) (AGM) Unilever (LON:ULVR) (TS) |
Aston Martin Lagonda Global Holdings (LON:AML) (Q3) Banco Santander (LON:BNC) (Q3) C&C (LON:CCR) (Interims) Georgia Capital (LON:CGEO) (Q2) GSK (LON:GSK) (Q3) International Paper (LON:IPC) (Q3) Standard Chartered (LON:STAN) (Q3) |
Automatic Data Processing (NSQ:ADP) (Q1) American Electric Power (NSQ:AEP) (Q3) Airbus SE (EPA:AIR) (Q3) (France) Aon (NYQ:AON) (Q3) Amphenol (NYQ:APH) (Q3) Boston Scientific (NYQ:BSX) (Q3) Chipotle Mexican Grill (NYQ:CMG) (Q3) Carvana (NYQ:CVNA) (Q3) Deutsche Bank AG (ETR:DBK) (Q3) (Germany) eBay (NSQ:EBAY) (Q3) Equinix (NSQ:EQIX) (Q3) Ford Motor (NYQ:F) (Q3) FedEx (NYQ:FDX) DX GE Vernova (NYQ:GEV) (Q3) Alphabet (NSQ:GOOGL) (Q3) KLA (NSQ:KLAC) (Q1) Microsoft (NSQ:MSFT) (FQ1) ServiceNow (NYQ:NOW) (Q3) O'Reilly Automotive (NSQ:ORLY) (Q3) Phillips 66 (NYQ:PSX) (Q3) TE Connectivity (NYQ:TEL) (FQ4) T-Mobile Us (NSQ:TMUS) (Q3) UBS AG (SWX:UBSG) (Q3) (Switzerland) Vertiv Holdings (NYQ:VRT) (Q3) |
|
Thursday 29 October |
ASA International (LON:ASAI) (TS) City Of London Investment Trust (LON:CTY) (AGM) Frontier Developments (LON:FDEV) (AGM) Glencore (LON:GLEN) (TS) HALEON (LON:HLN) (TS) ICFG (LON:ICFG) (AGM) IMI (LON:IMI) (TS) Murray Income Trust (LON:MUT) (AGM) PPHE Hotel (LON:PPH) (TS) Resolute Mining (LON:RSG) (TS) St James's Place (LON:STJ) (TS) WPP (LON:WPP) (TS) |
Lloyds Banking (LON:LLOY) (Q3) Shell (LON:SHEL) (Q3) |
Arthur J. Gallagher & Co. (NYQ:AJG) (Q3) Amazon.com (NSQ:AMZN) (Q3) Bristol-Myers Squibb (NYQ:BMY) (Q3) Caterpillar (NYQ:CAT) (Q3) CRH (NYQ:CRH) (Q3) Digital Realty Trust (NYQ:DLR) (Q3) Gilead Sciences (NSQ:GILD) (Q3) ING Groep (AMS:INGA) (Q3) (Netherlands) Intel (NSQ:INTC) (Q3) Linde (NSQ:LIN) (Q3) Eli Lilly and (NYQ:LLY) (Q3) Mastercard Incorporated (NYQ:MA) (Q3) Mondelez International (NSQ:MDLZ) (Q3) Monster Beverage (NSQ:MNST) (Q3) Altria (NYQ:MO) (Q3) Monolithic Power Systems (NSQ:MPWR) (Q3) Merck & Co (NYQ:MRK) (Q3) Quanta Services (NYQ:PWR) (Q3) Republic Services (NYQ:RSG) (Q3) Starbucks (NSQ:SBUX) (Q4) SanDisk (NSQ:SNDK) (FQ1) Trane Technologies (NYQ:TT) (Q3) TotalEnergies SE (LON:TTE) (Q3) (France) |
|
Friday 30 October |
EnSilica (LON:ENSI) (AGM) Fermi (LON:FRMI) (AGM) Filtronic (LON:FTC) (AGM) Investment (THE) (LON:INV) (AGM) ITM Power (LON:ITM) (AGM) |
AstraZeneca (LON:AZN) (Q3) BP (LON:BP.). (Q3) Natwest (LON:NWG) (Q3) |
AbbVie (NYQ:ABBV) (Q3) Colgate-Palmolive (NYQ:CL) (Q3) Chevron (NYQ:CVX) (Q3) Dominion Energy (NYQ:D) (Q3) General Dynamics (NYQ:GD) (Q3) Intesa Sanpaolo (BIT:ISP) (Q3) (Italy) Regeneron Pharmaceuticals (NSQ:REGN) (Q3) Sanofi SA (EPA:SAN) (Q3) (France) Exxonmobil Holdings (NYQ:XOM) (Q3) |
US "Hyperscalers"
Microsoft and Alphabet report after the US close on Wednesday, and Amazon follows on Thursday. The question for all three is the same: is cloud revenue growth running fast enough to justify the capex bill?
Demand for AI compute still outpaces supply, but the market has started punishing spending that isn't matched by visible revenue. Meta is the only one of the big four hyperscalers to have reported this season. Ad demand was strong, but even Meta is now cash-flow negative. However, the shares rose because the capex raise was backed by a revenue beat. Chip stocks also sold off after key earnings this week, showing how fragile AI sentiment is heading into these reports.
Microsoft (NSQ:MSFT)
Microsoft goes in with the cleanest story of the three: Azure re-accelerated last quarter, and the stock was rewarded for it:
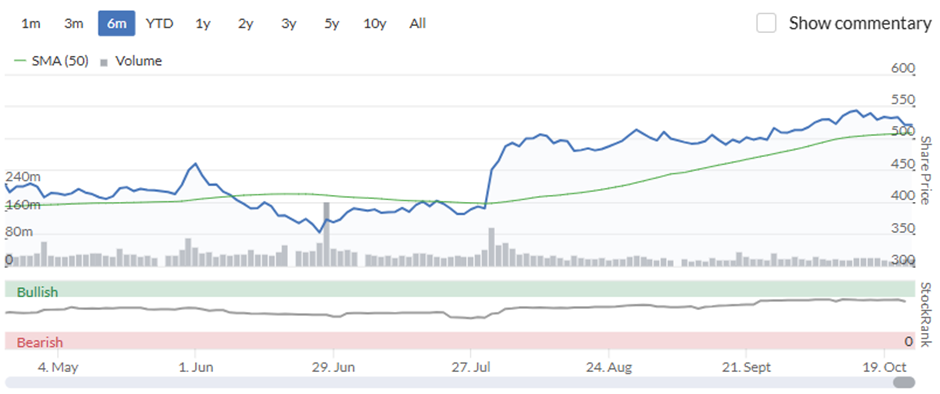
The risk is that a capex plan already guided up by more than a third still doesn't show up in revenue growth. Analysts already expect free cash flow to turn negative in the short term.
Here is what to look out for:
Azure growth: Meeting the 45% growth guidance keeps Azure the fastest-growing of the big three clouds at scale; a print in the low 40s would read as capacity or demand slipping. The key will be whether capacity, not demand, still limits growth.
Capex: The current $255–260bn yearly guidance averages about $64bn a quarter, against roughly $41bn last quarter, so this quarter's spend should jump sharply. Any further increase in guidance could cause the stock ot sell off.
Funding sources: So far, Microsoft has been the one big-tech name the market treats as self-funding; losing that status would matter to the optics. Look for new debt issuance or a slowdown in buybacks as warning signs.
Alphabet (NSQ:GOOG)
Alphabet has the strongest cloud momentum of the three but the weakest cash position. In July, it beat on revenue, posted 82% Cloud growth, and still fell because it raised capex and turned free cash flow negative:
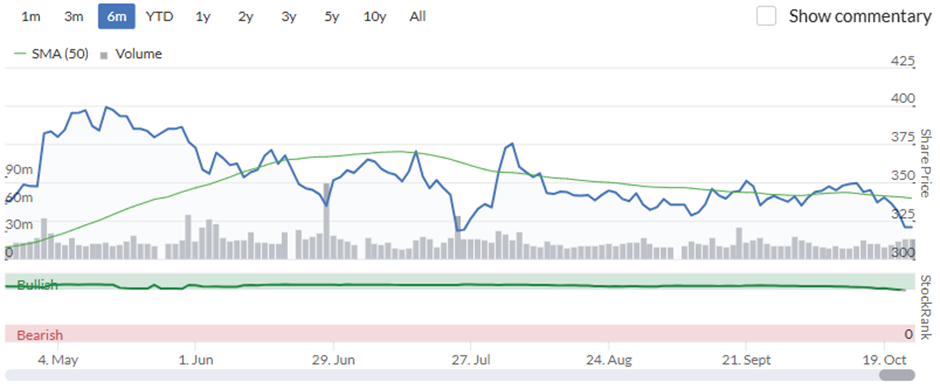
Here is what to look out for:
Growth & margins: At a historical 82% growth rate, some slowing may be forgiven. However, margins may drop as Alphabet rents third-party capacity as a bridge while its own data centres come online. This
Capex: Another raise to the $205bn guidance is likely given the industry trend. After July's reaction, the market will want it paired with backlog conversion, not presented alone.
Search: Search grew 17% last quarter while AI Mode passed 1 billion monthly users and the Gemini app reached 950 million. Steady Search growth with rising AI usage is the best rebuttal to disruption worries; any slowdown in paid clicks would be the warning sign.
Amazon.com (NSQ:AMZN)
Results here may be hard to untangle with an accelerating AWS, a retail business distorted by Prime Day timing, and the largest capex Budget of the three.
Here is what to look out for:
Growth & margins: AWS went from 28% to 37% growth in one quarter. Holding the high 30s is the core of the bull case. Watch the AWS backlog and any comments on how much capacity is coming online, since supply has constrained the industry.
Revenue timing: Amazon guided Q3 sales to $197–202bn (+9–12%), but says growth is only about 4% higher excluding the shift in Prime Day timing. An in-line revenue report may be treated as a miss given this factor.
UK Oil Giants
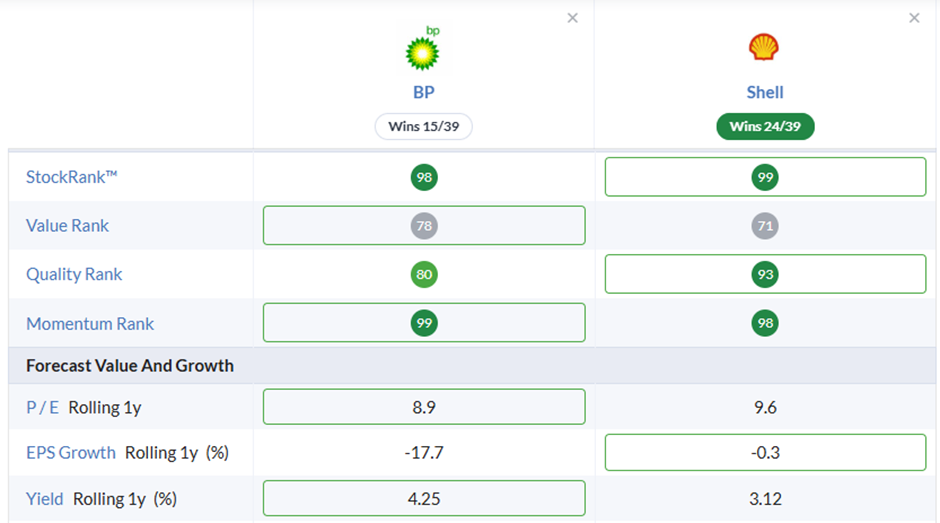
Q3 reports arrive next week for both Shell (LON:SHEL) and BP (LON:BP.). Each has already published a pre-results trading update, so most of the moving parts are known. The open questions are how big the beats are and what each does with shareholder payouts.
BP looks marginally cheaper, but Momentum investors will prefer Shell. Overall, they are both very highly-rated Super Stocks:
Here's what to look out for:
Refining Margins: The indicative refining margin jumped to $42/bbl from $24/bbl in Q2, while the indicative chemicals margin fell to $208/tonne from $270/tonne. B has already guided Q2 refining margins at $46.7/bbl. Products should gain $1.9–2.1bn from stronger realised refining margins, while the customers' business is expected to be weaker.
Upstream: BP's production was roughly flat in Q2, and output is guided at 2,190–2,240 mboe/d against 2,201 in Q2. Shell is in a similar position, with guidance of 1.74–1.84m boe/d versus 1.82m in Q2. However, Shell also expects about $300m of exploration write-offs. Offsetting production declines in mature fields remains a challenge for both.
Buybacks: Shell's current programme of a new $3bn plus the remaining $1.232bn from the suspended programme was expected to run through to this week. With that expiring, the main decision to watch is the size of the next tranche. In February, BP stopped its share buyback programme to repair the balance sheet. With net debt down by around $8bn in one quarter due to windfall profits, the question is whether it restarts buybacks now or waits for the December strategy update.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

10 comments
Mello London next month is fast approaching and Mark Simpson and Ed Croft are both speaking at the two day event. There are lots of quality speakers and 60 companies to engage with. Networking is the highlight and this event is Glastonbury for investors...
We only have a few newcomer tickets left...
If any of you have never been to a physical Mello conference before and would like to join us on a £30 one day only 'New to Mello' ticket we still have a few available for Stockopedia subscribers so just apply the code NEWBIE when booking here https://www.melloevents.com/mellolondon2026
Amazon/Microsoft/Alphabet
Thanks for the comments. I hold none of these; my view on the entry point has always been way to bearish. I see each as part of the US ' football game' surrounding AI and all its associated need for vast quatities of the green stuff. Something has to give and I just think Trump is going to leave an unholy financial mess for the next administration so the sooner the Street realises this we may see greater sense come to the party. OK bearish still then!
I am well underweight US given this stance and only hold ITs investing in the area Had I a preference this would be for Microsoft and Alphabet
What is phrase ' chips with everything'
Airtel Mobile Commerce NV (LON:AMC) reporting on Monday not AMC Entertainment Holdings (NYQ:AMC) as listed.
timarr
Thanks for UK Oil majors comment. I hold both and had been thinking about switching into BP (LON:BP.) from Shell (LON:SHEL). My holding in the former is 4 times smaller than the latter. A number of notable income investors feel that BP offers something better but I demurred given my preference for the stronger Gas position of Shell. Interestingly had I switched 6 months ago this would have been a poor decision given Shell has outperformed BP by 11% over said period. Yes there is a yield pick up and arguably BP cancelling its share buy back did the price no favours. Whether the pivot back to Oil and consequential deleveraging of the balance sheet justfies a more nuanced view is something to consider. Historically trading beteen the 2 was not a rare beast as those of my vintage will recall
Always a black art getting a reporting calendar together in the UK add Hunting (LON:HTG) HTG on Wed to the oilers and Ecora Royalties (LON:ECOR) to the resources : ITM Power (LON:ITM) just reported this week tho noted AGM
15 FTSE 100 names 21 from AIM/ All-Share
From a sector PoV bit of a Banks n Brokers one ~: 4 major banks 3 brokers inc St James's Place (LON:STJ) just 5% off 52 week lows under 4.5% shorts . Bit like Aston Martin Lagonda Global Holdings (LON:AML) in both price (8% off 52 week lows) and shorts (5.1% shorts or 19 days to cover)
Mark I have on my list SRT Marine Systems (LON:SRT) earnings update on 28 Oct and Airtel Africa (LON:AAF) HY27 results on 30 Oct.
SRT Marine Systems (LON:SRT) I hold
JimMcLad, where did you get this date from please, I don't see elsewhere.
I did an AI scan of my companies and it said it's "according to the SRT Marine Investors Calendar". If that date is not accurate an update is expected shortly.
Thanks. I did the same but my AI couldn’t find a published date. Will have await events. Must b due soon.
A very insightful and beneficial read, many thanks for your efforts.