The Week Ahead (30 Jun – 4 Jul): TACO?, House Prices, Constellation Brands, Supreme, Kitwave

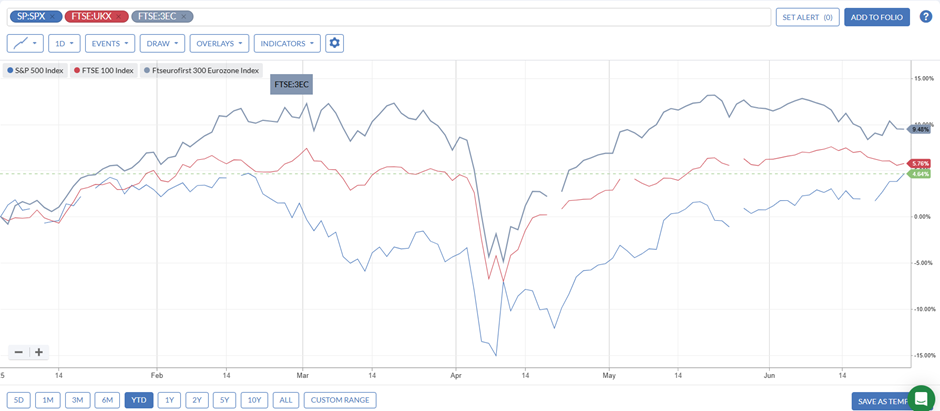
The FTSE is still clinging to a slender lead against the S&P 500 year-to-date. However, both indices continue to lag the Eurozone index:
Perhaps more notably, a strong week for the S&P means that this is hitting all-time highs:
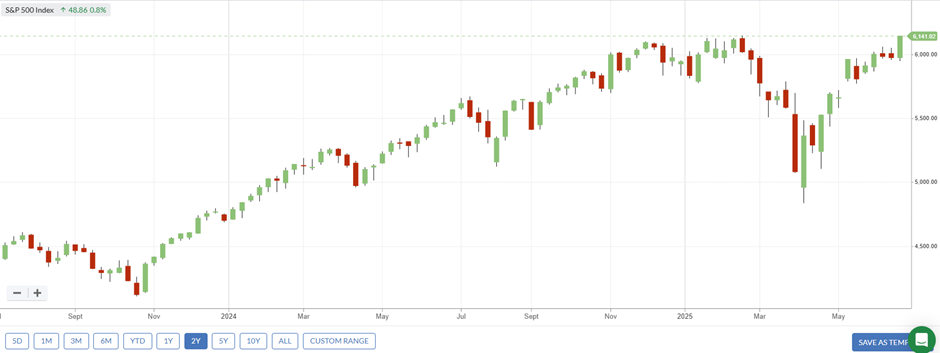
This is surprising, given the backdrop that includes a potential US war with Iran. The other thing that makes this strength surprising is that the "90-day pause" on Trump's tariffs expires on 9 July. The market is betting on TACO – Trump Always Chickens Out. This may be true. However, there is potential for a significant amount of market-moving noise before he inevitably caves. Despite these risks, the VIX trades at the bottom of its recent range (although higher than the first few months of 2025).
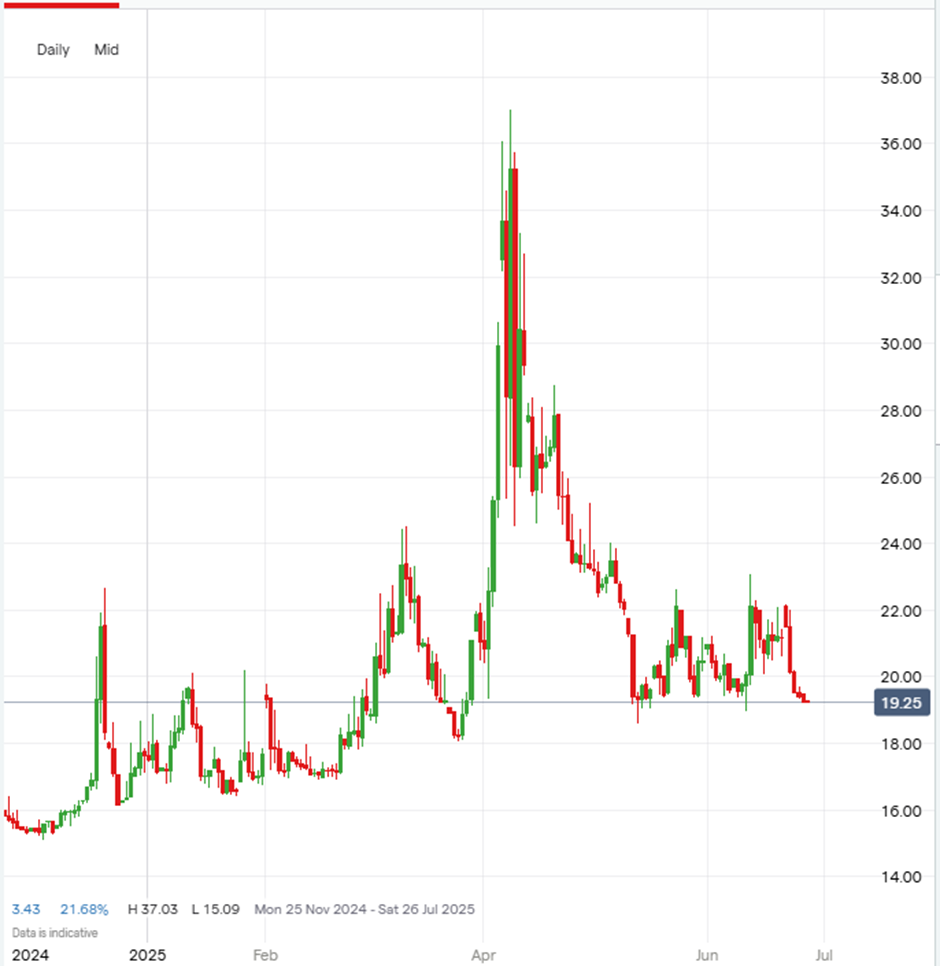
This could mean that those looking to protect their portfolio by using put options may be getting a good price.
Here's what we can look forward to next week:
Economic Calendar
Monday 30th Jun |
||
09:30 |
UK |
BOE Mortgage Approvals Nationwide HPI |
15:00 |
Germany |
CPI Inflation |
Tuesday 1st Jul |
||
10:00 |
Euro Area |
Inflation Rate |
15:00 |
United States |
Job Openings |
Wednesday 2nd Jul |
||
10:00 |
Euro Area |
Unemployment Rate |
15:30 |
United States |
Crude Oil stocks |
Thursday 3rd Jul |
||
13:30 |
United States |
Non-Farm Payrolls Unemployment Rate |
Friday 4th Jul |
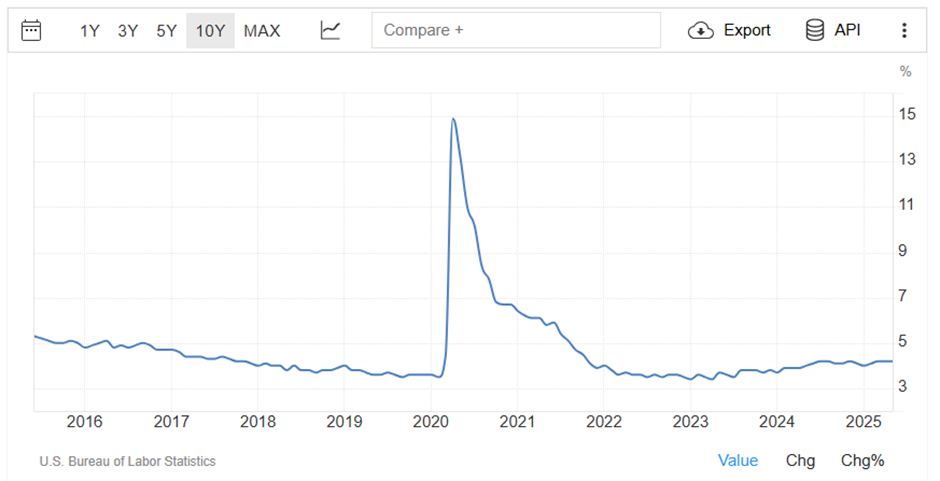
This week's economic news will be dominated by employment data, with both the Eurozone and the United States releasing their unemployment rate. There have been no surprises in 2025 with the rate hovering around the current 4.2%. This has been both consistent and in line with consensus estimates. Economists predict it will remain around the same levels, which indicates an economy neither in distress nor particularly hot, compared to long-term norms:
[Graphs in this section from Trading Economics]
While the Euro area still has a higher rate of unemployment, this has been in a longer-term structural decline:
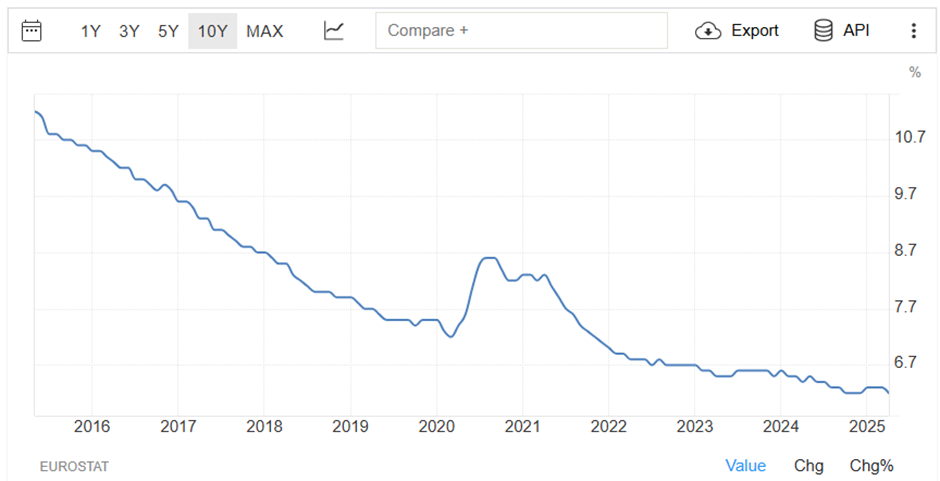
Investors will appreciate the stronger consumer demand this brings, and the rate still seems high enough that the risk of a wage inflation spiral is low in the short term.
Closer to home, house prices will be in focus, with Nationwide reporting their latest index figures. Last month, prices rose 3.5% year-on-year, slightly above market expectations, which were for a 2.9% rise.
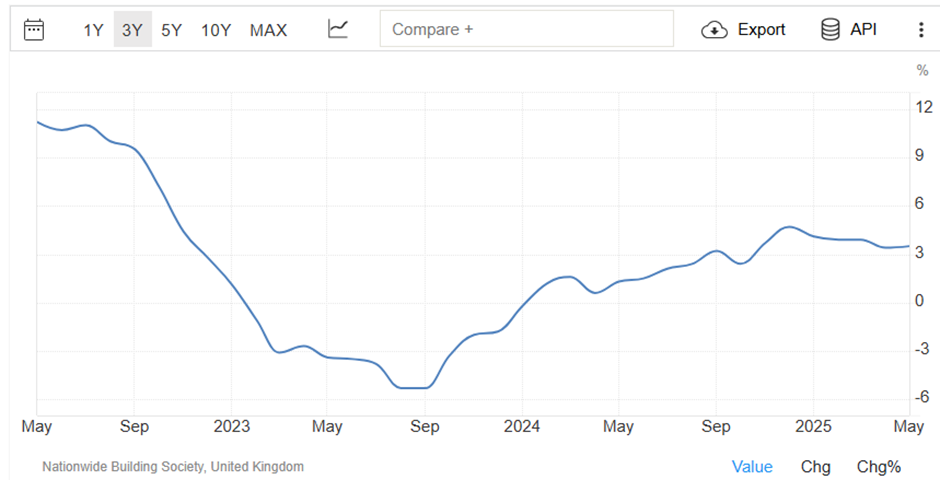
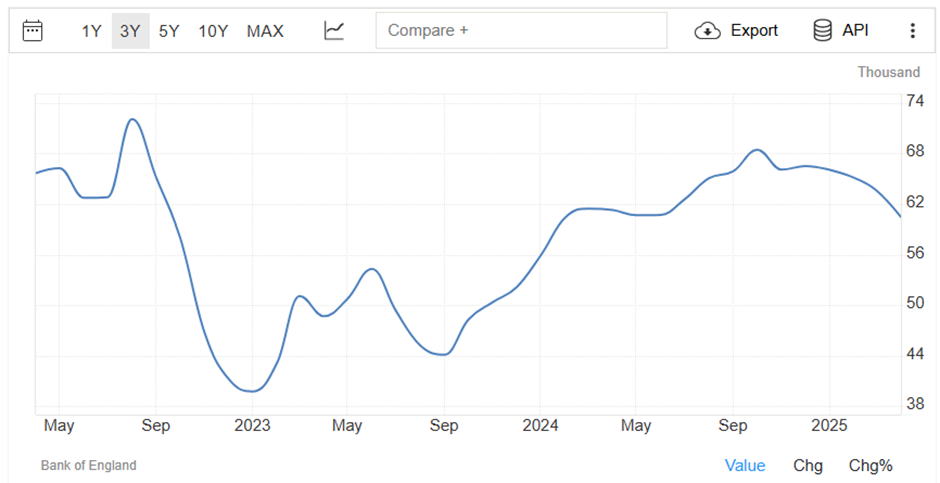
This means that house price inflation has been relatively stable in 2025. However, it I worth noting that several leading indicators, such as BOE Mortgage Approvals and the RICS Survey have started to turn down, which may indicate weaker conditions ahead. This is the 3-year chart of BOE Mortgage Approvals:
This is the RICS data over the same period:
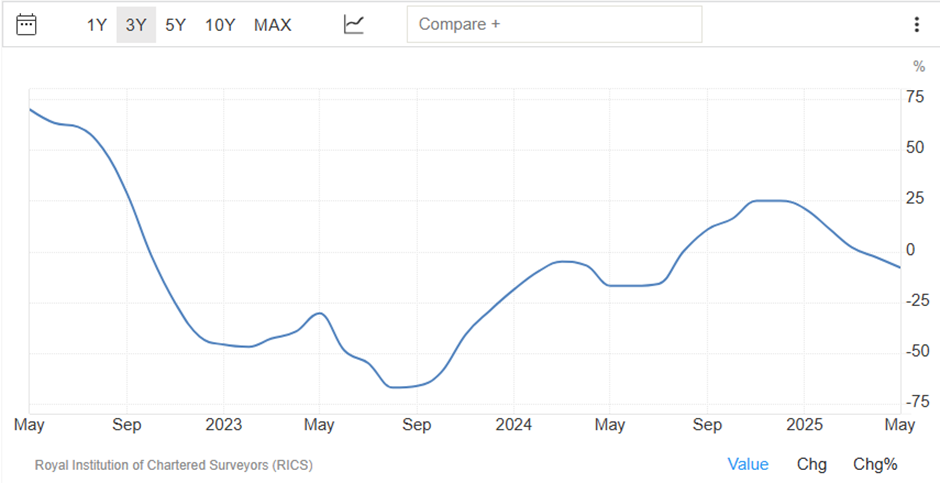
Property investors will be looking for any signs of this weakness in Monday's data.
Companies Reporting
UK Trading Updates |
UK Financial Results |
International Financial Results |
|
Monday 30 Jun |
Nb Distressed (AGM) Advanced Medical Solutions Group (AGM) Cornish Metals (AGM) IQE (AGM) Oberon Aim (AGM) Helios Underw (AGM) European Green Transition (AGM) Trellus Health. (AGM) Cobra Resources (AGM) Huddled Group (AGM) Argo Blockchain. (AGM) Kistos Holdings (AGM) Venture Life (AGM) Focus Xplore (AGM) ValiRx (AGM) Directa Plus (AGM) Bango (AGM) N4 Pharma Plc (AGM) Tern (AGM) Cizzle Biotech (AGM) Nostrum Oil&gas (AGM) Emv Capital (AGM) Bigblu Broadband (AGM) Nativo Resources (AGM) Angle (AGM) Panther Metals (AGM) Digitalbox (AGM) |
eEnergy (Finals) |
|
Tuesday 1 Jul |
Pacific Assets (AGM) Marks & Spencer (AGM) |
Mercia Asset (Finals) Gateley Holdings (Finals) Supreme Plc (Finals) Augmentum Fint. (Finals) Kitwave (Interims) Wynnstay (Interims) |
Constellation Brands (Q1) |
Wednesday 2 Jul |
JD Sports (AGM) Bytes Tech (AGM) Braemar Shipping (AGM) Avacta Group (AGM) Griffin Mining (AGM) |
Renold (Finals) |
|
Thursday 3 Jul |
Assura (AGM) Sainsbury's (AGM) Ceiba Investments (AGM) 3i Infrastructure (AGM) GPE (AGM) Peel Hunt (AGM) |
Currys (Finals) Baltic Classifieds Group (Finals) |
|
Friday 4 Jul |
Constellation Brands
It's an incredibly quiet US earnings week with just Constellation Brands reporting this week, presumably due to the US July 4th Holiday on Friday. Best known as the brewer of Corona beer, this is a business that has struggled recently:
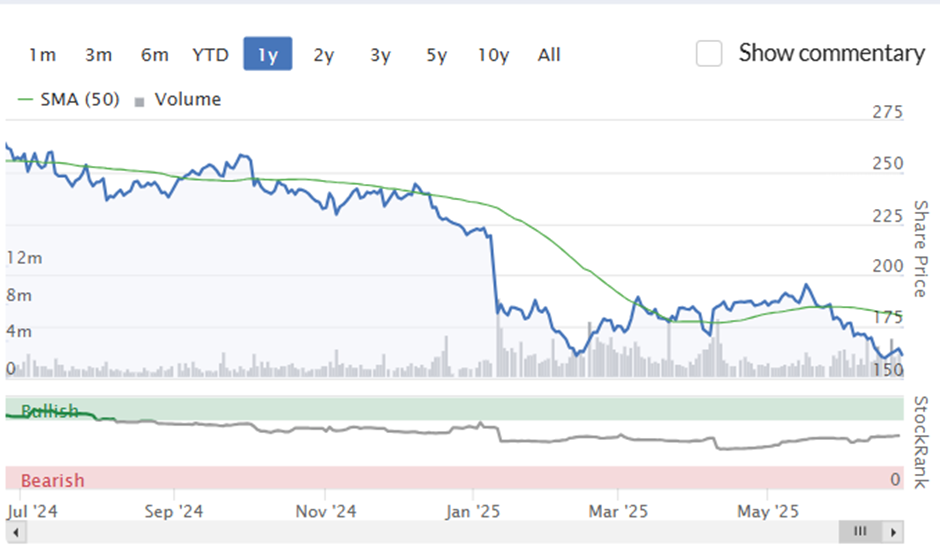
With share price falls reflecting EPS downgrades:
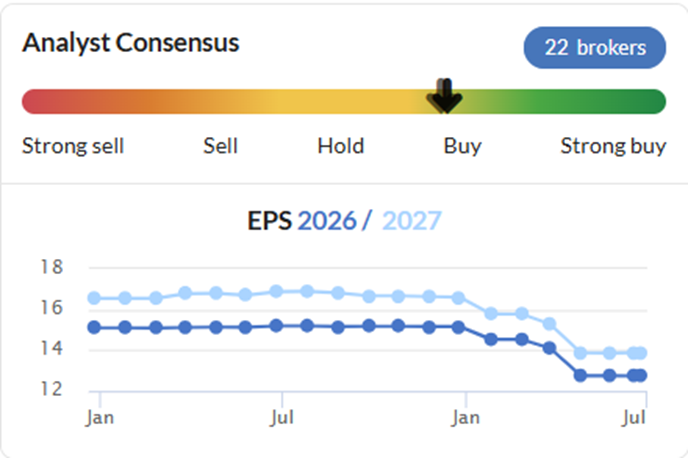
They have suffered from both weak consumer sentiment in the Hispanic community in the US and poor weather over there. Tariffs and other Trump-related actions still have the power to derail things here. However, it is worth noting that they beat estimates in Q4:
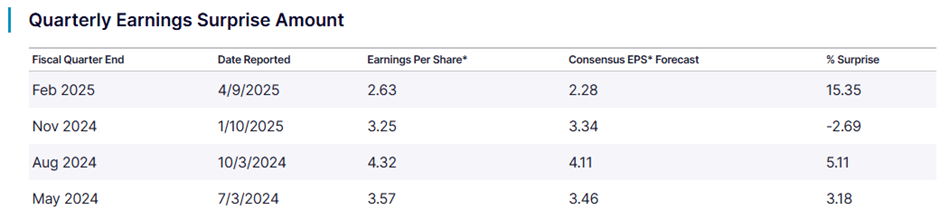
[Source: NASDAQ]
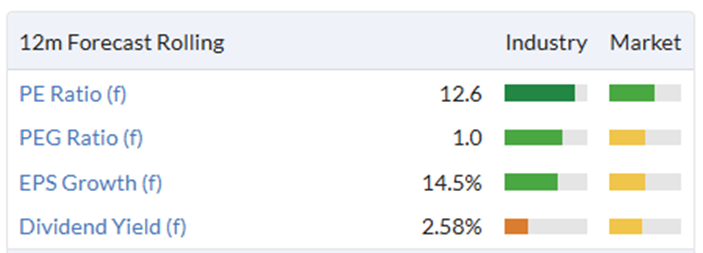
They look modestly priced for a US stock, with a PEG of around 1.0:
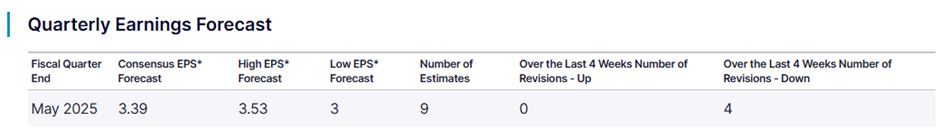
This will look even better value if they beat this week's Quarterly consensus:
[Source: NASDAQ]
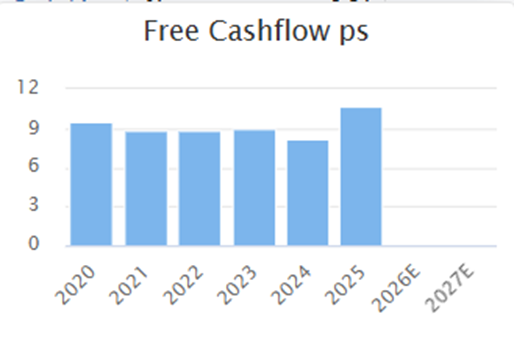
This is a pretty consistently cash-generative business:
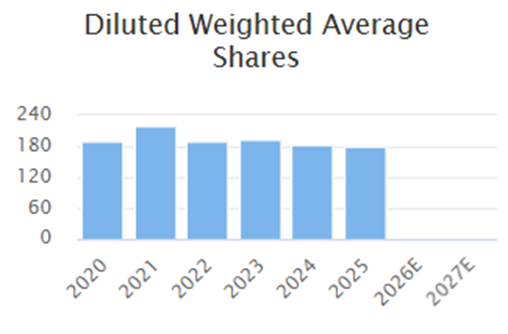
And while the dividend yield doesn't stand out, the company has been using buybacks to reduce their share count:
This may be attractive to the long-term investor willing to look through the short-term tariff-related impacts.
UK Distributors
While AGM updates are plentiful this week, UK results are a bit thinner on the ground. However, distributors have been some of the most popular stocks amongst the individual investor community recently, and two report this week:
Supreme (LON:SUP)
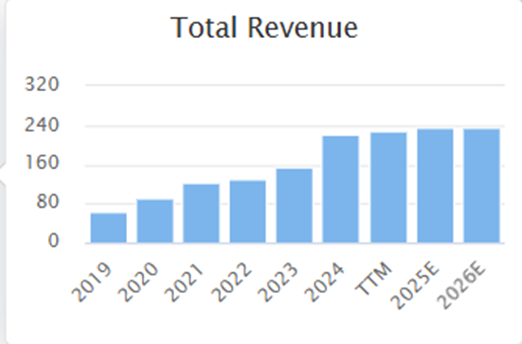
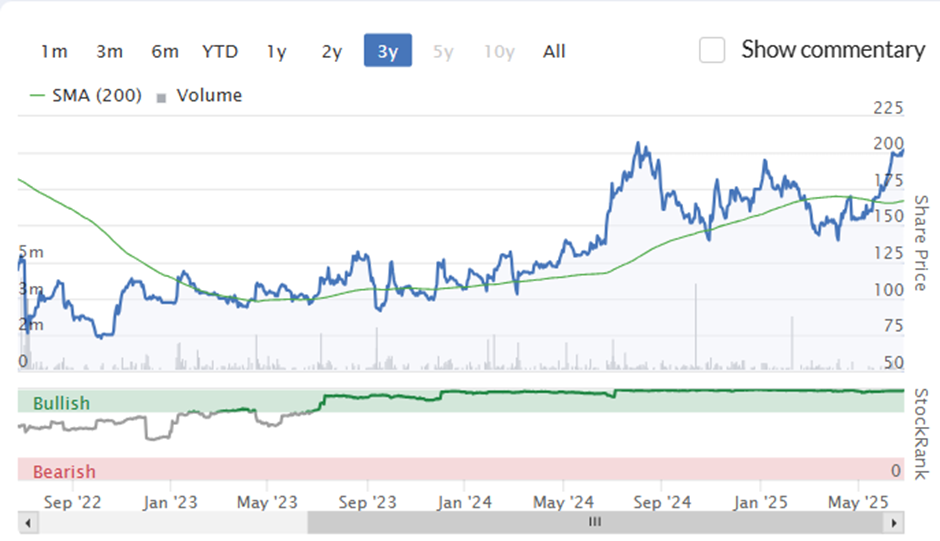
Supreme has been an investor favourite in recent years due to its entrepreneurial spirit and strong revenue growth:
This has been reflected in a rising share price:
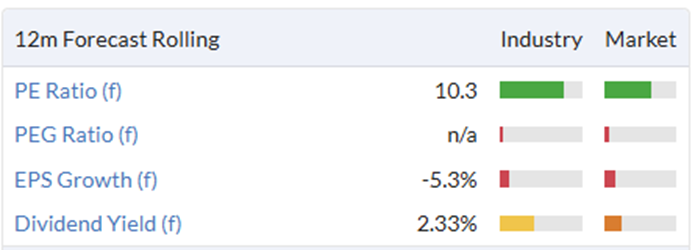
However, it has remained on a modest rating for such a cash-generative business:

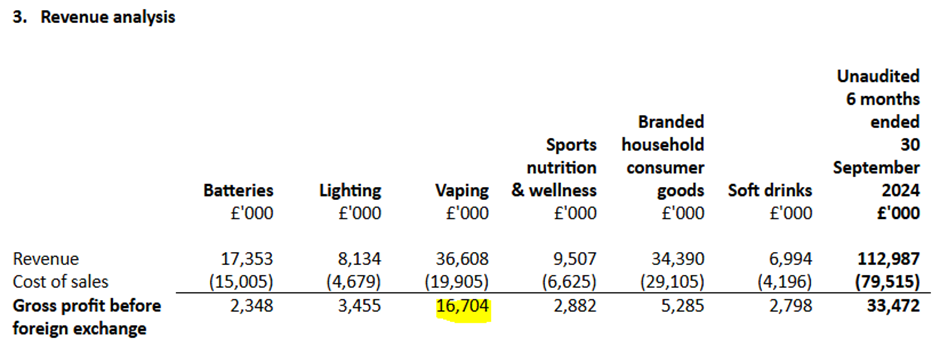
The issue has been that a significant part of their growth has been from vaping, such that in the H1 results, half the gross profit came from the vaping category:
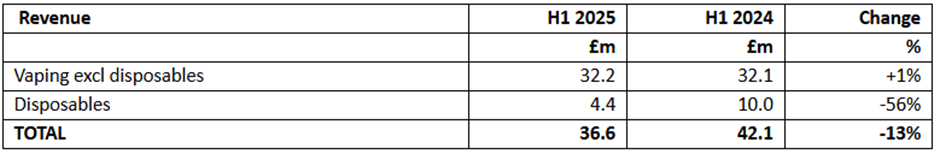
And disposable vapes were banned on 1 June this year. This will not have any impact on this week's results, and these had been reducing ahead of the ban (presumably as retailers start to de-stock).
However, it is worth noting that the most controversial vaping brands that they distribute are not included in their vaping category, but in Branded household goods:
The Branded Distribution category delivered revenues of £34.4 million, up 12% (H1 2024: £30.6 million), and gross profit for the category experienced growth of 56%. Our distribution of vape brands ElfBar and Lost Mary contributed 92% of the division's revenue in H1 2025 (H1 2024: 86%)
Therefore, vaping accounts for around 60% of revenues and 65% of gross profits here. The scale and nature of the shift from consumers buying disposable vapes to buying refillable ones are key considerations. As is the risk that further legislation will be introduced to make vapes sufficiently high-value that they aren't treated as disposable, despite being technically refillable.
In terms of financials, FY25 is in the bag, with their recent trading statement giving in-line guidance:
Supreme expects to report FY25 revenue of around £235.0 million (FY24: £221.2 million) and Adjusted EBITDA 1 of at least £40.0 million (FY24: £38.1 million), in-line with current market expectations . In addition, the Company expects to trade in-line with market expectations for FY26.
What investors will be looking for in these results is the mix of revenues and gross profit, as that will determine how the FY26 outlook appears. The other main factor will be how recent acquisitions, such as Typhoo Tea, are trading, as these have the capacity to take over from disposable vapes as the growth engine of the company in the long term.
Kitwave (LON:KITW)
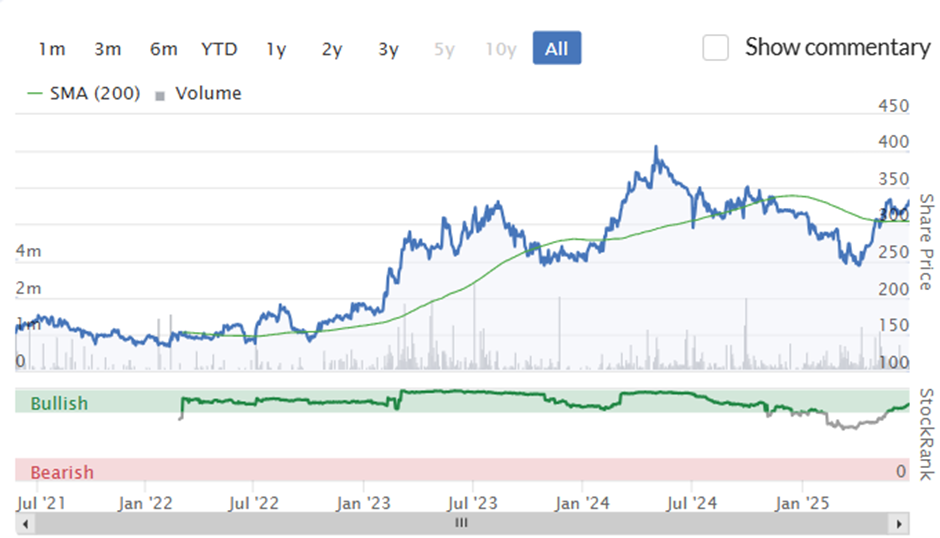
Kitwave has done very well for investors despite listing during the IPO boom of 2021:
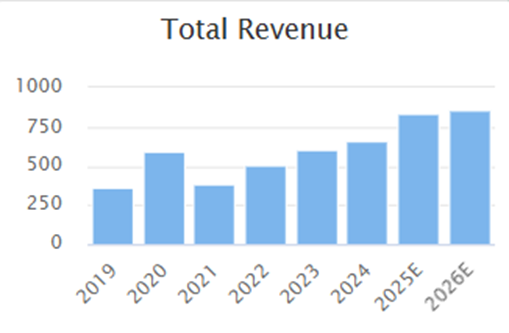
Revenue has grown strongly since listing:
Not all of this is organic, as the company has been highly acquisitive, and the EPS performance has been more modest (although still forecast to have grown by 50% over four years).
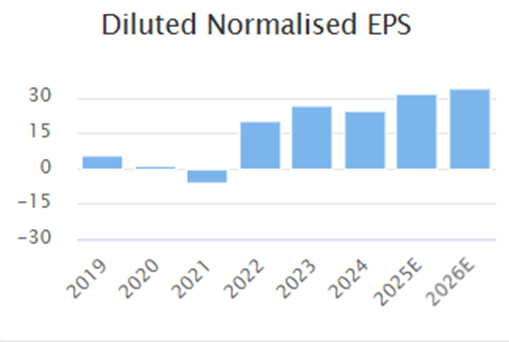
This is because the company has raised equity to make some of these acquisitions.
The valuation metrics make it look good value:
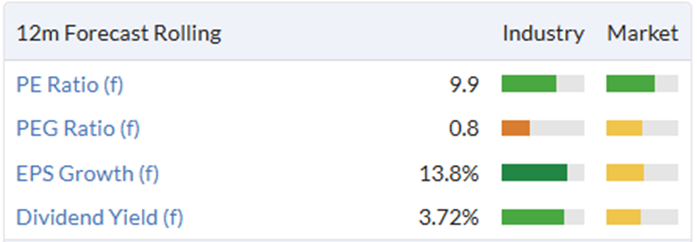
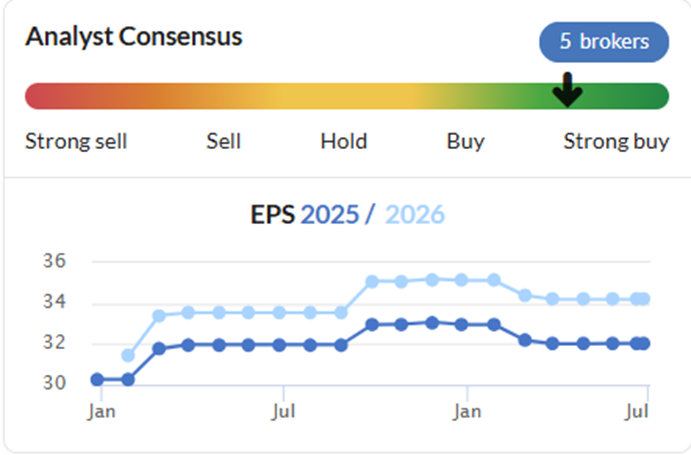
However, it is worth bearing in mind that these Stockopedia figures are based on forward estimates. After multiple upgrades last year, this year's broker forecasts have been downgraded, due to rising NI costs:
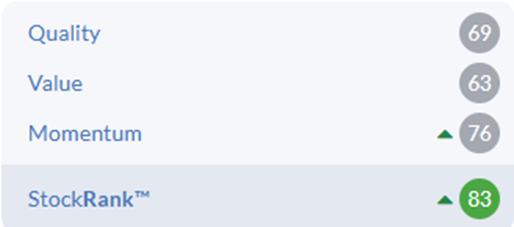
The Value Rank takes the historical figures and is only just above average at 63:
A lot rides on them hitting these forecasts, so it was good news when they said in their trading statement in May that:
As in previous years, and due to the seasonality of the business, performance is weighted towards the second half of the year. The Board is confident that full-year results will be in line with market expectations.
H2 weightings are always a risk, so investors will be looking for a similar statement about the H2 outlook in this week's H1 results.
The other focus, at least for me, will be the size of the adjustments. Many highly acquisitive companies want to take credit for the revenue and profit growth that comes from acquisitions, but they want investors to overlook the costs of making these acquisitions and the restructuring costs of integrating them. Kitwave is no different. Here are the adjustments from the FY24 results:
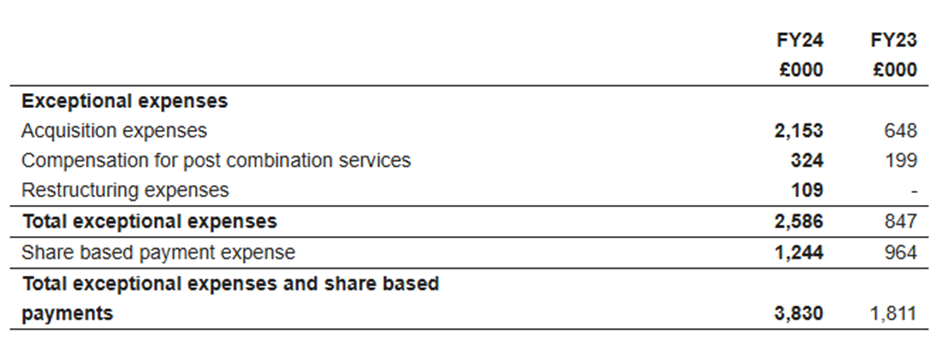
With no major acquisitions made in H1, I would expect much lower adjustments and a smaller gap between statutory and adjusted figures. Anything else would be a red flag.
On the other side, strong evidence that these acquisitions are bedding in well and the synergies are driving future strong growth would be a sign that this company is a good long-term investment.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

3 comments
Polar Capital Holdings plc ("Polar Capital" or the "Group"), the specialist active asset management group, is pleased to announce that Gavin Rochussen, CEO, and Samir Ayub, CFO, will be conducting a live online presentation covering the Group's Full Year results for the period ended 31 March 2025.
The presentation will take place on Monday 30 June 2025 at 12:15pm.
This is an Equity Development event
Thank you Mark. I'll be watching Mercia and Wynnstay on the 1st, we hold, currently slightly up on Mercia but down on Wynnstay which after selling half our Ramsdens is now our biggest holding by cost and value.
Both interesting asset plays, for different reasons. Looking for signs that Wynnstay can use those assets productively. Mercia for progress in rationalising their investments and shifting towards an asset manager.