The Week Ahead (3rd - 7th November): Interest Rate & Budget Countdown

Hello and welcome to this week’s edition of the Week Ahead!
This will mostly be an interest rate edition, taking a quick look at recent central bank decisions and then looking ahead to the decision that’s coming up next week for the UK.
Federal Reserve: the US is in the throes of political strife over a government shutdown, but I’ll put that to one side and focus on what the Fed had to say about its last interest rate cut. Note however that the shutdown means that some official US economic data is not currently being published.
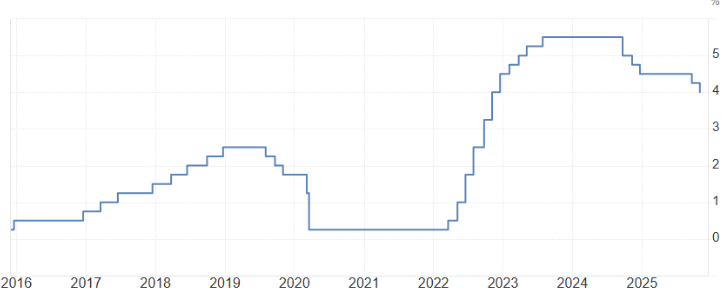
Here’s a 10-year chart of the Fed Funds rate. The latest cut takes it to 3.75% - 4.0%:
Source: tradingeconomics.com
The latest FOMC statement opens as follows:
Available indicators suggest that economic activity has been expanding at a moderate pace. Job gains have slowed this year, and the unemployment rate has edged up but remained low through August; more recent indicators are consistent with these developments. Inflation has moved up since earlier in the year and remains somewhat elevated.
The Fed has the so-called dual mandate - it’s explicitly tasked with both maximum employment and price stability (rather than just price stability).
This means that even if inflation is higher than its 2% long-run target, it can still, without embarrassment, keep rates low in order to boost economic activity.
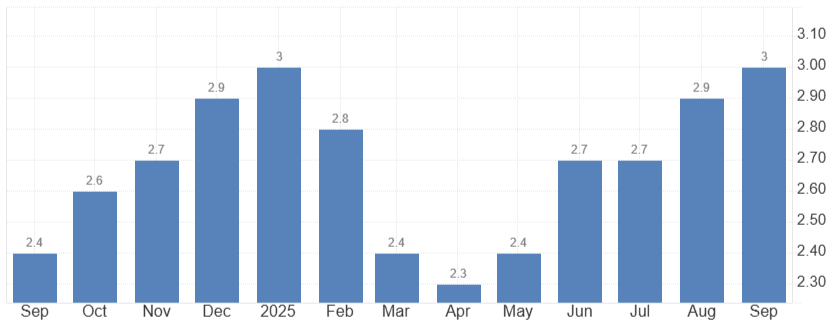
And inflation has been rising recently:
Source: tradingeconomics.com
Rising inflation should be a reason to hike rates, but the Fed is clearly not convinced that this is what the US economy needs at this time.
Which is strange, because the language used by the Fed in relation to the economy is actually more positive now than it was in the previous statement. This statement says that economic activity is “expanding at a moderate pace”, whereas the previous statement said that activity was moderating.
But they remain fundamentally cautious:
Uncertainty about the economic outlook remains elevated. The Committee is attentive to the risks to both sides of its dual mandate and judges that downside risks to employment rose in recent months.
The US unemployment rate is 4.3% and while this is still a little higher than it’s been over the past year, I would have always considered this to be full employment, or at least very close to it. So the Fed’s stance does strike me as rather timid!
As usual, they provide very little forward guidance, as future decisions depend on future data points.
After the meeting, markets became less certain of another rate cut in December, causing some interest rates to rise.
While the government shutdown is a domestic political crisis of sorts, the overall investment picture seems positive to me: moderate inflation, close to full employment, and a balanced monetary policy. Perhaps this is the “Goldilocks” type of economy that everyone is always talking about!
ECB: the ECB has been running much lower interest rates than the Federal Reserve, and it has kept its rates unchanged this week, as expected. Its main refinancing rate is 2.15%.
Here is their lead statement from Thursday:
Inflation remains close to the 2% medium-term target and the Governing Council’s assessment of the inflation outlook is broadly unchanged. The economy has continued to grow despite the challenging global environment. The robust labour market, solid private sector balance sheets and the Governing Council’s past interest rate cuts remain important sources of resilience. However, the outlook is still uncertain, owing particularly to ongoing global trade disputes and geopolitical tensions.
Euro area inflation is indeed running at 2.1%, close to target. That being the case, there is little reason to change policy, although these low euro interest rates make for a pretty poor environment for European savers.
I note again the mention of “uncertainty” - this is a running theme.
Bank of England preview: no cut is expected next Thursday with Base Rate forecast to remain at 4%.
A key data point was the inflation release this month, which stayed constant at 3.8%. A rise to 4% inflation had been expected by economists.
The news was bearish for Sterling as it pulled forward expectations of a rate cut to February 2026.
In politics, speculation is mounting ahead of the Autumn budget. Leaks to the media suggest that the OBR will find a £20 billion “gap” or, more dramatically, a “black hole” that will need to be filled in the public finances.
Tax rises and spending cuts are on the menu, as confirmed by Rachel Reeves.
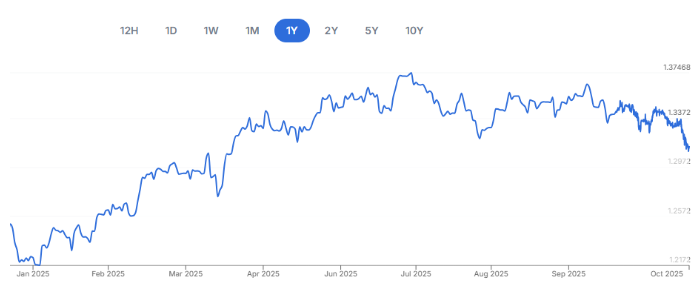
Economic bearishness and pulled-forward rate cut expectations have generated some weakness in the pound against the dollar:
Source: xe.com
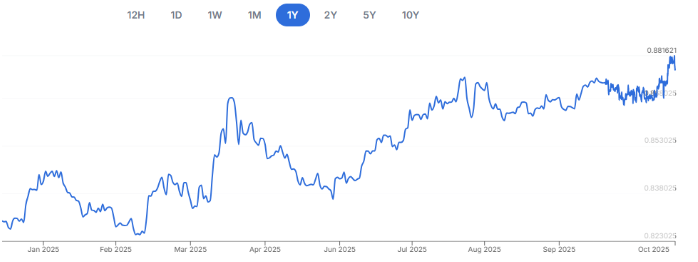
And similarly, there has been euro strength against the pound:
Source: xe.com
From an investment point of view, we will of course be on the lookout for Budget changes that could impact the companies we cover. The effects of higher national insurance contributions and increased government spending in certain sectors have already rippled through countless listed UK stocks - and more drama of this nature could be on the way in November.
Company news: there will be a large flow of company news for us to get our teeth into. And for those who follow US stocks - the flow of news there will be enormous, too. I’ve only mentioned the largest US and international companies below. Let me know if I’ve missed anything!
Economic Calendar
| Date | Time (GMT) | Country | Event |
|---|---|---|---|
3rd November | 15:00 | US | ISM Manufacturing PMI |
4th November | 13:30 | US | Balance of Trade |
4th November | 15:00 | US | Job Openings |
5th November | 12:00 | US | MBA 30-Year Mortgage Rate |
5th November | 15:00 | US | ISM Services PMI |
5th November | 15:30 | US | Crude Oil Inventories |
6th November | 09:30 | UK | S&P Global Construction PMI |
6th November | 10:00 | EU | Retail Sales |
6th November | 12:00 | UK | BOE Interest Rate Decision |
6th November | 13:30 | US | Initial Jobless Claims |
7th November | 07:00 | UK | Halifax House Price Index |
7th November | 13:30 | US | Non Farm Payrolls |
Companies Reporting
| Date | UK Trading Updates and AGMS | UK Financial Results | International Financial Results |
|---|---|---|---|
Monday 3 November | Kosmos Energy (LON:KOS) Diversified Energy (LON:DEC) | Spirax (LON:SPX) Croma Security Solutions (LON:CSSG) | Berkshire Hathaway (NYQ:BRK.B) Palantir Technologies (NSQ:PLTR) Vortex Energy (CNSX:VRTX) |
Tuesday 4 November | Murray Income Trust (LON:MUT) (AGM) BP (LON:BP.). International Workplace (LON:IWG) | Smiths News (LON:SNWS) EnSilica (LON:ENSI) Focusrite (LON:TUNE) dotDigital (LON:DOTD) AdvancedAdvT (LON:ADVT) Associated British Foods (LON:ABF) | Advanced Micro Devices (NSQ:AMD) Shopify (TSE:SHOP) Uber Technologies (NYQ:UBER) Arista Networks (NYQ:ANET) Amgen (NSQ:AMGN) Eaton (NYQ:ETN) Pfizer (NYQ:PFE) Spotify Technology SA (NYQ:SPOT) Nintendo Co (PNK:NTDOY) Mitsubishi (TYO:8058) |
Wednesday 5 November | Barratt Redrow (LON:BTRW) (AGM) Persimmon (LON:PSN) Lancashire Holdings (LON:LRE) Conduit Holdings (LON:CRE) J D Wetherspoon (LON:JDW) | Trainline (LON:TRN) Braemar (LON:BMS) Marks and Spencer (LON:MKS) | TOYOTA MOTOR (NYQ:TM) Novo Nordisk A/S (NYQ:NVO) Applovin (NSQ:APP) Mcdonalds (NYQ:MCD) Qualcomm (NSQ:QCOM) Arm Holdings (NSQ:ARM) Robinhood Markets (NSQ:HOOD) DoorDash (NSQ:DASH) McKesson (NYQ:MCK) |
Thursday 6 November | Diageo (LON:DGE) (AGM) Time Finance (LON:TIME) (AGM) Ashmore (LON:ASHM) (AGM) Tavistock Investments (LON:TAVI) (AGM) AstraZeneca (LON:AZN) TBC Bank (LON:TBCG) Helios Towers (LON:HTWS) Wheaton Precious Metals (LON:WPM) IMI (LON:IMI) Derwent London (LON:DLN) Vistry (LON:VTY) Howden Joinery (LON:HWDN) Osb (LON:OSB) Watches of Switzerland (LON:WOSG) S4 Capital (LON:SFOR) | NovaGold Resources (ASQ:NG). J Sainsbury (LON:SBRY) Tate & Lyle (LON:TATE) Auto Trader (LON:AUTO) | DBS group (SGX:D05) ConocoPhillips (NYQ:COP) Zurich Insurance AG (SWX:ZURN) |
Friday 7 November | International Consolidated Airlines SA (LON:IAG) ME International (LON:MEGP)
| Constellation Energy (NSQ:CEG) KKR & Co (NYQ:KKR) Enbridge (NYQ:ENB) |
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

32 comments
There's some great commentary here in this thread, but also some comments that need to be moderated - this isn't a place for personal attacks!
I can’t see any personal attacks here unless you are looking for one!
Grown up people having different opinions and views on how the markets will react to any changes in rates etc!
Q3 trading update from TP Icap (LON:TCAP) is due on Wednesday 5th. StockRank 95 and one in which I have quite a large position!
There is nothing worse than lazy posting.
I will urge all to try and listen Scott Bessent’s interview on CNN and the recession fears we are probably going through (US Housing market).
Thanks to BnB/Cancun/James that have provided some opposing views.
US rates are coming down and are coming down fast.
QE is just around the corner that it will take these rates to 2%.
All the best to all
Wise (LON:WISE) HY results due on Thursday the 6th
The big date to watch for this coming week is November the 5th which is when the US Supreme Court will start hearing arguments on Trump’s IEEPA tariffs (The IEEPA tariffs are trade duties imposed under the International Emergency Economic Powers Act, allowing the U.S. president to regulate imports during a declared national emergency). The IEEPA tariffs account for 55% of all tariffs which according to Goldman Sachs amount to some USD 200m. Goldman Sachs estimate 37% (rising to 55% by the end of 2025) is paid by US consumers; 22% by US businesses; 18% by foreign exporters and 5% is lost due to evasion.
If the US Supreme Court reverses the IEEPA tariffs, that is the equivalent of a USD200 billion boost. The betting sites odds suggest a 60 to 65% chance of a Supreme Court reversal, although the market brokered by Jefferies and others suggest hedge funds are settling their long / short trades with a 40 to 45% probability.
Other major liquidity events include:
I believe the Ukraine war will be over soon, and whilst wars are inflationary, there is a rebuild cost of US$525 billion. Wait until you see what that does to the price of steel and concrete in Poland.
I know the S&P is at the top of the channel going back to the GFC, and the internet is full of doomsters predicting the next crash, but I just cannot see this with all this liquidity about to hit the markets.
Markets currently assign a 99% probability to a 0.25% Fed rate cut at both the October 29 and December 10 meetings, with a base case of two cuts over the next 12 months.
I think we are in for a final melt-up before Project Zimbabwe gets going proper. I am long debasement assets including gold, but also long copper, grid capacity, resilience and intelligence; real assets, real asset managers like Brookfield (TSE:BN) and Sprott (TSE:SII), and long Poland.
It’s November now!
Just saying as you said we expect a rate cut in October…..
All the best
Following the cut last week, there's a 63% chance of a 25bp cut at the December meeting....
An interesting announcement on Friday 31st October from UK Government was on support (from April 2026) to reduce energy prices for industry as part of the "Modern Industrial Strategy". High energy prices have been a significant headwind for energy intensive UK companies, e.g. ceramics and chemicals . This should increase profitability, help reduce debt, and may also feed into a reduction in future inflation figures? I tend to be overweight industrials, so will be interested to see how this plays out on an individual business level in the coming weeks and months.
The official Government press release can be found here..
https://www.gov.uk/government/...
As from April 2026 this "brings UK industrial energy costs in line with European competitors" I am not sure how long the Government believes it has here. Even if we matched energy prices tomorrow it would already be too late for many industries.
INEOS have already flagged up that the fight as far as they are concerned is slowly being lost.
https://www.ineos.com/news/ine...
As a minor aside, It is being reported that Mr Miliband's carbon budget and growth delivery plan now excludes the much stated and repeated promise that households in the UK would have £300 cheaper energy bills by 2030.
Sadly (because I was once a chemist and remain a member of the Royal Society of Chemistry), the chemicals sector in the UK is totally un-investable because of the utter incompetence of this and past UK governments and their spectacularly sclerotic and incoherent energy policies. (That is one reason why Treatt (LON:TET) with their reliance on fractional distillation is, for me, un-investable; and why AI will never really get off the ground in the UK).
The peice I read on the ennergy costs cut mentioned it would only reduce bills by 18%, and companies wouldn't see any benefit until 2027. An 18% reduction doesn't do much when you consider how much costs have gone up.
As a residential user, my gas price has gone from around 2.1p to 5.8p per unit from May 21 to now. Electricty has gone from around 14p to 29p per kWh in the same tiime frame. While an 18% drop on that would be welcome, it's not enough to turn industry around.
Dear Graham,
You are looking at this US rates in a very amateur manner not looking at INFLATION EXPECTATIONS! What the market expects and what the market gets!
I understand you haven’t got the knowledge or perhaps the experience in how things actually work over the pond.
One to understand to fully understand on where future US rates are going should visit the cmegroup.com website and the 30 Day Federal Funds Futures and Options. I have explained in detail a couple of years ago on how you can read and analyse this data that 99% of the times is correct on future US rate decisions.
JEROME P WILL CUT RATES IN EVERY MEETING LEFT UNTIL HE GOES HOME.
All the best
You think rates will be 2.75 to 3.0 in May? I'll take the other side of that bet, Yiannos. The only way that'll eventuate is if the labour market collapses. Recent weakness has been about supply of workers, not dole queues. My bet is they'll make a hawkish cut in December (if at all) followed a pause in Jan - or vice versa. Where are the recession-baiting conditions today that call for cuts?
So much for the data-driven aspect of the decision-making. Cutting to issues of historical legacy, JP will want to go out as the chief who did not bow to Trump. And having been lambasted for not raising rates quickly enough in '22, he won't want his final act to be stoking inflation with unnecessary cuts in '26.
What could change this hypothesis? A market crash that bruises the wealth effect that is keeping the US consumer spending for one. Or any economic black swan, of course.
Everyone has been wrong about FOMC decisions for several years now. And now add you and me to the list!
Speak for yourself BnB!
You are totally and 100% wrong on US rate cuts! The FED will cut in every meeting until JP retires.
We had this conversation about 12 months ago when I told you that there are at least 3 rate cuts in 2025 and you were questioning me doing the same thing as now speaking about irrelevant stuff and inflation. What inflation? Graham’s chart? There is no inflation in the US.
Every 0.25% rate cut is a 100B less in interest paid by the US government. The US government also is about 2T pa short now as things stand. The 1T is approximately going to be covered by rates going under 3% (from 5%).
The other 1T?
Answers on a postcard please (so obvious!).
All the best
Growth?
No , Growth already counted in. If there was no growth the shortfall was going to be 7T!
All the best
IMHO it wont make up the $ 1 tn, but the US Govt will definitely be hoping that their AI related stock investments pick up some of the slack that tariffs are also filling ....
On-shoring manufacturing and opening up their mineral wealth - takes time but it's building - acorns and all that.
Why is Trump building the Big Beautiful Ballroom - 2026 will be 'golden' for the US 'by hook or by crook' - Trump birthday, some US founding date and something else can't remember.
Plus Aliens may drop in which hopefully puts a reset into all this one religion killing another religion/ideology nonsense.
Best advice I can give is - pay off all and any debt, live within your means and squirrel away gold and silver (but not where any government can confiscate it).
Wheaton Precious Metals (LON:WPM) will be my focus on Thursday. Miners making profit at 1700 and now 4000 - they will be holding back, keeping the equipment and workers employed and playing the long game - and why not - we want a new 'gold standard' and 'electric everything'.
IMHO inflation is unlikely to rear its head again as a) the labour market is soft, b) the K shaped economy in the US means that only the high income classes are doing well, so the majority of goods in the inflation basket won't be affected by demand pull , c) the modern economy is very global, with efficient supply chains , so IF the US and China are friends ( currently yes ), then competition keeps prices low ... and most importantly d) unless tariff percentages are increased every year, then by default they will drop out of the equation as a change year over year in April 2026 ... PCE ( the Fed's preferred inflation method ) is already as low as 2.7 % and that's including the effect of Tariffs, so when those are taken out , inflation should drop further...
Just my view obviously though....
Yiannos misinterpreted my post. I don’t think inflation is going to be a problem either. Not least because central banks will come round to the idea that 3% is the new 2%. But one of the reasons I think that we are unlikely to be shocked by inflation, is that I don’t believe that the Fed will cut incessantly into May. There is insufficient evidence in the US economy that the current rate is particularly restrictive.
It wasn't a mistake from Yiannos tbh BnB...
Potentially, the unnecessary cuts that you referenced are necessary to help Main Street USA... and I also believe that said rate cuts won't stoke inflation as you alluded .. However, I also don't think that the Fed will cut every meeting, purely because Powell won't want to be seen as Trump's lap dog, but running an independent committee... Although Yiannos is usually correct a lot more frequently than me, so I'll reserve judgement ...
It is also possible that monetary conditions are quite restrictive IMHO... illustrated by the fact that the Fed had to stop QT prematurely at the last meeting, because liquidity conditions in the repo market were getting too tight....
Other opinions welcome though ...
So QT is finished as we all know.
What comes next (2026 with Hassett as the new FED chair) to lower the rates even further?
Rates will go to 2% 2026-2027.
All the best
So the debt bill gets lower but inflation goes out of control.
Everyone says they need to stop spending (everyone) but then social unrest follows - voters vote for "free stuff" aka socialism. The federal shutdown has been funny to watch as fat people bemoan their food stamps. But they vote unfortunately.
Apologies - this is an investment website - "how to make, or better 'keep' your money" - is the No.1 priority.
Today is a BAD day in the UK imo. If the UK does not get its act together then its over. Investment, pension, work, house - sorry don't want to be stabbed on a flippin train - what's going on.
Haven’t got a clue on what you are talking about!
I don’t think you do either!
I'd like yiannos and B&B to agree a worthwhile bet on whether rates will be cut every meeting. It would add some entertainment to the madness.
I always enjoy the debates with BnB. He posts his views but always backed by decent arguments.
Better than reading posts about Sosandar (LON:SOS) being an excellent investment opportunity……….
The madness is not having an opinion amd trying to post irrelevant stuff.
I can have a decent bet with you (if you have an opinion) for charity of course.
To add entertainment to the madness…….
All the best
However, I also don't think that the Fed will cut every meeting, purely because Powell won't want to be seen as Trump's lap dog,
Which was my original argument before we got sidetracked onto inflation.